
 Global Artificial Intelligence-Emotion Recognition Market | 2026-2036
Global Artificial Intelligence-Emotion Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence-Emotion Recognition Market Foresight
Enterprise software licensing is fragmenting as emotion recognition vendors bypass traditional VAR networks and sell direct to platform integrators. Microsoft Corporation leverages its Azure cloud infrastructure to bundle facial analysis APIs with existing enterprise contracts. Affectiva Inc. specializes in automotive-grade driver monitoring, anchoring its position within Tier 1 supplier programs. Tobii AB controls the hardware-software stack for eye-tracking deployments, extending its reach beyond research into commercial safety applications.
Artificial intelligence-emotion recognition comprises machine learning models that infer affective states from multimodal inputs including facial micro-expressions, vocal prosody, galvanic skin response, and lexical sentiment, typically operating at inference latencies below 200 milliseconds for real-time applications. Facial recognition technology leads current deployment volumes due to mature computer vision pipelines and low-cost camera hardware, though edge computing architectures represent the fastest-growing deployment mode as latency-sensitive automotive and surveillance applications demand on-device processing. Cloud-based delivery retains margin concentration in customer experience management, where financial institutions and retail chains process high-volume, non-time-critical sentiment data.
The EU AI Act classifies emotion recognition in workplace and educational settings as high-risk, mandating conformity assessments and human oversight protocols that reshape product development roadmaps for vendors seeking European market access. The FDA maintains active engagement with digital biomarker frameworks that increasingly encompass affective computing for mental health monitoring, while China's SAMR enforces algorithmic recommendation provisions that constrain how emotion data trains consumer-facing models. Stakeholders must monitor divergent jurisdictional thresholds for biometric consent and algorithmic transparency that will determine which product architectures achieve cross-border deployability.
Market Dynamics
The EU AI Act's high-risk classification of workplace emotion recognition is forcing vendors to re-architect product roadmaps around human-in-the-loop oversight and conformity assessment protocols, compressing deployment timelines for European market entry.
Growth Catalysts
- Automotive safety mandates:NHTSA guidelines in the United States and parallel regulatory frameworks in Germany and Japan accelerate OEM integration of driver-monitoring systems for drowsiness and distraction detection.
- GDPR-compliant processing architectures:Privacy-preserving edge computing designs enable lawful deployment in European public spaces where cloud-based biometric analysis faces prohibitive consent requirements.
- Galvanic skin response sensors:Wearable form factors integrating GSR with heart rate variability expand addressable applications beyond vision-dependent systems into fitness and clinical monitoring.
Market Restraints
- GPU and NPU supply concentration:Taiwan-based foundry capacity constraints limit edge AI chip availability for automotive Tier 1 suppliers scaling driver-monitoring production.
- FDA digital biomarker validation timelines:Mental health monitoring applications face extended premarket pathways as the agency establishes evidentiary standards for affective computing claims.
- Cloud inference cost structures:High-volume sentiment analysis workloads in customer experience management incur escalating compute expenses that erode SaaS margins at scale.
Strategic Opportunities
- India's BIS certification pathway:The country's standards body is developing AI system safety frameworks that early movers can shape while accessing a large English-language training data pool.
- Multimodal fusion architectures:Convergence of facial micro-expression analysis with vocal prosody models enables higher-accuracy inference for security and healthcare screening applications.
- Direct platform integrator channels:Bypassing traditional VAR networks allows vendors to capture margin and accelerate deployment cycles within enterprise software ecosystems.
Industry Challenges
- Cross-functional talent scarcity:Product teams require simultaneous expertise in computer vision, psychophysiology, and regulatory compliance that few labor markets supply.
- ISO/IEC 27001 certification burden:Biometric data processors face extended audit timelines and documentation requirements that delay commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence-Emotion Recognition Market |
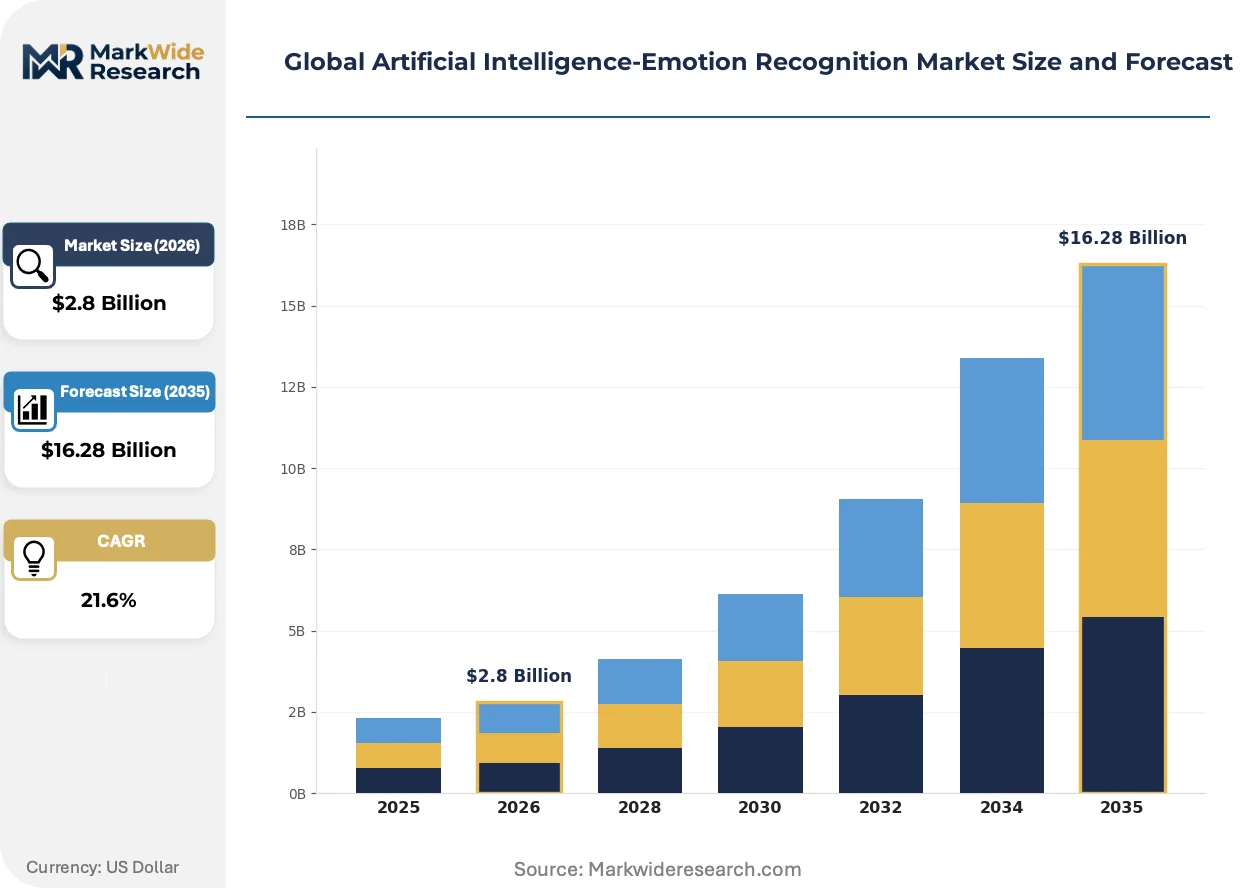
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Facial Recognition, Voice Analysis, Physiological Monitoring, Text Sentiment Analysis, Behavioral Analytics Application: Customer Experience Management, Security Surveillance, Automotive Safety Systems, Human Resources, Education Technology Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing End User: Retail Chains, Financial Institutions, Government Agencies, Telecom Operators |
| Companies Covered | Microsoft Corporation, IBM Corporation, Google LLC, Apple Inc., Smart Eye, Tobii AB, Affectiva Inc., Amazon Web Services, Realeyes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence-Emotion Recognition Market Shifts & Advancements
Edge-native inference architectures are collapsing the latency-performance tradeoff that previously favored cloud delivery, redistributing competitive advantage toward hardware-software co-design capabilities.
On-device neural processing units are collapsing the cost structure of real-time affective computing. Automotive OEMs in Germany and Japan now specify sub-50-millisecond inference latencies for safety-critical driver monitoring. This compression is eliminating the cloud intermediary layer that previously dominated enterprise sentiment analysis, forcing vendors to develop silicon partnerships or in-house chip design capabilities.
The EU AI Act's emotion recognition provisions are reshaping product development priorities across the vendor base. High-risk classification for workplace and educational deployments mandates conformity assessments and human oversight protocols that extend engineering cycles. European market entrants are responding with explainable AI features and audit trail architectures that exceed baseline technical requirements.
Enterprise buyers are consolidating vendor relationships around integrated platform providers rather than point solutions. Financial services and retail chains in the United States now demand API bundles that combine facial analysis with existing customer data infrastructure. This concentration is marginalizing standalone emotion recognition vendors that lack cloud ecosystem partnerships or enterprise software distribution channels.
Global Artificial Intelligence-Emotion Recognition Market Segmentation
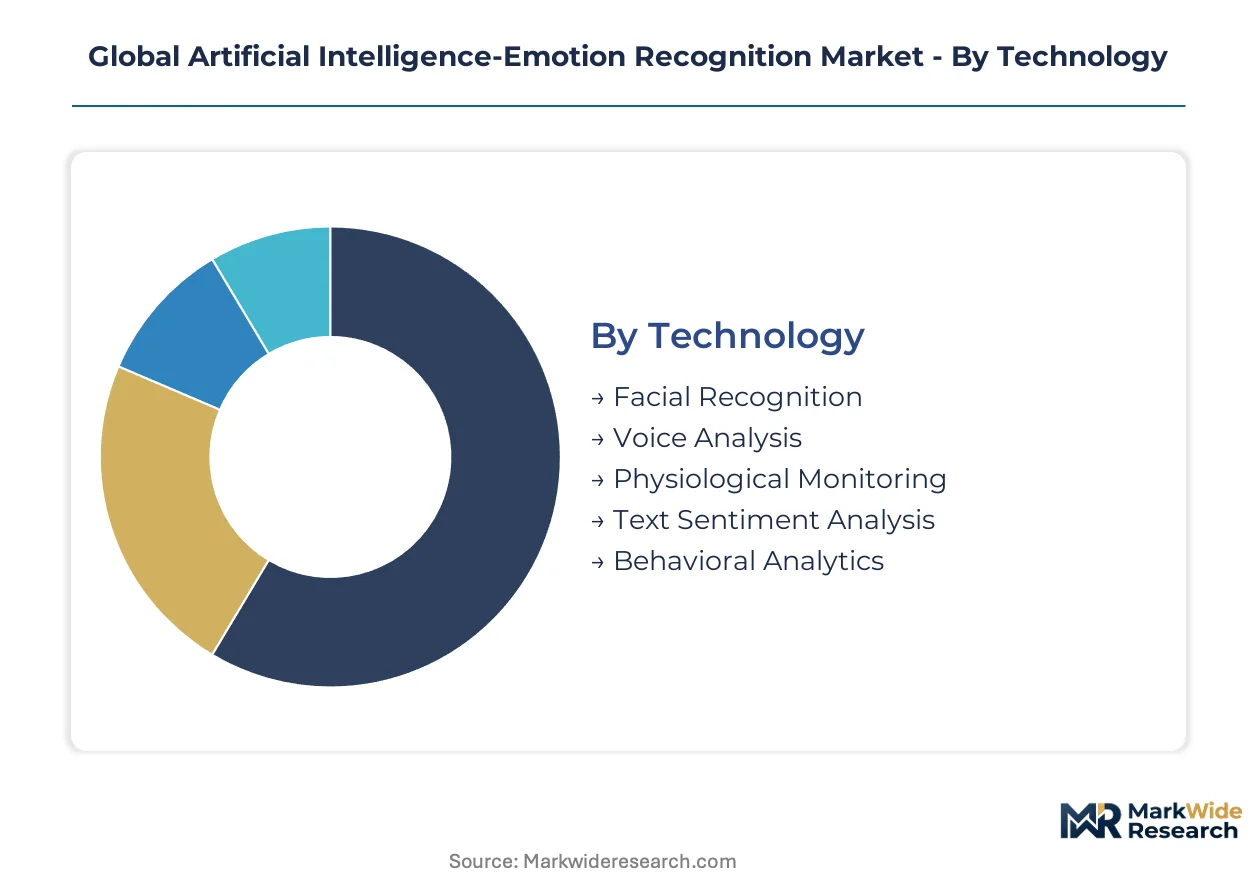
Segmentation in the AI-emotion recognition market reveals divergent engineering requirements across deployment contexts. Automotive safety systems demand sub-50-millisecond inference latencies that reshape hardware-software architectures, while customer experience management prioritizes multimodal fusion accuracy over speed constraints.
Technology:
After-sales service intensity varies sharply across technology modalities, with hardware-dependent physiological monitoring requiring field calibration support that software-centric text analysis avoids entirely.
- Facial Recognition:Computer vision pipelines analyze micro-expressions through convolutional neural networks trained on labeled affect datasets. Demand concentrates in security surveillance deployments across the United States and China, where low-cost camera hardware enables scalable installation.
- Voice Analysis:Prosodic feature extraction captures emotional valence from pitch variation, speech rate, and spectral dynamics. Financial institutions in Germany and Japan deploy voice analysis for call center quality assurance, driven by GDPR and APPI compliance requirements for biometric consent documentation.
- Physiological Monitoring:Galvanic skin response and heart rate variability sensors require wearable hardware integration with clinical validation pathways.
- Text Sentiment Analysis:Lexical and semantic parsing of written communication scales through cloud APIs without specialized hardware dependencies.
- Behavioral Analytics:Kinetic pattern recognition from gesture and posture data serves security screening applications with multimodal fusion requirements.
By volume, Facial Recognition leads. By growth pace, Physiological Monitoring is ahead.
Application:
Cost tier stratification separates safety-critical automotive systems with hardware certification burdens from lightweight SaaS deployments in human resources.
- Automotive Safety Systems:Driver-monitoring systems integrate infrared cameras and NPU acceleration for real-time drowsiness detection. OEM programs in Germany, Japan, and the United States mandate ISO 26262 functional safety compliance that extends development cycles.
- Customer Experience Management:Real-time sentiment scoring of voice and video interactions feeds agent coaching dashboards. Retail chains and telecom operators in the United States drive demand, prioritizing API integration with existing CRM infrastructure over standalone emotion recognition capabilities.
- Security Surveillance:Crowd affect monitoring in public spaces faces EU AI Act high-risk classification requiring conformity assessments.
- Human Resources:Interview and workplace emotion analysis encounters regulatory pushback under GDPR and emerging US state biometric laws.
- Education Technology:Student engagement tracking through facial analysis attracts scrutiny from France's CNIL and similar data protection authorities.
Automotive Safety Systems commands the highest unit economics. Customer Experience Management shows the steepest expansion trajectory in absolute deployment counts.
Deployment:
Volume concentration favors cloud delivery for non-time-critical workloads, though latency-sensitive applications are redistributing toward edge architectures.
- Edge Computing:On-device neural processing enables sub-200-millisecond inference without network dependency. Automotive Tier 1 suppliers in Germany and Japan specify edge-native designs to meet safety-critical response requirements.
- Cloud-Based:Centralized GPU clusters process high-volume sentiment analysis for customer experience management. Financial institutions and retail chains in the United States absorb escalating compute costs for historical trend analysis where latency tolerance permits.
- On-Premise:Air-gapped installations serve government agencies with classified data handling requirements.
- Hybrid:Tiered processing routes time-sensitive inference to edge while aggregating training data through cloud pipelines.
Cloud-Based retains volume leadership. Edge Computing is gaining share fastest as automotive safety mandates harden latency requirements.
End User:
Procurement sophistication separates enterprise-scale retail and financial deployments from government tenders with extended compliance documentation.
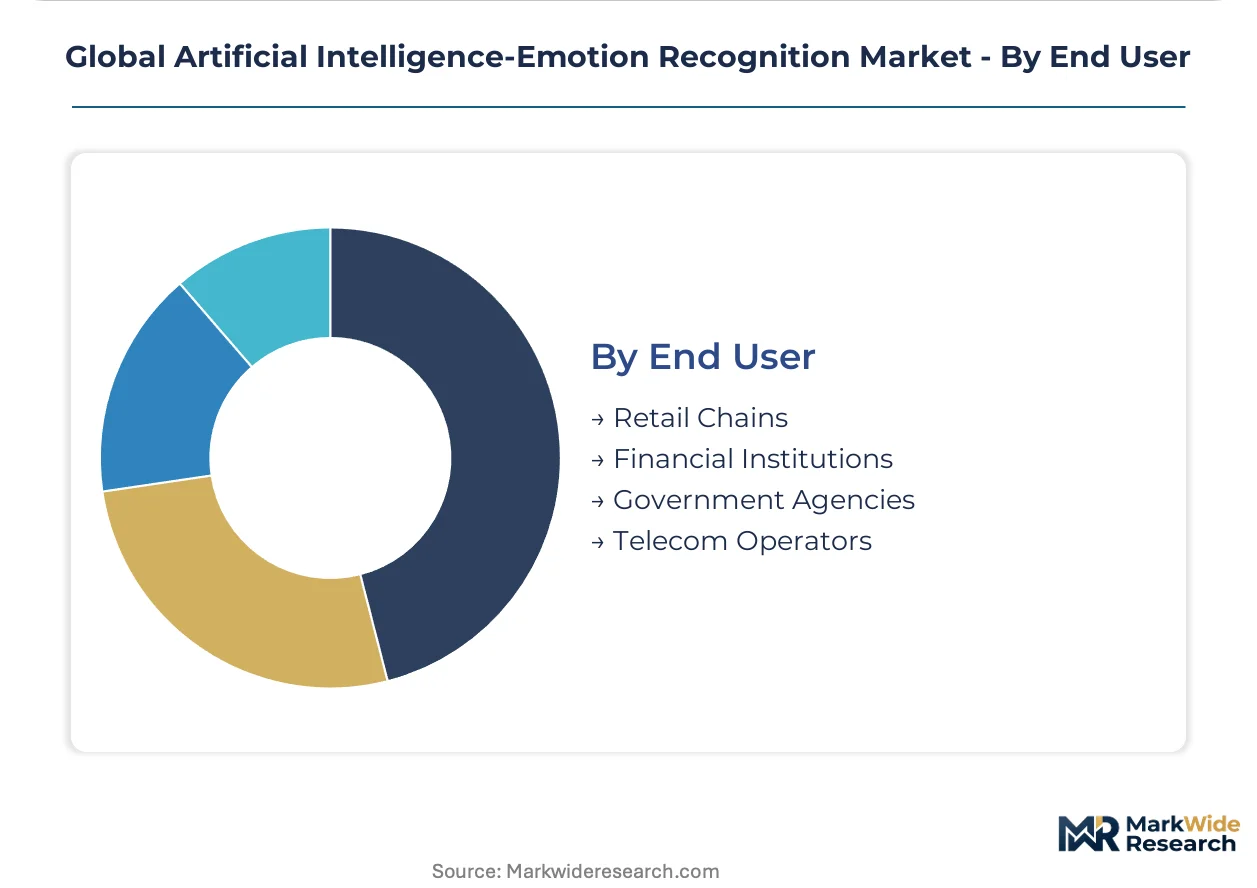
- Financial Institutions:Banks and insurers deploy voice and facial analysis across call centers and branch authentication workflows. US federal procurement guidelines and venture capital availability accelerate enterprise deployment timelines relative to European counterparts.
- Retail Chains:In-store customer journey analysis through video sentiment tracking informs layout optimization. Demand concentrates in the United States where biometric consent frameworks remain less restrictive than GDPR jurisdictions.
- Government Agencies:Border control and public safety applications face EU AI Act prohibition on real-time biometric identification in publicly accessible spaces.
- Telecom Operators:Call center quality management drives voice analysis adoption with API-first integration requirements.
Financial Institutions lead in average contract value. Retail Chains show the most rapid deployment expansion across store networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The NHTSA anchors the regulatory environment for automotive safety applications in the United States, where federal procurement guidelines and venture capital availability accelerate enterprise deployment timelines relative to other jurisdictions.
United States
Financial institutions and retail chains drive demand for customer experience management and call center quality assurance. The FDA maintains active engagement with digital biomarker frameworks for mental health monitoring applications. Silicon Valley clusters host cloud infrastructure providers bundling facial analysis APIs with enterprise contracts.
Germany
Automotive OEMs mandate ISO 26262 functional safety compliance for driver-monitoring systems with sub-50-millisecond inference requirements. The KBA enforces vehicle type approval standards that incorporate biometric safety technologies. Stuttgart and Munich anchor Tier 1 supplier programs integrating infrared cameras with neural processing units.
Japan
METI guidelines accelerate OEM integration of drowsiness detection systems through parallel regulatory frameworks to NHTSA. The APPI imposes strict biometric consent documentation requirements for voice analysis deployments. Nagoya and Tokyo house automotive electronics clusters developing edge-native inference architectures.
China
SAMR enforces algorithmic recommendation provisions constraining how emotion data trains consumer-facing models. The MIIT promotes domestic NPU development to reduce dependency on Taiwan-based foundry capacity. Beijing and Shanghai concentrate surveillance technology deployments leveraging low-cost camera hardware.
India
The BIS is developing AI system safety frameworks that early movers can shape while accessing large English-language training data pools. RBI guidelines influence biometric authentication standards for financial services applications. Bangalore and Hyderabad host software development centers building GDPR-compliant edge computing designs.
Global Artificial Intelligence-Emotion Recognition Market Competitive Landscape
Cloud hyperscalers and specialized automotive Tier 1 suppliers split the market into divergent capability stacks. The vendor base organizes around three strategic archetypes: infrastructure-integrated platform providers, hardware-software co-design specialists, and application-layer point solution vendors. Dominant competitive moves include direct platform integrator channel development and silicon partnership formation for edge-native architectures.
Within the infrastructure-integrated tier, Microsoft Corporation exemplifies cloud-first bundling strategies, while Affectiva Inc. occupies a position among automotive-grade specialists. Tobii AB anchors the hardware-software co-design archetype for eye-tracking deployments. These three entities represent the structural segmentation between cloud API provision, automotive safety integration, and specialized sensor fusion capabilities.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Google LLC |
| Apple Inc. |
| Smart Eye |
| Tobii AB |
| Affectiva Inc. |
| Amazon Web Services |
| Realeyes |
| Others |
Supply & Pricing Matrix
Taiwan-based foundry capacity for neural processing units concentrates upstream leverage among automotive Tier 1 suppliers, compressing margins for edge AI vendors while cloud API providers capture recurring SaaS value pools through enterprise platform bundling.
Pricing Analysis
Geographic price spreads separate GDPR-compliant edge deployments in Germany and Japan from cloud-based sentiment analysis contracts in the United States. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and after-sales calibration intensity. Pricing pressure stems from GPU and NPU supply constraints that elevate hardware costs for automotive safety systems. Retail chains demonstrate highest price sensitivity, while financial institutions absorb premium tiers for API integration with existing customer data infrastructure.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment constrain NPU flows to Chinese foundries, reshaping supplier geography. Taiwan, South Korea, and the United States anchor wafer fabrication for edge inference chips. Raw material dependencies include silicon wafers, advanced photoresists, and rare earth elements for sensor components. Single-source vulnerability concentrates in Taiwan-based advanced node capacity. Distribution runs through direct platform integrator channels that bypass traditional VAR networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional expertise spanning computer vision, psychophysiology, and EU AI Act compliance remains scarce across all major labor markets, constraining product development velocity and widening the capability gap between integrated platform providers and point solution vendors.
For Market Incumbents: Pre-empt margin erosion in cloud sentiment analysis by deepening silicon partnerships for edge-native architectures before automotive Tier 1 suppliers consolidate vendor relationships. Invest in explainable AI engineering cycles to satisfy EU AI Act conformity assessment requirements that emerging entrants lack resources to match. Lock in long-term foundry allocation agreements to defend against Taiwan capacity constraints. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification pathway by contributing to emerging AI safety framework standards while accessing English-language training data pools ahead of formal requirements. Target physiological monitoring wearables integrating galvanic skin response sensors, where clinical validation barriers filter out cloud-centric incumbents. Pursue direct hospital system partnerships for mental health monitoring applications facing extended FDA digital biomarker timelines. For Investors and Strategic Acquirers: Capital is best deployed toward hardware-software co-design specialists with captive eye-tracking or automotive-grade sensor fusion capabilities, as edge inference architectures displace cloud intermediaries across safety-critical applications. Favor vendors with ISO/IEC 27001 certification completion and active EU AI Act technical documentation. Watch for FDA evidentiary standard finalization as the inflection signal for mental health monitoring market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Partnership Formation | Secures NPU supply allocation from Taiwan foundries for sub-50-millisecond automotive inference. |
| EU AI Act Technical Documentation | Enables lawful deployment in European workplace and educational settings under high-risk classification. |
| Direct Platform Integrator Channel | Bypasses VAR networks to capture margin within Microsoft Azure and AWS enterprise contract ecosystems. |
| Multimodal Fusion Architecture | Combines facial micro-expression with vocal prosody models for security screening accuracy. |
| GDPR-Compliant Edge Design | Eliminates cloud biometric consent requirements for European public space deployments. |
Research Methodology
A standing panel of automotive Tier 1 supplier procurement managers, EU regulatory affairs consultants, and edge AI platform engineers provided ongoing calibration across the study period. Primary interviews with CTOs at financial institutions deploying voice analysis, hospital biomedical engineers evaluating digital biomarkers, and hyperscaler partnership directors were cross-referenced against FDA 510(k) filings, EU AI Act implementing act drafts, and automotive OEM production forecasts. Bottom-up deployment volume estimates and top-down venture capital flow analysis were triangulated to anchor market sizing.
Scenario-bracketing around NHTSA mandate timing, EU AI Act enforcement intensity, and Taiwan foundry capacity expansion generated high-low sensitivity bands across the projection horizon. Segmentation dimensions modeled include technology modality, deployment architecture, application safety-criticality, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting against historical adoption curves in adjacent biometric markets, with automotive safety system penetration rates and cloud API consumption metrics as primary demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or EU-China trade policy would shift the trajectory. Forecasts reflect assumptions regarding NPU cost decline curves and ISO certification audit timeline normalization. Material shifts in FDA digital biomarker evidentiary standards or Taiwan export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Global Call Center AI Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market