
 Supermarket AI-Powered Checkout Market | 2026-2036
Supermarket AI-Powered Checkout Market Size, Share, and Industry Trends Forecast 2026-2036
Supermarket AI-Powered Checkout Market Analysis
Edge silicon is expanding its footprint in checkout hardware as GPU and NPU modules replace legacy x86 architectures for on-device inference. Amazon.com Inc. leverages proprietary Just Walk Out sensors across Whole Foods locations, while Standard AI Inc. sustains R&D intensity on retrofit ceiling-mounted vision systems that require no shelf reconfiguration. Toshiba Global Commerce Solutions anchors its position through deep channel control with top-ten global grocers.
Supermarket AI-powered checkout denotes automated transaction systems that employ multi-camera computer vision arrays, weight-sensing shelves, and convolutional neural networks to identify items and process payments without human cashier intervention; typical installations achieve sub-200-millisecond recognition latency per SKU to maintain queue throughput. Self-service kiosks dominate current revenue as the most deployed format, though smart carts capture the fastest expansion trajectory by eliminating fixed infrastructure requirements. Computer vision leads technology adoption while biometric recognition faces slower penetration due to consent complexity and hardware cost.
FCC equipment authorization governs wireless payment transmission in US deployments, while GDPR and the EU AI Act constrain biometric data retention periods and algorithmic transparency across European installations. The US lacks unified federal AI retail regulation, leaving a patchwork of state biometric laws that fragment vendor compliance obligations. Stakeholders must monitor whether emerging FDA food traceability mandates integrate with AI checkout databases to create dual-use data infrastructure requirements.
Market Dynamics
Frictionless checkout deployment hinges on edge AI inference latency reduction, as sub-200-millisecond SKU recognition becomes the baseline for queue throughput in high-volume grocery environments.
Growth Catalysts
- Labor cost compression:Persistent wage inflation across US retail operations accelerates capital reallocation toward autonomous checkout infrastructure.
- GDPR biometric consent frameworks:Clarified opt-in protocols across European installations reduce legal uncertainty and unlock pilot program expansion.
- Smart cart form factor:Elimination of fixed ceiling infrastructure requirements enables retrofit deployment in legacy store footprints without construction downtime.
Market Restraints
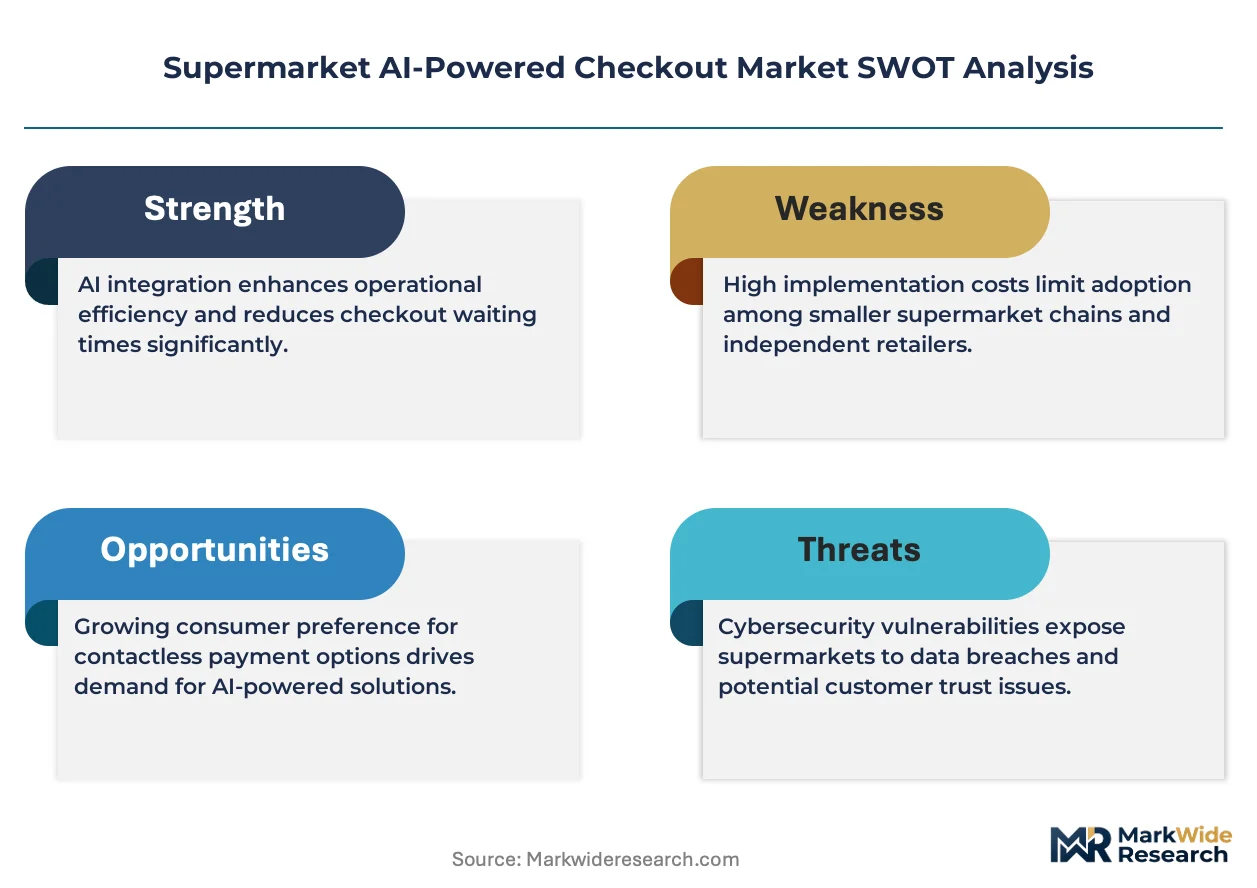
- Silicon supply concentration:GPU and NPU module sourcing depends on Taiwan-based foundry capacity, exposing deployment timelines to geopolitical disruption.
- Biometric hardware cost:Fingerprint and facial recognition sensor arrays add material cost premiums that compress margins in price-sensitive regional grocery segments.
- EU AI Act algorithmic transparency mandates:Convolutional neural network audit requirements impose documentation burdens that extend procurement cycles by months.
Strategic Opportunities
- India FSSAI food traceability integration:AI checkout databases can serve dual-use compliance infrastructure for emerging packaged goods provenance mandates.
- Computer vision-weight sensor fusion:Converging sensor modalities enable fresh produce recognition without barcode dependency, opening untapped self-service categories.
- Germany hypermarket channel:Discounter consolidation creates concentrated buyer power favorable to standardized retrofit system rollouts at scale.
Industry Challenges
- Edge ML engineer scarcity:On-device model optimization for ARM-based NPU architectures requires specialized talent pools concentrated in semiconductor hubs.
- Legacy POS integration complexity:ERP synchronization with decade-old inventory management systems demands custom middleware development per retailer.
- FCC equipment authorization timelines:Wireless payment transmission certification delays compress installation windows for seasonal retail capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supermarket AI-Powered Checkout Market |
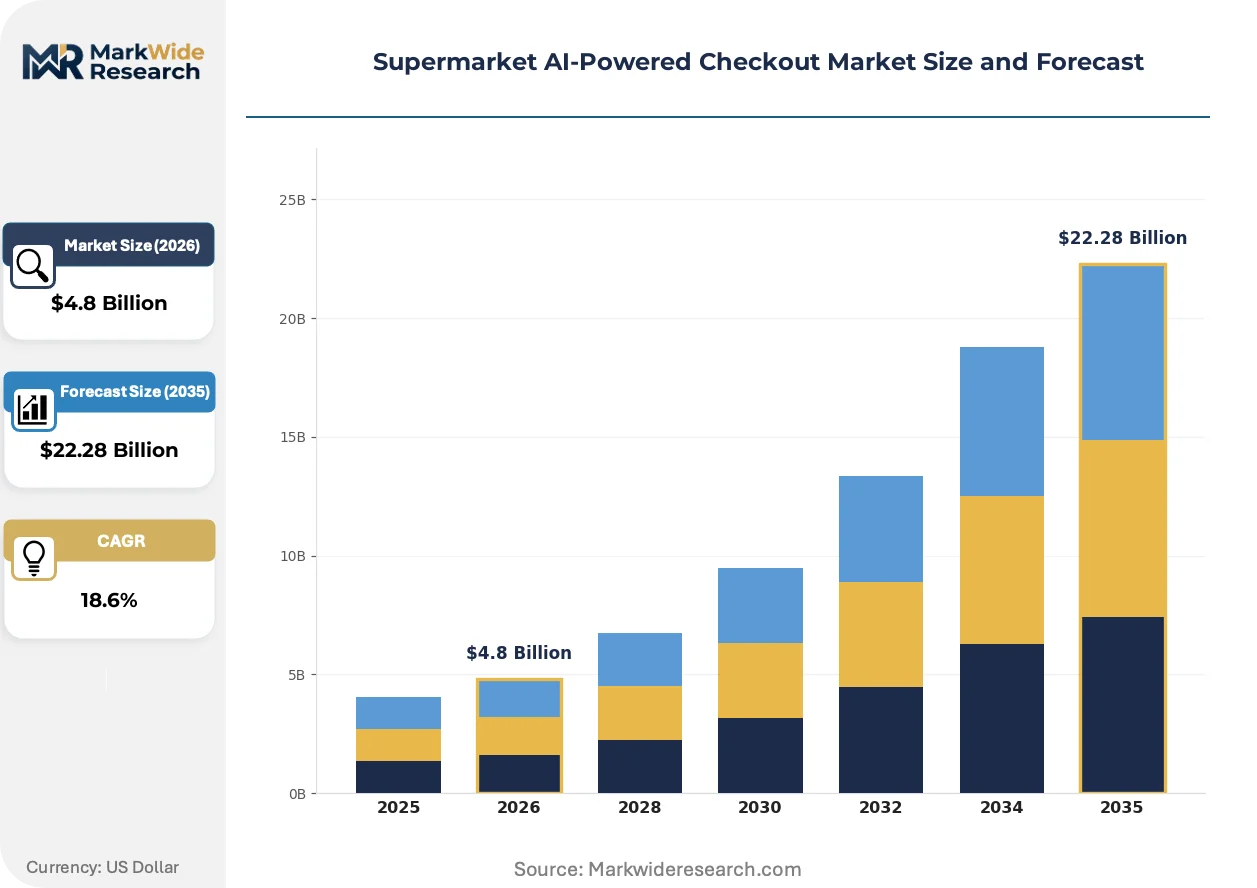
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
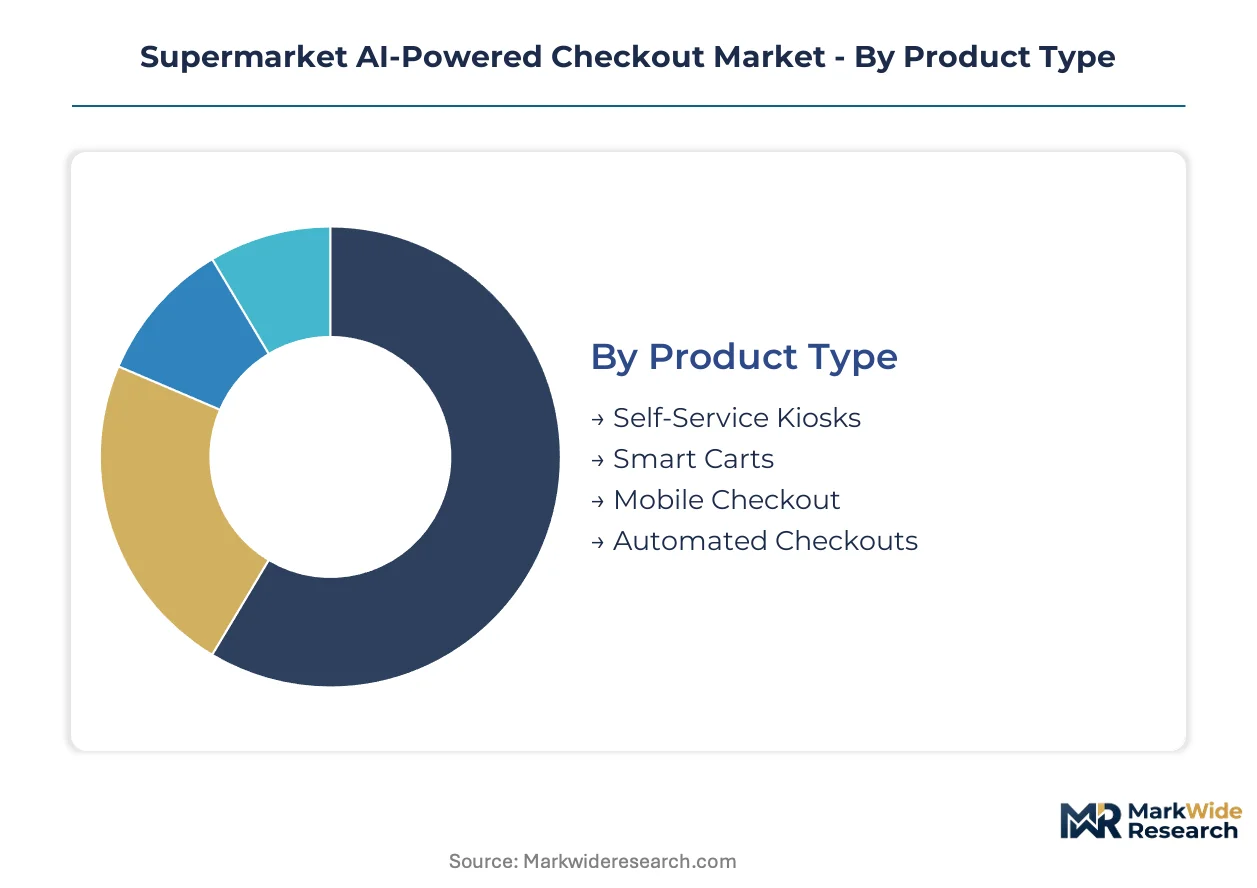
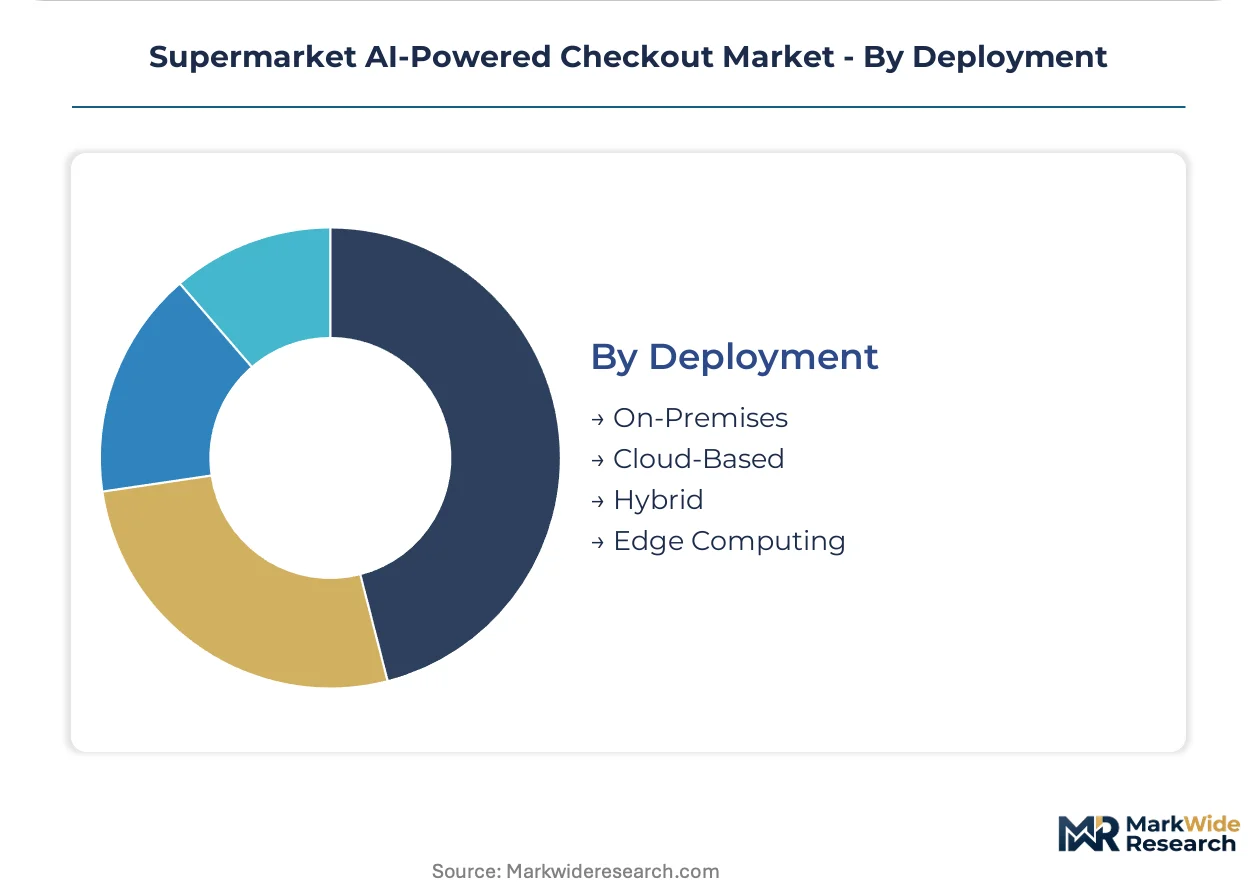
| Segmentation | Product Type: Self-Service Kiosks, Smart Carts, Mobile Checkout, Automated Checkouts Technology: Computer Vision, RFID, Machine Learning, Biometric Recognition End User: Large Supermarkets, Convenience Stores, Hypermarkets, Online Grocery Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | NCR Voyix Corporation, Diebold Nixdorf Inc., Amazon.com Inc., Zippin Inc., Everseen Inc., Standard AI Inc., Toshiba Global Commerce Solutions, Grabango Inc., Trigo Vision Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supermarket AI-Powered Checkout Market Emerging Trajectories
Checkout automation is bifurcating between fixed infrastructure retrofits and mobile form factors, with computer vision architectures becoming the common substrate across both deployment modes.
Multi-camera array edge inference is unifying product recognition, shopper tracking, and loss prevention into single silicon deployments. Tier-one US grocers are adopting these consolidated systems for new-build locations. This convergence is unifying three previously separate vendor relationships into single-source procurement contracts.
EU AI Act algorithmic transparency requirements are mandating convolutional neural network documentation for high-risk biometric applications. Retailers must maintain model training logs and decision boundary specifications for regulator inspection. European installations face the steepest compliance burden, with some operators pausing facial recognition pilots pending legal clarity.
Buyer preference is migrating from ownership models toward performance-guaranteed service contracts. Regional grocery cooperatives now procure recognition accuracy SLAs rather than hardware assets. This shift is most pronounced in the US Midwest, where capital-constrained operators favor opex treatment for checkout automation.
Supermarket AI-Powered Checkout Market Segmentation
Deployment form factor and inference architecture determine capital intensity, retrofit feasibility, and regulatory exposure across grocery automation investments. Segmentation reveals where hardware ownership yields to service-based procurement and which sensor modalities unlock fresh produce categories previously resistant to self-service.
Product Type:
Technology specification dictates infrastructure requirements and retrofit economics across deployment scenarios.
- Self-Service Kiosks:Fixed-location touchscreen terminals with integrated scales and barcode scanners dominate current installed base. Demand concentrates in Germany and United States hypermarket chains seeking queue compression without ceiling reconstruction.
- Smart Carts:Embedded computer vision arrays and weight sensors transform standard shopping carts into mobile checkout nodes. Elimination of fixed infrastructure drives fastest expansion among US regional grocers with legacy store footprints.
- Mobile Checkout:Smartphone-dependent scan-and-go applications leverage existing device penetration.
- Automated Checkouts:Turnkey frictionless exit systems combine ceiling-mounted vision with gated payment zones.
Mature deployment sits with Self-Service Kiosks. Newer deployment is concentrated in Smart Carts.
Technology:
Sensor modality selection shapes recognition accuracy, hardware cost structures, and biometric consent obligations.
- Computer Vision:Multi-camera convolutional neural network arrays achieve sub-200-millisecond SKU identification latency. Adoption concentrates in United States pilot programs at Kroger and Albertsons where produce recognition without barcode dependency opens high-margin categories.
- Machine Learning:On-device model optimization for ARM-based NPU architectures enables real-time inference without cloud dependency. Edge ML engineer scarcity constrains deployment velocity in Taiwan and South Korea semiconductor hubs.
- RFID:Tag-based item identification requires supplier ecosystem coordination.
- Biometric Recognition:Facial and fingerprint authentication faces GDPR consent complexity and hardware cost premiums.
Computer Vision anchors mainstream deployment. Biometric Recognition expansion depends on EU AI Act algorithmic transparency clarification.
End User:
Scale and format determine throughput requirements, loss prevention priorities, and integration complexity with legacy inventory systems.
- Large Supermarkets:Full-service grocers with 40,000+ SKUs require high-accuracy produce recognition and ERP synchronization. Demand clusters in US Midwest cooperatives favoring performance-guaranteed service contracts over hardware ownership.
- Hypermarkets:Discounter consolidation in Germany creates concentrated buyer power favorable to standardized retrofit rollouts.
- Convenience Stores:Limited assortment and space constraints favor compact kiosk formats.
- Online Grocery:Dark store fulfillment centers apply vision systems for order verification rather than customer-facing checkout.
Hypermarkets drive standardization. Large Supermarkets represent the fastest-growing demand source.
Deployment:
Infrastructure location determines latency, data sovereignty exposure, and FCC equipment authorization timelines.
- Edge Computing:On-device GPU and NPU inference eliminates network dependency and reduces GDPR data transfer risk. Taiwan foundry capacity concentration exposes timelines to geopolitical disruption.
- On-Premises:Local server racks maintain sub-50-millisecond response for high-volume locations.
- Cloud-Based:Centralized model training and updates reduce edge ML engineering burden.
- Hybrid:Tiered processing splits inference between device and cloud based on SKU complexity.
Edge Computing leads new-build installations. Cloud-Based deployment climbs fastest among capital-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hypermarket chains concentrate deployment velocity for frictionless checkout systems. Kroger and Albertsons pilot computer vision networks at scale. Regulatory fragmentation across state biometric laws shapes vendor compliance strategies.
United States
Kroger, Albertsons, and regional grocers drive computer vision pilot programs across Midwest and Southeast store networks. FCC equipment authorization governs wireless payment transmission timelines. Chicago and Dallas-Fort Worth metro areas host concentrated retrofit installations for legacy store footprints.
Germany
Discounter consolidation creates concentrated buyer power favorable to standardized retrofit rollouts. GDPR biometric consent frameworks clarify opt-in protocols and reduce legal uncertainty for pilot expansion. Berlin and Munich hypermarket clusters anchor ceiling-mounted vision system deployments.
Japan
Hypermarket chains accelerate frictionless checkout adoption amid persistent labor constraints. METI standards influence edge AI hardware certification requirements. Tokyo-Osaka corridor retailers test smart cart form factors to minimize infrastructure reconstruction.
India
Large supermarket cooperatives explore performance-guaranteed service contracts over hardware ownership models. FSSAI food traceability mandates create dual-use compliance infrastructure opportunities for AI checkout databases. Bangalore and Mumbai retail clusters incubate computer vision-weight sensor fusion pilots for fresh produce recognition.
United Kingdom
Tesco and Sainsbury's trial edge computing deployments to minimize GDPR data transfer risk. UK Information Commissioner's Office guidance shapes biometric retention period compliance. London and Manchester metropolitan stores lead hybrid cloud-edge architecture adoption.
Supermarket AI-Powered Checkout Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pure-play AI vision vendors competing against legacy POS incumbents retrofitting automation capabilities. The vendor base concentrates around three strategic archetypes: ceiling-mounted frictionless systems, smart cart mobile platforms, and self-service kiosk retrofits. M&A activity targets computer vision engineering talent pools. Strategic partnerships between semiconductor foundries and edge AI software houses accelerate NPU-optimized model deployment.
Within the legacy POS incumbent tier, NCR Voyix Corporation and Diebold Nixdorf Inc. occupy positions anchored by deep channel relationships with top-ten global grocers. Amazon.com Inc. represents the vertically integrated technology-architecture archetype through proprietary sensor networks. Among pure-play computer vision specialists, Standard AI Inc. and Trigo Vision Ltd. exemplify the ceiling-mounted retrofit approach that eliminates shelf reconfiguration requirements.
| Leading Market Players |
|---|
| NCR Voyix Corporation |
| Diebold Nixdorf Inc. |
| Amazon.com Inc. |
| Zippin Inc. |
| Everseen Inc. |
| Standard AI Inc. |
| Toshiba Global Commerce Solutions |
| Grabango Inc. |
| Trigo Vision Ltd. |
| Others |
Supply Flow & Price Mechanics
Edge ML engineer concentration in Taiwan and South Korea semiconductor hubs drives labor-cost differentials that widen pricing-tier spreads between premium vision-system vendors and economy kiosk manufacturers.
Pricing Analysis
Volume deployments through US Midwest cooperatives trade margin for market share, while premium smart-cart installations at Kroger and Albertsons capture pricing power through produce-recognition accuracy SLAs. Price differentiation rests on recognition latency guarantees and GDPR compliance documentation depth. Cost compression in the self-service kiosk tier intensifies because regional grocers demand opex-treated service contracts over hardware ownership. Capital-constrained operators exhibit highest price sensitivity; tier-one hypermarket chains with standardized rollout mandates show least.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundry capacity for GPU and NPU modules that anchor edge inference performance. Component sourcing draws from Taiwan, South Korea, and USA for advanced silicon, with camera array manufacturing concentrated in China and Vietnam. Tariff exposure on vision-system hardware threatens margin structures for US-bound deployments. Distribution runs through legacy POS vendor channels at NCR Voyix Corporation and Diebold Nixdorf Inc., with direct procurement emerging among smart-cart specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Proprietary sensor-network control over checkout-data pipelines represents the downstream lever that Amazon.com Inc. and Toshiba Global Commerce Solutions are pursuing.
For Market Incumbents: Deploy channel-control leverage to lock in multi-year retrofit contracts before smart-cart vendors displace fixed-infrastructure demand. Consolidate ceiling-mounted vision engineering talent through targeted acquisitions in Israel and UK computer vision clusters. Biometric consent complexity across EU installations threatens margin expansion for facial-recognition pilots. For New Entrants and Emerging Players: The 40-60% price-point gap between Amazon Just Walk Out deployments and regional grocer kiosk budgets opens white-space at the mid-market service-contract tier. India's FSSAI traceability mandate creates the most penetrable geography for dual-use database propositions. Target computer vision-weight sensor fusion for fresh produce as the go-to-market angle that bypasses barcode infrastructure entirely. For Investors and Strategic Acquirers: Re-rating potential sits with edge-AI software houses possessing NPU-optimized model libraries given the scarcity of ARM-based inference engineering talent. Long-term viability favors vendors with hybrid cloud-edge architectures that satisfy both latency-sensitive hypermarkets and capital-constrained cooperatives. Acquisition target archetype: computer vision specialists with existing FDA-adjacent food traceability integrations. The signal to watch is FCC equipment authorization timeline compression as indicator of seasonal capex cycle capture.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Cart Platform Integration | Eliminates fixed infrastructure requirements for legacy store footprints across US regional grocers. |
| Edge AI Chip Supply Agreement | Secures NPU module allocation from Taiwan foundries amid geopolitical capacity constraints. |
| GDPR Compliance Certification Program | Unlocks European pilot expansion through clarified biometric consent documentation standards. |
| Produce Recognition R&D Partnership | Fuses computer vision with weight sensors to open high-margin fresh categories without barcodes. |
| Performance-Guaranteed Service Contract | Converts capital-constrained Midwest cooperatives from hardware ownership to opex-based procurement. |
Methodological Framework
Independent corroboration across edge AI hardware vendors, supermarket technology procurement officers, and semiconductor foundry account managers underwrites the qualitative findings. Primary interviews with computer vision engineering leads, grocery cooperative CIOs, and legacy POS integration specialists combined with secondary validation through FCC equipment authorization filings, EU AI Act regulatory guidance documents, and hyperscaler retail capex disclosures. Bottom-up deployment tracking across Kroger, Albertsons, and Germany discounter networks triangulates against top-down market sizing.
Comparable-period anchoring to 2021-2023 pilot program rollouts established baseline adoption curves across the projection horizon. Segmentation dimensions modeled include deployment form factor, inference architecture, end-user scale tier, and regional regulatory cluster. CAGRs were derived from install-base velocity analysis and capital-commitment pipeline tracking. Industry-specific forecast inputs incorporate edge silicon lead times and EU AI Act algorithmic transparency compliance timeline assumptions.
Inputs from semiconductor foundry production schedules and grocery retailer capex plans were available through the study window; gaps in private smart-cart pilot performance data introduce uncertainty bands around adoption trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Cognitive Computing Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
Edge AI Software Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market