
 Model Validation and Automation Market | 2026-2036
Model Validation and Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Model Validation and Automation Market Analysis
Financial services demand is shifting toward continuous model monitoring as banks face intensifying supervisory scrutiny. UiPath leverages its robotic process automation foundation to extend into governance-heavy validation workflows. IBM Corporation anchors enterprise trust through its integrated AI governance stack. Microsoft Corporation competes by embedding automated validation within cloud-native analytics environments.
Model validation and automation encompasses software systems, tools, frameworks, and platforms that verify statistical and machine learning models against predefined accuracy, fairness, and stability thresholds through automated testing pipelines, version control, and documentation generation. These systems primarily serve regulated industries that must demonstrate reproducibility and defensible decision logic to auditors and supervisors. Software solutions dominate current spending as enterprises prioritize configurable platforms over point tools. Cloud-based deployment is accelerating fastest among mid-market adopters seeking elastic compute for large-scale model backtesting. Risk management applications capture the deepest margin pools given the complexity of credit and market model validation requirements.
The Federal Reserve's SR 11-7 guidance, the EU AI Act's conformity assessment requirements, and the Basel Committee's principles on model risk management collectively shape procurement priorities and technical specifications. FDA scrutiny of AI-enabled diagnostic algorithms further extends validation automation into healthcare compliance workflows. Stakeholders must weigh interoperability investments against the fragmentation emerging from jurisdiction-specific audit trail standards.
Market Dynamics
Regulatory fragmentation across jurisdictions is forcing financial institutions to rebuild validation infrastructure around explainability mandates rather than retrospective testing cycles.
Growth Catalysts
- EU AI Act Conformity Assessments:High-risk AI system classifications mandate automated documentation pipelines that financial institutions must deploy to satisfy notified body requirements.
- Continuous Monitoring Architecture:Banks are replacing point-in-time validation with real-time drift detection systems that trigger automated retraining protocols.
- Credit Risk Model Complexity:Basel Committee principles on model risk management require deeper backtesting infrastructure for internal ratings-based approaches.
Market Restraints
- Specialized Talent Scarcity:The intersection of quantitative modeling and software engineering commands premium compensation that mid-market vendors struggle to match.
- Cloud Concentration Risk:Three hyperscale providers dominate elastic compute for large-scale model simulation, creating single-point-of-failure exposure.
- Interpretability Trade-offs:Complex ensemble methods achieve predictive accuracy but resist automated explanation generation required by supervisory guidance.
Strategic Opportunities
- Healthcare Diagnostic Algorithms:FDA scrutiny of AI-enabled medical devices extends validation automation into clinical workflow compliance.
- Synthetic Data Generation:Privacy-preserving simulation techniques enable stress testing without exposing production customer records.
- API-First Validation Services:Embedded model monitoring through standardized interfaces allows fintechs to outsource governance infrastructure.
Industry Challenges
- Legacy System Integration:Decades-old core banking platforms resist API connectivity required for continuous validation pipelines.
- Cross-Border Audit Trail Standards:Jurisdiction-specific documentation formats fragment platform development roadmaps.
- Model Inventory Harmonization:Thousands of undocumented shadow models accumulated during rapid AI deployment must be catalogued retrospectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Model Validation and Automation Market |
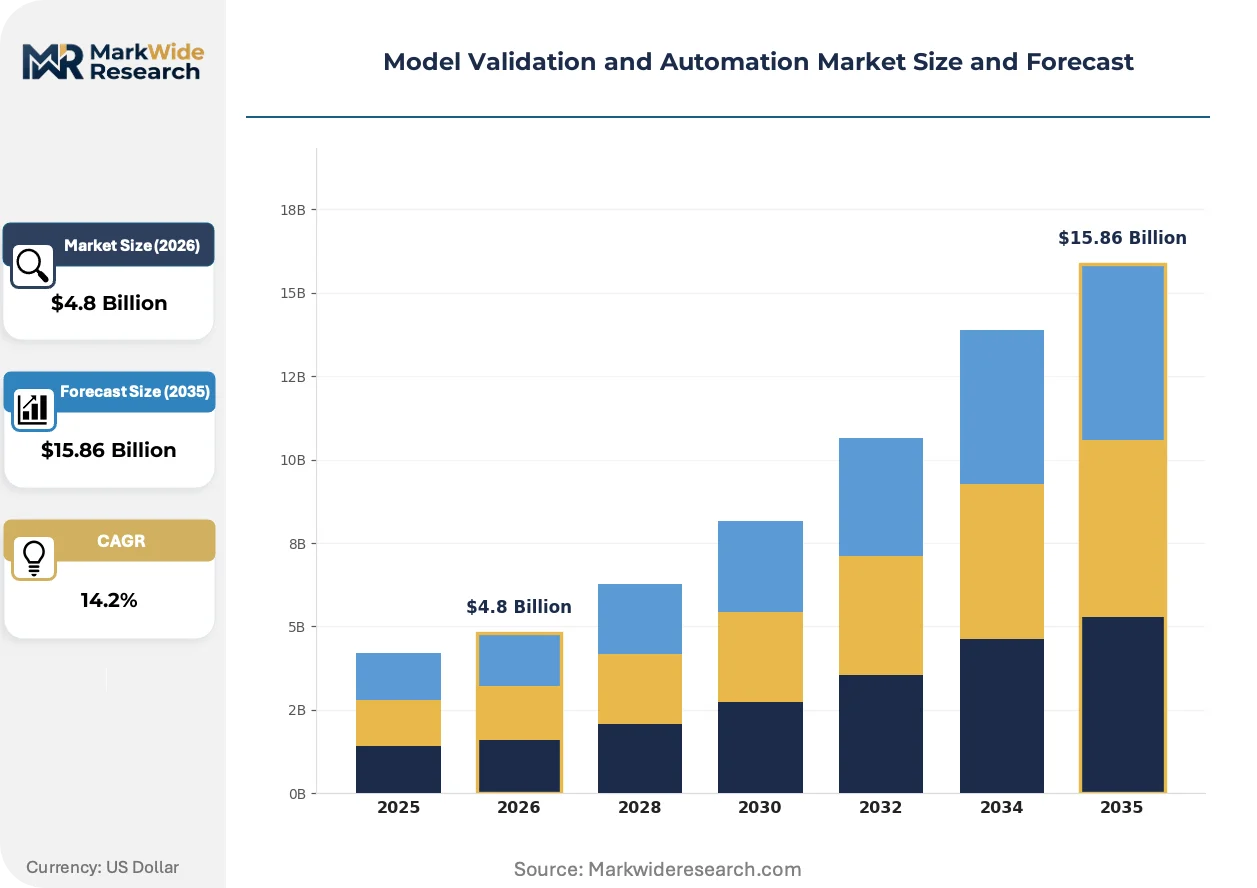
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Software, Tools, Frameworks, Platforms End User: Financial Services, Technology Firms, Healthcare Organizations, Government Agencies Application: Risk Management, Compliance, Fraud Detection, Data Analytics Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Tenant |
| Companies Covered | HCL Technologies Limited, Microsoft Corporation, International Business Machines (IBM) Corporation, Pegasystems Inc, UiPath, NICE Ltd, Blue Prism Limited, Automation Anywhere Inc, Hewlett Packard Enterprise Development Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Model Validation and Automation Market Emerging Trajectories
Automation vendors are converging on unified governance platforms that collapse the historical separation between model development, validation, and deployment workflows.
Explainable AI middleware is consolidating previously siloed interpretability methods into standardized attribution engines. Tier-one banks are embedding these layers directly into model serving infrastructure. This consolidation is compressing procurement cycles as buyers reject point-solution vendors lacking integrated governance stacks.
The EU AI Act's risk-based classification system is redrawing procurement specifications across European financial services. High-risk system designations now trigger mandatory conformity assessments that automated platforms must document. German and French supervisors are issuing supplementary guidance on algorithmic accountability that extends beyond the baseline regulation.
Enterprise buyers are unbundling validation services from core software licenses and contracting specialized third-party attestation providers. This pattern is most pronounced among asset managers seeking independent model risk opinions for investor due diligence. London and New York asset management clusters are driving demand for outsourced validation-as-a-service arrangements.
Model Validation and Automation Market Segmentation
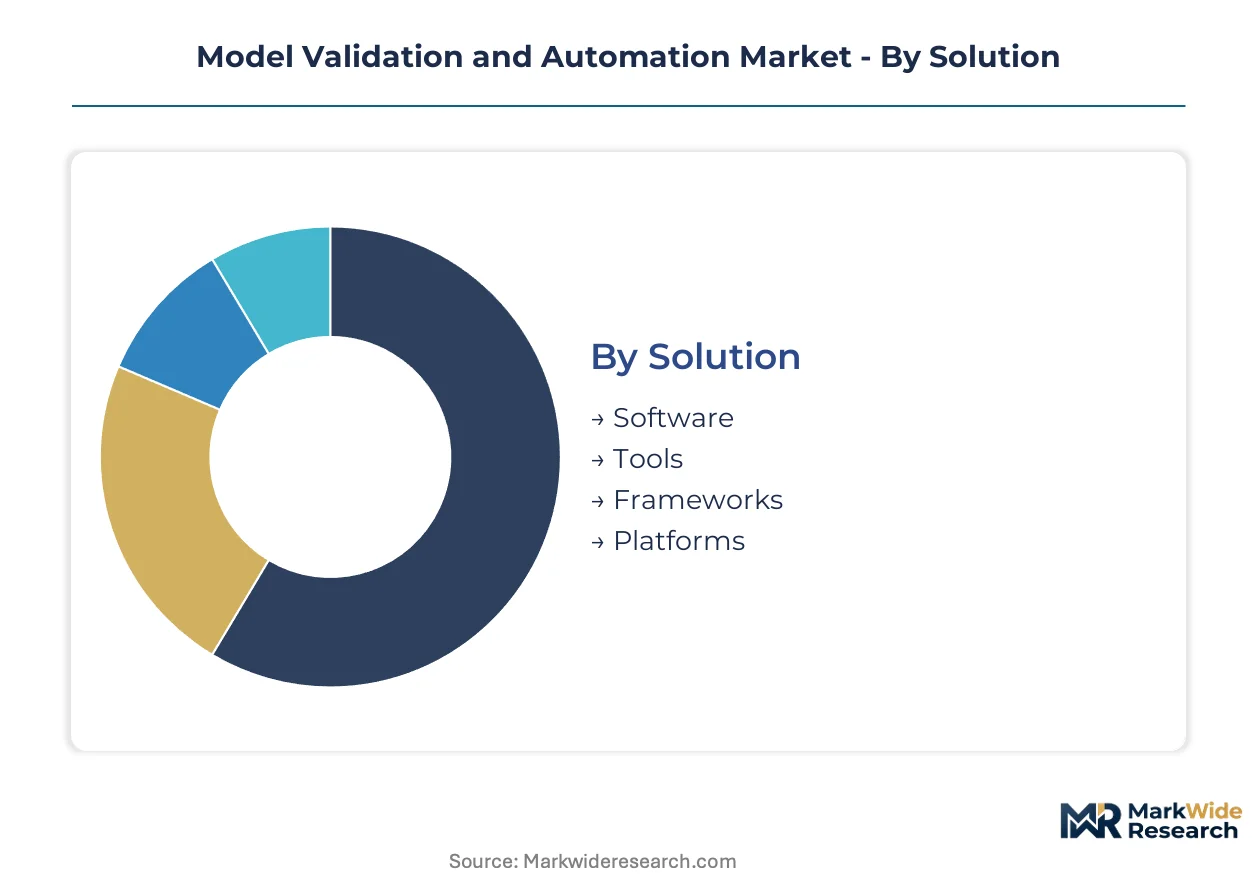
Segmentation reveals how procurement priorities diverge across regulated industries. Financial institutions prioritize configurable governance stacks over standardized tools. Healthcare buyers demand embedded compliance documentation that satisfies FDA audit protocols.
Solution:
Standardized frameworks lower entry costs for mid-market adopters, while configurable platforms command premium pricing from tier-one banks requiring bespoke validation pipelines.
- Software:Enterprise-grade applications automate model testing, version control, and documentation generation through integrated pipelines. Tier-one banks in the United States deploy these systems to satisfy Federal Reserve SR 11-7 guidance on continuous monitoring obligations.
- Tools:Point solutions address discrete validation tasks such as drift detection or bias auditing. Technology firms in California integrate these into existing MLOps stacks to accelerate deployment cycles without full platform replacement.
- Frameworks:Open-source and commercial libraries provide reusable validation components for custom development environments.
- Platforms:Unified governance environments collapse development, validation, and deployment workflows into single vendor relationships.
Most installed capacity flows through Software. Expansion is steepest in Platforms.
End User:
Risk-adjusted procurement budgets vary dramatically across these sectors, with financial services allocating the deepest investment pools and government agencies facing longest sales cycles.
- Financial Services:Banks, insurers, and asset managers deploy validation automation to satisfy Basel Committee principles and investor due diligence requirements. JPMorgan Chase and Goldman Sachs maintain dedicated model risk teams exceeding five hundred professionals each.
- Technology Firms:Cloud providers and AI-native companies embed validation into product offerings to demonstrate algorithmic accountability to enterprise customers.
- Healthcare Organizations:Hospitals and diagnostic device manufacturers face FDA scrutiny of AI-enabled algorithms, driving investment in automated documentation for 510(k) submissions and post-market surveillance.
- Government Agencies:Defense and civilian departments require validated models for benefit allocation, threat detection, and resource optimization, with procurement constrained by federal acquisition regulations.
Financial Services dominates current procurement volumes. Healthcare Organizations show the sharpest upward trajectory.
Application:
Margin profiles align with technical complexity, where risk management applications capture the deepest value pools and fraud detection commands the fastest deployment timelines.
- Risk Management:Credit, market, and operational model validation demands sophisticated backtesting infrastructure and regulatory-grade documentation. European banks under ECB supervision invest heavily here to satisfy internal ratings-based approach requirements.
- Compliance:Automated audit trail generation and conformity assessment documentation serve EU AI Act high-risk system obligations. German manufacturers deploy these capabilities to satisfy notified body requirements for algorithmic decision systems.
- Fraud Detection:Real-time transaction monitoring systems require continuous model recalibration and automated threshold adjustment.
- Data Analytics:Exploratory model validation supports marketing optimization and operational forecasting with lighter regulatory burden.
Risk Management absorbs the largest share of enterprise spending. Compliance applications are gaining share fastest.
Deployment:
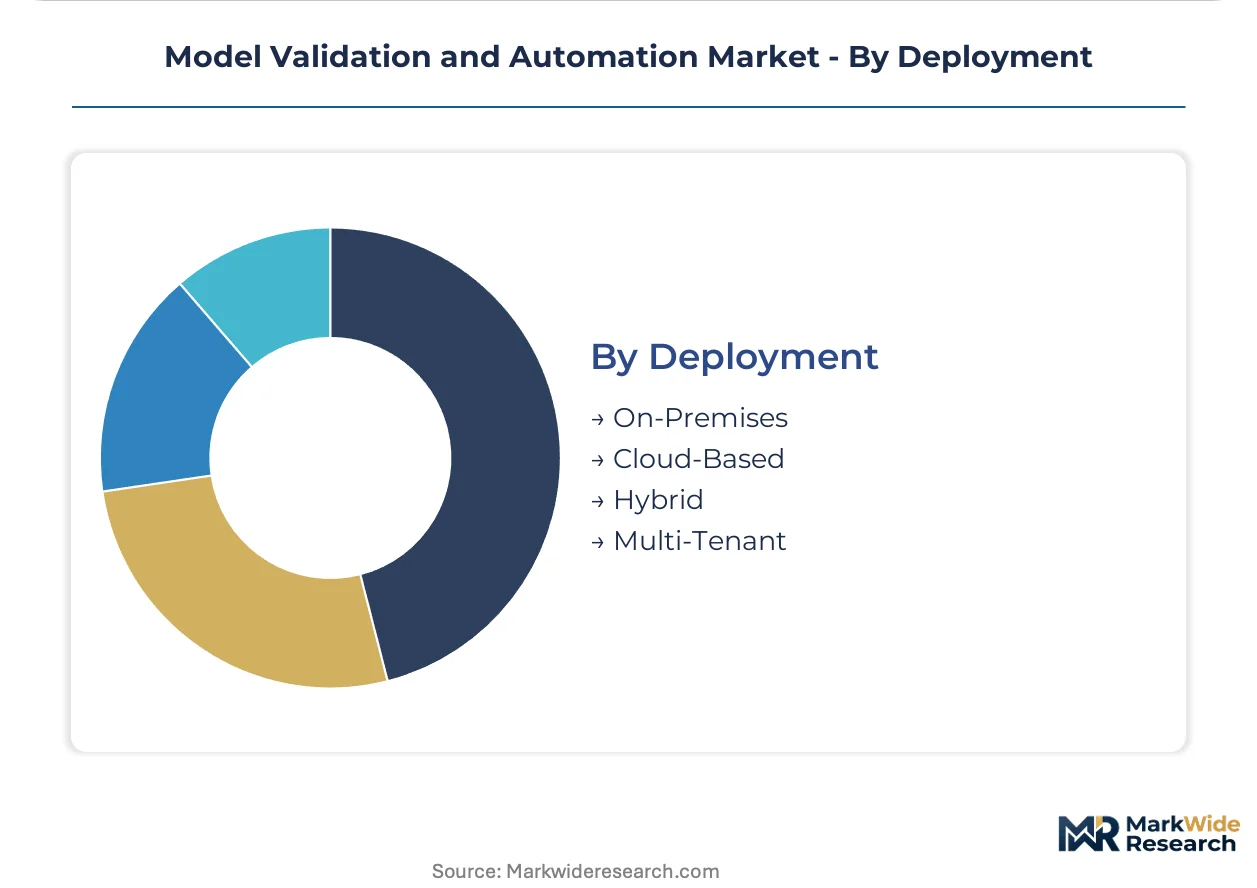
Elastic compute economics favor cloud architectures for simulation-heavy workloads, while data residency requirements preserve on-premises demand among defense and healthcare buyers.
- On-Premises:Dedicated hardware installations satisfy classified processing requirements and strict data localization mandates. Pentagon agencies and Swiss private banks maintain these configurations despite higher total cost of ownership.
- Cloud-Based:Elastic provisioning supports large-scale Monte Carlo simulations and parallel model backtesting without capital expenditure. Mid-market fintechs in Singapore and London prefer this model for rapid scaling.
- Hybrid:Split architectures keep sensitive training data on-premises while leveraging cloud compute for validation orchestration.
- Multi-Tenant:Shared infrastructure platforms reduce per-organization costs through standardized validation-as-a-service offerings.
Cloud-Based deployments host the majority of new implementations. Hybrid configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New York-Washington corridor anchors procurement concentration for model validation infrastructure, driven by federal banking supervision and asset management clustering. Regulatory divergence across major economies is fragmenting platform specifications and reshaping vendor roadmaps. Enterprise buyers in each jurisdiction prioritize compliance architectures aligned to local supervisory mandates.
United States
The Federal Reserve's SR 11-7 guidance and OCC model risk management bulletins compel tier-one banks to deploy continuous monitoring systems. JPMorgan Chase and Goldman Sachs maintain model risk teams exceeding five hundred professionals each in Manhattan. The SEC's scrutiny of AI-enabled investment advice extends validation automation into wealth management compliance workflows.
Germany
BaFin's algorithmic trading guidelines and the EU AI Act's high-risk system classifications drive demand for automated conformity documentation. Deutsche Bank and Commerzbank invest heavily in backtesting infrastructure to satisfy ECB internal ratings-based approach requirements. The Frankfurt financial cluster hosts specialized validation-as-a-service providers serving asset managers.
United Kingdom
The Bank of England's expectations for model risk management and the Financial Conduct Authority's consumer duty rules shape procurement specifications. London's asset management cluster drives demand for independent third-party model attestation services. The Prudential Regulation Authority's stress testing mandates require automated documentation pipelines for regulatory submissions.
Singapore
The Monetary Authority of Singapore's FEAT principles for AI fairness and ethics guide fintech validation architecture decisions. Mid-market financial institutions in the city-state prefer cloud-based deployment for elastic compute in Monte Carlo simulations. The Singapore Exchange's algorithmic trading rules necessitate real-time model monitoring for member firms.
Switzerland
FINMA's circulars on operational risk and outsourcing require Swiss private banks to maintain defensible model documentation for supervisory review. Zurich and Geneva private banking clusters preserve on-premises validation infrastructure despite higher total cost of ownership. The country's data localization mandates restrict cloud migration for sensitive credit risk models.
Model Validation and Automation Market Vendor Landscape
Platform consolidation dominates the current landscape as buyers reject point-solution vendors lacking integrated governance stacks. The vendor base organizes around three strategic archetypes: robotic process automation incumbents extending into validation workflows, cloud-native analytics providers embedding governance layers, and specialized model risk consultancies productizing attestation services. M&A activity and strategic partnerships represent the primary competitive vectors as incumbents acquire explainable AI capabilities and fintechs outsource infrastructure.
Within the automation-native tier, UiPath and Automation Anywhere exemplify vendors leveraging robotic process automation foundations to penetrate governance-heavy validation workflows. IBM Corporation occupies a position anchoring enterprise trust through integrated AI governance stacks. Microsoft Corporation represents the cloud-native archetype competing through embedded validation within analytics environments.
| Leading Market Players |
|---|
| HCL Technologies Limited |
| Microsoft Corporation |
| International Business Machines (IBM) Corporation |
| Pegasystems Inc |
| UiPath |
| NICE Ltd |
| Blue Prism Limited |
| Automation Anywhere Inc |
| Hewlett Packard Enterprise Development Ltd |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity documentation mandates gate qualified supply relationships and premium-tier pricing access for model validation platforms, forcing mid-market vendors toward standardized frameworks while tier-one banks absorb bespoke premium costs. Pricing pressure feeds back into supply chain consolidation as hyperscale cloud providers capture elastic compute margins from simulation-heavy validation workloads.
Pricing Analysis
Distributor margins in the model validation software channel compress to single digits for cloud-native platforms sold direct-to-enterprise, while systems integrators capture fifteen to twenty percent attach rates for implementation services. SaaS-tiered subscription structures dominate, with price differentiation driven by audit-grade certification tier and customization depth for regulatory jurisdiction. Pricing pressure stems from open-source framework commoditization of basic drift detection capabilities. Mid-market fintechs exhibit highest price sensitivity; tier-one banks under Federal Reserve scrutiny demonstrate lowest.
Supply Chain Analysis
Regional distribution centers for model validation software concentrate in Ireland for EU AI Act compliance workflows, Singapore for Asia-Pacific fintech deployment, and Virginia for US federal contracting accessibility. The supply chain draws from specialized GPU clusters in Taiwan, proprietary explainability IP in the United States, and regulatory consulting talent in the United Kingdom. Single-source vulnerability concentrates in hyperscale cloud compute for large-scale Monte Carlo backtesting. Distribution runs through direct enterprise sales with systems integrator overlay for legacy banking platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in model validation and automation rests on cloud infrastructure cost curves flattening and premium-tier demand concentrating among tier-one banks facing intensifying supervisory documentation requirements.
For Market Incumbents: Anticipate open-source explainability frameworks commoditizing point-solution drift detection, and respond by deepening vertical integration into regulatory consulting services while anchoring platform stickiness through API-embedded validation orchestration that locks in continuous monitoring revenue streams. For New Entrants and Emerging Players: Enter via healthcare diagnostic algorithm validation, where FDA 510(k) documentation automation remains underpenetrated relative to financial services saturation, and pursue a validation-as-a-service model targeting mid-market device manufacturers lacking in-house model risk teams. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized model risk consultancies productizing attestation services, with long-term viability hinging on EU AI Act enforcement breadth expanding beyond financial services into manufacturing and public sector procurement. The signal to watch is notified body accreditation timelines for high-risk AI system conformity assessments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | UiPath and IBM consolidate explainable AI middleware into unified governance stacks for tier-one banks. |
| Acquisition of Specialist Firm | Cloud-native vendors purchase regulatory consulting boutiques to embed conformity assessment expertise. |
| Strategic Partnership | Microsoft Azure partners with ECB-supervised institutions for internal ratings-based approach validation tooling. |
| Geographic Expansion | Validation-as-a-service providers establish Singapore hubs to serve MAS FEAT-guided fintech compliance. |
| Product Launch | Synthetic data generation modules launch to enable privacy-preserving stress testing without production exposure. |
Methodological Framework
Multiple input streams — structured interviews with model risk officers at tier-one banks, regulatory affairs leads at AI governance software vendors, and procurement managers at healthcare device manufacturers — were reconciled against secondary validation from SEC filings of publicly traded automation vendors, EU AI Act implementation guidance documents, and Federal Reserve SR 11-7 supervisory letters. Bottom-up sizing of software license revenue and top-down triangulation against aggregate IT risk management spending produced convergent estimates across the analysis window.
Cross-referencing historical adoption curves against panel input from chief technology officers at asset management firms yielded the projection framework. Segmentation dimensions modeled include deployment architecture, end-user industry vertical, application complexity tier, and regional regulatory cluster. CAGRs were derived from slope consistency across adjacent technology adoption cycles and validated against disclosed growth rates in comparable governance software categories. Industry-specific forecast inputs encompassed Basel Committee model risk management principle revision timelines and FDA AI-enabled device submission volume trajectories.
Inputs from notified body accreditation databases and cloud hyperscaler capex disclosures were available through the study window; gaps in shadow model inventory quantification at legacy banks introduce uncertainty bands around compliance-driven replacement demand estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and supervisory guidance evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Intelligent Personal Assistant Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
AI Recruitment Market