
 Edge AI Hardware Market | 2026-2036
Edge AI Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Edge AI Hardware Market Intelligence
The shift towards asset-light, subscription-based models for deploying AI capabilities is reshaping competitive positioning for hardware vendors. This model allows smaller enterprises to access advanced technology without large capital outlays. Qualcomm Technologies, Inc. specializes in power-efficient processors for mobile and IoT devices. NVIDIA Corporation dominates the high-performance accelerator segment, crucial for complex training and inference tasks. Intel Corporation competes with a diverse portfolio spanning CPUs, FPGAs, and dedicated AI ASICs.
Edge AI hardware comprises specialized semiconductor components designed to process machine learning algorithms directly on a device, independent of centralized cloud servers. These components, including processors and accelerators, are engineered for low-latency data processing and minimal power consumption. Their primary purpose is to enable real-time analytics and decision-making in applications like autonomous vehicles and industrial automation. Accelerators are the fastest-growing product type, essential for handling complex AI models. The automotive and manufacturing end-user segments are driving substantial volume.
Data privacy regulations, including the EU's GDPR, influence hardware design by favoring on-device processing to limit personal data transmission. In the United States, NHTSA guidelines for autonomous systems create demand for redundant and fail-safe hardware components. Standards from bodies like the ISO and IEC ensure interoperability and safety across different systems and geographies. Stakeholders must continuously balance the demand for higher computational performance against strict thermal and power consumption envelopes.
Market Dynamics
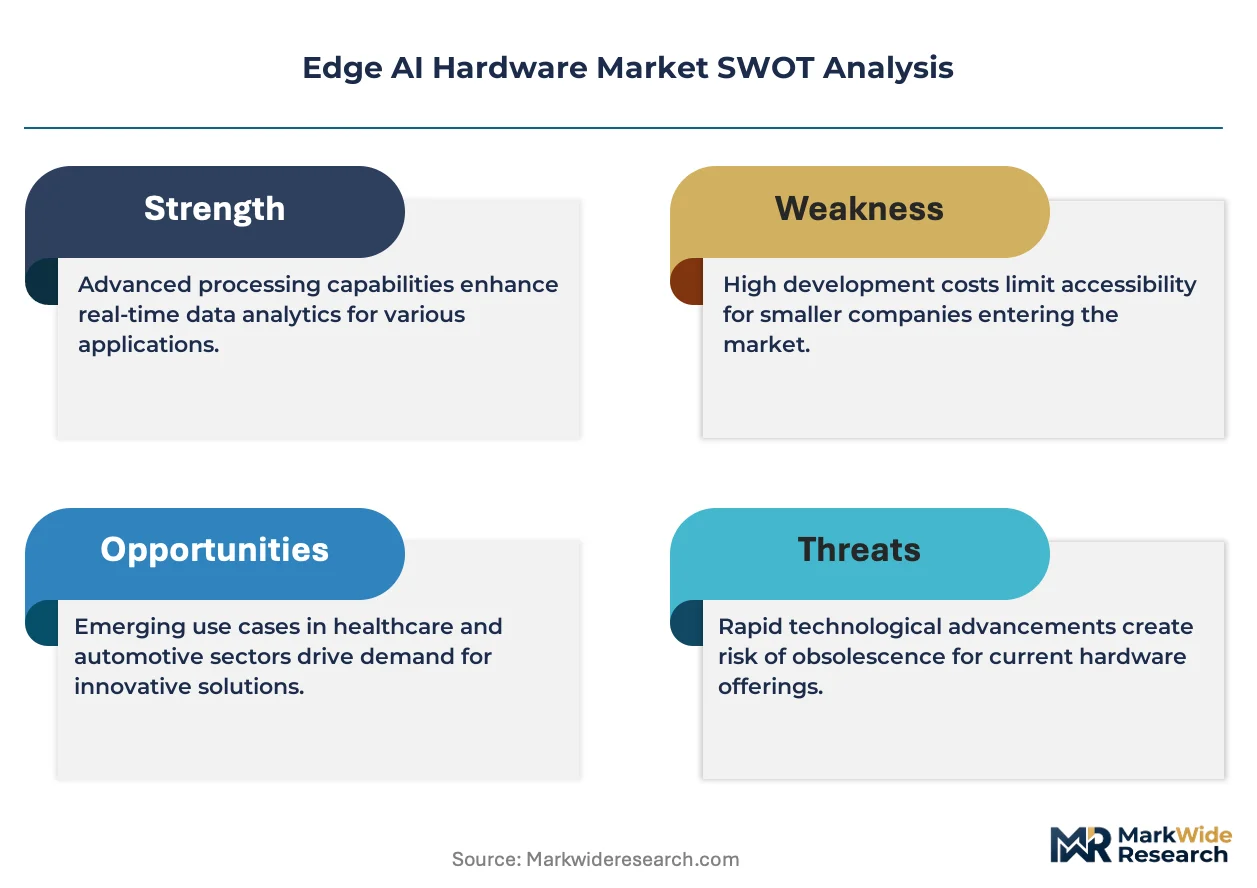
The central tension in the edge AI hardware market is the conflict between demand for greater on-device computational power and the physical constraints of power consumption and thermal management in compact form factors. This dynamic forces continuous innovation in chip architecture and materials science to meet performance requirements.
Growth Catalysts
- 5G Infrastructure Expansion:The rollout of 5G provides the low-latency connectivity essential for real-time edge AI applications like autonomous vehicles.
- Automotive Sector Integration:Demand for advanced driver-assistance systems (ADAS) and in-cabin monitoring drives volume adoption of specialized edge processors.
- National Digitalization Policies:Government initiatives in China and Germany supporting smart manufacturing create large-scale demand for industrial edge AI hardware.
Market Restraints
- Thermal and Power Constraints:The physical limits of heat dissipation and power draw in small form factors cap the computational performance of edge hardware.
- High ASIC Development Costs:The substantial non-recurring engineering costs for custom AI ASICs create high barriers to entry, favoring large-scale vendors.
- Software Fragmentation:A lack of standardized software frameworks across different hardware accelerators complicates application development and portability for engineers.
Strategic Opportunities
- Personalized Healthcare Devices:Edge AI enables on-device analysis for medical wearables, ensuring patient data privacy and delivering real-time health alerts.
- Autonomous Systems in Logistics:The expansion of e-commerce creates opportunities for autonomous mobile robots that rely on low-latency edge processing in warehouses.
- Precision Agriculture:Underpenetrated markets in the Americas exist for edge AI in crop monitoring, pest detection, and automated harvesting machinery.
Industry Challenges
- Specialized Talent Shortage:A scarcity of engineers skilled in both hardware architecture and machine learning model optimization creates a significant development bottleneck for vendors.
- Legacy System Integration:Integrating new edge AI components with existing industrial control systems and enterprise IT infrastructure is complex and slows enterprise adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge AI Hardware Market |
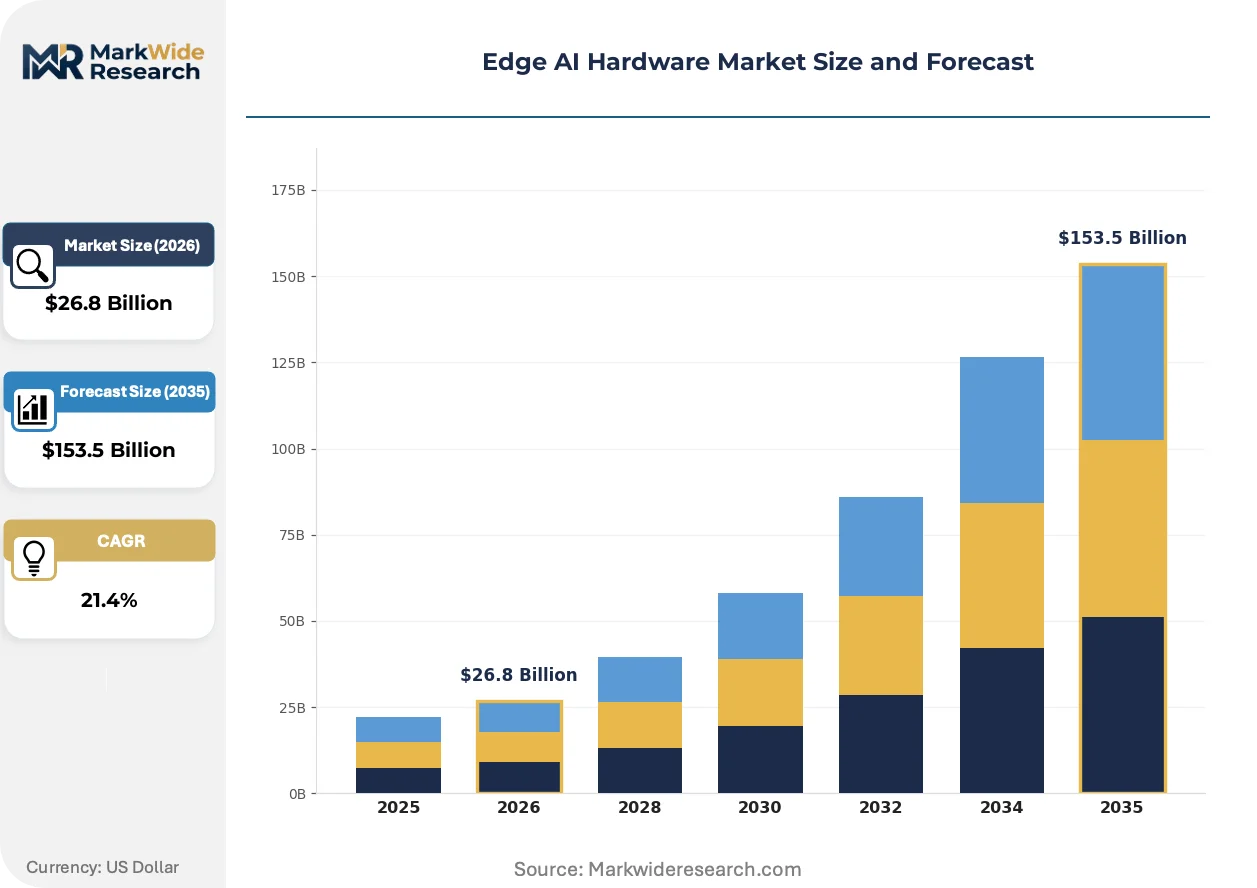
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $153.5 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processors, Accelerators, Servers, Gateways Technology: Computer Vision, Natural Language Processing, Machine Learning, Robotics End User: Manufacturing, Automotive, Retail, Healthcare Deployment Model: On-premises, Hybrid, Cloud-based, Virtualized |
| Companies Covered | Qualcomm Technologies, Inc., NVIDIA Corporation, Intel Corporation, Apple Inc., Samsung Electronics Co., Ltd., Huawei Technologies Co., Ltd., MediaTek Inc., Advanced Micro Devices, Inc., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge AI Hardware Market Strategic Shifts & Innovations
A defining market evolution is the push for specialized, application-specific hardware that balances extreme processing power with stringent energy efficiency. This drive prioritizes moving complex AI model execution from centralized clouds directly to the data source.
Neuromorphic computing architectures are designed to mimic the human brain's structure for highly efficient, low-power pattern recognition. This technology is gaining traction in advanced robotics and sensor fusion applications where power budgets are minimal. This architectural innovation is collapsing the traditional separation between memory and processing, enabling more powerful computation directly on the device.
The European Union's General Data Protection Regulation (GDPR) imposes strict rules on how personal data is collected, processed, and transferred. This policy directly incentivizes hardware designs that perform analysis on-device, minimizing the need to send sensitive information to cloud servers. The consumer electronics and automotive segments are most affected, prioritizing local processing to ensure compliance.
Enterprises are increasingly adopting subscription-based Hardware-as-a-Service (HaaS) models to deploy AI capabilities. This approach displaces large, upfront capital expenditures, allowing companies to use the latest AI accelerators through more flexible operational budgets. This shift is most prominent in industrial IoT and smart retail, where organizations seek to scale AI deployments without major hardware ownership risks.
Edge AI Hardware Market Segmentation
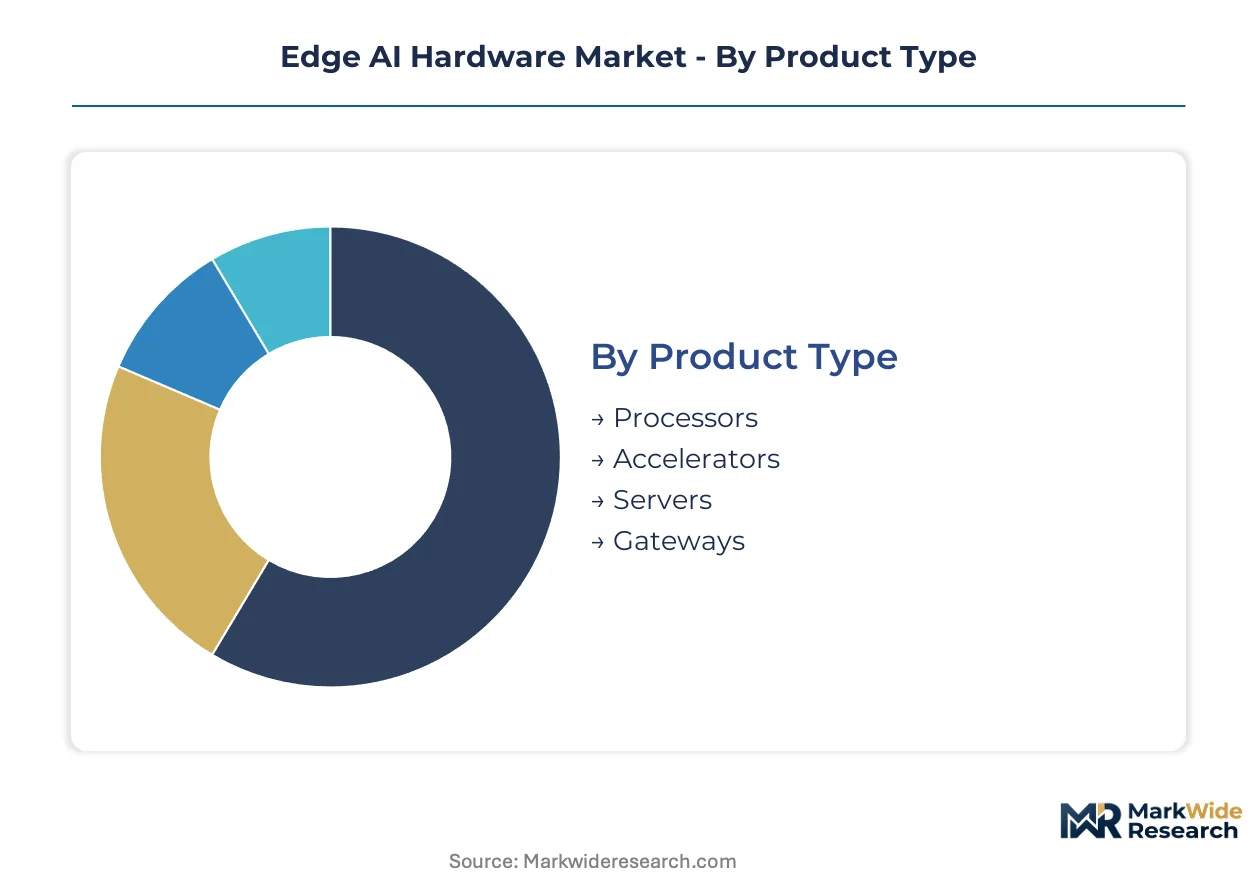
The Edge AI Hardware Market segmentation provides a granular view of the specialized components and deployment strategies driving real-time intelligence. Understanding these distinct segments helps stakeholders identify specific growth vectors and technological requirements across diverse applications. Each category reflects unique demands for computational power, energy efficiency, and integration capabilities.
Product Type:
The hardware component dimension delineates the core physical units enabling edge AI processing, each optimized for different performance and power envelopes.
- Accelerators:These specialized co-processors, such as GPUs and ASICs, are engineered for high-performance parallel computing, essential for complex AI model inference and training at the edge. Demand is expanding most quickly in automotive ADAS and industrial automation sectors requiring rapid data processing.
- Processors:CPUs and NPUs form the foundational computing layer, handling general-purpose tasks and orchestrating AI workloads directly on edge devices. These components are critical for mobile and IoT applications where power efficiency is paramount, particularly in consumer electronics.
- Servers:Edge servers provide robust computing resources for localized data centers and larger industrial deployments, supporting multiple AI applications simultaneously. These systems are crucial for smart factories and telecommunications infrastructure, managing aggregated edge data.
- Gateways:Edge gateways act as intermediaries, connecting diverse IoT devices to the network and performing initial data filtering and processing before transmission. They are vital for smart city initiatives and remote asset monitoring, ensuring secure data flow.
Accelerators hold installed capacity. Processors are rotating up the share rankings.
Technology:
The technology segment outlines the specific AI capabilities that edge hardware is designed to support, reflecting diverse application requirements.
- Machine Learning:This category encompasses hardware optimized for executing various machine learning algorithms, including deep learning and neural networks, directly on devices. It underpins predictive maintenance in manufacturing and personalized recommendations in retail, ensuring rapid local decision-making.
- Computer Vision:Hardware tailored for processing visual data enables real-time object detection, facial recognition, and scene understanding without cloud reliance. Autonomous vehicles and surveillance systems are primary drivers for this technology, demanding high-speed image analysis.
- Natural Language Processing:Edge AI hardware supporting NLP processes human language for tasks like voice commands, sentiment analysis, and translation locally. Smart assistants and customer service bots on devices benefit from this on-device capability, enhancing user experience.
- Robotics:Specialized hardware for robotics facilitates real-time sensor fusion, path planning, and motor control, allowing autonomous robots to operate efficiently. Logistics and precision agriculture are key end-user segments adopting these advanced robotic systems.
Computer Vision represents the fastest-growing trajectory. Machine Learning maintains significant market presence.
End User:
End-user segmentation clarifies the primary industries adopting edge AI hardware, each presenting unique operational demands and regulatory landscapes.
- Automotive:This sector integrates edge AI for advanced driver-assistance systems (ADAS), in-cabin monitoring, and autonomous driving functions, demanding high reliability and low latency. NHTSA guidelines in the United States influence the design of redundant and fail-safe hardware components.
- Manufacturing:Edge AI in manufacturing drives smart factory initiatives, enabling predictive maintenance, quality control, and robotic automation on the production floor. Government initiatives in China and Germany support large-scale demand for industrial edge AI hardware.
- Retail:Edge AI enhances customer experience through personalized recommendations, inventory management, and loss prevention systems directly within retail environments. These applications require robust, energy-efficient hardware for continuous operation.
- Healthcare:Edge AI devices in healthcare enable on-device analysis for medical wearables, remote patient monitoring, and diagnostic imaging. Data privacy regulations like GDPR in Europe incentivize local processing to protect sensitive patient information.
The Automotive sector commands substantial investment. Manufacturing is expanding rapidly.
Deployment Model:
Deployment model differentiation highlights how edge AI hardware is integrated into existing IT infrastructures, impacting scalability and data governance.
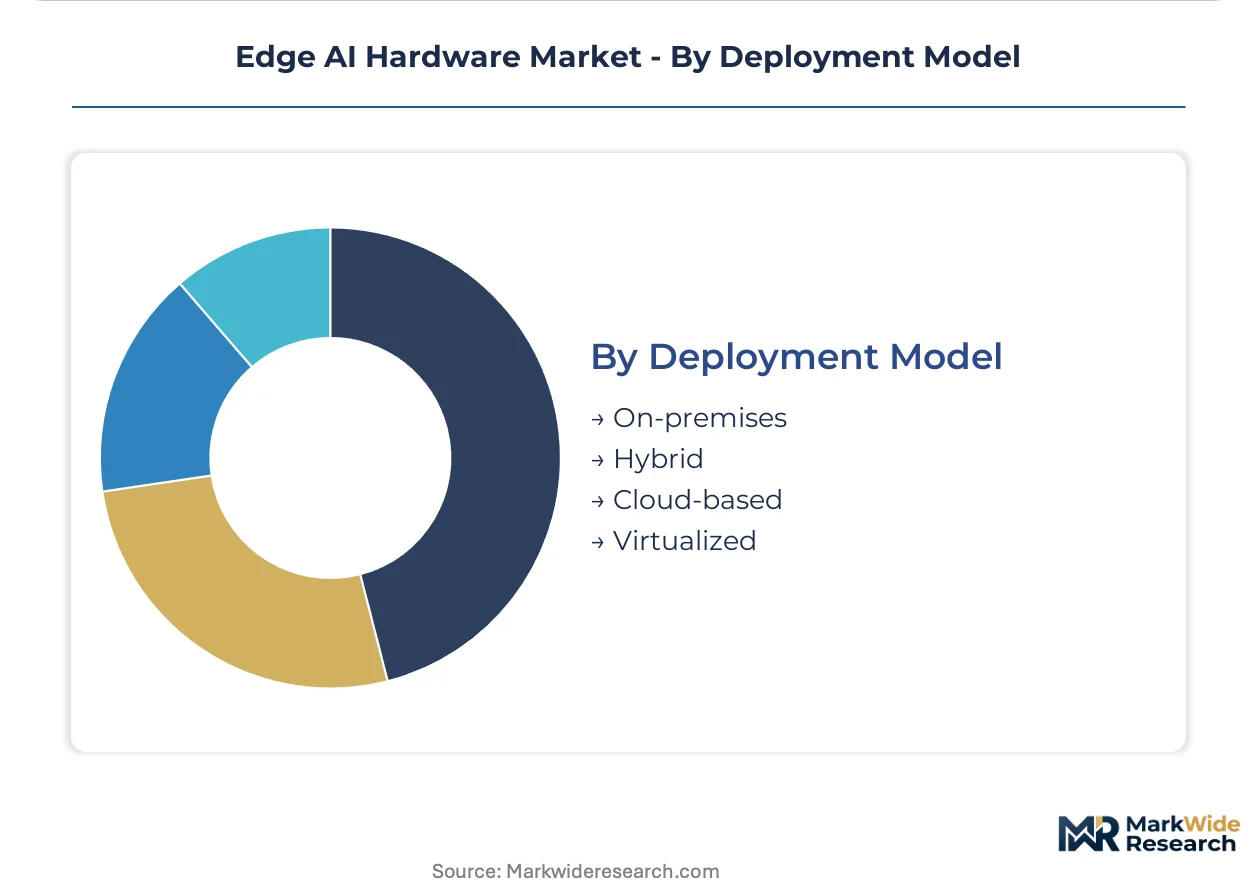
- On-premises:This model involves deploying edge AI hardware directly at the physical location where data is generated, ensuring maximum control, low latency, and data privacy. It is favored by industries with strict data sovereignty requirements, such as defense and critical infrastructure.
- Hybrid:Hybrid deployments combine on-premises edge processing with cloud-based resources, offering flexibility to offload complex tasks or store historical data remotely. Enterprises in industrial IoT leverage this model for balanced performance and scalability.
- Cloud-based:While primarily an edge market, cloud-based elements include management planes or specific AI model training that then deploys to the edge, rather than direct edge processing. This model suits applications where initial model development occurs centrally.
- Virtualized:Virtualized edge deployments abstract hardware resources, allowing multiple AI applications to run concurrently on shared physical infrastructure. This approach offers cost efficiency and flexibility for managing diverse workloads in dynamic environments.
On-premises deployments hold significant operational footprint. Hybrid models are gaining traction for their adaptability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives promoting smart infrastructure and advanced manufacturing significantly influence the global Edge AI Hardware Market. Policies in major economies foster domestic innovation and drive demand for localized AI processing capabilities. This strategic support accelerates adoption across various industrial and consumer applications.
United States
Demand for advanced driver-assistance systems and secure industrial automation drives the Edge AI Hardware Market in the United States. NHTSA guidelines for autonomous systems create specific requirements for redundant and fail-safe hardware components. Silicon Valley and other tech hubs like Austin concentrate significant R&D, fostering innovation in chip design and software integration.
China
China's Edge AI Hardware Market sees substantial demand from smart manufacturing and surveillance applications. Government initiatives, including national digitalization policies, actively support the development and deployment of industrial edge AI hardware. The Yangtze River Delta region, particularly in cities like Shanghai, serves as a hub for advanced semiconductor manufacturing and AI integration.
Germany
Industrial automation and precision robotics are primary demand drivers for edge AI hardware in Germany. The EU AI Act influences hardware design by emphasizing ethical AI and data governance, favoring on-device processing. Bavaria and Baden-Württemberg host major automotive and industrial equipment manufacturers, propelling the integration of edge AI into production lines.
Japan
Robotics and advanced consumer electronics applications fuel the Edge AI Hardware Market in Japan. METI provides strategic guidance and funding for AI research and development, encouraging innovation in specialized processors. The Tokyo metropolitan area and Kansai region are centers for high-tech manufacturing and robotics, driving demand for low-latency edge computing solutions.
South Korea
South Korea's Edge AI Hardware Market is propelled by strong consumer electronics and automotive sector investments. Government support through PLI schemes incentivizes local production and innovation in semiconductor technologies. The Seoul Capital Area, including cities like Suwon, concentrates major electronics manufacturers and automotive R&D facilities, integrating edge AI into next-generation products.
Edge AI Hardware Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established semiconductor giants competing alongside agile specialized AI chip startups. Large technology firms leverage extensive R&D budgets to dominate high-performance segments. This environment fosters significant investment in strategic partnerships and continuous portfolio diversification.
Specialists in power-efficient processing, such as Qualcomm Technologies, Inc., anchor the mobile and IoT segments. NVIDIA Corporation exemplifies leadership in high-performance accelerators for complex AI workloads. Intel Corporation occupies a diverse position, offering a broad portfolio spanning CPUs, FPGAs, and dedicated AI ASICs.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| NVIDIA Corporation |
| Intel Corporation |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| MediaTek Inc. |
| Advanced Micro Devices, Inc. |
| Google LLC |
| Others |
Cost & Logistics Intelligence
Semiconductor manufacturing concentration in East Asia dictates the cost structure for Edge AI hardware, influencing margin capture for downstream hardware vendors. This supply dynamic ensures that pricing power remains with key component suppliers, impacting overall market profitability.
Pricing Analysis
Performance tiers for Edge AI hardware create the primary pricing spread, differentiating between high-performance accelerators and power-efficient processors. Subscription-based Hardware-as-a-Service (HaaS) is gaining traction, alongside traditional per-unit transactional models. Customization for specific industrial use cases also drives higher pricing. High ASIC development costs contribute to pricing pressure for specialized components. Smaller enterprises exhibit higher price sensitivity, favoring HaaS, while automotive and industrial sectors prioritize performance and reliability over initial cost.
Supply Chain Analysis
Extended payment terms for critical semiconductor components support the complex supply chain dynamics within the Edge AI hardware market. Advanced semiconductor manufacturing heavily concentrates in Taiwan, South Korea, and increasingly China. The supply chain relies on specialized silicon wafers, advanced packaging materials, and high-performance memory chips. Geopolitical tensions surrounding key manufacturing hubs pose a structural risk to component availability. Hardware distribution primarily runs through direct sales channels to large automotive and industrial OEMs, supplemented by specialized distributors for broader enterprise adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Edge AI Hardware Market presents a capability scarcity challenge, particularly regarding engineers skilled in both hardware architecture and machine learning model optimization.
For Market Incumbents:Harden intellectual property portfolios around specialized AI ASIC designs to mitigate competitive threats from agile startups. Secure long-term supply agreements for advanced semiconductor fabrication and invest in ecosystem development for proprietary software frameworks. Software fragmentation and the high non-recurring engineering costs for ASICs challenge market dominance. Deepen vertical integration into specialized chip design and software toolchains to offer comprehensive solutions.
For New Entrants and Emerging Players:Build out niche application-specific hardware tailored for underpenetrated markets like precision agriculture in the Americas. Focus on personalized healthcare devices requiring robust data privacy and autonomous systems in logistics for warehouse automation. Small and medium-sized enterprises (SMEs) seeking cost-effective AI deployment via subscription-based HaaS models represent a penetrable segment. Offer comprehensive Hardware-as-a-Service packages that bundle specialized hardware with pre-optimized software frameworks.
For Investors and Strategic Acquirers:Capital is best deployed toward mid-cap specialists with proven neuromorphic computing architectures or strong intellectual property in power-efficient AI processing. The long-term viability hinges on companies that can balance extreme computational performance with stringent energy efficiency requirements. Target firms demonstrating expertise in specific application domains like computer vision for autonomous systems. Monitor the rate of adoption for standardized software frameworks across diverse hardware accelerators as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Neuromorphic Computing R&D | This advances ultra-low-power processing for robotics and sensor fusion applications. |
| Develop Application-Specific AI ASICs | This optimizes performance and energy efficiency for critical automotive and industrial workloads. |
| Expand Hardware-as-a-Service Offerings | This lowers capital expenditure barriers for enterprises adopting edge AI capabilities. |
| Form Strategic Partnerships for 5G Integration | This ensures seamless, low-latency connectivity for real-time edge AI deployments. |
| Prioritize GDPR-Compliant Hardware Design | This addresses data privacy regulations, especially in consumer electronics and healthcare. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary data validation. We engaged with chip architects, automotive ADAS engineers, industrial automation specialists, and enterprise IT procurement leads. Public company filings, industry association reports, government digitalization policies, and academic research on AI architectures served as secondary sources. This approach ensured robust bottom-up data collection and top-down market sizing validation.
The forecast inputs considered include technological advancements in chip design, regulatory shifts affecting data privacy, and evolving end-user demands. An analytical framework modeled market dynamics across the projection horizon, accounting for product type, technology, end-user, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected future demand, cross-referenced with macroeconomic indicators. Integration of 5G infrastructure and the pace of autonomous vehicle development served as key inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by semiconductor giants or disruptive AI chip startups would shift outcomes. Forecasts reflect documented assumptions regarding technological maturation and market adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Global Insight Engines Market
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Artificial Intelligence As a Service Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Aiops Market