
 Artificial Intelligence (AI) in Retail Market | 2026-2036
Artificial Intelligence (AI) in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Retail Market Analysis
Grocery stores is pivoting toward AI-powered inventory management and dynamic pricing, outpacing traditional apparel retailers in deployment velocity. Microsoft leverages its Azure cloud ecosystem to anchor enterprise retail contracts across North America and Europe. Amazon Web Services sustains dominance in real-time recommendation infrastructure for e-commerce platforms. NVIDIA differentiates through specialized GPU architectures that accelerate computer vision workloads in automated checkout systems.
Artificial Intelligence in Retail encompasses machine learning algorithms, deep learning neural networks, natural language processing engines, and computer vision systems deployed to automate merchandising decisions, optimize supply chains, and personalize consumer interactions at scale. These technologies process transactional, visual, and behavioral data streams through cloud-native architectures to generate predictive insights and autonomous operational responses. Recommendation engines command the largest installed base among product types, while visual search solutions represent the fastest-expanding category as mobile-first shopping behaviors mature. Machine learning occupies the core technology layer, though computer vision is displacing traditional barcode scanning in warehouse and storefront environments.
The EU AI Act classifies retail AI systems as high-risk when they influence consumer access to essential goods, mandating conformity assessments and human oversight protocols that reshape vendor compliance costs. The FDA regulates AI-enabled diagnostic tools in retail pharmacy settings, while the FTC monitors algorithmic pricing for collusion risks under antitrust frameworks. Stakeholders must weigh the trade-off between autonomous system deployment speed and emerging liability standards that assign accountability to retailers rather than software providers.
Market Dynamics
The EU AI Act is compressing deployment timelines for automated retail systems by mandating conformity assessments and human oversight protocols before consumer-facing rollouts. Retailers must now front-load compliance architecture into product development cycles, fundamentally restructuring how AI vendors and their enterprise customers negotiate liability allocation.
Growth Catalysts
- Cloud infrastructure concentration:Dense compute clusters in Seattle, San Francisco, and New York City lower latency for real-time inference workloads. Grocery chains leverage this proximity for demand forecasting pipelines.
- EU AI Act compliance services:Mandated human oversight and risk classification systems create specialized vendor ecosystems around conformity assessment automation.
- Computer vision maturation:Automated checkout systems displace barcode scanning in warehouse and storefront environments, reducing labor touchpoints per transaction.
Market Restraints
- GPU supply concentration:Specialized accelerator architectures for visual inference workloads depend on concentrated semiconductor fabrication capacity in East Asian foundries.
- EU AI Act liability friction:High-risk classification for systems influencing consumer access to essential goods assigns accountability to retailers rather than software providers, elevating insurance and legal review costs.
- Edge deployment capex:Real-time recommendation infrastructure requires distributed inference nodes that strain capital allocation frameworks against centralized cloud alternatives.
Strategic Opportunities
- Visual search expansion:Mobile-first shopping behaviors in urban United States corridors drive fastest-category growth for camera-based product discovery interfaces.
- FDA-regulated pharmacy AI:Diagnostic tool deployment in retail health settings creates compliant pathways for computer vision applications in medication verification and patient screening workflows.
- Dynamic pricing convergence:Grocery stores integrate demand forecasting with automated markdown engines, outpacing apparel retailers in deployment velocity for perishable inventory optimization.
Industry Challenges
- MLOps talent scarcity:Production-grade model monitoring and drift detection capabilities remain concentrated among specialists commanding premium compensation in Seattle and San Francisco metro areas.
- Legacy POS integration:Automated checkout systems require API reconstruction with decades-old transaction processing architectures, extending deployment timelines.
- FTC algorithmic pricing scrutiny:Antitrust monitoring of dynamic pricing engines for collusion risks demands audit trail infrastructure that many mid-market retailers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Retail Market |
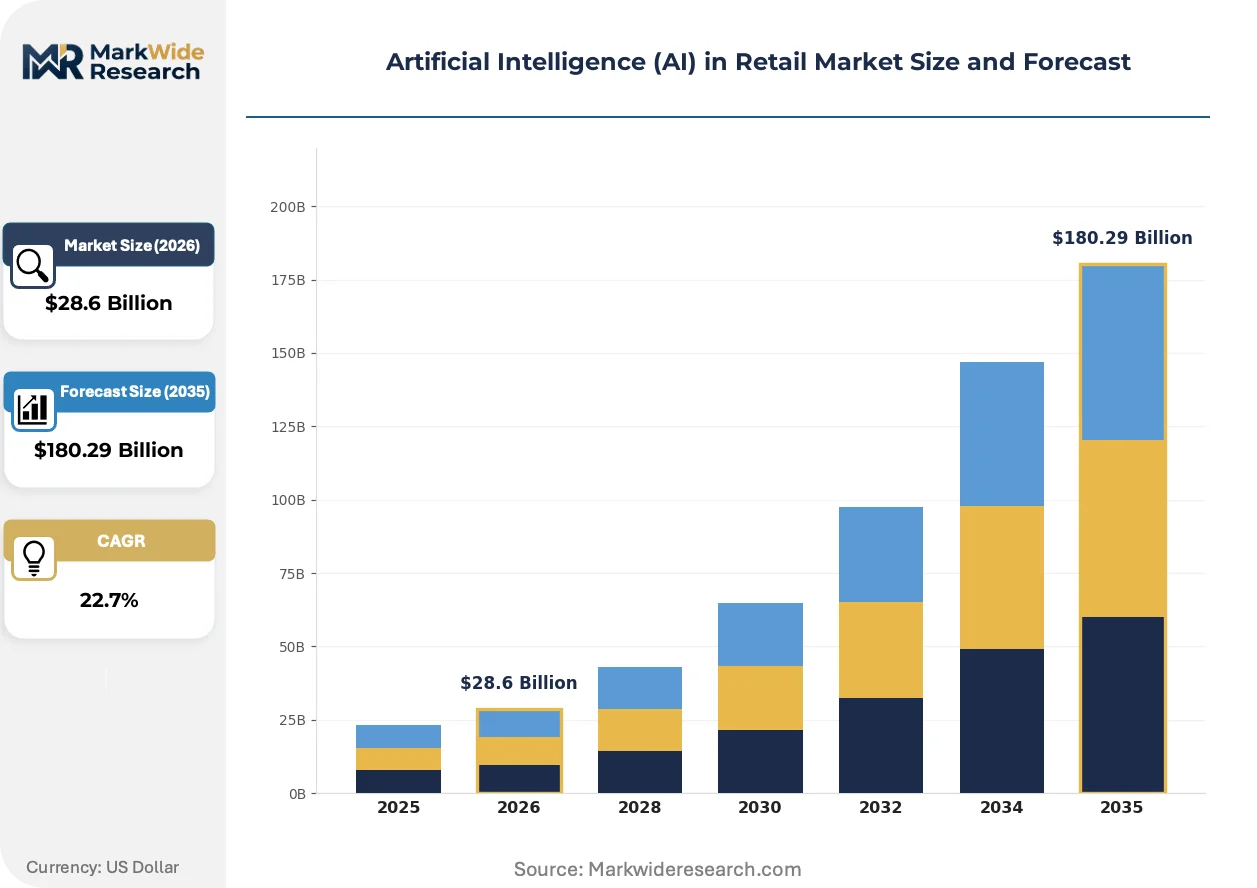
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $180.29 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbots, Recommendation Engines, Visual Search, Analytics Tools Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision Application: Customer Service, Inventory Management, Personalized Marketing, Sales Forecasting End User: Apparel Retailers, Grocery Stores, E-commerce Platforms, Specialty Shops |
| Companies Covered | Microsoft, Amazon Web Services, Google, IBM, Salesforce, Oracle, SAP, NVIDIA, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Retail Market Emerging Trajectories
Retail AI architecture is pivoting from centralized cloud inference toward distributed edge deployments that balance latency requirements against compliance data sovereignty mandates. This shift is compressing vendor consolidation timelines and forcing new partnerships between semiconductor suppliers and enterprise software platforms.
Computer vision is converging with natural language processing engines to enable multimodal shopping assistants that process both visual product queries and conversational refinement. Grocery chains in the United States are piloting these interfaces at highest velocity, seeking to reduce search friction in high-SKU environments. The structural consequence is collapsing the boundary between discovery and transaction, compressing the traditional purchase funnel into single-session completions.
The EU AI Act's high-risk classification system is forcing retailers to maintain human-in-the-loop protocols for automated merchandising decisions affecting essential goods access. European grocery operators are restructuring procurement contracts to embed compliance verification into vendor selection criteria. French and German retail chains are most advanced in deploying oversight dashboards that satisfy national regulator interpretive guidance.
Buyer concentration among cloud-native grocery chains is displacing traditional systems integrators from AI implementation workflows. These retailers now demand direct API access to model training pipelines, unbundling professional services from software licensing. The United States exhibits this pattern most acutely, where capital-rich regional grocers in Texas and Florida are building captive data science teams rather than outsourcing deployment.
Artificial Intelligence (AI) in Retail Market Segmentation
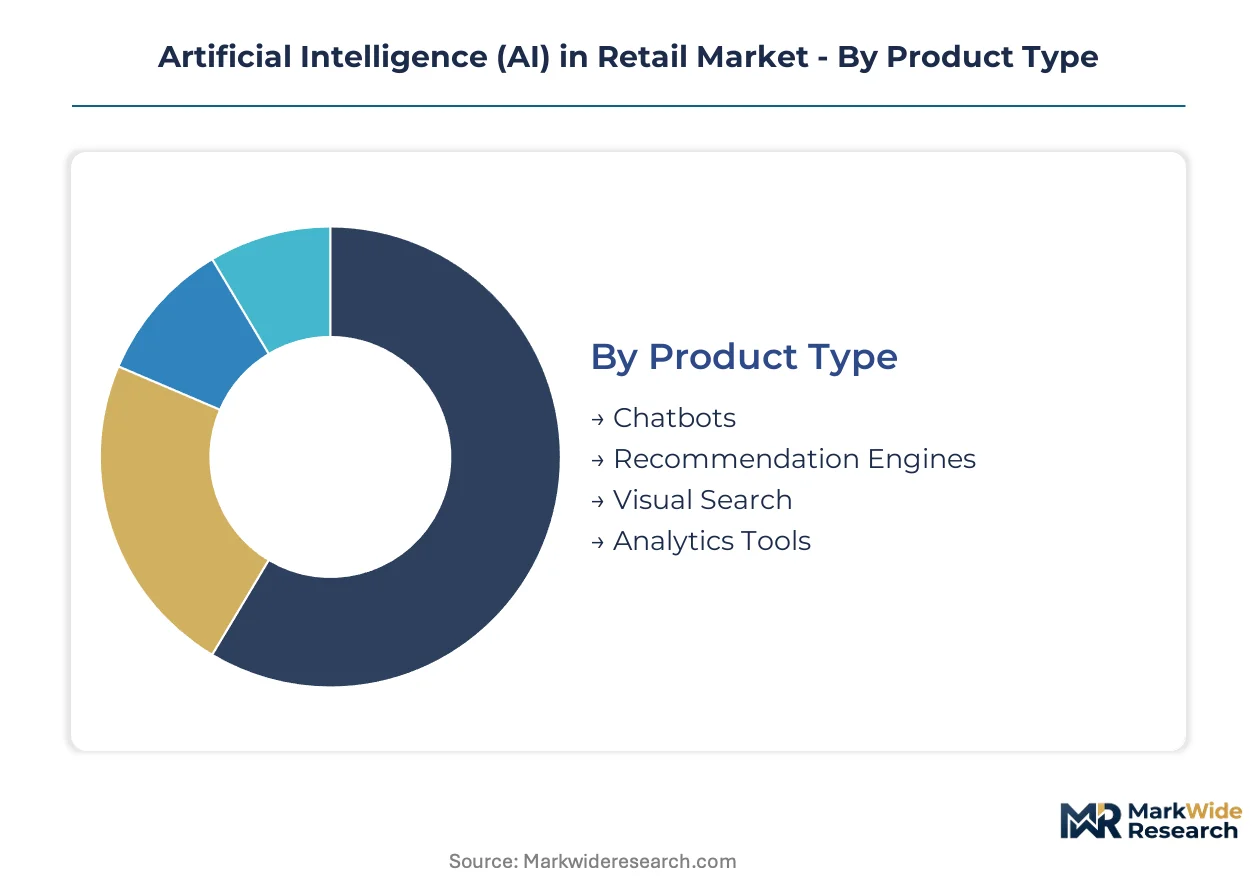
AI in retail segments diverge sharply in deployment economics. Cloud-native architectures favor certain product types, while legacy integration burdens constrain others. Understanding these capital dynamics reveals where vendor margins concentrate and where implementation friction persists.
Product Type:
Capital intensity varies dramatically across product categories, with infrastructure-heavy solutions demanding multi-year amortization schedules against lighter SaaS deployments.
- Recommendation Engines:These systems process behavioral and transactional data streams through collaborative filtering and neural architectures. United States e-commerce platforms concentrate demand here, driven by the need to compress purchase funnels in high-SKU environments. Cloud infrastructure costs scale with inference volume, creating tiered entry barriers.
- Visual Search:Camera-based discovery interfaces deploy convolutional neural networks trained on product image corpora. Mobile-first shoppers in urban United States corridors are driving fastest-category expansion, though GPU inference costs exceed traditional text-based search by an order of magnitude.
- Chatbots:Natural language interfaces automate customer service workflows through transformer-based dialogue models.
- Analytics Tools:Descriptive and predictive dashboards aggregate multi-source retail data for merchandising decisions.
Recommendation engines absorb the bulk of installed capacity; visual search is expanding most quickly.
Technology:
Foundation model economics reshape which technology layers capture enterprise investment, with pre-trained architectures displacing bespoke development.
- Machine Learning:Supervised and unsupervised algorithms form the operational backbone of demand forecasting and pricing optimization. Grocery chains in Texas and Florida deploy these systems at highest velocity, seeking to reduce perishable waste through predictive inventory positioning.
- Computer Vision:Automated checkout and shelf monitoring applications depend on specialized GPU architectures for real-time visual inference. The EU AI Act's high-risk classification for systems influencing essential goods access elevates compliance costs above other technology categories.
- Deep Learning:Multi-layer neural architectures power complex pattern recognition in unstructured data.
- Natural Language Processing:Text and speech understanding engines enable conversational commerce and sentiment analysis.
Machine learning retains the largest installed base; computer vision is climbing the fastest as automated checkout displaces barcode scanning.
Application:
Return-on-investment timelines segment applications, with cost-reduction use cases outpacing revenue-generating deployments in enterprise prioritization.
- Inventory Management:Automated replenishment and shelf optimization systems integrate point-of-sale data with supply chain signals. Grocery stores lead deployment here, motivated by margin compression in perishable categories and labor cost pressures in warehouse operations.
- Personalized Marketing:Dynamic content and offer customization engines process behavioral signals across channels. United States specialty shops concentrate investment, seeking to differentiate against mass-market competitors through tailored engagement.
- Customer Service:Automated response and escalation systems reduce human agent touchpoints.
- Sales Forecasting:Predictive models project demand patterns to inform procurement and staffing decisions.
Inventory management captures the largest share of enterprise AI budgets; personalized marketing is gaining share fastest as first-party data strategies mature.
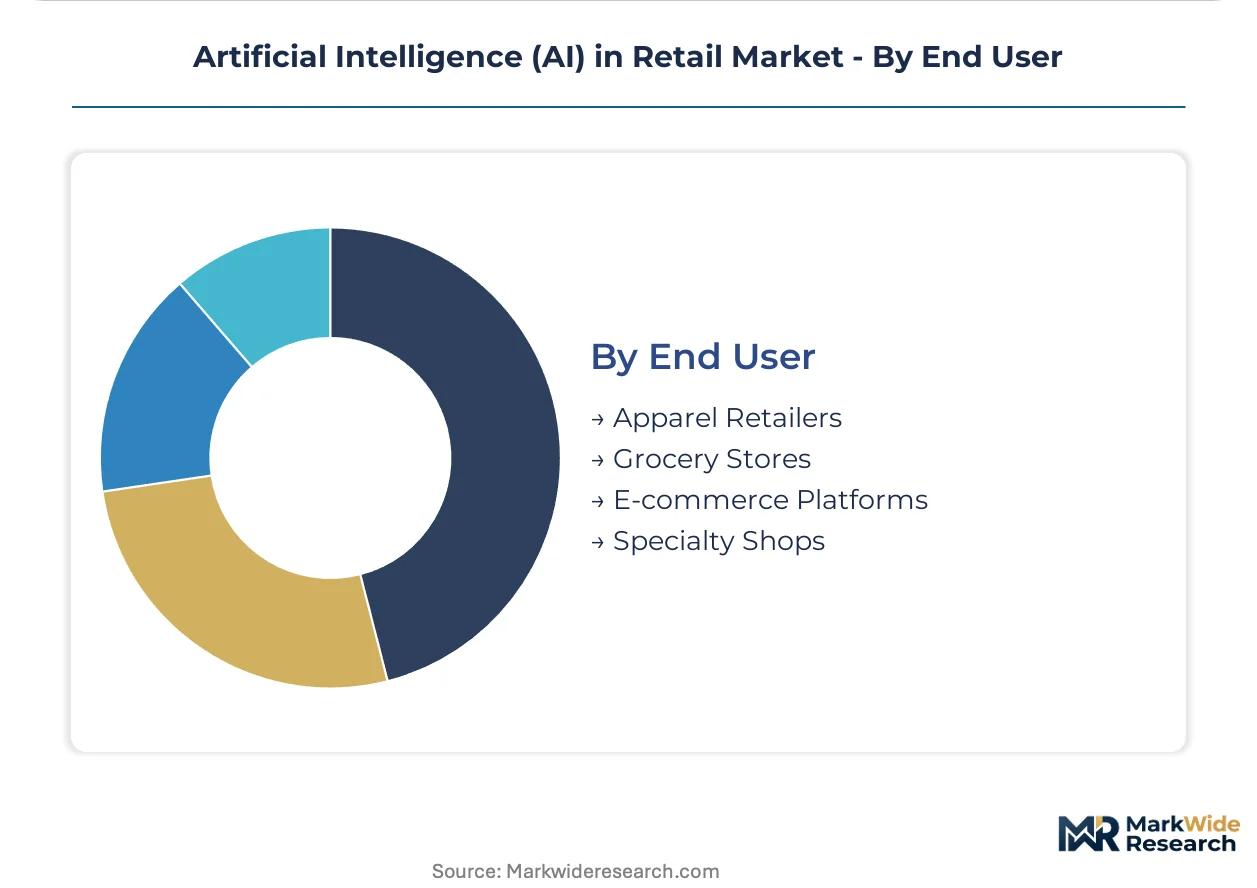
End User:
Digital maturity and margin structure determine which retail verticals can absorb AI implementation costs without operational disruption.
- E-commerce Platforms:Cloud-native architectures enable rapid AI integration without legacy system reconstruction. These operators concentrate in Seattle and San Francisco metro areas, leveraging proximity to specialized MLOps talent pools.
- Grocery Stores:Perishable inventory economics create urgent pressure for demand forecasting and dynamic pricing. United States regional chains are building captive data science teams rather than outsourcing, fundamentally restructuring vendor relationships.
- Apparel Retailers:Seasonal demand patterns and return-rate challenges motivate visual search and size recommendation investments.
- Specialty Shops:Niche assortment strategies favor personalized marketing over operational automation.
E-commerce platforms command the deepest AI integration; grocery stores are deploying fastest as competitive pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in Seattle and San Francisco concentrate cloud infrastructure investment for retail AI deployment. These federal tax incentives accelerate data center construction and MLOps talent recruitment. Dense compute clusters lower inference latency for real-time merchandising applications.
United States
Regional grocery chains in Texas and Florida build captive data science teams for perishable inventory optimization. The FTC monitors algorithmic pricing engines for collusion risks under antitrust frameworks. Seattle and San Francisco metro areas anchor cloud-native retail AI development through proximity to specialized engineering talent pools.
Germany
French and German retail chains deploy human-in-the-loop oversight dashboards for automated merchandising decisions. The EU AI Act mandates conformity assessments for high-risk systems influencing consumer access to essential goods. Berlin and Munich host compliance automation vendors serving continental grocery operators.
China
Automated checkout systems displace barcode scanning in warehouse and storefront environments at accelerated velocity. SAMR enforces algorithmic recommendation transparency rules for consumer-facing platforms. Yangtze River Delta manufacturing clusters supply specialized GPU architectures for visual inference workloads.
United Kingdom
London-based specialty shops concentrate investment in personalized marketing engines to differentiate against mass-market competitors. GDPR data sovereignty requirements compress deployment timelines for cloud-native retail architectures. The Southeast England corridor hosts fintech-retail convergence ventures integrating AI-powered payment authentication.
India
Domestic e-commerce platforms leverage PLI scheme incentives for local cloud infrastructure buildout. BIS certification requirements shape procurement criteria for imported AI hardware components. Bangalore and Hyderabad clusters concentrate MLOps talent for demand forecasting pipeline development in grocery and apparel verticals.
Artificial Intelligence (AI) in Retail Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers commanding enterprise retail contracts while semiconductor fabricators capture specialized accelerator margins. The vendor base concentrates around three strategic archetypes: cloud infrastructure platforms anchoring compute contracts, GPU architects supplying visual inference hardware, and enterprise software vendors unbundling professional services from licensing. Competitive positioning hardens through direct API access demands from capital-rich retailers and backward integration into model training pipelines.
Among hyperscale cloud providers, Microsoft and Amazon Web Services occupy positions as primary compute anchors for North American and European grocery chains. NVIDIA exemplifies the specialized hardware archetype, with its GPU architectures accelerating computer vision workloads in automated checkout deployments. These three companies represent the dominant competitive structure, though IBM and Google Cloud sit within adjacent tiers seeking enterprise retail expansion through differentiated compliance tooling.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| IBM |
| Salesforce |
| Oracle |
| SAP |
| NVIDIA |
| Intel |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud providers anchor enterprise retail contracts through Azure and AWS ecosystems, creating pricing discipline through multi-year subscription lock-in while GPU-dependent computer vision vendors face volatile component costs. This ownership concentration rewards software vendors with captive compute infrastructure while squeezing margins for hardware-dependent solution providers.
Pricing Analysis
Short lead-time deployments command premium pricing in automated checkout rollouts, while spot inventory of legacy POS integration modules trades at discount. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth under EU AI Act mandates. Pricing pressure stems from grocery chains unbundling professional services from software licensing. Mid-market regional retailers exhibit highest price sensitivity; capital-rich e-commerce platforms in Seattle and San Francisco demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced GPU architectures, while China and the United States dominate cloud infrastructure fabrication. NVIDIA's specialized accelerators draw from TSMC foundry capacity; memory components feed from Samsung and SK Hynix. Tariff exposure on semiconductor imports threatens automated checkout deployment timelines. Distribution runs through direct API relationships between cloud-native retailers and hyperscale providers, bypassing traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk classification system erects compliance moats that favor incumbent vendors with established conformity assessment infrastructure, penalizing entrants lacking human-in-the-loop protocol expertise.
For Market Incumbents: Hedge against unbundling pressure from capital-rich grocery chains by embedding compliance automation into core platform offerings. Microsoft and Amazon Web Services should deepen backward integration into model training pipelines to defend against retailer captive team formation. Vertical integration into MLOps talent acquisition in Seattle and San Francisco secures deployment velocity advantages. For New Entrants and Emerging Players: Capture white-space in EU AI Act compliance services for mid-market European grocery operators lacking internal risk classification expertise. French and German retail chains present most penetrable targets given national regulator interpretive guidance complexity. Go-to-market through Berlin and Munich compliance automation vendor partnerships accelerates credential establishment. For Investors and Strategic Acquirers: FDA-regulated pharmacy AI diagnostic tool approvals are the leading indicator that computer vision applications in retail health settings have crossed regulatory viability thresholds. Long-term positioning favors vendors with dual-use healthcare-retail capabilities and established reimbursement pathways. Watch for SAMR algorithmic transparency enforcement actions as signal of China market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Automation Platform Launch | EU AI Act mandates create specialized vendor ecosystems around conformity assessment. |
| GPU Architecture Partnership | NVIDIA's specialized accelerators anchor automated checkout system performance differentiation. |
| Captive Data Science Team Buildout | Texas and Florida regional grocers restructure vendor relationships through direct API access demands. |
| Human-in-the-Loop Dashboard Deployment | French and German retail chains satisfy national regulator interpretive guidance most advanced. |
| Edge Inference Node Expansion | Distributed deployment balances latency requirements against GDPR data sovereignty mandates. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents formed the secondary backbone, supplemented by customs records on AI hardware component trade flows. Primary interviews with CTOs at United States grocery chains, MLOps engineering leads in Seattle and San Francisco, compliance officers at European retail operators, and procurement directors at cloud infrastructure providers validated demand-side assumptions. Bottom-up deployment tallies and top-down cloud spend estimates were triangulated against vendor-reported contract values.
Historical trendline analysis of AI infrastructure investment patterns informed projection modeling across the analysis window. Segmentation dimensions included product type, technology layer, application use case, and end-user vertical, with regional regulatory cluster as an additional cross-cutting axis. CAGRs were derived from slope-fitting across validated data points, incorporating grocery chain inventory optimization spend trajectories and e-commerce recommendation engine scaling curves as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement variance and GPU supply chain disruption. Forecasts reflect documented assumptions on cloud infrastructure concentration persistence and grocery sector margin compression trajectories. Deviation in FTC algorithmic pricing scrutiny intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Voice User Interface Market
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
Global AI in Social Media Market