
 Global Artificial Intelligence in E-Commerce Market | 2026-2036
Global Artificial Intelligence in E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence in E-Commerce Market Foresight
The gap between premium AI-native platforms and commodity plugin tools is expanding in e-commerce infrastructure. Amazon leverages its proprietary recommendation algorithms and cloud compute scale to dominate enterprise deployments. Shopify anchors the mid-market with accessible machine learning APIs for independent merchants. Salesforce competes through its integrated CRM-AI stack that unifies customer data across channels.
Artificial intelligence in e-commerce encompasses machine learning models, natural language processing engines, and computer vision systems that process transactional data, visual product catalogs, and conversational queries to automate pricing, recommendations, and fulfillment decisions. Natural language processing powers real-time customer service automation while computer vision enables visual search and automated product tagging. Machine learning underpins personalized recommendations, the most mature application segment, whereas predictive analytics for demand forecasting captures expanding margin pools as supply chain volatility persists. Cloud-based deployment leads volume, though edge computing is gaining traction for latency-sensitive checkout experiences.
The EU AI Act, GDPR, and the US Federal Trade Commission's algorithmic fairness guidance collectively shape compliance burdens for cross-border e-commerce operators. GDPR's automated decision-making provisions restrict profiling intensity, while the EU AI Act imposes risk-classification requirements on recommendation systems used by major platforms. Stakeholders must monitor divergent regulatory timelines between Brussels and Washington to avoid fragmented compliance architectures that inflate engineering overhead.
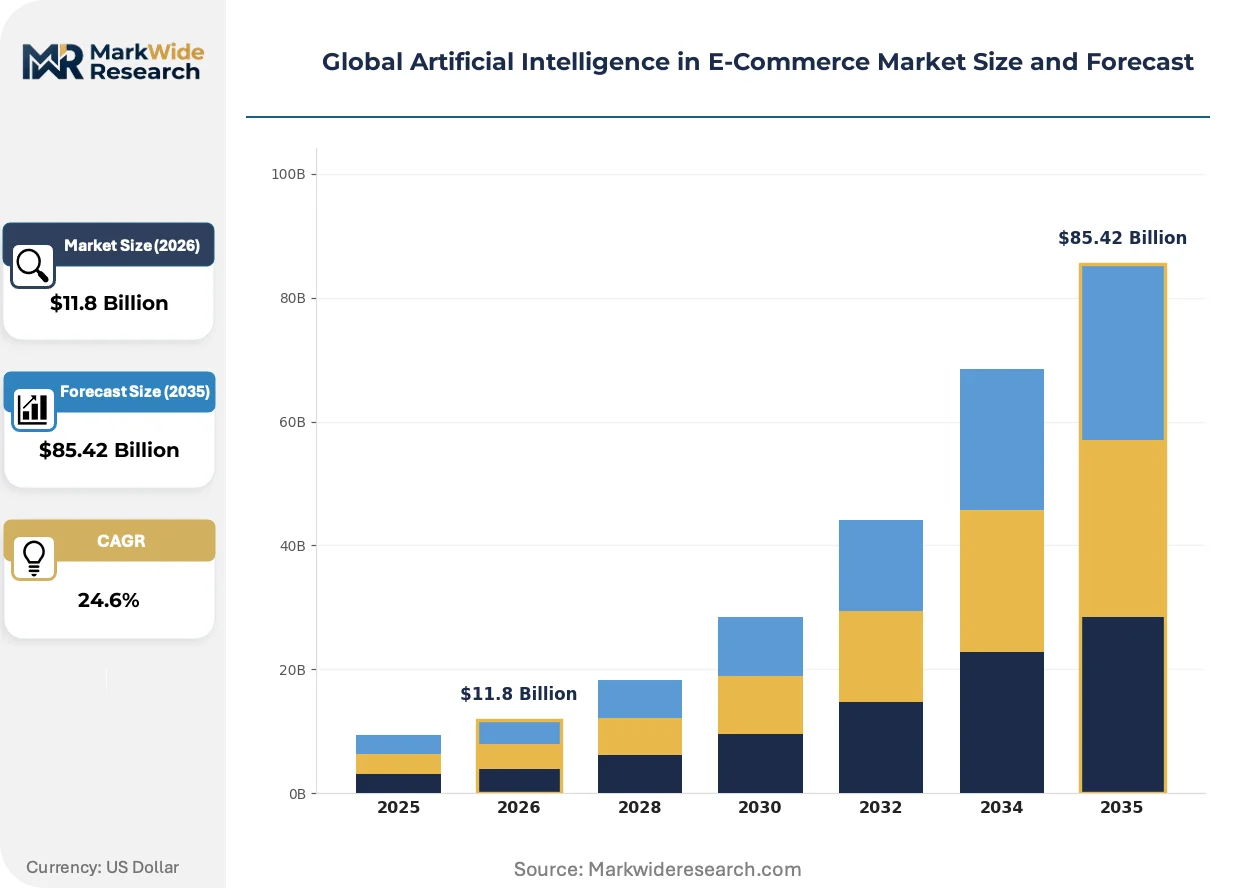
Market Dynamics
Generative AI architectures are compressing feature development cycles from quarters to weeks, forcing retailers to rebuild personalization stacks around large language models rather than legacy collaborative filtering systems.
Growth Catalysts
- EU AI Act risk classification:High-stakes automated decision systems now face mandatory conformity assessments, creating certified vendor ecosystems that reward compliant incumbents.
- Computer vision product tagging:Automated attribute extraction from unstructured image catalogs reduces manual enrichment costs by orders of magnitude for fashion marketplaces.
- United States cloud infrastructure concentration:Hyperscaler availability zones in Virginia, Oregon, and Ohio enable sub-50ms inference latency for real-time pricing engines.
Market Restraints
- GPU supply concentration:Taiwan Semiconductor Manufacturing dominates advanced node fabrication, creating single-source dependency for training infrastructure.
- GDPR automated decision-making restrictions:Article 22 limitations on profiling intensity cap recommendation system granularity in European deployments.
- Transformer architecture energy intensity:Inference costs for large language models scale non-linearly with sequence length, compressing margins on high-volume queries.
Strategic Opportunities
- India tier-2 city penetration:Vernacular language interfaces for Hindi, Tamil, and Telugu speakers remain underdeveloped relative to English-first platforms.
- Federated learning architectures:Privacy-preserving model training across siloed merchant data pools unlocks collaborative intelligence without raw data sharing.
- Edge compute checkout optimization:On-device inference for payment fraud detection reduces cloud egress costs and latency for physical retail hybrid models.
Industry Challenges
- Multimodal model integration complexity:Unifying text, image, and tabular pipelines requires scarce full-stack ML engineering talent.
- Algorithmic audit trail requirements:EU AI Act documentation mandates for high-risk systems extend deployment timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence in E-Commerce Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $85.42 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotic Process Automation, Predictive Analytics, Speech Recognition Application: Personalized Recommendations, Customer Service Automation, Inventory Management, Fraud Detection, Dynamic Pricing, Demand Forecasting Deployment: Cloud-Based, On-Premise, Hybrid Cloud, Edge Computing Customer Type: Online Retailers, Marketplaces, Brand Manufacturers, Third-Party Sellers, Subscription Services, Digital Wallet Providers |
| Companies Covered | Amazon, Shopify, Salesforce, Dynamic Yield, Riskified, Sift, LivePerson, Appier, ViSenze, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence in E-Commerce Market Shifts & Advancements
Foundation model commoditization is fragmenting competitive advantage from raw capability to proprietary data moats and fine-tuning infrastructure. Retailers now differentiate through exclusive behavioral datasets rather than base model access.
Multimodal retrieval-augmented generation is automating product discovery workflows by grounding conversational queries in live inventory vectors. Mid-market apparel merchants in Germany and France are piloting these systems for size-fit recommendations. The technology is automating the translation between vague customer intent and precise catalog matches, compressing the traditional search-browse-purchase funnel.
The EU AI Act's risk-tier framework imposes conformity obligations on recommendation engines above defined scale thresholds. Major platforms must maintain technical documentation, human oversight protocols, and accuracy metrics for automated decision systems. Fashion and electronics marketplaces with EU operations are restructuring algorithm governance teams to satisfy Brussels enforcement timelines.
Merchant procurement of AI infrastructure is consolidating around API-first consumption models rather than self-managed deployments. Independent sellers on Shopify and WooCommerce platforms now access enterprise-grade personalization through pay-per-call interfaces. This shift is most pronounced in the United States, where developer tooling ecosystems reduce integration friction for non-technical operators.
Global Artificial Intelligence in E-Commerce Market Segmentation
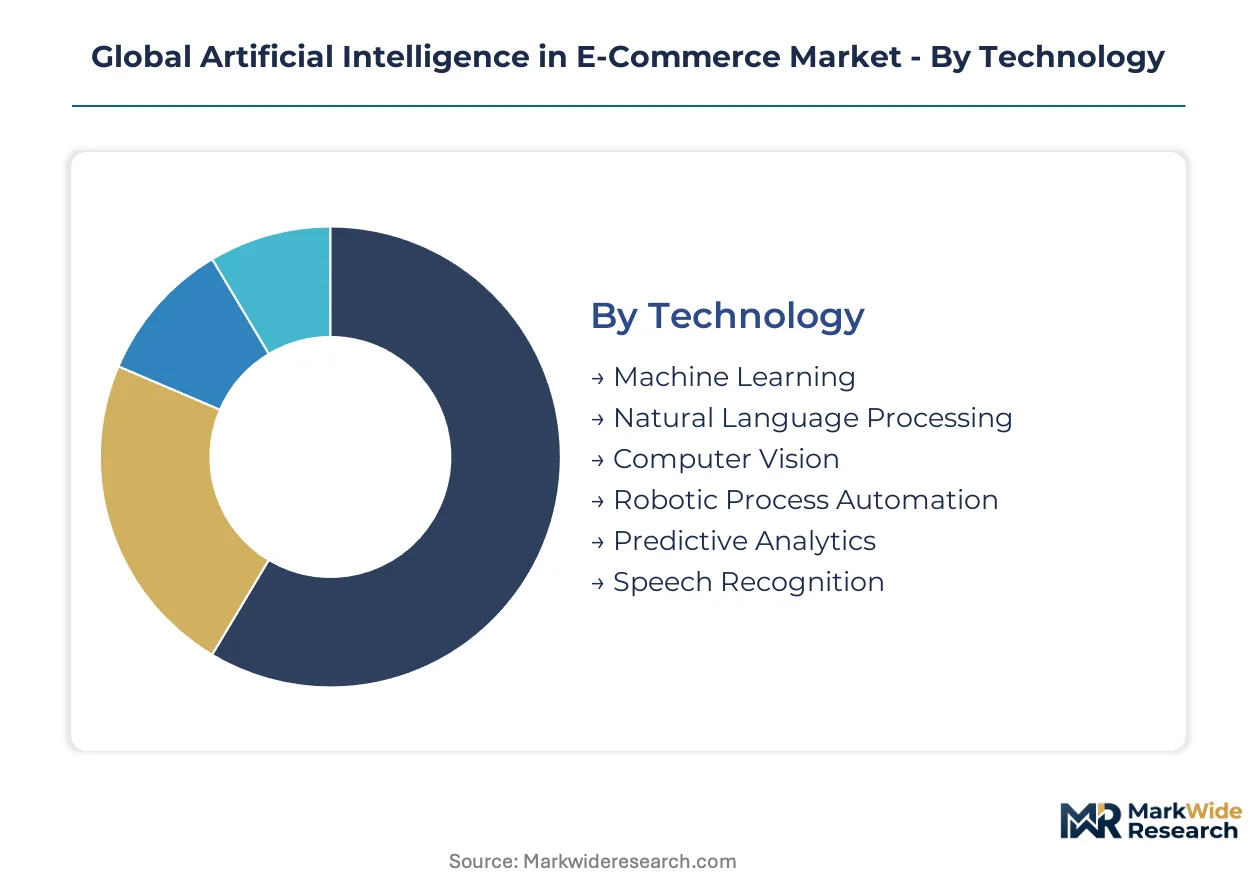
Technology differentiation determines infrastructure investment patterns across e-commerce AI deployments. Segmentation reveals how capability maturity, regulatory exposure, and compute economics concentrate margin pools in specific configurations.
Technology:
Technical architecture choices dictate data requirements, training costs, and inference latency profiles for retail operators.
- Machine Learning:Collaborative filtering and gradient-boosted models power recommendation engines with established training pipelines. Demand concentrates among United States enterprise retailers seeking predictive customer lifetime value scoring amid privacy signal degradation.
- Natural Language Processing:Transformer-based architectures enable conversational commerce and sentiment analysis across multilingual catalogs. Germany and France fashion merchants deploy these systems for size-fit guidance, driven by EU AI Act documentation requirements for automated advisory tools.
- Computer Vision:Convolutional neural networks extract product attributes from unstructured imagery.
- Robotic Process Automation:Rule-based automation handles order processing and returns workflows.
- Predictive Analytics:Time-series models forecast demand volatility for supply chain optimization.
- Speech Recognition:Audio interfaces enable voice commerce through smart speaker integrations.
Mature deployment sits with Machine Learning. Newer deployment is concentrated in Natural Language Processing.
Application:
Use-case prioritization reflects margin pressure points and customer experience friction in digital retail.
- Personalized Recommendations:Vector search and embedding models match behavioral signals to product catalogs. United States marketplaces invest heavily here, constrained by GDPR Article 22 profiling limitations in European deployments.
- Customer Service Automation:LLM-powered chatbots handle inquiry resolution at scale. India tier-2 city merchants adopt vernacular-language variants for Hindi and Tamil speakers, where English-first platforms underperform.
- Inventory Management:Reinforcement learning optimizes stock positioning across distributed fulfillment networks.
- Fraud Detection:Anomaly detection models flag payment and account takeover risks.
- Dynamic Pricing:Real-time elasticity models adjust quotes based on competitor monitoring.
- Demand Forecasting:Supply chain volatility drives adoption among apparel and electronics sellers.
Margin capture is deepest in Personalized Recommendations. Capability gaps persist in Demand Forecasting for long-tail SKU environments.
Deployment:
Infrastructure location decisions balance latency requirements against data sovereignty and egress cost constraints.
- Cloud-Based:Hyperscaler-managed inference dominates volume, with Virginia and Oregon availability zones enabling sub-50ms response times for real-time pricing engines.
- On-Premise:Self-managed clusters serve retailers with strict data residency requirements or specialized hardware needs.
- Hybrid Cloud:Split architectures process sensitive data locally while leveraging cloud scale for batch workloads.
- Edge Computing:On-device inference reduces latency for physical retail hybrid models and payment fraud detection.
Volume concentrates in Cloud-Based configurations. Edge Computing is climbing the fastest as checkout experience latency becomes competitive.
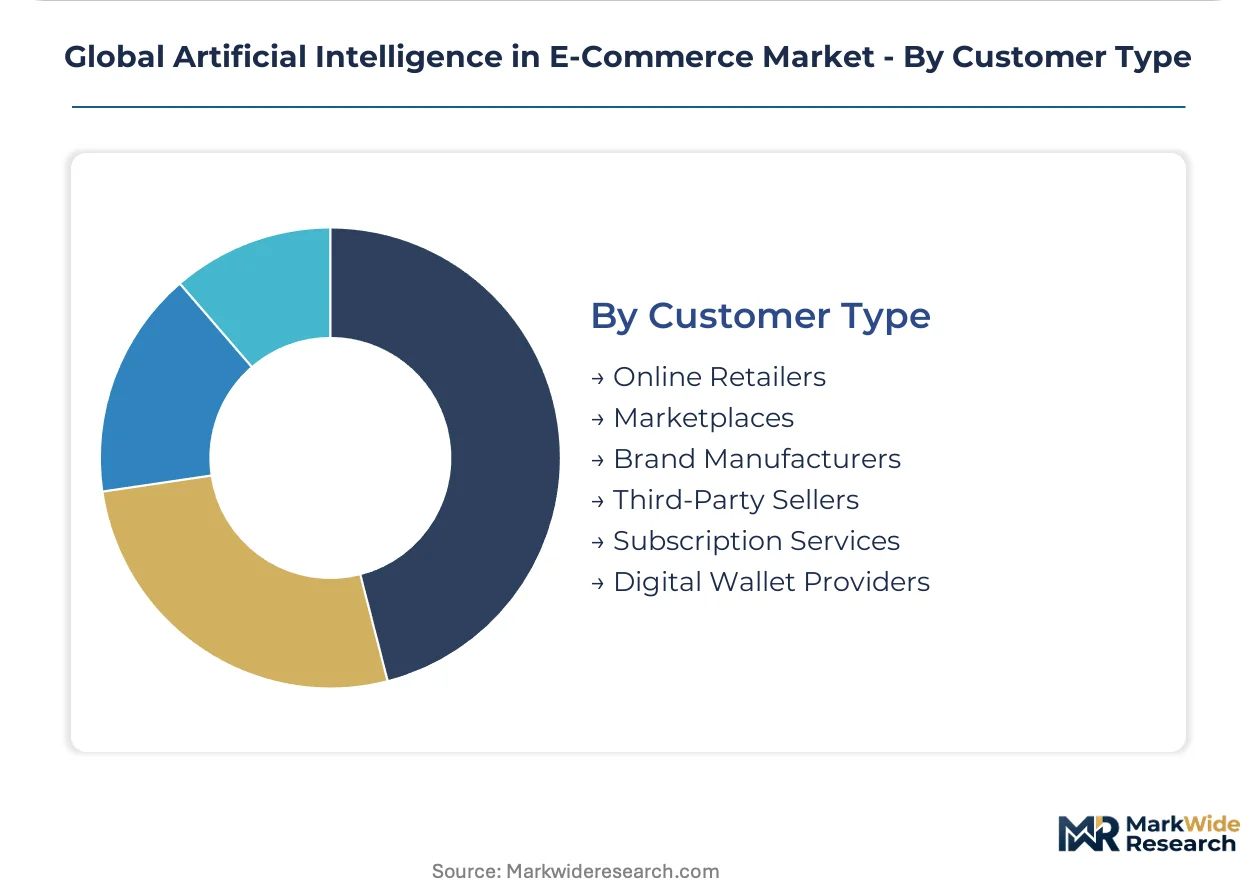
Customer Type:
Procurement sophistication and integration complexity vary sharply across seller archetypes.
- Online Retailers:Direct-to-consumer operators with unified data pipelines drive full-stack AI investments.
- Marketplaces:Platform operators face EU AI Act high-risk system classification for recommendation engines above scale thresholds.
- Brand Manufacturers:CPG companies deploy AI for direct channel optimization and retail network coordination.
- Third-Party Sellers:API-first personalization tools from Shopify and WooCommerce reduce integration friction for non-technical operators.
- Subscription Services:Recurring revenue models prioritize churn prediction and cohort-based personalization.
- Digital Wallet Providers:Payment platforms leverage transaction data for merchant-facing analytics and consumer recommendations.
Integration complexity is highest for Marketplaces. API accessibility is expanding fastest among Third-Party Sellers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors North American AI e-commerce infrastructure through Amazon's headquarters and cloud compute clusters. The metropolitan corridor hosts hyperscaler availability zones that enable sub-50ms inference latency for real-time pricing engines.
United States
Enterprise retailers in Virginia and Oregon availability zones invest heavily in predictive analytics infrastructure. FTC algorithmic fairness guidance shapes compliance architectures for automated decision-making systems. The San Francisco Bay Area concentrates venture-backed startups building multimodal retrieval-augmented generation tools for product discovery.
Germany
Fashion merchants in Berlin and Munich deploy natural language processing for size-fit guidance in German-language interfaces. EU AI Act documentation requirements for automated advisory tools extend deployment timelines. The Rhine-Ruhr corridor hosts compliance restructuring teams serving electronics marketplaces with EU operations.
India
Tier-2 city merchants adopt vernacular-language AI interfaces for Hindi, Tamil, and Telugu speakers. BIS standards and RBI digital payment frameworks influence fraud detection system design. Bangalore's technology corridor anchors machine learning engineering talent pools for API-first personalization tools.
China
Cross-border e-commerce operators in Shenzhen and Hangzhou integrate computer vision for automated product tagging. MIIT data localization requirements and SAMR platform governance rules constrain cloud deployment architectures. The Yangtze River Delta concentrates visual search development for fashion marketplace applications.
France
Paris-based apparel retailers pilot multimodal retrieval-augmented generation systems for conversational commerce. CNIL guidance on automated decision-making supplements EU AI Act risk-tier obligations. The Île-de-France region hosts algorithm governance teams restructuring recommendation engine oversight protocols.
Global Artificial Intelligence in E-Commerce Market Competitive Landscape
Capital-heavy cloud infrastructure providers compete with asset-light API platform designers for merchant relationships. The vendor base fragments across three tiers: hyperscaler-integrated stacks, mid-market SaaS platforms, and specialized fraud prevention services. Strategic archetypes include full-stack ecosystem builders, vertical personalization engines, and transaction security specialists. Competitive moves concentrate on M&A for data asset accumulation and strategic partnerships for edge compute deployment.
Within the hyperscaler-integrated tier, Amazon and Salesforce occupy positions as ecosystem anchors. Shopify exemplifies the mid-market API accessibility archetype. These three entities represent the dominant competitive configurations shaping procurement patterns across enterprise and independent merchant segments.
| Leading Market Players |
|---|
| Amazon |
| Shopify |
| Salesforce |
| Dynamic Yield |
| Riskified |
| Sift |
| LivePerson |
| Appier |
| ViSenze |
| Others |
Supply & Pricing Matrix
Venture-backed AI infrastructure specialists concentrated in Seattle and San Francisco have consolidated pricing discipline through recurring-revenue SaaS models that tether customer lifetime value to inference throughput commitments. This ownership pattern concentrates supply bargaining power among hyperscaler-aligned vendors while forcing mid-market API providers into volume-discount structures to retain merchant share.
Pricing Analysis
Value-based pricing anchored to recommendation-engine revenue lift dominates enterprise procurement, with United States retailers paying premium rates for real-time personalization APIs that demonstrate measurable conversion improvements. Price differentiation separates certified EU AI Act-compliant platforms from uncertified alternatives, with documentation overhead driving 15-30% cost premiums for high-risk system deployments. Pricing pressure stems from foundation model commoditization as raw LLM capabilities become interchangeable through OpenAI and Anthropic API standardization. Small merchants on Shopify and WooCommerce exhibit highest price sensitivity, while Amazon-scale marketplaces absorb premium rates for proprietary data moats and sub-50ms latency guarantees.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale retailer demand through dedicated customer success teams and custom integration engineering, while API-first self-service portals capture independent merchant volume with minimal touch. Taiwan and South Korea anchor advanced GPU fabrication through TSMC and Samsung foundry capacity, with United States cloud availability zones in Virginia and Oregon completing the inference delivery layer. Raw material dependencies center on NVIDIA H100 and A100 accelerators, high-bandwidth memory modules, and specialized optical interconnects for distributed training clusters. Single-source vulnerability concentrates in TSMC's 4nm and 5nm node production, where geopolitical disruption would cascade through training infrastructure availability within 90 days.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI architectures are displacing legacy collaborative filtering systems, compressing feature development cycles and forcing infrastructure reinvestment across personalization stacks. This technology transition rewards vendors with proprietary behavioral datasets and fine-tuning infrastructure over raw model access.
For Market Incumbents: Deploy exclusive data moat expansion through first-party behavioral signal capture, locking merchant switching costs via embedded workflow integration. Defend against open-source foundation model commoditization by deepening API ecosystem stickiness through Shopify-style app marketplace network effects. Accelerate EU AI Act certification investment to capture compliance-premium pricing tier before enforcement timelines harden competitive segmentation. For New Entrants and Emerging Players: Enter via vernacular-language NLP interfaces for India tier-2 cities, where Hindi, Tamil, and Telugu speaker demand outpaces English-first platform development. Target federated learning architectures that unlock collaborative model training across siloed merchant data pools without raw data sharing liability. Pursue edge-compute checkout optimization as the go-to-market angle, offering on-device fraud detection that reduces cloud egress costs for physical retail hybrid operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical personalization engines with exclusive fashion or electronics behavioral datasets in Germany and France, where EU AI Act compliance costs will strain undercapitalized competitors. Long-term viability centers on proprietary data acquisition rather than model capability ownership, with 5-10 year returns tethered to exclusive catalog enrichment and size-fit recommendation accuracy. Watch foundation model API pricing compression as the inflection signal—when OpenAI and Anthropic rate cuts accelerate, raw model access becomes unmoored from sustainable competitive advantage.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Mandatory conformity assessments for high-risk recommendation systems create certified vendor tier in Germany and France. |
| Vernacular Language NLP Development | Hindi, Tamil, and Telugu interfaces unlock tier-2 city merchant penetration in India where English-first platforms underperform. |
| Federated Learning Architecture Deployment | Privacy-preserving model training across siloed merchant pools enables collaborative intelligence without GDPR data-sharing liability. |
| Edge Compute Checkout Optimization | On-device inference for payment fraud detection reduces cloud egress costs and latency for physical retail hybrid models. |
| Proprietary Data Moat Acquisition | Exclusive behavioral datasets and fine-tuning infrastructure displace raw foundation model access as primary differentiation source. |
Research Methodology
Multi-period observation of GPU supply allocation, hyperscaler capex disclosures, and merchant API adoption rates anchored the trend analysis, supplemented by interviews with CTOs at United States enterprise retailers, platform engineering leads at Shopify-scale API providers, EU regulatory compliance officers, and machine learning infrastructure procurement managers at fashion marketplaces. Secondary validation drew from SEC 10-K filings, NVIDIA quarterly supply commentary, EU AI Act implementation guidance, and hyperscaler availability zone expansion announcements. Bottom-up merchant deployment estimates triangulated against top-down cloud infrastructure revenue segmentation.
Input-output matrices modeled technology adoption across deployment configuration, customer type sophistication, and application maturity dimensions over the projection horizon. Segmentation variables included machine learning versus natural language processing versus computer vision technology tiers, cloud-based versus edge computing infrastructure location, and marketplace versus third-party seller customer archetypes. CAGRs derived from S-curve diffusion modeling calibrated to historical SaaS platform penetration patterns, with elasticity adjustments for EU AI Act compliance cost shocks and GPU supply concentration risk.
Revisions become necessary when TSMC node capacity allocation shifts, foundation model API pricing undergoes step-function compression, or EU AI Act enforcement timelines accelerate beyond current Brussels guidance. Forecasts reflect assumptions regarding merchant infrastructure refresh cycles and hyperscaler competitive pricing discipline. Periodic stress-testing of base assumptions against GPU supply chain disruption scenarios and regulatory divergence patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
US Voice Recognition Market