
 NLP in Healthcare and Life Sciences Market | 2026-2036
NLP in Healthcare and Life Sciences Market Size, Share, and Industry Trends Forecast 2026-2036
NLP in Healthcare and Life Sciences Market Outlook
Software-defined NLP feature layers embedded within cloud-hosted clinical platforms is consolidating what healthcare providers actually purchase, shifting buyers from perpetual licenses toward metered API consumption. Microsoft Corporation leverages its Azure AI Health Bot infrastructure to anchor enterprise hospital deployments across North America. IBM competes through Watson Health's specialized oncology NLP modules, while Google differentiates via Vertex AI natural language models fine-tuned for biomedical literature extraction.
Natural language processing in healthcare and life sciences encompasses computational methods that interpret, classify, and generate human language from unstructured clinical text, voice recordings, and biomedical literature, typically operating on transformer architectures with domain-specific vocabularies exceeding 100,000 medical terms. Its primary commercial purpose is to automate information extraction from electronic health records, accelerate literature review in drug development, and enable conversational interfaces for patient triage. Speech recognition applications command mature installed bases in radiology and emergency departments, while predictive analytics represents the fastest-expanding margin pool as pharmaceutical companies deploy NLP for target identification and patient stratification. Machine learning technology leads deployment volume, though hybrid models combining deep learning with rule-based clinical logic capture premium pricing from buyers requiring explainable outputs for regulatory submission.
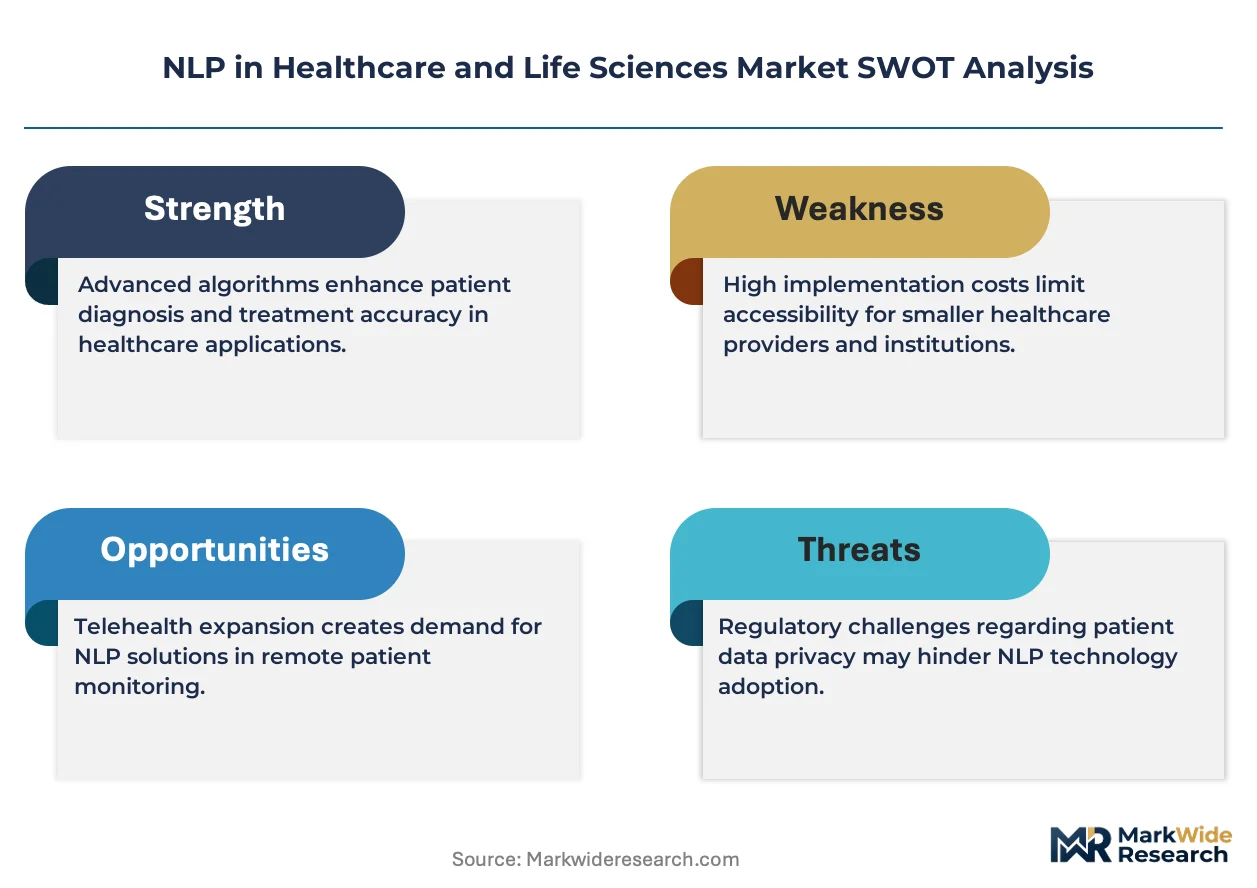
The FDA's software-as-a-medical-device framework and HIPAA security rule jointly shape how NLP vendors architect data pipelines, forcing on-premise or private-cloud deployments for identifiable patient data. The EMA's Good Machine Learning Practice guidance and EU AI Act risk-classification schema for clinical decision-support tools are creating divergent compliance burdens for vendors serving both markets. Stakeholders must monitor whether emerging FDA guidance on large language models in clinical settings triggers premarket submission requirements that reshape competitive economics for cloud-native entrants.
Market Dynamics
Software-defined NLP feature layers embedded within cloud-hosted clinical platforms is consolidating what healthcare providers actually purchase, shifting buyers from perpetual licenses toward metered API consumption. This structural force is compressing vendor margins while accelerating deployment velocity across hospital networks.
Growth Catalysts
- Federal health IT mandates in Germany:Hospital networks digitizing patient records under national interoperability standards are creating immediate demand for clinical NLP extraction tools.
- Transformer architectures with domain-specific vocabularies:Fine-tuned models exceeding 100,000 medical terms are enabling zero-shot clinical entity recognition that reduces manual annotation burdens.
- FDA's evolving guidance on AI-enabled medical devices:Clarified premarket pathways for clinical decision-support tools are reducing regulatory uncertainty for NLP vendors targeting US hospital systems.
Market Restraints
- Compute cost volatility:GPU cluster pricing fluctuations and cloud inference expenses create margin pressure for vendors offering real-time clinical documentation processing.
- Data localization requirements:HIPAA security rule and EU GDPR Article 9 restrictions on health data processing force duplicative infrastructure investments across jurisdictions.
- Clinical validation timelines:Retrospective studies required for FDA 510(k) submissions for NLP-based diagnostic aids extend product commercialization cycles by 18-36 months.
Strategic Opportunities
- Rural health system digitization in India:Central government eHealth initiatives and CDSCO regulatory harmonization are opening addressable markets for low-cost clinical speech recognition.
- Convergence of NLP with knowledge graphs:Biomedical literature extraction combined with structured drug-target databases is enabling automated hypothesis generation for pharmaceutical R&D pipelines.
- Outcome-based reimbursement in US Medicare:Value-based care models incentivizing reduced documentation burden are accelerating hospital procurement of ambient clinical intelligence systems.
Industry Challenges
- Clinical informaticist shortage:The gap between available talent and demand for professionals who bridge medicine, linguistics, and machine learning is constraining implementation velocity at mid-sized health systems.
- Legacy EHR integration complexity:Proprietary data formats and fragmented API ecosystems at Epic, Cerner, and MEDITECH deployments require custom pipeline engineering for each hospital network.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NLP in Healthcare and Life Sciences Market |
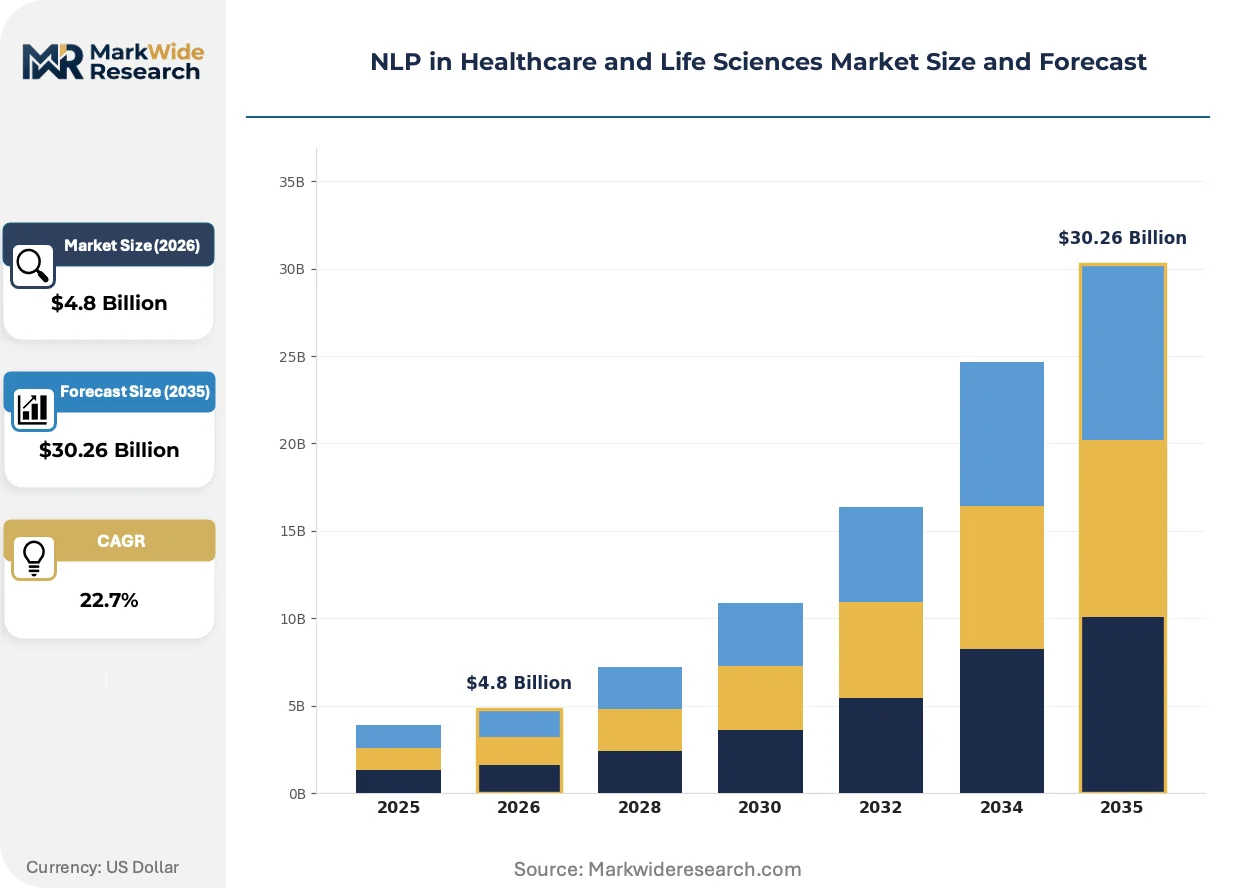
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text Analysis, Speech Recognition, Machine Translation, Predictive Analytics Application: Clinical Documentation, Patient Engagement, Drug Discovery, Medical Coding End User: Hospitals, Pharmaceutical Companies, Research Institutions, Insurance Providers Technology: Machine Learning, Deep Learning, Rule-Based Systems, Hybrid Models |
| Companies Covered | Amazon Web Services, Oracle, Google, 3M Company, Nuance Communications, IQVIA, IBM, Cerner Enviza, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NLP in Healthcare and Life Sciences Market Strategic Shifts
Transformer-based architectures fine-tuned on biomedical corpora are rewriting how unstructured clinical data converts into structured, actionable intelligence. Three distinct vectors of change are reshaping competitive positioning and buyer procurement patterns.
Large language models with retrieval-augmented generation capabilities are rewriting the economics of clinical literature review. Pharmaceutical companies deploying these systems for target identification and patient stratification are compressing discovery timelines from months to weeks. Biomedical literature extraction is becoming a margin-rich service layer distinct from core NLP infrastructure licensing.
The EU AI Act's risk-classification schema for clinical decision-support tools is creating divergent compliance architectures for vendors serving European versus US markets. High-risk system designations trigger conformity assessment requirements that favor established players with notified body relationships. EMA's Good Machine Learning Practice guidance is forcing documentation standards that smaller cloud-native entrants struggle to satisfy.
Hospital procurement committees are unbundling NLP capabilities from monolithic EHR contracts and sourcing specialized vendors through metered API consumption models. This disintermediation of traditional platform vendors is visible most acutely in US academic medical centers with dedicated innovation budgets. Buyers are prioritizing explainable output formats that satisfy institutional review board requirements for clinical research applications.
NLP in Healthcare and Life Sciences Market Segmentation
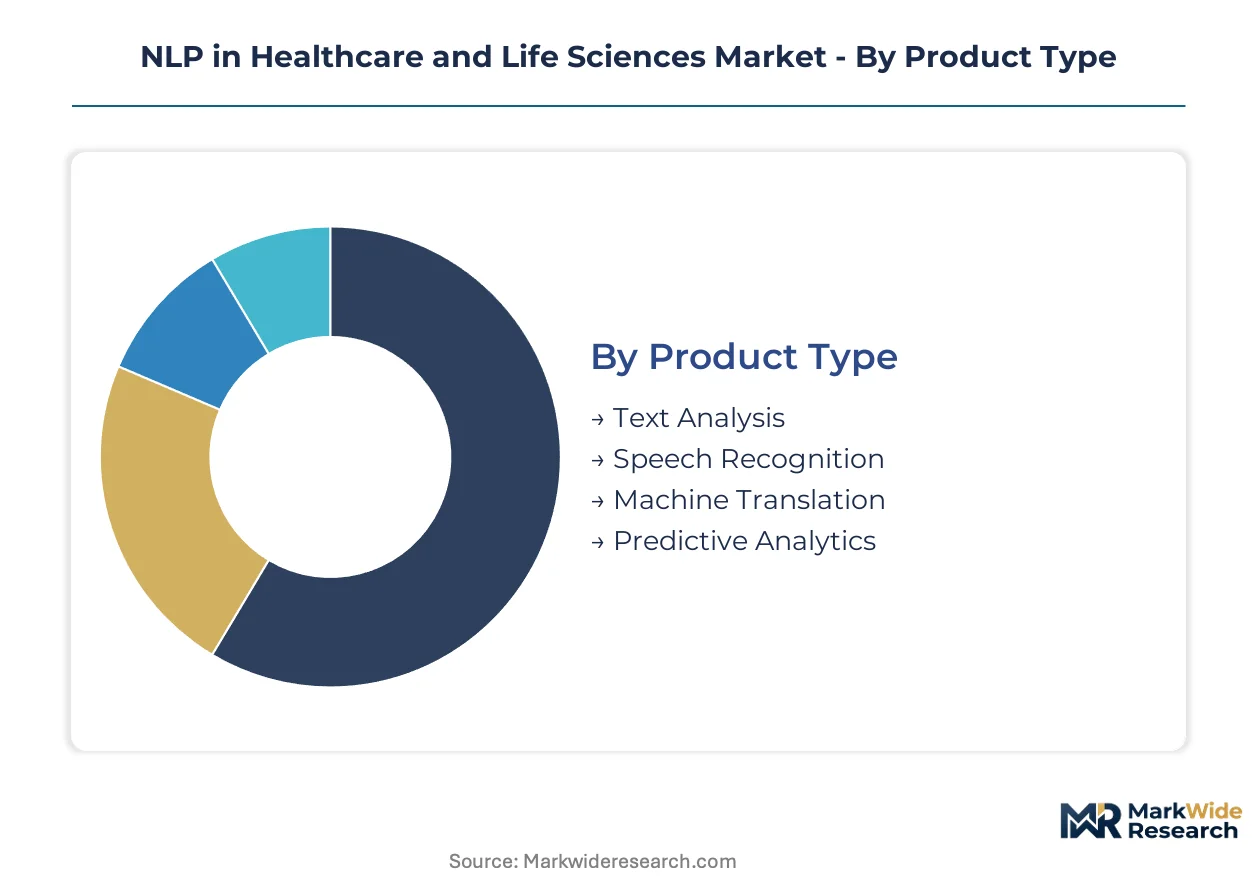
NLP deployment patterns in healthcare diverge sharply by clinical workflow, computational architecture, and procurement authority. Buyers prioritize explainability for regulatory submissions, real-time latency for bedside applications, and API flexibility for EHR integration.
Product Type:
Procurement committees weigh upfront licensing against metered consumption, with cloud-native vendors capturing share from perpetual-license incumbents.
- Text Analysis:Named entity recognition and relationship extraction from unstructured clinical notes, pathology reports, and discharge summaries. Demand concentrates in US academic medical centers automating retrospective research cohort identification under institutional review board protocols.
- Speech Recognition:Real-time voice-to-text conversion with medical vocabulary adaptation for radiology dictation and emergency department documentation. German hospital networks digitizing under federal health IT mandates are absorbing ambient clinical intelligence systems that reduce physician keyboard time.
- Machine Translation:Cross-lingual alignment of biomedical literature and patient records for multinational clinical trials. Regulatory submission packages require certified translation pipelines that hybrid neural-statistical architectures address.
- Predictive Analytics:Temporal pattern detection in longitudinal EHR data for readmission risk and sepsis early warning. Pharmaceutical companies deploy these tools for patient stratification in oncology trials.
Text Analysis leads on scale; Predictive Analytics leads on momentum.
Application:
Workflow automation potential and reimbursement alignment determine implementation sequencing across health systems.
- Clinical Documentation:Automated generation of structured encounter notes from ambient audio and EHR data synthesis. US Medicare value-based care models incentivizing reduced administrative burden accelerate hospital procurement of ambient intelligence systems.
- Patient Engagement:Conversational interfaces for symptom triage, medication adherence, and appointment scheduling. India's central government eHealth initiatives are opening addressable markets for low-cost multilingual chatbot deployments in rural health systems.
- Drug Discovery:Literature mining and hypothesis generation from biomedical corpora combined with knowledge graph traversal. Target identification timelines compress from months to weeks using retrieval-augmented generation architectures.
- Medical Coding:Automated ICD-10 and CPT code assignment from clinical notes for billing accuracy and revenue cycle optimization. Payers audit NLP-assisted coding for compliance with CMS documentation requirements.
Clinical Documentation dominates current procurement volumes; Drug Discovery exhibits the steepest expansion trajectory.
End User:
Data sovereignty requirements and validation timelines fragment vendor go-to-market strategies across buyer categories.
- Hospitals:Enterprise deployments spanning clinical documentation, coding automation, and operational analytics. Epic and Cerner EHR integration complexity forces custom pipeline engineering for each network deployment.
- Pharmaceutical Companies:R&D-focused applications in target identification, competitive intelligence, and regulatory submission preparation. EMA Good Machine Learning Practice documentation standards favor established vendors with notified body relationships.
- Research Institutions:Retrospective cohort studies and clinical trial matching using NLP-extracted phenotypes from multi-site EHR repositories. Federated learning architectures address HIPAA and GDPR cross-border restrictions.
- Insurance Providers:Prior authorization automation and fraud detection from clinical narrative review. CMS interoperability mandates accelerate claims data standardization for automated processing.
Hospitals anchor deployment volume; Pharmaceutical Companies drive premium pricing.
Technology:
Explainability requirements for FDA submissions and EU AI Act conformity assessments shape architecture selection.
- Machine Learning:Traditional supervised learning with feature engineering for clinical entity recognition and document classification. Mature installed bases in radiology reporting and emergency department triage support steady replacement demand.
- Deep Learning:Transformer architectures with domain-specific vocabularies exceeding 100,000 medical terms enabling zero-shot clinical entity recognition. GPU cluster pricing volatility creates margin pressure for real-time inference workloads.
- Rule-Based Systems:Deterministic clinical logic encoding specialist physician knowledge for high-stakes diagnostic applications. FDA 510(k) pathways for clinical decision-support tools favor transparent, auditable rule sets.
- Hybrid Models:Deep learning outputs filtered through rule-based clinical constraints for regulatory-grade explainability. Premium pricing reflects dual validation requirements for both statistical performance and clinical logic verification.
Deep Learning captures deployment volume growth; Hybrid Models command the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor deployment strategies as compliance-cost differentials between jurisdictions accelerate infrastructure migration decisions. Cloud-native NLP providers are establishing sovereign data enclaves in lower-friction regulatory environments while maintaining clinical validation operations in stringent markets.
United States
Hospital procurement of ambient clinical intelligence systems is accelerating under Medicare value-based care incentives. FDA software-as-a-medical-device frameworks clarify premarket pathways for clinical decision-support tools. The Boston-Cambridge corridor anchors pharmaceutical NLP deployments for target identification and patient stratification pipelines.
Germany
Federal health IT mandates are digitizing patient records across hospital networks under national interoperability standards. EU AI Act risk-classification requirements for clinical decision-support tools trigger conformity assessments favoring established vendors. The Rhine-Ruhr metropolitan region concentrates enterprise deployments of clinical documentation automation systems.
India
Central government eHealth initiatives are opening addressable markets for low-cost multilingual clinical speech recognition in rural health systems. CDSCO regulatory harmonization with ICH guidelines streamlines validation pathways for imported NLP tools. Karnataka's Bangalore cluster hosts indigenous health-tech ventures developing vernacular patient engagement interfaces.
United Kingdom
NHS England's AI Lab procurement frameworks are standardizing vendor selection criteria for clinical NLP applications. MHRA recognition of FDA-cleared devices accelerates market access for US-origin platforms. London's Golden Triangle research institutions deploy federated learning architectures for multi-site EHR phenotype extraction.
Japan
PMDA guidance on AI-enabled medical devices is converging with FDA predicate-device recognition for streamlined submissions. METI subsidies for digital health infrastructure reduce deployment costs at regional hospital networks. The Kansai region's Osaka-Kobe pharmaceutical corridor drives demand for biomedical literature extraction and regulatory submission automation.
NLP in Healthcare and Life Sciences Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with cloud hyperscalers capturing API consumption volumes while healthcare-native vendors command premium pricing for regulatory-grade implementations. The vendor landscape exhibits tiered concentration: dominant platform providers anchor enterprise hospital deployments, mid-scale clinical specialists occupy niche workflow automation segments, and academic spin-offs populate the research-tools fringe. Strategic moves center on EHR integration partnerships and vertical capability acquisitions that compress implementation timelines.
Within the platform-provider tier, Microsoft Corporation and Google exemplify cloud-native market positioning through metered infrastructure services, while Nuance Communications occupies a specialized position in clinical speech recognition workflows. These three anchors demonstrate divergent paths to market penetration: hyperscaler-backed breadth versus healthcare-optimized depth.
| Leading Market Players |
|---|
| Amazon Web Services |
| Oracle |
| 3M Company |
| Nuance Communications |
| IQVIA |
| IBM |
| Cerner Enviza |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees unbundling NLP capabilities from monolithic EHR contracts are forcing supply-side reconfiguration toward API-first delivery models that compress channel margins while accelerating deployment velocity. This buyer-driven shift from perpetual licensing to metered consumption is rewiring how vendors structure pricing tiers and where they locate cloud infrastructure.
Pricing Analysis
Direct-to-hospital enterprise discounts dominate high-volume deployments, with metered API consumption capturing mid-tier buyers and project-based professional services addressing complex EHR integration needs. Price differentiation rests on FDA 510(k) certification status and explainable output requirements for clinical research applications. Cost compression in cloud inference tiers is intensifying because GPU cluster pricing volatility erodes margins for real-time documentation processing. Academic medical centers with dedicated innovation budgets exhibit lowest price sensitivity, while rural health systems in price-sensitive markets demand lowest per-query rates.
Supply Chain Analysis
Regional distribution centers for cloud compute capacity concentrate in the United States, Germany, and India to satisfy data localization mandates under HIPAA and GDPR Article 9. The supply chain draws from NVIDIA GPU clusters, specialized biomedical training corpora, and clinical informaticist talent pools concentrated in Boston-Cambridge and Bangalore. Single-source vulnerability in transformer model training infrastructure poses structural risk given hyperscaler concentration. Distribution runs through direct sales teams for enterprise hospital networks and channel partners for mid-sized health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NLP in healthcare market functions as a stable compounder, with federal digitization mandates across multiple geographies ensuring sustained procurement velocity regardless of macroeconomic cycles.
For Market Incumbents: Anchor market position through exclusive EHR integration partnerships with Epic and Cerner that raise switching costs for hospital customers. Deepen backward integration into proprietary biomedical training data to defend against emerging open-source model entrants. Prioritize FDA 510(k) pathway investments for clinical decision-support modules to maintain premium pricing against uncertified competitors. For New Entrants and Emerging Players: CDSCO regulatory harmonization in India opens a window for low-cost multilingual speech recognition targeting rural health systems under central government eHealth initiatives. White-space opportunities concentrate in ambient clinical intelligence for outpatient clinics and automated medical coding for mid-sized payer organizations. A channel partnership strategy with regional health IT distributors accelerates market access without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid-model specialists combining deep learning with rule-based clinical logic for regulatory-grade explainability. Long-term viability hinges on sustainable differentiation in FDA/EMA submission support capabilities rather than raw model performance. Watch for inflection signals in pharmaceutical company R&D procurement velocity for retrieval-augmented generation literature mining tools.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Premarket clearance for clinical decision-support tools unlocks Medicare reimbursement eligibility and hospital procurement committee approval. |
| Hospital System Partnership | Exclusive EHR integration agreements with Epic or Cerner deployments create captive demand and raise competitive switching costs. |
| CE Marking Pathway | EU AI Act conformity assessment for high-risk clinical systems enables access to German hospital networks under federal digitization mandates. |
| Software Companion Development | Ambient clinical intelligence modules paired with diagnostic devices satisfy FDA software-as-a-medical-device framework requirements. |
| Reimbursement Strategy | CPT code alignment for automated documentation supports hospital CFO business cases under Medicare value-based care models. |
Study Parameters
Multiple input streams — structured interviews with hospital CIOs and clinical informaticists, pharmaceutical R&D procurement databases, and regulatory filing repositories — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged biomedical engineers, GPO contracts managers, and NLP vendor product strategists across the United States, Germany, and India. Secondary validation drew from FDA 510(k) databases, EMA Good Machine Learning Practice guidance documents, hospital procurement records, and CMS Medicare claims data. Bottom-up deployment counts by health system were triangulated against top-down vendor revenue segmentation.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with growth trajectories modeled by technology architecture, application workflow, and end-user category. Segmentation dimensions included deployment model, organization scale, EHR integration complexity, and regional regulatory cluster. CAGRs were derived from fitted adoption curves calibrated to historical EHR penetration patterns and pharmaceutical R&D automation timelines. Forecast inputs incorporated GPU cost trajectories, clinical validation study durations, and federal health IT mandate implementation schedules.
Revisions become necessary when FDA guidance on large language models in clinical settings triggers unexpected premarket submission requirements, or when EU AI Act enforcement patterns diverge from current conformity assessment assumptions. Forecasts reflect documented assumptions about regulatory pathway stability and cloud infrastructure cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Global Call Center AI Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market