
 Robotic Vision Market | 2026-2036
Robotic Vision Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Vision Market Intelligence
Production capacity for high-resolution imaging sensors in Japan and Germany is expanding to meet demand from automation integrators. This environment benefits established specialists like Cognex Corporation, which leverages its deep software expertise in inspection algorithms. Keyence Corporation competes on the basis of its direct sales model and extensive application support. FANUC Corporation integrates its vision systems directly into its own robotics platforms, controlling a significant portion of the factory automation value chain.
Robotic vision equips automated systems with the ability to interpret visual data from their environment. These systems typically integrate a camera or sensor with processing hardware and software algorithms capable of object recognition at sub-millimeter precision. The primary purpose is to guide robotic actions for tasks like inspection, navigation, or material handling. While 3D cameras represent the fastest-growing product segment, quality inspection applications continue to generate the largest share of revenue due to stringent requirements in electronics manufacturing and aerospace production.
Regulatory frameworks like the EU's Machinery Directive and safety standards from the U.S. Occupational Safety and Health Administration (OSHA) mandate fail-safes and performance criteria for collaborative robots. ISO standards for industrial automation also influence system design and interoperability requirements, shaping market access. Vendor selection will increasingly depend on the ability to provide certified systems that comply with evolving regional safety and data integrity protocols.
Market Dynamics
The central force is the push for manufacturing resilience and supply chain transparency, accelerated by policies like the EU's CSRD and China's industrial upgrade initiatives, which mandate higher levels of automated inspection and data traceability.
Growth Catalysts
- Manufacturing Automation:High-precision needs in electronics and automotive manufacturing in China and Germany drive adoption for quality control and guidance.
- Regulatory Mandates:The EU's CSRD requires production transparency met by automated inspection, while US OSHA standards promote systems for safety.
- Sensor Cost Reduction:Declining costs for high-resolution CMOS sensors from Japan make advanced vision systems more accessible to smaller enterprises.
Market Restraints
- High Integration Cost:Significant capital outlay and specialized engineering expertise are required to integrate vision systems with existing robotics, creating a barrier.
- Sensor Supply Concentration:Reliance on a few sensor manufacturers in Japan and Germany creates supply chain vulnerabilities and pricing pressure.
- Environmental Variability:Performance is sensitive to ambient light, reflections, and dust, requiring costly controls difficult to implement in industrial sites.
Strategic Opportunities
- Untapped Agricultural Sector:Applications in agriculture for automated harvesting and crop monitoring offer growth, particularly for produce in European markets.
- Logistics and Warehousing:E-commerce fuels demand for vision-guided robots for parcel sorting, palletizing, and inventory management in distribution centers.
- AI-Powered SaaS:Cloud-based AI platforms providing inspection analytics as a service lower the entry barrier for customers without in-house expertise.
Industry Challenges
- Algorithm Development Talent:A scarcity of engineers with dual expertise in machine learning and industrial automation complicates development of robust inspection algorithms.
- System Interoperability:Integrating vision systems from different vendors with various robot controllers and MES platforms remains complex due to a lack of universal communication standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Vision Market |
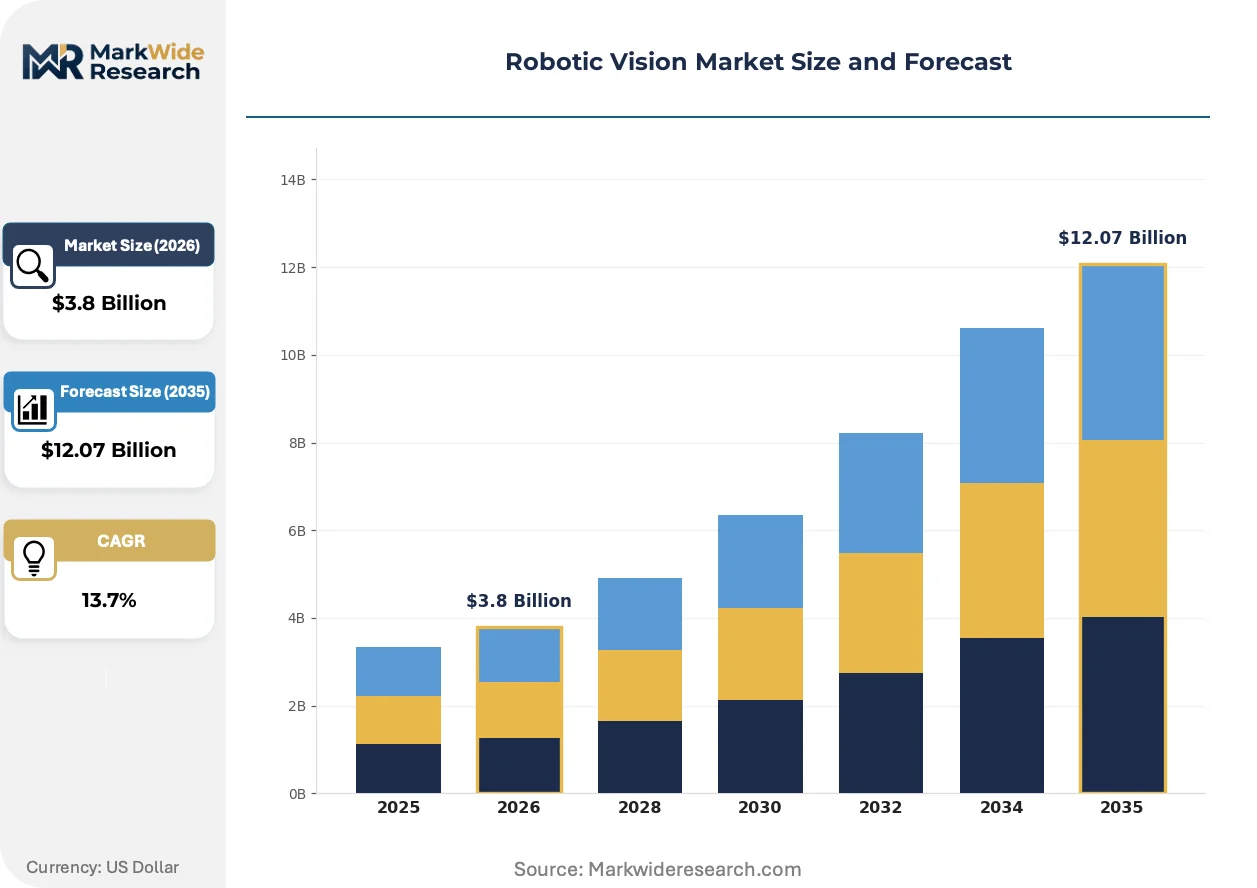
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Cameras, Machine Vision Cameras, Laser Scanners, Proximity Sensors, Thermal Cameras Technology: Structured Light, Time of Flight, Stereo Vision, LIDAR, Infrared Imaging Application: Quality Inspection, Pick and Place, Autonomous Navigation, Assembly Verification, Sorting Systems End User Industry: Electronics Manufacturing, Aerospace Production, Food Processing, Consumer Goods, Logistics Automation |
| Companies Covered | Cognex Corporation, Keyence Corporation, FANUC Corporation, Teledyne Technologies, Omron Corporation, Basler AG, Sick AG, Hexagon AB, National Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Vision Market Strategic Shifts & Innovations
Evolution in robotic vision is defined by the fusion of advanced imaging with sophisticated software intelligence. This synthesis enables systems to move beyond simple detection, interpreting complex scenes to guide more autonomous and flexible automation tasks across industries.
3D vision, using structured light or time-of-flight sensors, provides critical depth perception for complex robotic tasks. Electronics manufacturers and automotive suppliers are adopting this for bin picking and assembly guidance. This technology is converging with AI-driven point cloud processing software to enable robots to handle randomly oriented parts, reducing reliance on mechanical fixtures.
The EU AI Act introduces a risk-based framework for artificial intelligence systems, classifying many industrial robotics applications as high-risk. This regulation mandates stringent requirements for data quality, transparency, and human oversight. Consequently, vision system vendors targeting the European market must now invest heavily in documentation and certified development processes to prove compliance.
A shift toward subscription-based models for vision software and analytics is gaining traction. Instead of a large upfront capital purchase, manufacturers can access advanced inspection capabilities through a recurring fee, which includes updates and support. This model is most prominent in the food and beverage industry, where production lines frequently change.
Robotic Vision Market Segmentation
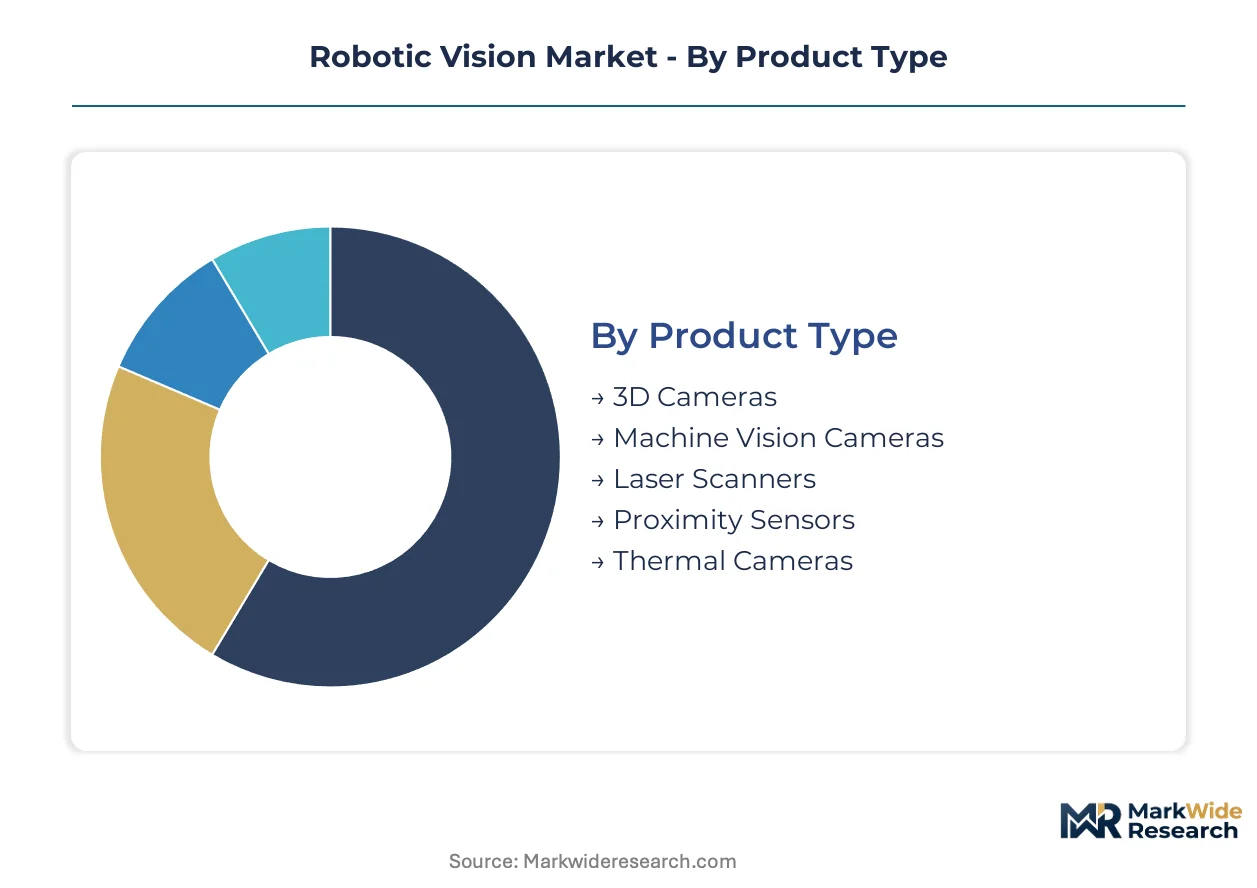
The robotic vision market categorizes solutions based on their core components, operational principles, and deployment scenarios. Understanding these distinctions helps manufacturers and integrators select systems best suited for specific industrial challenges and evolving automation requirements.
Product Type:
Manufacturers frequently evaluate existing robotic vision systems for upgrades, driving demand for newer product types that offer enhanced performance and reliability.
- 3D Cameras:These devices capture depth information using techniques like structured light or time-of-flight, providing critical perception for complex robotic tasks. Demand for 3D cameras expands quickly in electronics manufacturing for bin picking and assembly guidance.
- Machine Vision Cameras:Traditional 2D cameras form the backbone of many inspection and guidance systems, offering high-resolution imaging for detailed surface analysis. Their widespread use in quality control across automotive and general manufacturing sustains significant volume.
- Laser Scanners:These systems use laser triangulation to create precise 3D profiles of objects, often employed for metrology and quality assurance in aerospace production.
- Proximity Sensors:Basic vision components detect the presence or absence of objects, primarily used for simple navigation and collision avoidance in factory automation settings.
- Thermal Cameras:These cameras detect infrared radiation, enabling inspection of temperature profiles for quality checks or process monitoring in food processing.
Machine Vision Cameras sit at the top of the volume ranking, with 3D Cameras climbing the fastest.
Technology:
Different vision technologies present varied cost structures impacting adoption rates across diverse industrial budgets.
- Structured Light:This technique projects a known pattern onto an object and analyzes the deformation to reconstruct its 3D shape with high precision. Electronics manufacturers widely adopt structured light for sub-millimeter assembly verification.
- Time of Flight:Time of Flight sensors emit light pulses and measure the time taken for light to return, providing real-time depth maps for rapid object detection and navigation. Logistics and warehousing operations increasingly utilize this for parcel sorting.
- Stereo Vision:This technology mimics human binocular vision, using two or more cameras to calculate depth from parallax, suitable for dynamic environments in automotive assembly.
- LIDAR:Light Detection and Ranging (LIDAR) uses pulsed lasers to measure distances, creating detailed 3D maps for autonomous navigation in large-scale logistics facilities.
- Infrared Imaging:Employing non-visible light, infrared imaging detects heat signatures or provides vision in low-light conditions, important for security and specialized inspection.
Structured Light technology dominates high-precision assembly, while Time of Flight gains traction for rapid object detection.
Application:
The diverse applications of robotic vision systems directly influence their design and deployment across manufacturing and logistics.
- Quality Inspection:Robotic vision systems meticulously examine products for defects, ensuring adherence to stringent quality standards in electronics and aerospace production. This application generates the largest share of revenue due to critical regulatory requirements.
- Pick and Place:Robots equipped with vision accurately identify, locate, and manipulate objects, crucial for high-speed assembly lines and automated material handling in consumer goods manufacturing.
- Autonomous Navigation:Vision systems guide mobile robots through complex environments, enabling efficient movement and obstacle avoidance in large distribution centers.
- Assembly Verification:These systems confirm correct component placement and assembly sequences, preventing errors in complex manufacturing processes like automotive sub-assembly.
- Sorting Systems:Vision-guided robots categorize and separate items based on visual characteristics, enhancing efficiency in recycling plants and food processing lines.
Quality Inspection applications generate the largest revenue share, with Pick and Place increasing in complexity and adoption.
End User Industry:
Industrial automation volumes vary significantly across end-user industries, shaping the specific requirements for robotic vision deployment.
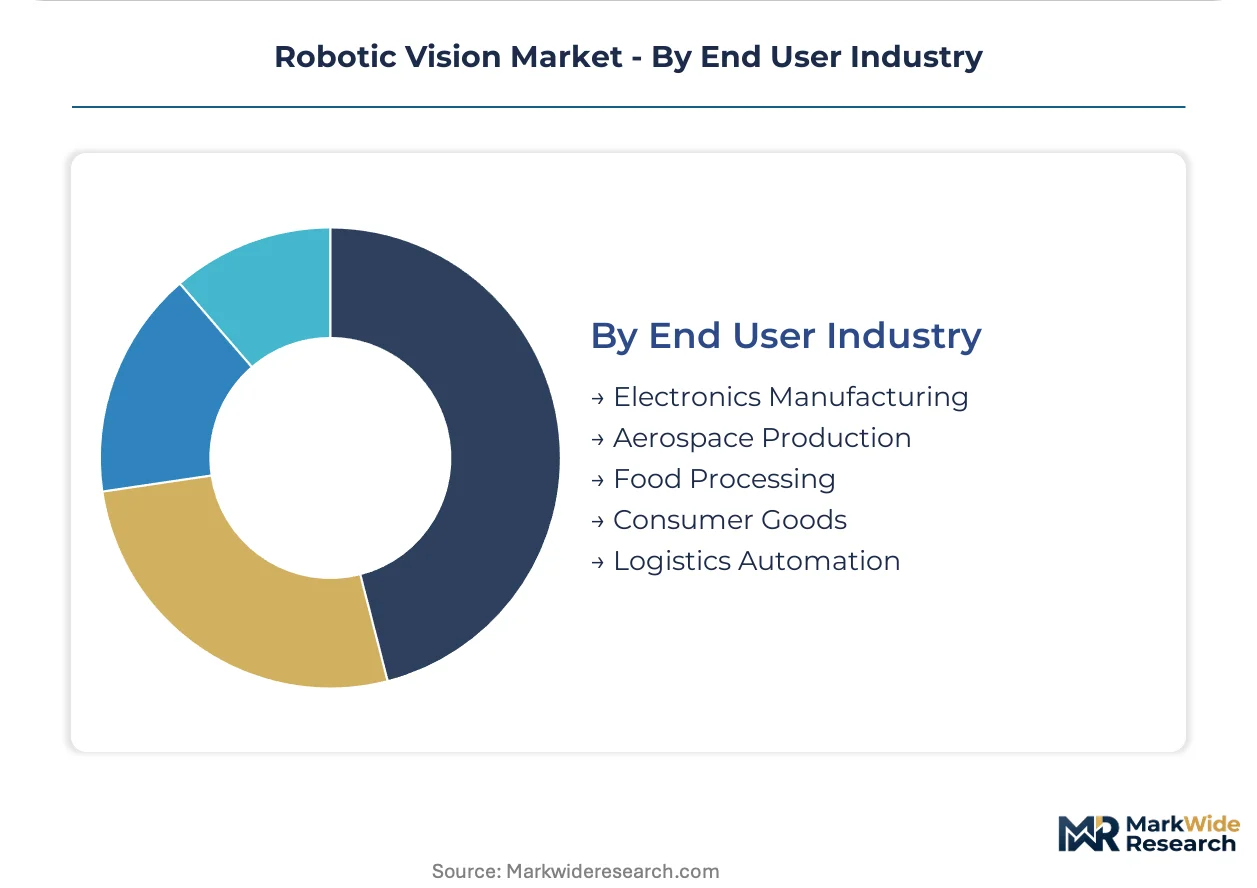
- Electronics Manufacturing:This sector requires robotic vision for high-precision assembly, quality control of minute components, and automated inspection to meet production transparency directives like the EU's CSRD. Demand concentrates in manufacturing hubs in China and Germany.
- Logistics Automation:E-commerce growth drives demand for vision-guided robots in warehouses for tasks such as parcel sorting, inventory management, and palletizing. This sector is expanding rapidly across global distribution networks.
- Aerospace Production:Stringent safety and quality requirements in aerospace drive the use of robotic vision for detailed inspection of critical components and assembly verification.
- Food Processing:Vision systems perform quality checks on produce, sort items by size and color, and ensure hygiene compliance in automated food production lines.
- Consumer Goods:Manufacturers use robotic vision for high-speed inspection, packaging verification, and assembly of diverse consumer products.
Electronics Manufacturing remains a core demand driver, as Logistics Automation expands its use of vision-guided robots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rapid industrial upgrade initiatives significantly boost robotic vision adoption, while Germany's focus on high-precision manufacturing also drives demand. Both nations prioritize automated inspection for quality control. This global market sees diverse regional drivers shaping its expansion.
China
Demand for robotic vision systems in China stems from electronics and automotive manufacturing for quality control and assembly guidance. China's industrial upgrade initiatives, including "Made in China 2025," mandate higher automation levels. Major manufacturing clusters in the Pearl River Delta and Yangtze River Delta are integrating advanced vision for production efficiency.
Germany
Germany's advanced manufacturing sector, particularly automotive and machinery, drives demand for high-precision robotic vision for assembly verification and inspection. The EU's Corporate Sustainability Reporting Directive (CSRD) pushes German firms towards automated inspection to improve production transparency. Bavaria and North Rhine-Westphalia house significant automation integrators expanding capacity for vision system deployment.
Japan
Japanese manufacturers are expanding production capacity for high-resolution imaging sensors, meeting global demand from automation integrators. Japan's METI promotes advanced robotics and automation, encouraging domestic adoption of vision-guided systems. Industrial areas around Tokyo and Nagoya are centers for sensor innovation and precision robotics development.
United States
Manufacturing automation in the United States, particularly in aerospace and electronics, relies on robotic vision for stringent quality inspection and assembly verification. US Occupational Safety and Health Administration (OSHA) standards promote vision systems for enhancing worker safety in collaborative robot applications. The Midwest industrial belt and West Coast tech hubs are adopting vision-guided robots for logistics and production.
France
French automotive and consumer goods sectors increasingly adopt robotic vision for high-speed inspection and pick-and-place applications. The EU AI Act introduces a risk-based framework for AI systems, impacting vision system vendors targeting the French market. Industrial clusters in Auvergne-Rhône-Alpes and Île-de-France are integrating certified vision systems into their advanced manufacturing lines.
Robotic Vision Market Key Industry Players
Japanese producers anchor one tier, emphasizing sensor technology and direct sales models; German specialists hold another, focusing on integrated factory automation solutions. The market structure exhibits a tiered consolidation, with established players leveraging deep software expertise. Three strategic archetypes include integrated automation providers, vision component specialists, and software-centric solution providers. Dominant competitive moves involve strategic partnerships for system integration and capacity expansion in high-resolution sensor manufacturing.
Within the integrated automation provider archetype, FANUC Corporation exemplifies a strategy of incorporating vision systems directly into its robotics platforms, controlling a significant portion of the factory automation value chain through comprehensive offerings. Cognex Corporation represents established specialists leveraging deep software expertise in inspection algorithms, providing advanced capabilities for quality control across diverse manufacturing environments requiring high precision. Keyence Corporation, a Japanese entity, anchors the direct sales model and extensive application support, positioning itself as a provider of readily deployable vision solutions that cater to a broad customer base seeking ease of integration.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| FANUC Corporation |
| Teledyne Technologies |
| Omron Corporation |
| Basler AG |
| Sick AG |
| Hexagon AB |
| National Instruments Corporation |
Cost & Logistics Intelligence
Engineers with dual expertise in machine learning and industrial automation command premium salaries, directly influencing pricing tiers for advanced robotic vision solutions. This talent concentration, particularly in Germany and Japan, creates cost differentials across the market.
Pricing Analysis
Capacity additions in Germany for automation integrators are reshaping price floors for complete robotic vision systems. Subscription-based models for vision software and project-based pricing for complex integrations dominate the market. Price differentiation stems from the level of EU AI Act compliance certification and the degree of system customization required. Cost compression in hardware components exerts downward pressure, yet stringent regulatory requirements maintain premium pricing for certified solutions. Smaller enterprises exhibit higher price sensitivity compared to aerospace and electronics manufacturers.
Supply Chain Analysis
Rising global freight costs impact the final price of robotic vision systems, especially for components sourced from specialized regions. Geographic supply concentrates in Japan for high-resolution CMOS sensors and in Germany for advanced automation integrators. The market relies heavily on these critical components, creating single-source vulnerability within the sensor segment. Distribution runs through direct sales models, exemplified by Keyence Corporation, and through a network of automation integrators who provide customized system deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic vision market presents a compelling margin-expansion story, driven by the shift towards AI-powered SaaS models that offer recurring revenue and specialized analytics. This evolution allows vendors to capture higher value beyond initial hardware sales.
For Market Incumbents:Acquire specialized AI software firms to deepen expertise in inspection algorithms and maintain competitive positioning against emerging SaaS providers. Invest significantly in certified development processes to meet EU AI Act requirements, mitigating regulatory compliance as a threat. Expanding capacity in high-resolution sensor manufacturing through R&D partnerships can secure critical upstream supply.
For New Entrants and Emerging Players:Small and medium-sized manufacturers represent an underserved buyer archetype, seeking accessible robotic vision solutions. Target the untapped agricultural sector for automated harvesting and the logistics market for inventory management in smaller distribution centers. The food and beverage industry offers a penetrable segment, amenable to subscription-based software models due to frequent production line adjustments. Offer cloud-based AI platforms as a service, lowering the entry barrier for customers without in-house expertise.
For Investors and Strategic Acquirers:Valuations sit cheapest among component specialists with concentrated sensor supply, offering attractive entry points for strategic consolidation. The market exhibits strong long-term viability, underpinned by accelerating manufacturing automation and regulatory mandates for production transparency. Target acquisition profiles include AI algorithm development firms and 3D vision software providers that enhance system flexibility. The signal to watch is the accelerated adoption rate of EU AI Act-certified vision systems across European industrial clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand High-Resolution Sensor Production | Secures critical supply for automation integrators and meets global demand from Japan. |
| Invest in AI Algorithm Development | Enhances object recognition capabilities and supports complex tasks in electronics manufacturing. |
| Pursue EU AI Act Certification | Ensures market access and builds trust for vision systems in the European market. |
| Develop Subscription-Based Software | Lowers entry barriers for smaller enterprises and provides recurring revenue in food processing. |
| Integrate Vision with Robotics Platforms | Offers comprehensive factory automation solutions, similar to FANUC Corporation's strategy. |
Research Approach
Direct dialogue with automation integrators, electronics manufacturing engineers, logistics managers, and vision system developers informed the qualitative insights. This primary research was validated through extensive secondary data sources, including corporate financial reports, industry association publications, and regulatory body directives. A robust bottom-up and top-down triangulation approach ensured data consistency across all market segments.
A bottom-up analytical lens, cross-referenced with top-down market sizing, defined the forecast framework over the projection horizon. Segmentation dimensions included product type, core technology, application, end-user industry, and regional adoption patterns. Compound annual growth rates were derived from historical trends, projected adoption rates, and anticipated technological advancements. Key forecast inputs included manufacturing output forecasts and industrial automation investment trends.
Inputs from public financial disclosures and regulatory filings were available through the study window; gaps in real-time supply chain disruption data introduce uncertainty bands. Forecasts reflect assumptions regarding geopolitical trade stability and consistent technology adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
AI Recruitment Market
Artificial Intelligence (AI)
Egypt Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
AI Content Creation Tool Market