
 Preschool Education Software Market | 2026-2036
Preschool Education Software Market Size, Share, and Industry Trends Forecast 2026-2036
Preschool Education Software Market Insights
North American edtech infrastructure investment is repositioning competitive dynamics across early childhood technology. Brightwheel leverages its integrated billing and classroom management stack to anchor market presence among multi-site operators. Procare Software sustains dominance through deep functionality in tuition processing and family engagement portals. HiMama competes aggressively on parent communication features, while Khan Academy Kids differentiates through adaptive learning pathways designed for developmental appropriateness.
Preschool education software encompasses digital platforms engineered to deliver curriculum management, developmental assessment, family communication, and administrative automation for learners typically aged three to five years. These systems operate through cloud-native architectures with API interoperability standards enabling data exchange between classroom devices, parent mobile applications, and state reporting systems. Learning Management Systems currently occupy the largest installed base, while Assessment Tools represent the fastest-expanding category as accountability requirements intensify. Cloud-Based delivery models are displacing On-Premises installations where capital constraints and IT staffing limitations dominate purchasing decisions.
The US Department of Education coordinates with state-level agencies to enforce Head Start Performance Standards that mandate digital documentation of child outcomes, directly stimulating platform procurement. GDPR in Europe and COPPA in the United States impose strict data minimization and parental consent protocols that reshape product architecture decisions for vendors serving cross-border markets. Stakeholders must monitor evolving interoperability mandates from the country's national education technology regulator as procurement shifts toward outcome-linked platform requirements rather than feature-based selection.
Market Dynamics
Cloud-native Learning Management Systems are compressing procurement cycles across multi-site preschool operators, forcing legacy vendors to rearchitect delivery models or cede share to API-first platforms.
Growth Catalysts
- Head Start Performance Standards:US Department of Education mandates for digital child outcome documentation create baseline procurement requirements across federally funded centers.
- Multi-site operator expansion:Private preschool chains prioritize integrated billing and classroom management stacks to standardize operations across geographically dispersed locations.
- State quality rating systems:Subsidized providers in Texas, California, and New York must submit assessment data through approved platforms, locking in vendor relationships.
Market Restraints
- COPPA compliance costs:Parental consent protocols and data minimization requirements inflate product development budgets for cross-border vendors.
- IT staffing scarcity:Rural early childhood providers lack technical personnel to configure on-premises installations, limiting addressable market for non-cloud solutions.
- Free alternatives:Khan Academy Kids and public library digital resources reduce willingness-to-pay among price-sensitive family childcare operators.
Strategic Opportunities
- Assessment Tools convergence:Developmental screening and state reporting functionality represents the fastest-expanding category as accountability requirements intensify.
- API interoperability standards:Vendors enabling seamless data exchange between classroom devices, parent mobile applications, and state systems capture multi-year contracts.
- Family engagement portals:Parent communication features command premium pricing in urban markets where competitive differentiation drives enrollment decisions.
Industry Challenges
- Interoperability mandate complexity:National education technology regulator requirements for outcome-linked platform selection compress vendor response timelines.
- GDPR-COPPA dual compliance:Vendors serving both European and US markets must maintain divergent data architectures, fragmenting engineering resources.
- Legacy system integration:Established providers with on-premises historical data resist migration to cloud-native architectures despite total cost of ownership advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preschool Education Software Market |
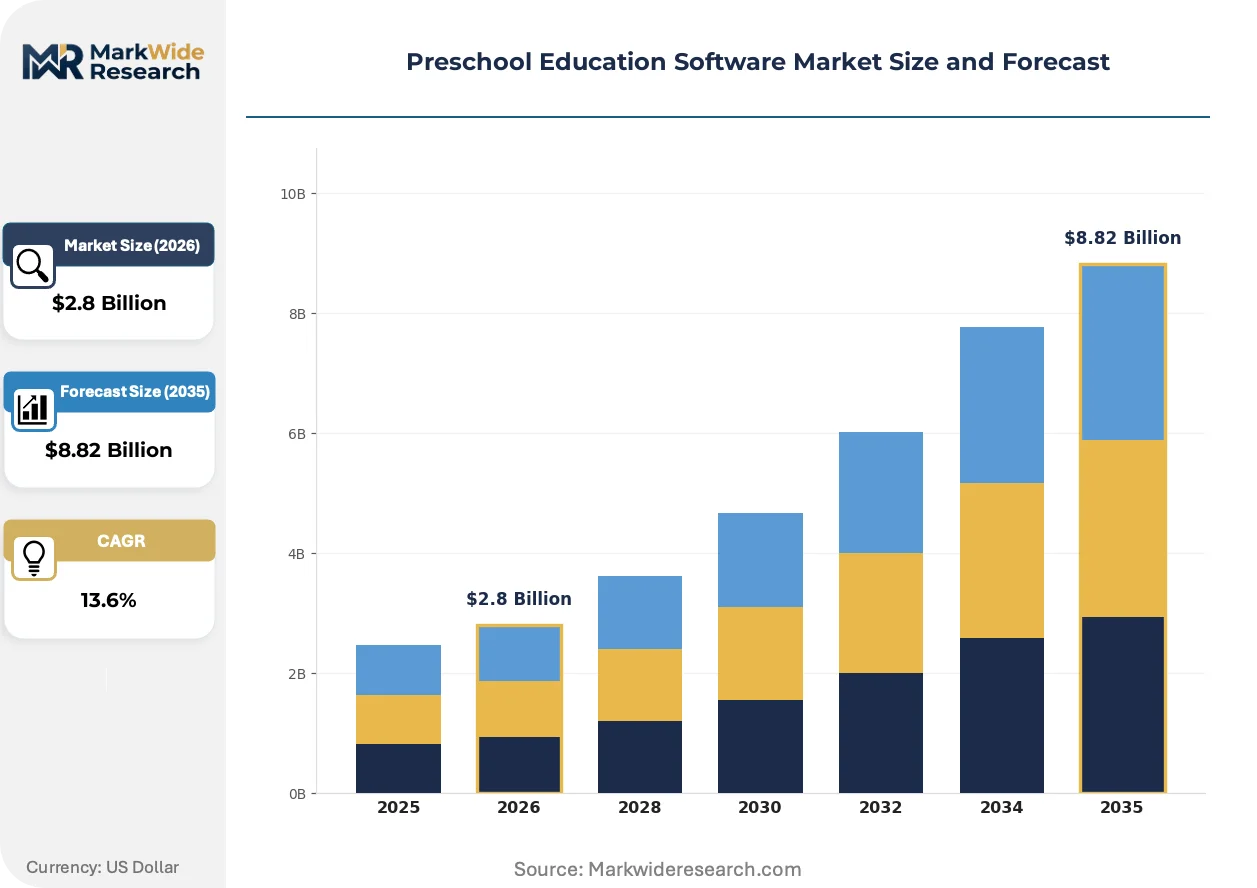
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Assessment Tools, Interactive Games, Curriculum Software Delivery Model: Cloud-Based, On-Premises, Hybrid, Subscription-Based End User: Preschools, Parents, Educational Institutions, Child Care Centers Feature: Progress Tracking, Communication Tools, Customizable Curriculum, Interactive Activities |
| Companies Covered | Brightwheel, Procare Software, HiMama, ABCmouse, Khan Academy Kids, Duolingo, Lingokids, LifeCubby, Kangarootime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preschool Education Software Market Trends and Innovations
Adaptive learning pathways and AI-powered developmental screening are redefining product architecture priorities, compressing the feature gap between premium platforms and mid-market alternatives.
Artificial intelligence-driven assessment engines analyze behavioral patterns from classroom device interactions to flag potential developmental delays for educator review. Head Start programs and state-subsidized centers in Illinois and Florida are piloting these tools to satisfy outcome documentation requirements. The technology is consolidating previously separate assessment and curriculum planning workflows into unified platforms, reducing vendor count per operator.
COPPA enforcement actions by the Federal Trade Commission have intensified scrutiny of third-party data sharing in children's applications. Vendors now embed privacy-by-design architectures and parental consent management as core product features rather than compliance add-ons. Assessment Tools vendors serving cross-border markets bear the highest compliance burden, reengineering data flows to satisfy both US and European requirements.
Subscription pricing models with usage-based tiers are displacing perpetual licenses among capital-constrained family childcare providers. Brightwheel and Procare Software have restructured offerings to capture this segment with lower entry points. Urban multi-site operators in metropolitan Texas and California markets exhibit the fastest migration toward these flexible commercial terms.
Preschool Education Software Market Segmentation
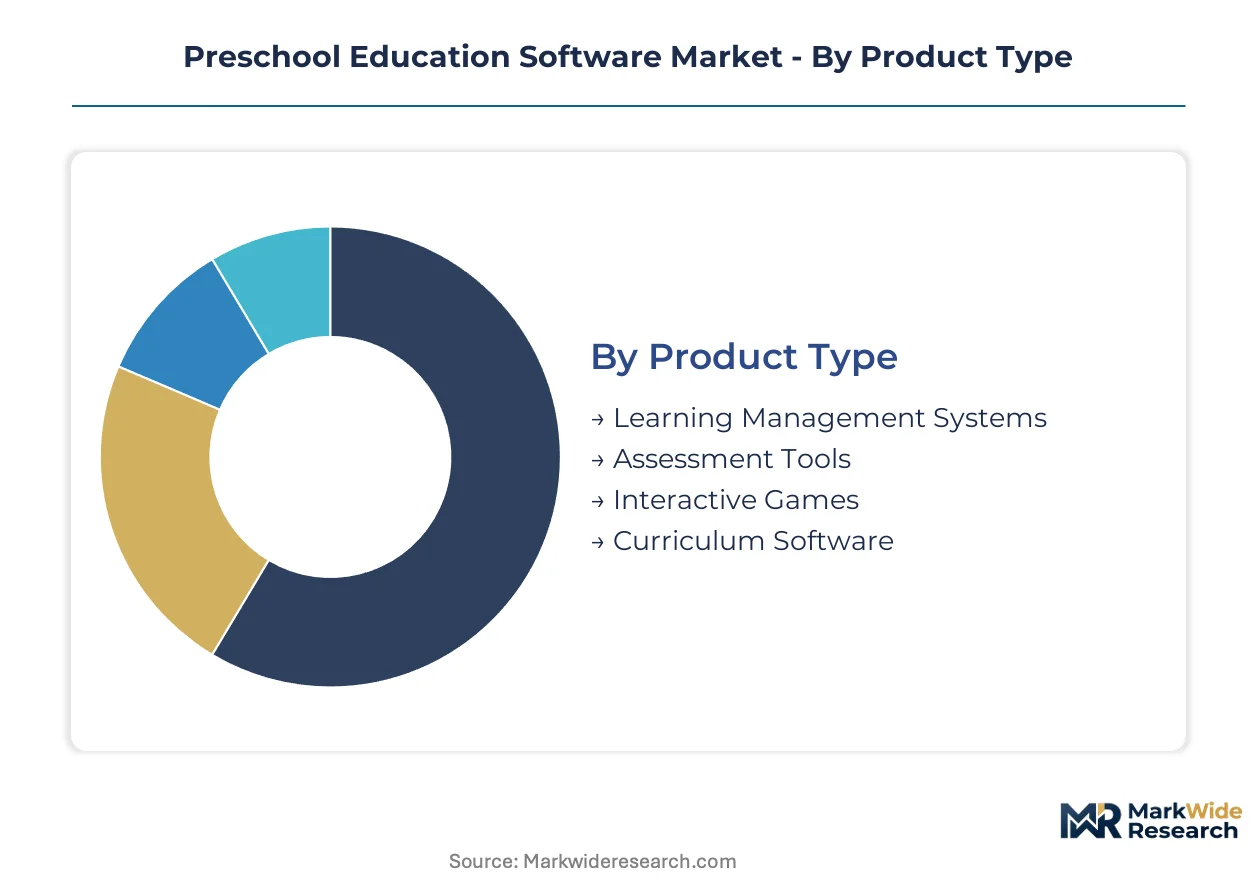
Segmentation in preschool education software reveals how procurement decisions split between administrative efficiency and pedagogical outcomes. Vendors must architect products for divergent buyer priorities across institutional scale, technical infrastructure, and regulatory exposure.
Product Type:
Learning Management Systems anchor installed base volume while Assessment Tools capture premium expansion as accountability mandates intensify.
- Learning Management Systems:Cloud-native platforms consolidating lesson planning, attendance tracking, and digital portfolio management. Demand concentrates among multi-site operators in Texas and California seeking operational standardization across dispersed locations.
- Assessment Tools:Developmental screening engines with state reporting interoperability for Head Start compliance. Illinois and Florida pilot programs are accelerating procurement as federally funded centers digitize outcome documentation workflows.
- Interactive Games:Play-based learning modules targeting cognitive and motor skill development.
- Curriculum Software:Standards-aligned content libraries with customization tools for state early learning guidelines.
Today's leader: Learning Management Systems. Tomorrow's challenger: Assessment Tools.
Delivery Model:
Cloud architectures dominate new procurement while hybrid deployments persist where legacy data migration costs deter full transition.
- Cloud-Based:API-first platforms with automatic updates and multi-device accessibility. Rural providers lacking IT staffing drive fastest adoption as capital constraints eliminate on-premises alternatives.
- On-Premises:Local server installations with full data sovereignty control. Urban districts with dedicated technology departments sustain demand where COPPA compliance complexity favors internal network isolation.
- Hybrid:Mixed infrastructure preserving historical records on-site while routing new workflows through cloud services.
- Subscription-Based:Usage-tiered pricing with monthly billing cycles reducing upfront capital requirements for family childcare operators.
Cloud-Based deployments hold current volume leadership. Subscription-Based commercial terms are gaining fastest among price-sensitive segments.
End User:
Institutional buyers prioritize administrative integration while parent-facing applications command urban premium pricing.
- Preschools:Licensed early childhood centers requiring comprehensive stacks spanning classroom management, billing, and family engagement.
- Parents:Consumer-grade applications for home learning supplementation with progress dashboards and activity recommendations.
- Educational Institutions:School district procurement offices mandating interoperability with existing student information systems.
- Child Care Centers:Family childcare homes and small group providers seeking lightweight solutions with minimal configuration overhead.
Preschools anchor current revenue concentration. Child Care Centers represent the steepest expansion trajectory as informal providers formalize operations.
Feature:
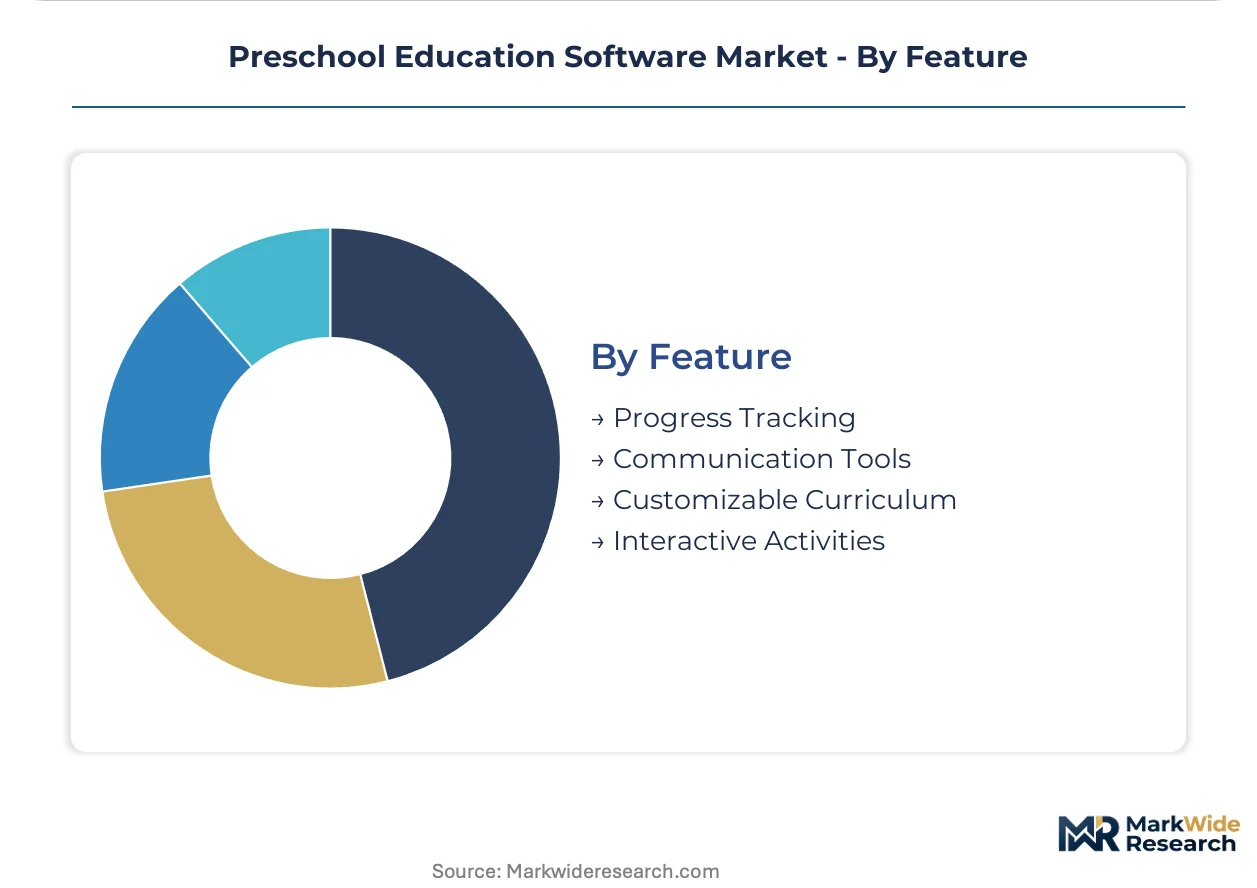
Communication functionality differentiates premium tiers while progress tracking becomes table stakes across all price segments.
- Progress Tracking:Individual child development dashboards with milestone mapping against state early learning standards.
- Communication Tools:Real-time messaging, photo sharing, and announcement distribution between educators and families.
- Customizable Curriculum:Content authoring interfaces allowing adaptation to program philosophy and regulatory requirements.
- Interactive Activities:Touch-optimized exercises with adaptive difficulty scaling based on demonstrated competency.
Communication Tools currently command pricing premiums. Interactive Activities are climbing fastest as adaptive learning engines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance cost disparities between jurisdictions are redirecting vendor engineering resources toward markets with streamlined data protection frameworks. Cloud infrastructure providers concentrate development operations in regions offering regulatory clarity for children's digital services.
United States
Head Start Performance Standards mandate digital documentation of child outcomes across federally funded centers. The FTC enforces COPPA with escalating penalties for third-party data sharing violations. Texas and California multi-site operators drive procurement volume as state quality rating systems lock in approved vendor relationships.
United Kingdom
Early years providers accelerate cloud migration to satisfy Ofsted inspection readiness requirements. The Information Commissioner's Office applies GDPR with sector-specific guidance for educational technology procurement. London-based nursery chains standardize on integrated platforms spanning billing, assessment, and parent communication.
Germany
Kita digitization programs receive federal funding for administrative automation and developmental tracking. The Federal Commissioner for Data Protection and Freedom of Information maintains strict consent protocols for children's biometric data. Bavarian municipal operators pilot API-first platforms linking classroom devices to state early education databases.
Canada
Provincial childcare expansion agreements prioritize technology infrastructure for licensed home providers. The Office of the Privacy Commissioner applies PIPEDA with provincial variations creating compliance complexity. Ontario's Greater Toronto Area concentrates vendor deployment as municipal quality rating systems mandate digital assessment submission.
Australia
National Quality Framework assessments drive demand for documentation platforms satisfying regulatory evidence requirements. The Office of the Australian Information Commissioner enforces the Privacy Act with children's data breach notification obligations. New South Wales and Victoria early learning networks standardize procurement across multi-site Catholic and community-based providers.
Preschool Education Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-powered assessment specialization. The vendor base clusters around three functional archetypes: integrated administrative suites, parent communication specialists, and adaptive learning engines. Consolidation pressure intensifies as multi-site operators demand single-stack solutions. Dominant competitive moves include API interoperability partnerships and subscription pricing restructuring for capital-constrained segments.
Within the integrated platform tier, Brightwheel and Procare Software exemplify scale-driven incumbents anchoring procurement relationships with multi-site operators. HiMama occupies a position among communication-focused specialists competing on parent engagement functionality. These three entities represent divergent strategic bets on whether administrative efficiency or family engagement commands stronger pricing power in urban markets.
| Leading Market Players |
|---|
| Brightwheel |
| Procare Software |
| HiMama |
| ABCmouse |
| Khan Academy Kids |
| Duolingo |
| Lingokids |
| LifeCubby |
| Kangarootime |
| Others |
Pricing and Supply Chain Analysis
COPPA compliance architecture gates qualified supply and premium-tier pricing access, as vendors serving US early childhood centers must embed parental consent management and data minimization protocols as core product features rather than compliance add-ons. Cloud-native platforms with pre-certified privacy-by-design stacks command subscription premiums from multi-site operators in Texas and California, while capital-constrained family childcare providers face exclusion from top-tier functionality due to implementation cost barriers.
Pricing Analysis
Distributor margins in the indirect channel run 15-25 percent for value-added resellers serving rural early childhood providers, compressing vendor net pricing in segments where direct salesforce coverage proves uneconomical. Subscription-based SaaS tiers dominate, with premium pricing anchored to assessment tool integration depth and state reporting interoperability. Price differentiation stems from certification level (COPPA-compliant vs. non-compliant architectures) and customization scope for multi-site operator standardization. Cost compression in the mid-market intensifies as Khan Academy Kids and public library resources reduce willingness-to-pay among price-sensitive buyers. Family childcare operators exhibit highest price sensitivity; urban multi-site chains with quality rating system mandates show lowest.
Supply Chain Analysis
Workforce availability for cloud infrastructure engineering concentrates in the United States, Ireland, and India, with Dublin and Bangalore serving as primary development hubs for vendors targeting GDPR-COPPA dual compliance. Platform development draws from specialized talent pools in machine learning, API architecture, and early childhood pedagogy. Raw material dependencies span cloud compute capacity from AWS, Azure, and Google Cloud; mobile SDKs for iOS and Android; and third-party assessment content libraries. Single-source vulnerability in hyperscaler infrastructure poses concentration risk. Distribution runs through direct enterprise sales for multi-site operators and value-added reseller networks for smaller providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in preschool education software rests on cloud delivery cost curves and premium-tier assessment tool bundling, as vendors consolidate previously separate administrative and pedagogical workflows into unified platforms.
For Market Incumbents: Anchor procurement relationships through API interoperability investments that lock in multi-year contracts with state-subsidized providers facing quality rating system mandates. Deepen defensive moats by acquiring specialized assessment tool vendors in Illinois and Florida pilot markets, neutralizing emerging entrant threats from AI-powered developmental screening specialists. Prioritize backward integration into proprietary content libraries to reduce third-party licensing costs and improve gross margins. For New Entrants and Emerging Players: Regional franchise development organizations offer the most penetrable channel partnership pathway, as these aggregators standardize technology procurement across dozens of independently operated centers. Target rural family childcare providers in states with expanding subsidy programs but limited vendor presence, where lightweight cloud solutions with minimal configuration overhead address unmet demand. Pursue white-label licensing to established childcare management consultants as a capital-efficient go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among assessment tool specialists with proven state reporting interoperability but limited administrative functionality breadth. Long-term viability over the five-to-ten year window favors vendors with diversified revenue across Head Start, private multi-site, and international early years markets. Watch Head Start program funding authorization cycles as the critical inflection signal for federal procurement volume.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates billing, assessment, and communication workflows for Texas multi-site operators. |
| Strategic Partnership | API interoperability agreements with state early education databases secure California procurement mandates. |
| Acquisition of Specialist Firm | AI-powered developmental screening engines fill capability gaps in legacy administrative suites. |
| Geographic Expansion | Kita digitization funding in Germany opens addressable market for COPPA-GDPR dual-compliant architectures. |
| Product Launch | Usage-based subscription tiers capture price-sensitive family childcare operators in Ontario expansion zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with preschool operations directors, early childhood technology procurement officers, state agency program administrators, and edtech platform product managers with secondary validation against SEC filings, Head Start program data releases, state quality rating system vendor approval lists, and cloud infrastructure hyperscaler capex disclosures. Bottom-up sizing from individual provider counts and top-down triangulation from aggregate software spending estimates converged on segment-level outputs.
Historical reference periods anchored the projection horizon to documented procurement cycles preceding Head Start digitization mandates and state quality rating system expansions. The analytical framework modeled deployment model, organization scale, regulatory compliance tier, and regional adoption pattern as core segmentation dimensions. CAGRs derived from fitted growth curves incorporating policy implementation timelines, multi-site operator expansion rates, and cloud migration velocity across rural and urban provider clusters.
Revisions become necessary when federal early childhood funding authorization delays, COPPA enforcement action escalations, or hyperscaler infrastructure pricing shocks materialize. Forecasts reflect documented assumptions regarding policy continuity and technology adoption elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Global Animation Software Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Account-Based Data Software Market
Software & Services
Server Virtualization Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Gym Management Software Market
Software & Services
Labor Management Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Global Referral Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Global Mindfulness Meditation Apps Market
Software & Services
Sales Training Software Market
Software & Services
Yacht Management Software Market