
 Global SAP S-4HANA Application Market | 2026-2036
Global SAP S-4HANA Application Market Size, Share, and Industry Trends Forecast 2026-2036
Global SAP S-4HANA Application Market Foresight
Mid-market manufacturers is redrawing demand patterns away from legacy SAP ECC holdouts across industrial verticals. Accenture leverages its deep SAP partnership and industry templates to anchor large-scale transformation programs. Deloitte competes through risk-advisory integration, embedding compliance and governance into S-4HANA rollouts. IBM sustains relevance via hybrid cloud orchestration, connecting on-premise SAP estates with public cloud analytics layers.
SAP S-4HANA is an intelligent ERP suite built on SAP HANA's in-memory database, enabling real-time transactional processing and advanced analytics within a unified data model. Its primary purpose is to replace legacy ECC systems with simplified data structures, Fiori user experience, and embedded artificial intelligence for predictive operations. Cloud deployment options are capturing the fastest growth trajectory as enterprises exit datacenter ownership, while Finance and Supply Chain solution offerings concentrate the deepest margin pools due to complexity and recurring advisory attach rates. Automotive OEMs represent the most vertically penetrated industry segment, though Pharmaceuticals shows accelerating interest driven by serialization and batch traceability requirements.
Germany's BSI and the EU's GDPR and CSRD frameworks shape S-4HANA demand by mandating auditable data lineage, sustainability disclosure automation, and cross-border governance controls. The EU AI Act adds algorithmic transparency requirements that SAP's embedded machine learning must satisfy, pushing buyers toward certified implementation partners with regulatory expertise. Stakeholders must monitor how rapidly national cloud sovereignty laws fragment deployment architectures and determine whether hybrid strategies preserve operational flexibility or create compliance complexity.
Market Dynamics
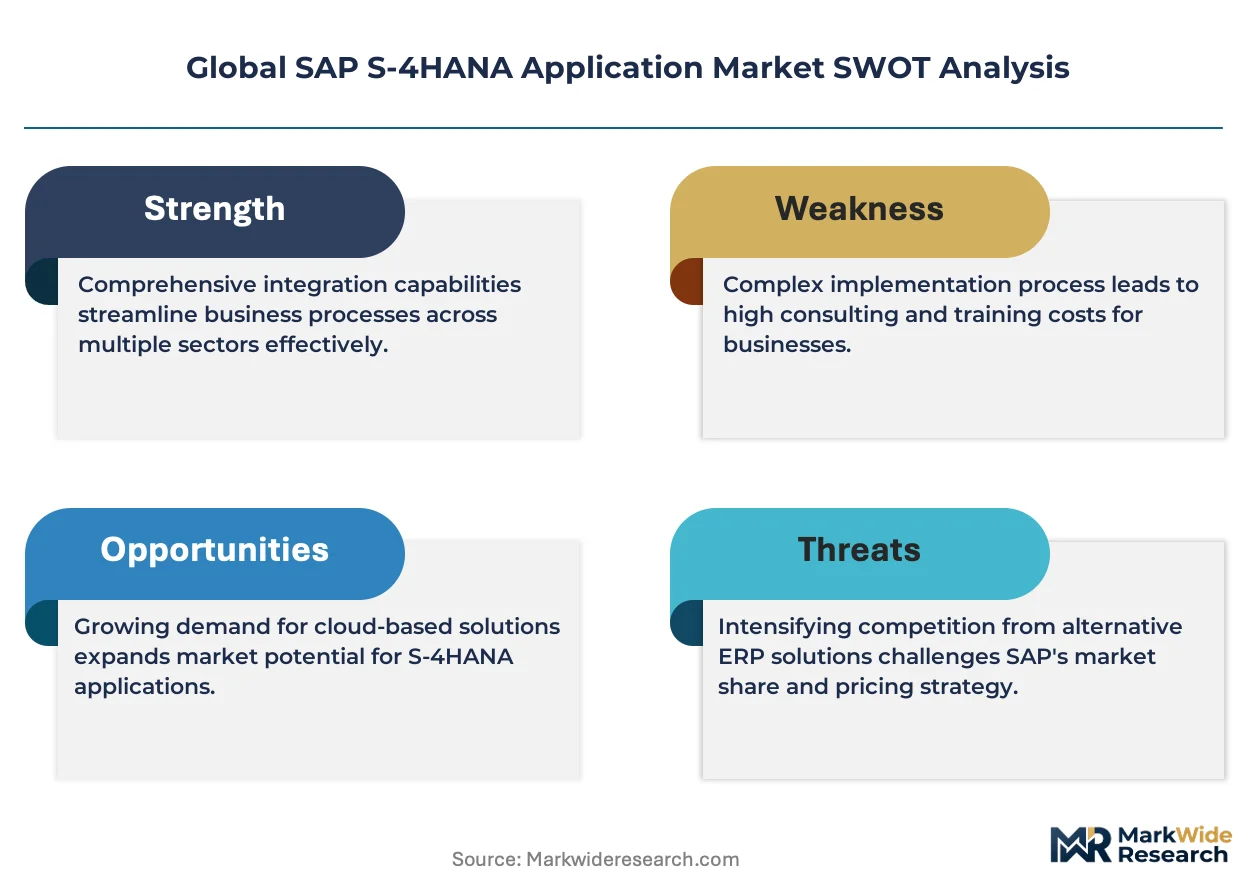
The migration from on-premise SAP ECC to cloud-native S-4HANA deployments is compressing implementation timelines while expanding the addressable base of mid-market manufacturers previously locked out by capital intensity.
Growth Catalysts
- CSRD Mandates:Europe's Corporate Sustainability Reporting Directive requires auditable ESG data pipelines that S-4HANA's embedded analytics modules automate, forcing disclosure-heavy industries toward integrated ERP upgrades.
- Automotive Supplier Consolidation:German OEM tier-one networks are mandating S-4HANA interoperability for vendor qualification, transmitting compliance pressure down multi-tier supply chains.
- Clean Core Methodology:SAP's standardized extensibility framework is decomposing custom code dependencies, reducing upgrade friction for legacy ECC estates and accelerating cloud conversion velocity.
Market Restraints
- Implementation Cost Structure:Data migration and process reengineering for complex manufacturing environments consume 40-60% of total project spend, freezing budget-constrained mid-market participants.
- Specialized Talent Scarcity:Certified S-4HANA architects and Fiori developers concentrate in Germany, the Netherlands, and India, creating geographic bottlenecks for rollout velocity elsewhere.
- EU AI Act Friction:Algorithmic transparency requirements for embedded machine learning modules add validation layers that extend deployment timelines for predictive maintenance and demand forecasting use cases.
Strategic Opportunities
- Pharmaceutical Serialization:Batch traceability mandates under the EU MDR and US DSCSA create unmet demand for S-4HANA's Advanced Track and Trace for Pharmaceuticals integration, an application layer with limited incumbent penetration.
- Indian Manufacturing Digitization:PLI scheme beneficiaries in electronics and automotive components are greenfield-deploying S-4HANA Cloud, bypassing legacy technical debt entirely.
- Edge-to-Cloud Convergence:Integration of SAP Edge Computing with central S-4HANA instances enables real-time shop-floor control for discrete manufacturers, opening industrial IoT attach revenue streams.
Industry Challenges
- ABAP Skill Obsolescence:Decades of custom ECC development created deep dependencies on legacy coding expertise that does not translate to S-4HANA's extensibility framework, forcing expensive retraining or replacement.
- Hybrid Architecture Complexity:Enterprises attempting phased cloud migrations must maintain data synchronization between on-premise and public cloud instances, multiplying integration failure points.
- Regulatory Multiplicity:Simultaneous compliance with GDPR data residency, CSRD disclosure automation, and EU AI Act algorithmic governance creates overlapping and occasionally conflicting technical requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SAP S-4HANA Application Market |
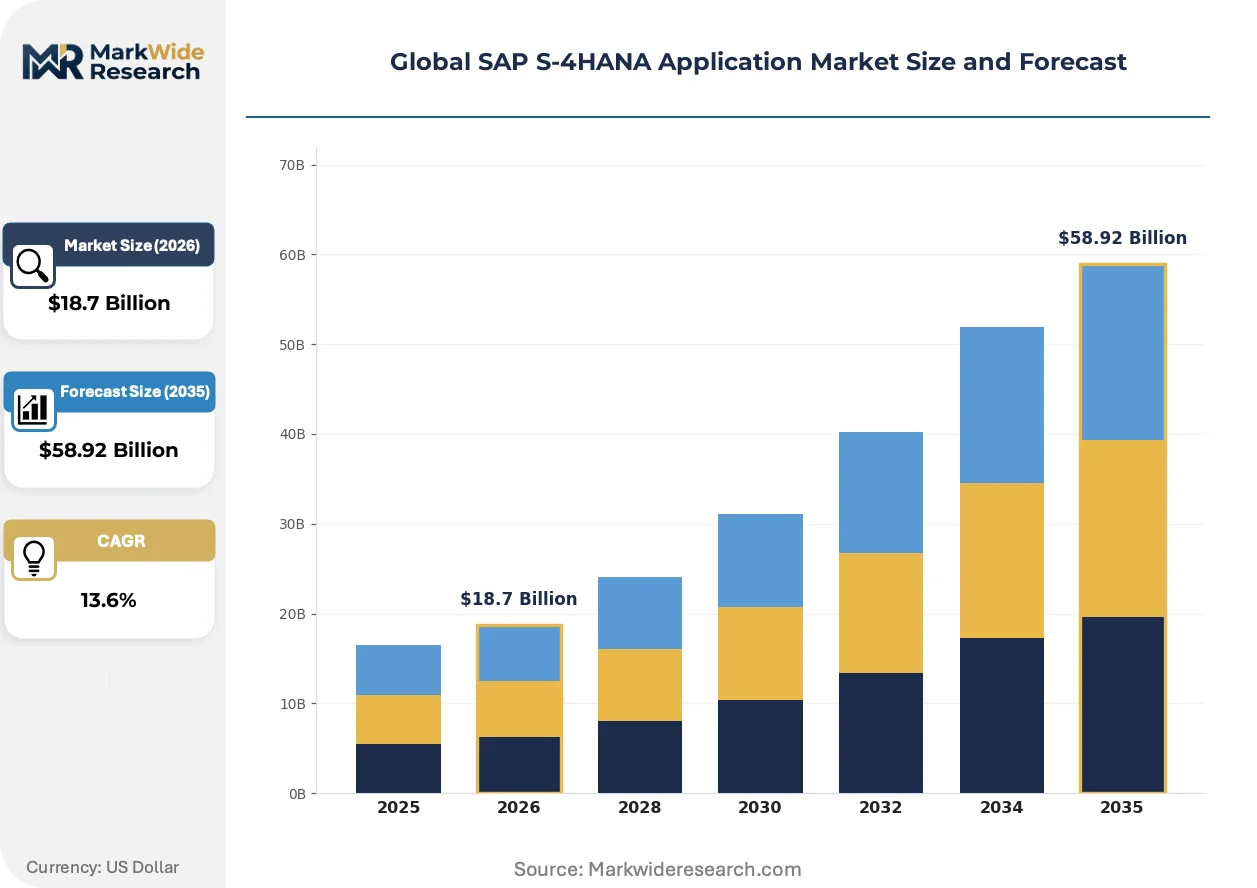
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, Private Cloud, Public Cloud Solution Offering: Finance, Manufacturing, Supply Chain, Sales & Marketing, Human Resources Use Case: Resource Planning, Asset Management, Customer Relationship Management, Compliance Management, Inventory Optimization Industry Vertical: Automotive OEMs, Telecommunications, Pharmaceuticals, Consumer Electronics, Energy Exploration |
| Companies Covered | Capgemini, Applexus Technologies, Accenture, Cloud Consulting Inc., LeverX, Deloitte, IBM, NTT Data, PwC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SAP S-4HANA Application Market Shifts & Advancements
Embedded artificial intelligence and sustainability reporting automation are redefining how enterprises evaluate ERP platform value, shifting procurement criteria from functional checklists to outcome-based transformation metrics.
Side-by-side extensibility using SAP BTP is decomposing the traditional upgrade cycle for monolithic ERP estates. Mid-market discrete manufacturers in Germany and Austria are adopting BTP-based custom applications at twice the rate of larger enterprises, compressing their dependence on lengthy on-premise enhancement projects. This architectural shift is enabling continuous delivery of business process improvements without core system modification.
The EU AI Act's risk-based classification system for algorithmic decision-making is forcing recertification of embedded predictive capabilities across finance and supply chain modules. Automotive OEMs in Stuttgart and Wolfsburg are requiring supplier proof of conformity for AI-driven demand forecasting integrations, transmitting compliance verification costs through tiered supply networks. Pharmaceutical manufacturers are responding fastest, embedding audit trails for machine learning model versioning directly within S-4HANA data models.
Subscription-based implementation partnerships are displacing fixed-scope system integrator contracts for cloud deployments. Industrial machinery buyers in Northern Italy and Switzerland are prioritizing outcome-based arrangements tying vendor compensation to realized process efficiency gains, transferring execution risk from enterprise IT to implementation partners. This reconfiguration is most advanced in finance transformation programs, where robotic process automation outcomes are now contractually guaranteed rather than projected.
Global SAP S-4HANA Application Market Segmentation
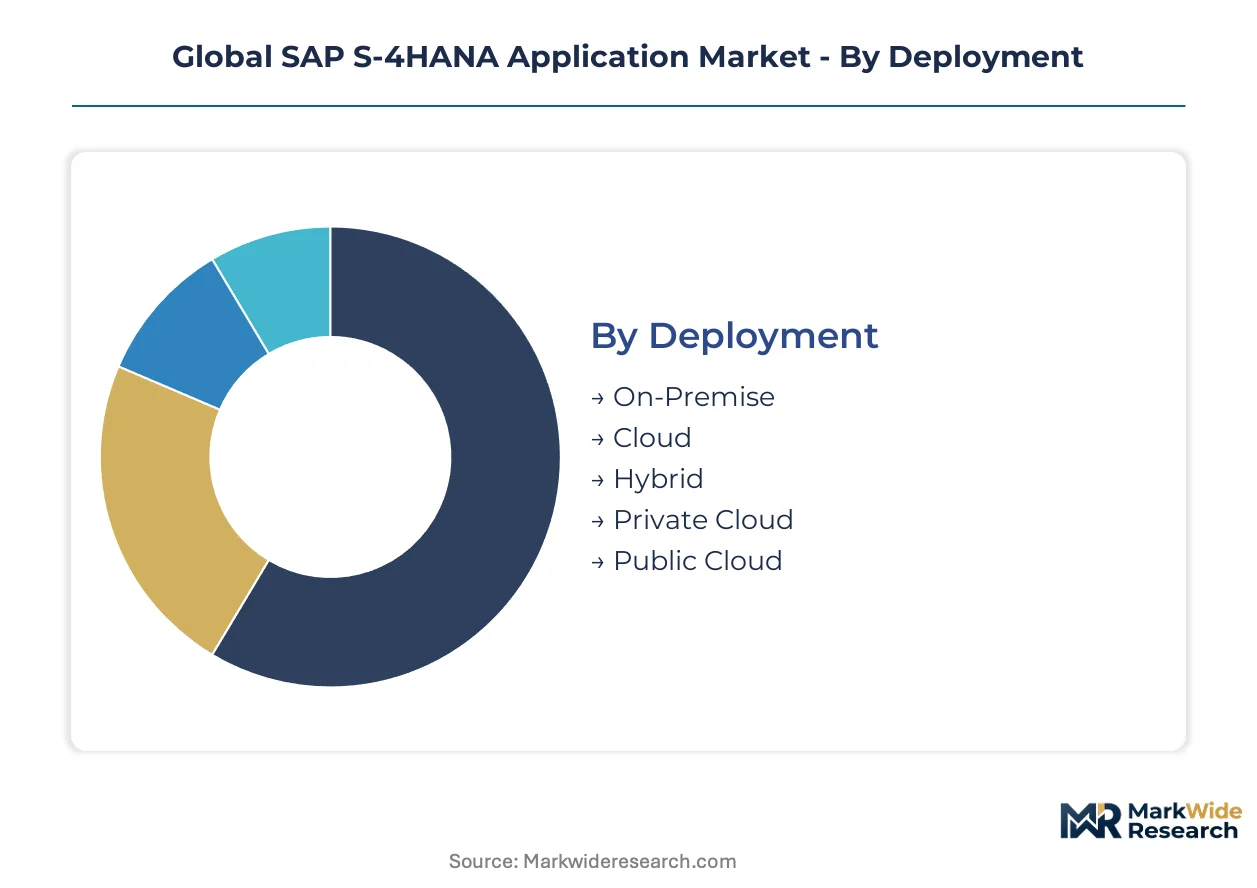
S-4HANA deployment architectures diverge sharply in margin economics, with cloud-native implementations commanding premium advisory attach rates while on-premise conversions absorb heavy data migration costs. Solution modules concentrate profitability differently—Finance transformations sustain recurring revenue pools, whereas Manufacturing deployments demand heavier customization that erodes standardization gains.
Deployment:
Margin pools concentrate in hybrid orchestration layers that bridge legacy estates with cloud analytics, capturing the highest professional services intensity per implementation dollar.
- Cloud:Multi-tenant SaaS architectures eliminate infrastructure ownership burdens for mid-market manufacturers in Germany and Austria. Pharmaceutical serialization mandates in Stuttgart and Basel are accelerating public cloud adoption for elastic compute during batch traceability spikes.
- Hybrid:Synchronized data pipelines between on-premise ECC remnants and S-4HANA cloud instances enable phased migration without operational discontinuity. German automotive tier-one networks mandate hybrid interoperability for supplier qualification, transmitting compliance architecture requirements through multi-tier supply chains.
- On-Premise:Retained for defense and critical infrastructure operators with data residency requirements under BSI Germany frameworks.
- Private Cloud:Single-tenant deployments hosted in certified facilities address EU AI Act algorithmic governance constraints for predictive maintenance modules.
- Public Cloud:Hyperscaler-managed instances with SAP-managed service level agreements reduce internal IT headcount for consumer electronics assemblers in Shenzhen and Taipei.
The dominant share belongs to Cloud, while Hybrid is closing the gap fastest as automotive OEMs mandate phased migration architectures.
Solution Offering:
Application modules stratify by implementation complexity, with Finance and Supply Chain commanding the deepest recurring advisory relationships due to regulatory reporting density.
- Finance:Embedded analytics automate CSRD sustainability disclosure pipelines and real-time consolidation for multi-entity manufacturers. German industrial conglomerates in Munich and Düsseldorf are consolidating legacy CO-PA structures into universal journals, driving template-based standardization demand.
- Supply Chain:Integrated demand forecasting and inventory optimization leverage HANA in-memory processing for sub-second MRP runs. Stuttgart automotive OEMs require supplier proof of EU AI Act conformity for algorithmic demand planning, embedding compliance verification into procurement specifications.
- Manufacturing:Production planning and quality management modules address discrete and process industry divergences through variant configuration.
- Sales & Marketing:Quote-to-cash automation with embedded pricing intelligence serves B2B machinery manufacturers in Northern Italy.
- Human Resources:Core HR and payroll localization for 40+ jurisdictions addresses multinational compliance fragmentation.
Finance captures the largest implementation base, though Supply Chain is expanding most quickly as serialization mandates proliferate.
Use Case:
Functional applications concentrate demand where regulatory automation intersects with operational efficiency—particularly compliance management and inventory optimization.
- Compliance Management:Automated audit trails and cross-border governance controls satisfy simultaneous GDPR data residency, CSRD disclosure automation, and EU AI Act algorithmic transparency requirements. Pharmaceutical manufacturers in Basel and Frankfurt are embedding machine learning model versioning directly within S-4HANA data models.
- Inventory Optimization:Real-time stock positioning across multi-echelon networks reduces working capital intensity for automotive component suppliers. Indian PLI scheme beneficiaries in electronics assembly are greenfield-deploying cloud-native S-4HANA to bypass legacy technical debt entirely.
- Resource Planning:Integrated financial and operational planning unifies budget-to-actual variance analysis.
- Asset Management:Predictive maintenance modules with IoT sensor integration serve energy exploration operators in the North Sea.
- Customer Relationship Management:Embedded SAP Sales Cloud integration addresses B2B complex selling configurations.
Compliance Management holds the deepest regulatory tailwinds, while Inventory Optimization is gaining share fastest among cost-constrained mid-market entrants.
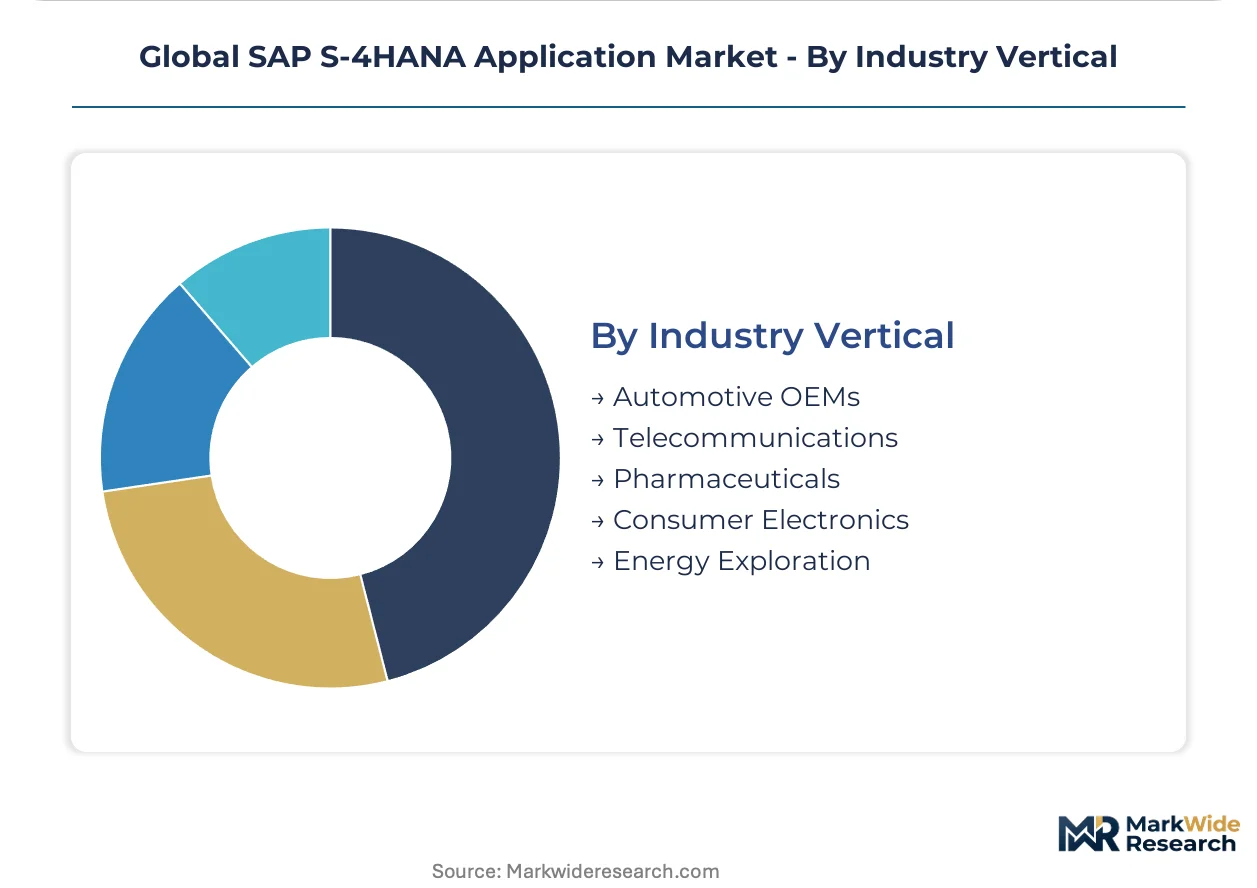
Industry Vertical:
Vertical penetration correlates with supply chain complexity and regulatory reporting burden—automotive and pharmaceuticals lead, while telecommunications and energy present underdeveloped template libraries.
- Automotive OEMs:Dense supplier networks in Baden-Württemberg and Bavaria mandate S-4HANA interoperability for vendor qualification, transmitting platform standardization pressure through tiered ecosystems. Stuttgart and Wolfsburg headquarters proximity to SAP Walldorf accelerates implementation velocity through certified architect availability.
- Pharmaceuticals:EU MDR and US DSCSA serialization requirements create unmet demand for Advanced Track and Trace integration. Batch traceability mandates in Basel and Frankfurt are driving embedded analytics adoption for genealogy reconstruction and recall automation.
- Telecommunications:Asset-intensive network infrastructure management competes with specialized OSS/BSS stacks.
- Consumer Electronics:High-velocity product lifecycle management in Shenzhen and Taipei favors cloud-native deployment to match demand volatility.
- Energy Exploration:Capital project management and joint venture accounting for North Sea operators require heavy customization.
Automotive OEMs retain the dominant implementation base, though Pharmaceuticals is climbing the fastest as serialization deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market manufacturers concentrate procurement authority in Germany, while pharmaceutical serialization mandates pull investment toward Switzerland and regulatory complexity drives US enterprise upgrades.
Germany
Automotive OEM supplier networks and CSRD disclosure requirements dominate S-4HANA procurement decisions. BSI Germany's data residency frameworks and EU AI Act algorithmic governance rules shape deployment architecture choices. Stuttgart and Wolfsburg industrial clusters mandate platform interoperability for tier-one vendor qualification, transmitting standardization pressure through Bavarian and Baden-Württemberg supply chains.
United States
Pharmaceutical serialization under FDA DSCSA and defense contractor CMMC cybersecurity requirements accelerate cloud migration timelines. HIPAA data lineage rules for healthcare ERP deployments add compliance validation layers. Boston and San Francisco biotech clusters embed machine learning audit trails within S-4HANA data models for algorithmic transparency verification.
Switzerland
Swissmedic serialization mandates and Basel pharmaceutical headquarters density create concentrated demand for Advanced Track and Trace integration. FINMA financial reporting requirements drive universal journal consolidation projects. Zurich and Geneva private banking clusters demand multi-entity consolidation modules with embedded ESG disclosure automation.
India
PLI scheme beneficiaries in electronics assembly and automotive components bypass legacy technical debt through greenfield cloud deployments. RBI data localization guidelines and SEBI corporate governance mandates shape hosting architecture decisions. Bengaluru and Pune manufacturing corridors adopt subscription-based implementation partnerships with outcome-based efficiency guarantees.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks complicates cross-border ERP standardization for multinational headquarters. FCA financial reporting requirements and HSE workplace safety data mandates drive compliance module adoption. London financial services clusters and Midlands automotive suppliers pursue hybrid deployment architectures for phased cloud transition.
Global SAP S-4HANA Application Market Competitive Landscape
Player mix skews toward global system integrators with deep SAP partnership credentials and specialized mid-market boutiques with vertical-specific templates. The competitive structure concentrates around three strategic archetypes: scale-driven transformation orchestrators, risk-advisory embedded compliance specialists, and cloud-native deployment accelerators. Dominant competitive moves include strategic partnerships with hyperscaler platforms and portfolio diversification into BTP-based extensibility services.
Within the global system integrator tier, Accenture and Deloitte occupy anchor positions representing scale-driven transformation and risk-advisory integration archetypes respectively. Capgemini exemplifies the European-centric deployment specialist model with concentrated automotive industry penetration. IBM sustains relevance through hybrid cloud orchestration capabilities that bridge legacy estates with public cloud analytics layers.
| Leading Market Players |
|---|
| Capgemini |
| Applexus Technologies |
| Accenture |
| Cloud Consulting Inc. |
| LeverX |
| Deloitte |
| IBM |
| NTT Data |
| PwC |
| Others |
Supply & Pricing Matrix
Capacity utilization at German system integrator hubs near Stuttgart and Walldorf shapes both supply concentration and implementation price floors, as certified S-4HANA architect scarcity concentrates delivery capacity in high-cost labor markets while compressing margins for mid-market bids elsewhere.
Pricing Analysis
Cost-plus contracts with SAP-certified partner indexation dominate large-scale transformation programs, tying professional services fees to named consultant day-rate benchmarks. Subscription-based SaaS tiers stratify across premium advisory bundles, standard implementation packages, and economy self-service cloud deployments, with price differentiation driven by CSRD compliance module depth and EU AI Act certification level. Pricing pressure stems from Indian PLI scheme beneficiaries bypassing legacy migration costs through greenfield cloud deployments. Mid-market manufacturers in Northern Italy exhibit highest price sensitivity, while German automotive OEMs prioritize outcome-based efficiency guarantees over unit cost.
Supply Chain Analysis
Inventory of certified S-4HANA architects concentrates in Germany, the Netherlands, and India, creating geographic lead-time disparities that extend project initiation windows by months outside these hubs. Delivery capacity draws from hyperscaler cloud infrastructure in Ireland and Frankfurt, SAP's proprietary HANA hardware supply chains, and specialized BTP development talent pools in Bengaluru and Pune. Single-source vulnerability attaches to SAP's controlled release cycles for Clean Core methodology updates. Distribution runs through tiered partner networks anchored by global system integrators, with mid-market boutiques filling vertical-specific gaps in pharmaceutical serialization and automotive supplier qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global SAP S-4HANA Application Market sits in a cyclical recovery phase, with CSRD disclosure deadlines and EU AI Act implementation timelines forcing disclosure-heavy industries into accelerated procurement cycles.
For Market Incumbents: Secure certified architect pipelines in Stuttgart and Bengaluru through captive training partnerships, insulating delivery capacity from talent scarcity that threatens rollout velocity. Defend margin position by embedding BTP-based extensibility services into recurring advisory relationships, countering subscription-based competitors with outcome-based efficiency guarantees. Prioritize CSRD automation module standardization to capture disclosure-mandate spending before template commoditization accelerates. For New Entrants and Emerging Players: Lead with pharmaceutical serialization expertise in Basel and Frankfurt, where Advanced Track and Trace integration demand outstrips incumbent capacity and EU MDR deadlines compress vendor selection timelines. Target mid-market discrete manufacturers in Austria and Switzerland with pre-configured industry templates that accelerate cloud deployment without heavy customization. Pursue outcome-based contracting models that transfer implementation risk from enterprise buyers to delivery partners, differentiating against fixed-scope system integrator incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among BTP-specialized boutiques with vertical-specific template libraries, as continuous extensibility services generate annuity streams beyond initial deployment. Long-term viability hinges on regulatory complexity persistence across GDPR, CSRD, and EU AI Act overlapping requirements. Target acquisition archetypes: mid-market SAP partners with certified EU AI Act compliance practices and concentrated automotive or pharmaceutical industry penetration. Monitor Clean Core methodology adoption rates as inflection signal—accelerated uptake indicates commoditization pressure on implementation margins.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Side-by-side extensibility via SAP BTP decomposes monolithic upgrade cycles for German mid-market manufacturers. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure enable hybrid orchestration layers bridging legacy ECC with cloud analytics. |
| Acquisition of Specialist Firm | BTP boutiques with pharmaceutical serialization templates capture unmet EU MDR compliance demand in Basel. |
| Geographic Expansion | Indian PLI scheme corridors in Bengaluru and Pune offer greenfield cloud deployment opportunities without legacy debt. |
| Product Launch | Embedded AI modules with EU AI Act conformity certification address Stuttgart OEM supplier qualification requirements. |
Research Methodology
Desk research of SAP partnership tier directories, hyperscaler co-sell disclosure filings, and EU regulatory implementation guidance preceded structured interviews with S-4HANA program directors, certified solution architects, pharmaceutical compliance officers, and automotive procurement leads. Primary fieldwork combined with secondary validation against BSI Germany framework documentation, EMA serialization mandate timelines, and SEC filings from listed system integrators. Bottom-up deployment volume estimates triangulated against top-down ERP replacement cycle modeling.
Variance decomposition across deployment architecture, solution module, and industry vertical dimensions shaped the analytical framework, with CAGRs derived from regression against historical ECC-to-S-4HANA conversion velocity and forward projection of CSRD mandate compliance windows. Cloud adoption curves, EU AI Act implementation phasing, and mid-market manufacturer capital availability patterns served as industry-specific forecast inputs throughout the projection horizon.
Forecasts assume regulatory continuity in EU CSRD, GDPR, and AI Act regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sales Force Automation Software Market
Software & Services
Global Remote Work Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Laboratory Management Software Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Generative Design Software Market
Software & Services
Terminal Emulator Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Enterprise-Grade Saas Market
Software & Services
Global Customer Service Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Open Stack Service Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Software Publishers Market
Software & Services
Global Sweepstakes Software Market