
 Global Driving School Software Market | 2026-2036
Global Driving School Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Driving School Software Market Foresight
Platform licensing revenue is fragmenting across specialized modules as driving schools abandon monolithic suites. Bookeo leverages integrated booking workflows to anchor its position among independent operators. TeachWorks sustains R&D intensity in instructor-centric customization, while Fleet Complete extends telematics expertise into compliance-heavy corporate training segments.
Global driving school software encompasses cloud-deployed and on-premise platforms that automate student enrollment, lesson scheduling, progress monitoring, and billing reconciliation through API-connected databases and mobile-responsive interfaces. The primary commercial purpose is to reduce administrative overhead while ensuring regulatory audit trails for licensing authorities. Cloud-based deployment leads volume adoption among independent schools seeking minimal IT infrastructure, while Learning Management Systems capture concentrated margin pools through recurring content licensing. Mobile Applications represent the fastest-expanding segment as Gen Z learners expect native app experiences for theory testing and lesson booking.
The United States Federal Motor Carrier Safety Administration shapes commercial driver training mandates, while the European Union's General Data Protection Regulation imposes strict student data handling protocols on cross-border SaaS providers. Australia's Transport Certification Australia enforces competency-based progression standards that software platforms must map precisely. Stakeholders must monitor divergent national licensing frameworks when prioritizing localization investments versus standardized product architectures.
Market Dynamics
Cloud-native scheduling architectures are fragmenting platform economics as independent driving schools abandon legacy client-server systems for API-first student management stacks.
Growth Catalysts
- Graduated Licensing Reforms:State-level tiered progression mandates in the United States and Australia require digitized competency tracking that only purpose-built software delivers.
- Electronic Logging Mandates:The Federal Motor Carrier Safety Administration's hours-of-service rules for commercial driver training centers force adoption of integrated telematics-dashboard platforms.
- Gen Z Learner Preferences:Native mobile-first interfaces for theory testing and lesson booking now determine vendor selection criteria among independent operators.
Market Restraints
- Data Sovereignty Compliance:The European Union's General Data Protection Regulation imposes cross-border hosting restrictions that inflate infrastructure costs for multi-national SaaS providers.
- Legacy System Entrenchment:Large municipal driving authorities in Germany and France operate on decades-old COBOL-based record systems with no migration budget.
- Substitute Platforms:Generic CRM tools from Salesforce and HubSpot capture price-sensitive micro-schools through education-vertical templates.
Strategic Opportunities
- India's Unorganized Sector:Over 80% of the country's 25,000-plus driving schools operate on paper ledgers, presenting white-space demand for cloud-based student management.
- AI-Generated Theory Content:Large language model integration enables automated exam preparation modules that reduce instructor labor costs per student.
- Brazil's CNH Digital Mandate:The national driver's license digitization program requires API connectivity that only modern platforms can provision.
Industry Challenges
- Instructor Technology Adoption:Veteran driving instructors aged 50-plus demonstrate resistance to tablet-based progress logging, requiring parallel paper workflows.
- Vehicle Telematics Integration:Connecting proprietary OEM black-box data formats from Toyota, Volkswagen, and Ford into unified lesson analytics demands expensive custom middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Driving School Software Market |
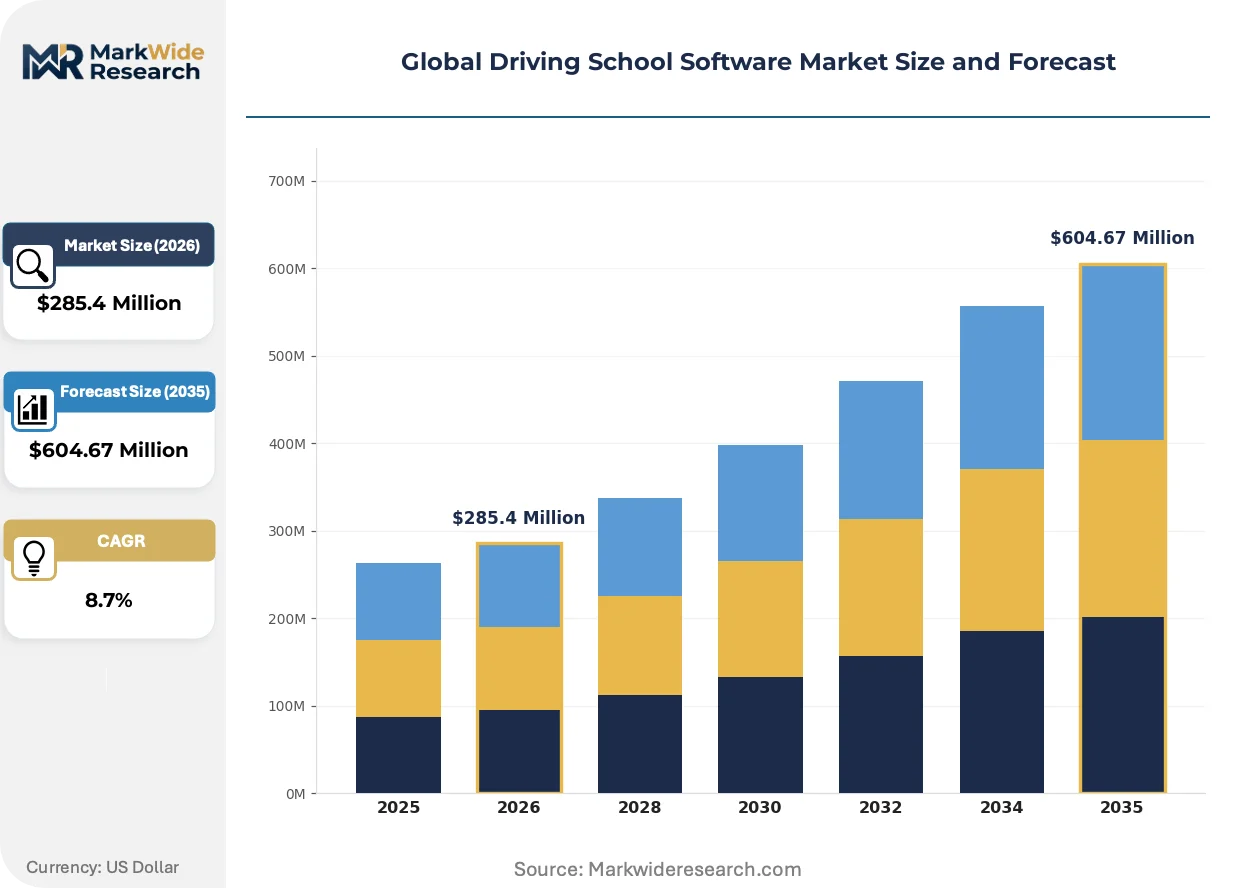
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premise, Hybrid, Software as a Service Application: Student Management, Scheduling, Performance Tracking, Billing Management, Digital Theory Testing Customer Type: Independent Schools, Franchise Chains, Corporate Training Centers, Government Training Facilities Solution Offering: Learning Management Systems, Mobile Applications, Reporting & Analytics, Instructor Management, Vehicle Tracking |
| Companies Covered | Bookeo, TeachWorks, DrivingSchoolSoftware.com, Fleet Complete, Drive Scout, Zutobi (Instructor), SimplyBook.me, IntelliShift, Colibri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Driving School Software Market Shifts & Advancements
Simulation-based training modules are compressing the boundary between digital theory instruction and behind-the-wheel practice, reshaping how competency is certified.
Virtual reality hazard perception systems are virtualizing the high-risk scenario exposure that previously required dedicated skid pads and closed-course facilities. Corporate training centers in the United Kingdom and Netherlands are deploying these systems at scale to reduce insurance premiums and vehicle wear. The technology is virtualizing capital allocation patterns as schools defer physical fleet expansion in favor of software licenses.
The European Union's AI Act imposes transparency requirements on automated driving assessment algorithms that score learner reactions in simulated environments. Vendors must now document training data provenance and decision logic for national transport authorities. German and Swedish regulators are requiring third-party algorithmic audits before platform certification, creating compliance bottlenecks for smaller developers.
Subscription-based pricing is displacing perpetual license models as independent schools prioritize operational expenditure flexibility over capital deployment. Tier-2 cities in the United States and regional Australian markets show the fastest migration to monthly SaaS tiers. This shift compresses vendor cash conversion cycles while expanding addressable market reach to credit-constrained operators.
Global Driving School Software Market Segmentation
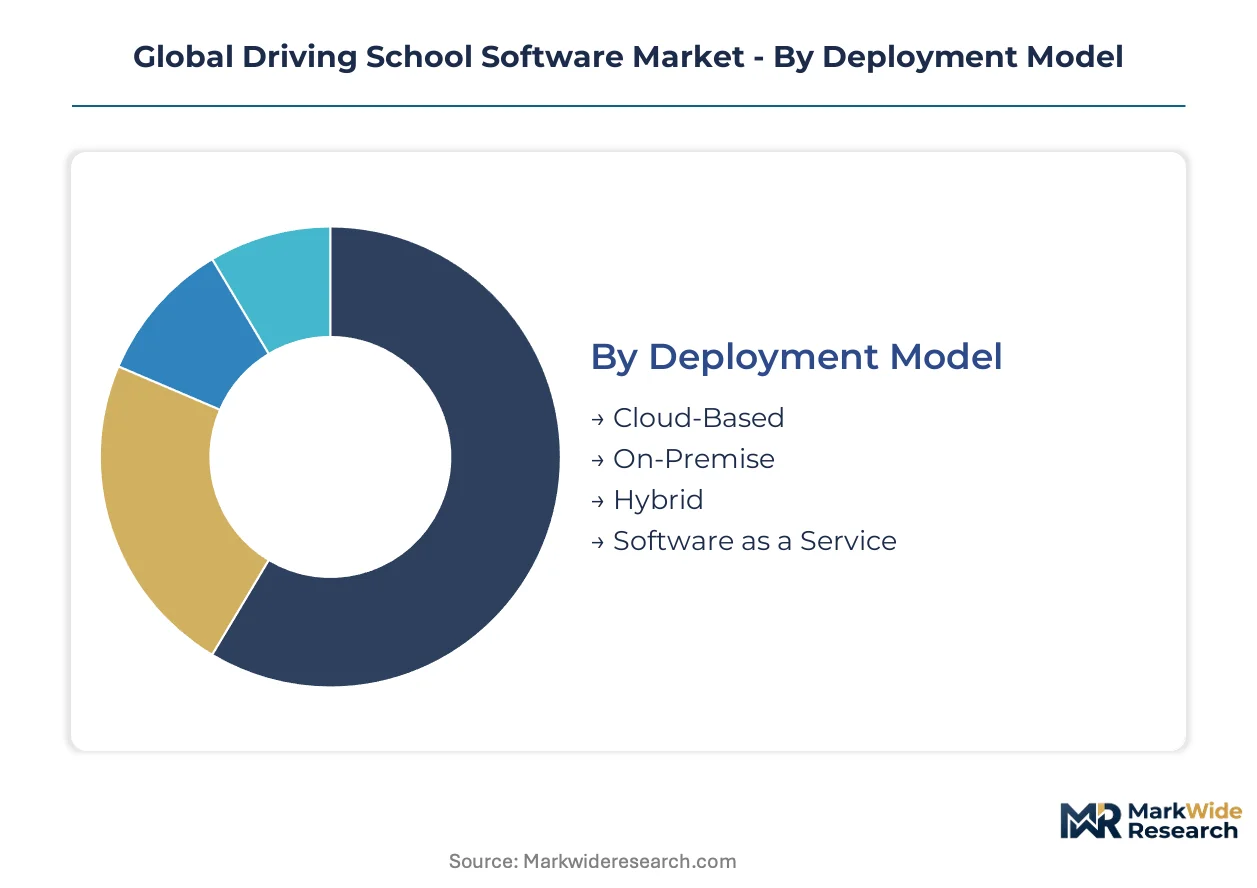
Driving school software vendors configure product architectures around deployment constraints, pedagogical workflows, and regulatory audit requirements. Segment boundaries increasingly blur as platform consolidation fuses scheduling, telematics, and compliance modules into unified stacks.
Deployment Model:
Mature cloud architectures dominate new procurement cycles, while legacy on-premise installations persist in jurisdictions with strict data localization mandates.
- Cloud-Based:Multi-tenant SaaS architectures with auto-scaling infrastructure eliminate server maintenance burdens for independent operators. Demand concentrates in the United States and Australia where FMCSA and Transport Certification Australia mandate real-time data accessibility for audit purposes.
- On-Premise:Single-tenant installations on local servers satisfy German KBA and French CNIL requirements for student data sovereignty. Municipal driving authorities in Bavaria and Ile-de-France maintain these deployments despite higher total cost of ownership.
- Hybrid:Split architectures keep sensitive student records on local servers while pushing scheduling and billing to cloud endpoints. German mid-size chains favor this model to balance GDPR compliance with mobile instructor access.
- Software as a Service:Fully managed subscription platforms with zero infrastructure footprint. Indian driving schools in Bangalore and Hyderabad adopt these tiers to bypass capital expenditure constraints.
Cloud-Based retains volume leadership; Software as a Service holds the steepest expansion curve.
Application:
Functional modules map directly to operational pain points, with scheduling and compliance tracking commanding premium pricing.
- Student Management:Enrollment workflows, document verification, and progress dashboards consolidated in unified databases. Franchise chains in Texas and Florida deploy these modules to standardize multi-location operations.
- Scheduling:Real-time instructor-vehicle-learner matching with automated conflict resolution. Independent schools in Sydney and Melbourne prioritize this capability to maximize fleet utilization rates.
- Performance Tracking:Competency-based progression logging aligned with graduated licensing frameworks. Australian state transport authorities require this functionality for certification eligibility.
- Billing Management:Package pricing, installment plans, and insurance integration for lesson revenue recognition. Corporate training centers in the United Kingdom leverage these tools for enterprise contract complexity.
- Digital Theory Testing:Browser-based and native app examination delivery with randomized question banks. Gen Z learners in Canada and Sweden expect this modality as standard.
Scheduling commands the highest module attach rates; Digital Theory Testing is climbing the fastest.
Customer Type:
Procurement sophistication varies sharply across operator scale, from paper-led independent schools to API-integrated government facilities.
- Independent Schools:Single-location operators with 5-15 vehicle fleets prioritizing cost-minimal solutions. These buyers in Spain and Italy drive volume for entry-tier SaaS pricing.
- Franchise Chains:Multi-location networks requiring centralized brand control and cross-site instructor pooling. US-based chains like those operating across California and Arizona demand white-label customization.
- Corporate Training Centers:Fleet operator academies with compliance-heavy documentation needs. Telecommunications and logistics companies in the Netherlands deploy these platforms for commercial driver certification.
- Government Training Facilities:State-run academies with public procurement processes and legacy system integration requirements. India's state transport department facilities present complex tender specifications.
Independent Schools retain volume leadership; Corporate Training Centers hold the steepest expansion curve.
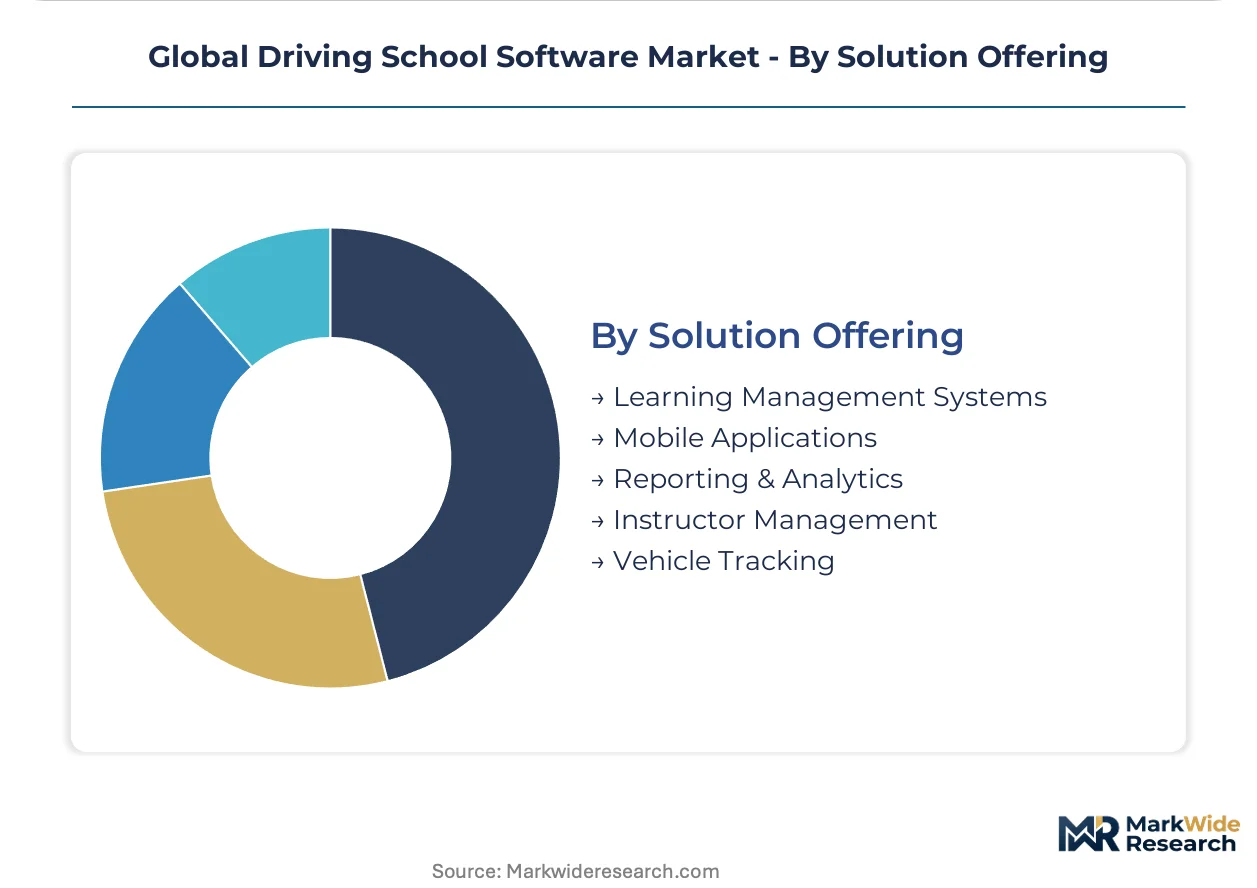
Solution Offering:
Product bundling strategies segment by technical depth, from lightweight mobile apps to telematics-integrated vehicle tracking.
- Learning Management Systems:Comprehensive content delivery platforms with SCORM-compliant theory modules and instructor dashboards. Swedish and Finnish driving schools favor these for structured curriculum alignment.
- Mobile Applications:Native iOS and Android experiences for lesson booking, progress viewing, and theory practice. Brazilian learners accessing CNH Digital mandates drive adoption acceleration.
- Reporting & Analytics:Business intelligence layers with pass-rate analysis, instructor productivity metrics, and revenue forecasting. UK insurance brokers require these outputs for premium risk assessment.
- Instructor Management:Credential tracking, availability optimization, and payroll integration for teaching staff. German instructor chambers mandate continuing education logging through these modules.
- Vehicle Tracking:GPS-integrated telematics capturing route data, harsh braking events, and lesson duration verification. FMCSA compliance requirements in the United States make this mandatory for commercial training.
Learning Management Systems retain volume leadership; Mobile Applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud deployment patterns diverge sharply across geographies, with Australia and the United States prioritizing real-time audit accessibility while Germany and France enforce strict data localization protocols that fragment vendor architectures.
United States
Fleet operators and commercial training centers drive concentrated demand for telematics-integrated platforms. The Federal Motor Carrier Safety Administration mandates electronic logging device compatibility for hours-of-service compliance. Texas and Florida host the densest independent school clusters, where franchise chains deploy centralized scheduling systems across multi-location networks.
Germany
Municipal driving authorities and mid-size chains sustain on-premise and hybrid deployment models. The Kraftfahrt-Bundesamt enforces stringent student data sovereignty requirements that complicate cloud migration. Bavaria maintains legacy COBOL-based record systems, while Berlin-Brandenburg driving schools experiment with split architectures balancing GDPR compliance against mobile instructor access.
Australia
State-level transport authorities mandate competency-based progression tracking that only specialized software delivers. Transport Certification Australia enforces real-time data accessibility for audit purposes. Sydney and Melbourne independent operators prioritize scheduling modules to maximize vehicle utilization rates in high-density urban training environments.
India
Over 80 percent of driving schools operate on paper ledgers, creating white-space demand for cloud-based student management. State transport departments issue complex tender specifications for government training facilities. Bangalore and Hyderabad SaaS adopters bypass capital expenditure constraints through fully managed subscription tiers.
Brazil
The national CNH Digital driver's license program requires API connectivity that modern platforms must provision. ANVISA-aligned data handling protocols shape vendor selection for cross-border SaaS providers. São Paulo and Rio de Janeiro training centers accelerate mobile application adoption as learners expect native app experiences for theory testing and lesson booking.
Global Driving School Software Market Competitive Landscape
Capability concentration sits with specialized scheduling and telematics developers; scale advantage sits with generalized booking platform operators with cross-vertical reach. The vendor base stratifies across three tiers: independent-school-focused SaaS providers, fleet-centric compliance platforms, and multi-vertical booking engines with education-vertical templates. Dominant competitive moves include API-first architecture development and strategic partnerships with vehicle telematics OEMs.
Within the scheduling-specialist tier, Bookeo and TeachWorks exemplify divergent positioning strategies. Bookeo anchors integrated booking workflows among independent operators seeking minimal configuration overhead. TeachWorks occupies a position emphasizing instructor-centric customization capabilities. Fleet Complete represents the telematics-integrated compliance archetype, extending vehicle tracking expertise into corporate training segments with heavy documentation requirements.
| Leading Market Players |
|---|
| Bookeo |
| TeachWorks |
| DrivingSchoolSoftware.com |
| Fleet Complete |
| Drive Scout |
| Zutobi (Instructor) |
| SimplyBook.me |
| IntelliShift |
| Colibri |
| Others |
Supply & Pricing Matrix
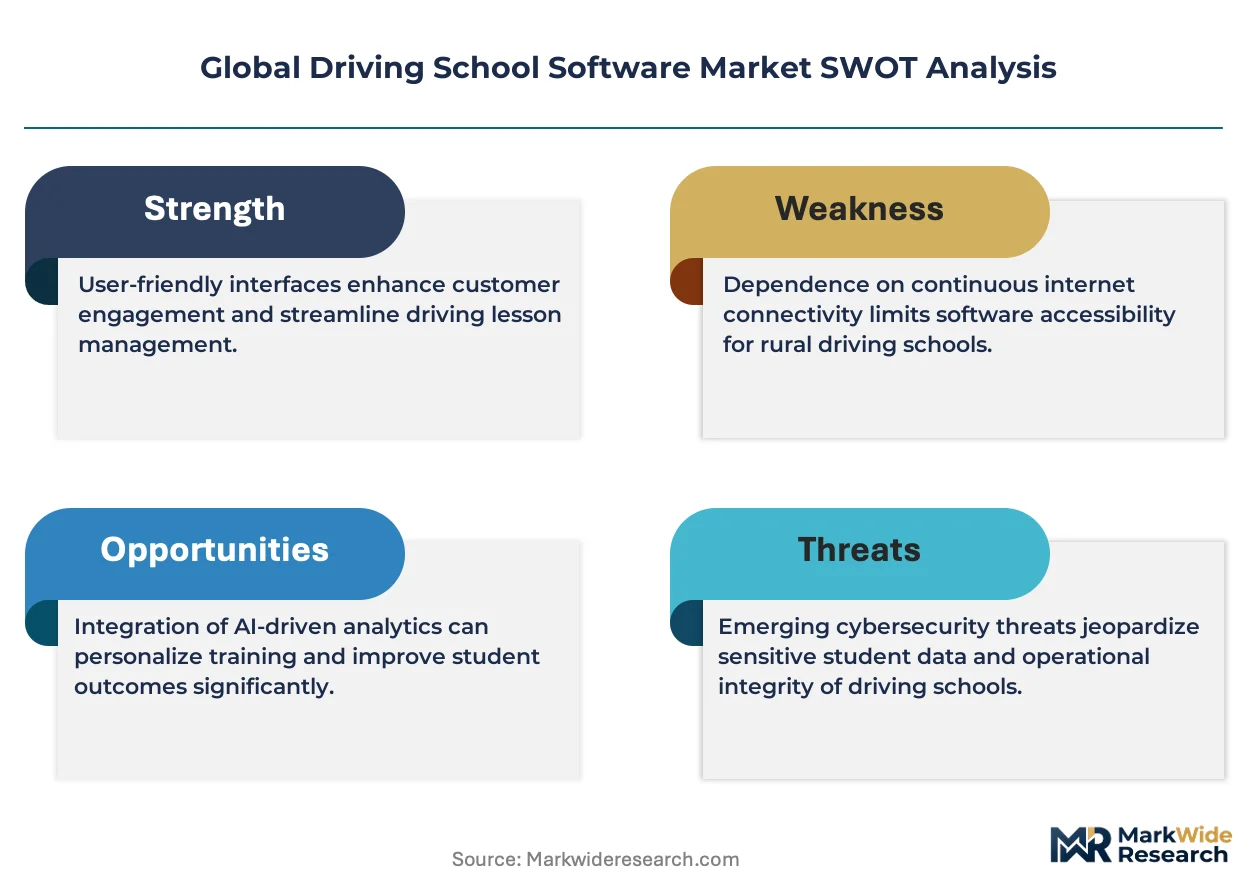
GDPR-mandated data localization requirements in Germany and France determine both pricing tier spreads and supply chain shape, forcing vendors to maintain redundant infrastructure across sovereignty zones while compressing margins on standardized SaaS offerings.
Pricing Analysis
Contract structures favor monthly SaaS subscriptions over perpetual licenses, with three-tier pricing stratifying across enterprise compliance suites, mid-market scheduling platforms, and entry-level mobile apps. Price differentiation hinges on telematics integration depth and FMCSA certification tier. Cost compression in the entry tier intensifies because generic CRM tools from Salesforce and HubSpot capture price-sensitive micro-schools. Independent operators in Spain and Italy demonstrate highest price sensitivity, while corporate training centers in the Netherlands show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Upstream feedstock for cloud-native platforms centers on hyperscaler compute capacity from Amazon Web Services, Microsoft Azure, and Google Cloud Platform, with secondary dependencies on specialized telematics hardware from Trimble and Geotab. Raw material dependencies include API middleware stacks, mobile development frameworks, and vehicle OEM data protocols. Supply chain risk manifests as single-source vulnerability in proprietary OEM black-box data formats from Toyota, Volkswagen, and Ford. Distribution runs through direct vendor sales teams for enterprise accounts and self-service web portals for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors face substitution defense imperatives as generic CRM platforms encroach on the scheduling-module segment with education-vertical templates.
For Market Incumbents: Insulate core scheduling functionality through deeper vehicle telematics integration with OEMs like Ford and Volkswagen, creating proprietary data pipelines that generic CRM tools cannot replicate. Consolidate position in the Australian and United States markets where Transport Certification Australia and FMCSA mandates create regulatory moats. Prioritize API-first architecture investment to maintain interoperability leadership against emerging platform competitors.
For New Entrants and Emerging Players: Establish a beachhead in India's unorganized driving school sector, where over 80 percent of 25,000-plus operators still use paper ledgers. Target Bangalore and Hyderabad for initial SaaS adoption given existing technology infrastructure familiarity. Deploy fully managed subscription tiers with zero infrastructure footprint to bypass capital expenditure constraints that deter traditional software procurement.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized telematics developers with proven FMCSA compliance track records. Long-term viability across the analysis window rests on regulatory certification depth rather than feature breadth. Monitor algorithmic audit requirements under the EU AI Act as the primary inflection indicator for platform certification bottlenecks affecting smaller developers.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified scheduling-telematics-compliance stacks reduce vendor fragmentation for franchise chains in Texas and Florida. |
| Strategic Partnership | OEM data-sharing agreements with Toyota and Volkswagen enable proprietary lesson analytics middleware. |
| Geographic Expansion | India's paper-led driving school sector offers white-space demand for cloud-based student management platforms. |
| Product Launch | AI-generated theory content modules reduce instructor labor costs per student in high-volume markets. |
| Acquisition of Specialist Firm | VR hazard perception developers in the United Kingdom and Netherlands virtualize capital allocation away from physical fleet expansion. |
Research Methodology
The analysis maps cloud deployment architectures, application modules, and customer type segments, each validated through primary interviews with driving school operators, fleet training managers, software procurement officers, and regulatory compliance leads. Secondary validation draws from FMCSA guidance documents, Transport Certification Australia audit protocols, GDPR implementation guidance, EU AI Act transparency requirements, and SEC filings from publicly traded telematics providers. Bottom-up unit economics from individual school operators triangulate against top-down market sizing from national licensing authority data.
Assumptions held fixed include current graduated licensing reform trajectories in the United States and Australia, GDPR enforcement intensity in Germany and France, and Gen Z learner preference stability for mobile-first interfaces. Variables tested include India's digitization pace for driving school records, Brazil's CNH Digital API connectivity rollout speed, and AI Act algorithmic audit requirement stringency. Segmentation dimensions modeled encompass deployment model, application function, customer scale tier, and solution technical depth. CAGRs derive from enrollment growth projections tied to demographic licensing age cohorts and commercial driver demand from logistics sector expansion.
Sensitivities concentrate around regulatory enforcement divergence across EU member states, India's state-level tender specification fragmentation, and OEM telematics data access policy changes. Forecasts reflect documented assumptions on cloud migration velocity and substitute platform competitive intensity. Cross-checking against national transport authority licensing statistics and commercial driver training center capacity reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Email Applications Market
Software & Services
Customs Declaration Software Market
Software & Services
Server Virtualization Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Machine Translation Software Market
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Specification Management Software Market
Software & Services
PAC Programming Software Market
Software & Services
Global Printing Software Market
Software & Services
Professional Service Automation Market
Software & Services
PLM Software Market
Software & Services
Drone Mapping Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Network Bandwidth Management Software Market