
 Indonesia Digital Transformation Market | 2026-2036
Indonesia Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Digital Transformation Market Insights
Indonesia's data center and cloud infrastructure build-out is reshaping how enterprises procure digital capabilities across the archipelago. Amazon Web Services Inc. anchors its Southeast Asia expansion through Jakarta-region availability zones, while Microsoft Corporation leverages local partnerships to distribute Azure services through state-linked channels. PT Telekomunikasi Indonesia dominates domestic connectivity backbones, extending fiber reach that underpins enterprise cloud adoption.
Indonesia Digital Transformation denotes the systematic integration of cloud computing, artificial intelligence, Internet of Things, and advanced analytics into organizational workflows to automate operations, enhance customer engagement, and generate data-driven decisions. Cloud computing leads technology deployment as enterprises migrate legacy workloads to public and hybrid environments, while AI segments capture expanding margin pools through predictive maintenance and fraud detection applications. Manufacturing end users drive IoT adoption for supply chain visibility, whereas retail sectors prioritize big data analytics for consumer behavior modeling.
Bank Indonesia's payment system roadmap and the Ministry of Communication and Informatics' data localization requirements shape infrastructure investment patterns, compelling foreign providers to establish domestic nodes. BIS-equivalent standards for cybersecurity certification and the Personal Data Protection Law create compliance thresholds that filter vendor participation. Stakeholders must monitor regulatory enforcement intensity around cross-border data flows as this determines whether global platforms or domestic integrators capture incremental enterprise contracts.
Market Dynamics
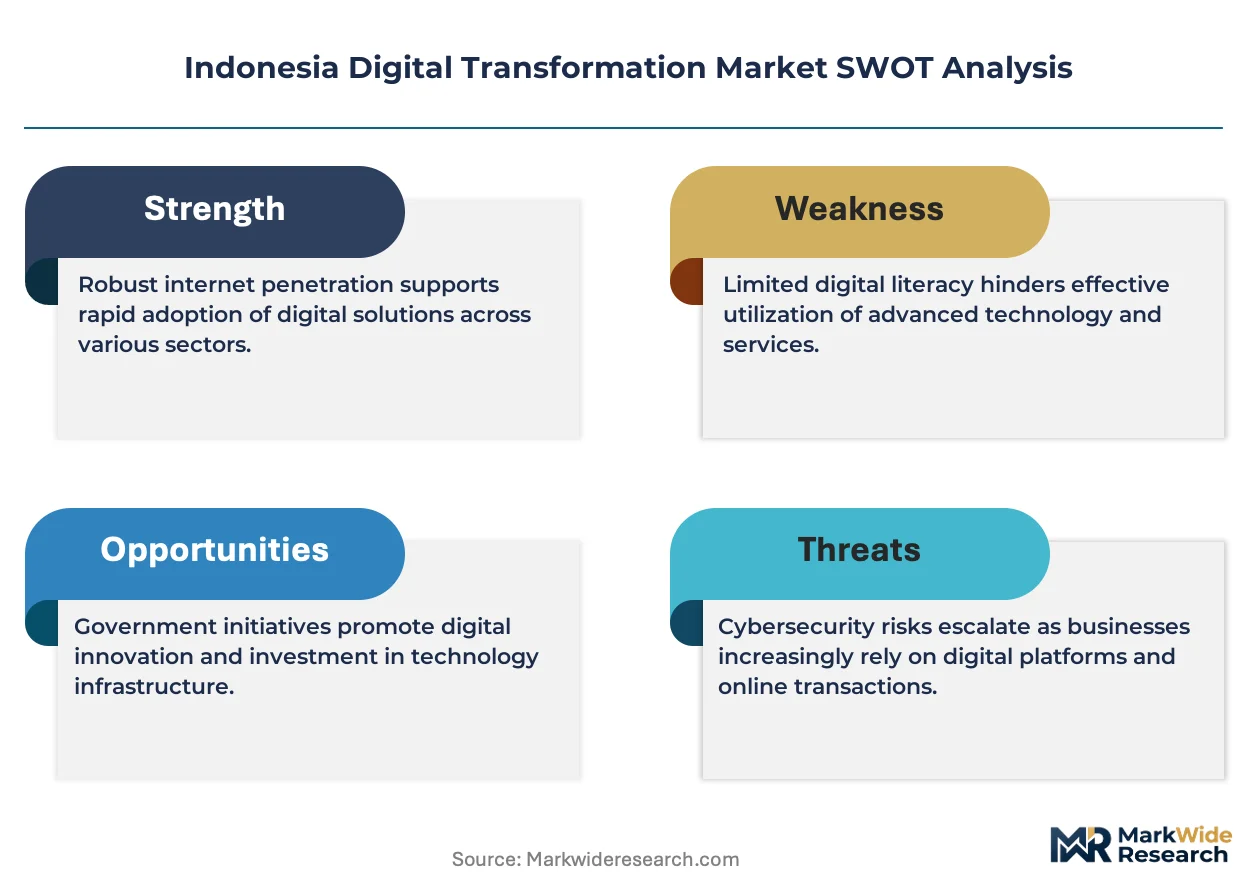
Bank Indonesia's payment system roadmap and the Personal Data Protection Law are compressing vendor qualification timelines while mandating domestic data residency, forcing foreign cloud providers to localize infrastructure or forfeit enterprise contracts to domestic integrators.
Growth Catalysts
- Bank Indonesia Payment Infrastructure Mandates:The central bank's real-time gross settlement and retail payment system modernization directives compel tier-one and tier-two banks to replace legacy core banking architectures with cloud-native platforms.
- Manufacturing IoT Adoption:Discrete and process manufacturers across Java and Batam deploy industrial IoT sensors for predictive maintenance and supply chain visibility, generating recurring demand for edge computing and analytics software.
- Jakarta Financial Technology Corridor Concentration:Venture capital deployment and regulatory sandbox approvals cluster in Greater Jakarta, creating network effects that accelerate enterprise digital procurement decisions.
Market Restraints
- Data Localization Compliance Costs:The Personal Data Protection Law requires domestic data storage and processing nodes, raising capex thresholds for foreign platform providers and limiting immediate market entry.
- Domestic Connectivity Backbone Concentration:PT Telekomunikasi Indonesia's dominance over submarine cable landing stations and inter-island fiber routes creates single-point-of-failure risk for enterprise cloud adoption outside Java.
- Legacy Core Banking Technical Debt:Cobol and mainframe-dependent institutions face multi-year migration timelines that delay full-stack digital transformation program rollouts.
Strategic Opportunities
- Eastern Indonesia Underpenetration:Sulawesi, Maluku, and Papua present greenfield opportunities for cloud infrastructure build-out as fiber connectivity expands and provincial enterprises digitize procurement and logistics.
- AI-Analytics Convergence in Retail:Consumer behavior modeling platforms that integrate computer vision, natural language processing, and demand forecasting capture expanding IT budgets from modern trade and e-commerce operators.
- Ministry of Communication and Informatics Certification Incentives:Domestic cloud provider accreditation programs create procurement preferences for locally certified vendors in government and state-owned enterprise tenders.
Industry Challenges
- Cloud Architecture Talent Scarcity:Enterprise demand for Kubernetes, DevOps, and multi-cloud governance expertise outstrips domestic supply, inflating compensation and extending implementation timelines.
- Inter-Island Integration Complexity:Enterprises operating across the archipelago face heterogeneous network latency and reliability conditions that complicate unified digital platform deployments.
- BIS-Equivalent Cybersecurity Certification Delays:The national cybersecurity certification framework's evolving technical standards create uncertainty for vendors preparing product submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Digital Transformation Market |
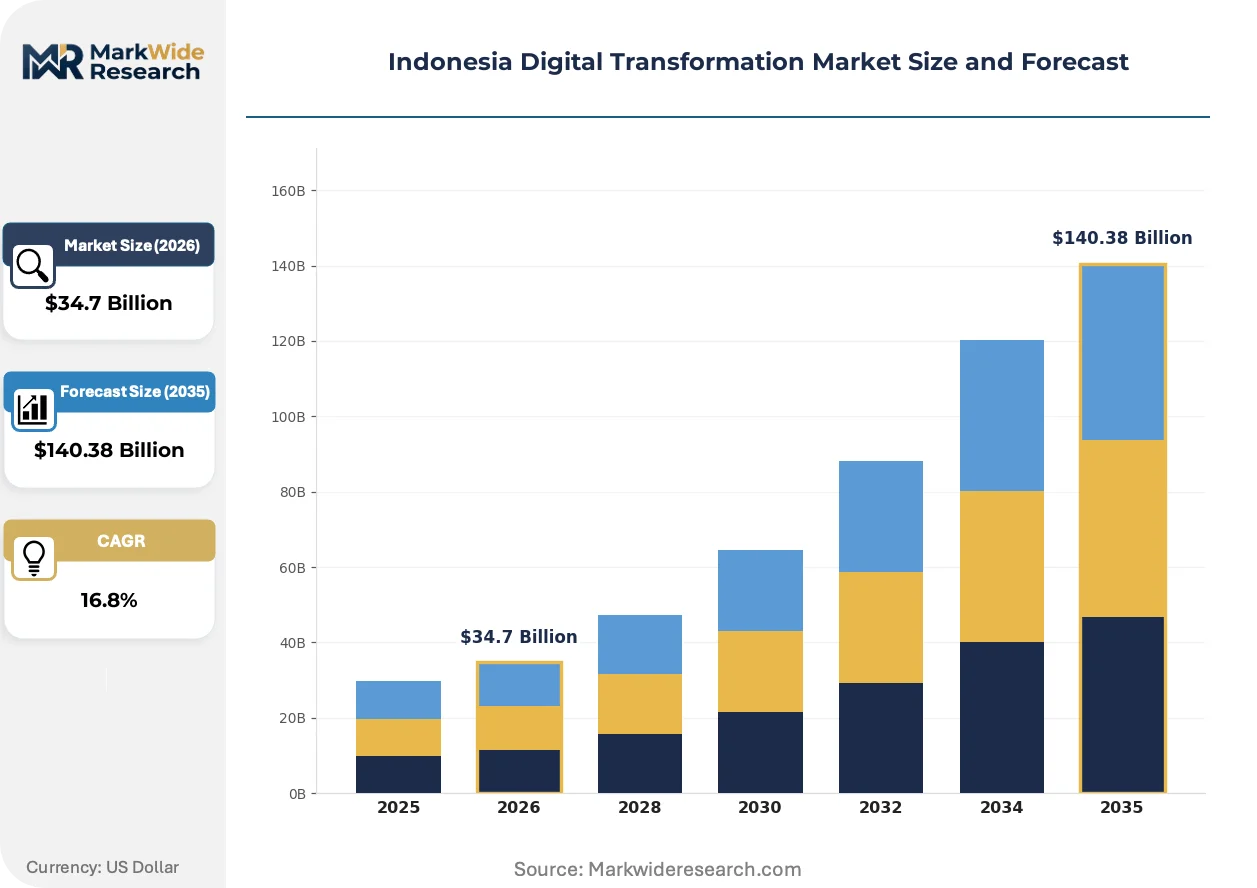
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $140.38 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Big Data Analytics, AI, IoT End User: Retail, Healthcare, Manufacturing, Education Deployment: On-premises, Hybrid, Public Cloud, Private Cloud Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | IBM Corporation, Amazon Web Services Inc., Accenture PLC, Oracle Corporation, SAP SE, Microsoft Corporation, PT Telekomunikasi Indonesia, PT Multipolar Technology Tbk, Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Digital Transformation Market Trends and Innovations
Cloud-native core banking platforms are displacing monolithic legacy systems while regulatory data localization mandates reshape infrastructure deployment geography across the archipelago.
Edge computing nodes paired with 5G network slices are digitizing manufacturing quality control and warehouse automation workflows. Automotive and electronics manufacturers in Bekasi and Karawang industrial zones deploy these configurations for sub-10 millisecond latency applications. The technology stack is digitizing operational technology-IT convergence and compressing defect detection response cycles from hours to seconds.
Bank Indonesia's Payment System Roadmap 2025 mandates real-time gross settlement interoperability and retail payment system standardization. The regulation forces domestic banks to modernize core banking architectures and integrate with national payment switches. Tier-two regional banks face the steepest compliance curves as they lack in-house integration capabilities.
Enterprise software procurement through state-linked distribution channels is displacing direct vendor relationships for foreign platform providers. Microsoft and Amazon Web Services route Azure and Jakarta-region services through PT Telekomunikasi Indonesia and other domestic partners to satisfy government procurement regulations. State-owned enterprises and public sector agencies drive this channel shift through tender requirements that favor locally contracted service delivery.
Indonesia Digital Transformation Market Segmentation
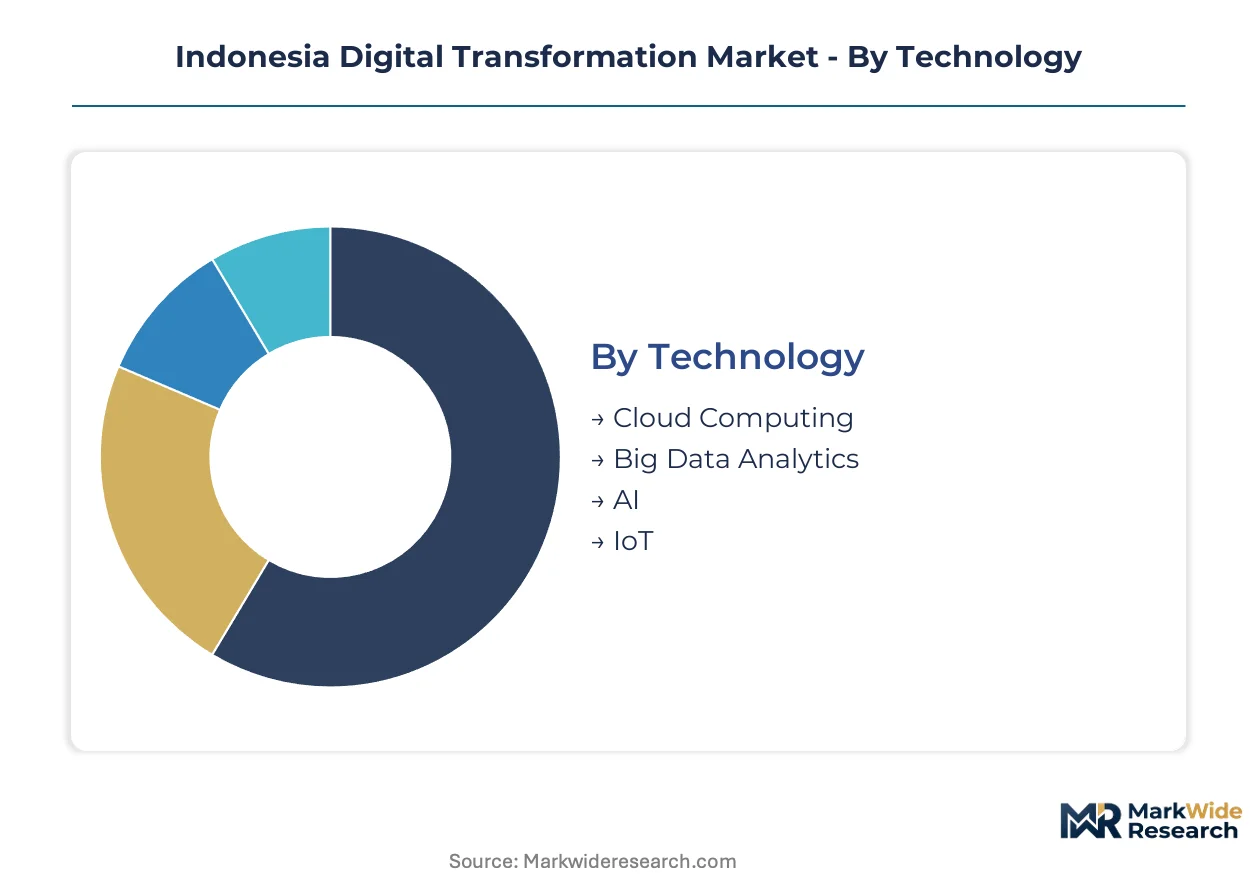
Technology deployment patterns across Indonesia's archipelago create divergent procurement requirements between mature Java-based enterprises and emerging provincial markets. Segmentation reveals how regulatory mandates and infrastructure maturity reshape vendor strategies and customer investment priorities.
Technology:
Mature infrastructure segments dominate enterprise spending while emerging categories capture venture capital and pilot program allocations.
- Cloud Computing:Public and hybrid environments host enterprise workload migrations as Jakarta-region availability zones from AWS and Azure anchor Southeast Asia expansion. Financial services and state-owned enterprises drive demand under Bank Indonesia's payment system modernization directives.
- AI:Predictive maintenance platforms and fraud detection systems capture expanding IT budgets through machine learning pipelines deployed at manufacturing facilities and banking operations. Natural language processing applications for customer service automation concentrate in telecommunications and e-commerce.
- Big Data Analytics:Consumer behavior modeling tools process transaction streams from modern trade and digital payment networks.
- IoT:Industrial sensors for supply chain visibility and quality control digitize manufacturing floors across Java and Batam.
Cloud Computing handles the majority of throughput; AI is the fastest mover on share.
End User:
Cost tier stratification separates capital-intensive manufacturing deployments from services-led retail and healthcare implementations.
- Manufacturing:Discrete and process manufacturers deploy edge computing nodes and industrial IoT for predictive maintenance across Bekasi and Karawang industrial zones. Electronics and automotive producers prioritize sub-10 millisecond latency applications for quality control automation.
- Retail:Modern trade operators and e-commerce platforms invest in demand forecasting and computer vision for inventory management. Consumer behavior modeling integrates online and offline transaction data to optimize merchandising decisions.
- Healthcare:Hospital information systems and telemedicine platforms expand under Ministry of Health digitization programs.
- Education:Learning management systems and digital credentialing platforms scale through government procurement initiatives.
Manufacturing commands the largest project values; Retail is expanding most quickly as consumer data monetization accelerates.
Deployment:
Customer type divides between regulated institutions requiring data sovereignty and agile enterprises prioritizing scalability.
- Public Cloud:Scalable compute and storage services attract technology-native enterprises and startups through consumption-based pricing models. SaaS applications for customer relationship management and enterprise resource planning dominate procurement.
- Hybrid:Workload portability between on-premises infrastructure and public environments satisfies financial services compliance requirements. Tier-one banks maintain sensitive core banking functions locally while bursting non-critical operations to cloud.
- Private Cloud:Dedicated infrastructure deployments serve defense, critical infrastructure, and data-sensitive government agencies.
- On-premises:Legacy system retention persists in institutions with mainframe-dependent technical debt.
Hybrid deployments satisfy the broadest regulatory requirements; Public Cloud is gaining share fastest among mid-market enterprises.
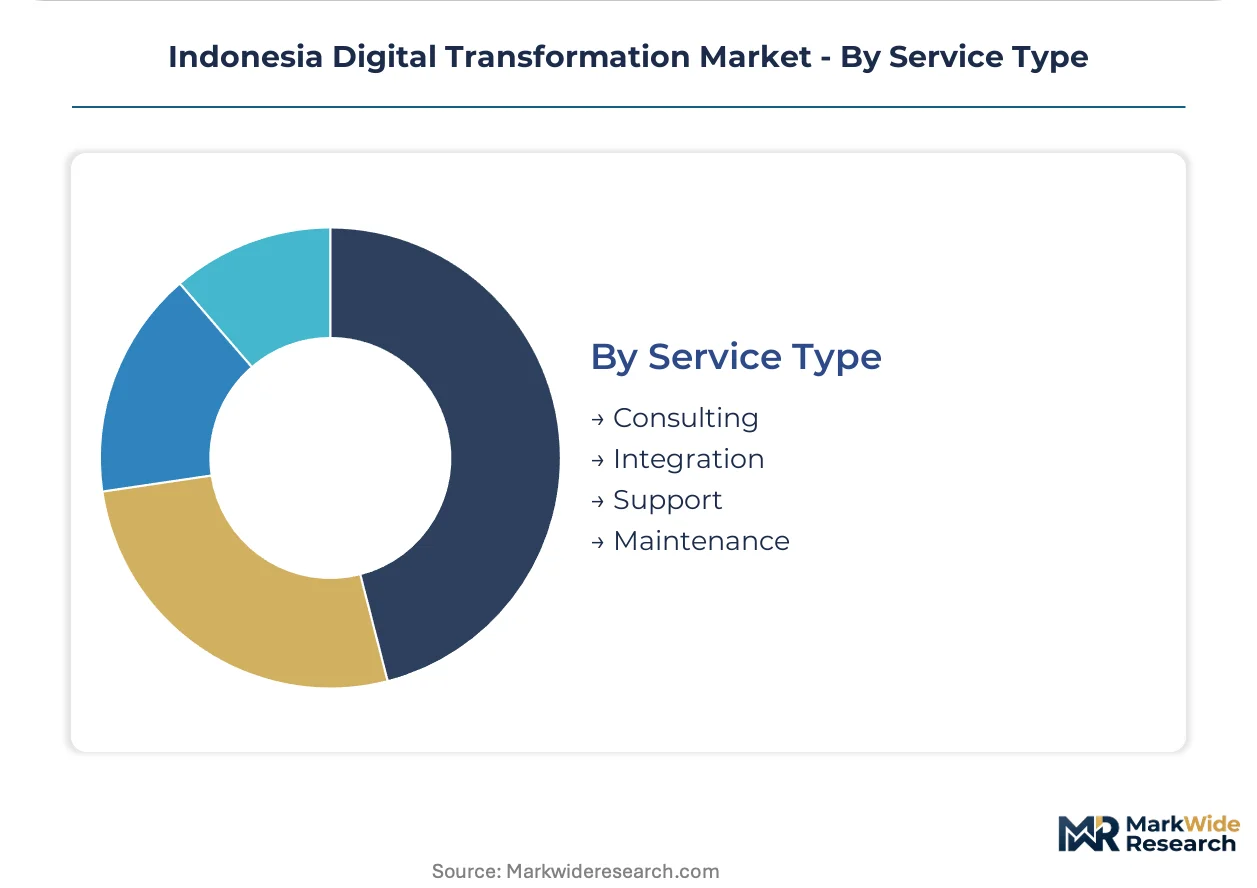
Service Type:
Supply concentration in Jakarta creates geographic clustering for high-value consulting and integration engagements.
- Integration:System interoperability projects connect legacy core banking architectures with cloud-native platforms and national payment switches. Regional banks lacking in-house capabilities drive third-party demand under Bank Indonesia compliance timelines.
- Consulting:Digital transformation strategy and change management services guide state-owned enterprises through multi-year modernization programs. Cloud migration roadmaps and cybersecurity assessments dominate engagement scopes.
- Support:Managed services for infrastructure monitoring and incident response operate across 24/7 coverage requirements.
- Maintenance:Application updates and security patching sustain operational continuity for deployed platforms.
Integration captures the highest project margins; Consulting is climbing the fastest as strategic planning precedes execution spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java-based enterprises consume digital transformation services through hybrid cloud deployments, while Eastern Indonesian provinces prioritize connectivity infrastructure over advanced analytics. This consumption-mix differential shapes vendor resource allocation and partnership strategies across the archipelago.
Greater Jakarta
Financial services and e-commerce platforms drive cloud-native platform procurement under Bank Indonesia's payment system modernization mandates. The Ministry of Communication and Informatics' data localization requirements compel foreign providers to establish domestic availability zones. The Jakarta-Bogor-Depok-Tangerang-Bekasi corridor concentrates venture capital deployment and enterprise software procurement decisions.
West Java
Discrete manufacturers in Bekasi and Karawang industrial zones deploy industrial IoT sensors for predictive maintenance and quality control automation. The provincial government's smart manufacturing incentives accelerate edge computing node installations. Electronics and automotive producers in these zones prioritize sub-10 millisecond latency applications for defect detection workflows.
East Java
Port and logistics operators in Surabaya invest in supply chain visibility platforms as Tanjung Perok port expansion digitizes cargo tracking. The provincial administration's e-government procurement platforms create demand for locally certified cloud integrators. Surabaya's emerging fintech cluster replicates Jakarta's regulatory sandbox model for payment system innovation.
Batam
Electronics manufacturing services firms deploy industrial IoT for production line monitoring under Batam Free Trade Zone investment incentives. The island's submarine cable landing stations attract hyperscaler edge computing deployments. Batam Industrial Park hosts precision manufacturers integrating computer vision systems for component inspection workflows.
Eastern Indonesia
Sulawesi, Maluku, and Papua present greenfield opportunities as PT Telekomunikasi Indonesia extends fiber connectivity beyond Java. Provincial enterprises in mining and agriculture sectors digitize procurement and logistics with basic cloud infrastructure. Government procurement preferences for locally certified vendors create entry barriers for foreign platform providers in this underpenetrated zone.
Indonesia Digital Transformation Market Competitive Landscape
Capability concentration sits with global hyperscalers possessing certified cloud infrastructure; scale advantage sits with domestic integrators controlling state-linked distribution channels. The market structures around three tiers: foreign platform providers establishing localized availability zones, domestic telecommunications incumbents leveraging connectivity backbones, and systems integrators bridging compliance requirements. Strategic moves center on infrastructure localization partnerships and domestic certification acquisition to satisfy government procurement regulations.
Among global technology providers, Amazon Web Services Inc., Microsoft Corporation, and IBM Corporation occupy positions representing the hyperscaler archetype establishing Jakarta-region infrastructure. These entities exemplify the foreign platform tier navigating data residency mandates through domestic partnership structures. PT Telekomunikasi Indonesia and PT Multipolar Technology Tbk sit within the domestic integrator tier, anchoring state-linked distribution channels that satisfy public sector tender requirements. Google LLC and Oracle Corporation represent alternative cloud and enterprise software positioning within this competitive configuration.
| Leading Market Players |
|---|
| IBM Corporation |
| Amazon Web Services Inc. |
| Accenture PLC |
| Oracle Corporation |
| SAP SE |
| Microsoft Corporation |
| PT Telekomunikasi Indonesia |
| PT Multipolar Technology Tbk |
| Google LLC |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler infrastructure concentration in Singapore and US West Coast data centers governs where margin pools accumulate across Indonesia's digital transformation value chain. Cloud-native platform providers capture recurring revenue streams while domestic integrators extract implementation premiums from compliance-heavy deployments.
Pricing Analysis
Project-based professional services and multi-year SaaS subscriptions dominate contract structures, with Bank Indonesia compliance timelines forcing tier-two banks toward fixed-scope integration engagements. Price differentiation rests on domestic certification tier and localization depth, with PD Law-certified deployments commanding premiums over uncertified alternatives. Cost compression in public cloud compute tiers is intensifying because hyperscaler competition accelerates in Jakarta availability zones. State-owned enterprises exhibit lowest price sensitivity due to procurement preference mandates, while provincial mid-market manufacturers face acute budget constraints.
Supply Chain Analysis
US export controls on advanced AI accelerators and semiconductor manufacturing equipment limit hyperscaler capacity expansion in Southeast Asian nodes. Hardware supply concentrates in Taiwan, South Korea, and mainland China for server components and networking equipment. Raw material dependencies span advanced lithography equipment, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability runs through submarine cable landing stations controlled by PT Telekomunikasi Indonesia. Distribution runs through state-linked channel partners that satisfy government procurement regulations for public sector tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around interoperable payment infrastructure as Bank Indonesia's real-time gross settlement mandates force architectural standardization across previously siloed banking systems.
For Market Incumbents: Build switching-cost moats through deep integration with national payment switches and core banking modernization programs. Deepen backward integration into domestic data center operations to satisfy PD Law residency requirements without margin erosion to foreign hyperscalers. Expand certification engineering teams to accelerate BIS-equivalent cybersecurity approval timelines ahead of regulatory enforcement intensification. For New Entrants and Emerging Players: Eastern Indonesian provincial capitals with nascent fiber connectivity represent the most penetrable entry point for cloud infrastructure build-out ahead of hyperscaler node expansion. Mid-market regional banks lacking in-house integration capabilities offer concentrated demand for compliance-focused professional services. Partner with PT Telekomunikasi Indonesia's enterprise division to access state-linked distribution channels required for government and SOE procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic systems integrators possessing established government relationships and certification portfolios but limited platform technology ownership. Long-term viability hinges on migration from project-based implementation revenue toward recurring managed services and platform subscription models. Monitor regulatory enforcement intensity around cross-border data flow restrictions as the signal indicating whether global platforms or domestic integrators capture incremental enterprise contract growth.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Availability Zone Establishment | AWS and Azure Jakarta-region expansion satisfies Bank Indonesia data localization mandates for financial services workloads. |
| State-Linked Distribution Partnership | Microsoft's channel arrangement with PT Telekomunikasi Indonesia unlocks public sector procurement pathways. |
| Core Banking Integration Specialization | Accenture's regional bank modernization practice captures compliance-driven replacement cycles under payment system mandates. |
| Edge Computing Node Deployment | Manufacturing IoT adoption in Bekasi and Karawang zones drives sub-10 millisecond latency infrastructure investment. |
| Cybersecurity Certification Acquisition | Domestic integrator investment in BIS-equivalent standards creates procurement preference advantages in government tenders. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings on vendor qualification timelines and enforcement patterns. Conversations with Bank Indonesia policy officers, cloud platform engineers at hyperscaler Jakarta operations, regional bank CTOs, and systems integrator delivery heads inform implementation timeline and budget allocation assessments. Secondary sources include Ministry of Communication and Informatics certification databases, Bank Indonesia payment system roadmap documentation, and enterprise software procurement records from state-owned enterprise tenders. Bottom-up project pipeline analysis and top-down market sizing triangulate volume estimates.
Calibration against historical technology adoption curves in comparable Southeast Asian markets shapes the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user industry vertical, organization size tier, and geographic infrastructure maturity. CAGRs derive from fitted growth curves applied to technology-specific penetration rates, with AI-analytics convergence and manufacturing IoT adoption treated as independent forecast inputs alongside cloud migration velocity.
Macroeconomic conditions sit as an overlay; deviation in rupiah exchange rate stability and central bank interest rate trajectories would shift the trajectory of infrastructure investment cycles. Forecasts reflect assumptions on regulatory enforcement timing and fiber connectivity expansion schedules. Material shifts in US technology export control scope or domestic data localization interpretation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Digital Transformation Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
Saudi Arabia Digital Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
Digital Transformation in Supply Chain Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
Japan Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Oman Digital Transformation Market