
 United States Digital Transformation Market | 2026-2036
United States Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
United States Digital Transformation Market Insights
Subscription-based software-defined networking is rebalancing how enterprises procure connectivity and security, shifting capital expenditure to recurring operational models. Microsoft Corporation leverages its Azure ecosystem to anchor hybrid cloud deployments across federal and commercial accounts. IBM Corporation sustains mainframe modernization services that bridge legacy infrastructure with containerized workloads. Amazon Web Services dominates public cloud capacity expansion, controlling data center buildouts in Northern Virginia and Oregon.
United States Digital Transformation encompasses the integration of digital technologies into organizational processes, systems, and customer interactions, typically involving API-driven architectures, microservices orchestration, and real-time data pipelines operating at sub-100-millisecond latency thresholds. Its primary purpose is to enhance operational efficiency, decision velocity, and customer engagement across physical and virtual value chains. Cloud-based deployment leads in new contract value as enterprises exit owned data centers, while artificial intelligence within solution types captures expanding margin pools through predictive maintenance and generative workflow automation. Managed services within service types are maturing fastest as providers assume full operational accountability for client technology estates.
Federal mandates from the Cybersecurity and Infrastructure Security Agency, alongside NIST frameworks and state-level data privacy statutes such as the California Consumer Privacy Act, shape procurement standards and vendor qualification requirements for public-sector contracts. The Federal Risk and Authorization Management Program creates a compliance gateway that filters market access for cloud service providers seeking federal business. Stakeholders must monitor evolving FedRAMP authorization timelines and state privacy fragmentation as determinants of competitive positioning and geographic service eligibility.
Market Dynamics
Federal cloud migration mandates under executive orders are compressing procurement cycles and forcing legacy infrastructure exits across civilian and defense agencies. Healthcare providers in Texas and California are accelerating electronic health record modernization to meet interoperability deadlines.
Growth Catalysts
- FedRAMP Authorization Pathway:The Federal Risk and Authorization Management Program creates standardized security baselines that streamline cloud vendor qualification for federal contracts. Defense and civilian agencies now require FedRAMP Moderate or High for new procurements.
- Artificial Intelligence Integration:Manufacturing workflows in the Great Lakes industrial corridor are embedding predictive maintenance and generative automation into production lines. Automotive and aerospace suppliers report measurable throughput gains from real-time data pipelines.
- Electronic Health Record Mandates:Texas and California hospital systems are expanding EHR modernization to achieve API-driven interoperability under federal healthcare IT standards. Rural provider networks receive targeted funding for telehealth infrastructure.
Market Restraints
- Specialized Talent Scarcity:Kubernetes orchestration and zero-trust architecture skills command premium compensation in Northern Virginia and Seattle metro areas. Federal contractors face clearance backlogs that extend hiring timelines.
- State Privacy Fragmentation:The California Consumer Privacy Act conflicts with emerging statutes in Texas and Virginia, forcing multi-state enterprises to maintain parallel data governance frameworks. Compliance costs scale with geographic footprint.
- Legacy Technical Debt:COBOL-based federal payment systems and mainframe-dependent state unemployment platforms resist containerization. Migration failures at the Department of Veterans Affairs demonstrate operational continuity risks.
Strategic Opportunities
- Underpenetrated State and Local:Municipal governments in the Southeast and Mountain West lag federal cloud adoption by three to five years. Subscription-based software-defined networking offers operational expenditure models that bypass capital budget constraints.
- Edge Computing Convergence:5G network slicing combined with containerized microservices enables sub-50-millisecond latency for autonomous vehicle testing in Arizona and industrial IoT in Ohio. Telecommunications carriers are partnering with hyperscalers on distributed cloud nodes.
- Managed Services Expansion:Healthcare providers in Florida and Pennsylvania are outsourcing full technology estate operations to assume outcome-based accountability. Vendors absorb infrastructure risk while capturing recurring revenue streams.
Industry Challenges
- Zero-Trust Implementation Complexity:Federal agencies struggle to segment legacy networks without disrupting mission-critical workflows. The Cybersecurity and Infrastructure Security Agency's 2024 guidance requires continuous verification architectures that conflict with flat network designs.
- Interoperability Standard Delays:Healthcare data exchange protocols remain fragmented between HL7 FHIR versions. Epic and Cerner implementations require expensive custom integration layers that erode modernization budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Digital Transformation Market |
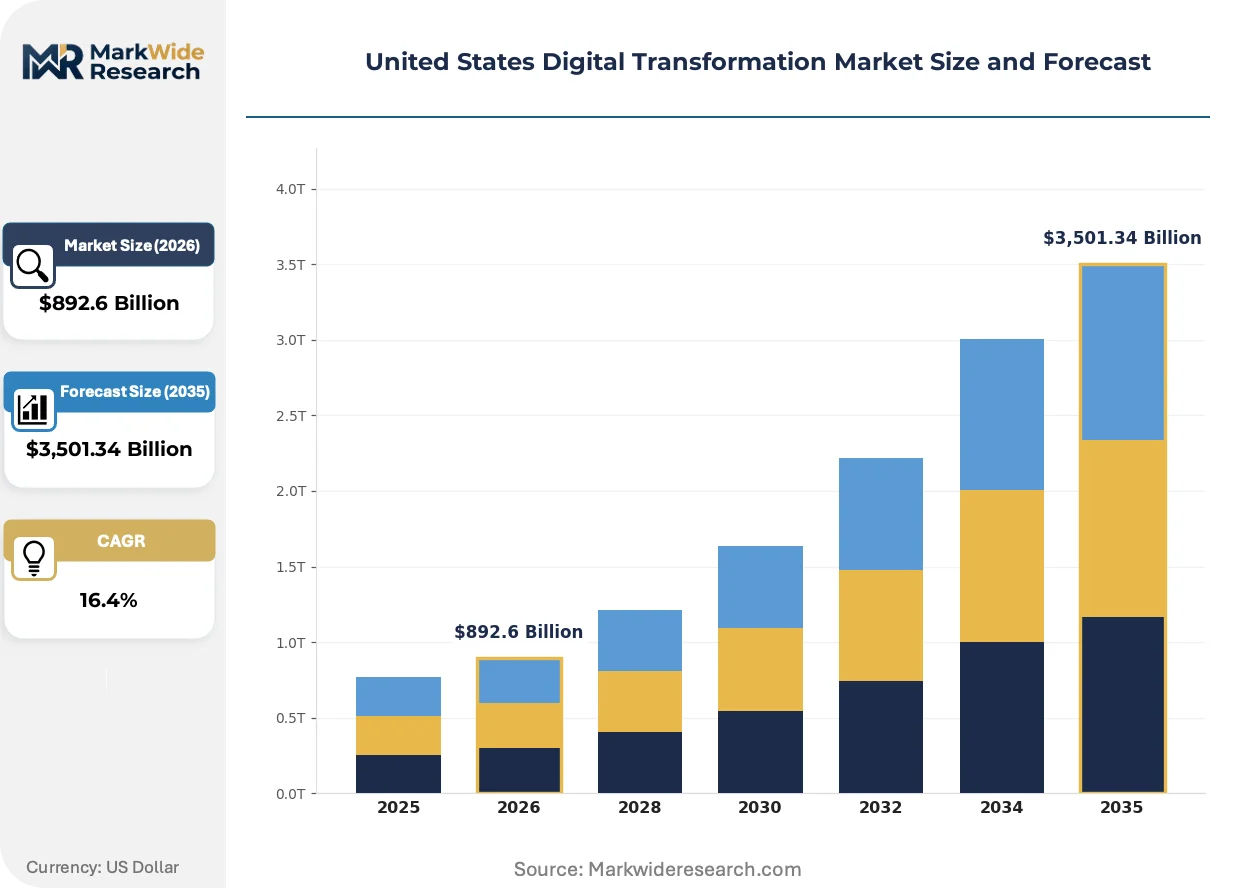
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $3,501.34 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Type: Analytics, Automation, IoT, Artificial Intelligence End User: Manufacturing, Retail, Healthcare, Education Service Type: Consulting, Integration, Support, Managed Services |
| Companies Covered | Microsoft Corporation, IBM Corporation, Amazon Web Services, Accenture, Cisco Systems, Google LLC, Oracle Corporation, Cognizant Technology Solutions, Salesforce, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Digital Transformation Market Trends and Innovations
API-driven architectures are compressing system integration timelines from months to weeks across federal and commercial deployments. Real-time data pipelines now operate at latency thresholds that enable predictive rather than reactive decision-making.
Edge computing infrastructure is decentralizing data processing from centralized hyperscale regions to distributed nodes within 50 miles of end-users. Manufacturing facilities in Michigan and Ohio are deploying containerized workloads on factory-floor servers to eliminate cloud round-trip delays. Automotive suppliers report 40-millisecond response times for quality-control computer vision that previously required dedicated on-premise data centers.
The Cybersecurity and Infrastructure Security Agency's zero-trust architecture mandate is forcing network perimeter redesign across executive branch departments. Agencies must implement continuous verification protocols that replace implicit trust based on network location. Defense contractors in Northern Virginia are accelerating security stack consolidation to meet 2027 compliance deadlines.
Subscription-based procurement is displacing perpetual license models in state government technology acquisitions. Texas and North Carolina procurement offices now prioritize operational expenditure structures that align vendor payments with measurable service outcomes. Managed service providers assume operational accountability for client infrastructure while capturing multi-year recurring revenue commitments.
United States Digital Transformation Market Segmentation
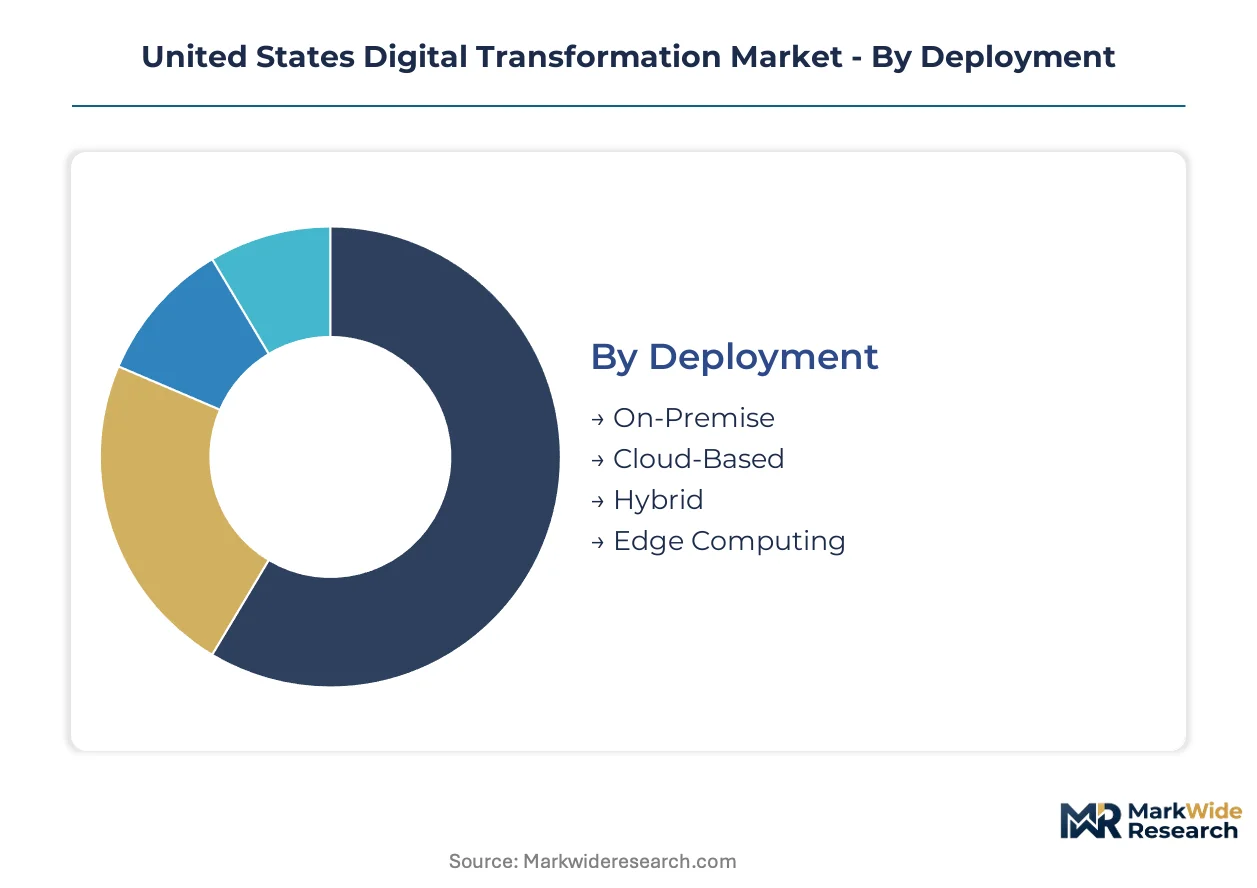
Segmentation of the United States Digital Transformation Market reveals how procurement patterns concentrate around specific deployment architectures and vertical applications. Vendors align capability investments with the service models and end-use requirements that dominate contract value.
Deployment:
Supply concentration in hyperscale data center regions shapes deployment preferences across federal and commercial accounts.
- Cloud-Based:Public cloud infrastructure delivers elastic compute and storage through API-driven provisioning. Federal agencies in Northern Virginia and civilian departments in Oregon are compressing procurement cycles under executive migration mandates.
- Hybrid:Workload portability between on-premise and cloud environments bridges legacy mainframe estates with containerized microservices. Financial services firms in New York and Chicago maintain sensitive transaction processing on-premise while bursting analytics to cloud.
- On-Premise:Dedicated infrastructure retains dominance in classified defense environments and regulated healthcare data centers.
- Edge Computing:Distributed nodes within 50 miles of end-users enable sub-50-millisecond latency for industrial IoT and autonomous vehicle testing.
Cloud-Based absorbs the bulk of installed capacity; Edge Computing is expanding most quickly.
Solution Type:
Margin pools concentrate around predictive capabilities that reduce operational downtime and automate decision workflows.
- Artificial Intelligence:Machine learning models embedded in manufacturing workflows enable predictive maintenance and generative automation. Automotive and aerospace suppliers in the Great Lakes corridor report measurable throughput gains from real-time quality-control computer vision.
- Analytics:Real-time data pipelines operating at sub-100-millisecond latency thresholds compress decision cycles from reactive to predictive. Retailers in California and Texas deploy customer behavior analytics to optimize inventory positioning.
- Automation:Robotic process automation and intelligent document processing streamline back-office operations across federal agencies.
- IoT:Sensor networks and connected device platforms monitor asset performance in industrial and healthcare settings.
Analytics commands the largest share of current solution spending; Artificial Intelligence is climbing the fastest.
End User:
Customer concentration in regulated industries drives compliance-heavy procurement specifications and extended sales cycles.
- Healthcare:Electronic health record modernization and API-driven interoperability dominate capital allocation. Hospital systems in Texas and California accelerate deployments to meet federal healthcare IT deadlines, while rural networks receive targeted telehealth infrastructure funding.
- Manufacturing:Predictive maintenance and digital twin implementations concentrate in the Great Lakes industrial corridor. Michigan and Ohio facilities deploy containerized workloads on factory-floor servers to eliminate cloud round-trip delays.
- Retail:Omnichannel customer engagement platforms and supply chain visibility tools reshape inventory and fulfillment operations.
- Education:Learning management systems and campus-wide IoT networks modernize administrative and instructional delivery.
Healthcare captures the deepest solution penetration; Manufacturing is gaining share fastest.
Service Type:
Procurement patterns are shifting from project-based engagements to recurring operational models that transfer infrastructure risk to vendors.
- Managed Services:Providers assume full operational accountability for client technology estates, capturing multi-year recurring revenue commitments. Healthcare providers in Florida and Pennsylvania outsource complete infrastructure operations to align vendor payments with measurable outcomes.
- Integration:API-driven architectures and microservices orchestration compress system integration timelines from months to weeks. Federal contractors face clearance backlogs that extend deployment timelines in Northern Virginia.
- Consulting:Strategy and roadmap engagements guide legacy modernization decisions for agencies burdened by COBOL technical debt.
- Support:Maintenance and break-fix services sustain operational continuity for hybrid infrastructure environments.
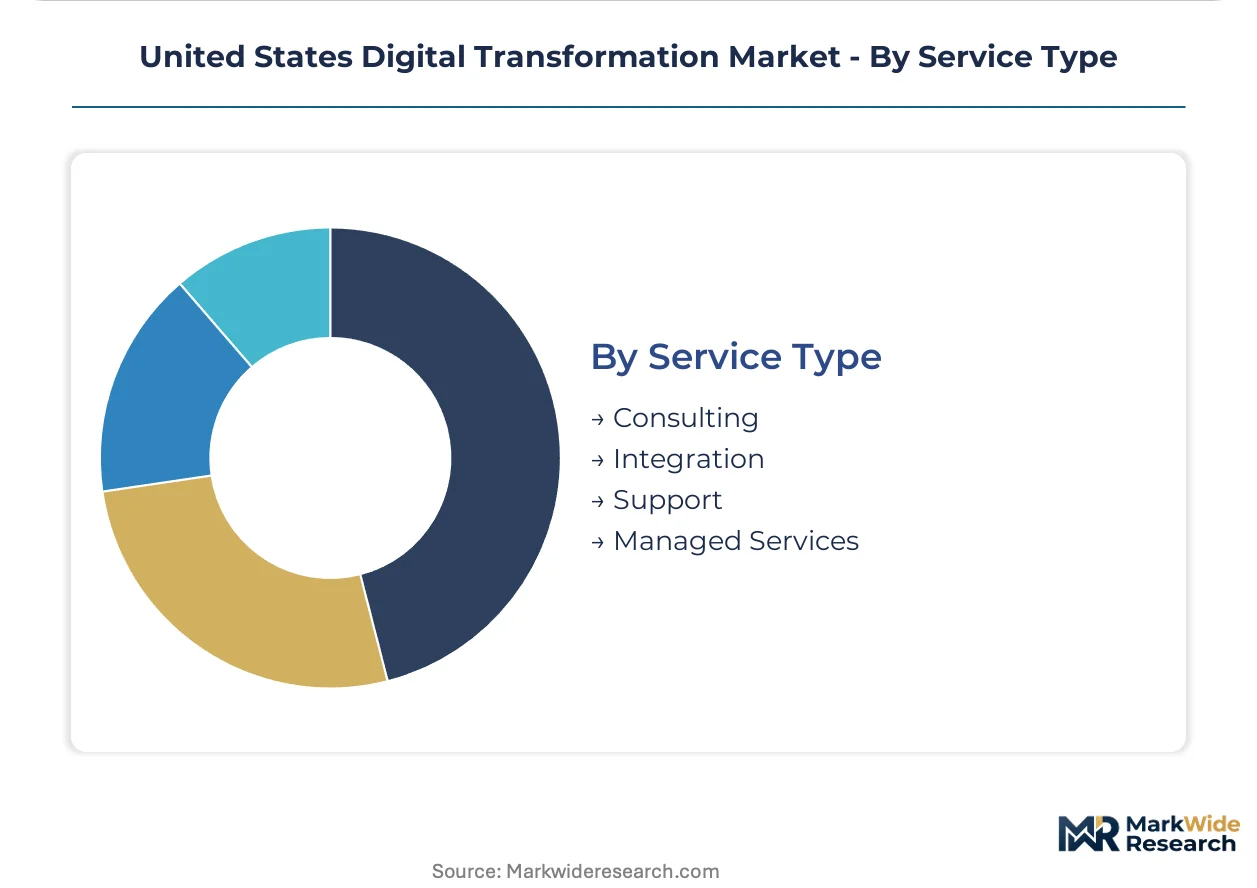
Integration absorbs the bulk of professional services capacity; Managed Services is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in hyperscale data center clusters while consumption spreads across federal, healthcare, and manufacturing verticals. Northern Virginia and Oregon anchor cloud infrastructure buildouts. Texas and California drive healthcare digitization demand.
California
Hospital systems in Los Angeles and San Francisco accelerate electronic health record modernization to meet interoperability deadlines under federal healthcare IT standards. The California Consumer Privacy Act imposes strict data governance requirements on multi-state enterprises operating within the state. Silicon Valley technology vendors and San Diego biotech clusters generate substantial demand for API-driven architectures and real-time analytics pipelines.
Texas
Rural provider networks receive targeted federal funding for telehealth infrastructure expansion across the Dallas-Fort Worth and Houston medical corridors. State procurement offices prioritize operational expenditure models that align vendor payments with measurable service outcomes. Austin and San Antonio emerging technology hubs concentrate managed services demand from state agencies and municipal governments.
Northern Virginia
Defense contractors and civilian agencies compress procurement cycles under executive cloud migration mandates. The Federal Risk and Authorization Management Program creates compliance gateways that filter market access for service providers seeking federal business. The Dulles data center corridor hosts the densest concentration of hyperscale cloud capacity in the United States.
Great Lakes Corridor
Michigan and Ohio manufacturing facilities deploy containerized workloads on factory-floor servers to eliminate cloud round-trip delays for predictive maintenance systems. Automotive and aerospace suppliers report measurable throughput gains from real-time quality-control computer vision. Cleveland and Detroit industrial clusters anchor digital twin implementations for production line optimization.
Pacific Northwest
Seattle metro area Kubernetes orchestration and zero-trust architecture skills command premium compensation across federal contractor labor markets. Oregon data center regions expand public cloud capacity to serve civilian agency workloads. Portland and Seattle technology ecosystems sustain hybrid cloud deployment expertise for enterprise accounts exiting owned data centers.
United States Digital Transformation Market Competitive Landscape
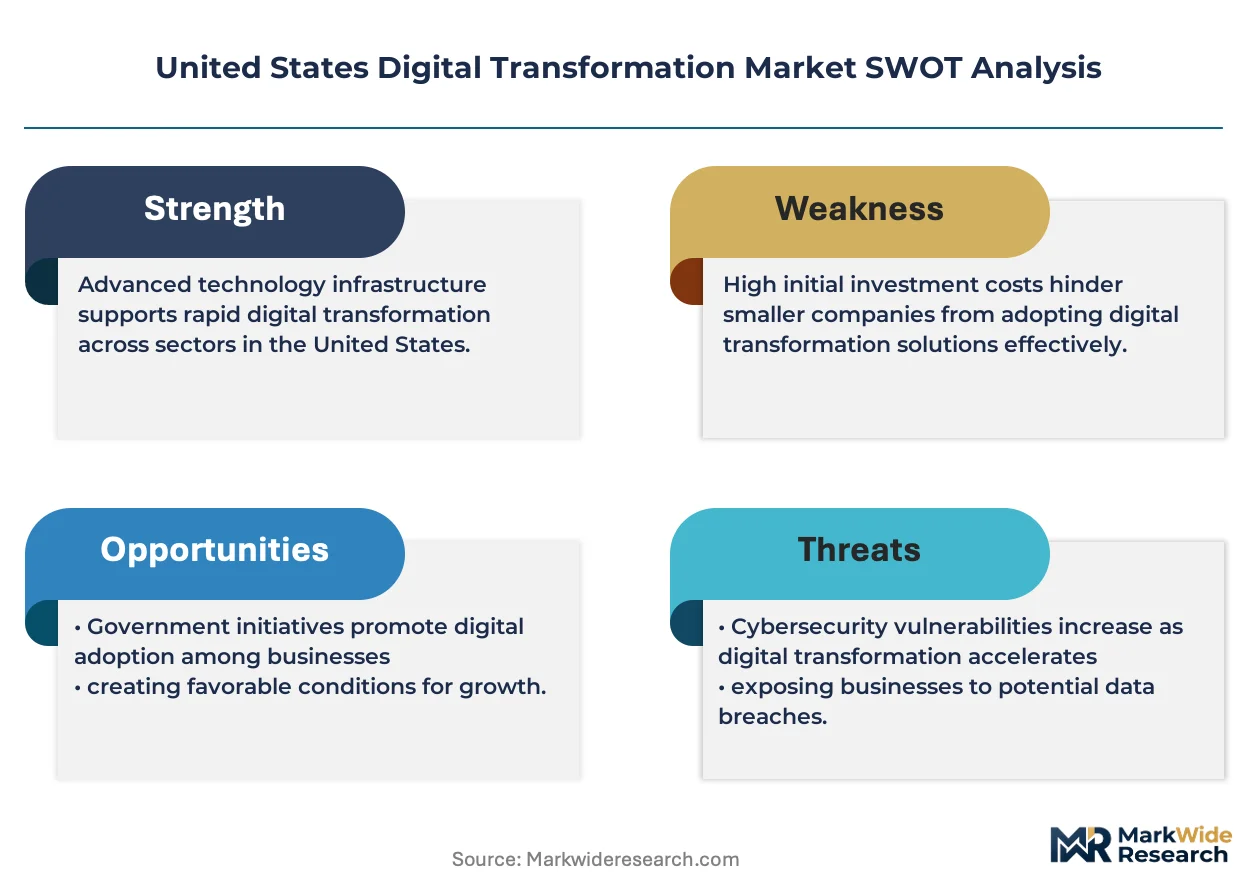
Top-tier vendors anchor hyperscale cloud and platform ecosystems, while mid-tier systems integrators and specialized consultancies fill implementation and compliance gaps. The vendor base stratifies across three tiers: infrastructure providers controlling data center capacity, platform vendors delivering API-driven orchestration layers, and service firms assuming operational accountability for client estates. Two strategic archetypes dominate: cloud-native challengers displacing legacy procurement models and mainframe modernization specialists bridging technical debt. Competitive moves concentrate on FedRAMP authorization acquisition and managed services portfolio expansion.
Within the infrastructure tier, Microsoft Corporation and Amazon Web Services exemplify contrasting approaches to hybrid deployment architectures. IBM Corporation occupies a distinct position bridging legacy mainframe estates with containerized workloads. These three entities represent the dominant competitive anchors around which federal contracting ecosystems and commercial procurement patterns organize.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| Accenture |
| Cisco Systems |
| Google LLC |
| Oracle Corporation |
| Cognizant Technology Solutions |
| Salesforce |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up managed services specialists anchor pricing discipline through multi-year recurring revenue contracts that transfer infrastructure risk to vendors while compressing procurement cycles. Their ownership structure rewards predictable cash flows over project-based margin volatility, reshaping how federal agencies and healthcare providers evaluate total cost of ownership against capital budget constraints.
Pricing Analysis
Margin tightening in cloud migration services reflects hyperscaler capacity expansion in Northern Virginia and Oregon that commoditizes baseline compute offerings. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP High-authorized environments from Moderate and provisional tiers. Cost-down pressure on hybrid integration accelerates because mainframe-dependent agencies demand bridge architectures without full legacy retirement. State and local governments exhibit highest price sensitivity due to capital budget constraints, while defense contractors absorb premium pricing for classified environment compliance.
Supply Chain Analysis
Hardware refresh and decommissioning flows from federal data center consolidations feed secondary markets for certified refurbished servers in domestic redistribution channels. Taiwan and South Korea anchor semiconductor supply for edge computing nodes deployed in Michigan and Ohio manufacturing facilities. Mexico and Canada provide nearshore assembly capacity for telecommunications infrastructure supporting 5G network slicing. Single-source vulnerability concentrates in specialized zero-trust security silicon from a dominant foundry. Distribution runs through systems integrator-led channel partnerships that bundle hardware procurement with managed service obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized microservices architectures displace monolithic legacy estates across federal and healthcare verticals, compressing modernization timelines from years to months.
For Market Incumbents: Anticipate margin compression in baseline cloud compute as hyperscalers expand capacity, and respond by deepening vertical integration into managed services portfolios that assume full operational accountability. FedRAMP authorization timelines represent a critical defensive lever—accelerate security stack consolidation to maintain procurement gateway control. Kubernetes orchestration talent scarcity in Northern Virginia and Seattle threatens service delivery capacity. For New Entrants and Emerging Players: Cloud-native channel routes through state procurement offices in Texas and North Carolina bypass entrenched federal contractor relationships. Municipal governments in the Southeast and Mountain West present the most penetrable segment, lagging federal cloud adoption by three to five years. Target operational expenditure models that align vendor payments with measurable service outcomes, bypassing traditional capital budget approval cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor managed services specialists with established FedRAMP authorization in the Great Lakes corridor manufacturing vertical. Long-term viability hinges on recurring revenue concentration and outcome-based contract structures that retain clients through technology transitions. Monitor CISA zero-trust implementation guidance revisions as inflection indicators for security stack consolidation demand.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acquisition | Defense contractors in Northern Virginia compress timelines to meet 2027 CISA compliance deadlines. |
| Managed Services Portfolio Expansion | Healthcare providers in Florida outsource full technology estate operations to assume outcome-based accountability. |
| Edge Computing Infrastructure Deployment | Automotive suppliers in Ohio achieve 40-millisecond response times for factory-floor quality-control computer vision. |
| Hybrid Cloud Integration Platform | Financial services firms in Chicago maintain sensitive transaction processing on-premise while bursting analytics to cloud. |
| Zero-Trust Architecture Implementation | Federal agencies segment legacy networks under CISA continuous verification mandates without disrupting mission workflows. |
Research Methodology
Independent corroboration across federal procurement officers, healthcare CIOs, and manufacturing operations directors underwrites the qualitative findings on modernization prioritization. Primary interviews with cloud platform engineers, systems integrator delivery leads, and state technology procurement managers captured deployment timeline and budget allocation patterns. Secondary validation drew from FedRAMP authorization databases, CISA guidance documents, and hyperscaler capital expenditure disclosures. Bottom-up contract value aggregation and top-down macroeconomic adjustment produced convergent market sizing.
Rate-of-change decomposition across deployment model, solution type, vertical, and service model dimensions structured the analytical framework. Segmentation modeling incorporated organization size, integration complexity, and regional adoption pattern variations. CAGRs were derived from fitted growth curves calibrated to disclosed contract values and procurement pipeline data. Artificial intelligence solution penetration and managed services revenue mix served as industry-specific forecast inputs throughout the projection horizon.
The model holds under sustained federal cloud migration mandates and stable FedRAMP authorization timelines; deviation in CISA zero-trust implementation deadlines or state privacy statute fragmentation would shift vendor competitive positioning. Practitioners should monitor FedRAMP authorization queue lengths and state-level data governance harmonization efforts for early signals of procurement velocity changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
MENA Digital Transformation Market