
 Powder Compacting Pressers Market | 2026-2036
Powder Compacting Pressers Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Compacting Pressers Market Intelligence
The direct sales channel between European press builders and Asian battery material producers is narrowing as regional distributors consolidate aftermarket service contracts. Dorst Technologies GmbH & Co. KG leverages its ceramic pressing heritage to dominate isostatic graphite anode production lines. SACMI Imola S.C. anchors the pharmaceutical tablet press segment through continuous manufacturing platforms. Fette Compacting GmbH specializes in high-speed rotary presses for nutraceutical applications, competing on tooling changeover speed.
Powder compacting pressers are mechanical or hydraulic machines that apply controlled uni-axial or isostatic pressure to metal, ceramic, or composite powders within hardened die cavities, typically achieving green densities of 85-95 percent theoretical with tolerances of ±0.02 mm. These systems enable net-shape manufacturing of complex geometries for powder metallurgy bushings, ceramic substrates, and pharmaceutical tablets where machining would destroy material integrity or raise costs prohibitively. Hydraulic double-action pressers command the largest installed base across automotive powder metallurgy, though electric servo-driven automated systems are displacing mechanical designs in electronics ceramic manufacturing where layer thickness precision determines circuit performance. Pneumatic technology persists in low-tonnage packaging applications where margin pools have compressed to maintenance-contract economics.
EPA particulate matter standards and REACH chemical registration requirements are forcing press manufacturers to engineer sealed die chambers and dust collection integration as preconditions for North American and European market access. FDA cGMP guidelines for pharmaceutical manufacturing further constrain equipment validation protocols, raising barriers for manual and semi-automated press categories. Stakeholders must weigh captive powder supply integration against modular press platforms as material specifications fragment across solid-state battery and additive manufacturing feedstock markets.
Market Dynamics
Electric vehicle battery anode production is pulling isostatic pressing capacity toward graphite densification lines, while EPA particulate standards force sealed-chamber retrofits across legacy automotive powder metallurgy installations.
Growth Catalysts
- EV Powertrain Metallurgy:Solid-state battery developers require ultra-dense silicon-graphite composite anodes that only cold isostatic pressing can achieve at production scale.
- REACH Chemical Registration:ECHA compliance mandates for cobalt and nickel powder handling accelerate replacement of open mechanical presses with enclosed automated systems in European facilities.
- Additive Manufacturing Feedstock:Gas-atomized titanium and aluminum powders for binder jetting need spherical particle densification that rotary press tooling now accommodates.
Market Restraints
- Tungsten Carbide Die Costs:Tooling represents 35-40 percent of press system lifecycle cost, with cobalt binder price volatility transmitted directly to equipment tenders.
- Hydraulic Fluid Supply Concentration:Specialized fire-resistant hydraulic fluids for high-tonnage presses concentrate among German and Japanese chemical suppliers, creating single-source vulnerability.
- Mechanical Press Obsolescence Risk:Fixed-stroke mechanical designs face functional substitution by servo-electric systems in electronics ceramic applications requiring sub-10-micron layer precision.
Strategic Opportunities
- Indian Pharmaceutical Contract Manufacturing:CDSCO cGMP certification requirements for export-oriented tablet production create demand for continuous rotary press validation support services.
- US IRA Clean Energy Manufacturing:Domestic content bonuses for battery cell production incentivize greenfield pressing line deployment in Michigan and Nevada.
- Solid-State Electrolyte Densification:Sulfide and oxide ceramic electrolyte processing converges with pharmaceutical tablet manufacturing expertise in multi-layer compaction control.
Industry Challenges
- Servo Drive Calibration Expertise:Electric press commissioning requires motion control engineers familiar with both powder rheology and programmable force profiling, a skill set concentrated among German and Japanese OEM service teams.
- FDA Process Analytical Technology Validation:Real-time compaction force monitoring for pharmaceutical applications demands 18-24 month qualification timelines that delay revenue recognition on new equipment sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Compacting Pressers Market |
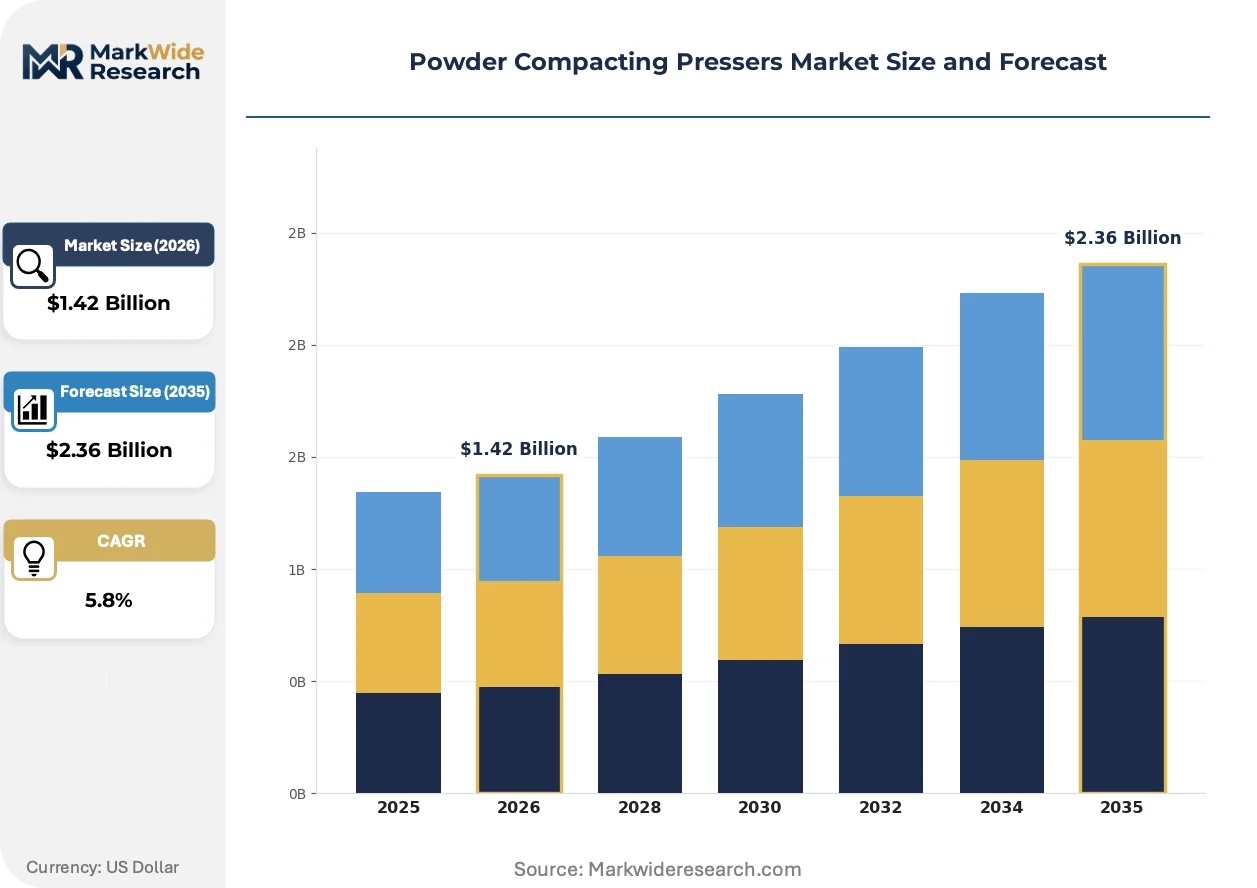
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Action, Double Action, Hydraulic, Mechanical Technology: Pneumatic, Electric, Manual, Automated End User: Aerospace, Pharmaceuticals, Electronics, Automotive Application: Powder Metallurgy, Ceramic Manufacturing, Tooling, Packaging |
| Companies Covered | SACMI Imola S.C., Gasbarre Products, Inc., Dorst Technologies GmbH & Co. KG, Osterwalder AG, SMS group GmbH, Beckwood Press, Ajax CECO Erie Press, Fette Compacting GmbH, Nanjing East Precision Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Compacting Pressers Market Strategic Shifts & Innovations
Servo-electric actuation is collapsing the performance gap between mechanical speed and hydraulic precision, while regulatory pressure on particulate emissions forces fundamental press architecture redesign across all major manufacturing geographies.
Electric servo press technology is collapsing cycle time disadvantages against mechanical flywheel designs through direct-drive torque motors and adaptive force profiling. Electronics ceramic manufacturers in Japan and South Korea now specify servo systems for multilayer ceramic capacitor production where electrode alignment tolerance sits below 5 microns. The technology is collapsing the traditional segmentation between automotive powder metallurgy and precision electronics manufacturing.
EPA National Ambient Air Quality Standards for PM2.5 and PM10 are compelling press manufacturers to engineer negative-pressure die chambers with HEPA filtration as standard equipment. Metal powder handlers in Ohio and Michigan now face OSHA permissible exposure limit enforcement that retroactively classifies legacy open-press installations as non-compliant. The regulatory pressure is collapsing the aftermarket for unenclosed mechanical press rebuilds.
After-sales service contracts are unbundling from equipment sales as battery material producers prioritize uptime guarantees over capital expenditure minimization. Asian cathode and anode manufacturers now procure pressing lines through operational expenditure models where OEMs retain tooling ownership and charge per-compacted-ton fees. The contract structure is concentrating service revenue with Dorst Technologies and SACMI Imola in Germany and Italy respectively.
Powder Compacting Pressers Market Segmentation
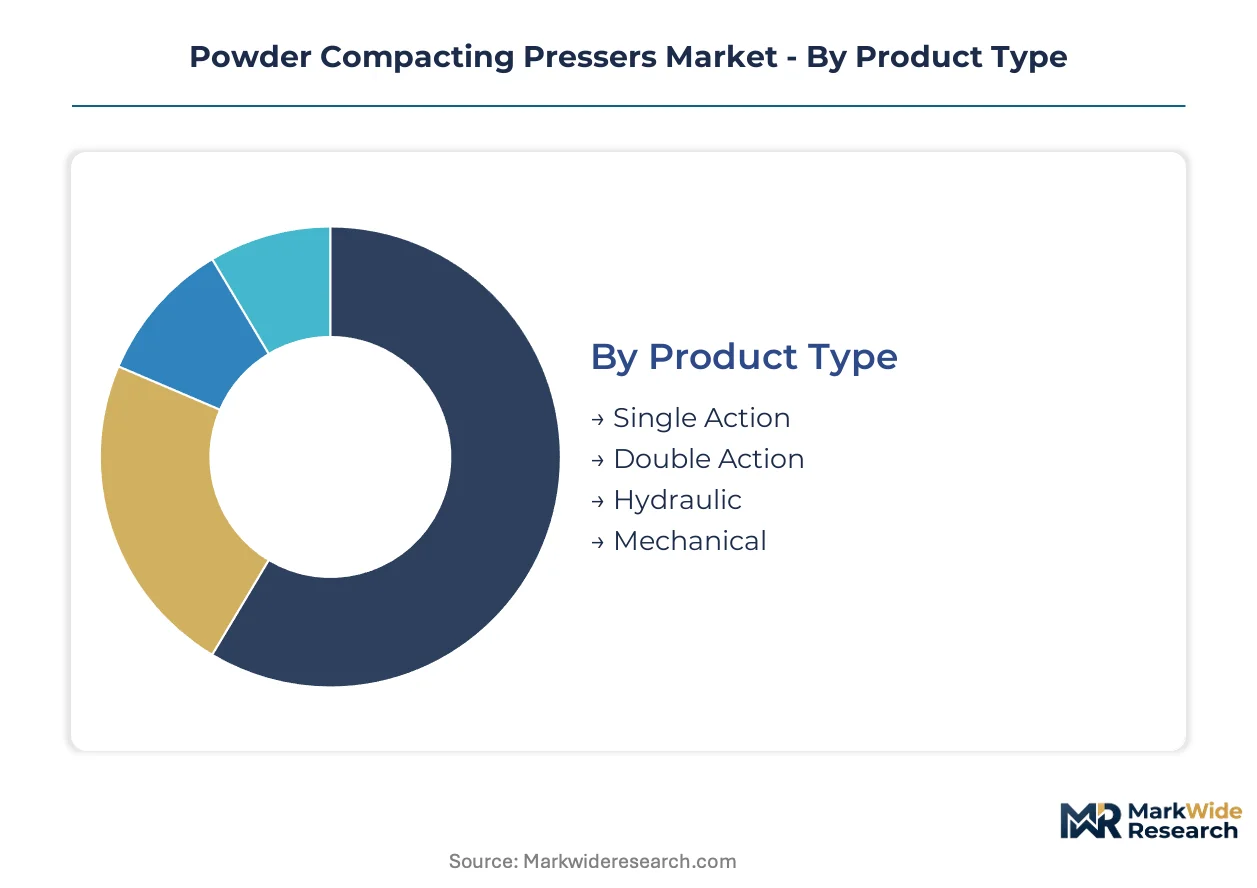
Powder compacting presser procurement patterns diverge sharply across product configurations, with service contract structures and tooling lifecycle economics driving vendor selection more than initial capital outlay. Segmentation clarity enables equipment buyers to match pressing technology against material specifications, regulatory compliance tiers, and production volume requirements.
Product Type:
After-sales service intensity varies dramatically by press configuration, with hydraulic systems demanding fluid analysis contracts and mechanical designs requiring precision rebuild programs.
- Single Action:Uni-directional force application from below produces simpler green compacts with density gradients concentrated at the punch contact surface. Automotive powder metallurgy shops in Germany favor these units for high-volume bushing production where die wear predictability supports scheduled maintenance programs.
- Double Action:Simultaneous upper and lower punch movement yields uniform density distribution critical for complex geometries in aerospace turbine blades. The synchronized motion control requires specialized calibration expertise concentrated among Japanese and German OEM service teams.
- Hydraulic:Fluid-powered systems deliver sustained tonnage across extended dwell times for ceramic substrate densification. Fire-resistant hydraulic fluid supply chains concentrate among German chemical suppliers, creating aftermarket vulnerability.
- Mechanical:Flywheel-driven crank mechanisms achieve fastest cycle rates for pharmaceutical tablet production. Fixed-stroke limitations face functional displacement by servo-electric alternatives in electronics applications.
By volume, Single Action leads. By growth pace, Double Action is expanding most quickly.
Technology:
Capital deployment patterns cluster around automation level, with battery material producers prioritizing operational expenditure models over equipment ownership.
- Pneumatic:Compressed air actuation persists in low-tonnage packaging applications where margin compression has reduced economics to maintenance-contract viability. Compressed air quality monitoring determines tooling life in food-grade tablet pressing.
- Electric:Servo-driven torque motors enable adaptive force profiling with sub-10-micron precision for multilayer ceramic capacitors. South Korean and Japanese electronics manufacturers specify these systems exclusively for electrode alignment tolerance below 5 microns.
- Manual:Hand-operated presses survive in laboratory-scale powder metallurgy R&D and artisan ceramic production. OSHA and REACH compliance costs now exceed equipment value for commercial manufacturing applications.
- Automated:Fully enclosed systems with integrated dust collection satisfy EPA PM2.5 standards and ECHA cobalt handling mandates. Asian anode manufacturers procure through per-ton service contracts where OEMs retain tooling ownership.
By installed base, Hydraulic dominates. By contract value migration, Automated systems are climbing the fastest.
End User:
Validation protocol intensity separates end-use segments, with pharmaceutical and aerospace applications demanding extended qualification timelines.
- Aerospace:Superalloy powder densification for turbine disks requires isostatic pressing with vacuum encapsulation. FAA material certification and AS9100 quality standards extend equipment commissioning to 24-36 months.
- Pharmaceuticals:Rotary tablet presses face FDA Process Analytical Technology validation requirements for real-time compaction force monitoring. Continuous manufacturing platforms now displace batch operations in large-scale generic production.
- Electronics:Multilayer ceramic capacitor manufacturing drives demand for servo-electric precision with layer thickness control below 2 microns. Japanese producers anchor specification development for this segment.
- Automotive:Powder metallurgy powertrain components—gears, bearings, and structural parts—constitute the largest equipment installed base. EV transmission designs are shifting material specifications toward silicon-rich sintered alloys.
By equipment count, Automotive leads. By specification escalation, Electronics is gaining share fastest.
Application:
Material handling requirements fragment application segments, with reactive metal powders and ceramic oxides demanding incompatible chamber designs.
- Powder Metallurgy:Ferrous and non-ferrous metal powder densification for structural components employs mechanical and hydraulic presses across 50-2000 ton ranges. German precision tooling clusters around Stuttgart supply hardened die sets with cobalt-bonded tungsten carbide inserts.
- Ceramic Manufacturing:Oxide and non-oxide ceramic pressing requires thermal management and abrasive wear resistance beyond metal powder applications. Solid-state battery electrolyte processing is converging with pharmaceutical expertise in multilayer compaction control.
- Tooling:Cemented carbide and diamond compact production uses ultra-high tonnage isostatic systems. Die insert manufacturing itself consumes substantial pressing capacity.
- Packaging:Low-density compaction for consumer goods employs pneumatic systems with minimal precision requirements. This segment exhibits highest price sensitivity and lowest service contract attachment rates.
By revenue concentration, Powder Metallurgy leads. By technology refresh rate, Ceramic Manufacturing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German press builders capture 35-40% lifecycle value through service contracts, while Chinese manufacturers compete on capital outlay alone. This pricing-power asymmetry shapes procurement patterns across battery material and pharmaceutical segments.
United States
Domestic content bonuses under the Inflation Reduction Act are accelerating greenfield pressing line deployment in Michigan and Nevada for battery cell production. EPA National Ambient Air Quality Standards for PM2.5 now retroactively classify legacy open-press installations as non-compliant, forcing sealed-chamber retrofits. Metal powder handlers in Ohio face heightened OSHA permissible exposure limit enforcement.
Germany
Precision tooling clusters around Stuttgart and Dortmund anchor European supply chains for hardened die sets with cobalt-bonded tungsten carbide inserts. ECHA REACH compliance mandates for cobalt and nickel powder handling are accelerating replacement of open mechanical presses with enclosed automated systems. Dorst Technologies GmbH & Co. KG leverages its ceramic pressing heritage to dominate isostatic graphite anode production lines.
Japan
Electronics ceramic manufacturers specify servo-electric systems exclusively for multilayer ceramic capacitor production where electrode alignment tolerance sits below 5 microns. METI industrial policy supports precision equipment R&D through targeted subsidies. Japanese producers anchor specification development for sub-10-micron layer precision applications.
China
Cathode and anode manufacturers now procure pressing lines through operational expenditure models where OEMs retain tooling ownership and charge per-compacted-ton fees. NMPA pharmaceutical manufacturing guidelines and MIIT industrial equipment standards constrain import specifications. Nanjing East Precision Machinery Co., Ltd. represents domestic fabrication capacity serving regional battery material producers.
India
CDSCO cGMP certification requirements for export-oriented tablet production create demand for continuous rotary press validation support services. Domestic pharmaceutical contract manufacturing is expanding capacity for generic drug exports to regulated markets. Mumbai-Pune and Ahmedabad-Vadodara industrial corridors concentrate equipment procurement decision-making.
Powder Compacting Pressers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in die tooling and hydraulic fluid supply. The vendor base organizes around three strategic archetypes: German precision-engineering houses with ceramic heritage, Japanese electronics-focused automation specialists, and Chinese scale-driven fabricators. Competitive moves cluster on aftermarket service contract unbundling and per-ton operational expenditure models that shift capital risk to OEMs.
Among German-based precision houses, Dorst Technologies GmbH & Co. KG and Fette Compacting GmbH exemplify the platform-integrator archetype with deep ceramic and pharmaceutical heritage respectively. SACMI Imola S.C. anchors Italian continuous manufacturing expertise, while Nanjing East Precision Machinery Co., Ltd. represents Chinese fabrication capacity competing on equipment cost. These three occupy positions spanning premium service-contract economics to capital-outlay-driven procurement.
| Leading Market Players |
|---|
| SACMI Imola S.C. |
| Gasbarre Products, Inc. |
| Dorst Technologies GmbH & Co. KG |
| Osterwalder AG |
| SMS group GmbH |
| Beckwood Press |
| Ajax CECO Erie Press |
| Fette Compacting GmbH |
| Nanjing East Precision Machinery Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Cobalt binder price volatility in tungsten carbide die manufacturing compresses margin pools across equipment tiers while simultaneously forcing buyers toward captive tooling arrangements or long-term service contracts. This input-cost instability widens the spread between configured-to-order German precision systems and standardized Asian fabrication, reshaping procurement patterns across battery material and pharmaceutical end users.
Pricing Analysis
Configured-to-order pricing for servo-electric systems with sub-10-micron precision commands substantial premiums over standardized hydraulic mechanical presses. Pricing stratifies across premium, standard, and economy tiers based on automation level and FDA/EMA validation status, with pharmaceutical-grade systems carrying the steepest premiums. Cost compression in economy-tier pneumatic packaging presses is intensifying because Chinese fabricators compete on capital outlay alone. Battery material producers show lowest price sensitivity, prioritizing uptime guarantees and per-ton service contracts over initial equipment cost.
Supply Chain Analysis
Contract manufacturing concentration for precision die sets sits with German tooling clusters around Stuttgart and Dortmund, alongside Japanese tungsten carbide specialists and Chinese volume fabricators. Raw material dependencies center on cobalt-bonded tungsten carbide inserts, specialized fire-resistant hydraulic fluids from German and Japanese chemical suppliers, and rare-earth servo motor components. Single-source vulnerability in hydraulic fluid supply creates aftermarket risk for high-tonnage press operators. Distribution runs through direct OEM channels for premium systems and regional distributors for standardized equipment, with Asian battery material producers increasingly favoring operational expenditure models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as solid-state battery electrolyte processing converges with pharmaceutical multilayer compaction expertise, creating specification niches that reward specialized platform integrators over generalist fabricators.
For Market Incumbents: Insulate service revenue streams by unbundling aftermarket contracts from equipment sales and capturing per-ton operational expenditure models. Dorst Technologies and SACMI Imola demonstrate this path through tooling ownership retention. Backward integration into cobalt-bonded tungsten carbide die manufacturing reduces exposure to commodity volatility. Priority lever: sealed-chamber retrofit programs for EPA and ECHA compliance in legacy automotive and European installations. For New Entrants and Emerging Players: Build out validation support capabilities for Indian pharmaceutical contract manufacturing, where CDSCO cGMP certification requirements create demand for continuous rotary press commissioning expertise. Target white-space in solid-state electrolyte densification equipment, where sulfide and oxide ceramic processing expertise remains scarce. Go-to-market angle: motion control engineering partnerships with German or Japanese OEM service teams to bridge servo drive calibration gaps. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors precision-engineering houses with ceramic heritage over mechanical press rebuild specialists. Long-term viability favors platform integrators commanding 35-40 percent lifecycle value through service contracts. Acquisition target archetype: mid-cap servo-electric automation specialists with pharmaceutical validation experience. Signal to watch: per-ton operational expenditure contract penetration rates in Asian anode manufacturing as indicator of pricing power migration.| Strategic Initiative | Industry Significance |
|---|---|
| Sealed-Chamber Retrofit Deployment | EPA PM2.5 compliance mandates in Ohio and Michigan force fundamental press architecture redesign. |
| Servo-Electric Platform Migration | Sub-10-micron precision requirements in Japanese MLCC production displace fixed-stroke mechanical designs. |
| Per-Ton Service Contract Unbundling | Asian battery material producers shift capital risk to OEMs through operational expenditure models. |
| Backward Integration into Die Manufacturing | Captive tungsten carbide supply insulates against cobalt binder price volatility transmitted to equipment tenders. |
| Validation Support Service Expansion | FDA Process Analytical Technology qualification timelines create 18-24 month revenue delay that specialists can compress. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC equipment manufacturer filings, ECHA REACH registration databases, EPA enforcement action records, and trade customs data for powder metallurgy machinery. Primary interviews engaged maintenance directors at automotive powder metallurgy shops, pharmaceutical manufacturing engineers, battery material procurement leads, and aftermarket service heads at German and Japanese OEMs. Bottom-up equipment shipment tracking triangulates against top-down end-use demand modeling across automotive, pharmaceutical, and electronics segments.
Forecast inputs incorporate press technology substitution curves, regulatory compliance deadline clustering, and raw material cost pass-through elasticity across the projection horizon. Segmentation dimensions modeled include automation level, end-use industry, regional regulatory cluster, and material handling specification. CAGRs derive from equipment procurement pipeline analysis and capacity expansion announcements. Industry-specific inputs capture solid-state battery commercialization timelines and pharmaceutical continuous manufacturing adoption rates.
Sensitivities concentrate around cobalt price volatility, EPA enforcement intensity variations, and servo drive component availability. Forecasts reflect assumptions on regulatory deadline adherence and technology substitution pace without guaranteed outcome. Quarterly review of ECHA substance restriction proposals, EPA National Ambient Air Quality Standard revisions, and Asian battery cell capacity buildout announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Nut Runner Market
Tools
Impact Sockets Market
Tools
Taps and Dies Market
Tools
Stand Tile Saw Market
Tools
Drill Bit Market
Tools
Ratchet Wringer Market
Tools
Multi Spindle Machines Market
Tools
Workholding Tools Market
Tools
Tension Tester Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
US Chalk Reel and Line Market
Tools
Foam Cutting Machine Market
Tools
Broaching Tools Market
Tools
Global Vertical Grinding Machine Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Painting Tools Market