
 Emollients Market | 2026-2036
Emollients Market Size, Share, and Industry Trends Forecast 2026-2036
Emollients Market Intelligence
The competitive landscape for emollients is shifting as the performance gap between premium, naturally-derived ingredients and lower-cost synthetic alternatives widens. BASF SE leverages its chemical production scale to compete on cost in high-volume segments. Croda International Plc specializes in sustainable, bio-based emollients for the premium personal care sector. The Lubrizol Corporation sustains its position by offering advanced functional emollients with specific sensory profiles.
Emollients are chemical agents designed to soften and soothe skin by forming an occlusive layer that reduces water loss. These ingredients, primarily lipids and oils, are fundamental to the texture and efficacy of topical formulations. Creams and lotions represent the largest product type categories, driven by their use in daily skincare. Demand from dermatology clinics and the pharmaceuticals end-user segment is expanding for formulations targeting specific skin conditions.
Ingredient safety and labeling are governed by stringent regulations, including the EU's REACH framework and oversight from the US FDA. In Japan, the PMDA sets standards for ingredients used in quasi-drug cosmetic products, influencing formulation choices. Future supplier success will depend on navigating the complex and divergent international standards for natural and synthetic ingredients.
Market Dynamics
The emollients market is defined by the fundamental tension between demands for scientifically-proven therapeutic efficacy and the consumer-driven shift toward natural, sustainable ingredients. This dynamic forces ingredient suppliers to balance investment in clinical validation against the complexities of securing and certifying bio-based feedstocks.
Growth Catalysts
- Therapeutic Skincare Demand:Heightened use of emollients in formulations for dermatology clinics, specifically targeting chronic conditions like eczema and psoriasis, drives consumption of high-performance, clinically-validated ingredients.
- EU Regulatory Frameworks:The EU's REACH regulation, coupled with consumer pressure for "clean labels," accelerates the replacement of older synthetic chemicals with newer, well-documented, and often naturally-derived emollients in new product formulations.
- Manufacturing Sector Concentration:Germany’s advanced personal care manufacturing ecosystem acts as a significant catalyst, pulling in a high volume of both standard and specialty emollients to supply its large-scale production of cosmetics for European and export markets.
Market Restraints
- Feedstock Price Volatility:Prices for natural emollients are subject to the volatility of agricultural commodity markets, affecting the cost structure for vegetable oils and butters and creating margin pressure for suppliers.
- Divergent Regulatory Standards:Conflicting and non-harmonized regulations for cosmetic ingredients, such as the differences between the EU's REACH and Japan's PMDA requirements, create compliance burdens and increase time-to-market for suppliers.
- Synthetic Substitution:In high-volume, cost-sensitive product segments like mass-market lotions, lower-cost synthetic emollients like mineral oil and silicones present a persistent substitution threat to more expensive bio-based alternatives.
Strategic Opportunities
- Male Grooming Formulations:The expanding male personal care market presents an opportunity for emollients with specific sensory profiles, such as non-greasy, fast-absorbing esters, tailored for products like beard oils and aftershave balms.
- Bio-fermented Ingredients:Developing novel emollients through bio-fermentation offers a path to creating unique, high-performance ingredients with strong sustainability credentials that are not dependent on traditional agricultural cycles.
- Southeast Asian Market Penetration:Rising disposable incomes and urbanization in countries like Indonesia and Vietnam create significant white space for both mass-market and premium skincare products, opening new channels for emollient suppliers.
Industry Challenges
- Multi-Regional Compliance Costs:The expense and administrative complexity of navigating ingredient registration and safety dossier submissions across multiple jurisdictions, including processes governed by the ECHA in Europe and the FDA in the US, is a major operational hurdle.
- Natural Ingredient Traceability:Ensuring consistent quality, purity, and ethical sourcing for naturally-derived emollients sourced from fragmented global agricultural supply chains poses a significant logistical and quality assurance challenge for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emollients Market |
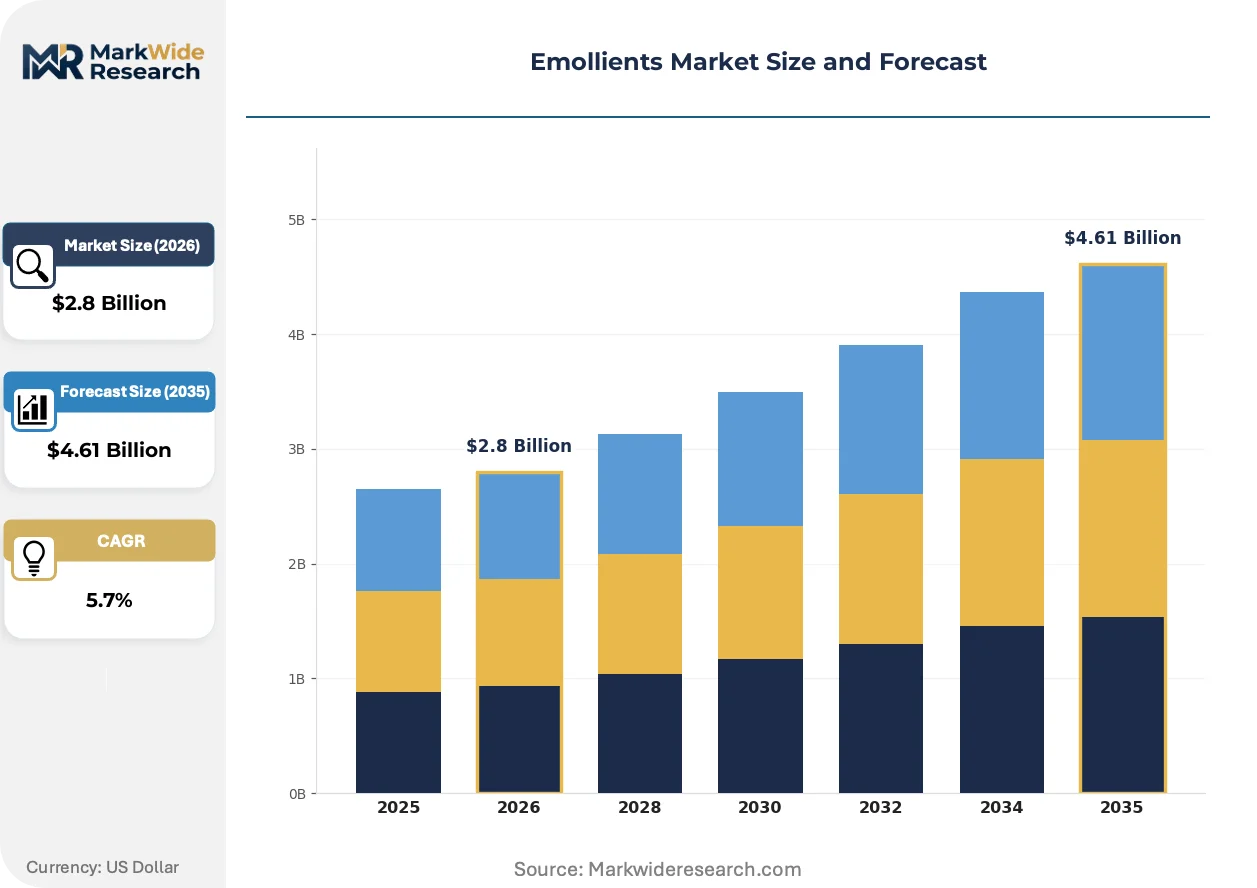
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balms, Creams, Lotions, Ointments End User: Households, Dermatology Clinics, Hospitals, Pharmaceuticals Form: Liquid, Gel, Stick, Spray Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Eastman Chemical Company, Lonza Group AG, BASF SE, Covestro AG, The Lubrizol Corporation, Croda International Plc, Clariant AG, Ashland Global Holdings Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emollients Market Strategic Shifts & Innovations
Innovation in the emollients sector is driven by a convergence of material science and sustainability mandates. Formulators are moving beyond basic moisturization, seeking ingredients that deliver specific sensory experiences and active functional benefits while meeting stringent environmental and safety criteria.
Advanced esterification and bio-fermentation are key production technologies. These processes create novel lipids and fatty acid derivatives that offer unique textures and improved compatibility with active ingredients. Premium personal care and derma-cosmetic brands are the primary adopters, seeking differentiation. This technological shift is rewriting the performance possibilities for sustainable ingredients, closing the gap with traditional synthetics.
Regulatory frameworks are increasingly focused on supply chain transparency. The EU's Corporate Sustainability Reporting Directive (CSRD) compels companies to disclose detailed environmental and social impacts. This forces emollient suppliers selling into the EU to provide verifiable lifecycle data for their products. The directive most acutely affects suppliers of "natural" ingredients, who must now substantiate their marketing claims with robust documentation.
Consumer preference for "skinimalism" is altering product formulation strategies. This trend favors multi-functional products over complex, multi-step routines. It disrupts the market for single-benefit ingredients and creates demand for advanced emollients that offer secondary benefits, such as soothing properties or barrier repair. This shift is most visible within the direct-to-consumer (DTC) beauty segment in North America.
Emollients Market Segmentation
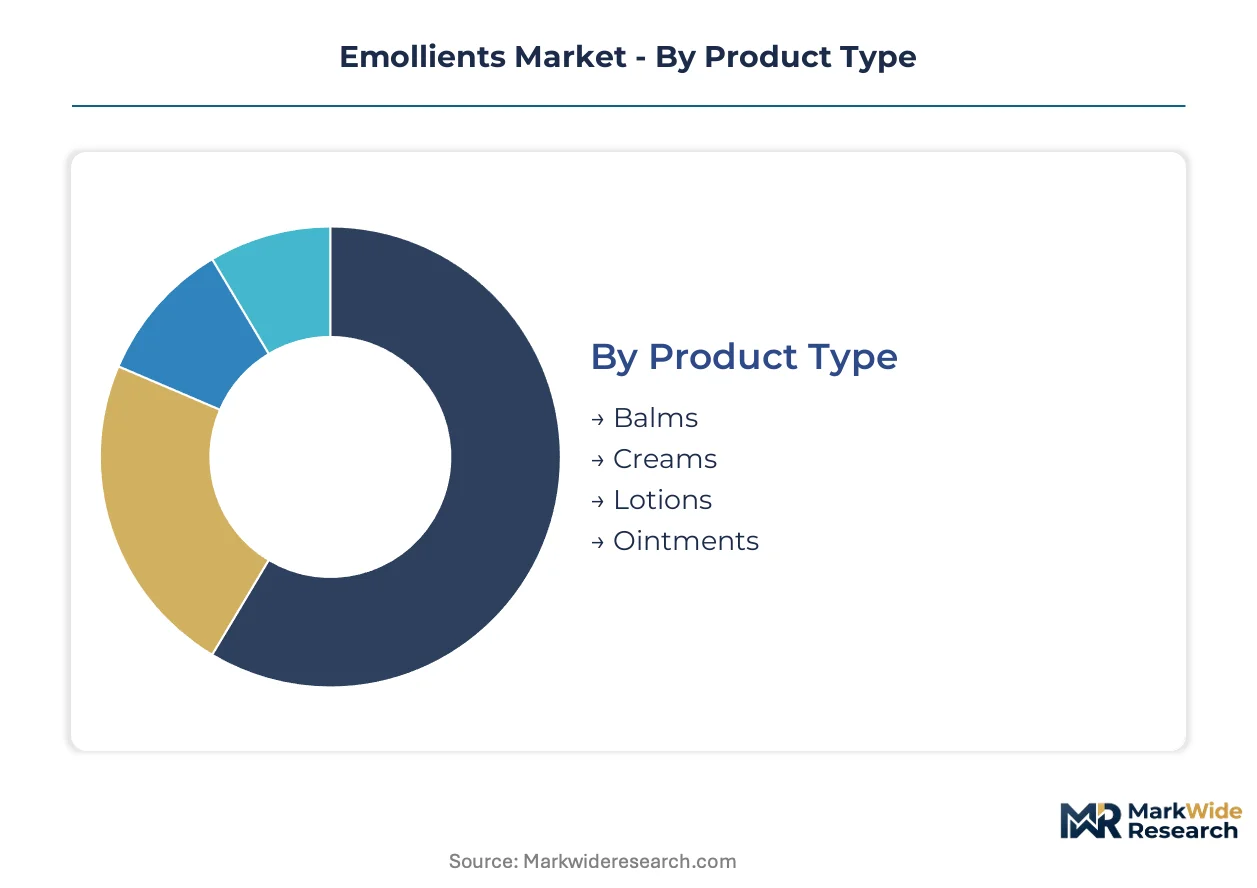
The emollients market is diverse, reflecting varied consumer needs and therapeutic applications for skin health. Understanding these distinct segments is critical for suppliers to tailor product development and market strategies effectively. This analysis breaks down the market by product type, end user, form, and distribution channel, highlighting key areas of demand.
Product Type:
Buyers differentiate emollients based on their intended skin penetration, occlusivity, and overall sensory feel.
- Creams:These semi-solid emulsions contain a balanced mix of oil and water, offering moderate occlusivity and a rich texture. Demand concentrates in dermatology clinics across Germany and the United States for formulations targeting conditions like eczema and psoriasis, driven by clinical validation.
- Lotions:Characterized by a higher water content and lighter texture than creams, lotions provide easy spreadability and less occlusive hydration. Significant demand originates from daily skincare routines in households globally, particularly for mass-market products where cost-effectiveness is a primary driver.
- Balms:Typically anhydrous or with very low water content, balms provide a highly occlusive barrier, often used for intense moisturization or protection in harsh conditions.
- Ointments:These oil-based, highly occlusive formulations are designed for maximum skin barrier repair and are frequently prescribed for severe dry skin or compromised barrier function.
Volume sits with Lotions; growth tilts toward Ointments.
End User:
End-user choice reflects the desired level of therapeutic intervention and specific skin health outcomes.
- Dermatology Clinics:These facilities utilize emollients in therapeutic skincare regimens for chronic conditions, requiring high-performance, clinically-validated ingredients. Demand for specialized formulations in clinics across Europe and North America is driven by an aging population and rising incidence of skin disorders.
- Pharmaceuticals:The pharmaceutical sector incorporates emollients as excipients or active ingredients in medicated topical formulations for specific skin conditions. Stringent regulatory oversight from bodies like the US FDA and Japan's PMDA influences ingredient selection and formulation choices for these products.
- Households:Consumers use emollients for general skincare, daily moisturization, and minor skin irritations, driving demand for a wide range of accessible and affordable products.
- Hospitals:Medical institutions employ emollients for patient care, including post-operative skin healing, pressure ulcer prevention, and general skin hydration for inpatients.
Demand for Households drives overall consumption; Pharmaceuticals show the steepest expansion trajectory.
Form:
Form factor selection depends on application convenience, sensory experience, and desired area of coverage.
- Liquid:These low-viscosity formulations offer easy spreadability and rapid absorption, suitable for large body areas or light moisturization. Liquid emollients find widespread use in daily body care products and bath additives.
- Spray:Spray emollients provide convenient, touch-free application and even distribution, appealing to consumers seeking quick and hygienic solutions. The male grooming segment in North America shows particular interest in fast-absorbing spray formats.
- Gel:Gels are water-based, non-greasy formulations that offer a cooling sensation and are preferred for oily or acne-prone skin types.
- Stick:Solid stick emollients provide targeted application and portability, commonly used for localized dry patches or lip care.
Liquid forms lead in general consumption; Spray formats are expanding most quickly.
Distribution Channel:
Channel selection reflects consumer purchasing habits, product positioning, and the need for expert advice.
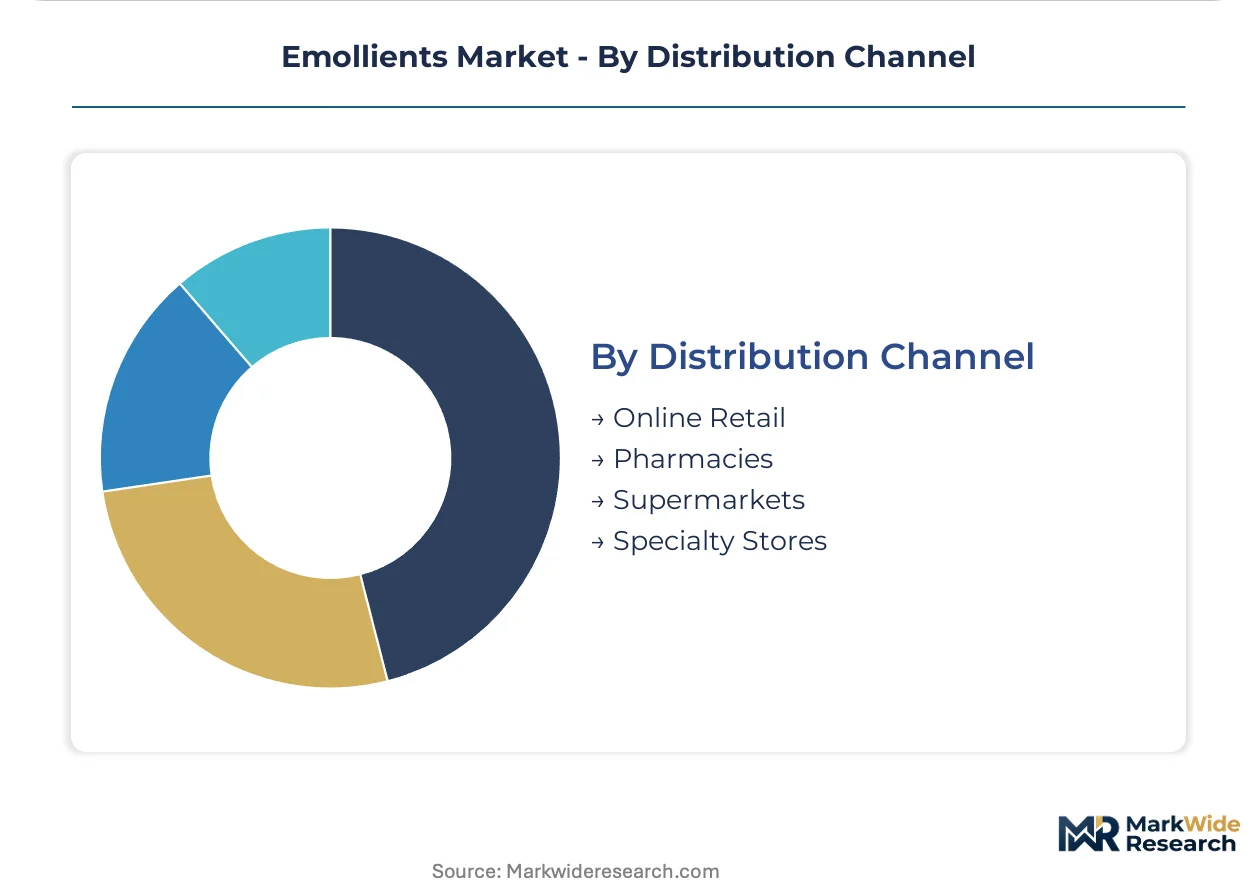
- Online Retail:E-commerce platforms facilitate broad product access and direct-to-consumer sales, enabling niche brands to reach a global audience. This channel is particularly strong in North America for specialty and premium emollients.
- Pharmacies:These outlets serve as key distribution points for therapeutic and dermocosmetic emollients, benefiting from consumer trust and pharmacist recommendations. Pharmacies in the EU are crucial for products compliant with REACH regulations.
- Supermarkets:Mass-market emollients, including lotions and creams for daily use, are widely available in supermarkets, catering to convenience and affordability.
- Specialty Stores:These retail environments focus on premium, natural, or organic emollient brands, offering a curated selection and personalized customer service.
Supermarkets account for significant volume; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced personal care manufacturing ecosystem drives significant emollient consumption across Europe. This concentration of production attracts both standard and specialty emollient suppliers. The country's strong regulatory environment also influences product development for the wider European market.
Germany
Demand for emollients in Germany originates from a robust personal care manufacturing sector producing for European and export markets. The EU's REACH regulation governs chemical safety, accelerating the adoption of well-documented, naturally-derived emollients. Berlin and Hamburg serve as key hubs for cosmetic R&D and production, fostering innovation in ingredient formulation.
United States
The United States market demonstrates high demand for high-performance emollients, particularly from dermatology clinics. The US FDA's stringent oversight shapes ingredient selection for pharmaceutical and medical-grade skincare products. Major cosmetic manufacturing clusters in states like California and New Jersey continuously seek advanced functional emollients for new product lines.
Japan
Japan's emollients market is characterized by specific regulatory requirements for quasi-drug cosmetic products. The PMDA sets rigorous standards for ingredient safety and efficacy, influencing formulation choices for local and international suppliers. Tokyo and Osaka remain central to the development of sophisticated skincare formulations, often incorporating novel textures and sensory profiles.
France
France, a global leader in premium personal care and luxury cosmetics, exhibits strong demand for sustainable and bio-based emollients. The country adheres to the EU's Corporate Sustainability Reporting Directive (CSRD), compelling suppliers to provide verifiable lifecycle data. Paris and Lyon are significant centers for cosmetic innovation and production, driving the adoption of advanced esterification and bio-fermentation technologies.
Emollients Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the emollients market, creating a diverse competitive structure. The industry exhibits a tiered landscape, with large chemical manufacturers occupying high-volume segments and specialized ingredient developers targeting premium niches. Companies primarily engage in strategic partnerships to enhance product portfolios and invest in advanced research and development for novel ingredients.
At the scale-driven end, BASF SE exemplifies a major chemical producer leveraging its extensive production capabilities to deliver cost-competitive emollients for mass-market applications. Croda International Plc occupies a position within the premium segment, specializing in sustainable, bio-based emollients for high-end personal care brands. The Lubrizol Corporation represents a key player focused on advanced functional emollients, providing specific sensory profiles and performance characteristics to formulators.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Lonza Group AG |
| BASF SE |
| Covestro AG |
| The Lubrizol Corporation |
| Croda International Plc |
| Clariant AG |
| Ashland Global Holdings Inc. |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
A clear performance gap between premium bio-based emollients and cost-effective synthetics drives divergent pricing strategies and complex supply chain configurations in the market.
Pricing Analysis
Value-based pricing anchors premium emollient sales, reflecting clinical validation and specific sensory profiles. Price differentiation stems from sustainability certifications like COSMOS or ECOCERT, alongside volume scale for mass-market offerings. Pricing pressure stems from bio-based innovation, which challenges older synthetic alternatives on performance and sustainability grounds. Households represent the most price-sensitive buyers, while dermatology clinics and pharmaceuticals prioritize performance over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the emollients supply chain, ensuring efficient delivery to diverse manufacturing clusters. Geographic supply concentration includes Germany for advanced manufacturing, Southeast Asia for natural feedstocks, and China for synthetic components. The market relies on vegetable oils, butters, and petrochemical derivatives as key raw materials. Agricultural commodity price volatility represents a significant structural risk. Distribution runs through direct sales to manufacturers, specialized ingredient distributors, and online retail for finished products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emollients market is becoming a consolidation play, driven by escalating multi-regional compliance costs that pressure smaller ingredient suppliers.
For Market Incumbents: Extend R&D into novel bio-fermentation techniques to secure unique ingredient profiles and counter feedstock price volatility. Invest in multi-regional regulatory compliance platforms to mitigate operational hurdles across diverse markets. Control of proprietary production technologies offers a competitive advantage against emerging substitute technologies.
For New Entrants and Emerging Players: The EU's Corporate Sustainability Reporting Directive in Europe opens a window for new entrants offering verifiable lifecycle data for natural ingredients. Target the premium derma-cosmetic segment with bio-fermented ingredients for superior sensory profiles. Focus on direct-to-consumer channels in North America for agile market penetration.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized bio-fermented ingredient producers given increasing consumer demand for sustainable and high-performance solutions. Focus on firms with proprietary fermentation technologies and robust supply chain traceability. Watch for increased M&A activity in the sustainable feedstock space as a key inflection indicator for long-term viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Support rising demand for emollients in Germany's advanced manufacturing sector. |
| Green Manufacturing Transition | Align with EU CSRD requirements for verifiable lifecycle data. |
| Long-term Supply Agreement | Mitigate feedstock price volatility for natural emollients. |
| Joint Venture | Access advanced esterification technologies for novel lipid development. |
| Geographic Expansion | Penetrate Southeast Asian markets with mass-market and premium skincare products. |
Research Approach
Independent corroboration across scientific literature, regulatory body publications, and industry trade reports underwrites the qualitative findings of this analysis. Primary interviews with R&D directors, procurement leads, and brand managers provided critical insights. Bottom-up and top-down triangulation ensured data validation and robustness across all market segments.
Forecasts were anchored to historical growth rates by analyzing comparable periods across the analysis window. Segmentation dimensions modeled include product type, end user, form, and distribution channel. Compound annual growth rates were derived from identified market drivers and restraints. Key forecast inputs include raw material availability and regulatory compliance costs.
The model assumes a particular bio-fermentation technology adoption path; alternative pathways for synthetic ingredient innovation would alter the outlook. Forecasts reflect current regulatory landscapes and consumer preferences. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market