
 Global Cosmetic Peptide Synthesis Market | 2026-2036
Global Cosmetic Peptide Synthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Peptide Synthesis Market Foresight
Automated solid-phase synthesis platforms is reconfiguring production economics for cosmetic-grade peptides, compressing cycle times while tightening batch-to-batch consistency. Givaudan SA (Active Beauty) leverages its integrated fragrance-to-actives pipeline to secure preferred supplier status with multinational personal care brands. Bachem Holding AG anchors its position through cGMP-compliant manufacturing infrastructure purpose-built for high-purity peptide APIs. Lonza Group AG competes on microbial expression systems that extend its reach into recombinant peptide architectures.
Cosmetic peptide synthesis encompasses the chemical or biological production of short amino acid chains engineered to modulate skin physiology, typically ranging from two to fifty residues and manufactured to cosmetic-grade purity standards below pharmaceutical thresholds. These bioactive molecules function primarily as cell-signaling agents that stimulate collagen production, inhibit melanin transfer, or modulate neurotransmitter release in topical applications. Signal peptides command the largest share of current output, while enzyme inhibitors represent the fastest-expanding category as brands target hyperpigmentation concerns across diverse skin phototypes. Microwave-assisted synthesis technology is gaining commercial traction by reducing solvent consumption and accelerating coupling efficiencies relative to conventional thermal methods.
REACH registration requirements in Europe and FDA's Modernization of Cosmetics Regulation Act in the United States are elevating toxicological documentation burdens, effectively filtering smaller suppliers from premium supply chains. China's NMPA cosmetic ingredient filing system and South Korea's MFDS functional cosmetic approval pathway add further jurisdictional complexity for peptide suppliers seeking multi-territory distribution. Stakeholders must monitor regulatory divergence between safety assessment frameworks and adapt ingredient dossiers to preempt market access friction across priority beauty manufacturing hubs.
Market Dynamics
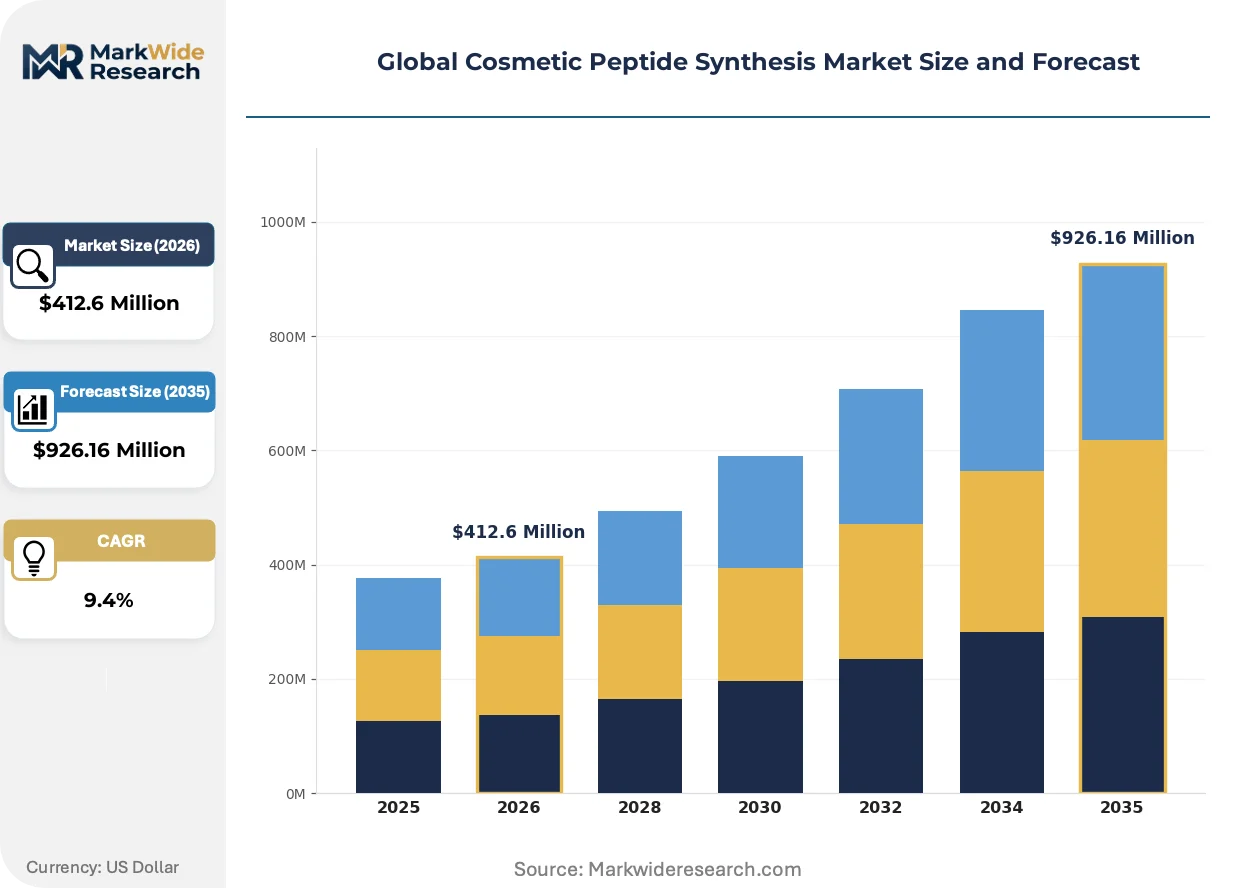
Automated solid-phase synthesis platforms are compressing production economics while REACH and FDA purity mandates filter sub-scale suppliers from premium supply chains. This dual pressure of technological acceleration and regulatory elevation defines current competitive restructuring.
Growth Catalysts
- Signal peptide demand:Anti-aging formulations from South Korean and Chinese personal care manufacturers are absorbing expanding volumes of collagen-stimulating peptides.
- REACH compliance:Europe's registration requirements for bioactive ingredients are consolidating demand around certified high-purity suppliers capable of toxicological documentation.
- Microwave-assisted synthesis:This coupling technology is reducing solvent consumption and accelerating batch throughput for cosmetic-grade peptide manufacturers.
Market Restraints
- Amino acid input volatility:Fluctuating costs of protected amino acid building blocks compress margin predictability for synthesis providers.
- Supplier concentration:cGMP-compliant manufacturing infrastructure for high-purity peptides concentrates among Swiss and German specialist facilities.
- Enzymatic substitution:Recombinant microbial expression systems from Lonza and competing biotech platforms threaten chemical synthesis for longer peptide chains.
Strategic Opportunities
- India domestic skincare:Underpenetrated peptide adoption in India's rapidly scaling beauty manufacturing sector offers first-mover positioning for compliant suppliers.
- Enzyme inhibitor expansion:Hyperpigmentation-targeting peptides for diverse skin phototypes represent the fastest-growing functional category.
- EU Green Deal alignment:Sustainability mandates favor suppliers with solvent-reduction credentials and renewable feedstock integration.
Industry Challenges
- Peptide chemist scarcity:Specialized expertise in solid-phase synthesis and purification optimization remains concentrated among aging European-trained specialists.
- Multi-jurisdictional dossier complexity:Divergent safety assessment frameworks across NMPA, MFDS, and FDA require redundant toxicological investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Peptide Synthesis Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $926.16 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Peptides, Carrier Peptides, Enzyme Inhibitors, Neurotransmitter Peptides, Matrix Peptides Application: Anti-Aging, Skin Lightening, Wrinkle Reduction, Moisturizing, Hair Care End User: Personal Care Manufacturers, Dermatology Clinics, Beauty Salons, Cosmetic Laboratories Technology: Solid Phase Synthesis, Liquid Phase Synthesis, Recombinant DNA Technology, Microwave-Assisted Synthesis |
| Companies Covered | Givaudan SA (Active Beauty), Bachem Holding AG, BASF SE, Lonza Group AG, PolyPeptide Group, Croda International plc (Sederma), DSM-Firmenich (Pentapharm), Evonik Industries, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Peptide Synthesis Market Shifts & Advancements
Process intensification and regulatory digitization are converging to reshape how cosmetic peptides move from laboratory bench to formulated product, with implications for speed-to-market and compliance burden distribution.
Flow chemistry platforms are digitizing peptide synthesis by enabling real-time reaction monitoring and automated parameter adjustment. Mid-scale cosmetic ingredient manufacturers in Switzerland and the Netherlands are deploying these systems to compress development timelines from months to weeks. This shift is enabling rapid iteration on custom peptide sequences for boutique beauty brands.
REACH's updated requirements for endocrine disruption screening are elevating documentation burdens for peptide suppliers seeking European market access. The regulation's industrial consequence is a bifurcation between dossier-capable incumbents and documentation-constrained challengers. Signal peptide suppliers serving multinational personal care brands are absorbing the highest compliance costs while securing preferred supplier status.
Direct formulation partnerships between peptide manufacturers and finished goods brands are displacing traditional distributor-mediated procurement in Asia-Pacific markets. South Korean beauty conglomerates are establishing captive synthesis relationships or equity stakes in specialized producers. This concentration is most visible in Seoul's advanced beauty manufacturing cluster, where vertical coordination compresses ingredient development cycles.
Global Cosmetic Peptide Synthesis Market Segmentation
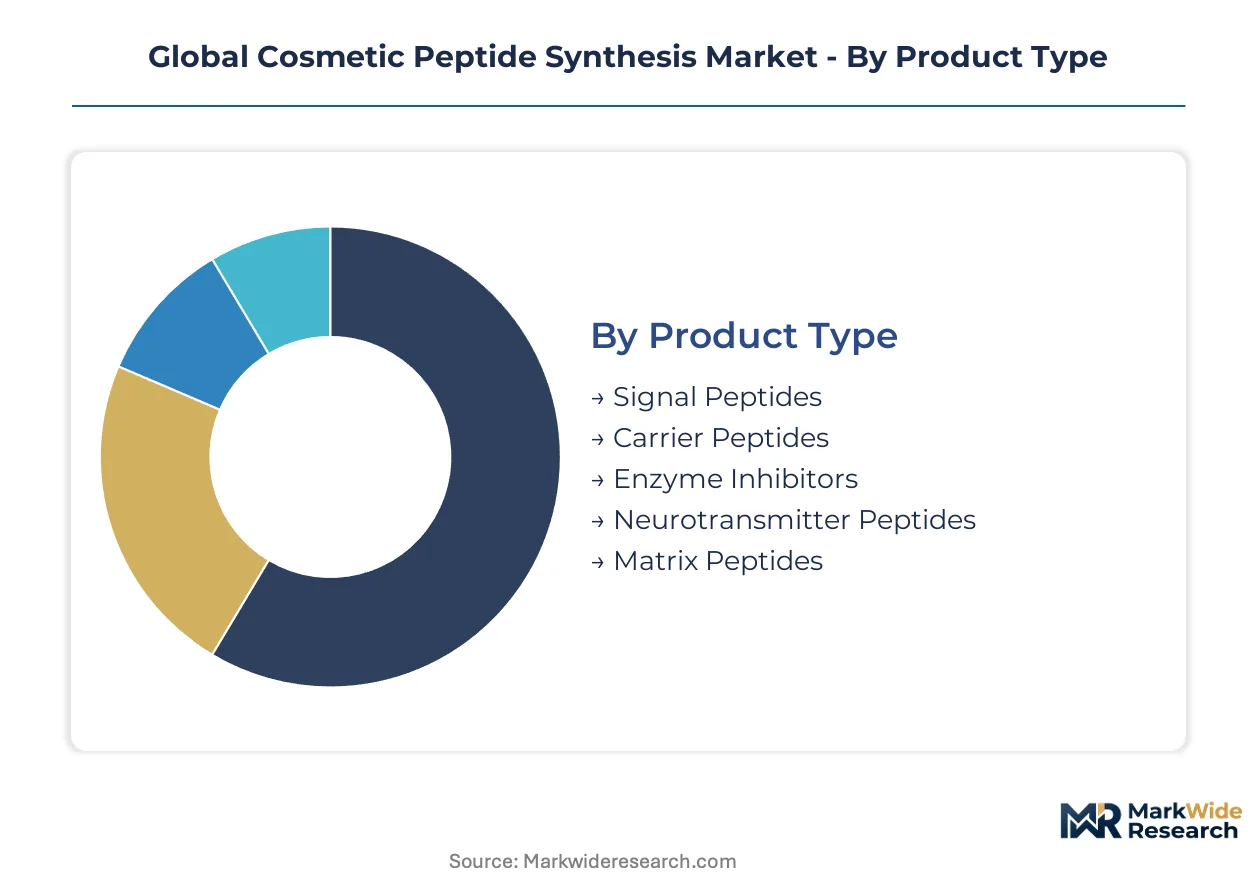
Cosmetic peptide synthesis segments diverge sharply in technical complexity and regulatory burden. Signal peptides and enzyme inhibitors command premium pricing due to documented efficacy requirements, while synthesis technology choices determine capital intensity and batch scalability.
Product Type:
After-sales technical support intensity varies dramatically across peptide categories, with signal peptides requiring formulation guidance and neurotransmitter peptides demanding stability consulting.
- Signal Peptides:Short amino acid sequences engineered to stimulate collagen synthesis and extracellular matrix remodeling. Demand concentrates among South Korean and Chinese personal care manufacturers targeting anti-aging serum formulations, driven by clinical substantiation requirements for functional cosmetic claims.
- Enzyme Inhibitors:Peptides blocking tyrosinase or MMP activity to address hyperpigmentation and collagen degradation. Beauty brands targeting diverse skin phototypes in India and Brazil are absorbing expanding volumes as melanin-modulating claims gain regulatory scrutiny.
- Carrier Peptides:Metal-ion chelating sequences enhancing mineral bioavailability in topical applications.
- Neurotransmitter Peptides:Botulinum-toxin mimics modulating SNARE complex formation for wrinkle reduction.
- Matrix Peptides:Structural proteins supporting tissue repair and barrier function in dermal matrices.
By volume, signal peptides lead. By growth pace, enzyme inhibitors are ahead.
Application:
Cost tier stratification separates premium clinical-grade applications from mass-market cosmetic positioning.
- Anti-Aging:Collagen-stimulating and elastin-preserving peptide formulations targeting dermal rejuvenation. South Korean beauty conglomerates and Chinese domestic skincare brands are the dominant demand centers, absorbing volumes for both premium and masstige product lines.
- Skin Lightening:Tyrosinase-inhibiting peptides for melanin suppression across Fitzpatrick skin types. Regulatory restrictions on hydroquinone alternatives in Europe and Asia are redirecting formulation investment toward peptide-based depigmentation agents.
- Wrinkle Reduction:Neurotransmitter-modulating peptides for expression line mitigation.
- Moisturizing:Barrier-supporting peptides enhancing natural moisturizing factor production.
- Hair Care:Follicle-stimulating sequences for scalp health and growth promotion.
Anti-aging commands the largest revenue pool. Skin lightening is climbing the fastest.
End User:
Customer type determines order frequency, with personal care manufacturers running continuous procurement versus project-based laboratory purchasing.
- Personal Care Manufacturers:Multinational and regional beauty brands integrating peptides into finished formulations. Procurement concentrates among South Korean chaebol-affiliated beauty groups and China's emerging domestic skincare champions, with REACH-compliant documentation now mandatory for European market access.
- Dermatology Clinics:Medical aesthetic practices dispensing peptide-enhanced topical protocols.
- Beauty Salons:Professional treatment providers utilizing peptide-infused professional-grade products.
- Cosmetic Laboratories:Third-party formulators and contract manufacturers developing custom peptide blends.
Personal care manufacturers dominate volume. Dermatology clinics are gaining share fastest.
Technology:
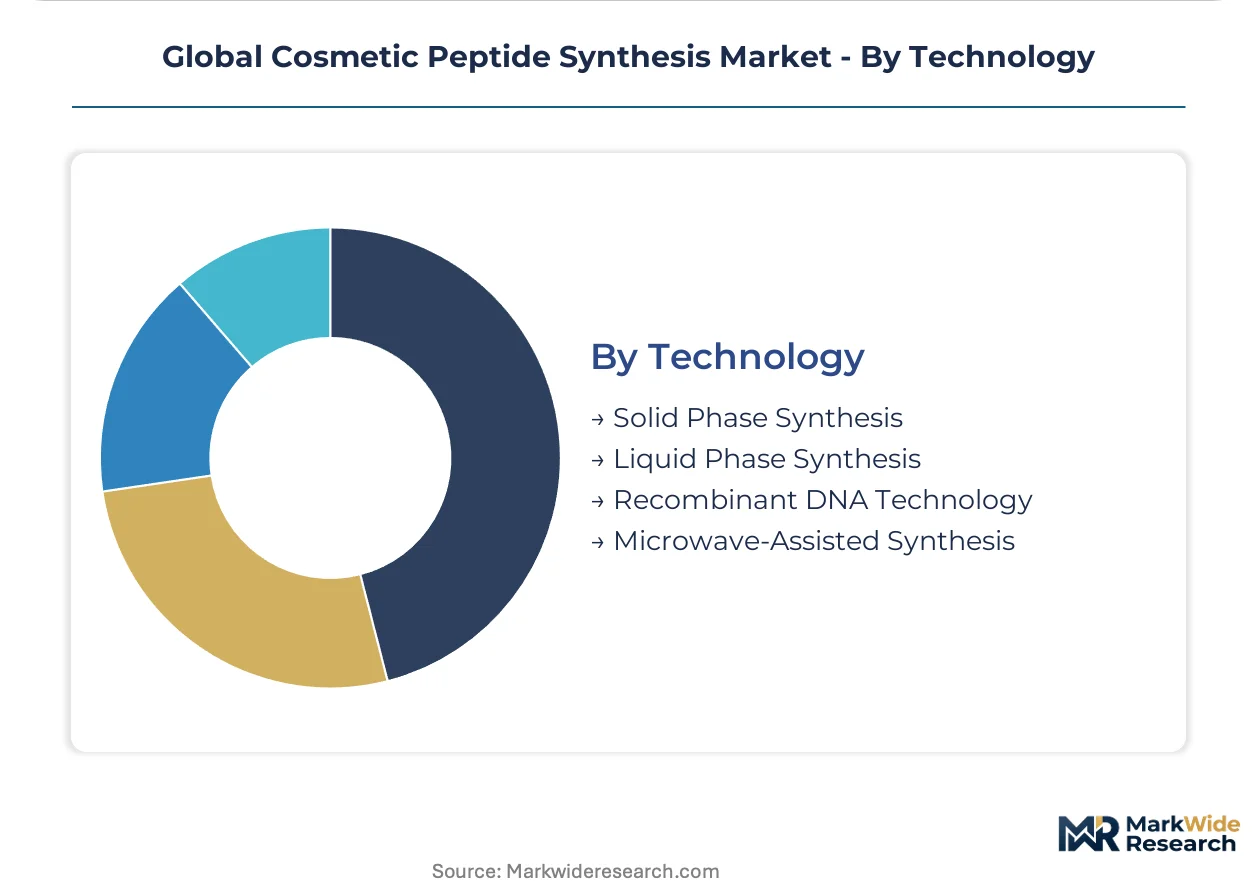
Supply concentration in Swiss and German specialist facilities favors solid-phase and recombinant platforms over emerging microwave methods.
- Solid Phase Synthesis:Automated resin-based peptide assembly enabling high-throughput cosmetic-grade production. Bachem Holding AG and specialized Swiss manufacturers anchor capacity, serving multinational brands with cGMP-compliant batch documentation.
- Microwave-Assisted Synthesis:Electromagnetic heating accelerating coupling reactions and reducing solvent consumption. Dutch and Swiss mid-scale manufacturers are deploying these systems to compress development timelines for boutique beauty brands.
- Liquid Phase Synthesis:Solution-phase chemistry for shorter peptide sequences and fragment condensation.
- Recombinant DNA Technology:Microbial expression systems for longer peptide chains and complex post-translational modifications.
Solid phase synthesis leads by installed capacity. Microwave-assisted methods are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Personal care manufacturers in South Korea and China absorb the largest peptide volumes, while Swiss and German suppliers anchor high-purity production capacity. Regulatory divergence between REACH, FDA, NMPA, and MFDS frameworks shapes market access patterns across manufacturing clusters.
South Korea
Seoul Capital Area beauty conglomerates drive demand for collagen-stimulating signal peptides in anti-aging serums. MFDS functional cosmetic approval pathways require clinical substantiation documentation that filters smaller suppliers. Busan-Ulsan manufacturing corridors host captive synthesis partnerships between chaebol-affiliated brands and specialized peptide producers.
China
Domestic skincare champions in Shanghai and Hangzhou scale peptide procurement for masstige and premium product lines. NMPA cosmetic ingredient filing mandates toxicological dossiers that elevate compliance costs for foreign suppliers. Yangtze River Delta biotech parks attract joint ventures between local beauty groups and European synthesis specialists.
Switzerland
Basel-region chemical conglomerates and specialized manufacturers anchor cGMP-compliant peptide API production for multinational personal care brands. Swissmedic oversight and REACH alignment position Swiss facilities as preferred suppliers for documentation-intensive European markets. Zurich-area automation specialists deploy microwave-assisted synthesis platforms for boutique beauty brand clients.
United States
New Jersey and California-based personal care manufacturers integrate peptides into clinical-positioned anti-aging formulations. FDA Modernization of Cosmetics Regulation Act requirements for safety substantiation concentrate procurement around dossier-capable suppliers. Greater Boston biotech corridors develop recombinant peptide expression systems competing with chemical synthesis methods.
Germany
Rhineland chemical clusters supply protected amino acid building blocks and synthesis equipment to cosmetic peptide manufacturers worldwide. ECHA REACH enforcement and EU Green Deal sustainability mandates favor suppliers with solvent-reduction credentials and renewable feedstock integration. Bavaria-based mid-scale manufacturers deploy flow chemistry platforms for rapid custom sequence development.
Global Cosmetic Peptide Synthesis Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply tiers. Fragrance-to-actives conglomerates and pharmaceutical-grade peptide specialists dominate premium procurement relationships with multinational brands. Three archetypes define competitive positioning: integrated beauty-ingredient conglomerates with captive R&D pipelines; Swiss and German cGMP-compliant synthesis specialists; and biotechnology platforms leveraging microbial expression systems. Capacity expansion in automated solid-phase synthesis and strategic partnerships for multi-jurisdictional regulatory dossiers represent the dominant competitive moves.
Among integrated ingredient conglomerates, Givaudan SA exemplifies the fragrance-to-actives pipeline archetype, while Bachem Holding AG anchors the Swiss specialist manufacturing tier. Lonza Group AG occupies a position representing biotechnology-driven recombinant peptide production. These three entities collectively illustrate the competitive spectrum from chemical synthesis through biological expression, each sitting within distinct capability domains that shape supplier selection criteria for personal care manufacturers.
| Leading Market Players |
|---|
| Givaudan SA (Active Beauty) |
| Bachem Holding AG |
| BASF SE |
| Lonza Group AG |
| PolyPeptide Group |
| Croda International plc (Sederma) |
| DSM-Firmenich (Pentapharm) |
| Evonik Industries |
| Symrise AG |
| Others |
Supply & Pricing Matrix
Basel-region cGMP facilities anchor global high-purity peptide capacity, concentrating pricing leverage among Swiss and German specialists while compressing margin headroom for smaller synthesis providers. This geographic concentration of certified manufacturing infrastructure enables incumbent suppliers to command premium positioning for REACH-compliant documentation.
Pricing Analysis
Cost-plus contracts indexed to protected amino acid feedstock costs dominate procurement relationships between peptide manufacturers and multinational personal care brands. Pricing stratifies across cGMP-certified premium tiers, REACH-aligned standard tiers, and non-certified economy tiers based on documentation depth and batch certification level. Cost compression in the economy tier is intensifying because Chinese domestic skincare brands are scaling volume procurement of cosmetic-grade peptides without toxicological dossier requirements. Personal care manufacturers in South Korea and China exhibit the highest price sensitivity due to volume procurement pressures, while European boutique beauty brands show the least sensitivity given regulatory compliance mandates.
Supply Chain Analysis
Tariff exposure between Switzerland and China dominates supply chain risk planning for peptide manufacturers serving dual-market strategies. Production gravity centers on Switzerland, Germany, and China, with Swiss and German facilities supplying high-purity APIs and Chinese manufacturers scaling cosmetic-grade volume output. Feedstock supply draws from Rhineland chemical clusters for protected amino acid building blocks and Dutch automation specialists for synthesis equipment. Single-source vulnerability concentrates in Fmoc-protected amino acid derivatives and specialized solid-phase resins. Distribution runs through direct formulation partnerships in Asia-Pacific markets and distributor-mediated channels in European and North American territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated synthesis platforms are reconfiguring this market toward platform-economics dynamics, where interoperability between peptide libraries and formulation databases determines competitive positioning. Direct API-to-brand relationships in Seoul and Shanghai are displacing traditional distributor hierarchies.
For Market Incumbents: Insulate cGMP-certified capacity through backward integration into protected amino acid production and captive supply of critical Fmoc building blocks. Lonza's microbial expression systems and Bachem's solid-phase infrastructure represent substitutable threats that demand continuous automation investment to defend process economics. Certification depth in REACH and FDA dossier capabilities remains the priority lever for preferred supplier status with multinational brands. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated domestic skincare sector, where peptide adoption lags Chinese and South Korean penetration rates by several years. Microwave-assisted synthesis platforms offer capital-efficient entry with solvent-reduction credentials that align with EU Green Deal procurement preferences. Partner with regional beauty conglomerates for captive synthesis relationships rather than competing for spot market volumes. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors synthesis-automation specialists with regulatory dossier capabilities over commodity peptide manufacturers. The five-to-ten year viability window rewards platforms with multi-jurisdictional compliance infrastructure across REACH, FDA, NMPA, and MFDS frameworks. Target acquisition archetypes include Dutch and Swiss mid-scale manufacturers deploying flow chemistry platforms. The signal to watch is consolidation momentum among South Korean chaebol-affiliated beauty groups establishing equity stakes in specialized peptide producers.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Solid-Phase Capacity Expansion | Compresses cycle times for Bachem and Givaudan while tightening batch consistency for multinational brands. |
| REACH Dossier Investment | Filters smaller suppliers from European premium supply chains and secures preferred status with personal care manufacturers. |
| Microwave-Assisted Synthesis Deployment | Reduces solvent consumption for Dutch mid-scale manufacturers serving boutique beauty brand clients. |
| Direct Formulation Partnership | Displaces distributor channels in Seoul and Shanghai manufacturing corridors for chaebol-affiliated brands. |
| Recombinant Expression Platform Development | Extends Lonza's reach into longer peptide chains with complex post-translational modifications. |
Research Methodology
Desk research of customs trade data, ECHA REACH registration filings, and SEC 10-K disclosures preceded structured interviews with peptide synthesis plant managers, personal care manufacturer procurement leads, and regulatory affairs directors at multinational beauty brands. Primary fieldwork combined telephone interviews with synthesis specialists and formulation chemists alongside secondary validation against NMPA cosmetic ingredient filings and MFDS functional cosmetic approval records. Bottom-up volume estimates from individual facility capacities were triangulated against top-down demand projections from personal care manufacturer procurement patterns.
Forecast assumptions held regulatory timelines and technology adoption curves fixed while varying peptide incorporation rates across anti-aging and skin lightening application segments. The analytical framework modeled product type, synthesis technology, application category, and geographic manufacturing cluster dimensions across the analysis window. CAGRs were derived from compound growth trajectory fitting to bottom-up capacity expansion schedules and top-down brand formulation pipeline disclosures. Protected amino acid cost volatility and REACH documentation burden escalation served as key forecast sensitivity inputs.
Stress conditions across amino acid feedstock price bands, regulatory enforcement intensity, and synthesis technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about South Korean and Chinese demand concentration and Swiss-German supply capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market