
 Gemstone Cosmetics Powder Market | 2026-2036
Gemstone Cosmetics Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Gemstone Cosmetics Powder Market Foresight
Skilled mineral formulators with gemological expertise is unwinding supply constraints that previously limited batch consistency in gemstone-derived pigments. L'Oréal S.A. leverages integrated pigment sourcing networks across multiple continents to secure raw material streams. Estée Lauder Companies Inc. anchors its prestige portfolio through controlled distribution in high-end department stores and dedicated e-commerce platforms. Shiseido Company Limited specializes in micronization technologies that yield sub-15-micron particle sizes for superior skin adhesion.
Gemstone cosmetics powder comprises finely milled crystalline minerals—predominantly iron oxides, mica substrates, and semi-precious stone derivatives—processed to cosmetic-grade purity for topical application, with particle size distribution typically controlled between 5 and 25 microns to achieve blendability without occluding pores. Loose powder formulations dominate volume consumption among professional makeup artists who prioritize customizable coverage and hygienic single-use dispensing, while compact powder variants capture higher margin pools through convenience-driven retail consumer adoption. Diamond and sapphire variants lead the gemstone type hierarchy due to established consumer perception of luminosity and hardness-associated durability, though amethyst and citrine infusions are gaining traction in wellness-positioned product lines.
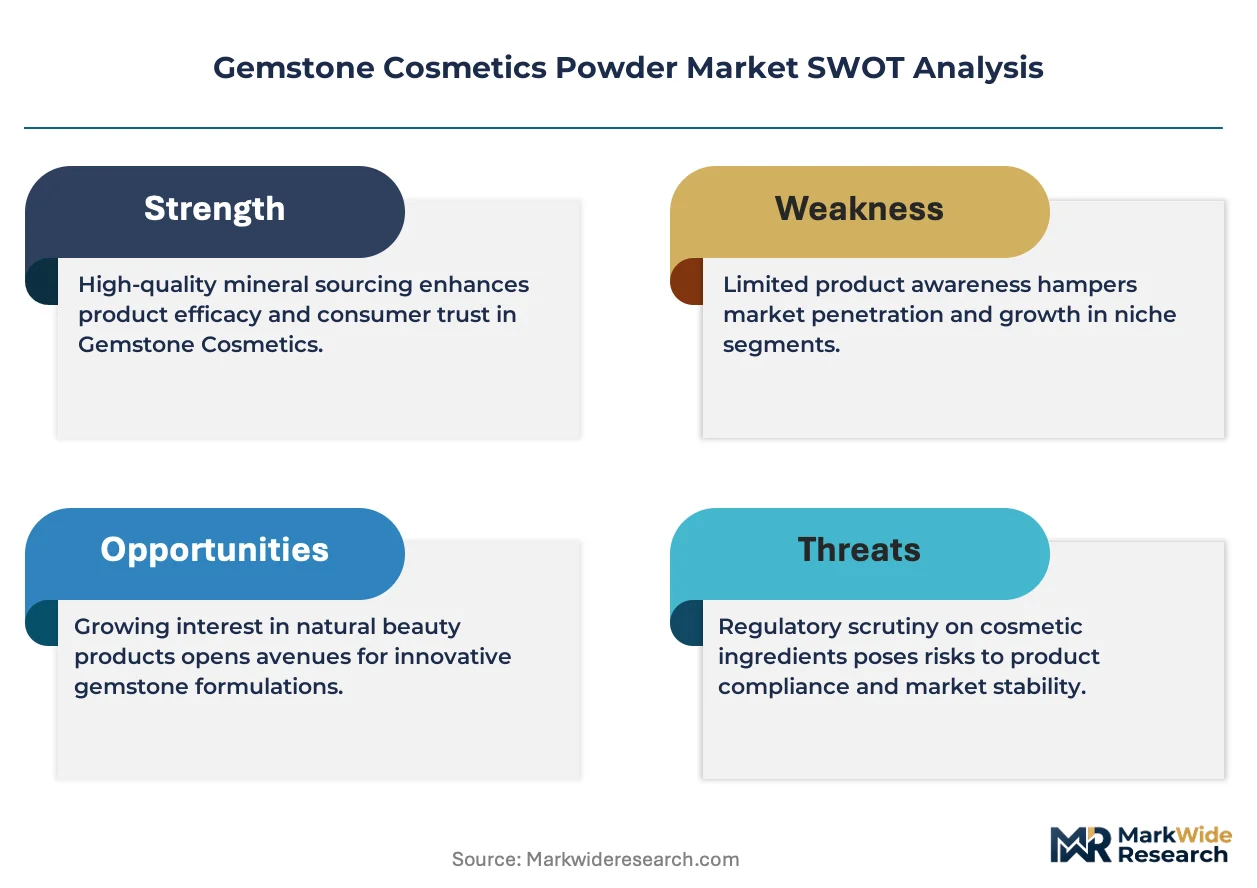
FDA cosmetic labeling requirements and the EU REACH framework govern heavy metal thresholds and nanoparticle disclosure, compelling reformulation investments that favor suppliers with in-house analytical laboratories. The EU Green Deal's chemical sustainability roadmap is tightening upstream sourcing audits for mica and gemstone feedstocks. Stakeholders must monitor evolving clean beauty certification standards from third-party validators and assess whether captive mineral processing capabilities or external specialty supplier partnerships offer superior compliance economics.
Market Dynamics
REACH compliance in the European Union and clean beauty certification shifts in the United States are forcing reformulation investments that favor suppliers with captive mineral processing capabilities and in-house analytical laboratories.
Growth Catalysts
- EU Green Deal chemical sustainability roadmap:Tightening upstream sourcing audits for mica and gemstone feedstocks are compelling premium brands to verify ethical mineral provenance.
- Micronization technology advancement:Sub-15-micron particle size achievement enables superior skin adhesion and drives professional makeup artist channel adoption.
- South Korea:Wellness-positioned product lines featuring amethyst and citrine infusions are expanding addressable consumer segments beyond traditional luminosity-focused buyers.
Market Restraints
- Batch consistency limitations:Skilled mineral formulators with gemological expertise remain scarce, constraining supply reliability for small-batch gemstone-derived pigments.
- Heavy metal threshold compliance:FDA cosmetic labeling requirements and EU REACH framework nanoparticle disclosure rules impose analytical cost burdens on mid-tier suppliers lacking laboratory infrastructure.
- Natural mineral substitutes:Synthetic mica and lab-grown crystal alternatives threaten price premiums for authentic gemstone-derived formulations in mass-market segments.
Strategic Opportunities
- India:Underpenetrated professional makeup artist channels present expansion potential for loose powder formulations with customizable coverage positioning.
- Direct-to-consumer e-commerce platforms:Dedicated digital storefronts bypass department store margin compression while capturing data on shade-matching preferences.
- Convergence of gemological authentication and blockchain traceability:Immutable provenance records differentiate premium offerings amid clean beauty certification proliferation.
Industry Challenges
- Formulation talent scarcity:Cross-disciplinary expertise spanning cosmetic chemistry and crystallography commands premium compensation, compressing R&D budgets.
- Clean beauty certification timeline complexity:Third-party validator standards lack harmonization, forcing redundant testing protocols across EU and US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gemstone Cosmetics Powder Market |
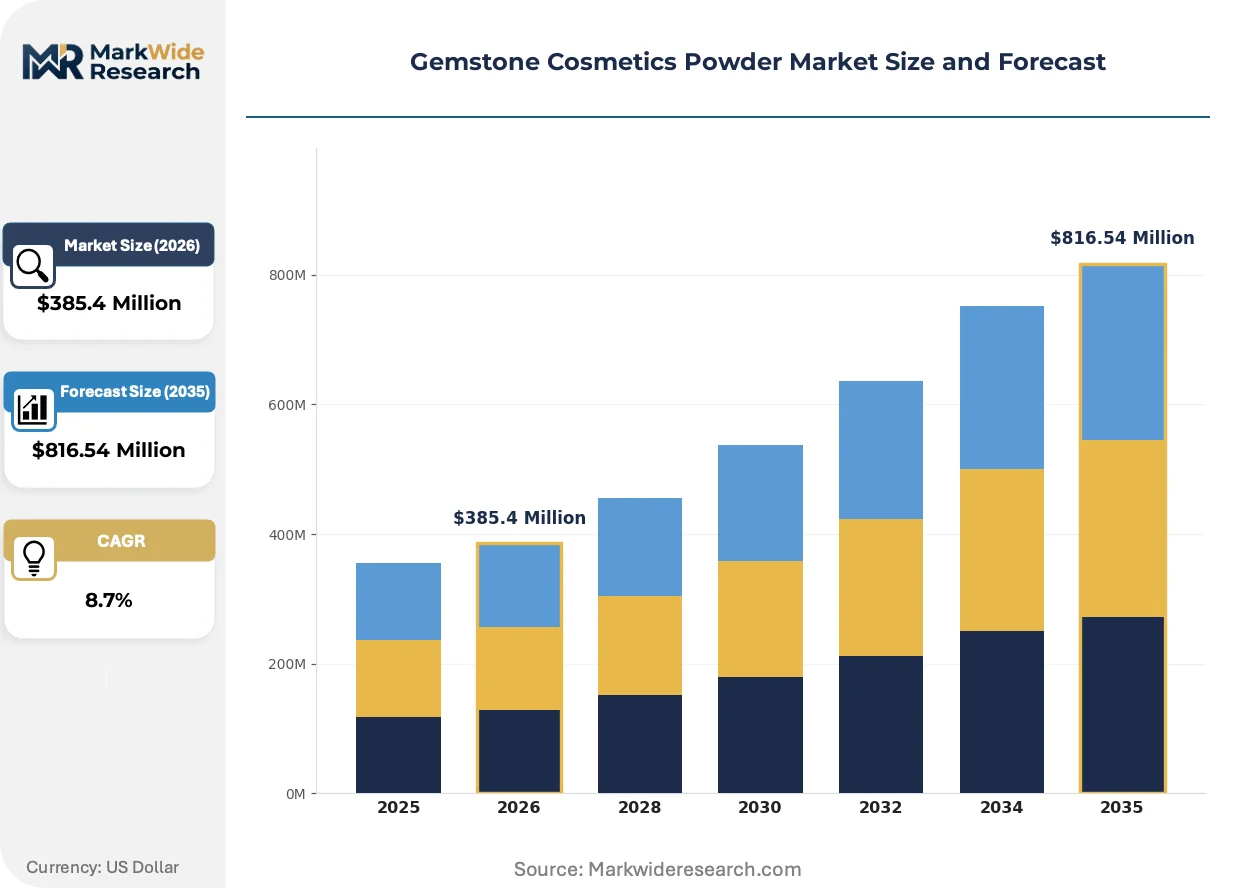
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Loose Powder, Compact Powder, Pressed Powder, Mineral Powder, Finishing Powder Gemstone Type: Diamond, Sapphire, Ruby, Emerald, Amethyst, Citrine Application: Face Makeup, Eye Makeup, Lip Makeup, Body Makeup, Nail Art, Special Effects End User: Professional Makeup Artists, Retail Consumers, Beauty Salons, Cosmetic Manufacturers |
| Companies Covered | L'Oréal S.A., Estée Lauder Companies Inc., Shiseido Company Limited, Jane Iredale, RMS Beauty, Youngblood Mineral Cosmetics, Alima Pure, ILIA Beauty, Lune+Aster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gemstone Cosmetics Powder Market Shifts & Advancements
Active reshaping of the gemstone cosmetics powder sector centers on particle engineering breakthroughs, regulatory disclosure intensification, and channel restructuring that privileges digital-first engagement over traditional retail gatekeepers.
Jet-milling and air-classification systems for crystalline minerals is miniaturizing particle size distribution control to the 5-15 micron range. Prestige beauty brands in France and the United States are accelerating adoption of these processed formulations. This precision is compressing the performance gap between loose and compact powder variants while maintaining pore-non-occluding properties.
REACH framework heavy metal thresholds and nanoparticle disclosure mandates in the European Union are compelling reformulation investments across the supply base. Suppliers without in-house analytical laboratories face exclusion from premium brand vendor lists. Compact powder variants targeting retail consumers exhibit the most intensive compliance response due to higher regulatory scrutiny on leave-on face products.
Professional makeup artists are consolidating purchasing through specialized beauty supply distributors and direct brand relationships, bypassing traditional department store counters. Loose powder formulations dominate this channel shift due to hygienic single-use dispensing requirements. France, the United States, and South Korea display the most pronounced channel restructuring as artist-led education content drives product discovery.
Gemstone Cosmetics Powder Market Segmentation
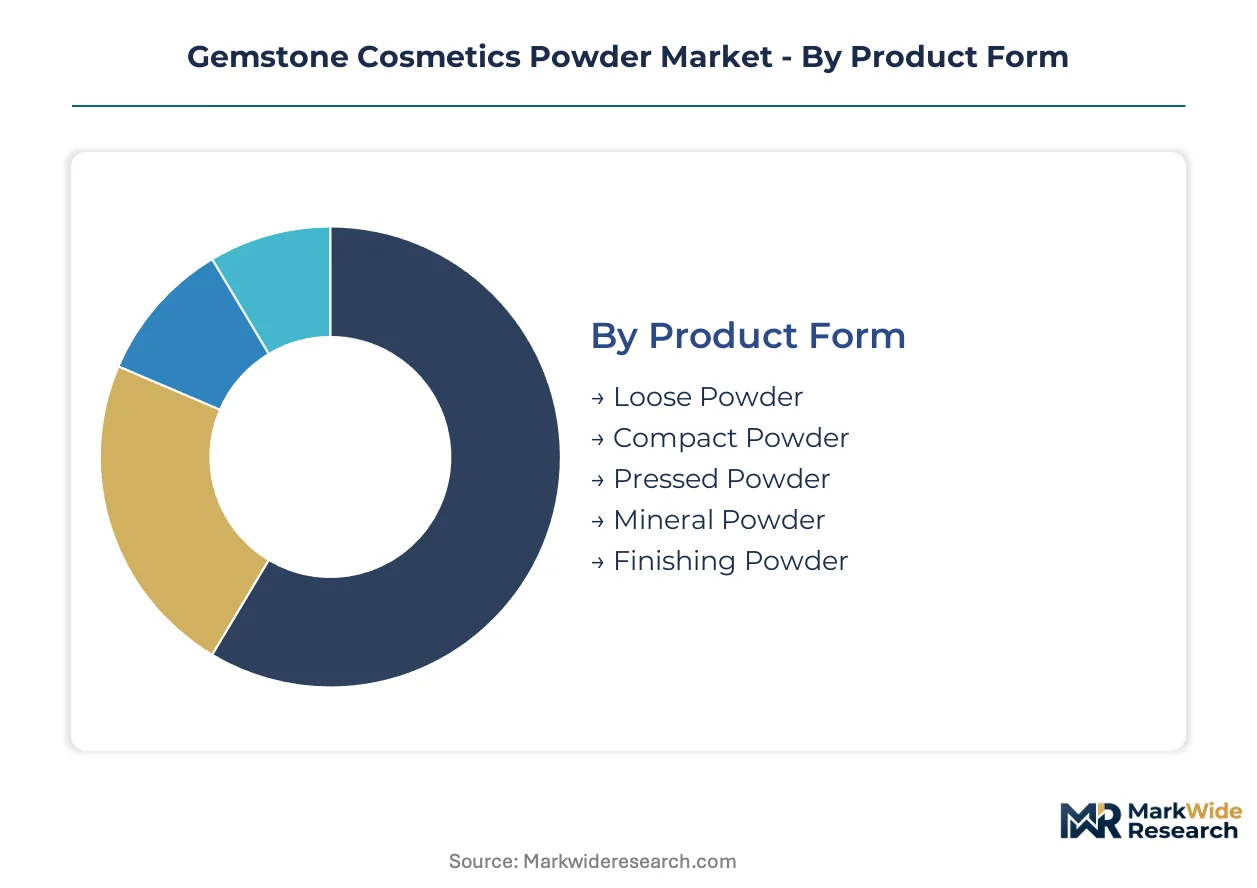
Segmentation in gemstone cosmetics powder reveals how formulation format, mineral composition, and channel economics fragment margin capture across the value chain. Manufacturers must align particle engineering investments with the specific performance demands of professional versus retail channels.
Product Form:
Margin pools concentrate in compact and pressed powder variants where packaging innovation commands premium shelf positioning, while loose powder volumes anchor professional channel penetration.
- Loose Powder:Finely milled crystalline minerals with particle sizes between 5-25 microns enable customizable coverage blending. Demand concentrates among professional makeup artists in France and the United States who prioritize hygienic single-use dispensing protocols and adjustable opacity for editorial and bridal work.
- Compact Powder:Pressed formulations with binding agents achieve convenience-driven retail adoption through portable application. Higher margin pools in South Korea and United States department stores reflect consumer willingness to pay for travel-friendly formats with integrated mirror and applicator systems.
- Pressed Powder:High-compression manufacturing yields durable pans resistant to breakage during shipping. Beauty salons in metropolitan France favor these formulations for client service durability.
- Mineral Powder:Unadulterated iron oxide and mica substrates without synthetic fillers target clean beauty certification requirements. Retail consumers in EU markets drive verification demand for REACH-compliant sourcing documentation.
- Finishing Powder:Translucent micronized silica and diamond dust variants provide light-diffusing final layers. Special effects makeup departments in United States film production clusters represent concentrated professional adoption.
Compact powder holds installed capacity. Mineral powder is rotating up the share rankings.
Gemstone Type:
Volume throughput clusters around diamond and sapphire derivatives where established luminosity perception supports price premiums, while wellness-positioned variants expand addressable segments.
- Diamond:Micronized carbon crystal structures refract light across the visible spectrum for maximum brilliance. Professional channels in the United States and South Korea concentrate demand for high-definition photography and broadcast applications where skin luminosity must withstand intense lighting.
- Sapphire:Corundum-based aluminum oxide delivers hardness-associated durability perceptions alongside subtle blue-white undertones. Prestige beauty brands in France anchor luxury positioning through limited-edition sapphire-infused compacts.
- Ruby:Chromium-doped corundum provides warm pink-red colorants for lip and cheek applications. Clean beauty formulators in the United States leverage ruby for natural pigment alternatives to synthetic dyes.
- Emerald:Beryllium aluminum silicate yields green tones for corrective color balancing. Niche professional use in theatrical makeup segments persists.
- Amethyst:Purple quartz variants align with wellness and crystal healing positioning in South Korean and United States direct-to-consumer channels.
- Citrine:Yellow-to-orange quartz derivatives target energy and vitality marketing narratives. Expanding fastest in wellness-positioned product lines across France and South Korea.
Diamond commands the highest unit economics. Amethyst is gaining share fastest among wellness-positioned entrants.
Application:
Revenue concentration in face makeup reflects the leave-on product classification that triggers stringent regulatory scrutiny and supports premium pricing justification.
- Face Makeup:Foundation, setting powder, and highlighter applications dominate volume consumption. Professional makeup artists in France, the United States, and South Korea drive loose powder adoption for customizable coverage across diverse skin tones and lighting conditions.
- Eye Makeup:Eyeshadow and liner formulations exploit mica substrate shimmer properties. REACH heavy metal thresholds for periorbital use impose analytical cost burdens that favor suppliers with captive laboratory infrastructure.
- Lip Makeup:Ingestible-adjacent applications require elevated purity standards and FDA cosmetic labeling compliance. Ruby and diamond dust variants appear in premium lip toppers.
- Body Makeup:Decolletage and limb applications for editorial and bridal work utilize larger particle sizes for photographic durability.
- Nail Art:Gemstone dust additives in gel and lacquer systems create textured finishes. Beauty salons in South Korea experiment with diamond and sapphire inclusions.
- Special Effects:Theatrical and film production applications demand batch consistency for continuity across shooting schedules. United States production clusters represent concentrated demand.
Face makeup anchors formulation R&D investment. Eye makeup is climbing the fastest as periorbital safety positioning commands premium validation.
End User:
Professional makeup artists generate the highest per-unit margins through specialized distributor relationships, while retail consumer scale justifies compact powder manufacturing investments.
- Professional Makeup Artists:Editorial, bridal, and film specialists prioritize loose powder formats with hygienic dispensing and precise shade matching. France, the United States, and South Korea display pronounced channel consolidation through specialized beauty supply distributors and direct brand relationships.
- Retail Consumers:Convenience-driven adoption of compact and pressed powder variants dominates mass-market and prestige beauty segments. E-commerce platforms in the United States and South Korea capture data on shade-matching preferences that inform formulation development.
- Beauty Salons:Service-oriented establishments favor durable pressed powder pans for repeated client application. Metropolitan France and South Korea urban centers concentrate salon density.
- Cosmetic Manufacturers:Private label and contract manufacturing demand for bulk gemstone-derived pigments supports mid-tier supplier viability. REACH and FDA compliance documentation requirements favor partnerships with analytical laboratory-equipped vendors.
Professional makeup artists hold the premium pricing tier. Retail consumers are expanding most quickly through direct-to-platform digital engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cosmetic labeling requirements anchor the United States as the dominant geography, while EU REACH framework compliance shapes European formulation strategies. Prestige beauty brands concentrate mineral sourcing and micronization investments across France, South Korea, and Japan.
United States
Professional makeup artist channels in Los Angeles and New York drive loose powder volumes for editorial and broadcast applications. FDA heavy metal disclosure rules for leave-on face products compel reformulation investments among mid-tier suppliers. California-based clean beauty certification validators are tightening third-party audit standards for gemstone provenance documentation.
France
Prestige department stores in Paris anchor luxury compact powder positioning for sapphire and diamond-infused formulations. EU REACH nanoparticle disclosure mandates favor suppliers with captive analytical laboratories in the Île-de-France cluster. L'Oréal S.A. leverages integrated pigment sourcing networks across multiple continents to secure raw material streams.
South Korea
Wellness-positioned amethyst and citrine infusions expand addressable consumer segments beyond traditional luminosity buyers in Seoul. MFDS cosmetic safety standards govern periorbital application thresholds for mica-based eye formulations. Beauty salons in Busan-Ulsan experiment with diamond dust nail art additives for textured gel finishes.
Japan
Shiseido Company Limited specializes in sub-15-micron particle micronization technologies from its Kanto region facilities. METI industrial standards for cosmetic-grade mineral purity support premium export positioning. Osaka-based formulators emphasize crystallography expertise for batch consistency in small-batch gemstone pigments.
Germany
EU Green Deal chemical sustainability roadmaps tighten upstream mica sourcing audits for brands operating through Frankfurt and Munich distribution hubs. ECHA compliance documentation requirements favor partnerships with laboratory-equipped specialty suppliers. Bavaria-based analytical service providers are expanding heavy metal testing capacity for REACH-certified feedstocks.
Gemstone Cosmetics Powder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the gemstone cosmetics powder market. Prestige conglomerates with captive mineral processing capabilities capture premium margin pools, while clean beauty specialists compete on certification authenticity and direct-to-consumer engagement. Three archetypes dominate: vertically integrated beauty conglomerates, mineral-specialist independents, and private-label contract manufacturers. Competitive moves center on backward integration into pigment sourcing and portfolio diversification into wellness-positioned gemstone variants.
Within the integrated conglomerate tier, L'Oréal S.A. and Estée Lauder Companies Inc. exemplify scale-driven mineral formulation capabilities spanning multiple continents. Shiseido Company Limited occupies a distinct position emphasizing micronization technology leadership from its Japanese manufacturing base. Among mineral-specialist independents, Jane Iredale and RMS Beauty represent clean beauty certification-focused archetypes with concentrated professional channel relationships.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estée Lauder Companies Inc. |
| Shiseido Company Limited |
| Jane Iredale |
| RMS Beauty |
| Youngblood Mineral Cosmetics |
| Alima Pure |
| ILIA Beauty |
| Lune+Aster |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between prestige beauty conglomerates and mica processors in India lock in both supply access and price visibility, insulating premium brands from spot-market volatility in gemstone feedstocks while compressing margin flexibility for mid-tier competitors lacking comparable procurement scale.
Pricing Analysis
Project-based pricing for small-batch gemstone-derived pigments stratifies across premium, standard, and economy tiers based on certification grade and particle size precision. Price differentiation hinges on REACH compliance documentation and sub-15-micron micronization capability. Pricing pressure stems from synthetic mica substitutes eroding authenticity premiums in mass-market segments. Retail consumers exhibit highest price sensitivity, while professional makeup artists prioritize batch consistency over unit cost.
Supply Chain Analysis
Inventory lead times for ethically sourced mica extend 12-18 months due to ECHA-mandated upstream audits under the EU Green Deal roadmap. Supply concentrates in India, Madagascar, and Brazil for natural mica substrates, with synthetic alternatives emerging from China and Japan. Raw material dependencies center on iron oxide precursors, crystalline silica, and binding agents for pressed formulations. Single-source vulnerability pervades gemological expertise for small-batch pigment processing. Distribution runs through specialized beauty supply distributors and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gemstone cosmetics powder functions as a platform economy where direct-to-consumer storefronts and blockchain traceability systems create interoperability between mineral provenance data and clean beauty certification validators, shifting value capture from traditional retail gatekeepers to vertically integrated brand ecosystems.
For Market Incumbents: Compound defensive positioning through captive micronization facilities in Japan and France, securing sub-15-micron particle engineering capacity that synthetic substitutes cannot replicate. Deepen backward integration into ethically audited mica sourcing networks across India and Madagascar before ECHA compliance documentation becomes a mandatory vendor qualification. Channel control through specialized beauty supply distributors remains essential as professional makeup artists consolidate purchasing power. For New Entrants and Emerging Players: Differentiate on wellness-positioned amethyst and citrine infusions targeting South Korean and United States direct-to-consumer channels, where crystal healing narratives command price premiums beyond luminosity performance. Target India's underpenetrated professional makeup artist segment with loose powder formats emphasizing hygienic single-use dispensing. Deploy gemological authentication paired with blockchain traceability as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mineral-specialist independents with established clean beauty certification and concentrated professional channel relationships, as these assets command scarcity premiums in a market where formulation talent spans cosmetic chemistry and crystallography. Long-term viability favors suppliers with in-house analytical laboratories capable of REACH and FDA compliance documentation. Watch for inflection when EU Green Deal chemical sustainability roadmaps trigger mandatory upstream sourcing audits that exclude laboratory-deficient competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethical Mica Sourcing | Captive supply networks in India and Madagascar satisfy ECHA audit requirements for premium brand vendor lists. |
| Micronization Technology Investment | Sub-15-micron particle capability from Japanese facilities enables superior skin adhesion for professional channels. |
| Blockchain Traceability Implementation | Immutable provenance records differentiate offerings amid proliferating clean beauty certification standards. |
| Direct-to-Consumer Platform Launch | Dedicated digital storefronts bypass department store margin compression while capturing shade-matching preference data. |
| Wellness-Positioned Product Line Extension | Amethyst and citrine infusions expand addressable segments beyond traditional luminosity-focused buyers in Seoul. |
Research Methodology
A spread of perspectives from mineral formulators, gemological consultants, professional makeup artists, and clean beauty certification validators converged on the working assumptions underlying this analysis. Primary interviews with procurement leads at prestige beauty brands, technical R&D directors at micronization facilities, and regulatory affairs specialists navigating REACH and FDA frameworks were cross-referenced against secondary sources including ECHA compliance databases, SEC 10-K filings from listed beauty conglomerates, and customs records tracking mica import flows. Bottom-up triangulation across product-form and gemstone-type segments was reconciled with top-down macroeconomic indicators.
Segmentation dimensions modeled span product form, gemstone type, application category, and end-user archetype across the analysis window. CAGRs were derived through regression analysis of historical volume trajectories and forward projection of regulatory compliance cost burdens. Industry-specific forecast inputs include ECHA enforcement intensity for nanoparticle disclosure and MFDS periorbital safety standard evolution for mica-based eye formulations.
Material uncertainties — regulatory enforcement variance, synthetic substitute performance breakthroughs, and gemological expertise scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding clean beauty certification harmonization timelines and ethical sourcing audit standardization. Revision becomes warranted when EU Green Deal chemical sustainability roadmap implementation crosses thresholds that fundamentally alter upstream sourcing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Hair Lightening Product Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Anti-Acne Serum Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market