
 Global Mineral Cosmetics Market | 2026-2036
Global Mineral Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mineral Cosmetics Market Outlook
Direct-to-consumer digital channels are tilting as specialty beauty retailers lose foot traffic to algorithm-driven discovery platforms. L'Oréal S.A. leverages its dermatological science heritage to anchor credibility in physician-dispensed mineral lines. The Estée Lauder Companies Inc. sustains prestige positioning through limited-edition artist collaborations. Iredale Cosmetics, Inc. specializes in clinical-grade mineral formulations that dominate post-procedure skincare protocols.
Mineral cosmetics comprise pigment and coverage products formulated primarily with inorganic compounds such as titanium dioxide, zinc oxide, iron oxides, and mica, processed through micronization or surface-coating techniques to achieve particle sizes between 5 and 25 microns for skin adhesion and light diffusion. These formulations serve consumers seeking reduced synthetic additive exposure and photoprotection integration. Foundation commands the largest revenue pool among product types due to repeat purchase frequency and shade-matching complexity. Online retail represents the fastest-growing distribution channel, though department stores retain outsized margin capture through consultation-dependent transactions. Bridal makeup applications generate concentrated seasonal demand spikes that strain inventory planning.
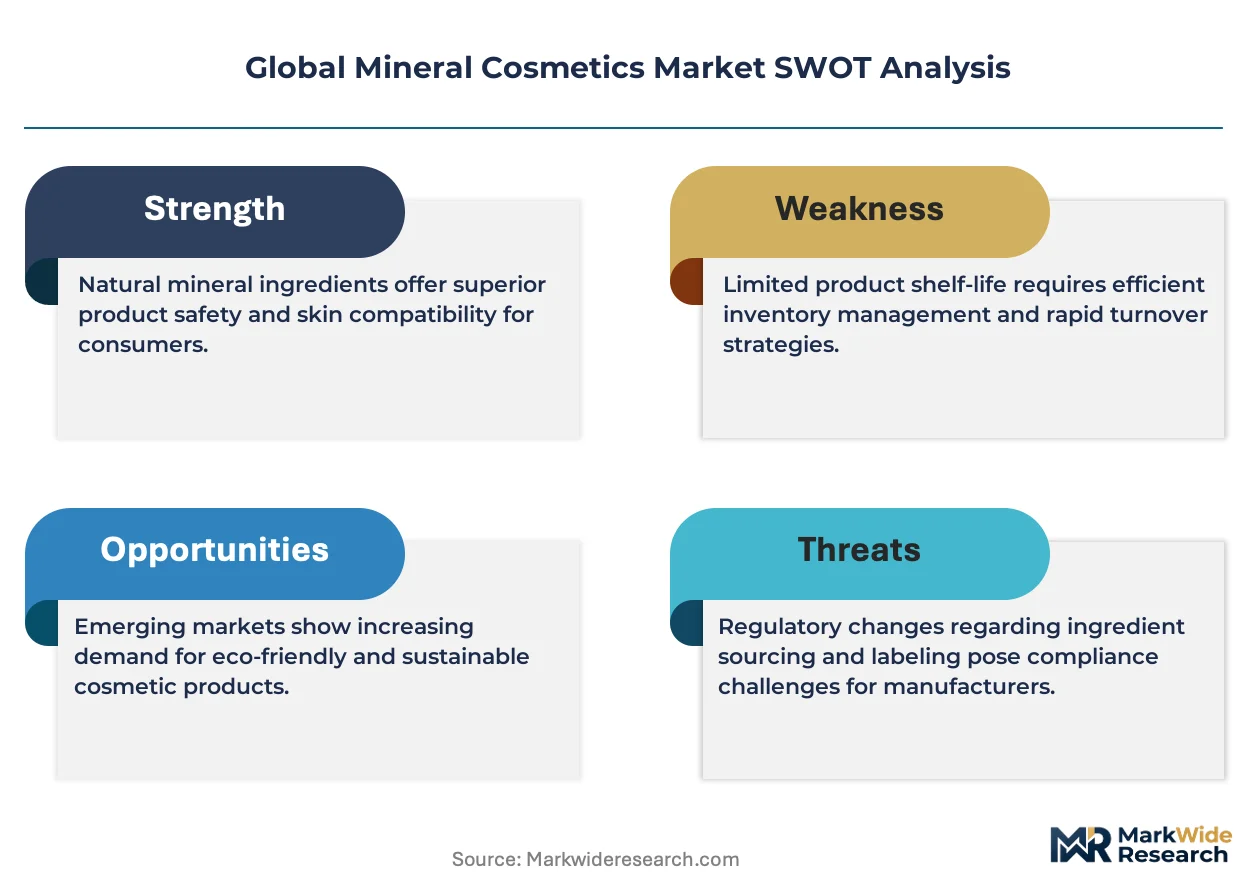
FDA cosmetic labeling requirements and EU REACH substance restrictions jointly elevate compliance costs for cross-border mineral pigment sourcing. ECHA's ongoing microplastic restriction consultations threaten conventional glitter and filler additives, pushing reformulation toward natural mica and boron nitride alternatives. BIS certification mandates in India create additional testing layers for imported mineral powders. Stakeholders must monitor evolving nanomaterial classification debates, as regulatory reclassification of micronized titanium dioxide would force substantial manufacturing process redesigns.
Market Dynamics
Clean beauty mandates are compressing formulation timelines as cosmetic chemists race to replace petroleum-derived binders with bio-based alternatives before EU REACH microplastic restrictions take full effect.
Growth Catalysts
- EU REACH substance transparency:The framework's tightening disclosure requirements for titanium dioxide and zinc oxide are forcing suppliers to upgrade micronization documentation, which paradoxically builds consumer trust in mineral ingredient safety profiles.
- Post-procedure dermatology protocols:Medical spa networks in Germany and South Korea now specify clinical-grade mineral foundation for laser recovery patients, creating institutional procurement channels that bypass traditional retail markup structures.
- Algorithmic discovery platforms:TikTok and Instagram's recommendation engines are surfacing shade-matching tutorials that convert viewers directly to DTC mineral brands, collapsing the traditional editorial-to-retail discovery funnel.
Market Restraints
- Indian BIS certification layers:Imported mineral powders face mandatory testing at designated laboratories, adding 8-12 weeks to shipment timelines and freezing out smaller suppliers lacking dedicated compliance staff.
- Natural mica supply concentration:Jharkhand and Madagascar together control roughly 60% of cosmetic-grade mica extraction, leaving formulators exposed to artisanal mining scrutiny and sudden export moratoriums.
- Silicone substitution limitations:Boron nitride and silica microspheres can replicate some skin-feel properties but fail to match dimethicone's spreadability at equivalent cost, forcing uncomfortable price-positioning tradeoffs.
Strategic Opportunities
- Brazil's ANVISA green channel:The regulator's expedited pathway for naturally-derived cosmetics could position early entrants before Mercosur harmonization spreads EU-equivalent standards across South America.
- Men's grooming mineral adoption:Undertone-matching services originally built for women's complexions are being repurposed for male skin texture patterns, opening incremental volume in previously ignored demographic segments.
- Refillable compact systems:Magnetic pan architectures that separate metal shells from pressed mineral cakes align with France's anti-gaspi regulations and create recurring revenue through cartridge replenishment.
Industry Challenges
- Colorist talent scarcity:Formulators capable of balancing iron oxide blends across Fitzpatrick skin types I-VI command premium compensation, and training pipelines have not kept pace with brand proliferation.
- Legacy ERP integration:Batch-level traceability requirements for REACH compliance clash with decades-old manufacturing execution systems that cannot attribute specific mica lots to finished goods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mineral Cosmetics Market |
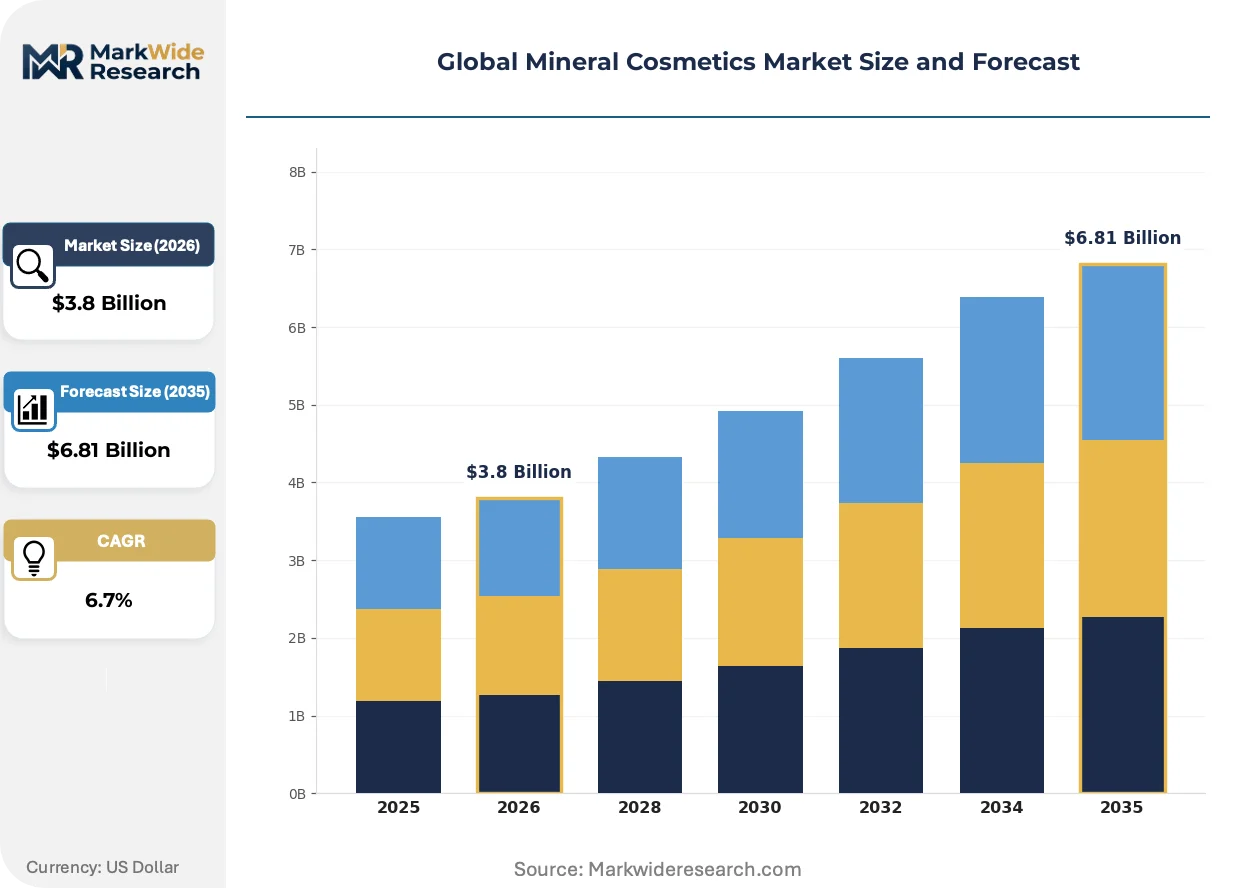
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foundation, Blush, Eyeshadow, Mascara Application: Everyday Use, Bridal Makeup, Professional Makeup, Photography End User: Women, Salons, Makeup Artists, Retail Stores Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | L’Oréal S.A., The Estée Lauder Companies Inc., Glo Skin Beauty, Iredale Cosmetics, Inc., Mineralissima, Shiseido Company, Limited, BASF SE, Revlon, Inc., Cover FX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mineral Cosmetics Market Strategic Shifts
Surface-coating chemistry and particle engineering are converging to solve the historical tradeoff between mineral coverage and skin comfort, unlocking professional makeup artist adoption that previously favored liquid formulations.
Encapsulated zinc oxide with porous silica shells is rendering obsolete the chalky white cast that limited mineral sunscreen acceptance among medium and deep skin tones. Professional makeup artists in Los Angeles and Lagos are switching entire kit inventories within single seasons. The technology is compressing the historical 18-month shade expansion cycle to under six months for responsive brands.
ECHA's ongoing microplastic restriction consultations are forcing glitter and synthetic filler elimination from European formulations by 2026. Manufacturers are accelerating natural mica flake processing and boron nitride synthesis to maintain optical effects. Pressed powder and loose highlighter categories face the steepest reformulation costs, with some suppliers already discontinuing conventional polyethylene-based lines.
Physician-dispensed channels are unbundling consultation fees from product margins as telemedicine platforms enable asynchronous shade matching. Dermatology practices in Seoul and São Paulo now ship mineral samples ahead of virtual appointments, converting diagnostic conversations into automated replenishment subscriptions. This pattern concentrates lifetime value capture in platforms with integrated logistics rather than traditional wholesale-dependent brands.
Global Mineral Cosmetics Market Segmentation
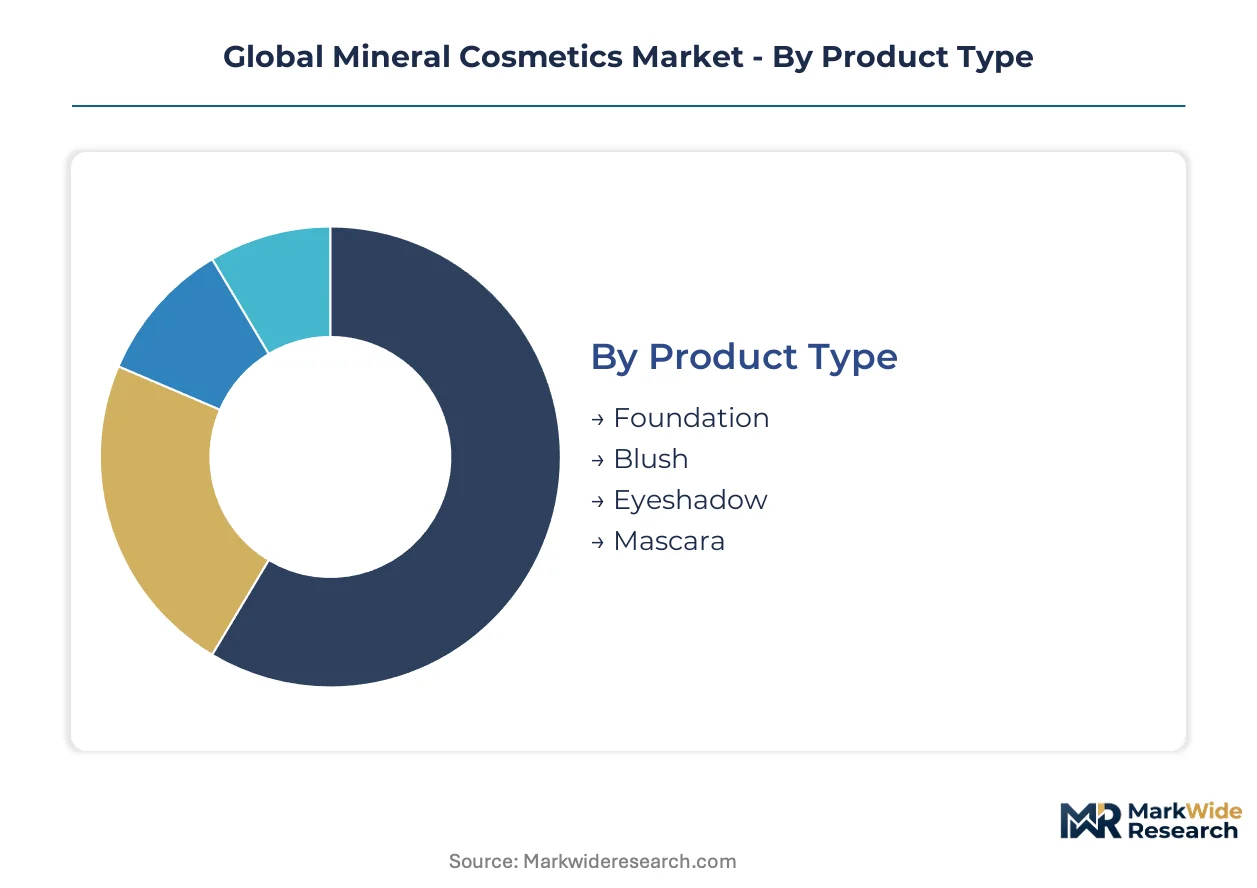
Mineral cosmetics segmentation reflects divergent performance requirements across usage occasions and procurement channels. Formulators must balance micronization grades against finish expectations while distributors navigate channel-specific margin compression.
Product Type:
Cost tier differentiation separates mass-market pressed powders from clinical-grade loose minerals with pharmaceutical documentation.
- Foundation:Liquid and pressed formulations incorporate titanium dioxide and zinc oxide at 15-25% concentration for coverage and photoprotection. Repeat purchase cycles concentrate demand in the United States and Germany, where shade-matching complexity drives subscription replenishment models.
- Blush:Iron oxide blends with mica substrates deliver buildable color saturation through micronized particle distribution. Bridal makeup seasons in South Korea and India generate concentrated procurement spikes that strain mica supply contracts.
- Eyeshadow:Pressed pigment cakes rely on boron nitride and silica microspheres for adhesion without synthetic binders.
- Mascara:Mineral formulations face technical constraints around lash-lengthening fibers, limiting category penetration.
Foundation holds installed capacity. Blush is rotating up the share rankings.
Application:
Volume concentration varies dramatically between daily replenishment and event-driven procurement.
- Everyday Use:Lightweight BB creams and tinted moisturizers with SPF integration dominate morning routine substitution. German consumers prioritize ECHA-compliant ingredient transparency over finish variety.
- Bridal Makeup:Long-wear mineral formulations with flashback-resistant silica finishing command premium positioning. Seasonal demand in India and the United States creates inventory planning challenges for mica-dependent suppliers.
- Professional Makeup:Kit-grade loose minerals with pan-refill compatibility reduce plastic waste for working artists.
- Photography:High-definition finishing powders with light-diffusing particle engineering minimize retouching requirements.
Everyday Use captures baseline volume. Professional Makeup is climbing the fastest as artist education expands.
End User:
Customer type determines packaging format, shade range breadth, and consultation intensity.
- Women:Direct-to-consumer brands with algorithmic shade-matching tools convert trial to loyalty through personalized refill schedules. TikTok discovery patterns in the United States and South Korea accelerate brand switching.
- Salons:Institutional procurement favors bulk loose mineral dispensers with hygienic single-use portioning. German medical spa networks specify clinical-grade documentation for post-procedure applications.
- Makeup Artists:Freelance professionals prioritize magnetic pan systems compatible across multiple brand ecosystems.
- Retail Stores:Counter-based consultation models retain margin capture through shade-matching services that online channels cannot replicate.
Women represent the largest addressable base. Salons are gaining share fastest through institutional contracting.
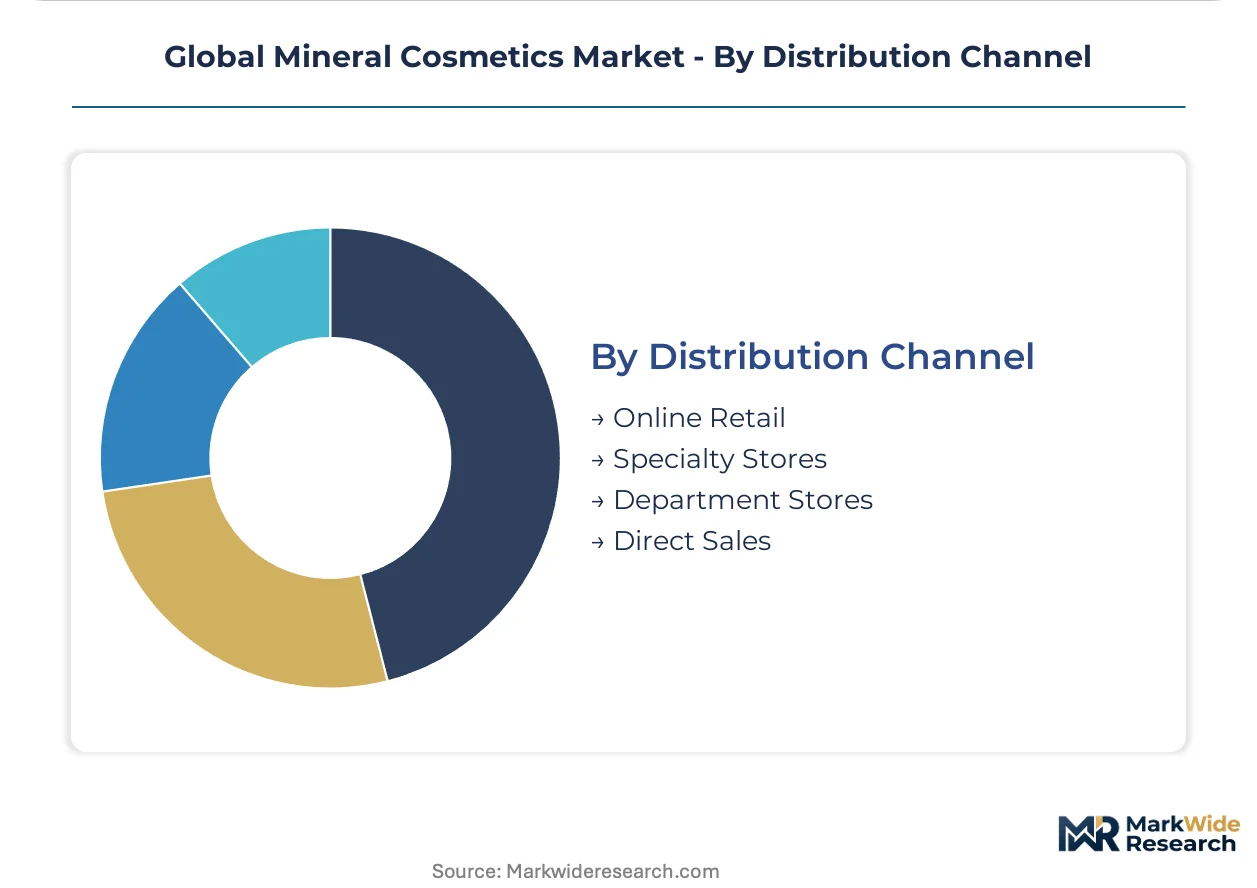
Distribution Channel:
Margin structure and customer acquisition cost vary substantially across channel architecture.
- Online Retail:Algorithmic discovery platforms collapse traditional editorial-to-purchase funnels, with TikTok and Instagram driving direct conversion. South Korean e-commerce integrations with telemedicine shade-matching create subscription lock-in.
- Specialty Stores:Clean beauty retailers face foot traffic erosion as discovery migrates to digital platforms, forcing experiential reinvestment.
- Department Stores:Consultation-dependent transactions retain outsized margin capture through personalized service and exclusive shade launches.
- Direct Sales:Multi-level marketing networks leverage social selling relationships for demographic penetration beyond coastal urban centers.
Department Stores hold legacy margin structures. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's mineral pigment import capacity, while Incheon International Airport's cold-chain logistics anchor South Korea's clinical-grade cosmetic distribution to Asian medical spa networks.
United States
Algorithmic discovery platforms on TikTok and Instagram convert shade-matching tutorials directly to direct-to-consumer mineral brands. FDA cosmetic labeling requirements elevate compliance costs for cross-border titanium dioxide sourcing. Los Angeles-based professional makeup artists now specify encapsulated zinc oxide formulations for medium and deep skin tone coverage.
Germany
Medical spa networks specify clinical-grade mineral foundation for post-laser recovery patients, creating institutional procurement channels. EU REACH substance transparency mandates force suppliers to upgrade micronization documentation for titanium dioxide and zinc oxide. The Rhine-Ruhr industrial cluster hosts specialized boron nitride synthesis facilities serving pressed powder reformulation needs.
South Korea
Telemedicine platforms enable asynchronous shade matching that unbundles consultation fees from product margins. MFDS regulates cosmetic ingredient safety with standards converging toward EU REACH equivalency. Seoul's Gangnam district concentrates dermatology practices shipping mineral samples ahead of virtual appointments.
India
Bridal makeup seasons generate concentrated procurement spikes that strain mica supply contracts. BIS certification mandates add mandatory testing layers for imported mineral powders at designated laboratories. Jharkhand's artisanal mining regions face export scrutiny that threatens formulation input security.
Brazil
Men's grooming mineral adoption accelerates as undertone-matching services repurpose algorithms for male skin texture patterns. ANVISA's expedited green channel for naturally-derived cosmetics positions early entrants before Mercosur harmonization spreads EU-equivalent standards. São Paulo's telemedicine platforms integrate mineral sample logistics into dermatology subscription models.
Global Mineral Cosmetics Market Competitive Environment
On the supply side, the industry is tiered between mass-market conglomerates with dermatological science heritage and clinical-grade specialists with pharmaceutical documentation capabilities. Three strategic archetypes dominate: multinational beauty conglomerates leveraging R&D scale, mineral-pure specialists commanding post-procedure protocols, and ingredient suppliers pivoting into finished formulations. Competitive moves concentrate on algorithmic shade-matching technology licensing and magnetic pan refill system standardization.
Within the clinical-grade specialist tier, Iredale Cosmetics, Inc. exemplifies pharmaceutical-grade mineral formulation positioning, while L'Oréal S.A. occupies a scale-driven archetype leveraging dermatological credibility across physician-dispensed channels. The Estée Lauder Companies Inc. anchors prestige positioning through artist collaboration networks that sustain margin capture in consultation-dependent transactions.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Glo Skin Beauty |
| Iredale Cosmetics, Inc. |
| Mineralissima |
| Shiseido Company, Limited |
| BASF SE |
| Revlon, Inc. |
| Cover FX |
| Others |
Value Chain & Pricing Dynamics
Jharkhand's artisanal mica mining districts concentrate supply leverage for cosmetic-grade flake inputs, translating upstream scarcity into downstream pricing power for clinical-grade mineral foundation tiers. Formulators face compressed margins when export moratoriums interrupt Jharkhand-Madagascar supply corridors, forcing emergency sourcing at premium differentials.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, prestige-positioned, and mass-market levels separates clinical documentation tiers from standard cosmetic filings. Price differentiation hinges on EU REACH micronization certification and dermatologist endorsement density, with prestige tiers capturing margin through physician-dispensed channel control. Pricing pressure stems from silicone substitution costs as boron nitride fails to match dimethicone spreadability at equivalent unit economics. Mass-market pressed powders exhibit highest price sensitivity, while post-procedure clinical lines retain inelastic demand.
Supply Chain Analysis
Tariff exposure between India and European processing hubs dominates supply chain risk calculus for cosmetic-grade mica flake. Raw material sourcing draws from Jharkhand's artisanal districts, Madagascar's industrial mines, and China's processed boron nitride synthesis facilities. Single-source vulnerability concentrates in Jharkhand's export-dependent regions subject to sudden labor scrutiny. Distribution runs through Rotterdam's chemical handling infrastructure for European formulators and Incheon's cold-chain logistics for Asian medical spa networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral cosmetics incumbents face substitution defense against hybrid liquid-mineral formulations that replicate coverage with superior skin-feel properties. The report identifies structural responses across three stakeholder archetypes.
For Market Incumbents: Build regulatory documentation moats through REACH-compliant micronization traceability systems that entrench physician-dispensed channel relationships. Secure captive mica supply through direct Jharkhand sourcing partnerships before export moratoriums harden. Counter hybrid formulation threats by accelerating encapsulated zinc oxide scale-up for medium and deep skin tone coverage. For New Entrants and Emerging Players: Build out men's grooming mineral lines by repurposing undertone-matching algorithms for male skin texture patterns, a demographic segment with minimal incumbent saturation. Target Brazil's ANVISA green channel before Mercosur harmonization spreads EU-equivalent standards. Launch through telemedicine-integrated subscription models that capture lifetime value in Seoul and São Paulo dermatology platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinical-grade specialists with pharmaceutical documentation capabilities over mass-market conglomerates facing silicone substitution cost pressure. Long-term viability centers on magnetic pan refill system standardization and algorithmic shade-matching IP. Monitor ECHA microplastic restriction implementation timelines as inflection signal for natural mica demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Micronization Certification | Entrenches physician-dispensed channel access for clinical-grade foundation lines. |
| Encapsulated Zinc Oxide Scale-Up | Resolves chalky white cast limitations for medium and deep skin tone expansion. |
| Magnetic Pan Refill System Standardization | Aligns with France's anti-gaspi regulations and creates recurring cartridge revenue. |
| Telemedicine Shade-Matching Integration | Captures subscription lifetime value in Seoul and São Paulo dermatology platforms. |
| Jharkhand Direct Sourcing Partnerships | Insulates against artisanal mining scrutiny and sudden export moratoriums. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with cosmetic chemists, dermatology practice managers, medical spa procurement leads, and clean beauty retail buyers; and secondary validation through EU REACH substance databases, ECHA restriction consultation records, FDA cosmetic labeling guidance, and customs trade data for titanium dioxide and zinc oxide imports. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, application occasion, end user archetype, and distribution channel dimensions.
Forecast inputs incorporated mineral pigment substitution elasticities, REACH compliance cost trajectories, and algorithmic discovery platform conversion rates across the analysis window. Segmentation dimensions modeled include product formulation grade, procurement channel architecture, skin tone coverage requirement, and regional regulatory cluster. CAGRs were derived through demand-side adoption curve analysis and supply-side capacity constraint assessment, with specific weighting for bridal makeup seasonality and post-procedure dermatology protocol expansion.
Practitioners should monitor ECHA microplastic restriction finalization, Jharkhand export policy shifts, and encapsulated zinc oxide patent expirations for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market