
 Anti-Wrinkle Products Market | 2026-2036
Anti-Wrinkle Products Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Wrinkle Products Market Analysis
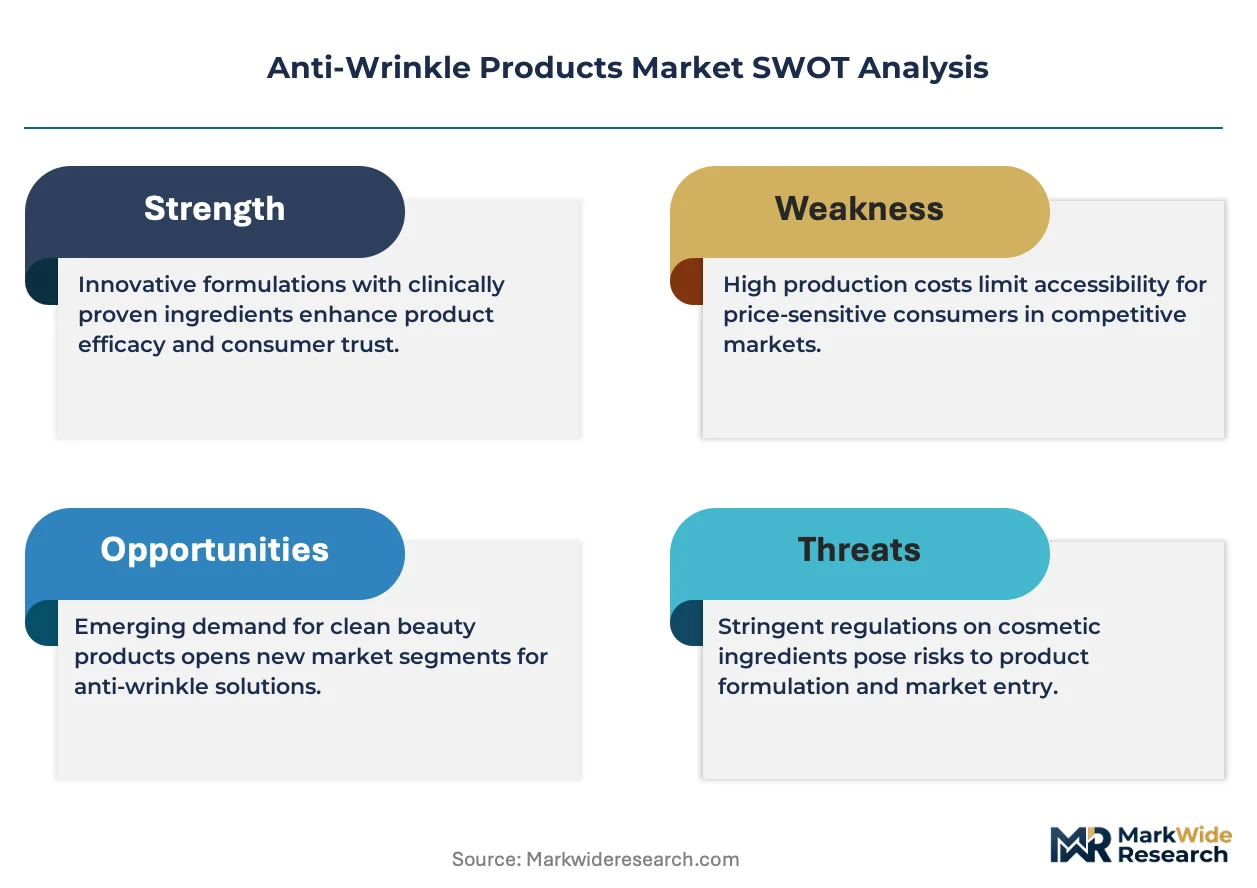
The capital-intensity divergence between mass-market manufacturers and clinical-grade formulators is unwinding as ingredient transparency becomes a baseline cost rather than a premium feature. L'Oréal Groupe leverages its dermatological research infrastructure to sustain patent-protected peptide complexes across multiple price tiers. Galderma S.A. anchors its portfolio in prescription-adjacent retinoid delivery systems that compete directly with over-the-counter alternatives. La Roche-Posay Laboratoire Dermatologique differentiates through thermal spring water formulations that occupy pharmacy-dominant distribution channels in Europe.
Anti-wrinkle products comprise topical formulations engineered with bioactive concentrations of retinoids, peptides, or hyaluronic acid matrices designed to modulate collagen synthesis and transepidermal water loss in photoaged skin. These products function primarily as prophylactic and corrective interventions within consumer dermatology and professional aesthetic medicine. Serums command concentrated margin pools due to higher active-ingredient payloads and premium positioning, while creams retain volume leadership through broader demographic accessibility. Retinol-based formulations lead the active ingredient dimension despite tolerability challenges, whereas peptide complexes represent the fastest-growing category as consumers seek alternatives to prescription retinoids.
The EU Cosmetics Regulation and REACH framework mandate exhaustive safety dossiers for new active ingredients, extending development timelines and favoring incumbents with established regulatory affairs capacity. The FDA's over-the-counter drug monograph system governs retinoid concentration limits in US formulations, directly constraining product-performance claims and channel strategy. Stakeholders must monitor evolving classification debates around cosmetic-versus-drug boundaries as peptide technologies advance toward pharmacological efficacy thresholds.
Market Dynamics
Ingredient disclosure mandates under EU REACH and FDA monograph systems are compressing development timelines and consolidating regulatory affairs capacity among incumbents with established safety dossier infrastructure.
Growth Catalysts
- Peptide Complex Innovation:Bioengineered signal peptides that modulate collagen synthesis are attracting consumers seeking alternatives to prescription retinoids, expanding the addressable market beyond dermatology clinic channels.
- Dermatology Channel Expansion:Medical spas across the United States are integrating professional-grade retinol protocols into treatment menus, creating pull-through demand for maintenance formulations.
- REACH Compliance Infrastructure:Established formulators with exhaustive safety documentation are capturing shelf space as smaller competitors face extended approval timelines for novel actives.
Market Restraints
- Retinoid Tolerability Ceiling:Concentration limits under FDA over-the-counter drug monographs constrain performance claims and prevent parity with prescription tretinoin efficacy.
- Hyaluronic Acid Feedstock Volatility:Fermentation-derived sodium hyaluronate supply concentrates among Chinese biotech manufacturers, exposing formulators to input cost fluctuations.
- Clinical Validation Burden:Peptide technologies approaching pharmacological efficacy thresholds trigger cosmetic-versus-drug classification debates, delaying commercialization.
Strategic Opportunities
- Pharmacy-Dominant Distribution:Thermal spring water formulations with documented dermatological heritage are securing preferred placement in European pharmacy channels, commanding premium positioning.
- Men's Grooming Penetration:Underpenetrated male demographics in the United States represent expansion potential for gender-neutral serum packaging and marketing.
- Biostimulator Convergence:Injectable poly-L-lactic acid and calcium hydroxylapatite technologies are creating adjacency opportunities for topical maintenance protocols in aesthetic medicine practices.
Industry Challenges
- Formulation Stability Expertise:Retinoid oxidation control and encapsulation engineering require specialized chemist talent that concentrates among legacy dermatological laboratories.
- Multi-Jurisdiction Registration:Divergent safety dossier requirements between FDA, ECHA, and Health Canada extend time-to-market for novel active ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Wrinkle Products Market |
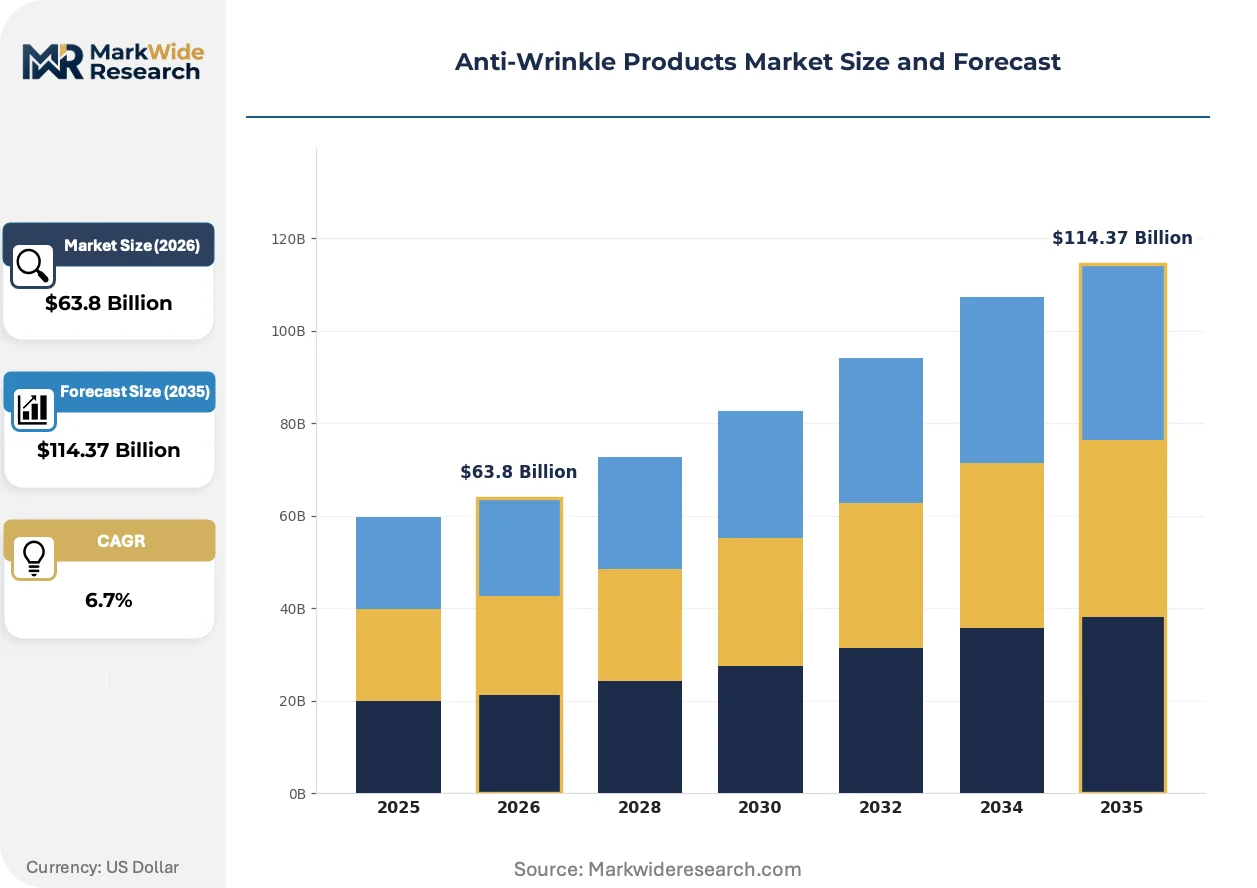
| Market Size in 2026 | $63.8 Billion |
| Market Size in 2035 | $114.37 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Gels, Masks Active Ingredient: Retinol, Peptides, Hyaluronic Acid, Vitamin C Application Area: Face, Neck, Eyes, Forehead Formulation Type: Organic, Synthetic, Herbal, Water-Based |
| Companies Covered | L'Oréal Groupe, Olay, CeraVe, Neutrogena, RoC Skincare, Pond's, La Roche-Posay Laboratoire Dermatologique, REN Clean Skincare, Galderma S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Wrinkle Products Market Emerging Trajectories
Microencapsulation and lipid-delivery technologies are reshaping tolerability profiles and channel economics, enabling professional-grade actives to migrate into direct-to-consumer formats without clinical supervision.
Liposomal retinoid delivery systems are supplanting traditional emulsion bases in premium serum formulations. Dermatology clinics in Germany and South Korea are adopting these technologies to reduce patient irritation incidents and improve protocol adherence. The structural consequence is compression of the efficacy gap between over-the-counter and prescription retinoid categories, forcing repositioning of mid-tier clinical brands.
ECHA's 2024 updates to REACH substance evaluation criteria are extending safety assessment timelines for novel peptide actives. Formulators must now submit chronic dermal toxicity data earlier in development cycles, favoring incumbents with captive toxicology facilities. European mid-market brands are responding by licensing established peptide complexes rather than developing proprietary molecules.
Subscription-based replenishment models are displacing traditional retail purchasing for core skincare regimens. United States consumers aged 35-54 are consolidating purchases through dermatologist-affiliated platforms that bundle professional consultation with automated delivery. This channel shift concentrates customer lifetime value data with platform operators, eroding traditional brand-direct relationships.
Anti-Wrinkle Products Market Segmentation
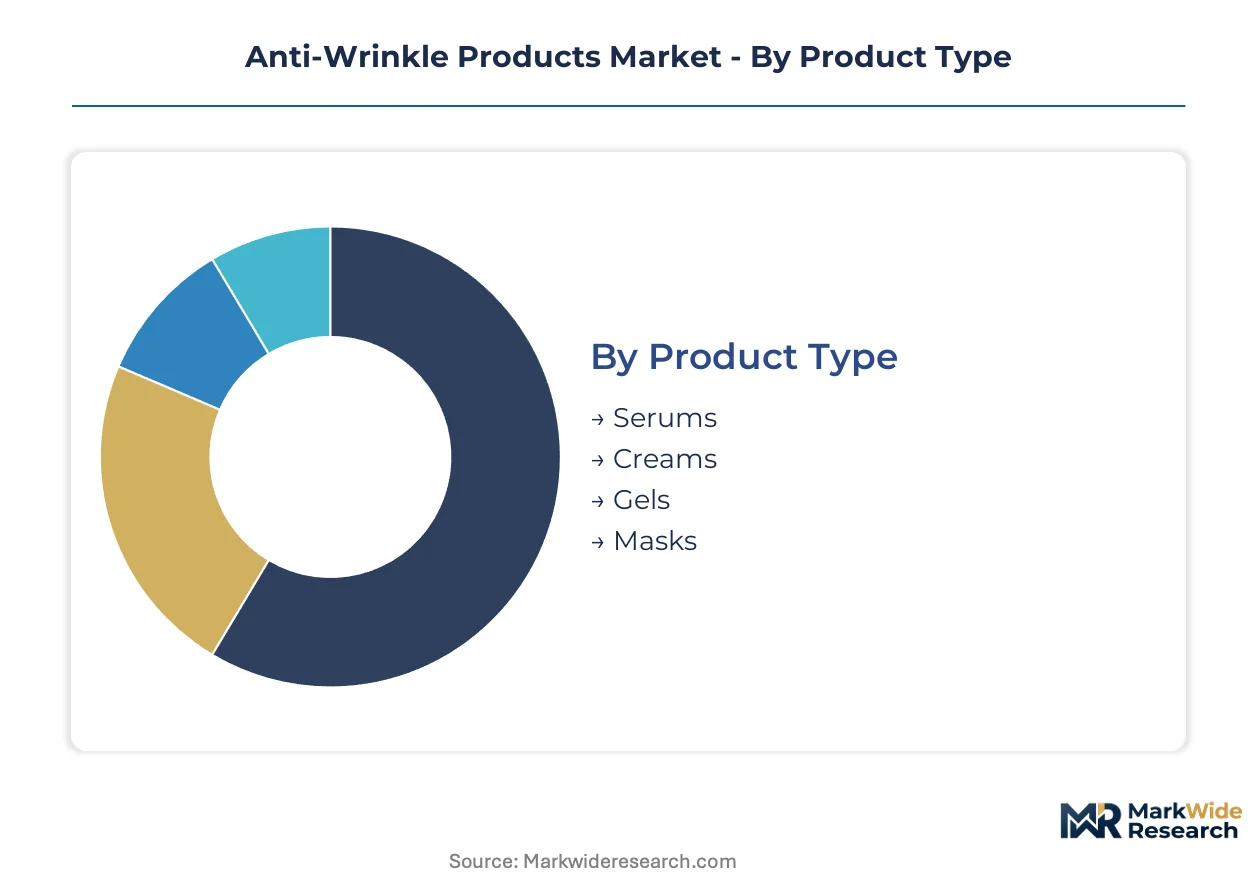
Regulatory classification thresholds fragment the anti-wrinkle landscape into distinct compliance tiers. Formulators must navigate divergent safety dossier requirements across peptide, retinoid, and hyaluronic acid matrices, reshaping competitive positioning within each segment cluster.
Product Type:
FDA monograph concentration limits and EU REACH disclosure mandates create divergent margin structures across delivery formats.
- Serums:High active-ingredient payloads in aqueous or lipid-delivery bases command premium positioning through dermatologist and medical spa channels. Demand concentrates in the United States among consumers aged 35-54 seeking maintenance protocols post-clinical treatment.
- Creams:Emulsion-based formulations with broader tolerability profiles retain volume leadership through mass-market and pharmacy distribution. European pharmacy channels favor thermal spring water cream bases with documented dermatological heritage.
- Gels:Lightweight, fast-absorbing vehicles target oily and combination skin demographics through direct-to-consumer platforms.
- Masks:Occasional-use sheet and rinse-off formats occupy entry-price positioning for trial and travel occasions.
Creams handle the majority of throughput; serums are the fastest mover on share.
Active Ingredient:
Cost tier stratification separates prescription-adjacent retinoids from accessible peptide and antioxidant alternatives.
- Retinol:Vitamin A derivatives modulate collagen synthesis and cellular turnover, constrained by FDA over-the-counter concentration ceilings that prevent parity with prescription tretinoin. Tolerability challenges limit expansion beyond dermatology-supervised protocols.
- Peptides:Bioengineered signal peptides represent the fastest-expanding category as consumers seek alternatives to prescription retinoids. ECHA's 2024 REACH substance evaluation criteria extend safety assessment timelines, favoring incumbents with captive toxicology facilities.
- Hyaluronic Acid:Fermentation-derived sodium hyaluronate matrices address transepidermal water loss in photoaged skin. Supply concentrates among Chinese biotech manufacturers, exposing formulators to input cost volatility.
- Vitamin C:L-ascorbic acid and stabilized derivatives target oxidative stress in daytime regimens, requiring sophisticated encapsulation engineering to prevent degradation.
Retinol anchors revenue concentration despite regulatory constraints; peptides are climbing the fastest on volume contribution.
Application Area:
Customer type differentiation separates professional protocol adjacencies from self-directed maintenance routines.
- Face:Comprehensive anti-aging regimens span multiple active categories and command the highest per-ritual spend through subscription replenishment models.
- Neck:Specialized formulations address thinner, more photo-damaged dermal layers with adjusted retinoid concentrations and enhanced emollient bases.
- Eyes:Low-tolerance orbital formulations require microencapsulated delivery systems and exclude fragrance, driving premium positioning in pharmacy and prestige channels.
- Forehead:Expression-line targeted products compete with injectable neuromodulator maintenance, creating convergence opportunities for topical biostimulator adjacencies.
Face applications absorb the dominant share of formulation output; neck-specific development is gaining momentum fastest.
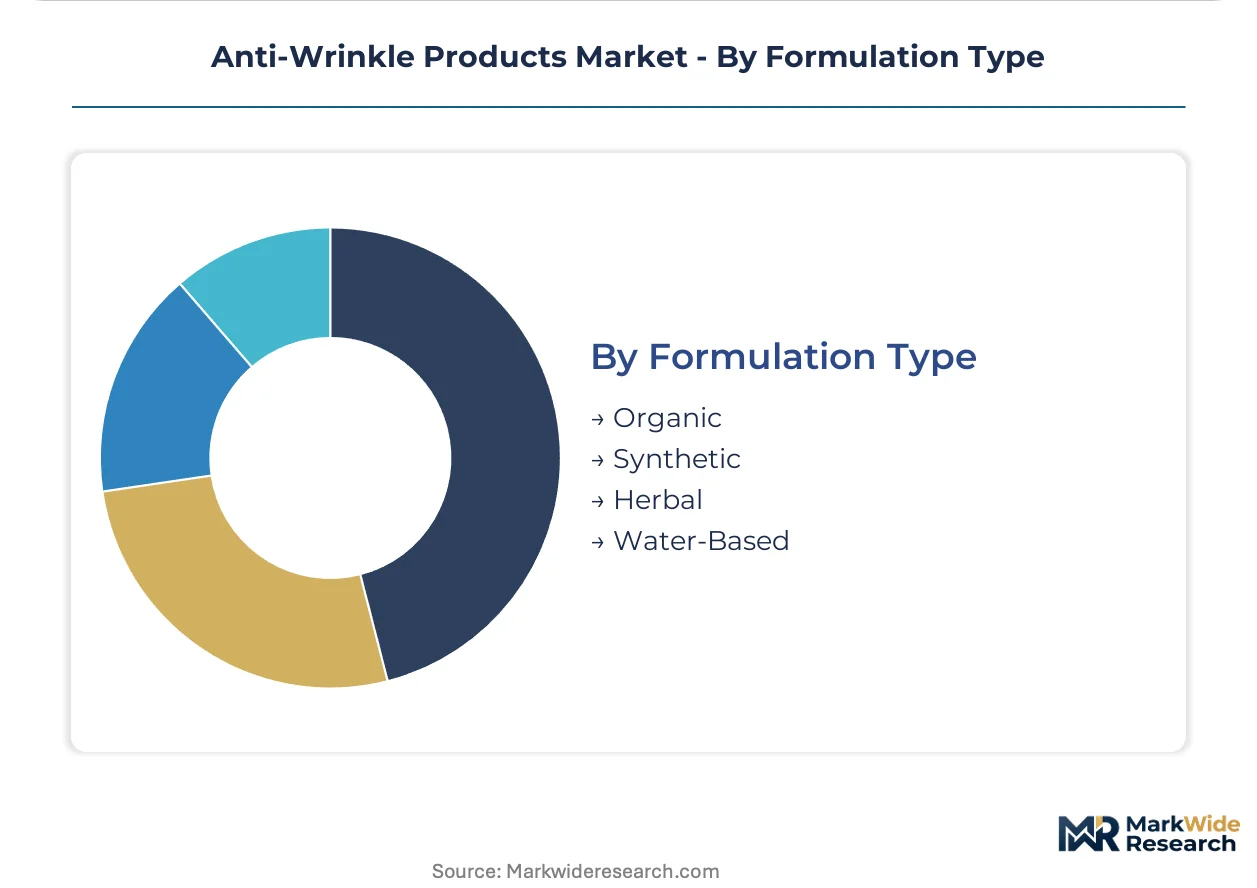
Formulation Type:
Supply concentration of certified organic feedstocks and fermentation-derived actives shapes procurement patterns across origin claims.
- Organic:Certified botanical extracts and cold-pressed carrier oils command shelf-space premiums in natural-specialty retail, constrained by batch-to-batch active variability.
- Synthetic:Laboratory-engineered actives and optimized delivery vehicles enable precise concentration control and extended stability profiles for clinical-grade positioning.
- Herbal:Traditional botanical complexes with documented ethnobotanical use target preference segments in Asian pharmacy and apothecary channels.
- Water-Based:Thermal spring water and purified aqueous bases dominate European pharmacy distribution, leveraging documented mineral content for tolerability claims.
Synthetic formulations carry the largest production volume; organic-certified development is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by substantial margins, while Chinese manufacturing clusters absorb disproportionate hyaluronic acid feedstock demand. Dermatology channel density and regulatory classification stringency create divergent margin structures across national markets.
United States
Consumers aged 35–54 drive premium serum purchases through dermatologist-affiliated subscription platforms. FDA over-the-counter drug monographs constrain retinoid concentration claims and channel positioning. Medical spa density concentrates in Los Angeles, Miami, and New York metropolitan corridors, generating pull-through demand for maintenance formulations.
Germany
Pharmacy-dominant distribution channels favor thermal spring water formulations with documented dermatological heritage. ECHA's 2024 REACH substance evaluation updates extend safety assessment timelines for novel peptide actives. Dermatology clinics in Munich and Düsseldorf adopt liposomal retinoid delivery systems to reduce patient irritation incidents.
China
Fermentation-derived sodium hyaluronate supply concentrates among domestic biotech manufacturers, exposing formulators to input cost volatility. NMPA cosmetic registration requirements mandate exhaustive safety dossiers for new active ingredients. Shanghai and Hangzhou host the dominant peptide synthesis and encapsulation engineering clusters serving regional brands.
South Korea
Advanced microencapsulation capabilities enable professional-grade actives to migrate into direct-to-consumer formats without clinical supervision. MFDS cosmetic regulations govern retinoid concentration limits and performance claim substantiation. Seoul-based dermatology clinics pioneer sheet mask delivery systems for retinol protocols.
France
Thermal spring water heritage brands command preferred placement in European pharmacy channels through documented mineral content tolerability claims. ANSM enforces stringent ingredient disclosure requirements under EU Cosmetics Regulation alignment. Lyon and Paris house specialized toxicology facilities serving incumbent formulators with captive regulatory affairs capacity.
Anti-Wrinkle Products Market Vendor Landscape
Concentration sits with diversified dermatological research conglomerates and prescription-adjacent specialty formulators. The vendor base stratifies across three tiers: legacy beauty conglomerates with captive R&D infrastructure, clinical-grade laboratories anchored in pharmacy channels, and direct-to-consumer challengers leveraging subscription replenishment models. Dominant competitive moves include strategic licensing of established peptide complexes rather than proprietary molecule development, and backward integration into fermentation-derived hyaluronic acid feedstocks.
Among diversified research conglomerates, L'Oréal Groupe exemplifies archetype positioning through dermatological research infrastructure sustaining patent-protected peptide complexes. Galderma S.A. occupies the prescription-adjacent tier, while La Roche-Posay Laboratoire Dermatologique represents pharmacy-channel anchoring through thermal spring water heritage. These three entities collectively illustrate the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| L'Oréal Groupe |
| Olay |
| CeraVe |
| Neutrogena |
| RoC Skincare |
| Pond's |
| La Roche-Posay Laboratoire Dermatologique |
| REN Clean Skincare |
| Galderma S.A. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for fermentation-derived sodium hyaluronate lock in supply access and price visibility for formulators exposed to Chinese biotech manufacturer concentration. These contractual structures insulate incumbent brands from feedstock volatility while compressing margin flexibility for mid-market competitors lacking procurement scale.
Pricing Analysis
The customization-premium spread separates clinical-grade peptide serums from mass-market retinol creams by a factor driven by active-ingredient payload concentration and dermatologist channel certification. Three-tier pricing structure across premium, standard, and economy levels stratifies around FDA monograph compliance tiers and REACH documentation depth. Pricing pressure stems from hyaluronic acid feedstock cost compression as Chinese fermentation capacity expands. Mass-market retailers exhibit highest price sensitivity; medical spa channels demonstrate lowest elasticity due to protocol bundling.
Supply Chain Analysis
Inventory lead times for novel peptide actives have extended following ECHA's 2024 REACH substance evaluation updates, forcing formulators to front-load toxicology documentation. Supply concentrates in China for sodium hyaluronate, South Korea for microencapsulation engineering, and France for thermal spring water extraction. Raw material dependencies include fermentation-derived hyaluronic acid, bioengineered signal peptides, and stabilized retinoid precursors. Single-source vulnerability concentrates in Chinese biotech feedstock manufacturers. Distribution runs through dermatologist-affiliated subscription platforms, European pharmacy networks, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. Exhaustive safety dossier requirements under FDA and REACH frameworks create switching costs that concentrate competitive advantage among incumbents with captive toxicology infrastructure.
For Market Incumbents: Compound regulatory affairs capacity through captive toxicology facility investment in Lyon or Paris clusters to accelerate novel peptide approval timelines. Deepen backward integration into fermentation-derived hyaluronic acid production to neutralize Chinese supply concentration risk. Defend against direct-to-consumer challengers by consolidating dermatologist-affiliated subscription platform relationships.
For New Entrants and Emerging Players: Anchor in underpenetrated male grooming demographics through gender-neutral serum packaging and clinical-performance positioning without fragrance. Target United States medical spa corridor expansion in secondary metropolitan markets beyond Los Angeles, Miami, and New York. Pursue licensing agreements for established peptide complexes rather than proprietary molecule development to circumvent extended REACH assessment timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward clinical-grade laboratories with pharmacy-channel anchoring and documented dermatological heritage across the medium-term viability window. Acquisition target archetype: mid-market formulators with REACH-compliant peptide portfolios and European thermal spring water sourcing rights. Monitor ECHA substance evaluation backlog depth as inflection indicator for competitive timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hyaluronic Acid Feedstock | Captive fermentation capacity insulates formulators from Chinese supply concentration and input cost volatility. |
| Liposomal Retinoid Delivery System Launch | Professional-grade tolerability profiles enable migration into direct-to-consumer channels without clinical supervision. |
| Pharmacy-Dominant Distribution Expansion | Thermal spring water heritage secures preferred placement in European pharmacy channels commanding premium positioning. |
| Peptide Complex Licensing Agreement | Established molecule access circumvents ECHA's extended safety assessment timelines for novel actives. |
| Subscription Replenishment Platform Partnership | Dermatologist-affiliated bundling concentrates customer lifetime value and erodes traditional brand-direct relationships. |
Methodological Framework
Cross-validation between primary interviews with dermatology clinic directors, regulatory affairs leads at cosmetic formulators, medical spa procurement managers, and pharmacy chain category buyers anchors the qualitative findings. Secondary validation draws from FDA over-the-counter drug monograph filings, ECHA REACH substance evaluation databases, NMPA cosmetic registration records, and customs trade data for sodium hyaluronate feedstock flows. Bottom-up demand modeling triangulates against top-down market sizing across product type, active ingredient, application area, and formulation origin claims.
Sensitivity analysis across the projection horizon tests input assumptions including hyaluronic acid feedstock cost trajectories, REACH approval timeline scenarios, and medical spa channel expansion rates. Segmentation dimensions modeled span delivery format, active ingredient category, regional regulatory cluster, and channel archetype. CAGRs derive from triangulated volume and value build-ups incorporating peptide complex adoption curves, retinoid tolerability ceiling constraints, and subscription platform penetration patterns.
Material uncertainties — regulatory reclassification of peptide technologies as pharmacological agents, Chinese biotech manufacturer supply disruptions, FDA monograph concentration limit revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision contingent on these structural triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Minoxidil Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
US Minoxidil Market