
 Hair Gloss Market | 2026-2036
Hair Gloss Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Gloss Market Foresight
REACH is broadening the cost-of-entry calculus for hair gloss manufacturers targeting European distribution. L'Oréal leverages integrated R&D pipelines to navigate complex substance authorization protocols. Wella anchors its competitive stance through specialized professional salon channels that demand batch-level safety documentation.
Hair gloss denotes a surface-coating treatment engineered with refractive index modifiers, typically silicones or natural oils at 2–8% concentration, to enhance light reflection on the cuticle layer while depositing tonal pigment or sealing frizz. The product serves commercial stylists and retail consumers seeking non-permanent aesthetic modification between chemical service intervals. Shine enhancer formulations occupy the mature volume tier, while color-depositing variants capture expanding margin pools as fashion-cycle compression accelerates refresh frequency. Spray forms lead salon backbar deployment for speed of application, though cream formats sustain higher per-unit economics through take-home retail conversion.
FDA cosmetic labeling requirements and EU REACH substance restrictions collectively shape permissible ingredient palettes and claims substantiation. ECHA's ongoing microplastic restriction evaluations are forcing reformulation timelines for synthetic polymer-based gloss systems. Stakeholders must monitor regulatory divergence between the United States and European Union to avoid dual-compliance cost escalation.
Market Dynamics
Professional salon channels are consolidating purchasing power around color-depositing formulations, compressing formulation refresh cycles while forcing manufacturers to navigate divergent regulatory disclosure requirements across distribution geographies.
Growth Catalysts
- Fashion-cycle compression:Social media-driven aesthetic turnover accelerates consumer refresh frequency for tonal adjustments between permanent color services.
- REACH substance authorization protocols:Early compliance investments by integrated manufacturers create defensive moats against smaller competitors lacking batch-level documentation capabilities.
- Brazilian professional service density:Salon backbar penetration in São Paulo and Rio de Janeiro supports premium gloss adoption through stylist education infrastructure.
Market Restraints
- Silicone feedstock volatility:Refinery-linked dimethicone supply exposes margin structures to petrochemical price swings without viable natural oil substitutes at scale.
- ECHA microplastic restriction timelines:Synthetic polymer-based gloss systems face forced reformulation windows that compress R&D amortization periods.
- DIY color kit substitution:At-home semi-permanent colorants capture price-sensitive consumers seeking single-step tonal modification without salon labor costs.
Strategic Opportunities
- South Korean male grooming expansion:Underpenetrated male professional styling services present whitespace for neutral-toned gloss formulations targeting gray blending.
- Clean beauty certification convergence:USDA BioPreferred and EWG Verified standards create premium positioning anchors for silicone-free oil-based systems.
- Direct-to-stylist subscription models:Digital platforms bypass distributor markups while capturing recurring revenue through calibrated color-matching algorithms.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning refractive index engineering and pigment stability commands premium compensation, constraining mid-tier manufacturer hiring pipelines.
- Dual-compliance documentation burden:Simultaneous FDA cosmetic labeling and REACH substance dossier maintenance requires dedicated regulatory affairs headcount that smaller players cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Gloss Market |
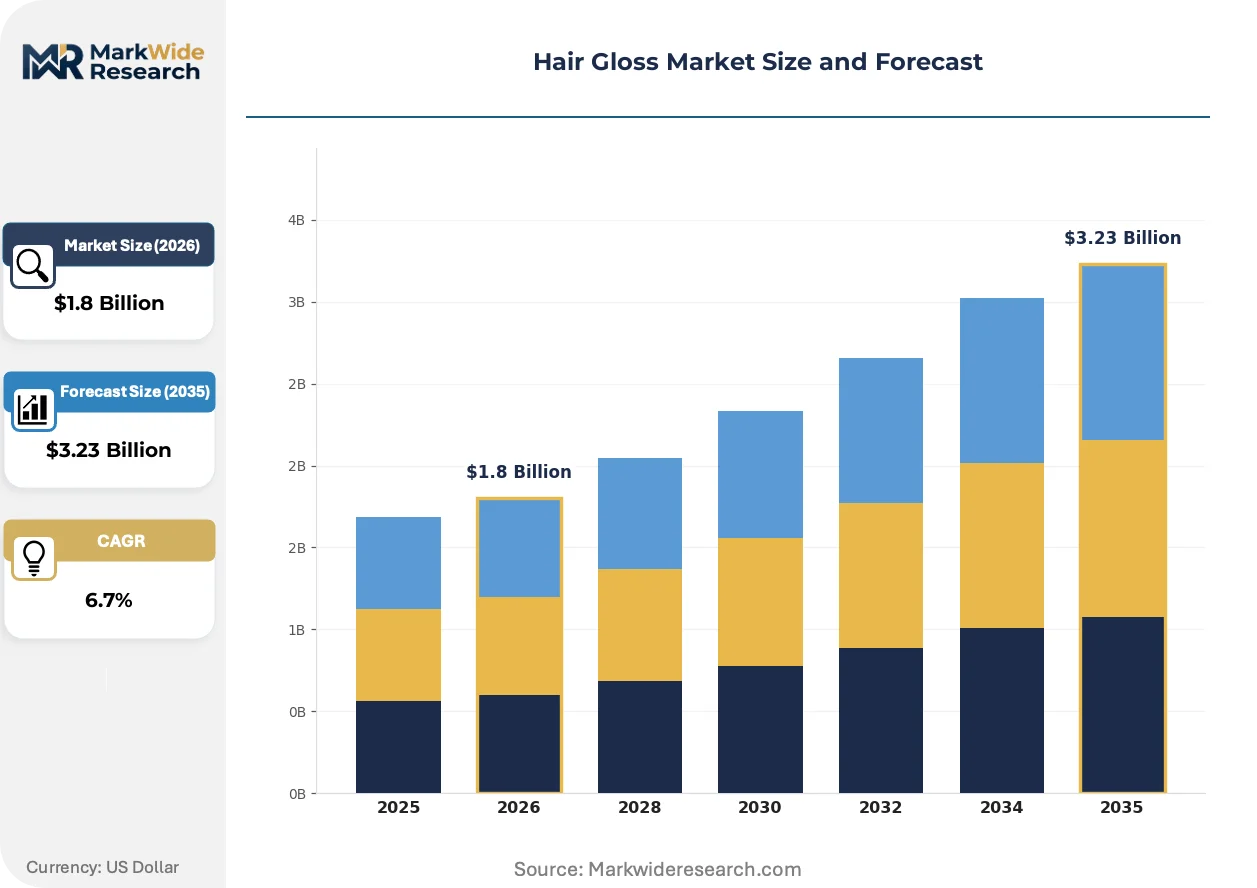
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shine Enhancer, Color Depositing, Smoothing, Moisturizing Form: Cream, Spray, Gel, Liquid Ingredient: Organic, Silicone, Natural Oils, Synthetic Distribution Channel: Online, Supermarkets, Specialty Stores, Salons |
| Companies Covered | Milbon, Wella, Redken, Bumble and bumble, Oribe, L'Oréal, Pravana, Moroccanoil, Shu Uemura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Gloss Market Shifts & Advancements
Refractive index engineering is advancing beyond silicone dependence, while regulatory disclosure requirements and channel consolidation reshape competitive positioning across professional and retail segments.
Plant-derived squalane and hemisqualane blends are overtaking dimethicone as the dominant light-reflecting base in prestige formulations. Clean beauty-oriented salons in Copenhagen and Portland now specify silicone-free backbar standards. This shift is compressing conventional gloss margins while rewarding suppliers with captive fermentation-derived lipid supply chains.
EU REACH microplastic restriction evaluations are forcing synthetic polymer reformulation timelines for European distribution. Manufacturers must substitute acrylate copolymers with natural film-forming alternatives before 2027 enforcement windows. Color-depositing variants face the steepest technical barriers given pigment suspension requirements.
Salon backbar purchasing is consolidating through professional distributor consolidation, displacing fragmented direct manufacturer relationships. Large multi-location chains in Texas and Florida now negotiate master service agreements with formulation houses. This concentration is visible most acutely in sunbelt markets where salon density supports volume-based procurement leverage.
Hair Gloss Market Segmentation
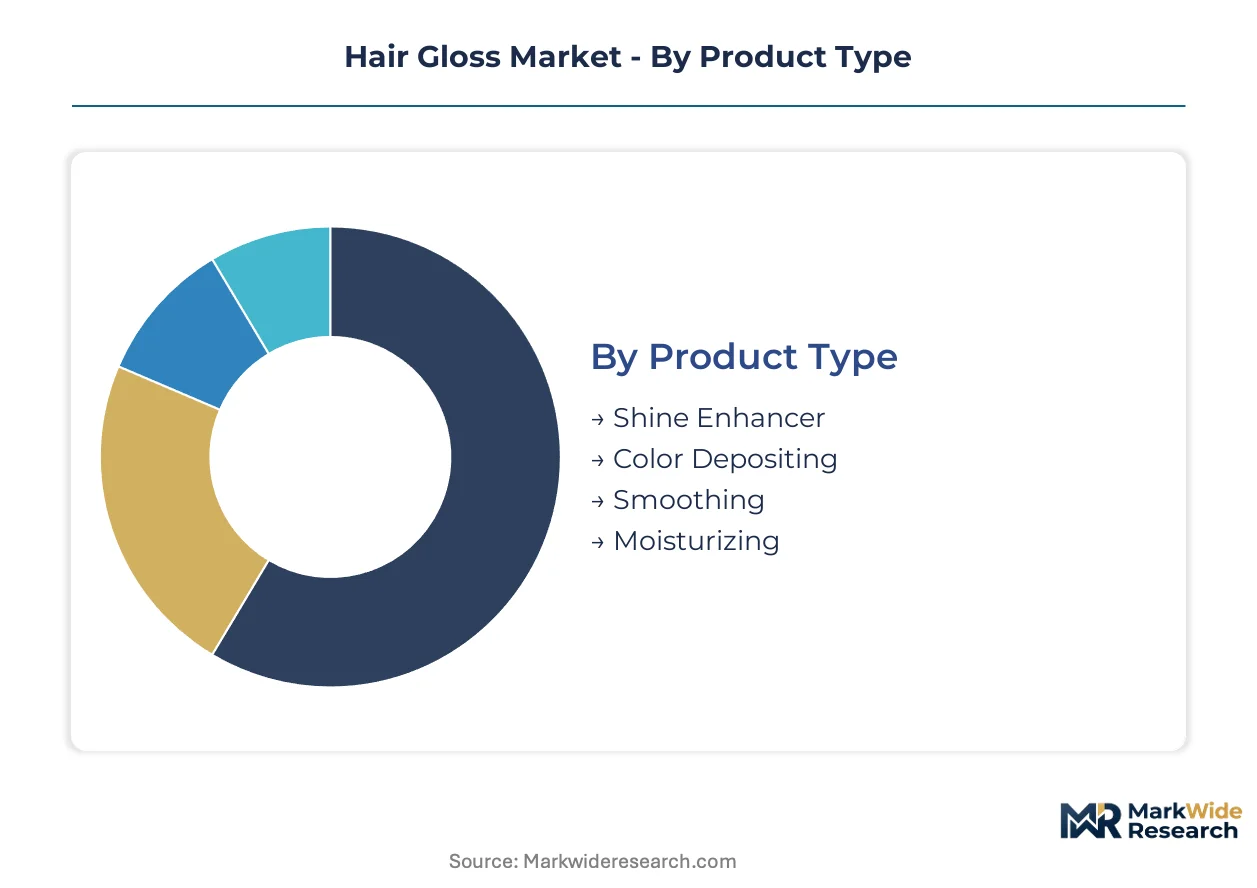
Hair gloss segmentation tracks how formulation chemistry, application format, and channel economics reshape purchase patterns between professional service intervals and at-home refresh cycles. Understanding these divides exposes where margin pools concentrate and where volume growth accelerates.
Product Type:
Upgrade cycles in hair gloss correlate with permanent color service frequency, creating distinct replacement windows across functional categories.
- Shine Enhancer:Silicone or oil-based formulations at 2–8% refractive index modifier concentration maximize cuticle light reflection without pigment load. Salon backbar deployment in São Paulo and Rio de Janeiro supports steady volume through stylist education infrastructure.
- Color Depositing:Tonal pigment suspensions engineered for semi-permanent deposition between chemical services capture expanding margin pools as social media compression accelerates refresh frequency. Fashion-cycle turnover in South Korea and Brazil drives fastest adoption.
- Smoothing:Frizz-sealing variants target humidity-exposed climates with cationic conditioning polymers.
- Moisturizing:Humectant-rich formulations address chemically damaged hair recovery segments.
Shine Enhancer sits at the top of the volume ranking, with Color Depositing climbing the fastest.
Form:
Application speed requirements in professional settings versus retail convenience preferences split demand across physical formats.
- Cream:Thickened emulsions sustain higher per-unit economics through take-home retail conversion and controlled dosing precision. US specialty store channels favor cream tubes for premium positioning.
- Spray:Aerosol or pump-dispersed fine mists dominate salon backbar deployment for speed of application during high-volume service windows. Brazilian professional service density supports spray volume leadership.
- Gel:Clear polymer matrices target male grooming segments seeking non-greasy finish.
- Liquid:Fluid concentrates enable custom dilution protocols in professional formulation houses.
Spray formats command the largest installed base, while Cream variants gain share fastest through retail premiumization.
Ingredient:
Feedstock chemistry determines regulatory compliance pathways and clean beauty certification eligibility across distribution geographies.
- Organic:USDA BioPreferred and EWG Verified standards create premium positioning anchors for certification-dependent consumer segments. Copenhagen and Portland salon networks now specify organic backbar standards.
- Silicone:Dimethicone and cyclomethicone bases remain dominant in conventional formulations despite ECHA microplastic restriction pressures. Refinery-linked supply exposes margins to petrochemical volatility without scalable natural substitutes.
- Natural Oils:Plant-derived squalane and hemisqualane blends overtake silicone in prestige tier as fermentation-derived lipid supply chains mature.
- Synthetic:Acrylate copolymers and petroleum-derived film formers face forced reformulation timelines before EU enforcement windows.
Silicone ingredients retain volume leadership, with Natural Oils expanding most quickly through clean beauty certification convergence.
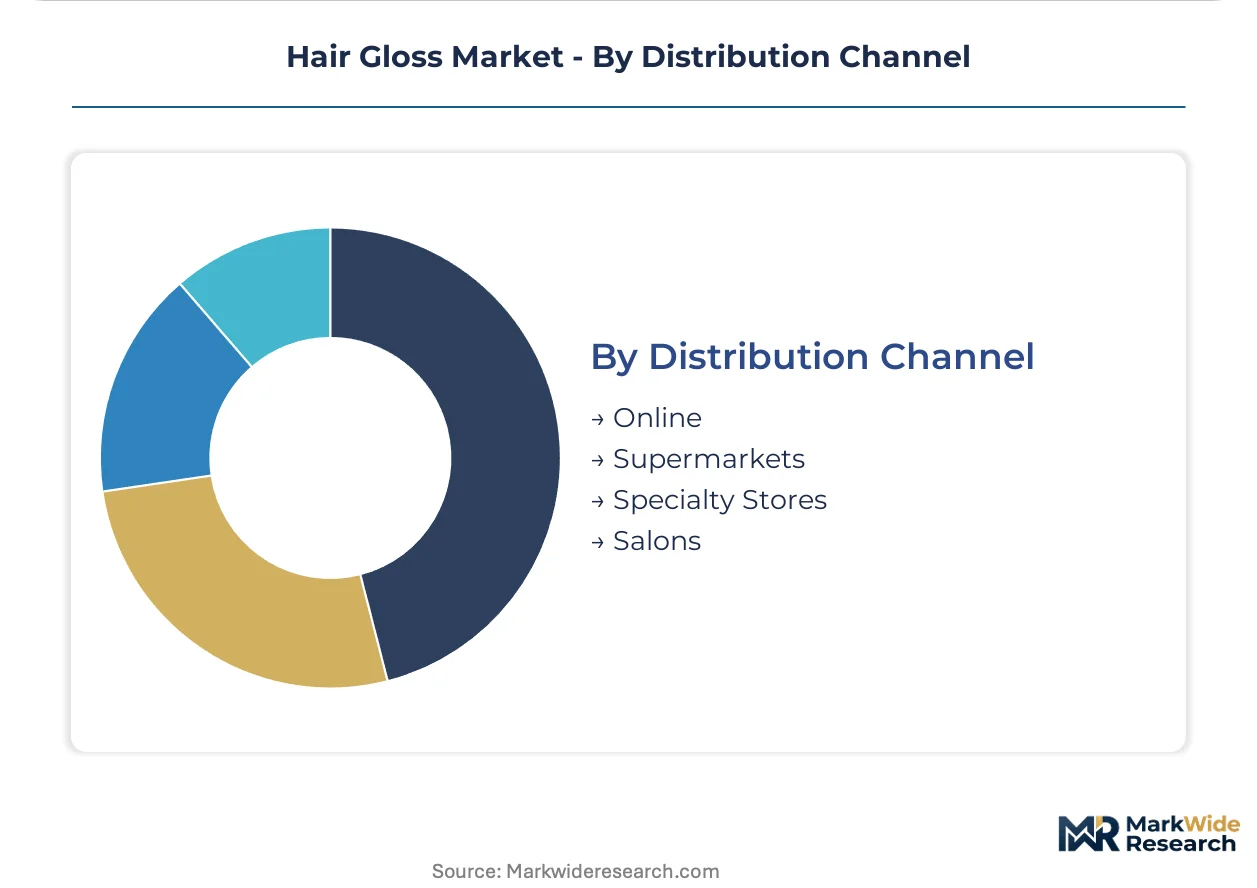
Distribution Channel:
Channel consolidation and direct-to-stylist digital platforms are fragmenting traditional wholesale relationships while compressing distributor markups.
- Salons:Professional backbar purchasing concentrates through multi-location chain master service agreements in Texas and Florida. Large salon groups negotiate volume-based procurement leverage displacing fragmented manufacturer relationships.
- Online:Direct-to-stylist subscription platforms bypass distributor tiers while capturing recurring revenue through calibrated color-matching algorithms. Digital penetration accelerates in South Korean male grooming expansion.
- Supermarkets:Mass retail placement captures price-sensitive consumers seeking single-step tonal modification without salon labor costs.
- Specialty Stores:Curated beauty retailers anchor premium silicone-free and organic certification positioning.
Salons dominate current volume capture, with Online channels showing steepest expansion trajectory through platform disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional hair gloss formulations first achieved commercial scale in France and Italy during the 1970s salon boom, then migrated to the United States through New York and Los Angeles celebrity stylist networks. Today's demand geography reflects this heritage plus newer high-service-density markets in Brazil and South Korea.
United States
Professional salon backbar purchasing concentrates through multi-location chains in Texas and Florida negotiating master service agreements. FDA cosmetic labeling rules govern ingredient disclosure and claims substantiation for all formulations sold through retail channels. New York City and Los Angeles maintain the densest stylist education infrastructure, driving premium gloss adoption through celebrity-influenced service menus.
Brazil
São Paulo and Rio de Janeiro support the highest professional service density in Latin America, with salon backbar penetration accelerating color-depositing gloss volumes. ANVISA regulates cosmetic safety and ingredient thresholds for imported formulations. The southeastern corridor from São Paulo through Belo Horizonte generates concentrated demand for humidity-resistant smoothing variants.
South Korea
Male grooming service expansion in Seoul and Busan creates whitespace for neutral-toned gloss formulations targeting gray blending. MFDS oversees cosmetic manufacturing standards and import registration requirements. The Seoul Capital Area drives fastest adoption of fashion-cycle-driven color refresh services through digitally native salon platforms.
Germany
REACH substance authorization protocols impose the strictest compliance burden for silicone-based and synthetic polymer formulations seeking European distribution. ECHA microplastic restriction evaluations are forcing reformulation timelines before 2027 enforcement windows. The Düsseldorf-Cologne corridor anchors professional distributor consolidation for Central European salon supply.
France
L'Oréal's integrated R&D pipeline near Paris navigates complex REACH dossier requirements that create defensive moats against smaller competitors. ANSM enforces cosmetic product safety alongside EU-level regulations. The Île-de-France region sustains formulation innovation clusters serving prestige salon channels across Western Europe.
Hair Gloss Market Competitive Landscape
The competitive structure tilts toward integrated beauty conglomerates with captive R&D pipelines and professional distributor relationships. Three to five multinational holding companies control majority volume through portfolio brand architectures. Strategic archetypes separate conglomerate-integrated manufacturers, independent professional specialists, and clean-beauty-positioned challengers. Dominant competitive moves include direct-to-stylist digital platform launches and silicone-free formulation line extensions.
Within the conglomerate-integrated tier, L'Oréal S.A. and Wella occupy positions exemplifying batch-level documentation capabilities and professional channel anchoring respectively. Among Japan-origin specialists, Milbon Co., Ltd. and Shu Uemura represent archetypes of fermentation-derived lipid supply chain control and prestige salon positioning. Bumble and bumble, a New York-originated standalone, illustrates independent brand cultivation through stylist education infrastructure before acquisition into larger portfolios.
| Leading Market Players |
|---|
| Milbon |
| Wella |
| Redken |
| Bumble and bumble |
| Oribe |
| L'Oréal |
| Pravana |
| Moroccanoil |
| Shu Uemura |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up professional distributor networks concentrate procurement leverage across Texas and Florida salon chains, compressing manufacturer margins while simultaneously rewarding integrated suppliers with captive fermentation-derived lipid supply chains that command premium positioning in clean beauty channels.
Pricing Analysis
Three-tier pricing structure across prestige, professional, and mass retail levels governs the market, with differentiation anchored in clean beauty certification tier and stylist education bundling. Cost compression in the silicone-based tier intensifies because refinery-linked dimethicone supply exposes margins to petrochemical volatility without scalable natural substitutes. Supermarket channels exhibit highest price sensitivity, while prestige salons demonstrate lowest sensitivity due to service-menu bundling economics.
Supply Chain Analysis
Dimethicone and cyclomethicone feedstock draws from petrochemical complexes in the United States, Germany, and South Korea, with plant-derived squalane alternatives emerging from fermentation facilities in Japan and Brazil. Acrylate copolymer film formers and refractive index modifiers constitute critical formulation inputs. Single-source vulnerability concentrates in Japanese fermentation-derived lipid supply chains. Distribution runs through professional distributor consolidation in sunbelt markets and direct-to-stylist digital platforms bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hair gloss market reads as a late-cycle quality story where social media-driven fashion-cycle compression funnels demand toward premium color-depositing formulations with clean beauty credentials.
For Market Incumbents: Hedge silicone feedstock exposure through backward integration into fermentation-derived squalane supply chains or long-term offtake agreements with Japanese lipid producers. Defend against DIY color kit substitution by embedding gloss services into mandatory color-maintenance protocols taught through stylist education infrastructure. For New Entrants and Emerging Players: Launch via direct-to-stylist subscription platforms targeting South Korean male grooming whitespace with neutral-toned gray-blending formulations. Penetrate the underexploited organic certification segment in Copenhagen and Portland salon networks where backbar standards now specify silicone-free requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers lacking batch-level REACH documentation capabilities. Long-term viability favors targets with captive clean beauty certification and professional channel anchoring. Watch ECHA microplastic enforcement timelines as inflection indicator for synthetic polymer-dependent formulation houses facing forced asset impairment.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Free Formulation Line Extension | Captures Copenhagen and Portland salon backbar standards shifting toward organic certification requirements. |
| Direct-to-Stylist Digital Platform Launch | Bypasses consolidated distributor markups in Texas and Florida while capturing recurring subscription revenue. |
| Fermentation-Derived Lipid Supply Chain Investment | Secures captive squalane and hemisqualane feedstock against Japanese supply concentration risk. |
| REACH Batch-Level Documentation Capability Buildout | Creates defensive moat against smaller competitors lacking substance authorization dossier maintenance resources. |
| South Korean Male Grooming Market Entry | Exploits whitespace in neutral-toned gray-blending services through Seoul and Busan salon platform partnerships. |
Research Methodology
Multiple input streams — primary interviews with cosmetic chemists and professional salon owners, secondary validation through ANVISA and MFDS regulatory filings, and customs trade data — were reconciled across bottom-up formulation house surveys and top-down distributor volume estimates. Stakeholder consultations spanned R&D directors at integrated beauty conglomerates, procurement leads at multi-location salon chains, and regulatory affairs specialists navigating REACH substance authorization protocols.
Data-stream reconciliation anchored volume projections across product type, formulation chemistry, distribution channel, and regional service density dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate blending weighted by base-year revenue contribution. Industry-specific forecast inputs included stylist education infrastructure penetration rates and social media aesthetic turnover velocity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA microplastic enforcement or sustained dimethicone feedstock price volatility. A small set of named triggers — regulatory divergence between FDA and REACH, salon chain consolidation pace, and fermentation capacity expansion timelines — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
Anti-Aging Serums Market