
 Metal Banding Machine Market | 2026-2036
Metal Banding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Banding Machine Market Foresight
Skilled technician availability is bifurcating the competitive landscape between premium automated suppliers and manual-equipment vendors. FROMM Holding AG leverages its Swiss engineering heritage to sustain high-margin friction-sealing systems for European steel mills. Signode Industrial Group anchors North American demand through captive service networks and in-house production of consumables. Mosca GmbH differentiates via modular heat-sealing architectures that reduce floor-space requirements for mid-size German manufacturers.
Metal banding machines apply high-tensile steel or composite strap around palletized loads, with tension forces typically ranging from 500 to 2,500 newtons and seal joint strengths determining system throughput in industrial packaging lines. Their primary purpose is unitizing heavy or irregular shipments for safe transit across multimodal logistics networks. Fully automatic systems command the largest installed base among product types due to throughput requirements in automotive and metals processing plants, while electric variants represent the fastest-growing technology segment as warehouses phase out pneumatic infrastructure. Friction sealing dominates high-volume palletizing applications where polypropylene and woven polyester straps require consistent weld integrity.
OSHA machine-guarding standards and the EU Machinery Directive shape design requirements for operator-access zones and emergency-stop configurations, compelling vendors to redesign feed mechanisms. ISO 9001 quality-management certification and CE marking govern market access for European and export-oriented suppliers. Stakeholders must monitor how Germany's KBA transport-safety protocols and evolving EPA industrial-efficiency guidelines reshape specification thresholds for strap-recycling and energy-consumption metrics in next-generation equipment procurement.
Market Dynamics
The metal banding machine market is undergoing a fundamental restructuring as logistics operators automate palletizing lines to offset climbing labor costs, while OSHA and EU machinery directives force simultaneous redesigns of operator-access zones and emergency-stop configurations.
Growth Catalysts
- EU Machinery Directive compliance mandates:Stricter safety requirements for strapping equipment are compelling facilities to replace aging manual systems with guarded automatic architectures, accelerating replacement cycles in European steel and automotive plants.
- Automotive export hub concentration:Germany's automotive and steel export corridors drive specification-heavy procurement for high-throughput friction-sealing systems capable of handling irregular palletized loads.
- Pneumatic-to-electric infrastructure transition:Warehouses phasing out pneumatic systems are creating pull for electric banding variants, particularly in facilities targeting EPA industrial-efficiency guidelines for energy-consumption metrics.
Market Restraints
- High-tensile steel strap price volatility:Raw material cost swings for steel and composite feedstock compress margins for equipment vendors locked into long-term service contracts with fixed consumable pricing.
- Skilled technician scarcity:The bifurcation between premium automated suppliers and manual-equipment vendors is widening as qualified service personnel concentrate in Swiss and German engineering clusters.
- Plastic strap substitution pressure:Woven polyester and polypropylene alternatives in lightweight logistics applications are displacing metal banding in shipments below 500-newton tension thresholds.
Strategic Opportunities
- Modular heat-sealing architecture adoption:Mid-size German manufacturers are prioritizing floor-space-efficient systems, creating white space for vendors offering reconfigurable sealing heads and compact feed mechanisms.
- Captive consumables integration:In-house production of steel strap and seals is enabling margin defense for vendors with backward integration into metallurgical supply chains.
- KBA transport-safety protocol alignment:Germany's evolving road freight regulations for load securement are opening specification windows for next-generation equipment with integrated tension monitoring and digital seal verification.
Industry Challenges
- ISO 9001 certification timeline compression:European suppliers face extended audit cycles and documentation burdens when adapting quality-management systems to cover redesigned feed mechanisms and new safety interlocks.
- Legacy pneumatic system integration friction:Electric banding machine deployment in brownfield warehouses requires costly retrofitting of power distribution and control architecture, delaying payback periods.
- CE marking complexity for multi-territory deployment:Vendors serving cross-border logistics networks must reconcile diverging national implementations of EU Machinery Directive annexes, particularly for emergency-stop response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Banding Machine Market |
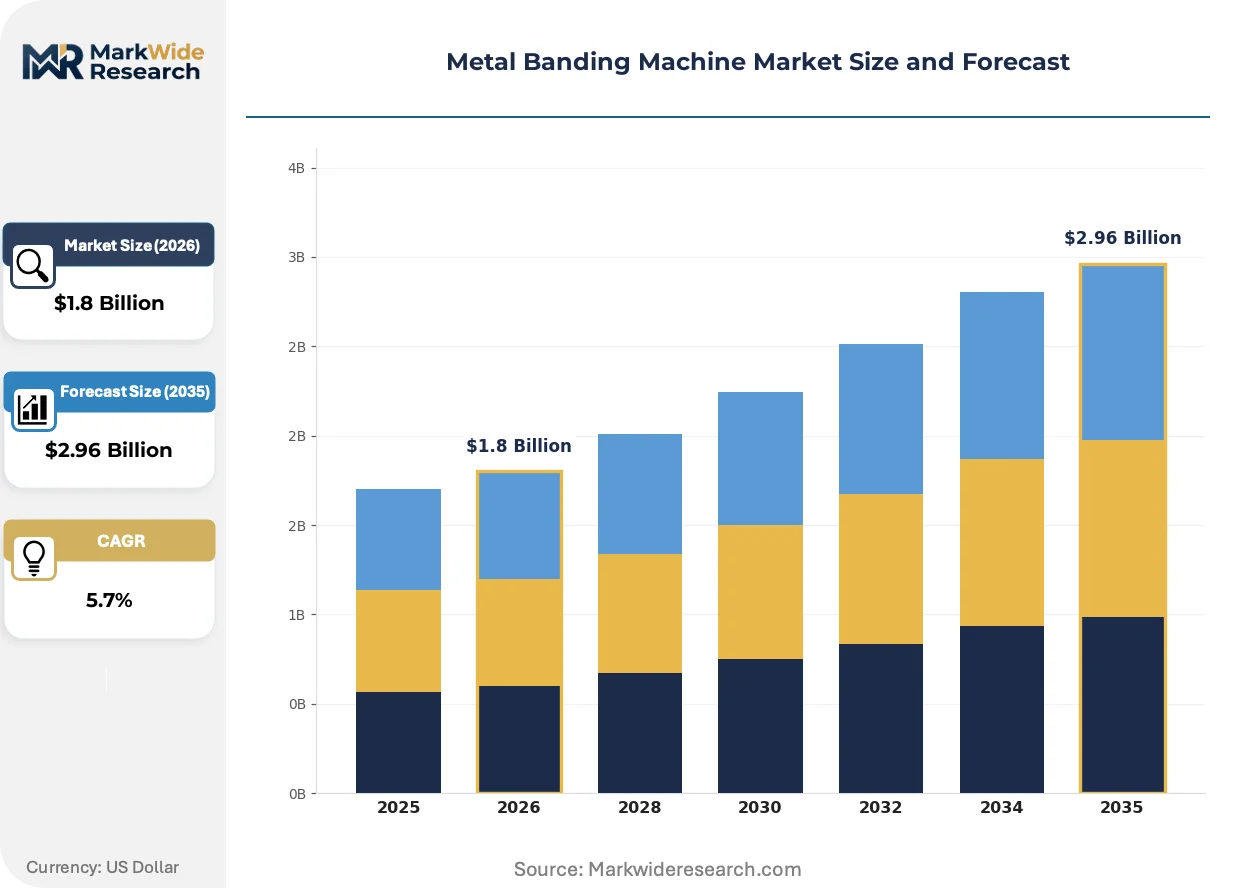
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, Electric Application: Palletizing, Packaging, Logistics, Manufacturing End User: Manufacturers, Distributors, Retailers, Wholesalers Technology: Heat Sealing, Friction Sealing, Buckle Clipping, Others |
| Companies Covered | Signode Industrial Group, FROMM Holding AG, Polychem Corporation, Cyklop International, Mosca GmbH, StraPack Corp, Samuel, Son & Co., Limited, MAILLIS GROUP, TITAN Umreifungstechnik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Banding Machine Market Shifts & Advancements
Three interconnected shifts are restructuring competitive advantage in metal banding: electric drive technology is displacing pneumatic infrastructure, regulatory safety mandates are forcing mechanical redesigns, and procurement patterns are favoring vendors with integrated consumables and service networks.
Friction-sealing technology is bifurcating the installed base between high-volume palletizing applications and mid-tier operations. European steel mills and automotive plants are adopting advanced friction-weld systems for polypropylene and woven polyester straps at accelerated rates. This technology compression is enabling consistent weld integrity at throughputs exceeding manual sealing capacity by orders of magnitude, while marginalizing vendors without precision heat-control engineering.
OSHA machine-guarding standards are mandating physical barriers and interlocked access panels on all new strapping equipment installations. The industrial consequence is a complete redesign of feed mechanisms to eliminate pinch points and entanglement hazards. North American automotive and metals processing facilities are responding by specifying fully automatic systems with enclosed strap paths, effectively disqualifying semi-automatic architectures from new capital budgets.
Specification-heavy buyers in German automotive export hubs are consolidating vendor relationships around providers offering captive strap supply and preventive maintenance contracts. The traditional equipment-plus-consumables split is collapsing into bundled lifecycle agreements. This pattern is most visible in Baden-Württemberg and Bavaria, where OEM logistics operators prioritize uptime guarantees over upfront equipment cost minimization.
Metal Banding Machine Market Segmentation
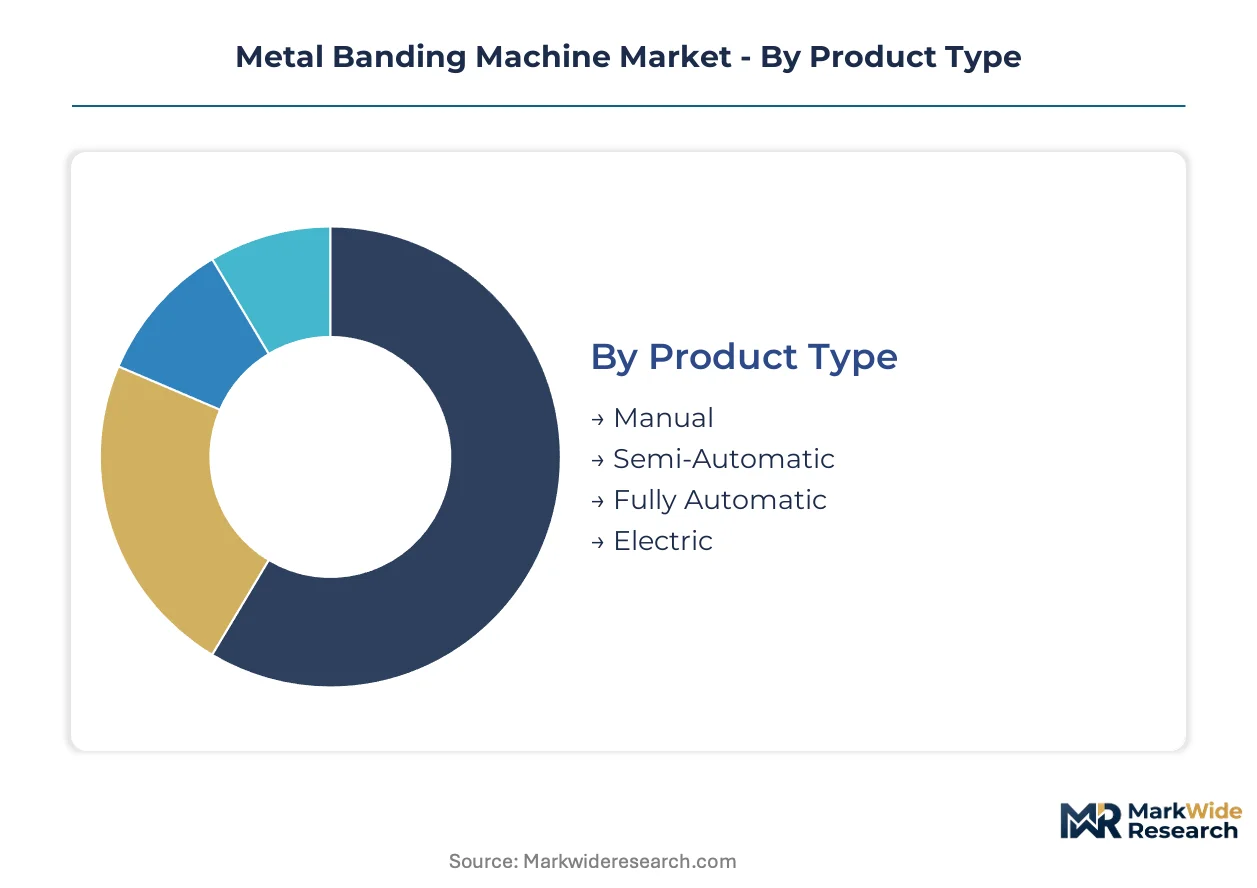
Segmentation in metal banding equipment reveals divergent procurement patterns between export-heavy automotive corridors and domestic logistics networks. Specification intensity varies sharply across product tiers, with German steel mills demanding friction-sealing precision while North American warehouses prioritize electric retrofit compatibility.
Product Type:
German automotive export hubs drive specification-heavy procurement for fully automatic architectures, while domestic warehousing operations in the US Midwest favor electric variants for brownfield compatibility.
- Fully Automatic:Enclosed strap paths with interlocked access panels dominate high-throughput automotive and metals processing lines. German OEM logistics operators in Baden-Württemberg specify these systems for palletized steel coil shipments to Rotterdam and Hamburg ports.
- Electric:Tension forces ranging from 500 to 2,500 newtons with programmable seal verification. Warehouses phasing out pneumatic infrastructure in EPA-regulated zones specify these for energy-consumption compliance.
- Semi-Automatic:Bridging architecture for mid-size manufacturers with intermittent throughput requirements.
- Manual:Portable units for field repairs and low-volume irregular loads in construction supply yards.
Fully automatic systems command the established base. The steepest expansion runs through electric variants.
Application:
Cost tier differentiation separates capital-intensive palletizing lines from maintenance-light packaging operations.
- Palletizing:High-tensile steel strap application at 1,500-2,500 newton tension ranges for multimodal load securement. German KBA transport-safety protocols mandate integrated tension monitoring for road freight export corridors.
- Packaging:Heat-sealing and friction-weld systems for unitized consumer goods and industrial components. Mid-size German manufacturers prioritize floor-space-efficient modular architectures.
- Logistics:Cross-dock operations with rapid strap changeover requirements.
- Manufacturing:Inline integration with conveyor systems for just-in-time production flows.
Palletizing absorbs the heaviest capital deployment. Packaging is gaining share fastest through mid-tier manufacturer automation.
End User:
Customer type determines service contract structure, with manufacturers bundling lifecycle agreements and distributors accepting equipment-only procurement.
- Manufacturers:Automotive and steel processing plants with captive consumables integration and preventive maintenance contracts. Swiss and German engineering clusters concentrate qualified technician networks for these accounts.
- Distributors:Third-party logistics operators with variable throughput and seasonal demand spikes.
- Retailers:Warehouse club and big-box distribution centers with standardized pallet configurations.
- Wholesalers:Building material and industrial supply intermediaries with mixed load requirements.
Manufacturers anchor premium system demand. Distributors are climbing the fastest through 3PL automation mandates.
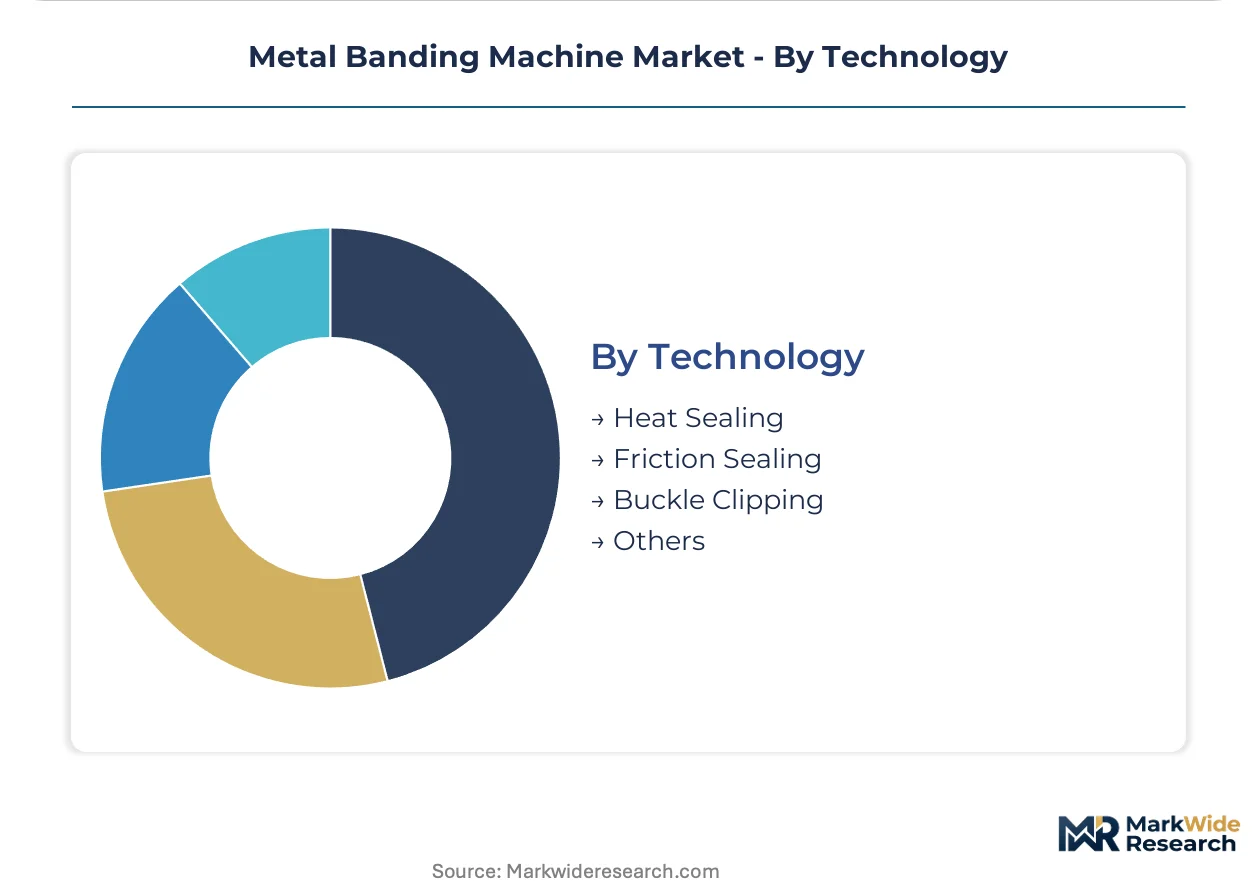
Technology:
Margin concentration follows sealing precision, with friction-weld engineering commanding premium positioning against commodity buckle systems.
- Friction Sealing:Polypropylene and woven polyester strap welding at throughputs exceeding manual capacity by orders of magnitude. European steel mills specify these for consistent weld integrity in high-volume palletizing.
- Heat Sealing:Modular architectures with reconfigurable sealing heads reducing floor-space requirements. Mosca GmbH differentiates in this segment for mid-size German manufacturers.
- Buckle Clipping:Mechanical joint systems for field repairs and temporary load securement.
- Others:Emerging ultrasonic and laser sealing technologies in pilot deployment.
Friction sealing holds the dominant installed position. Heat sealing is expanding most quickly through space-constrained facility retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand composition varies sharply across geographies. German automotive export corridors specify friction-sealing precision for steel coil shipments, while North American warehouses prioritize electric retrofit compatibility for brownfield facilities. Asian markets concentrate in coastal manufacturing zones with distinct regulatory compliance frameworks.
Germany
Automotive OEM logistics operators in Baden-Württemberg and Bavaria drive specification-heavy procurement for high-throughput palletizing systems. KBA transport-safety protocols mandate integrated tension monitoring for road freight export corridors to Rotterdam and Hamburg ports. Stuttgart-based engineering clusters concentrate qualified technician networks serving captive consumables contracts.
United States
OSHA machine-guarding standards compel enclosed strap paths and interlocked access panels on new installations. Midwest warehouses phasing out pneumatic infrastructure specify electric variants for EPA industrial-efficiency compliance. Detroit automotive and metals processing facilities anchor demand for fully automatic architectures with preventive maintenance agreements.
China
Coastal manufacturing zones in Yangtze River Delta and Pearl River Delta absorb mid-tier semi-automatic systems for export packaging. GB standards and MIIT industrial-efficiency guidelines shape equipment procurement for energy-consumption metrics. Shanghai port logistics operators drive demand for rapid strap changeover capabilities in cross-dock operations.
Japan
METI industrial automation incentives accelerate replacement of legacy manual systems in automotive component supply chains. JIS quality-management certification requirements filter vendor selection for precision heat-sealing applications. Nagoya and Osaka manufacturing belts concentrate demand for modular floor-space-efficient architectures.
Switzerland
Swiss engineering heritage sustains premium positioning for friction-sealing precision in European steel mill applications. Swissmedic-equivalent machinery safety standards exceed baseline EU Machinery Directive requirements. Zurich and Basel industrial corridors maintain specialist technician density for high-margin service contracts.
Metal Banding Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding bundled lifecycle agreements and captive consumables supply. The middle tier fragments across regional fabricators with equipment-only procurement models. Two strategic archetypes dominate: precision-engineering specialists leveraging Swiss and German heritage, and scale-driven operators with backward integration into metallurgical supply chains. Competitive moves concentrate on geographic expansion through service network density and portfolio diversification into adjacent sealing technologies.
Among German-based precision specialists, Mosca GmbH and TITAN Umreifungstechnik GmbH & Co. KG occupy positions exemplifying modular heat-sealing and friction-weld engineering respectively. Swiss-heritage integrated leader FROMM Holding AG anchors the premium tier through high-margin friction-sealing system representation. North American scale operator Signode Industrial Group exemplifies the captive consumables and service network archetype. These three companies collectively represent the structural bifurcation between engineering-intensive European positioning and integrated North American supply chain control.
| Leading Market Players |
|---|
| Signode Industrial Group |
| FROMM Holding AG |
| Polychem Corporation |
| Cyklop International |
| Mosca GmbH |
| StraPack Corp |
| Samuel, Son & Co., Limited |
| MAILLIS GROUP |
| TITAN Umreifungstechnik GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Sixteen-week lead times for high-tensile steel strap from European mills concentrate pricing power with backward-integrated vendors, while spot-market buyers absorb volatility from alloy surcharge fluctuations. This inventory compression at German automotive export hubs forces specification-heavy procurement toward bundled lifecycle contracts that lock in consumable supply.
Pricing Analysis
Long-term offtake agreements dominate premium system procurement, with German OEM logistics operators in Baden-Württemberg and Bavaria favoring bundled equipment-consumables contracts over transactional spot purchases. Price differentiation separates ISO 9001-certified friction-sealing architectures from standard heat-sealing tiers, while CE marking and KBA protocol alignment command additional premiums. Pricing pressure stems from raw material cost swings for steel and composite feedstock, compressing margins for vendors locked into fixed consumable pricing. Distributors and third-party logistics operators exhibit highest price sensitivity due to variable throughput, whereas manufacturers prioritize uptime guarantees over upfront cost minimization.
Supply Chain Analysis
Inventory buffers at North American warehouses stretch to twelve weeks for electric drive components, reflecting lead-time volatility from Asian motor suppliers. Raw material sourcing draws from German and Swiss engineering clusters for precision sealing heads, Chinese coastal zones for semi-automatic system components, and domestic North American mills for high-tensile steel strap. Single-source vulnerability concentrates in friction-weld control modules from specialized German electronics vendors. Distribution runs through captive service networks for premium automated systems, while mid-tier equipment flows through industrial distributors with regional stocking points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward German automotive OEM logistics operators as they consolidate vendor relationships around bundled lifecycle agreements, fragmenting procurement influence among smaller distributors.
For Market Incumbents: Compound service network density in Stuttgart and Nagoya manufacturing belts to defend against modular heat-sealing entrants. Deepen backward integration into metallurgical supply chains to offset steel strap price volatility. Prioritize ISO 9001 certification maintenance as audit timelines compress for redesigned feed mechanisms. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships opens specification windows in European steel and automotive plants. Target mid-size German manufacturers with floor-space-constrained facilities seeking modular heat-sealing architectures. Deploy direct field technician teams to overcome skilled service personnel scarcity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized strapping equipment divisions lacking captive consumables integration. Five-to-ten year viability favors vendors with electric drive technology portfolios aligned with EPA industrial-efficiency guidelines. Monitor KBA transport-safety protocol revisions as inflection indicators for next-generation equipment procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgical Supply | Captive steel strap production defends margins against alloy surcharge volatility for German mill suppliers. |
| Modular Heat-Sealing Architecture Development | Reconfigurable sealing heads reduce floor-space requirements for mid-size Baden-Württemberg manufacturers. |
| Electric Drive Technology Transition | Programmable tension systems align with EPA energy-consumption metrics for Midwest warehouse retrofits. |
| Captive Service Network Expansion | Preventive maintenance contracts lock in automotive OEM logistics operators across Stuttgart engineering clusters. |
| KBA Protocol Alignment Investment | Integrated tension monitoring meets evolving German road freight regulations for Rotterdam export corridors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at automotive and steel processing facilities; and secondary validation against customs trade records, SEC filings from listed industrial equipment vendors, OSHA machine-guarding standard documentation, and EU Machinery Directive implementation guidance. Bottom-up equipment shipment tallies triangulated against top-down consumables consumption estimates across the projection horizon.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, sealing technology, end-user category, and regional regulatory cluster. CAGRs derived from historical shipment patterns, replacement cycle analysis, and penetration rate assumptions for electric versus pneumatic infrastructure. Industry-specific inputs included KBA transport-safety protocol adoption curves, EPA industrial-efficiency guideline compliance timelines, and skilled technician availability indices.
The analysis sits within stated boundaries; outcomes outside sustained German automotive export volume growth or accelerated OSHA enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding steel strap price stabilization and electric drive component supply normalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Bottle Capping Machines Market