
 Blown Film Extrusion Machine Market | 2026-2036
Blown Film Extrusion Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Blown Film Extrusion Machine Market Outlook
The EU Green Deal is repositioning demand toward mono-material and recyclable film architectures across European flexible packaging supply chains. Reifenhäuser Blown Film leverages its German engineering base to dominate high-output co-extrusion lines for regulated markets. Windmöller & Hölscher anchors premium segments through integrated process control systems that sustain OEE metrics. Bandera competes on modular platform designs that extend machine lifecycles without full replacement.
A blown film extrusion machine manufactures plastic film by extruding molten polymer through a circular die and inflating it into a tubular bubble, typically achieving gauges from 8 to 150 microns depending on resin and cooling configuration. The process serves primary industrial functions in food packaging barrier films, agricultural mulch and greenhouse covers, and protective industrial wraps. Multi-layer co-extrusion systems capture disproportionate margin pools where EVOH and nylon barrier architectures command premium pricing against commodity single-layer alternatives. High-speed automatic lines are displacing semi-automatic configurations in packaging end-use as labor cost arbitrage diminishes and throughput consistency becomes the decisive operational metric.
REACH and RoHS frameworks govern chemical composition and restricted substances in European-sold machinery and films, while FDA compliance shapes export qualification for US-bound food-contact applications. Germany's KBA and France's ANSM enforce machinery safety and pharmaceutical-contact standards that filter down to film converter procurement specifications. Stakeholders must monitor evolving extended producer responsibility schemes and decide between platform standardization versus regional customization before regulatory divergence hardens supply chain costs.
Market Dynamics
Mono-material film architectures are forcing machinery retrofits across European flexible packaging supply chains as recyclability mandates harden from policy guidance into procurement specifications.
Growth Catalysts
- EU Green Deal recyclability mandates:Packaging converters in Germany and France must demonstrate closed-loop compatibility, driving replacement of legacy multi-material lines with mono-material-capable co-extrusion systems.
- Food packaging barrier film demand:Extended shelf-life requirements for fresh protein and dairy products are pulling high-output lines with EVOH and nylon barrier layers into North American processor facilities.
- Agricultural film mechanization:Large-scale greenhouse operations in Spain and Italy are adopting automated blown film lines for mulch and tunnel covers to reduce seasonal labor dependency.
Market Restraints
- Specialized screw and barrel alloys:Corrosion-resistant bimetallic components for aggressive barrier resins carry 40-60% cost premiums over standard tool steel, compressing margins on mid-tier equipment.
- German engineering concentration:Critical drive systems and precision air rings source predominantly from Baden-Württemberg and Bavaria supplier clusters, creating geographic single-point vulnerability.
- REACH chemical compliance friction:Substance of Very High Concern (SVHC) candidate list expansions force reformulation of lubricants and hydraulic fluids, extending machine qualification timelines.
Strategic Opportunities
- India packaging machinery localization:PLI scheme incentives for food processing equipment create entry pathways for European and East Asian blown film OEMs to establish assembly operations serving domestic flexible packaging growth.
- Pharmaceutical-grade film certification:Annex 1 compliance for sterile barrier systems opens premium pricing tiers for lines validated to produce ISO Class 7-8 compatible packaging films.
- Digital twin integration:Convergence of real-time extrusion process data with predictive maintenance algorithms enables outcome-based service contracting and remote technical support revenue streams.
Industry Challenges
- Multi-layer process engineering expertise:Seven-layer and nine-layer co-extrusion die design requires polymer rheology specialization that outstrips vocational training pipeline output in most manufacturing regions.
- Legacy control system integration:Retrofitting Industry 4.0 connectivity onto 1990s-vintage lines with proprietary PLC architectures demands custom gateway development that stretches project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blown Film Extrusion Machine Market |
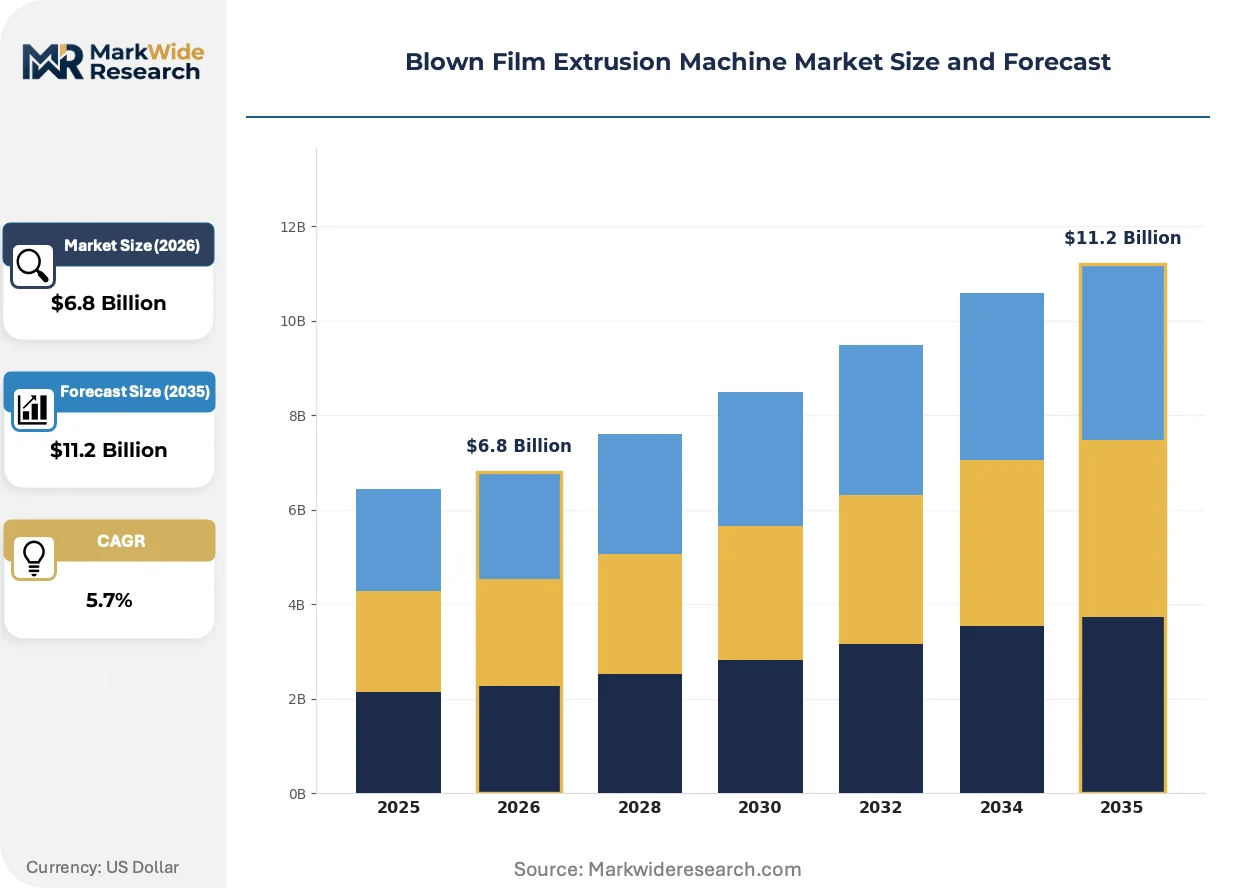
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Multi Layer, Co-extrusion, Turbo Blown Technology: Manual, Automatic, Semi-automatic, High-speed End User: Packaging, Agriculture, Automotive, Consumer Goods Application: Food Packaging, Agricultural Films, Protective Packaging, Others |
| Companies Covered | Bandera, Plastmach, Reifenhäuser Blown Film, Kappa, Colines, Windmöller & Hölscher, Macchi, Anger, Zhejiang Zhuxin Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blown Film Extrusion Machine Market Strategic Shifts
Active materials substitution and regulatory compression are reshaping equipment specifications faster than standard product development cycles can accommodate.
High-performance polyamide and EVOH barrier resins are consolidating their position in food-contact flexible packaging as brand owners eliminate aluminum foil laminates to satisfy recyclability audits. Major dairy and ready-meal processors in Germany and the Netherlands have accelerated qualification timelines for transparent barrier alternatives. This resin transition is consolidating demand around co-extrusion lines with specialized screw designs and enhanced cooling capacity for heat-sensitive barrier polymers.
REACH SVHC notification requirements and impending microplastic restrictions are forcing machinery OEMs to pre-certify lubricant formulations and belt materials for downstream film compliance. The European Chemicals Agency's 2024-2025 candidate list expansion covers several polymer processing additives previously considered inert. Film converters serving regulated European markets now require machinery suppliers to provide full material declarations, shifting procurement due diligence upstream.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale flexible packaging converters facing margin pressure from resin volatility. German machinery financiers and captive leasing arms of major OEMs have structured throughput-guarantee arrangements that bundle maintenance, upgrades, and resin optimization consulting. This financing innovation is most visible in the Benelux region, where private-equity-backed converter roll-ups prioritize operational flexibility over balance-sheet ownership.
Blown Film Extrusion Machine Market Segmentation
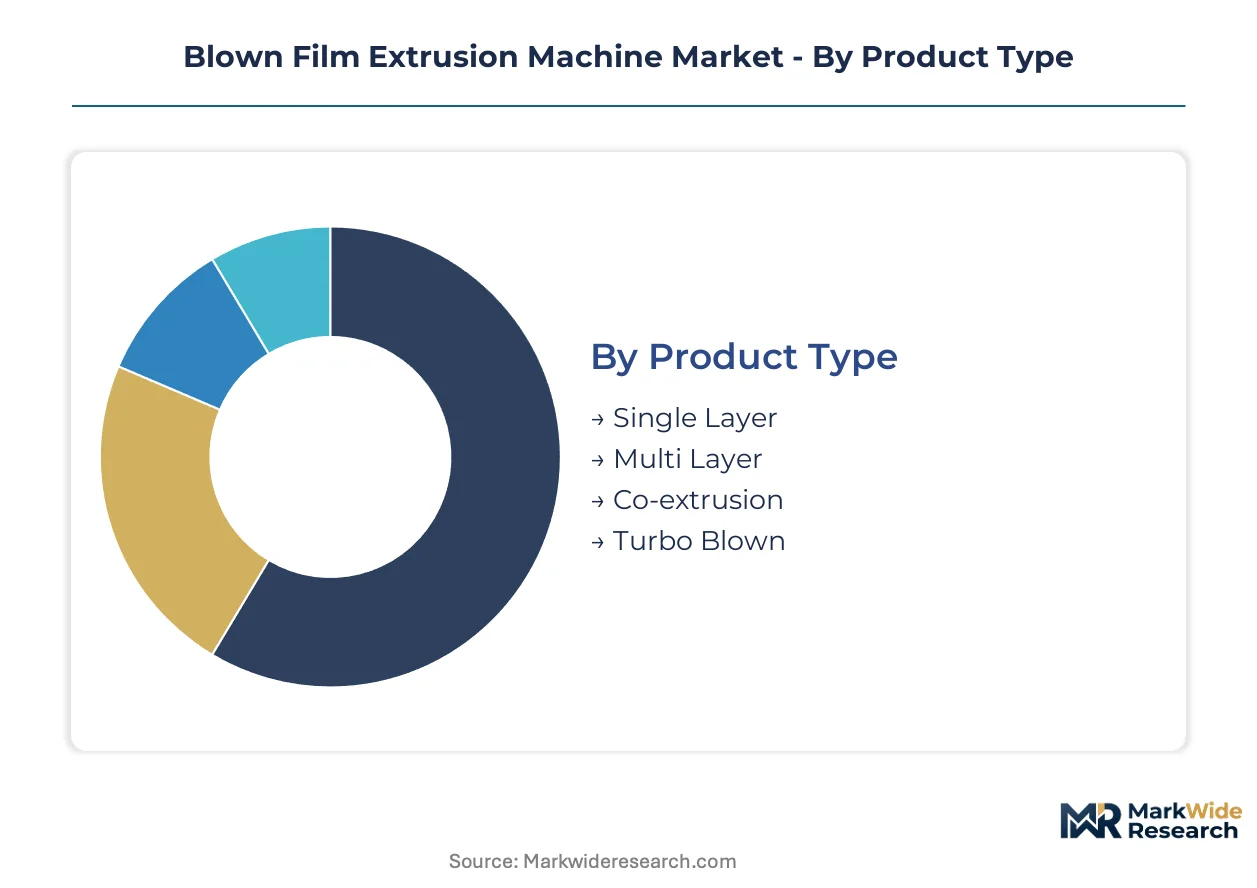
Segmentation in blown film extrusion machinery reflects divergent capital intensity and regulatory compliance requirements. Equipment buyers select configurations based on barrier performance needs, labor cost structures, and recyclability mandates that vary sharply across end-use verticals.
Product Type:
Volume concentration sits with single-layer commodity lines, while premium capture belongs to sophisticated co-extrusion architectures serving regulated barrier film markets.
- Multi Layer:Seven-layer and nine-layer die configurations enable EVOH and nylon barrier architectures for extended shelf-life dairy and protein packaging. German and Dutch food processors dominate demand as EU Green Deal recyclability audits eliminate aluminum foil laminates.
- Co-extrusion:Specialized screw designs and enhanced cooling systems accommodate heat-sensitive barrier polymers transitioning into transparent flexible packaging. France's ANSM pharmaceutical-contact standards filter into converter procurement specifications for sterile barrier films.
- Single Layer:Commodity polyethylene lines serve high-volume agricultural mulch and industrial wrap applications with minimal barrier requirements.
- Turbo Blown:High-output configurations with accelerated cooling achieve micron-precision gauges for premium stretch film and collation shrink applications.
Today's leader: Multi Layer. Tomorrow's challenger: Co-extrusion.
Technology:
Automation intensity separates labor-cost-sensitive emerging markets from throughput-obsessed developed economies seeking OEE optimization.
- High-speed:Fully integrated process control systems sustain line speeds exceeding 500 meters per minute for North American food packaging converters facing resin volatility margin pressure. Real-time gauge control and automatic die adjustment minimize material giveaway.
- Automatic:Robotic roll handling and continuous web monitoring displace semi-automatic configurations in Benelux private-equity-backed converter roll-ups prioritizing operational flexibility.
- Semi-automatic:Intermediate automation levels persist in Spanish and Italian agricultural film operations with seasonal production patterns.
- Manual:Basic configurations remain viable for small-batch industrial wrap producers and developing market entry-level installations.
Automatic systems command current procurement volumes; high-speed lines are climbing the fastest as labor arbitrage opportunities diminish.
End User:
Application-specific barrier requirements and regulatory exposure create divergent equipment specification patterns across customer verticals.
- Packaging:Flexible film converters supplying regulated European markets drive specification of mono-material-capable co-extrusion lines with full material declaration compliance for REACH SVHC requirements.
- Agriculture:Large-scale greenhouse operators in Spain and Italy adopt automated lines for mulch and tunnel covers to reduce seasonal labor dependency and achieve consistent film durability.
- Automotive:Protective film applications for component shipping and surface protection demand puncture-resistant multi-layer architectures.
- Consumer Goods:Personal care and household product packaging requires print-ready film surfaces and consistent optical properties.
Packaging verticals absorb the dominant equipment flow; agriculture represents the steepest expansion trajectory as mechanization accelerates.
Application:
Regulatory stringency and performance specifications fragment demand across use cases with incompatible barrier and recyclability requirements.
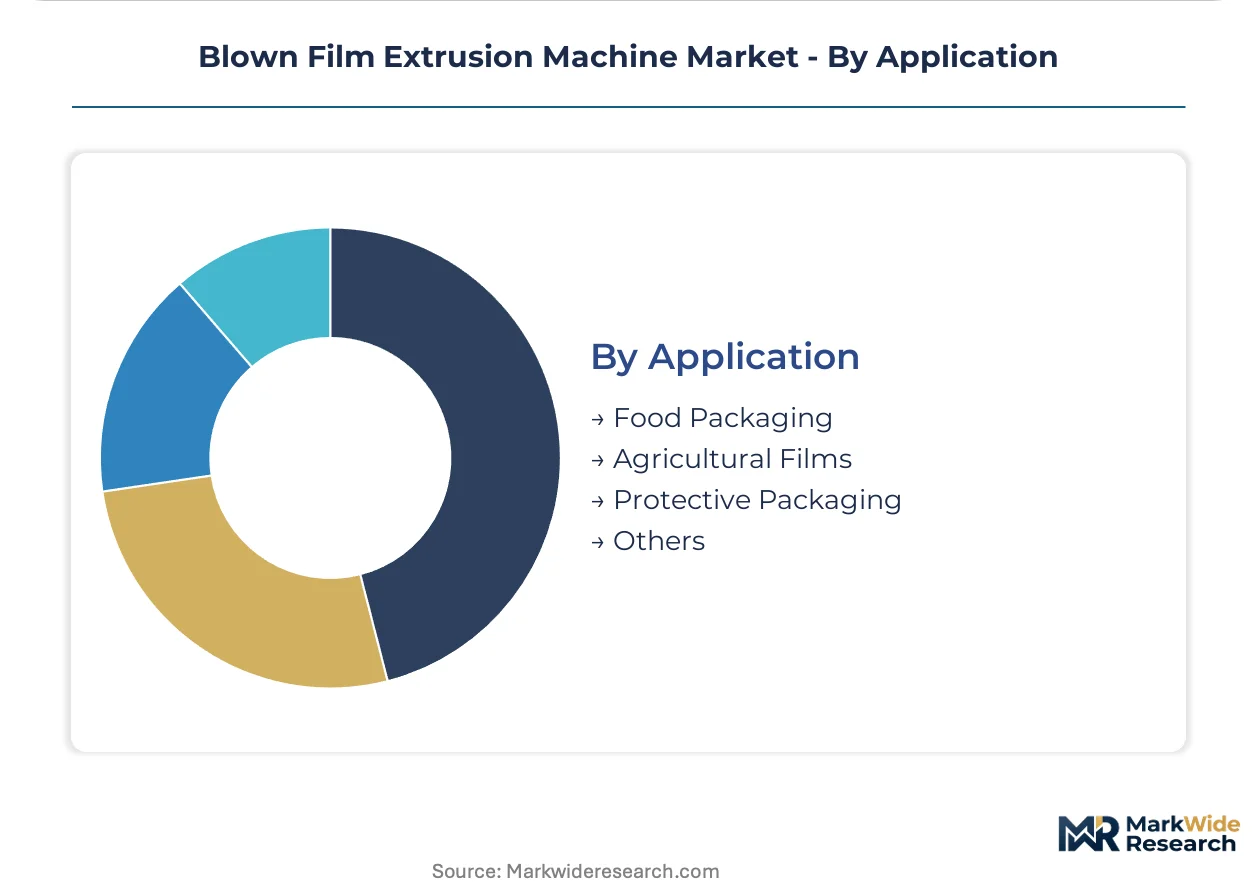
- Food Packaging:Barrier film producers in Germany expand capacity to serve export-oriented converters supplying EU-regulated markets with extended shelf-life solutions for fresh protein and dairy.
- Agricultural Films:Mulch and greenhouse cover applications prioritize UV stabilization and mechanical durability over optical precision, favoring robust single-layer and three-layer configurations.
- Protective Packaging:Industrial wrap and surface protection films emphasize puncture resistance and cling properties for automotive and electronics logistics.
- Others:Medical and pharmaceutical barrier applications impose ISO Class 7-8 cleanliness validation requirements with premium pricing tiers for qualified production lines.
Food Packaging leads current investment cycles; pharmaceutical-grade certification opens tomorrow's premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blown film extrusion machinery originated in German engineering workshops during the post-war plastics revolution, with Baden-Württemberg and Bavaria supplier clusters still anchoring precision component manufacturing. Today, demand distributes across regulated European markets, North American food packaging hubs, and emerging Asian converter bases.
Germany
Flexible film converters in Baden-Württemberg and Bavaria upgrade legacy lines to meet EU Green Deal recyclability mandates for mono-material architectures. The KBA enforces machinery safety standards that filter into export specifications for regulated European markets. Stuttgart and Munich engineering clusters supply precision drive systems and air rings to converters across the continent.
United States
Fresh protein and dairy processors in Wisconsin and California pull high-output co-extrusion lines with EVOH barrier layers for extended shelf-life packaging. FDA compliance requirements shape machinery specifications for food-contact film exports. Chicago and Milwaukee converter hubs concentrate demand for automated systems that minimize resin giveaway amid volatility.
India
Domestic flexible packaging growth in Maharashtra and Gujarat creates entry pathways for European and East Asian OEMs under PLI scheme incentives for food processing equipment. The BIS governs machinery safety standards that converge with import specifications. Ahmedabad and Mumbai converter clusters drive adoption of mid-tier automatic lines for snack and beverage packaging.
Italy
Large-scale greenhouse operators in Emilia-Romagna and Sicily adopt automated blown film lines for agricultural mulch and tunnel covers to reduce seasonal labor dependency. CE marking requirements align machinery specifications with broader European procurement standards. Bologna and Milan equipment distributors serve Mediterranean agricultural film demand.
China
Packaging machinery localization accelerates in Jiangsu and Zhejiang provinces as domestic converters scale capacity for e-commerce logistics films. GB standards and MIIT industrial policy shape equipment qualification timelines for both domestic and export markets. Ningbo and Suzhou manufacturing clusters integrate precision components from German and Japanese suppliers.
Blown Film Extrusion Machine Market Competitive Environment
Capital-heavy German engineering houses compete with asset-light Italian specialists and Asian fabricators across divergent price-performance tiers. The vendor base concentrates in Central European precision manufacturing clusters with secondary nodes in East Asian assembly operations. Three archetypes dominate: integrated process control specialists, modular platform designers, and cost-optimized volume producers. Competitive moves center on digital twin integration for remote service revenue and regional assembly partnerships to bypass tariff exposure.
Among German engineering houses, Reifenhäuser Blown Film GmbH and Windmöller & Hölscher KG exemplify the integrated process control archetype, while Bandera SpA represents Italian modular platform specialization. Zhejiang Zhuxin Machinery Co., Ltd. anchors the East Asian volume-optimized tier. These entities occupy positions across premium, mid-market, and economy pricing strata without overlapping customer segments.
| Leading Market Players |
|---|
| Bandera |
| Plastmach |
| Reifenhäuser Blown Film |
| Kappa |
| Colines |
| Windmöller & Hölscher |
| Macchi |
| Anger |
| Zhejiang Zhuxin Machinery |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal recyclability mandates for mono-material film architectures are forcing converters to specify machinery with full material declaration compliance, compelling OEMs to absorb certification costs and restructure component sourcing. This procurement shift concentrates pricing power with German engineering houses that control precision drive systems and air ring manufacturing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated process control specialists from modular platform designers and cost-optimized volume producers. Price differentiation hinges on automation intensity and REACH SVHC pre-certification status. Cost compression in mid-tier equipment is intensifying because corrosion-resistant bimetallic screw and barrel alloys carry substantial premiums over standard tool steel. Agricultural film producers in Southern Europe exhibit highest price sensitivity; pharmaceutical-grade film converters demonstrate lowest sensitivity due to Annex 1 compliance premiums.
Supply Chain Analysis
Regional distribution centers in Stuttgart and Munich anchor hub-and-spoke patterns serving European converter clusters, with secondary nodes emerging in Ningbo and Suzhou for Asia-Pacific demand. Manufacturing gravity centers on Germany, Italy, and China. Critical supply chains draw from Baden-Württemberg precision component clusters for drive systems and air rings. Single-source vulnerability concentrates in German engineering workshops for high-performance die heads. Distribution runs through captive leasing arms and machinery financiers offering throughput-guarantee arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory stringency creates premium pricing tiers unavailable in developing markets with less stringent chemical compliance frameworks.
For Market Incumbents: Deploy digital twin integration to convert hardware sales into recurring remote service revenue streams. Defensive priorities include backward integration into precision air ring manufacturing to reduce Baden-Württemberg supplier dependency, and pre-certification of lubricant formulations against ECHA SVHC list expansions to accelerate converter qualification timelines. Threats include asset-light Italian specialists capturing mid-market share through modular retrofits. For New Entrants and Emerging Players: Enter via PLI scheme partnerships in Maharashtra and Gujarat to establish assembly operations serving India's domestic flexible packaging growth without incurring full German engineering cost structures. White-space targets include mid-tier automatic lines for snack and beverage packaging, and pharmaceutical-grade film certification services for sterile barrier applications. Go-to-market angle should emphasize outcome-based contracting with throughput guarantees rather than capital purchase models. For Investors and Strategic Acquirers: Asymmetric upside sits with modular platform designers possessing established retrofit capabilities for legacy line Industry 4.0 integration. Long-term viability favors specialists with demonstrated seven-layer and nine-layer co-extrusion die expertise rather than commodity single-layer producers. Acquisition target archetype: Italian or East Asian fabricators with regional assembly partnerships and established pharmaceutical-contact certification pathways. Signal to watch: converter consolidation activity in Benelux private-equity roll-ups prioritizing operational flexibility over balance-sheet ownership.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Enables predictive maintenance algorithms and remote technical support revenue streams for OEMs. |
| Backward Integration into Precision Components | Reduces geographic single-point vulnerability from Baden-Württemberg supplier concentration. |
| Pharmaceutical-Grade Film Certification | Opens premium pricing tiers for lines validated to ISO Class 7-8 cleanliness standards under ANSM oversight. |
| Regional Assembly Partnerships | Bypasses tariff exposure and accelerates qualification timelines for PLI scheme incentives in India. |
| Outcome-Based Service Contracting | Displaces capital purchase models among margin-pressed converters facing resin volatility. |
Study Parameters
Multiple input streams — primary interviews with machinery OEM technical directors, flexible packaging converter procurement leads, and aftermarket service heads; secondary validation through customs/trade data, SEC machinery filings, and BIS equipment safety registrations — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification patterns across German, Italian, and Indian converter facilities. Secondary sources included ECHA SVHC candidate list documentation, FDA food-contact machinery guidance, and EU Green Deal implementation timelines.
Historical shipment data was cross-referenced against panel input from engineering houses and distribution channel partners to anchor projections. Segmentation modeling spanned product type layers, automation technology tiers, end-use verticals, and application-specific barrier requirements across the projection horizon. CAGRs were derived from demand elasticity analysis against regulatory mandate implementation schedules and resin transition timelines for aluminum foil laminate substitution.
Inputs from ECHA pre-certification databases and PLI scheme administrative records were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around equipment replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Global Wrapping Machine Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Case Packing Machines Market