
 Corrugated Paper Machine Market | 2026-2036
Corrugated Paper Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Paper Machine Market Outlook
E-commerce fulfillment centers are rotating demand away from traditional food-and-beverage converters toward electronics and direct-to-consumer packaging specialists. BHS Corrugated dominates high-speed corrugator installations for these automated warehouses across Central Europe. Isowa Corporation specializes in lean single-facer configurations that fit retrofit layouts in older Asian mill buildings. MarquipWardUnited controls the North American aftermarket for precision slitting and scoring modules.
A corrugated paper machine forms fluted medium between flat linerboards through heat, pressure, and adhesive bonding, typically operating at speeds exceeding 300 meters per minute on continuous rolls. Its primary purpose is producing engineered paperboard for protective shipping containers, retail displays, and industrial transit packaging. Flexo folder gluer lines lead volume output in mature markets where brand owners demand pre-printed retail-ready cases. Fully automatic technology is displacing semi-automatic configurations as labor costs rise and order batch sizes shrink. Digital print integration represents the fastest-growing capability segment, enabling variable-data graphics without plate changes.
The EU F-Gas Regulation and REACH compliance frameworks restrict solvent-based adhesives and certain thermal fluids in corrugator heating systems, pushing OEMs toward water-based starch formulations and electric infrared drying. The EPA enforces Maximum Achievable Control Technology standards on US paper machine emissions, affecting dryer section energy profiles and wet-end chemistry choices. Stakeholders must monitor how California's SB 54 extended producer responsibility rules cascade into box specifications and recycled-content mandates across North American supply chains.
Market Dynamics
Automated box-making lines are compressing order batch sizes across e-commerce fulfillment networks, forcing corrugator OEMs to engineer modular single-facer configurations that retrofit legacy mill footprints without structural demolition.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for lighter flute profiles and fiber-based plastic alternatives are accelerating converter investment in precision micro-flute corrugators across Germany, France, and the Netherlands.
- Digital print integration:Variable-data graphics capability eliminates plate-change downtime, enabling electronics and direct-to-consumer packaging specialists to run shorter production cycles profitably.
- Central European machinery cluster:Dense supplier networks near the Dutch-German border reduce lead times for high-speed corrugator components and specialized aftermarket service.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container stock prices fluctuate with municipal collection efficiency and export demand from Asian packaging mills, squeezing converter margins unpredictably.
- Heating system reconfiguration:EU F-Gas Regulation phase-downs of hydrofluorocarbon thermal fluids force capital-intensive retrofits of corrugator drying sections toward electric infrared or water-based starch systems.
- Substitute material encroachment:Molded pulp and expanded polystyrene alternatives capture protective packaging share in temperature-sensitive pharmaceutical and fresh-produce segments.
Strategic Opportunities
- India packaging modernization:BIS certification requirements and FSSAI food-contact standards are driving domestic converter upgrades from manual slotters to automatic flexo folder gluer lines.
- California SB 54 cascade:Extended producer responsibility rules are propagating recycled-content mandates through North American brand-owner specifications, favoring machinery with inline quality verification.
- Convergence of AI vision and corrugator control:Real-time flute profile adjustment combined with predictive maintenance algorithms reduces waste in high-mix, low-volume production environments.
Industry Challenges
- Controls engineering talent scarcity:Servo drive programming and HMI integration expertise for Industry 4.0 retrofits outpaces vocational training pipeline output in Midwestern US manufacturing corridors.
- Legacy wet-end chemistry incompatibility:Water-based adhesive formulations required by REACH compliance often degrade performance on corrugators originally specified for solvent-bonded starch systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Paper Machine Market |
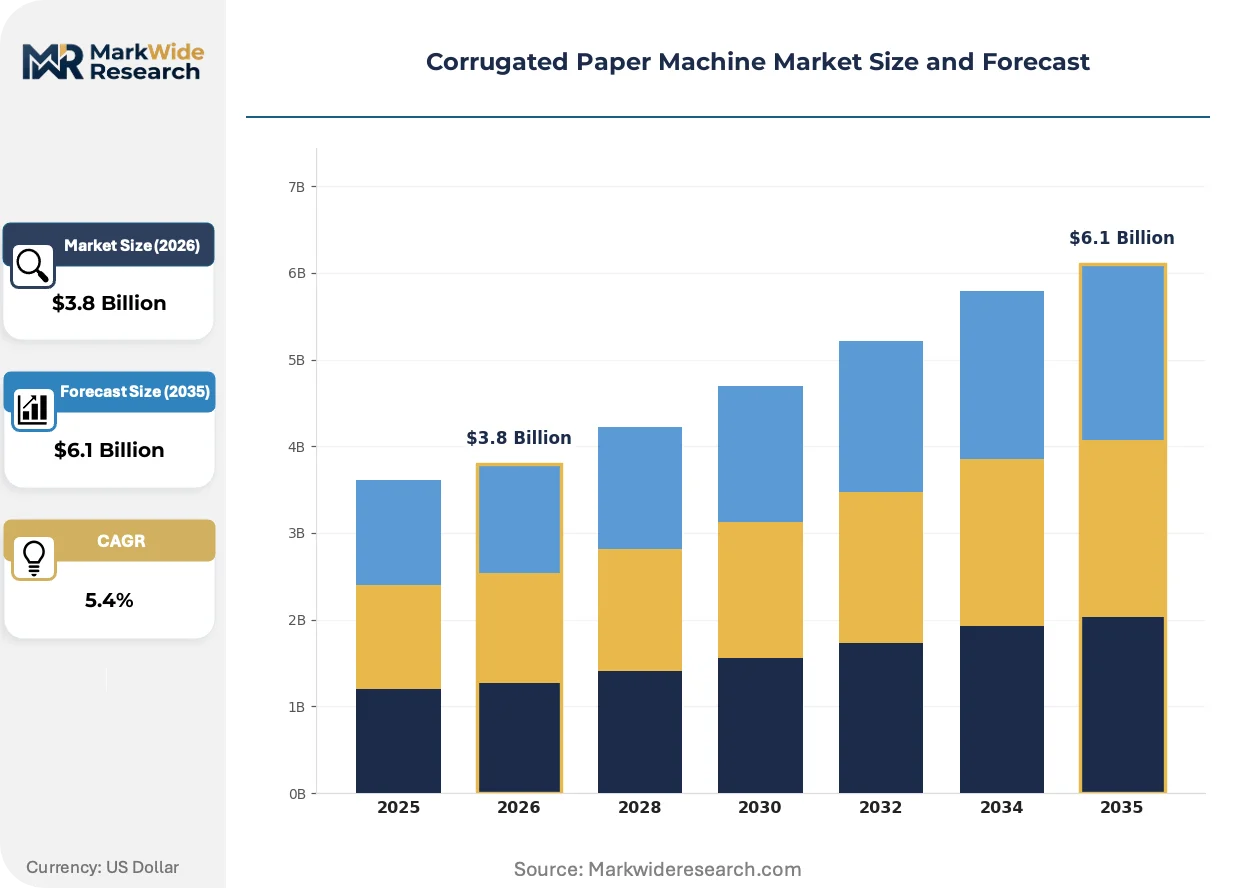
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Facer, Double-Backer, Flexo Folder Gluer, Rotary Die Cutter Technology: Mechanical, Semi-Automatic, Fully Automatic, Digital End User: Packaging Industry, Food & Beverage, Electronics, E-commerce Form: Flat Sheet, Pre-Cut Shapes, Roll, Box |
| Companies Covered | MarquipWardUnited, Isowa Corporation, BHS Corrugated, Hebei Shengli, Bobst Group SA, Fosber Group, BW Papersystems, Andritz, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Paper Machine Market Strategic Shifts
Corrugator architecture is fragmenting into modular subsystems that permit incremental automation rather than greenfield replacement, reflecting capital discipline among packaging converters facing compressed return-on-asset timelines.
Digital print units integrated downstream of the double backer are decomposing the traditional separation between corrugated board production and finished box graphics. Electronics fulfillment centers in Germany and the Netherlands are adopting these configurations to eliminate pre-print inventory risk. The technology is decomposing volume thresholds that historically justified rotary die cutting and separate print house relationships.
REACH authorization requirements for formaldehyde-releasing adhesives are compelling wet-end chemistry reformulation across EU-27 converter operations. The regulation compresses allowable emission profiles from corrugator starch kitchens and hot-plate sections. German machinery OEMs are responding with closed-loop adhesive preparation systems that recover thermal energy from exhaust streams.
Brand-owner specification of retail-ready cases is shortening procurement cycles from annual blanket orders to quarterly SKU-specific tenders. North American grocery and mass-merchandise channels are unbundling corrugator maintenance contracts from original equipment supply, creating independent service-provider opportunities in precision slitting and scoring module overhaul. This behavioral shift concentrates aftermarket revenue with specialized technicians rather than full-line OEMs.
Corrugated Paper Machine Market Segmentation
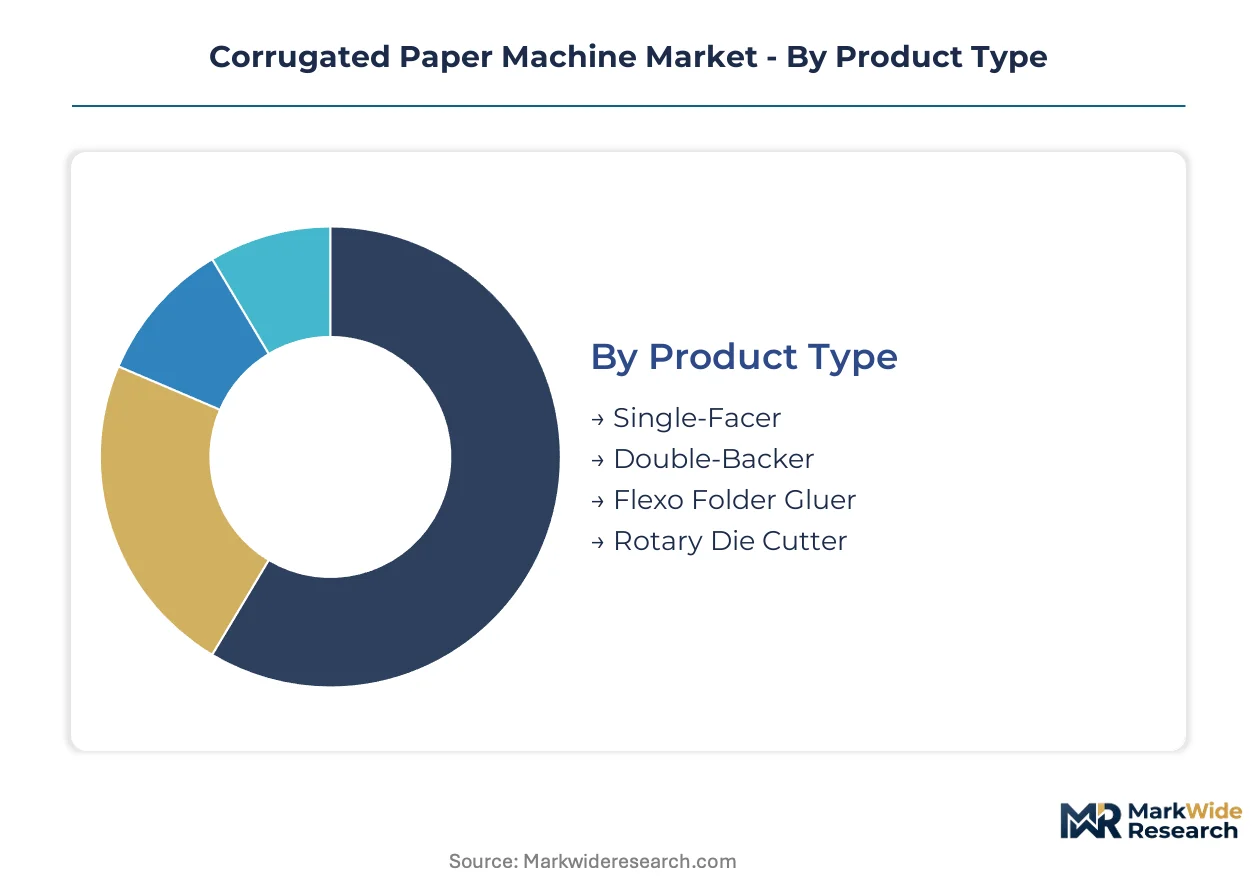
Corrugated paper machine procurement patterns diverge sharply between export-oriented board producers and domestic box converters. Understanding these segment boundaries clarifies why certain configurations dominate specific geographies while others remain niche.
Product Type:
Domestic fulfillment networks in Germany and the Netherlands favor integrated lines that compress board production and box conversion into single footprints. Export-led mills across India and Southeast Asia prioritize standalone components that retrofit existing wet-end infrastructure.
- Single-Facer:Forms the fluted medium layer between steam-heated corrugating rolls at speeds exceeding 300 meters per minute. Demand concentrates in legacy Asian mill retrofits where Isowa Corporation's lean configurations fit constrained building envelopes without structural demolition.
- Double-Backer:Bonds single-faced board to linerboard through heated pressure plates and adhesive application. German e-commerce fulfillment centers specify these modules for automated warehouse integration, driven by dimensional weight reduction mandates from parcel carriers.
- Flexo Folder Gluer:Prints, scores, folds, and adhesively seals corrugated blanks into finished boxes in continuous operation. Food-contact converters in India upgrade manual slotters to these lines under FSSAI hygiene standards.
- Rotary Die Cutter:Cuts complex shapes from corrugated sheets using cylindrical cutting dies on vacuum transfer systems. Electronics packaging specialists deploy these for retail-ready case geometries with tight dimensional tolerances.
Flexo folder gluer lines command the established base across mature markets. The steepest expansion runs through single-facer retrofits in emerging Asian board production.
Technology:
Capital deployment splits between premium automation tiers serving labor-constrained European markets and cost-optimized mechanical systems sustaining volume throughput in developing economies.
- Mechanical:Cam-driven timing and manual adjustment systems requiring skilled operator intervention. Indian domestic converters maintain these configurations for commodity box grades where labor cost arbitrage sustains viability.
- Semi-Automatic:Partial servo control with manual load/unload stations. Mid-tier European converters retain these for seasonal demand spikes where full automation cannot justify capital recovery timelines.
- Fully Automatic:Complete servo drive integration with automatic splicers, wash-up systems, and waste ejection. German electronics fulfillment centers mandate these specifications to eliminate touch labor from high-mix production schedules.
- Digital:Inkjet or toner-based print units integrated downstream of board production, enabling variable-data graphics without plate manufacture. Dutch direct-to-consumer packaging specialists adopt these for SKU-specific tender requirements that compress procurement cycles.
Fully automatic systems anchor revenue concentration in Central European machinery clusters. Digital configurations are expanding most quickly as brand-owner specifications decompose traditional volume thresholds for customized graphics.
End User:
Demand fragmentation accelerates as e-commerce fulfillment networks displace traditional food-and-beverage converters from technology leadership positions.
- Packaging Industry:Independent converters serving multiple brand owners with standardized RSC and die-cut configurations. German machinery OEMs dominate specification-setting for these volume producers through bundled maintenance contracts.
- Food & Beverage:Hygienic board production with moisture-resistant barriers and direct-contact compliance. REACH adhesive restrictions and FSSAI standards jointly reshape wet-end chemistry specifications across EU-27 and Indian operations.
- Electronics:Anti-static coatings, precision scoring, and retail-ready graphics for high-value device protection. Netherlands-based fulfillment centers specify micro-flute profiles to minimize dimensional weight charges on air freight.
- E-commerce:Right-sized box algorithms and on-demand print for direct-to-consumer shipment protection. California SB 54 extended producer responsibility rules propagate recycled-content mandates through these specifications.
Food and beverage applications retain the installed base majority. Electronics and e-commerce fulfillment are climbing the fastest as order batch sizes compress and graphics customization requirements intensify.
Form:
Physical output configurations align with downstream automation requirements in recipient facilities, from flat sheet palletization to erect-ready case delivery.
- Flat Sheet:Uncut corrugated board in master roll or palletized sheet format for downstream converter processing. Export-oriented mills in India ship these to domestic box plants lacking integrated corrugators.
- Pre-Cut Shapes:Die-cut blanks requiring only folding and gluing for final assembly. European display packaging specialists source these for point-of-sale assembly with minimal labor.
- Roll:Continuous wound single-face or double-face board for in-line conversion operations. Automated German box-making lines consume these formats to eliminate sheet handling stages.
- Box:Finished erected cases ready for immediate product loading. E-commerce fulfillment networks in the Netherlands specify these from toll converters to compress dock-to-stock intervals.
Flat sheet shipments dominate inter-regional trade volumes. Finished box delivery is gaining share fastest among urban fulfillment networks optimizing last-mile logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce fulfillment operators concentrate procurement authority in Germany and the Netherlands, while export-oriented board producers dominate investment flows across India and Southeast Asia. Machinery specification patterns diverge sharply between these buyer archetypes.
Germany
Automated warehouse networks along the Dutch border specify high-speed corrugators for dimensional weight reduction. The EU F-Gas Regulation phases down hydrofluorocarbon thermal fluids, forcing dryer section retrofits toward electric infrared systems. The machinery cluster near Düsseldorf anchors component supply chains for Central European converter upgrades.
United States
California SB 54 extended producer responsibility rules propagate recycled-content mandates through brand-owner box specifications. The EPA enforces Maximum Achievable Control Technology standards on paper machine emissions, reshaping wet-end chemistry choices. Midwestern manufacturing corridors face controls engineering talent scarcity for Industry 4.0 servo drive programming.
India
Domestic converter upgrades from manual slotters to automatic flexo folder gluer lines accelerate under FSSAI food-contact standards. BIS certification requirements tighten quality verification protocols for packaging materials. Gujarat and Maharashtra host the densest concentrations of retrofit single-facer installations serving regional fulfillment networks.
Netherlands
Direct-to-consumer packaging specialists adopt digital print integration downstream of double backers to eliminate pre-print inventory risk. REACH authorization requirements for formaldehyde-releasing adhesives compel wet-end chemistry reformulation. The Randstad logistics hub concentrates demand for right-sized box algorithms and on-demand graphics.
China
Export-oriented mills prioritize standalone corrugator components that retrofit existing wet-end infrastructure rather than greenfield lines. The country's national environmental regulator tightens emission profiles from starch kitchens and hot-plate sections. Yangtze River Delta converters experiment with micro-flute profiles for electronics air freight protection.
Corrugated Paper Machine Market Competitive Environment
Player mix skews toward European full-line OEMs with bundled aftermarket service contracts, Japanese precision specialists focused on lean single-facer configurations, and North American precision module providers controlling slitting and scoring aftermarket revenue. Two strategic archetypes dominate: integrated corrugator system houses and component specialists serving retrofit markets. Competitive moves concentrate on modular subsystem development for incremental automation and geographic expansion through localized service partnerships.
Within the European integrated tier, BHS Corrugated and Fosber Group exemplify full-line system houses anchoring specification-setting authority through dense supplier networks near the Dutch-German border. Isowa Corporation occupies a position among Japanese precision specialists, representing lean configuration expertise for constrained Asian mill footprints. These three companies collectively illustrate how regional machinery clusters shape competitive positioning through proximity to concentrated buyer demand.
| Leading Market Players |
|---|
| MarquipWardUnited |
| Isowa Corporation |
| BHS Corrugated |
| Hebei Shengli |
| Bobst Group SA |
| Fosber Group |
| BW Papersystems |
| Andritz |
| Mitsubishi Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for precision slitting modules from German component suppliers concentrate pricing power with BHS Corrugated and Fosber Group near the Dutch border, while Asian retrofit buyers face cost premiums on lean single-facer configurations shipped from Japanese precision specialists.
Pricing Analysis
Current-generation fully automatic corrugators command 40-60% premiums over semi-automatic configurations, with next-generation digital-integrated lines widening the gap further. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and certification grade differentiation under EU F-Gas Regulation compliance. Pricing pressure stems from recycled fiber cost volatility squeezing converter capital budgets. Domestic fulfillment networks in Germany and the Netherlands show least price sensitivity due to dimensional weight charge avoidance, while Indian commodity box converters operate at highest sensitivity.
Supply Chain Analysis
Inventory cycles for corrugator heating systems stretch to sixteen weeks as EU F-Gas Regulation phase-downs disrupt thermal fluid availability. Component manufacturing concentrates in Germany, Japan, and China, with precision servo drives and HMI modules drawing from German engineering clusters. Steel corrugating rolls, ceramic coating services, and water-based adhesive formulations constitute critical input dependencies. Single-source vulnerability runs through specialized corrugating roll grinding capacity concentrated near Düsseldorf. Distribution runs through OEM-direct channels for greenfield installations and independent service providers for aftermarket retrofit modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce fulfillment network consolidation into Germany and the Netherlands shifts procurement leverage toward automated warehouse operators, fragmenting traditional converter buying power across smaller electronics packaging specialists.
For Market Incumbents: Secure aftermarket service contract renewals through predictive maintenance algorithm deployment, defending against independent slitting module specialists unbundling maintenance from original equipment supply. Deepen upstream control over ceramic coating services for corrugating rolls to lock in roll refurbishment revenue streams threatened by Chinese component entrants. For New Entrants and Emerging Players: Aftermarket AI vision integration for legacy wet-end systems presents a service-layer gap where incumbents under-serve Midwestern US converters facing controls engineering talent scarcity. Target modular single-facer retrofits in Gujarat and Maharashtra where FSSAI compliance deadlines accelerate manual slotter replacement. Lead with subscription-based predictive maintenance pricing to bypass capital-intensive equipment financing barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected corrugator component divisions lacking digital integration roadmaps. Long-term viability hinges on water-based adhesive formulation expertise as REACH restrictions expand. Watch for EU Packaging and Packaging Waste Regulation enforcement intensity as the inflection signal for micro-flute capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Single-Facer Retrofit | Enables Asian mill automation without structural demolition, addressing constrained building envelopes in India. |
| Digital Print Integration | Eliminates pre-print inventory risk for Dutch direct-to-consumer packaging specialists facing SKU proliferation. |
| Predictive Maintenance Platform | Reduces waste in high-mix German electronics fulfillment centers through real-time flute profile adjustment. |
| Water-Based Adhesive Formulation | Ensures REACH compliance for EU-27 converters while recovering thermal energy from exhaust streams. |
| Regional Service Partnership | Compresses lead times for California SB 54-mandated inline quality verification module deployment. |
Study Parameters
The analysis maps single-facer, double-backer, flexo folder gluer, and rotary die cutter sub-sectors, each validated through converter procurement directors, OEM sales engineers, aftermarket service technicians, and regulatory compliance officers across Germany, the United States, India, and the Netherlands. Primary interview intelligence triangulates against customs trade records for corrugator component imports, EU F-Gas Regulation implementation timelines, EPA Maximum Achievable Control Technology enforcement patterns, and SEC filings from disclosed packaging machinery revenue streams. Bottom-up equipment installation tracking and top-down converter capital expenditure surveys reconcile volume and value estimates.
Forecast outputs were validated against external benchmarks including regional paperboard production capacity expansions, e-commerce fulfillment square footage growth, and REACH adhesive authorization schedules. Segmentation modeling spans product type, automation technology tier, end-use industry, and geographic machinery cluster. CAGRs derive from equipment replacement cycle analysis and incremental automation penetration curves. Key inputs include labor cost arbitrage thresholds for semi-automatic versus fully automatic configuration decisions, and digital print adoption rates among direct-to-consumer packaging specialists.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules, California SB 54 extended producer responsibility implementation, and Indian FSSAI food-contact standard enforcement; material policy accelerations or delays would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
Automated Poly Bagging Machines Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Packaging Machine Heaters Market