
 Romania Telecom Market | 2026-2036
Romania Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Telecom Market Insights
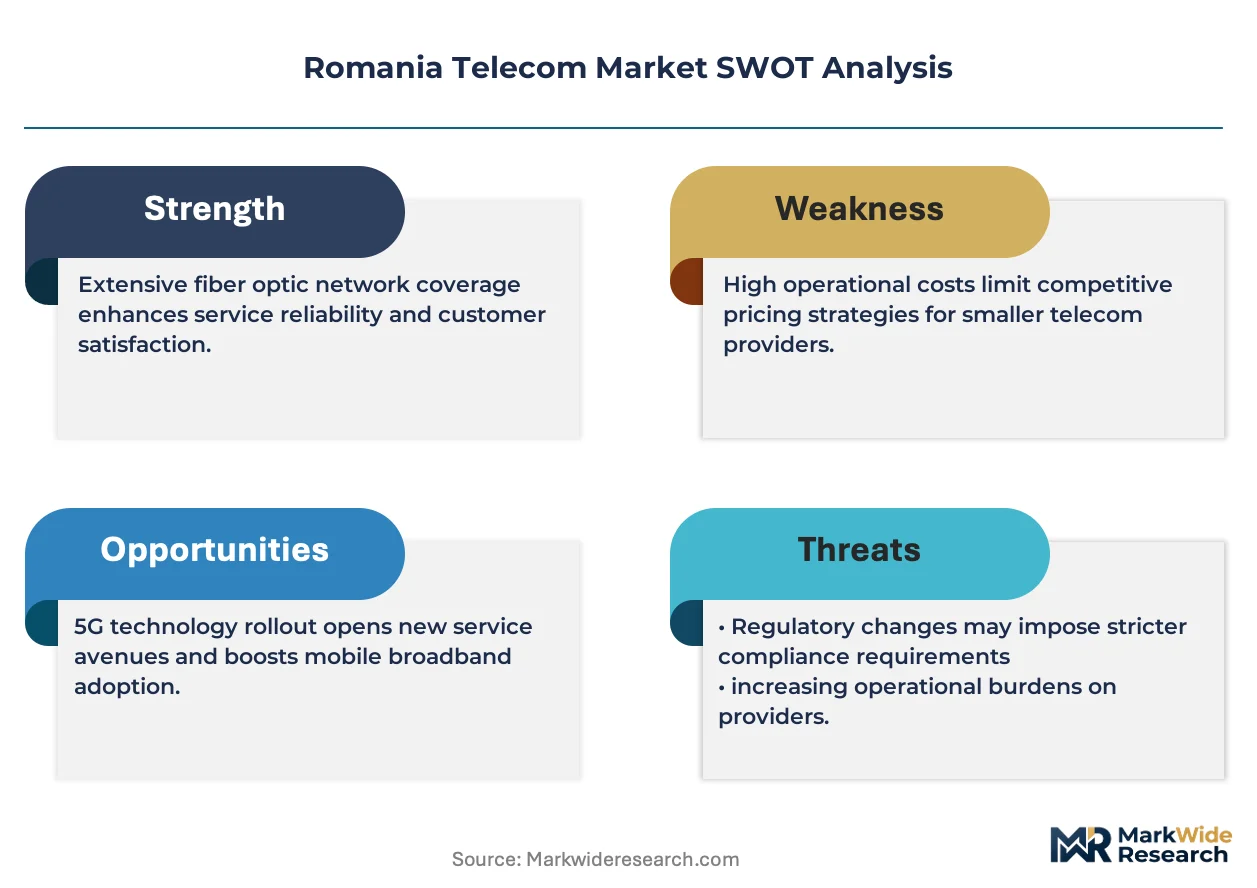
ANCOM's 5G spectrum auction conditions is expanding the capital threshold for new market entrants, favoring incumbents with existing infrastructure leverage. Orange Romania sustains nationwide coverage density through aggressive fiber-to-the-home expansion. Vodafone Romania anchors its position in enterprise mobility and IoT verticals. Digi Communications dominates the residential broadband segment with price-disruptive gigabit offerings.
Romania Telecom encompasses fixed and wireless communication infrastructure delivering voice, data, and video services across copper, fiber, and radio access networks operating at frequencies from 700 MHz to 3.5 GHz and beyond. The sector enables digital commerce, remote work, industrial automation, and public administration through guaranteed quality-of-service parameters including latency below 10 ms for 5G ultra-reliable applications. Fiber optic infrastructure captures the dominant share of fixed-line investment as operators replace aging DSL footprints with GPON and XGS-PON architectures capable of symmetric 10 Gbps delivery. Mobile voice and Internet access services generate the largest revenue pools, though IPTV and bundled convergent packages are deepening customer stickiness and average revenue per user. Enterprise customer segments represent the fastest-growing demand vector as Romanian manufacturers adopt private 5G networks and cloud-edge integration.
ANCOM enforces network security standards and interconnection tariffs that directly shape operator cost structures and retail pricing flexibility. The European Electronic Communications Code, transposed into Romanian law, mandates universal service obligations and infrastructure sharing requirements that reduce duplication in rural coverage. GDPR compliance costs and data localization expectations from Romanian enterprise clients add operational complexity for cloud-dependent service portfolios. Stakeholders must monitor ANCOM's pending decisions on mmWave spectrum licensing and wholesale access pricing, as these will determine whether challenger operators can achieve viable economics in enterprise 5G and fixed wireless access.
Market Dynamics
ANCOM's spectrum reallocation mandates are compressing infrastructure modernization timelines across Romanian operators, forcing simultaneous fiber densification and 5G radio access network deployment while enterprise cloud connectivity demand accelerates among manufacturers.
Growth Catalysts
- Enterprise cloud-edge integration:Romanian manufacturers and logistics operators are adopting private 5G networks to synchronize industrial automation with real-time data processing, creating dedicated connectivity demand that bypasses public network congestion.
- ANCOM infrastructure sharing requirements:The European Electronic Communications Code transposition mandates reduce rural coverage duplication costs, enabling faster geographic expansion through co-location agreements on cell towers and fiber ducts.
- Smart city investments in Bucharest and Cluj-Napoca:Municipal IoT deployments for traffic management, energy grids, and public safety are concentrating procurement volumes and justifying fiber-to-the-premises overbuild in urban cores.
Market Restraints
- Capex intensity of GPON-to-XGS-PON upgrades:The full replacement of aging DSL access nodes with symmetric 10 Gbps-capable fiber terminals requires substantial sunk investment before revenue recognition from higher-tier service tiers.
- Romanian enterprise data localization expectations:GDPR compliance costs and domestic server requirements for cloud-dependent service portfolios add operational complexity that slows multinational operator entry.
- Copper network maintenance drag:Incumbent operators retain legacy DSL infrastructure obligations under universal service mandates, diverting technical resources from next-generation deployment priorities.
Strategic Opportunities
- Transylvania manufacturing corridor private networks:Industrial zones around Cluj-Napoca and Timișoara remain underpenetrated by dedicated 5G campus deployments, offering first-mover positioning for system integrators with radio access network expertise.
- Fixed wireless access in secondary cities:mmWave spectrum licensing pending at ANCOM would enable 5G-based broadband competition against fiber in Brașov, Constanța, and Iași where trenching costs delay wireline buildouts.
- Convergent IPTV-broadband-mobile bundles:Residential customer stickiness deepens through triple-play packaging that locks in longer contract terms and reduces quarterly churn volatility.
Industry Challenges
- Radio frequency engineer scarcity:Romanian technical universities produce insufficient graduates with 5G network planning and optimization skills, forcing operators to recruit from competing Eastern European markets at wage premiums.
- Legacy billing system integration:Convergent service packaging requires real-time rating engines that interoperate with decade-old copper-era subscriber management platforms, extending IT transformation timelines.
- ANCOM wholesale access pricing uncertainty:Pending decisions on unbundled fiber loop rates and bitstream margins create investment planning ambiguity for challenger operators assessing retail market entry economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Telecom Market |
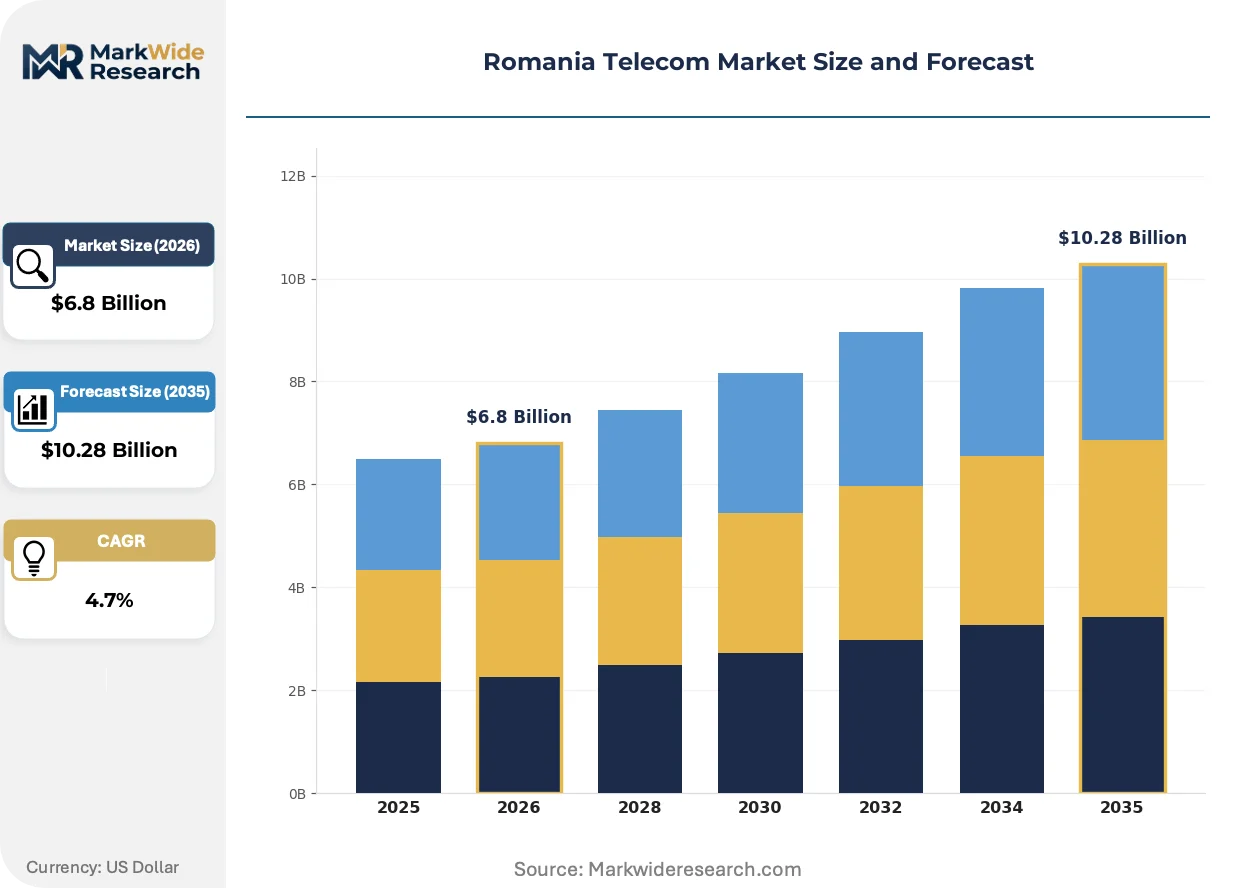
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 5G, 4G, Fiber Optic, DSL Service Type: Mobile Voice, Internet Access, IPTV, VoIP Customer Type: Residential, Small Business, Enterprises, Government Pricing Model: Prepaid, Postpaid, Bundled, Pay-As-You-Go |
| Companies Covered | Orange Romania, Vodafone Romania, Digi Communications, Telekom Romania, RCS & RDS, UPC Romania, Lycamobile Romania, NextGen Communications, GTS Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Telecom Market Trends and Innovations
XGS-PON fiber technology is rewriting bandwidth economics for Romanian residential and enterprise segments simultaneously, collapsing the cost per gigabit delivered while enabling symmetric upload speeds that support remote work and cloud application performance.
Open RAN architectures are rewriting vendor lock-in dynamics for Romanian mobile operators. Diversified radio unit suppliers and cloud-native baseband software are reducing dependence on single-source equipment providers. Orange Romania and Vodafone Romania are trialing multi-vendor deployments in Bucharest metro cells to validate interoperability before national scaling.
ANCOM's pending mmWave spectrum licensing framework is compressing fixed wireless access deployment timelines. The regulator's consultation on 26 GHz and 28 GHz band rules will determine whether operators can bypass fiber trenching in secondary cities. Rural municipalities and suburban residential clusters stand to benefit most from accelerated broadband competition if auction conditions favor infrastructure-light market entry.
Enterprise procurement of network services is consolidating toward outcome-based connectivity contracts. Romanian manufacturers are shifting from bandwidth purchases to guaranteed latency and uptime agreements with penalty clauses. Automotive suppliers in Argeș and Prahova counties are pioneering this model, requiring operators to assume operational risk for production line continuity.
Romania Telecom Market Segmentation
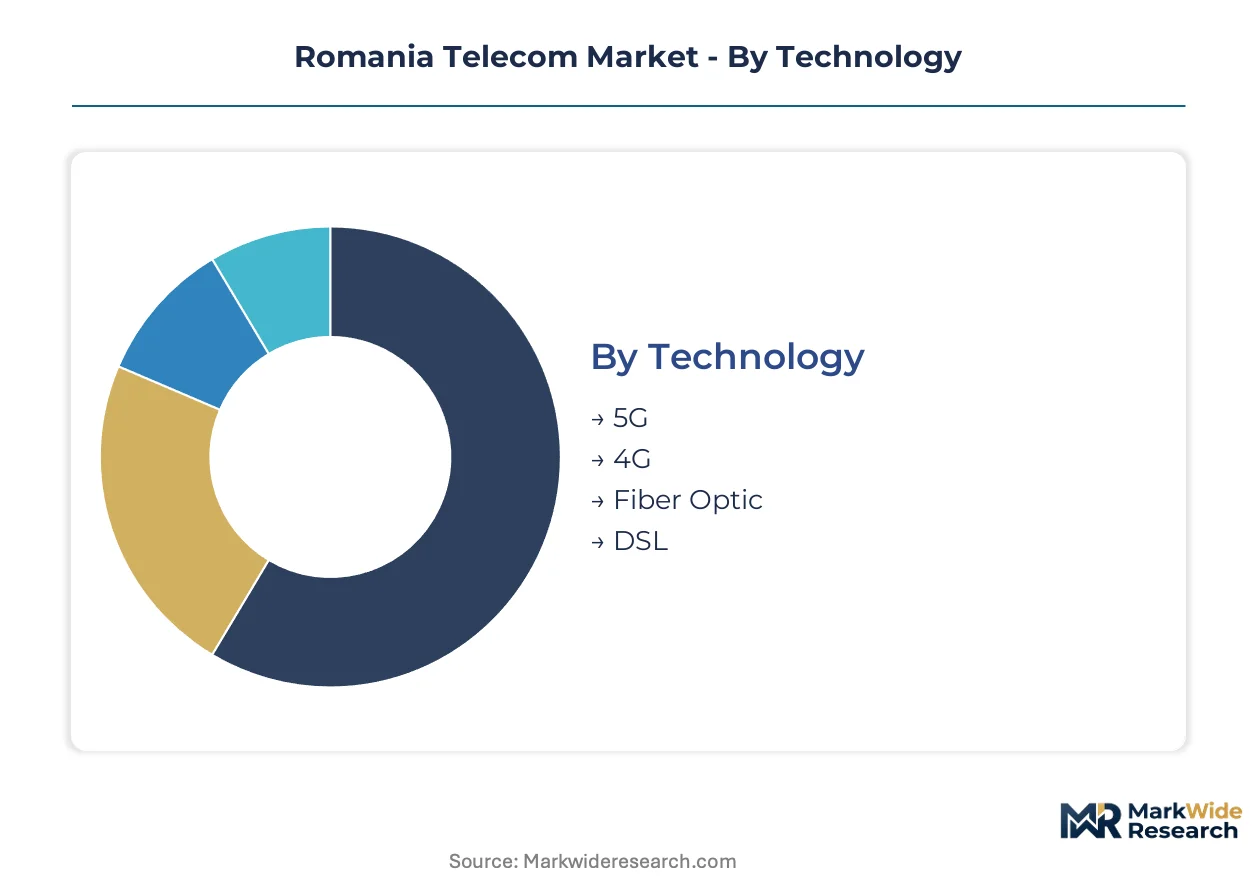
Romania's telecom infrastructure replacement cycles create distinct investment windows across technology generations. Service bundling patterns and customer procurement maturity further stratify addressable revenue pools. Understanding these segment boundaries clarifies where operators must prioritize capital deployment against ANCOM-mandated modernization deadlines.
Technology:
Upgrade cycles from legacy copper to fiber and from 4G to 5G radio access networks are compressing timelines as ANCOM spectrum reallocation forces simultaneous multi-generation deployment.
- 5G:New radio access networks operating at 700 MHz, 3.5 GHz, and pending mmWave bands deliver sub-10 ms latency for industrial automation. Demand concentrates in Bucharest and Cluj-Napoca manufacturing corridors where private network deployments bypass public congestion.
- Fiber Optic:GPON and XGS-PON architectures replace aging DSL nodes with symmetric 10 Gbps capability. Romanian residential clusters and enterprise parks in Transylvania drive trenching investments as operators compete on gigabit speed tiers.
- 4G:Existing LTE infrastructure provides coverage continuity during 5G non-standalone transition phases. Rural municipalities and secondary cities rely on 4G fixed wireless access where fiber economics remain prohibitive.
- DSL:Copper-based asymmetric digital subscriber line technology retains universal service obligations in remote localities. Maintenance costs divert technical resources from next-generation priorities despite declining subscriber bases.
Fiber Optic sits at the top of the volume ranking, with 5G climbing the fastest.
Service Type:
Revenue concentration patterns across service categories reflect shifting customer willingness to pay for guaranteed quality versus best-effort delivery.
- Internet Access:Fixed and mobile broadband connectivity generates the largest revenue pool through tiered speed-based pricing. Romanian remote work adoption and cloud application dependency sustain demand for upload symmetry that fiber uniquely delivers.
- Mobile Voice:Traditional circuit-switched and VoLTE calling services retain sticky subscriber relationships despite declining per-minute yields. Enterprise mobility contracts in logistics and field services anchor B2B voice volumes.
- IPTV:Internet protocol television delivery over fiber and 4G/5G networks deepens residential customer stickiness through triple-play bundling. Urban households in Bucharest and Cluj-Napoca drive premium content tier subscriptions.
- VoIP:Session initiation protocol-based voice services enable cost-disruptive enterprise communications and international calling. Small business segments in secondary cities adopt hosted PBX solutions to replace legacy on-premise hardware.
Internet Access commands the dominant revenue share, with IPTV expanding most quickly through convergent packaging.
Customer Type:
Procurement sophistication and contract scale vary dramatically across customer categories, dictating sales motion complexity and service level guarantee requirements.
- Enterprises:Large manufacturers and logistics operators purchase outcome-based connectivity with guaranteed latency and uptime penalties. Automotive suppliers in Argeș and Prahova counties pioneer private 5G campus networks for production line continuity.
- Residential:Individual households select speed-tiered broadband and bundled entertainment services on 12-24 month contracts. Price sensitivity in secondary cities sustains Digi Communications' gigabit disruption against incumbent fiber offerings.
- Small Business:Shops, professional services, and regional distributors require reliable connectivity without dedicated network engineering resources. Managed WiFi and converged voice-data packages reduce internal IT burden for this segment.
- Government:Public administration and municipal entities procure through framework agreements with security and data localization requirements. Smart city deployments in Bucharest concentrate IoT connectivity demand for traffic and energy management.
Residential subscribers form the volume base, with Enterprises gaining share fastest through private network premiums.
Pricing Model:
Customer liquidity preferences and usage predictability determine model selection, with bundled offerings capturing the highest lifetime value.
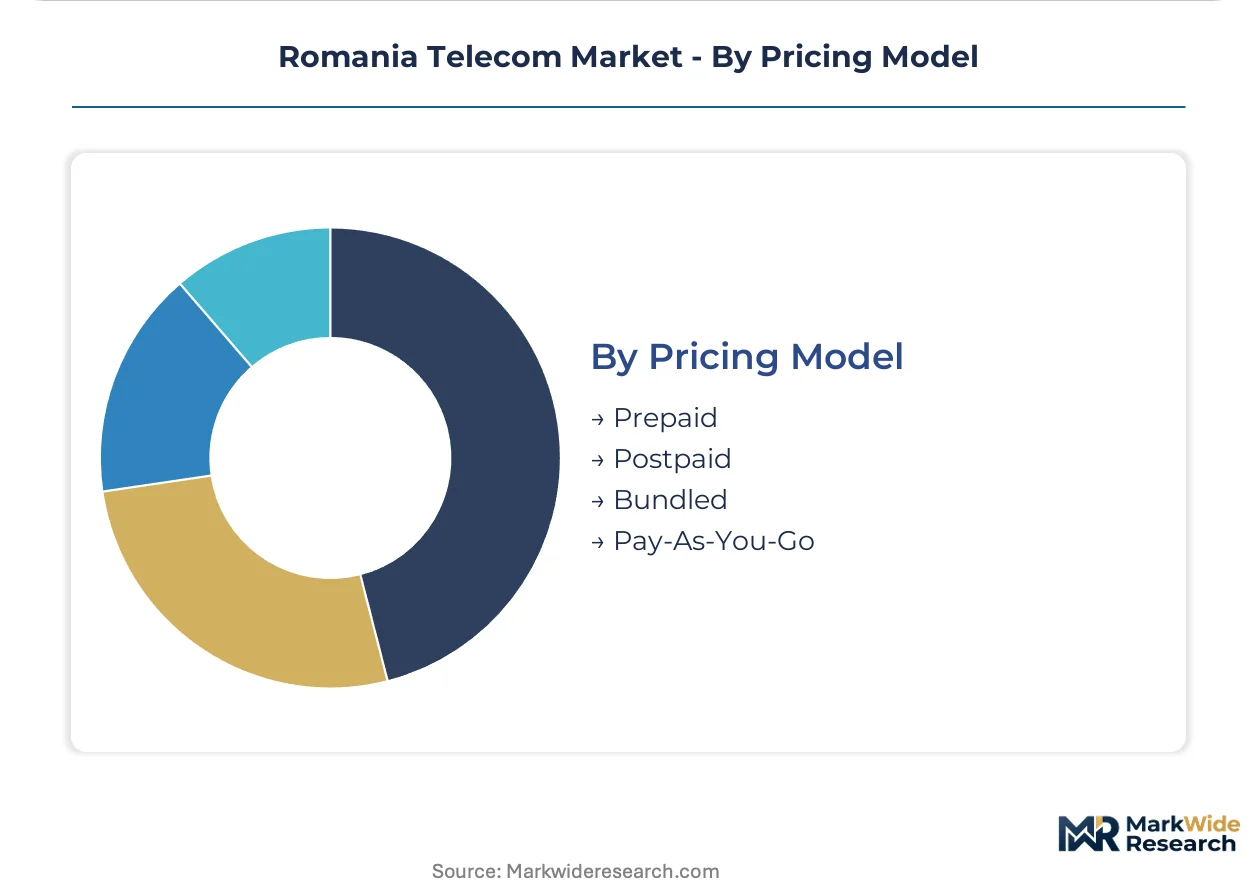
- Bundled:Triple-play and quad-play packages combine fixed broadband, mobile, IPTV, and voice into single-contract offerings. Romanian households in urban centers accept longer terms in exchange for discounted effective per-service pricing.
- Postpaid:Monthly invoiced contracts with committed usage allowances dominate enterprise and affluent residential segments. Credit verification requirements and early termination penalties reduce churn volatility for operators.
- Prepaid:Top-up based mobile services serve price-sensitive subscribers and temporary residents without banking relationships. Young demographics and rural populations sustain this model despite smartphone data consumption growth.
- Pay-As-You-Go:Pure consumption-based billing without base fees appeals to highly variable usage patterns. IoT device fleets and seasonal business applications occasionally deploy this model for cost control.
Postpaid arrangements anchor operator cash flow stability, with Bundled packages showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romania's telecom infrastructure emerged from the post-communication era through state-owned Romtelecom, with modernization accelerating after EU accession in 2007 and the entry of multinational operators seeking Eastern European expansion corridors.
Bucharest-Ilfov
Enterprise demand from financial services and technology sectors drives fiber densification across the capital region. ANCOM's spectrum auction conditions concentrate 5G deployment investment here first. Data center clustering in Pipera and Otopeni zones anchors cross-border connectivity routes toward Bulgaria and Hungary.
Cluj-Napoca and Transylvania
Manufacturing automation in automotive and electronics supplier parks creates private network procurement volumes. The European Electronic Communications Code infrastructure sharing rules reduce duplication costs across hilly terrain. Smart city investments in traffic management and energy grids justify fiber-to-the-premises overbuild in the urban core.
Timișoara and Western Banat
Logistics operators serving Hungarian and Serbian border crossings adopt cloud-edge integration for warehouse automation. GDPR compliance requirements from German-owned manufacturing subsidiaries shape local data center placement decisions. Industrial zones around Recaș and Lugoj remain underpenetrated by dedicated campus connectivity.
Constanța and Black Sea Coast
Port automation and maritime logistics generate low-latency connectivity demand for container tracking and customs processing. ANCOM's pending mmWave licensing could enable fixed wireless access competition where submarine cable landing stations complicate fiber trenching. Tourism-dependent seasonal usage patterns challenge revenue stability for infrastructure investors.
Iași and Moldova Region
Cross-border traffic toward Republic of Moldova and Ukraine sustains international gateway investments. Secondary city status delays fiber economics compared to western urban centers, preserving DSL maintenance obligations under universal service mandates. Technical university output supplies radio frequency engineering talent to national operators.
Romania Telecom Market Competitive Landscape
The competitive structure tilts toward incumbent leverage with infrastructure-heavy positioning. Orange Romania and Vodafone Romania anchor the premium tier through nationwide coverage density and enterprise relationship depth. Digi Communications occupies a disruptive price-position with residential gigabit offerings. Three archetypes define the field: integrated multinational incumbents with spectrum portfolios, cable-born challengers with fiber-overbuild capabilities, and mobile virtual operators serving price-sensitive segments. Competitive moves concentrate on convergent bundle packaging and fiber-to-the-home expansion racing against ANCOM-mandated modernization deadlines.
Among the multinational incumbents, Orange Romania and Vodafone Romania exemplify spectrum-rich positioning with enterprise mobility anchoring. Digi Communications represents the cable-originated challenger archetype that has crossed into mobile services through infrastructure ownership. Telekom Romania, despite its heritage lineage, sits within a restructuring trajectory that reflects the broader European consolidation patterns affecting former state-owned operators.
| Leading Market Players |
|---|
| Orange Romania |
| Vodafone Romania |
| Digi Communications |
| Telekom Romania |
| RCS & RDS |
| UPC Romania |
| Lycamobile Romania |
| NextGen Communications |
| GTS Telecom |
| Others |
Pricing and Supply Chain Analysis
Speed-tier bifurcation between gigabit fiber and legacy DSL services manifests in divergent pricing power and sourcing intensity across Romanian operator portfolios. ANCOM's infrastructure modernization mandates compress upgrade timelines, forcing simultaneous investment in XGS-PON terminals and 5G radio units that reshape procurement priorities alongside retail rate structures.
Pricing Analysis
Bundled triple-play packages dominate Romanian residential pricing, separating premium fiber-to-the-home tiers from economy DSL maintenance obligations. Price differentiation rests on upload symmetry guarantees and latency commitments rather than raw bandwidth alone. Cost compression in the residential broadband segment intensifies as Digi Communications' gigabit disruption forces incumbent repricing. Small businesses show highest price sensitivity, while enterprise manufacturers accept premium rates for private 5G campus networks with production-line uptime penalties.
Supply Chain Analysis
ANCOM's domestic infrastructure sharing requirements and GDPR data localization expectations reshape sourcing patterns toward EU-based equipment vendors and local fiber deployment contractors. Romanian operators draw from German, Chinese, and Finnish suppliers for radio access network gear and optical terminal hardware. Single-source vulnerability concentrates in 5G baseband processor supply, where geopolitical export controls threaten delivery continuity. Distribution runs through direct operator procurement with systems integrator intermediation for enterprise private network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's telecom market compounds regulatory obligation with infrastructure investment, as ANCOM's spectrum reallocation deadlines force synchronized multi-generation network deployment that sustains equipment demand regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin compression in residential broadband by accelerating XGS-PON overbuild ahead of challenger fixed wireless access entry. Prioritize vertical integration into enterprise private network systems integration to capture automotive and logistics automation demand before specialized integrators consolidate radio access expertise. Defend spectrum portfolio value through preemptive mmWave trial deployments that establish technical credibility for pending ANCOM licensing rounds. For New Entrants and Emerging Players: Launch via wholesale fiber bitstream access in secondary cities where ANCOM's pending unbundled loop pricing decisions may create retail margin headroom. Target the Transylvania manufacturing corridor around Timișoara and Cluj-Napoca for private 5G campus networks, where industrial zone underpenetration offers first-mover positioning without incumbent fiber density advantages. Pursue outcome-based connectivity contracts with penalty structures that shift operational risk onto emerging operators with specialized radio frequency engineering capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where copper-era billing systems and legacy subscriber management platforms create technical debt burdens that exceed standalone transformation economics. Long-term viability favors operators with convergent service packaging capabilities and fiber ownership depth over pure mobile spectrum plays. Watch ANCOM's mmWave auction conditions as the inflection signal determining whether infrastructure-light fixed wireless access challengers can achieve viable secondary city economics.| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Fiber Densification | Symmetric 10 Gbps capability captures enterprise cloud-edge integration demand in Bucharest and Cluj-Napoca manufacturing zones. |
| Private 5G Campus Network Deployment | Industrial automation contracts with automotive suppliers in Argeș and Prahova counties bypass public network congestion premiums. |
| Convergent Triple-Play Bundling | IPTV-broadband-mobile packaging locks residential subscribers into longer contract terms reducing quarterly churn volatility. |
| Open RAN Architecture Migration | Multi-vendor radio unit sourcing reduces dependence on single-source equipment providers during geopolitical supply constraints. |
| mmWave Fixed Wireless Access Launch | Pending ANCOM 26 GHz and 28 GHz licensing enables broadband competition in Brașov and Iași where trenching costs delay fiber buildouts. |
Research Methodology
Coverage spans Bucharest-Ilfov, Transylvania, Western Banat, Black Sea Coast, and Moldova regions, with primary inputs from each informing demand calibration. The analysis combines structured interviews with network planning executives, enterprise procurement managers at manufacturing subsidiaries, ANCOM regulatory affairs specialists, and systems integrators with radio access deployment expertise. Secondary validation draws from ANCOM spectrum auction documentation, European Electronic Communications Code transposition filings, operator infrastructure disclosure reports, and smart city municipal procurement records. Bottom-up service revenue modeling triangulates against top-down capital expenditure flow analysis.
Granularity-level modeling distinguishes technology generation upgrade cycles, service type revenue concentration, customer procurement sophistication tiers, and pricing model liquidity preferences across the projection horizon. Segmentation dimensions include 5G radio access deployment stage, fiber architecture generation, enterprise vertical adoption maturity, and bundled versus unbundled contract structures. CAGRs derive from equipment replacement cycle analysis and subscriber migration trajectory modeling. Forecast inputs incorporate ANCOM regulatory milestone timelines and enterprise cloud connectivity adoption curves specific to Romanian manufacturing automation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated mmWave licensing or delayed infrastructure sharing agreement enforcement. The analytical envelope reflects assumptions regarding spectrum auction participation thresholds, radio frequency engineer supply constraints, and copper network maintenance obligation durations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
South Africa Telecom Tower Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Myanmar ICT Market
Telecommunications
Global LTE Market
Telecommunications
Mexico MNVO Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Voip Phone Market
Telecommunications
Denmark Telecom Market
Telecommunications
Egypt Telecom Tower Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Telecom Managed Services Market