
 Asia Pacific Mobile Virtual Network Operator (MVNO) Market | 2026-2036
Asia Pacific Mobile Virtual Network Operator (MVNO) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Mobile Virtual Network Operator (MVNO) Market Outlook
CE marking under the EU AI Act is rotating as a de facto benchmark for data governance practices among Asia Pacific MVNOs serving multinational enterprise clients. Rakuten Mobile leverages its cloud-native architecture to sustain cost advantages in wholesale network access. Soracom anchors its position through specialized IoT connectivity platforms that dominate industrial sensor deployments across Japanese manufacturing zones.
A Mobile Virtual Network Operator leases wireless network infrastructure from host mobile network operators and resells branded voice, data, and messaging services under its own commercial terms, typically operating through software-defined provisioning platforms that manage subscriber authentication via SIM profiles or eSIM remote provisioning. The Asia Pacific MVNO landscape segments structurally by service type, where full MVNOs that operate dedicated core network elements capture premium enterprise contracts while light MVNOs compete aggressively on consumer price positioning. Customer type segmentation reveals IoT solutions as the fastest-expanding revenue pool, with enterprises in smart logistics and predictive maintenance driving volume commitments that dwarf individual consumer ARPU.
TRAI in India enforces tariff transparency and interconnection rules that govern how MVNOs access incumbent networks, while Japan's MIC spectrum allocation policies shape which virtual operators can offer 5G-tier services. Australia's ACCC monitors wholesale pricing to prevent host networks from squeezing MVNO margins through asymmetric access fees. Stakeholders must track eSIM standardization timelines and evolving data localization requirements as these will determine which operators can scale across multiple national markets without rebuilding core infrastructure.
Market Dynamics
Enterprise IoT deployments across Japanese manufacturing zones and Indian logistics corridors are compressing wholesale network access economics, forcing MVNOs to rebuild core infrastructure around cloud-native orchestration layers rather than legacy provisioning stacks.
Growth Catalysts
- TRAI's mobile number portability framework:India's interconnection rules lower subscriber switching costs and accelerate churn-based competitive pressure across South Asian markets.
- Industrial sensor deployments:Predictive maintenance contracts in Japanese automotive clusters generate volume commitments that stabilize wholesale revenue pools for specialized connectivity platforms.
- eSIM remote provisioning:The technology eliminates physical SIM logistics and enables instant carrier switching for enterprise fleet managers across Australian mining operations.
Market Restraints
- Asymmetric wholesale access fees:Australia's ACCC monitoring has not prevented host networks from extracting margin compression through variable interconnection pricing tiers.
- Spectrum allocation constraints:Japan's MIC policies restrict which virtual operators can access 5G-tier radio frequencies, capping service differentiation potential.
- Data localization mandates:Fragmented national requirements force redundant core infrastructure builds in each operating jurisdiction.
Strategic Opportunities
- Southeast Asia portability harmonization:Emerging regulatory alignment across ASEAN member states creates cross-border subscriber mobility without infrastructure replication.
- Digital payment integration:India's UPI-linked subscription models enable prepaid micro-transactions that expand addressable consumer segments beyond traditional credit-scored bases.
- Cloud-native core convergence:Containerized network functions and edge computing fabrics are merging to slash capital intensity for new market entrants.
Industry Challenges
- Legacy billing system integration:Enterprise MVNOs face protracted reconfiguration cycles when interfacing with incumbent host network charging platforms.
- Certification timeline compression:CE marking requirements under the EU AI Act are accelerating compliance deadlines for data governance practices without corresponding resource expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Mobile Virtual Network Operator (MVNO) Market |
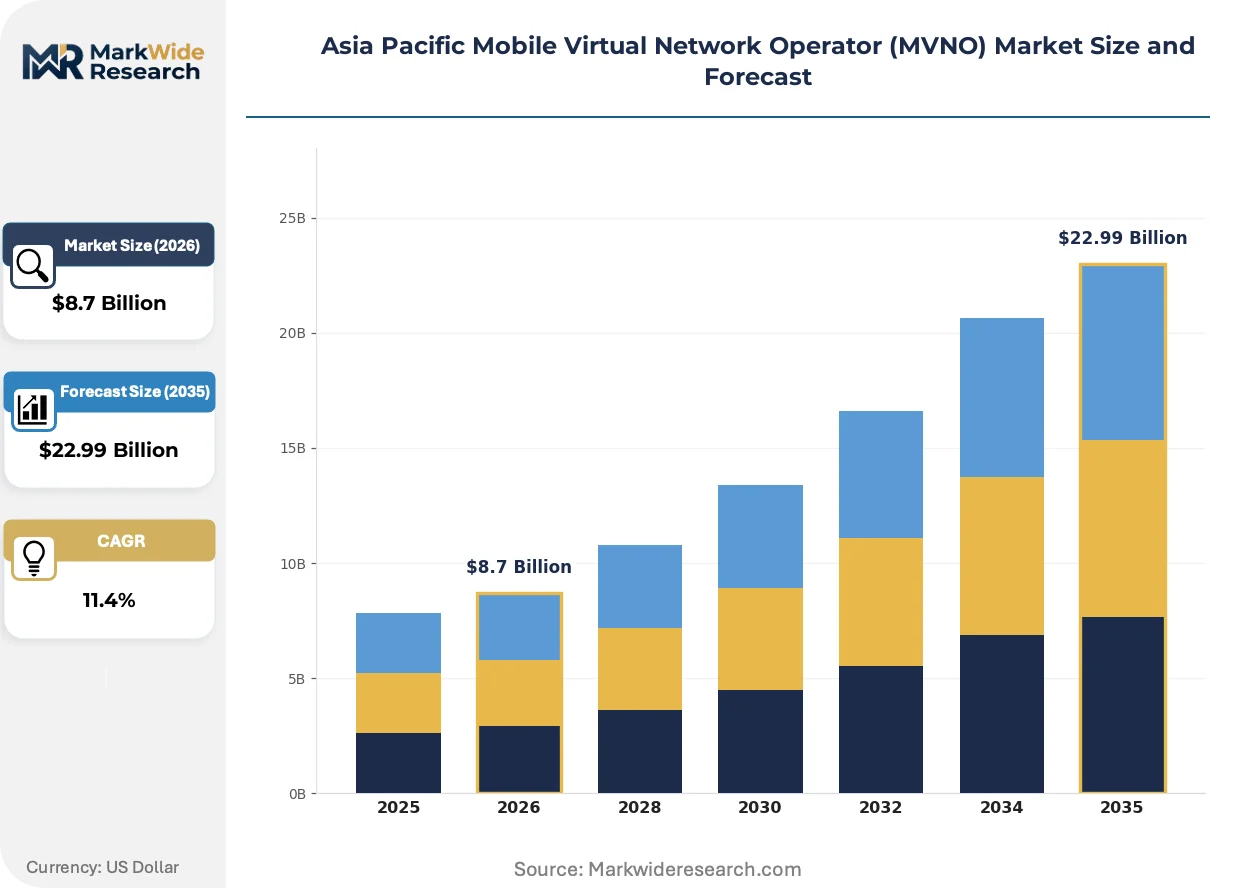
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full MVNO, Light MVNO, Brand MVNO, Wholesaler MVNO Customer Type: Consumers, Enterprises, IoT Solutions, Resellers Technology: GSM, LTE, VoLTE, 5G Distribution Channel: Online, Retail Stores, Direct Sales, Affiliates |
| Companies Covered | Kogan Mobile Operations, GOMO, Circles.Life, Soracom, Lycamobile, Rakuten Mobile, Tune Talk, MyRepublic Group, Amaysim Mobile, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Mobile Virtual Network Operator (MVNO) Market Strategic Shifts
Software-defined provisioning platforms are actively displacing hardware-centric network functions across Asia Pacific MVNO operations. Three interconnected developments are compressing deployment timelines and reshaping competitive entry economics.
Containerized network functions are decomposing monolithic core infrastructure into modular, API-orchestrated components. Japanese manufacturing conglomerates are deploying these architectures across multi-site IoT fleets within eighteen-month procurement cycles. The shift is compressing capital barriers for new MVNO entrants and enabling rapid service reconfiguration without hardware swaps.
TRAI's tariff transparency mandates are forcing real-time disclosure of wholesale access cost structures. Indian enterprise buyers now negotiate connectivity contracts with full visibility into underlying host network economics. The regulation most acutely affects light MVNOs competing on consumer price positioning, who must defend margin structures under heightened scrutiny.
Subscription unbundling is fragmenting traditional voice-data-SMS bundles into usage-based micro-services. Australian logistics operators are procuring connectivity as a variable operational expense tied to shipment volume rather than fixed per-device fees. The pattern concentrates most visibly in mining and freight corridors where seasonal demand volatility rewards elastic cost structures.
Asia Pacific Mobile Virtual Network Operator (MVNO) Market Segmentation
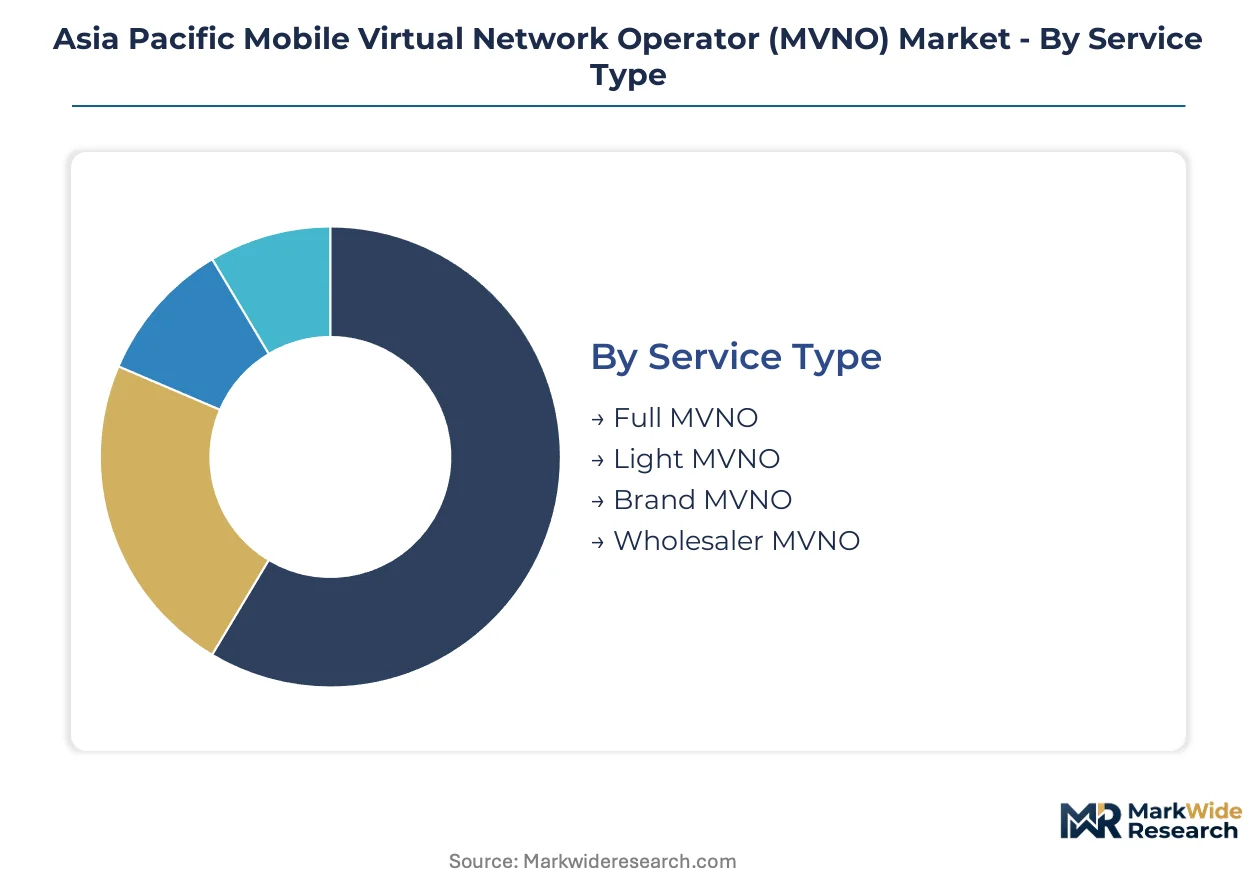
Asia Pacific MVNOs slice their addressable markets across four structural dimensions. Each segmentation axis reveals distinct margin profiles, infrastructure requirements, and regulatory exposure that shape operator strategy across India, Japan, and Australia.
Service Type:
Geographic deployment patterns diverge sharply by infrastructure control depth. Full MVNOs concentrate in Japan and Australia where wholesale economics justify dedicated core investments. Light MVNOs dominate India's price-sensitive consumer tiers.
- Full MVNO:Operates dedicated core network elements including HLR/HSS and mobile switching centers, requiring substantial capital deployment. Japanese automotive conglomerates and Australian mining operators procure these for guaranteed service-level agreements and data sovereignty compliance. TRAI's interconnection rules in India increasingly accommodate this model for enterprise IoT contracts.
- Light MVNO:Resells host network services without core infrastructure ownership, minimizing entry barriers. India's prepaid consumer base and Southeast Asian price-sensitive segments concentrate demand here, though margins compress under TRAI's tariff transparency mandates.
- Brand MVNO:Retail and media brands lease network capacity for customer loyalty extension. Australian supermarket chains and Japanese e-commerce platforms deploy this model for bundled subscription ecosystems.
- Wholesaler MVNO:Sells bulk connectivity to downstream resellers and niche service providers. Concentrated in Singapore and Hong Kong as regional hub operations serving cross-border enterprise fleets.
Full MVNO commands the established base among enterprise contracts. The steepest expansion runs through Light MVNO as India's digital payment integration unlocks prepaid micro-transaction volumes.
Customer Type:
Margin structures invert across this axis. Individual consumers generate thin spreads but massive scale. Enterprise and IoT segments yield superior unit economics with longer contract tenures.
- Consumers:Individual subscribers purchasing voice, data, and messaging bundles. India's UPI-linked prepaid models and Australia's subscription unbundling trends reshape procurement patterns across price tiers.
- Enterprises:Corporate mobility contracts spanning field workforces and executive tiers. Japanese manufacturing zones and Indian logistics corridors drive volume commitments with customized quality-of-service guarantees.
- IoT Solutions:Connected device fleets for predictive maintenance, asset tracking, and environmental monitoring. Soracom's specialized platforms anchor Japanese industrial sensor deployments, while Australian mining operations deploy eSIM-enabled fleet management at scale.
- Resellers:Downstream distributors purchasing wholesale capacity for niche market segments. Concentrated in Southeast Asian markets with fragmented retail infrastructure.
Consumer segments anchor volume foundations. IoT Solutions climb fastest as manufacturing automation and smart logistics compress procurement cycles.
Technology:
Network generation adoption tracks national spectrum policy maturity. 5G access remains gated by regulator licensing timelines across the region.
- GSM:Legacy 2G infrastructure supporting basic voice and SMS services. Persistent demand in India's rural coverage gaps and Southeast Asian cost-optimized IoT deployments.
- LTE:Dominant 4G standard for current consumer and enterprise data services. Australia's wholesale pricing frameworks and Japan's MIC allocation policies shape competitive access economics.
- VoLTE:Voice-over-LTE enabling HD voice and simultaneous data sessions. Required capability for Japan's enterprise MVNOs serving financial services and healthcare compliance use cases.
- 5G:Next-generation radio with network slicing and ultra-reliable low-latency capabilities. Japan's MIC restricts virtual operator access, while Australia's ACCC monitors wholesale terms for emerging entrants.
LTE retains the installed revenue base. 5G claims the steepest upward trajectory as spectrum liberalization proceeds across ASEAN markets.
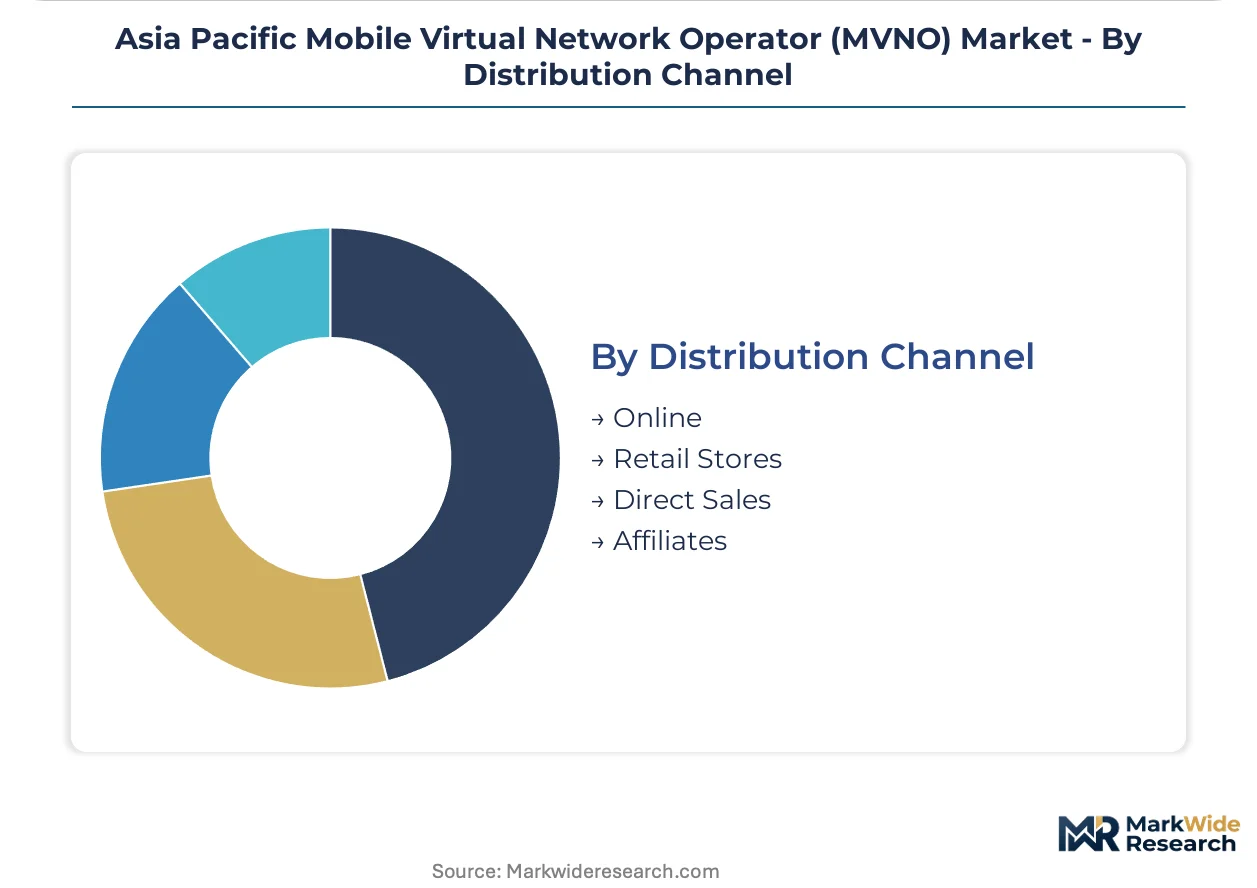
Distribution Channel:
Channel mix reflects national retail infrastructure density and digital payment penetration. Urban-rural divides within India and Australia force hybrid approaches.
- Online:Digital-first acquisition through apps and web portals. India's UPI integration enables instant activation without physical documentation. Australian mining and logistics operators procure enterprise fleets through dedicated B2B platforms.
- Retail Stores:Branded and partner physical locations for SIM distribution and customer service. Concentrated in Japanese urban corridors and Indian tier-2 cities where smartphone penetration lags digital payment adoption.
- Direct Sales:Field teams targeting enterprise accounts with customized connectivity proposals. Japanese automotive clusters and Australian freight corridors rely on this channel for complex IoT solution design.
- Affiliates:Third-party agents and comparison platforms driving subscriber acquisition. Prevalent in Southeast Asian markets with fragmented brand awareness and price-sensitive switching behavior.
Retail Stores maintain the deepest subscriber relationships. Online channels expand most rapidly as eSIM remote provisioning eliminates physical logistics constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IoT buyers cluster in Japanese manufacturing corridors, Indian logistics hubs, and Australian mining operations. TRAI's portability mandates and Japan's MIC spectrum policies reshape competitive entry economics across these demand centers.
India
Digital payment penetration through UPI-linked prepaid models unlocks micro-transaction volumes in tier-2 cities and rural coverage gaps. TRAI enforces tariff transparency and interconnection rules governing how virtual operators access incumbent networks. Manufacturing and logistics corridors in Maharashtra and Gujarat drive enterprise IoT procurement with customized quality-of-service guarantees.
Japan
Industrial sensor deployments for predictive maintenance in automotive clusters generate volume commitments that stabilize wholesale revenue pools. MIC spectrum allocation policies restrict which virtual operators can access 5G-tier radio frequencies. Kansai and Chubu manufacturing zones anchor specialized connectivity platform demand from automotive and electronics conglomerates.
Australia
Mining operations and freight corridors deploy eSIM-enabled fleet management at scale, rewarding elastic cost structures tied to shipment volume. ACCC monitors wholesale pricing to prevent host networks from extracting margin compression through asymmetric access fees. Western Australia and Queensland mining belts concentrate procurement for remote asset tracking and environmental monitoring.
Singapore
Regional hub operations serve cross-border enterprise fleets with bulk connectivity resale to downstream resellers. The national regulator shapes data governance requirements for multinational enterprise clients. The city-state's financial and logistics infrastructure supports wholesaler MVNOs targeting ASEAN market fragmentation.
Asia Pacific Mobile Virtual Network Operator (MVNO) Market Competitive Environment
Player mix skews toward full MVNOs and specialized IoT platforms with cloud-native core investments. Market structure concentrates around three strategic tiers: infrastructure-heavy operators with dedicated network elements, digital-native challengers with software-defined provisioning, and brand-led retailers extending customer loyalty ecosystems. Dominant competitive moves include cloud-native core convergence and strategic partnerships for cross-border subscriber mobility.
Among Asia Pacific-based operators, Rakuten Mobile, Soracom, and Circles.Life occupy distinct archetype positions. Tokyo-headquartered Rakuten Mobile exemplifies the cloud-native infrastructure tier through its wholesale network access model. Soracom represents specialized IoT connectivity platforms serving industrial sensor deployments. Singapore-originated Circles.Life sits within the digital-native challenger tier with software-defined customer acquisition platforms.
| Leading Market Players |
|---|
| Kogan Mobile Operations |
| GOMO |
| Circles.Life |
| Soracom |
| Lycamobile |
| Rakuten Mobile |
| Tune Talk |
| MyRepublic Group |
| Amaysim Mobile |
| Others |
Value Chain & Pricing Dynamics
Cloud-native orchestration layers substituting for legacy provisioning stacks are redrawing supply geography toward software development clusters in Singapore and Bangalore while compressing capital barriers that once anchored pricing power in hardware-heavy full MVNOs.
Pricing Analysis
Cost-plus contracts with wholesale access fees indexed to host network capacity utilization dominate enterprise IoT procurement. Price differentiation hinges on quality-of-service tier guarantees and TRAI-mandated tariff transparency levels. Pricing pressure intensifies as light MVNOs compete on consumer price positioning under heightened regulatory scrutiny. Individual prepaid subscribers exhibit highest price sensitivity, while Japanese automotive conglomerates prioritize SLA reliability over unit cost.
Supply Chain Analysis
Inventory cycles for eSIM profile provisioning have compressed from weeks to hours through API-orchestrated remote activation. Supply concentrates in Japan, India, and Singapore as core infrastructure development hubs. Raw material dependencies span semiconductor chipsets, secure element modules, and cloud compute capacity. Single-source vulnerability persists in host network access agreements with incumbent mobile operators. Distribution runs through direct sales teams for enterprise accounts and digital platforms for consumer acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific MVNOs represent a service-attach opportunity where recurring connectivity management fees and predictive maintenance platform subscriptions expand faster than underlying hardware module sales.
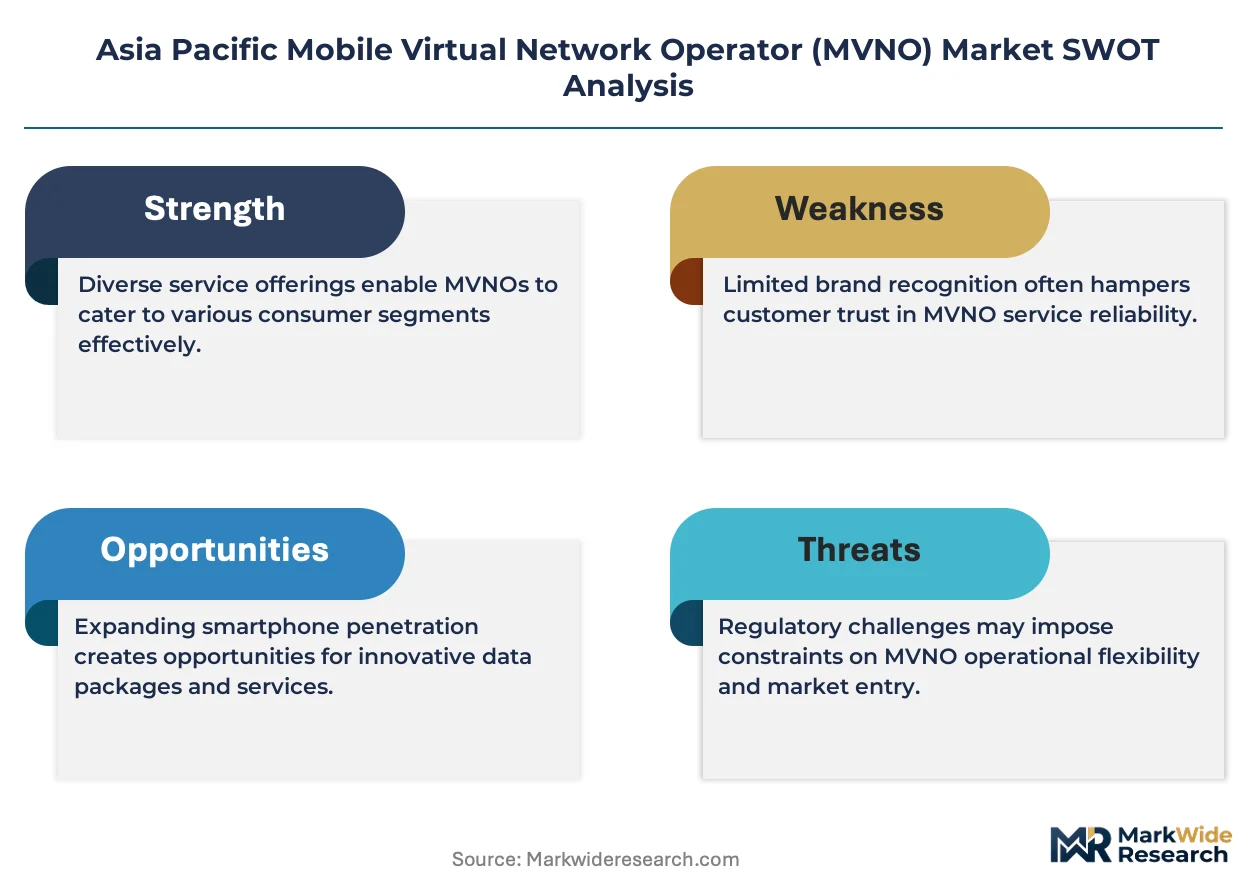
For Market Incumbents: Compound defensive positioning through cloud-native core convergence and strategic partnerships for cross-border subscriber mobility. Threats emerge from digital-native challengers with software-defined provisioning platforms and margin compression under TRAI's tariff transparency mandates. Priority levers include vertical integration into edge computing fabrics and certification investment for EU AI Act CE marking compliance. For New Entrants and Emerging Players: Enterprise IoT solution gaps in Indian logistics corridors and Australian mining operations offer white-space entry where incumbents under-serve with legacy provisioning stacks. Most penetrable segment concentrates in light MVNO tiers for price-sensitive prepaid consumers enabled by UPI-linked micro-transaction models. Go-to-market angle centers on eSIM-enabled instant activation platforms bypassing physical SIM logistics. For Investors and Strategic Acquirers: The market sits at an infrastructure consolidation phase that favors cloud-native specialists with dedicated core network elements over hardware-dependent legacy operators. Long-term viability over the coming decade hinges on software-defined provisioning scalability and cross-border regulatory harmonization. Acquisition target archetype: specialized IoT connectivity platforms with established industrial sensor deployment relationships. Signal to watch: eSIM standardization timelines and ASEAN portability harmonization progress as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Convergence | Containerized network functions slash capital intensity for new MVNO entrants across Japanese manufacturing zones. |
| eSIM Remote Provisioning Platform | Instant carrier switching eliminates physical SIM logistics for Australian mining fleet managers. |
| Strategic Partnership for Cross-Border Mobility | ASEAN regulatory alignment enables subscriber portability without infrastructure replication. |
| Specialized IoT Connectivity Platform | Predictive maintenance contracts stabilize wholesale revenue pools in Japanese automotive clusters. |
| Digital Payment Integration | UPI-linked subscription models expand addressable segments beyond credit-scored bases in India. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of TRAI tariff orders, Japan MIC spectrum allocation records, and ACCC wholesale pricing determinations. Interviews span MVNO operations executives, host network wholesale managers, enterprise IoT procurement leads, and cloud infrastructure architects. Secondary sources include regulatory filings, spectrum auction databases, and customs records for telecommunications equipment. Bottom-up subscriber and revenue modeling triangulates against top-down market sizing from infrastructure deployment tracking.
Segmentation dimensions modeled cover service type, customer type, network generation technology, and distribution channel across the analysis window. Analytical framework projects value expansion through compound annual growth rate derivation from underlying driver elasticity. Industry-specific forecast inputs incorporate eSIM adoption curves, data localization mandate implementation timelines, and industrial sensor deployment commitments from Japanese manufacturing conglomerates.
Forecasts assume regulatory continuity in TRAI interconnection regimes, Japan MIC spectrum policies, and ACCC wholesale pricing oversight; material policy shifts would require re-modeling. Specific risk factors include asymmetric host network access fee renegotiation, fragmented national data localization requirements, and 5G spectrum liberalization delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
South Africa Telecom Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Poland Telecom Market
Telecommunications
Nigeria Telecom Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Belgium ICT Market
Telecommunications
Brazil Telecom Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Australia Telecom Tower Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
Indonesia ICT Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Global Small Cell 5G Network Market