
 A2P SMS Market | 2026-2036
A2P SMS Market Size, Share, and Industry Trends Forecast 2026-2036
A2P SMS Market Intelligence
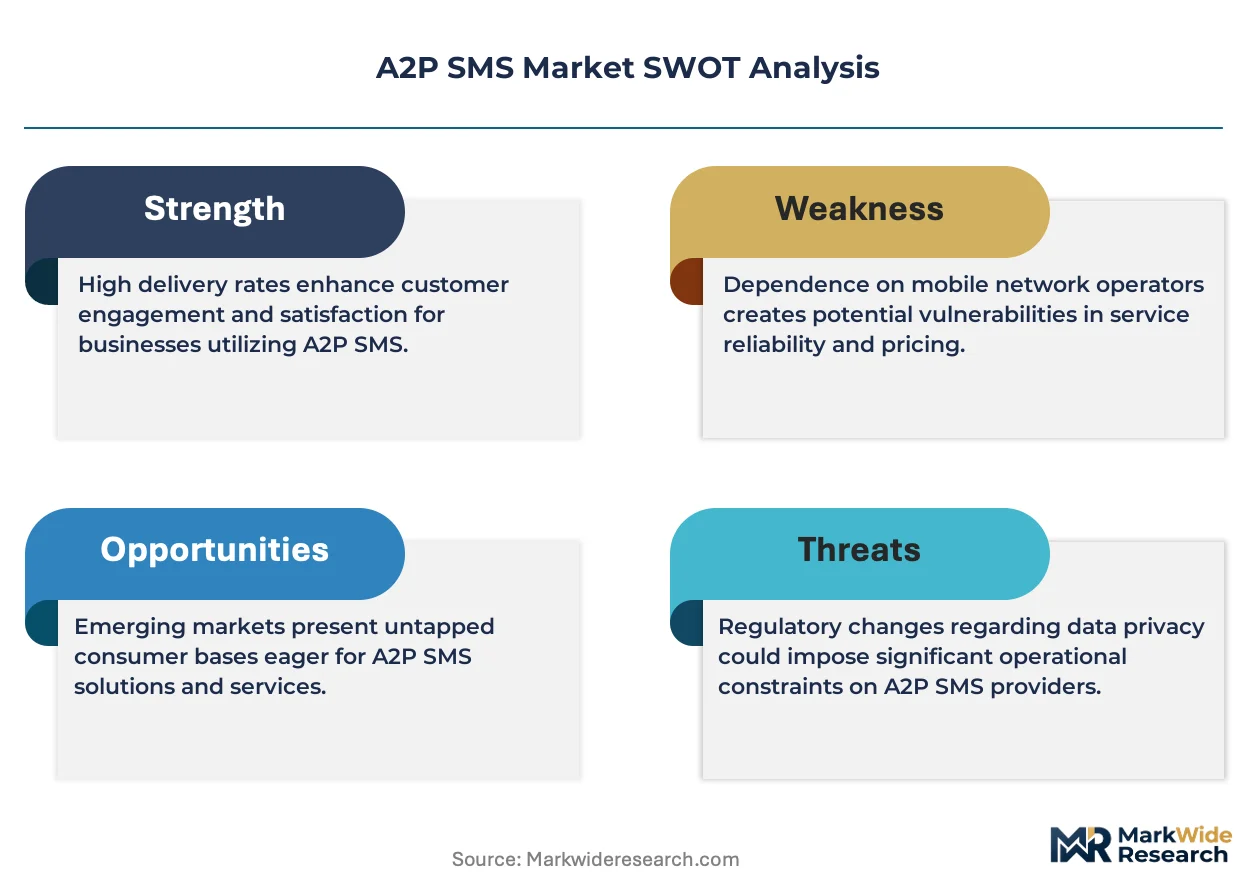
The A2P SMS sector is pivoting between premium API-driven platforms and commodity wholesale routing. Twilio leverages its developer-centric stack to command higher per-message margins. Infobip anchors its position through direct carrier relationships across emerging markets. TextMagic competes on simplicity for mid-market SMEs seeking self-service campaign tools.
Application-to-person messaging delivers one-way text communications from software systems to individual mobile subscribers, typically via SMPP or REST APIs with throughput rates from 1 to 10,000 messages per second depending on carrier grade. Its primary commercial purpose spans authentication, alerts, marketing, and operational notifications. Transactional OTP and service alerts dominate volume share due to banking and e-commerce dependency, while promotional marketing campaigns concentrate margin pools for platforms with campaign analytics. Cloud-based deployment is displacing on-premises installations as latency requirements and elastic scaling demands intensify.
FCC rules on robotext blocking and opt-in consent in the United States, alongside GDPR's strict opt-in requirements enforced by CNIL in France and other European data protection authorities, reshape deliverability standards and list-building economics. India's TRAI regulations on commercial messaging through distributed ledger technology scrubbing add compliance layers for route providers. Stakeholders must weigh carrier direct access against aggregator resilience as filtering algorithms and sanctioned pathway requirements tighten.
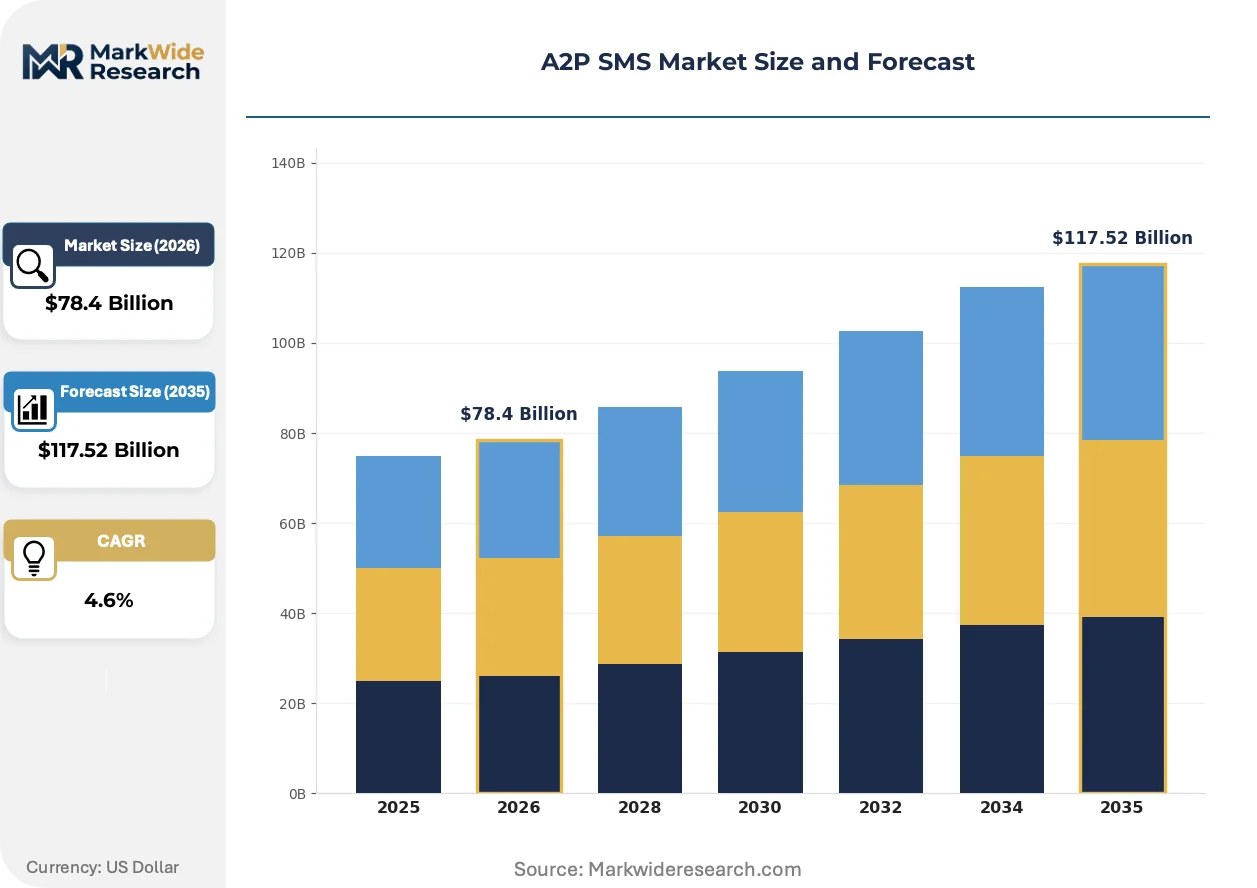
Market Dynamics
Carrier-grade filtering algorithms and sanctioned pathway mandates are compressing route diversity while concentrating volume through compliant aggregators. Platforms must now embed real-time scrubbing against distributed ledger registries to maintain deliverability.
Growth Catalysts
- TRAI DLT Mandate:India's distributed ledger technology scrubbing requirements for commercial messaging are consolidating legitimate traffic onto verified routes, reducing grey-route competition and improving yield for compliant providers.
- Financial Services Authentication:RBI guidelines mandating two-factor authentication for digital transactions sustain OTP volume growth across banking, payments, and securities applications.
- Cloud Migration:Brazilian enterprises are abandoning on-premises SMS gateways for elastic cloud deployments that scale with promotional campaign spikes and transactional bursts.
Market Restraints
- Input Cost Volatility:Termination rates in African and Southeast Asian markets fluctuate with carrier consolidation, squeezing aggregator margins on international routes.
- Supply Concentration Risk:Tier-1 carrier direct access in the United States, United Kingdom, and Germany is controlled by a handful of network owners, limiting route redundancy.
- Substitution Threat:Rich Communication Services (RCS) and over-the-top messaging applications are capturing promotional and conversational use cases from traditional SMS.
Strategic Opportunities
- Underpenetrated Geographies:Nigeria's banking digitization and mobile money expansion create demand for reliable transactional messaging infrastructure.
- Technology Convergence:Artificial intelligence-powered fraud detection is unifying with SMS delivery platforms to preempt account takeover attempts before OTP generation.
- Regulatory Tailwind:Brazil's LGPD enforcement parallels GDPR consent requirements, creating compliance service opportunities for platforms with European expertise.
Industry Challenges
- Certification Timeline Compression:FCC robotext blocking rules and carrier-specific trust scores demand continuous re-certification, draining operational resources.
- Legacy System Integration:Enterprise resource planning and customer relationship management platforms in established markets require custom SMPP bindings that delay cloud migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A2P SMS Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $117.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Message Type: Promotional, Transactional, OTP, Service Alerts, Notifications, Marketing Campaigns Industry Vertical: Banking, Telecommunications, E-commerce, Logistics, Hospitality, Education Deployment Mode: Cloud-based, On-premises, Hybrid, Managed Services End User Type: Enterprises, Government Agencies, SMEs, Marketing Agencies, Financial Institutions |
| Companies Covered | Invoke Mobile, TextMagic, Twilio, GoHighLevel, Zoho, Infobip, SimpleTexting, Attentive, EngageLab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A2P SMS Market Strategic Shifts & Innovations
API abstraction layers are collapsing the distinction between premium managed services and self-serve developer tools. Platforms now compete on embedding compliance automation directly into message orchestration workflows.
Conversational AI orchestration is unifying natural language processing with SMS delivery infrastructure. E-commerce and logistics providers in India and Southeast Asia are adopting these hybrid stacks to automate delivery notifications and returns handling. The technology is compressing customer service labor costs while maintaining regulatory consent trails.
GDPR's strict opt-in requirements, enforced by CNIL in France and peer authorities across the European Union, are mandating granular consent logging at the message level. Marketing platforms must now maintain auditable proof of subscriber permission before each campaign dispatch. Financial services and retail verticals in Germany and the Netherlands are investing in consent management platforms that integrate directly with SMS APIs.
Buyer procurement patterns are fragmenting across self-serve developer portals and managed service contracts. Mid-market retailers in Brazil and Mexico are bypassing traditional reseller channels to access direct carrier relationships through cloud-native platforms. This disintermediation is most visible in promotional campaign volumes where real-time analytics and A/B testing capabilities drive vendor selection.
A2P SMS Market Segmentation
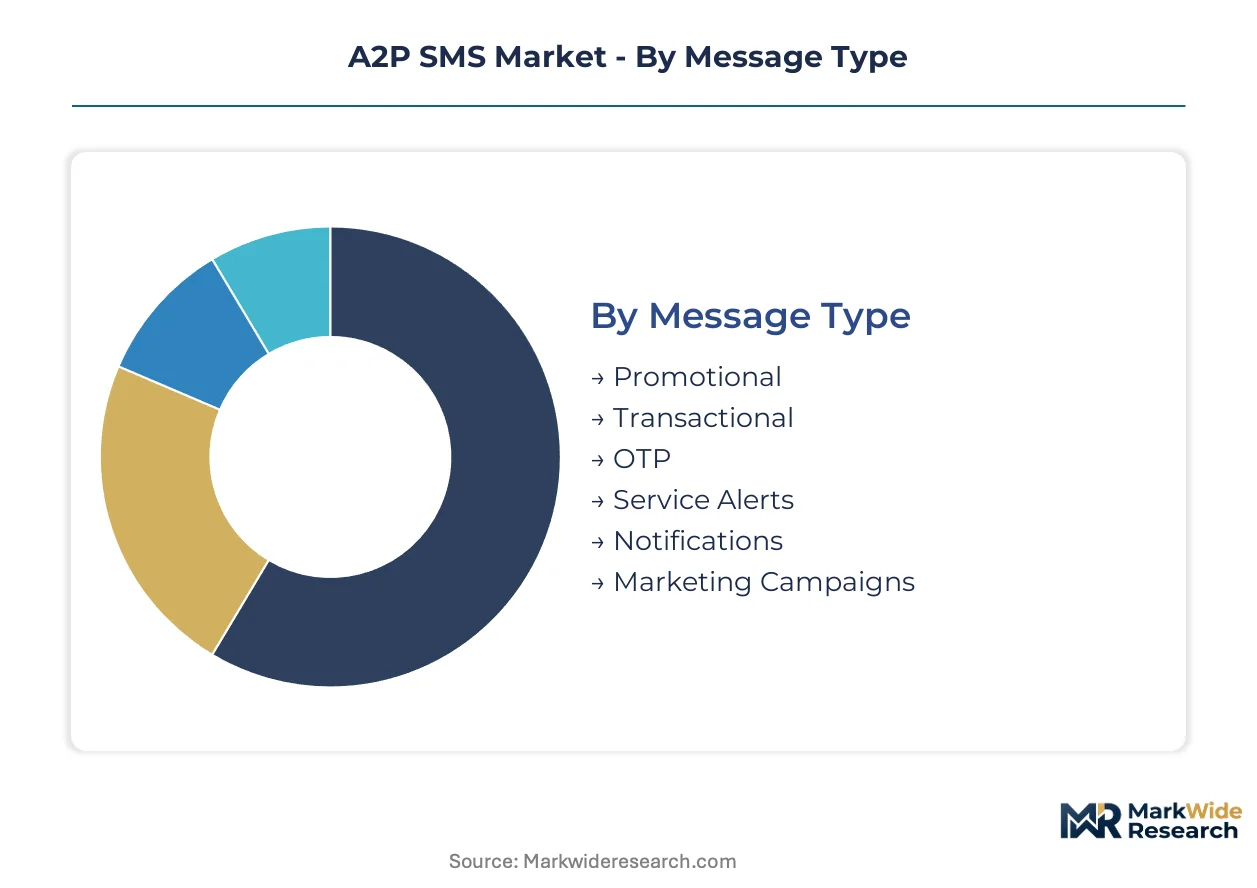
Route economics and compliance requirements fragment the A2P SMS landscape across multiple dimensions. Each segmentation axis reveals distinct margin structures, regulatory exposure, and technology investment priorities for platform providers.
Message Type:
Supply concentration varies sharply by message category, with OTP and transactional traffic commanding dedicated carrier-grade pathways while promotional volume flows through more commoditized routes.
- Promotional:Marketing campaigns and sales announcements deliver bulk messaging with lower per-unit margins. Brazilian retailers and Indian e-commerce platforms drive volume concentration here, though GDPR-style consent requirements in Europe and LGPD in Brazil compress list-building economics and raise compliance costs.
- Transactional:Order confirmations, shipping updates, and payment receipts constitute high-velocity, low-latency traffic. Nigerian banking digitization and Southeast Asian logistics expansion concentrate demand growth, with platforms competing on API reliability and carrier direct access.
- OTP:One-time passwords for authentication represent the most latency-sensitive segment with strict deliverability SLAs. RBI-mandated two-factor authentication across Indian financial services sustains premium pricing power for compliant aggregators with TRAI DLT registry integration.
- Service Alerts:Account notifications, policy renewals, and subscription reminders balance volume with moderate latency tolerance. German insurance and Dutch utility verticals emphasize consent audit trails under GDPR enforcement.
- Notifications:General system alerts and status updates span diverse use cases with variable throughput requirements. Mid-market adoption in Mexico and Indonesia favors self-service cloud platforms with elastic scaling.
- Marketing Campaigns:Sophisticated segmentation and A/B testing capabilities differentiate premium platforms. French retailers under CNIL scrutiny invest in consent management platform integration to maintain dispatch permissions.
Today's leader: OTP. Tomorrow's challenger: Transactional.
Industry Vertical:
Vertical-specific compliance regimes and integration complexity create divergent customer acquisition economics across sectors.
- Banking:Regulatory mandates for authentication and fraud prevention dominate procurement criteria. Indian banks under RBI guidelines and Nigerian mobile money operators drive infrastructure investment, with artificial intelligence-powered fraud detection layering onto SMS delivery stacks.
- Telecommunications:Carriers themselves represent both customers and competitors, using A2P for subscriber management while controlling termination access. Brazilian and Indonesian operators balance wholesale revenue against over-the-top substitution threats.
- E-commerce:Order lifecycle messaging and returns automation concentrate volume in India and Southeast Asia. Conversational AI orchestration is compressing customer service labor costs while maintaining consent trails.
- Logistics:Delivery notifications and driver coordination demand real-time routing with geographic redundancy. Last-mile providers in Nigeria and Mexico prioritize reliable infrastructure over advanced analytics.
- Hospitality:Booking confirmations and guest service alerts favor platforms with multilingual template management. European chains under GDPR face granular consent logging requirements.
- Education:Administrative alerts and examination result distribution show price-sensitive procurement patterns. Public sector tenders in India and Brazil emphasize cost efficiency over feature depth.
Banking captures premium margins through regulatory stickiness. E-commerce offers the steepest expansion trajectory as conversational AI penetrates customer service workflows.
Deployment Mode:
Cloud infrastructure economics are systematically displacing capital-intensive on-premises installations as latency requirements and elastic scaling demands intensify.
- Cloud-based:API-first platforms with pay-per-message pricing and automatic scaling dominate new procurement. Brazilian enterprise migration from legacy gateways exemplifies the shift, with promotional campaign spikes and transactional bursts driving elasticity requirements.
- On-premises:Dedicated hardware installations persist where data sovereignty or legacy ERP integration demands local control. German financial institutions and Indian public sector banks maintain captive infrastructure despite higher total cost of ownership.
- Hybrid:Split architectures route sensitive authentication through private infrastructure while pushing promotional volume to cloud endpoints. This configuration appeals to mid-market retailers in Mexico balancing compliance anxiety with cost pressure.
- Managed Services:Fully outsourced messaging operations with SLA guarantees attract resource-constrained SMEs. French and Dutch marketing agencies favor this model to offload consent management complexity under GDPR enforcement.
Cloud-based deployment claims the dominant share of new contract value. Hybrid architectures are gaining share fastest among regulated mid-market verticals seeking risk-adjusted migration paths.
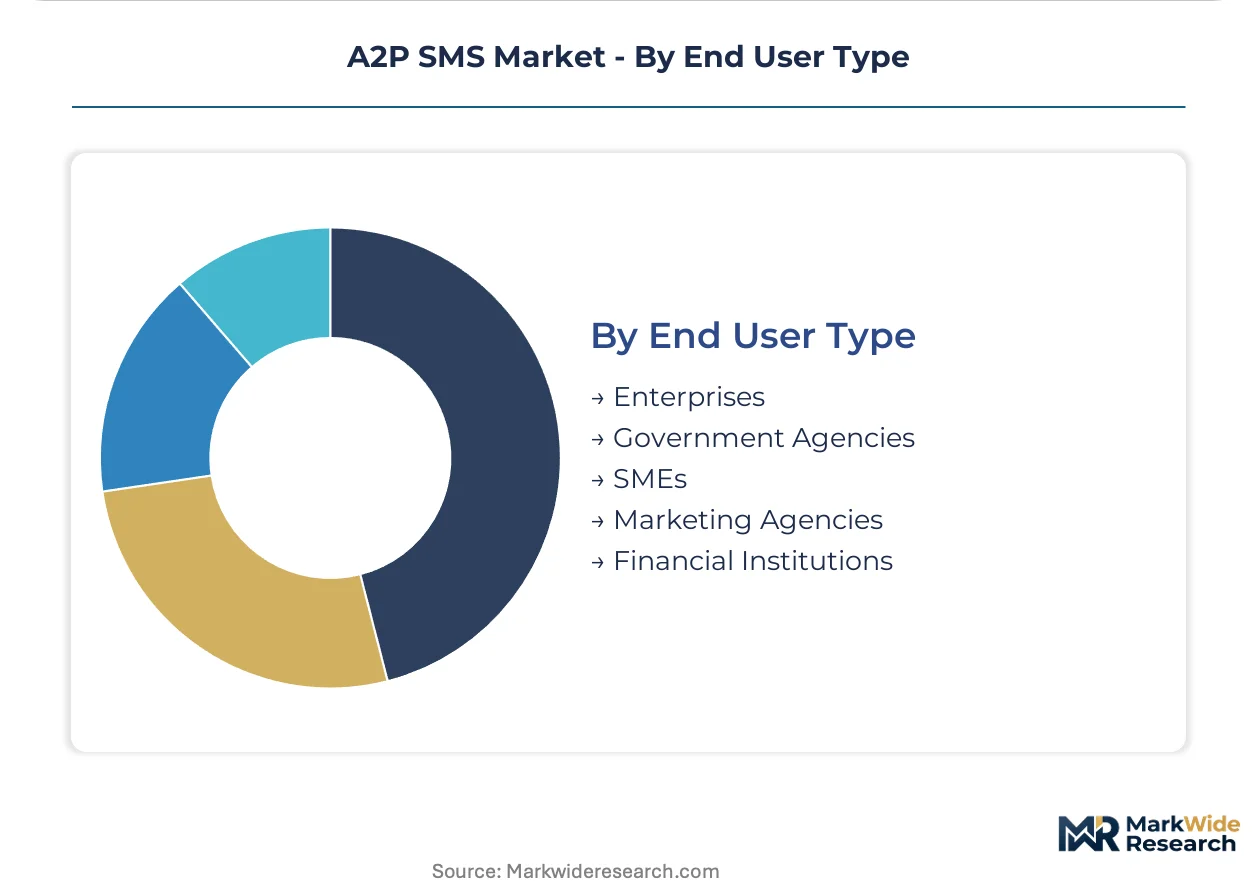
End User Type:
Procurement sophistication and integration requirements stratify the customer base across self-serve developer portals and managed enterprise contracts.
- Enterprises:Large organizations demand carrier-grade SLAs, custom SMPP bindings, and dedicated account management. Legacy ERP integration requirements in established markets delay cloud migration for some procurement cycles.
- Government Agencies:Public sector tenders emphasize cost efficiency, data localization, and audit compliance. Indian state governments and Brazilian federal entities drive volume through formal procurement channels with extended sales cycles.
- SMEs:Small and mid-sized enterprises favor self-service campaign tools with transparent pricing. Brazilian and Mexican retailers bypass traditional resellers to access direct carrier relationships through cloud-native platforms.
- Marketing Agencies:Intermediaries managing client campaigns prioritize real-time analytics, A/B testing, and multi-tenant consent management. European agencies under GDPR and emerging Brazilian agencies under LGPD invest in compliance automation.
- Financial Institutions:Banks, insurers, and payment processors represent the most demanding segment for latency, deliverability, and fraud prevention. RBI-regulated Indian banks and Central Bank of Nigeria-supervised operators sustain premium pricing for verified route access.
Enterprises anchor current revenue concentration. SMEs offer the most aggressive expansion profile as self-serve platforms disintermediate traditional reseller channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Bangalore, São Paulo, and San Francisco anchor platform development, while carrier relationship teams concentrate in European telecom hubs and Southeast Asian gateway cities.
United States
FCC robotext blocking rules and carrier trust score mandates compress certification timelines for route providers. Financial services authentication demand from New York and Chicago banking clusters sustains OTP volume. Silicon Valley API-first platforms compete with legacy aggregators for enterprise developer adoption.
India
RBI-mandated two-factor authentication drives banking OTP volumes while TRAI DLT scrubbing consolidates traffic onto verified routes. Mumbai's financial district and Bangalore's technology corridor host competing platform development centers. Cloud migration accelerates among mid-market retailers seeking elastic campaign scaling.
Brazil
LGPD enforcement parallels GDPR consent requirements, creating compliance service opportunities for platforms with European expertise. São Paulo anchors both fintech authentication demand and promotional campaign volume from retail headquarters. Enterprises abandon on-premises gateways for cloud deployments handling transactional bursts.
Germany
GDPR granular consent logging mandates under BfDI enforcement reshape marketing platform procurement. Frankfurt's banking cluster and Munich's insurance headquarters drive service alert volume with strict audit trail requirements. Hybrid deployment architectures appeal to mid-market verticals balancing compliance anxiety with cost pressure.
Nigeria
Central Bank of Nigeria supervision of mobile money operators sustains demand for reliable transactional infrastructure. Lagos concentrates fintech development while Kano and Port Harcourt expand last-mile logistics notification use cases. Banking digitization outpaces domestic platform capacity, creating import dependency for verified route access.
A2P SMS Market Key Industry Players
Top-tier vendors anchor carrier-direct relationships and developer-centric API stacks, while mid-tier aggregators compete on regional route density and compliance automation. The market structure stratifies across premium managed services, self-serve cloud platforms, and wholesale routing specialists. Three archetypes dominate: API-first developer platforms, carrier-relationship aggregators with emerging market depth, and vertical-focused campaign tools for regulated industries. Consolidation concentrates through strategic partnerships binding compliance technology to delivery infrastructure, alongside geographic expansion capturing underpenetrated banking digitization corridors.
Within the API-first tier, Twilio and Infobip exemplify divergent geographic strategies—one anchoring North American developer adoption, the other cultivating direct carrier relationships across emerging markets. TextMagic occupies a position serving mid-market SMEs with self-service simplicity, representing the campaign-tool archetype where transparent pricing and template management outweigh enterprise integration depth. These three patterns—developer-centric, carrier-anchored, and simplicity-positioned—capture the competitive vectors reshaping procurement decisions across financial services and retail verticals.
| Leading Market Players |
|---|
| Invoke Mobile |
| TextMagic |
| Twilio |
| GoHighLevel |
| Zoho |
| Infobip |
| SimpleTexting |
| Attentive |
| EngageLab |
| Others |
Cost & Logistics Intelligence
Carrier termination rate indices in African and Southeast Asian corridors cascade through aggregator margin structures, compressing yields on international routes while concentrating volume through compliant pathways that command premium positioning.
Pricing Analysis
Bundled API platforms with embedded compliance automation capture premium positioning against unbundled wholesale routing. Per-message transactional pricing dominates, with differentiation resting on carrier-direct access and real-time DLT registry integration. Pricing pressure stems from RCS and OTT substitution eroding promotional SMS margins. SMEs exhibit highest price sensitivity, while financial institutions under RBI and CBN mandates absorb premium rates for verified route SLAs.
Supply Chain Analysis
Engineering talent scarcity in Bangalore and São Paulo constrains platform development velocity, pushing cloud infrastructure investment toward automated orchestration layers. Supply concentrates in India for DLT registry integration expertise, the United States for carrier-grade filtering technology, and Estonia for regulatory compliance tooling. Raw material dependencies include carrier termination agreements, cloud compute capacity, and fraud detection AI licensing. Single-source vulnerability runs through Tier-1 carrier direct access in the United States, United Kingdom, and Germany. Distribution runs through API-first developer portals and managed service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Indian banks under RBI guidelines and Nigerian mobile money operators under CBN supervision are shifting procurement toward premium platforms with embedded compliance automation and sub-second OTP delivery guarantees.
For Market Incumbents: Deploy DLT registry integration as a defensive moat against grey-route competitors. Strengthen direct carrier relationships in India and Brazil to maintain yield as TRAI and LGPD enforcement tightens. Acquire conversational AI capabilities to offset RCS substitution in customer service workflows. Certification investment in FCC robotext compliance protects United States route access. For New Entrants and Emerging Players: LGPD enforcement in Brazil opens a window for GDPR-experienced European platforms to offer compliance-as-a-service bundles. Target Nigerian banking digitization corridors where domestic platform capacity lags demand for verified transactional infrastructure. Pursue self-serve SME segments in Mexico and Indonesia where cloud-native disintermediation is accelerating. Go-to-market through direct carrier API partnerships rather than legacy reseller channels. For Investors and Strategic Acquirers: Asymmetric upside sits with carrier-relationship aggregators possessing emerging market depth and regulatory technology integration. Long-term viability favors platforms with sticky financial services authentication revenue and expanding conversational AI orchestration capabilities. Watch TRAI DLT registry adoption velocity as an inflection indicator for route consolidation and margin expansion in India.| Strategic Initiative | Industry Significance |
|---|---|
| DLT Registry Integration | TRAI-mandated scrubbing in India consolidates legitimate traffic onto verified routes, eliminating grey-route competition. |
| Conversational AI Orchestration | Hybrid NLP-SMS stacks automate delivery notifications for Indian e-commerce and Southeast Asian logistics providers. |
| Carrier Direct Access Expansion | Direct relationships with Brazilian and Nigerian operators bypass aggregator intermediation for OTP volume. |
| Compliance Automation Embedding | Granular consent logging at message level satisfies CNIL enforcement for French retailers under GDPR. |
| Cloud Migration Acceleration | Elastic scaling infrastructure captures Brazilian enterprise abandonment of on-premises SMS gateways. |
Research Approach
Multiple input streams — platform engineering leads at API-first providers, carrier wholesale managers in India and Brazil, regulatory affairs specialists at TRAI and LGPD enforcement bodies, and enterprise IT procurement officers at financial institutions — were reconciled against secondary validation. Primary interviews with fraud detection technology vendors and conversational AI orchestration providers supplemented route economics intelligence. Secondary sources included TRAI DLT registry disclosures, RBI circulars on two-factor authentication, FCC robotext blocking orders, and cloud infrastructure capex filings. Bottom-up message volume modeling and top-down market sizing triangulated across deployment modes and industry verticals.
Historical trajectory analysis cross-referenced against panel input from carrier relationship executives and compliance platform architects shaped the analytical framework. Segmentation dimensions modeled encompassed message type, deployment mode, industry vertical, and end user procurement sophistication across the projection horizon. CAGRs derived from elasticity-adjusted volume growth curves and pricing power assessments by route tier. Industry-specific forecast inputs included OTP velocity requirements under banking supervision mandates and promotional campaign burst patterns in retail verticals.
Revisions become necessary when regulatory enforcement timelines accelerate, carrier consolidation alters termination economics, or RCS adoption curves steepen beyond substitution thresholds. Forecasts reflect documented assumptions regarding DLT registry penetration rates and cloud migration velocity in emerging markets. Material deviation in TRAI compliance adoption, FCC certification timelines, or OTT messaging substitution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Optical Fronthaul Market
Telecommunications
Global 5G in Healthcare Market
Telecommunications
Telecom Services Market
Telecommunications
Esim Subscription Market
Telecommunications
Austria Telecom Market
Telecommunications
Promotional Sms Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Telecommunication Service Market
Telecommunications
Global Radio Access Network Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
Fixed LTE Market
Telecommunications
Cloud RAN Market
Telecommunications
Dialer Market
Telecommunications
Algeria Telecom Market