
 Gelatin Hydrolysates Market | 2026-2036
Gelatin Hydrolysates Market Size, Share, and Industry Trends Forecast 2026-2036
Gelatin Hydrolysates Market Foresight
Aftermarket technical service revenue for enzymatic hydrolysis optimization is tilting toward contract manufacturers that lack in-house peptide engineering capabilities. Gelita AG leverages its German R&D campus to sustain leadership in cold-water soluble hydrolysate formulations. Rousselot anchors European supply through its integrated porcine and bovine raw material networks. PB Leiner competes on marine-sourced alternatives, differentiating its product slate for pescatarian-label cosmetic brands.
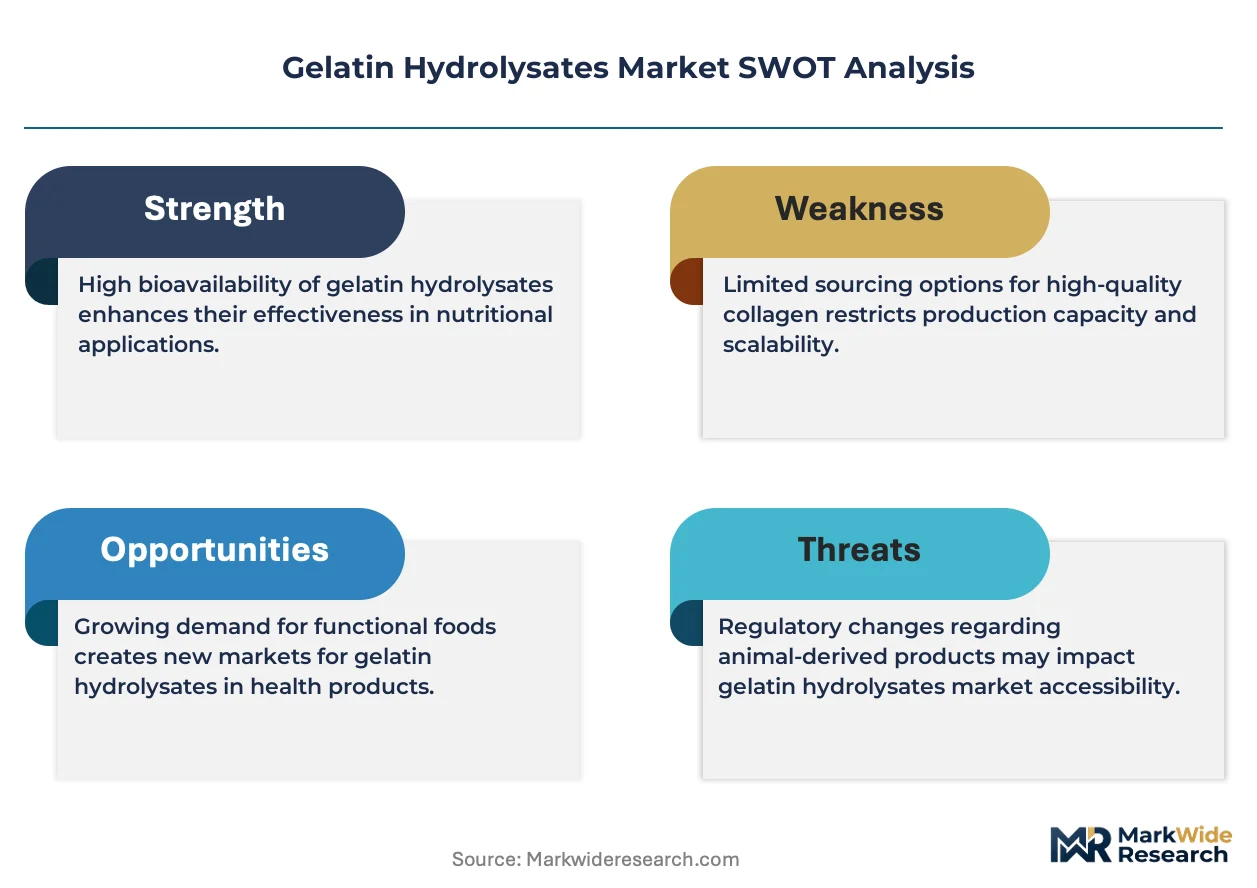
Gelatin hydrolysates are collagen proteins fragmented by controlled enzymatic hydrolysis into peptides with molecular weights typically below 10,000 Daltons, yielding cold-water soluble powders with enhanced bioavailability for oral and topical delivery systems. The primary commercial purpose centers on supplying functional peptides that support connective tissue claims in nutraceutical and dermal applications. Pharmaceutical Grade hydrolysates command premium positioning due to USP and EP compliance burdens that limit supplier pools, while Dietary Supplements as an application segment leads volume throughput driven by sports nutrition and anti-aging positioning. Powder forms dominate industrial handling economics, though Liquid formats are gaining traction in ready-to-drink functional beverage formulations where dispersion speed determines manufacturing line efficiency.
FDA dietary supplement cGMP enforcement and the European Pharmacopoeia's monograph updates for hydrolyzed collagen are elevating analytical testing burdens, forcing smaller hydrolysate traders to exit or consolidate. Japan's Ministry of Health, Labour and Welfare maintains distinct FOSHU approval pathways that restrict collagen peptide health claims to substantiated dossiers, creating a dual-track market where Japan-bound supply requires separate clinical validation investments. Stakeholders must monitor evolving allergen labeling thresholds for bovine and marine sources as these determine formulation flexibility across cosmetic and pharmaceutical pipelines.
Market Dynamics
Enzymatic hydrolysis technology maturation is compressing batch-to-batch variability, forcing suppliers to invest in continuous-flow reactor systems or cede contract manufacturing volumes to specialized toll processors.
Growth Catalysts
- Collagen peptide nutraceuticals:Sports nutrition and anti-aging formulations in Germany and the United States are absorbing expanded pharmaceutical-grade hydrolysate output.
- EU Novel Food Regulation:Tightened purity thresholds for ingestible collagen are consolidating demand around certified suppliers with validated dossiers.
- Marine-sourced alternatives:Pescatarian-label cosmetic brands are driving procurement of fish-derived hydrolysates as bovine and porcine sourcing faces consumer scrutiny.
Market Restraints
- Raw material concentration:Integrated porcine and bovine rendering networks in Western Europe create supply vulnerability during livestock disease outbreaks.
- Enzyme cost volatility:Protease prices fluctuate with fermentation feedstock markets, squeezing toll processors without long-term enzyme supply contracts.
- Plant protein substitution:Pea and rice protein isolates are capturing share in mass-market sports nutrition, pressuring mid-grade gelatin hydrolysate pricing.
Strategic Opportunities
- Ready-to-drink beverages:Liquid hydrolysate formats are penetrating functional beverage lines where dispersion speed determines manufacturing line efficiency.
- Japan FOSHU pathway:Substantiated health claims for collagen peptides command premium positioning in regulated nutraceutical channels.
- Cold-water soluble powders:Enhanced bioavailability formulations are opening topical delivery applications in dermal cosmetic pipelines.
Industry Challenges
- Peptide engineering talent scarcity:Contract manufacturers lack in-house enzymatic optimization expertise, creating dependency on external technical service providers.
- Dual-track validation burden:Separate clinical dossiers for Japan-bound versus EU-bound supply strains R&D allocation across product lines.
- Allergen labeling complexity:Evolving thresholds for bovine and marine source declarations complicate formulation flexibility across cosmetic and pharmaceutical portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gelatin Hydrolysates Market |
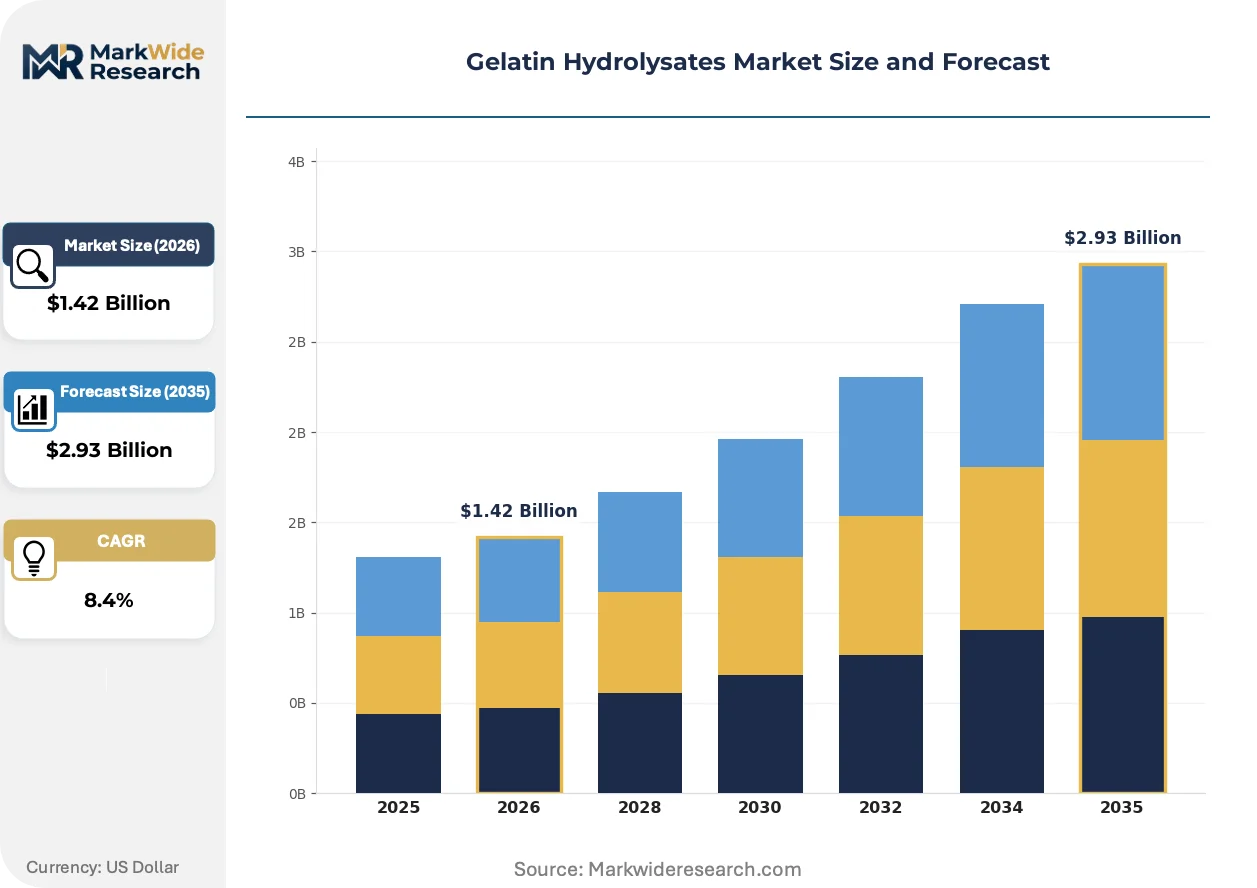
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Technical Grade Application: Dietary Supplements, Functional Foods, Personal Care, Animal Nutrition, Pharmaceuticals End User: Dietitians, Cosmetic Manufacturers, Livestock Producers, Medical Facilities, Nutraceutical Companies Form: Powder, Liquid, Granules, Tablets, Capsules |
| Companies Covered | Gelita AG, Rousselot, PB Leiner, Nitta Gelatin, Weishardt Group, Ewald-Gelatine GmbH, Italgel, Sterling Biotech, Trobas Gelatine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gelatin Hydrolysates Market Shifts & Advancements
Continuous enzymatic hydrolysis systems are collapsing traditional batch economics, while regulatory fragmentation across major jurisdictions is forcing parallel compliance investments. Procurement patterns are tilting toward toll processors with validated peptide engineering capabilities.
Continuous-flow enzymatic reactors are collapsing residence time requirements from hours to minutes while maintaining peptide molecular weight distribution control. Cosmetic and pharmaceutical contract manufacturers are adopting these systems fastest to secure cGMP-compliant capacity. The technology is collapsing minimum efficient scale thresholds, enabling mid-size toll processors to capture volumes previously reserved for integrated majors.
European Pharmacopoeia monograph updates for hydrolyzed collagen are elevating analytical testing burdens beyond the reach of smaller hydrolysate traders. FDA dietary supplement cGMP enforcement is synchronizing with EP standards, creating transatlantic compliance convergence. Pharmaceutical-grade hydrolysate suppliers are responding by consolidating testing capabilities in centralized analytical laboratories serving multiple production sites.
Aftermarket technical service contracts are unbundling from raw material supply agreements as buyers seek independent peptide optimization expertise. Cosmetic formulators in Germany and France are contracting directly with enzymatic engineering specialists rather than relying on supplier-provided support. This pattern concentrates procurement leverage with buyers possessing internal formulation capabilities while squeezing commodity traders from value-added service revenue.
Gelatin Hydrolysates Market Segmentation
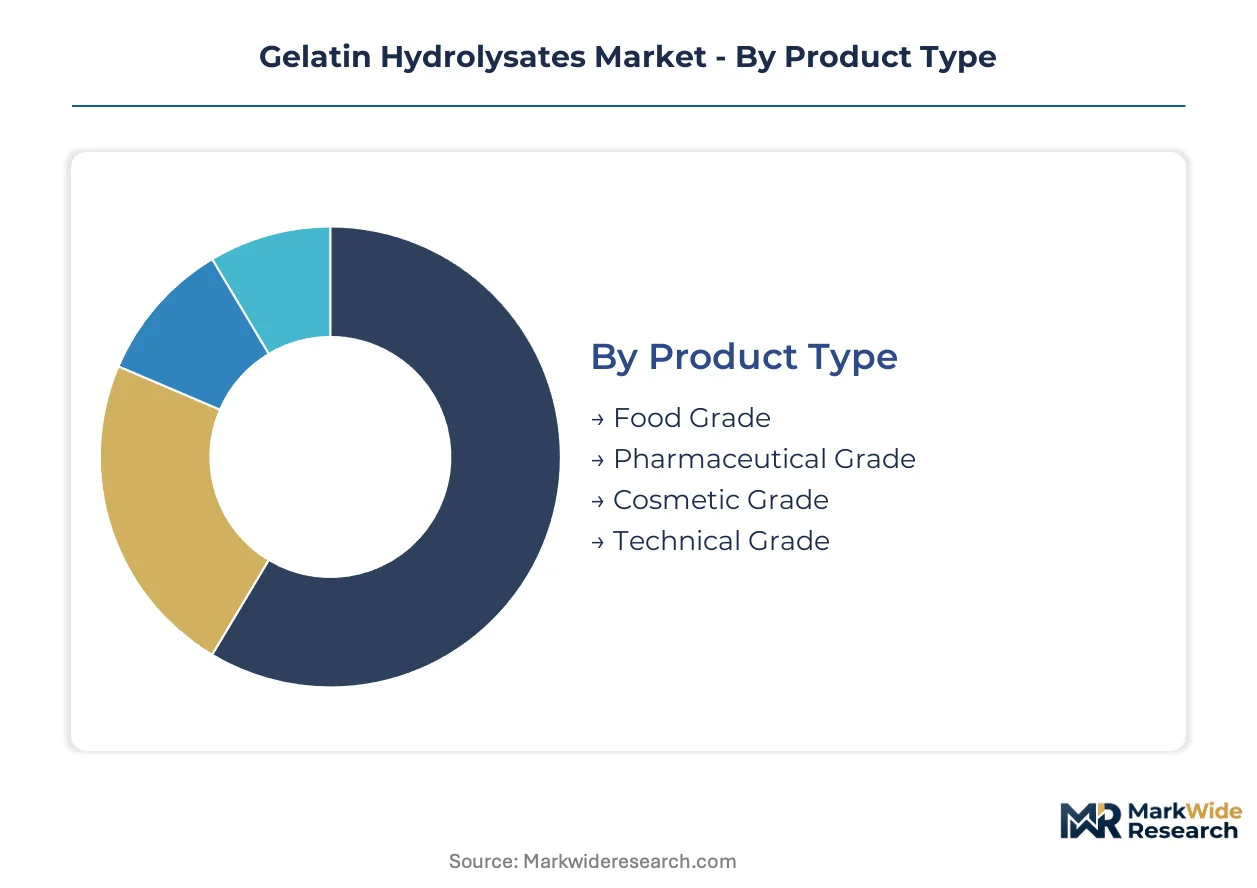
Segmentation in gelatin hydrolysates reveals how purity grades, delivery formats, and end-use specifications fragment procurement patterns across nutraceutical, pharmaceutical, and cosmetic value chains. Each dimension carries distinct compliance burdens and margin structures that reshape supplier selection criteria.
Product Type:
Purity tiers determine analytical testing intensity, regulatory documentation requirements, and accessible customer pools across the value chain.
- Pharmaceutical Grade:Hydrolysates meeting USP and EP monograph specifications for endotoxin limits, heavy metals, and molecular weight distribution. German and Swiss pharmaceutical contract manufacturers concentrate procurement here for collagen peptide parenteral and oral dosage forms, with EMA's tightened impurity thresholds elevating supplier qualification costs.
- Food Grade:Ingestible hydrolysates complying with FSSAI, FDA, and EFSA food additive frameworks for functional beverages and fortified foods. Demand clusters in United States sports nutrition and India ayurvedic formulation sectors where FSSAI's recent collagen notification requirements are reshaping import documentation.
- Cosmetic Grade:Topical peptide preparations with specified Dalton ranges for dermal penetration claims, serving French and German cosmetic formulators seeking cold-water soluble powders for anti-aging serums.
- Technical Grade:Industrial applications including photographic emulsions and adhesive formulations where bioavailability specifications are absent and cost efficiency dominates procurement.
Pharmaceutical Grade commands the established base. The steepest expansion runs through Food Grade as functional beverage lines proliferate.
Application:
End-use sectors separate by claim substantiation requirements, dosing formats, and channel regulatory intensity.
- Dietary Supplements:Collagen peptide powders and capsules positioned for joint health, skin elasticity, and sports recovery claims. United States and Japan dominate volume, with Japan's FOSHU approval pathway restricting health claims to clinically validated dossiers and creating dual-track supply requirements.
- Pharmaceuticals:Wound healing matrices, hemostatic agents, and drug delivery excipients requiring batch-level Certificates of Analysis and stability data. German medical device and pharmaceutical manufacturers anchor European demand.
- Functional Foods:Ready-to-drink beverages, fortified bars, and dairy alternatives where dispersion speed and neutral taste profiles determine formulation acceptance.
- Personal Care:Topical peptides in moisturizers, masks, and hair care where molecular weight specifications correlate with marketed penetration claims.
- Animal Nutrition:Pet food and livestock feed applications leveraging gelatin hydrolysates as palatability enhancers and protein sources with lower regulatory scrutiny than human applications.
Dietary Supplements retains the volume anchor position. Pharmaceuticals delivers the margin expansion trajectory.
End User:
Customer types fragment by technical capability, quality system maturity, and reliance on supplier technical services.
- Nutraceutical Companies:Vertically integrated brands and contract manufacturers sourcing pharmaceutical-grade hydrolysates for collagen peptide formulations, with Germany and United States facilities driving specification intensity.
- Cosmetic Manufacturers:French and German formulators demanding cold-water soluble powders with validated peptide profiles for topical delivery claims, increasingly contracting independent enzymatic engineering specialists.
- Medical Facilities:Hospitals and clinics procuring wound care products and hemostatic agents with strict lot traceability and sterilization validation requirements.
- Dietitians:Clinical practitioners recommending collagen supplementation protocols, influencing brand selection through professional channel relationships.
- Livestock Producers:Agricultural operations incorporating hydrolysates into feed formulations for palatability and protein fortification.
Nutraceutical Companies dominate procurement volume. Cosmetic Manufacturers are climbing fastest as marine-sourced alternatives penetrate pescatarian-label positioning.
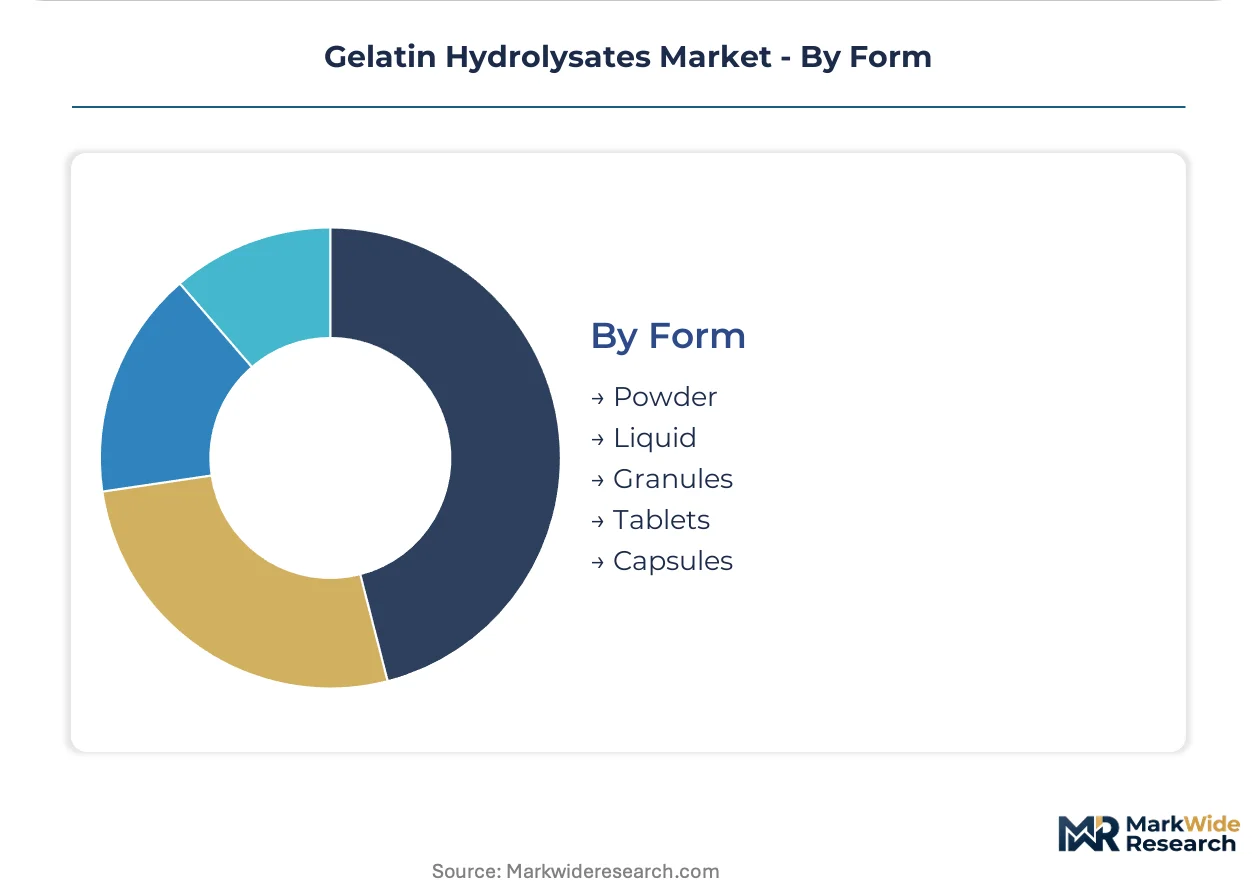
Form:
Physical formats determine handling economics, dissolution kinetics, and manufacturing line integration requirements.
- Powder:Cold-water soluble hydrolysates in bulk and sachet formats dominating industrial handling economics and dry blend applications. German and United States nutraceutical manufacturers prefer this format for tablet compression and capsule filling operations.
- Liquid:Pre-dispersed hydrolysate solutions gaining traction in ready-to-drink functional beverage lines where dispersion speed determines manufacturing line efficiency and batch consistency.
- Granules:Intermediate particle size formats for specific tableting and direct compression applications requiring controlled flow properties.
- Tablets:Finished dosage forms for retail supplement channels, typically manufactured by brand owners rather than hydrolysate suppliers.
- Capsules:Hard-shell and soft-gel delivery systems for collagen peptide supplements, with two-piece hard capsules dominating vegetarian-label positioning.
Powder commands the established base. Liquid formats are gaining share fastest in beverage manufacturing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German enzymatic hydrolysis facilities anchor supply for European cosmetic and medical buyers. Demand clusters concentrate where collagen peptide formulation capabilities intersect with stringent regulatory validation requirements.
Germany
Nutraceutical contract manufacturers in Baden-Württemberg absorb expanded pharmaceutical-grade hydrolysate output for sports nutrition applications. EMA's tightened impurity thresholds for hydrolyzed collagen elevate supplier qualification costs beyond smaller traders' reach. Gelita AG operates its R&D campus in Eberbach, sustaining leadership in cold-water soluble formulations for dermal delivery systems.
United States
FDA dietary supplement cGMP enforcement synchronizes with EP standards, creating transatlantic compliance convergence for collagen peptide suppliers. Sports nutrition brands in Utah and California drive volume throughput for anti-aging and joint health positioning. German-headquartered suppliers maintain analytical testing laboratories in New Jersey to serve North American pharmaceutical contract manufacturers.
Japan
METI oversees FOSHU approval pathways that restrict collagen peptide health claims to substantiated clinical dossiers. Osaka-based nutraceutical formulators command premium positioning in regulated channels through dual-track validation investments. Consumer demand for substantiated skin elasticity claims absorbs marine-sourced hydrolysate volumes from European toll processors.
France
Cosmetic formulators in Île-de-France contract directly with enzymatic engineering specialists rather than relying on supplier-provided technical services. ANSM monitors allergen labeling thresholds for bovine and marine sources that determine formulation flexibility across dermal pipelines. Rousselot anchors European supply through integrated rendering networks serving Paris-cluster cosmetic manufacturers.
India
FSSAI's recent collagen notification requirements reshape import documentation for hydrolysate traders serving ayurvedic formulation sectors. Maharashtra-based nutraceutical contract manufacturers lack in-house peptide engineering capabilities, creating dependency on external technical service providers. Sterling Biotech occupies a position within domestic supply chains for pharmaceutical-grade hydrolysate procurement.
Gelatin Hydrolysates Market Competitive Landscape
Integrated majors and specialized toll processors split the market between captive enzymatic capacity and outsourced peptide engineering services. Continuous-flow reactor investments compress minimum efficient scale thresholds, enabling mid-size processors to capture volumes previously reserved for large-scale operators. Three archetypes dominate: backward-integrated rendering-to-hydrolysate suppliers, toll processors with validated peptide capabilities, and marine-source specialists serving pescatarian-label positioning. Competitive moves concentrate on capacity expansion in cGMP-compliant facilities and technology licensing for continuous enzymatic systems.
Among German-headquartered suppliers, Gelita AG exemplifies the backward-integrated archetype with in-house enzymatic optimization capabilities, while Ewald-Gelatine GmbH occupies a position within specialized toll processing tiers. PB Leiner represents the marine-source specialist vector, differentiating its product slate for cosmetic brands seeking alternatives to bovine and porcine sourcing. These three anchors illustrate how geographic concentration in Western Europe intersects with divergent raw material strategies and end-use specializations.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| PB Leiner |
| Nitta Gelatin |
| Weishardt Group |
| Ewald-Gelatine GmbH |
| Italgel |
| Sterling Biotech |
| Trobas Gelatine |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit enzyme feedstock cost volatility directly into German hydrolysate pricing, amplifying the spread between pharmaceutical-grade premiums and food-grade baselines as supply concentrates around Eberbach and Lille production clusters.
Pricing Analysis
EMA's tightened impurity thresholds for hydrolyzed collagen dictate the pricing tier structure across the value chain. Three-tier pricing structure across pharmaceutical, food, and cosmetic certification levels separates USP-compliant batches from FSSAI-registered imports and technical-grade commodities. Cost compression in food-grade segments is intensifying because pea protein isolates capture sports nutrition share. Nutraceutical contract manufacturers in Utah exhibit highest price sensitivity, while Osaka-based FOSHU-validated formulators absorb premium positioning with minimal elasticity.
Supply Chain Analysis
German and French cosmetic contract manufacturers hold the densest validated peptide engineering capacity in Western Europe. Raw material procurement draws from integrated porcine rendering networks in Germany, marine collagen harvesting in Norway, and bovine processing in Argentina. Single-source vulnerability concentrates around protease enzyme supply from fermentation facilities in Denmark. Distribution runs through Rotterdam port consolidation for Asian-bound pharmaceutical grades and direct rail links to Baden-Württemberg nutraceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collagen peptide formulation platforms are approaching an interoperability inflection where FOSHU-validated dossiers become portable across EU Novel Food and FDA cGMP frameworks, compressing R&D duplication for multi-jurisdiction suppliers.
For Market Incumbents: Entrench cold-water soluble formulation leadership through captive enzymatic optimization capabilities at German R&D campuses. Add cGMP-compliant continuous-flow reactor capacity in New Jersey to defend against toll processor encroachment. Plant protein substitution in mass-market sports nutrition threatens mid-grade pricing power; respond with marine-source differentiation for pescatarian-label positioning. For New Entrants and Emerging Players: Build out peptide engineering service contracts with French cosmetic formulators seeking independent technical support outside integrated supplier relationships. India ayurvedic formulation sectors present the most penetrable white space given FSSAI notification reshaping import documentation requirements. Lead with liquid hydrolysate formats for ready-to-drink beverage manufacturing integration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors toll processors with validated continuous-flow enzymatic capabilities over backward-integrated rendering majors. Long-term viability hinges on dual-track validation infrastructure spanning EMA and PMDA jurisdictions. Monitor protease enzyme supply contract tenures as inflection signal for input cost volatility transmission.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Investment | Collapses residence time requirements while maintaining EMA-compliant peptide distribution control for cosmetic contract manufacturers. |
| FOSHU Dossier Parallel Validation | Enables premium positioning in Osaka regulated channels without duplicating clinical investment for EU-bound supply. |
| Marine-Source Raw Material Integration | Secures pescatarian-label positioning for French cosmetic formulators facing bovine allergen scrutiny. |
| Technical Service Contract Unbundling | Captures value-added revenue from German cosmetic manufacturers seeking independent peptide optimization expertise. |
| cGMP Analytical Laboratory Consolidation | Serves multiple production sites under synchronized FDA and EP testing standards for pharmaceutical-grade batches. |
Research Methodology
A standing panel of enzymatic engineering specialists, cosmetic formulator procurement leads, nutraceutical contract manufacturing executives, and FSSAI regulatory affairs officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EMA impurity threshold notifications, FDA cGMP inspection records, FOSHU approval dossiers, and customs trade data for hydrolysate imports. Bottom-up capacity modeling at continuous-flow reactor facilities triangulated against top-down demand aggregation across dietary supplement and pharmaceutical application segments.
Scenario bracketing around enzyme feedstock cost volatility, livestock disease outbreak probability, and plant protein substitution pace bounded the projection horizon. Segmentation dimensions spanned purity grade tiers, delivery format specifications, end-use regulatory intensity, and regional validation pathway clusters. CAGRs were derived from capacity utilization trajectories at German and United States production facilities, cross-referenced with collagen peptide formulation expansion rates in sports nutrition and anti-aging positioning.
Stress conditions across protease price spikes, EMA monograph revision timing, and FOSHU approval backlog duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding continuous enzymatic technology adoption curves and toll processor market share capture. Quarterly review of enzyme supply contract renewal rates and FSSAI import documentation compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Extracts and Distillates Market
Extracts
Patchouli Oil Market
Extracts
Solid Phase Extraction Market
Extracts
Algae Extracts Market
Extracts
Asia-Pacific Mineral Turpentine Market
Extracts
Glycerol Extracts Market
Extracts
Gum Turpentine Oil Market
Extracts
Global Ginseng Extracts Market
Extracts
Medicinal Plant Extracts Market
Extracts
Aloe Vera Extract Market
Extracts
Sage Extract Market
Extracts
Europe Mineral Turpentine Market
Extracts
Corn Steep Powder Market
Extracts
Herba Houttuyniae Extract Market
Extracts
Basil Extracts Market
Extracts
Global Rose Oils Market