
 Leather Chemicals Market | 2026-2036
Leather Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Chemicals Market Intelligence
Automotive interiors is shifting toward higher-grade leather specifications as OEMs upgrade cabin material standards. Lanxess sustains strong positions in water-based finishing systems through dedicated R&D scale. BASF SE differentiates via polymer chemistry breadth spanning wet-end through top-coat applications. Stahl Holdings dominates high-performance coating technologies for luxury automotive seating programs.
Leather chemicals encompass tanning agents, dyes, fatliquors, and finishing formulations that modify collagen matrices to achieve specified softness, colorfastness, and durability metrics; chromium salts remain the dominant tanning chemistry despite environmental scrutiny, while vegetable tannins and synthetic polymers gain share in premium and regulatory-sensitive segments. Chromium salts still anchors volume demand across mass-market footwear tanneries in Asia, yet vegetable tannins captures margin pools in Italian and French luxury leather goods where chrome-free claims command price premiums. Synthetic polymers expands fastest in automotive upholstery as OEMs specify consistent lot-to-lot performance and reduced volatile emissions.
REACH in Europe restricts chromium VI migration limits and mandates chemical safety dossiers for tanning auxiliaries, while EPA oversight in the US enforces wastewater discharge standards that affect tannery chemical selection; India's Central Pollution Control Board implements zero liquid discharge mandates in Kanpur and Unnao leather clusters. Stakeholders must monitor regulatory divergence between jurisdictions where chrome-free mandates advance at uneven speeds.
Market Dynamics
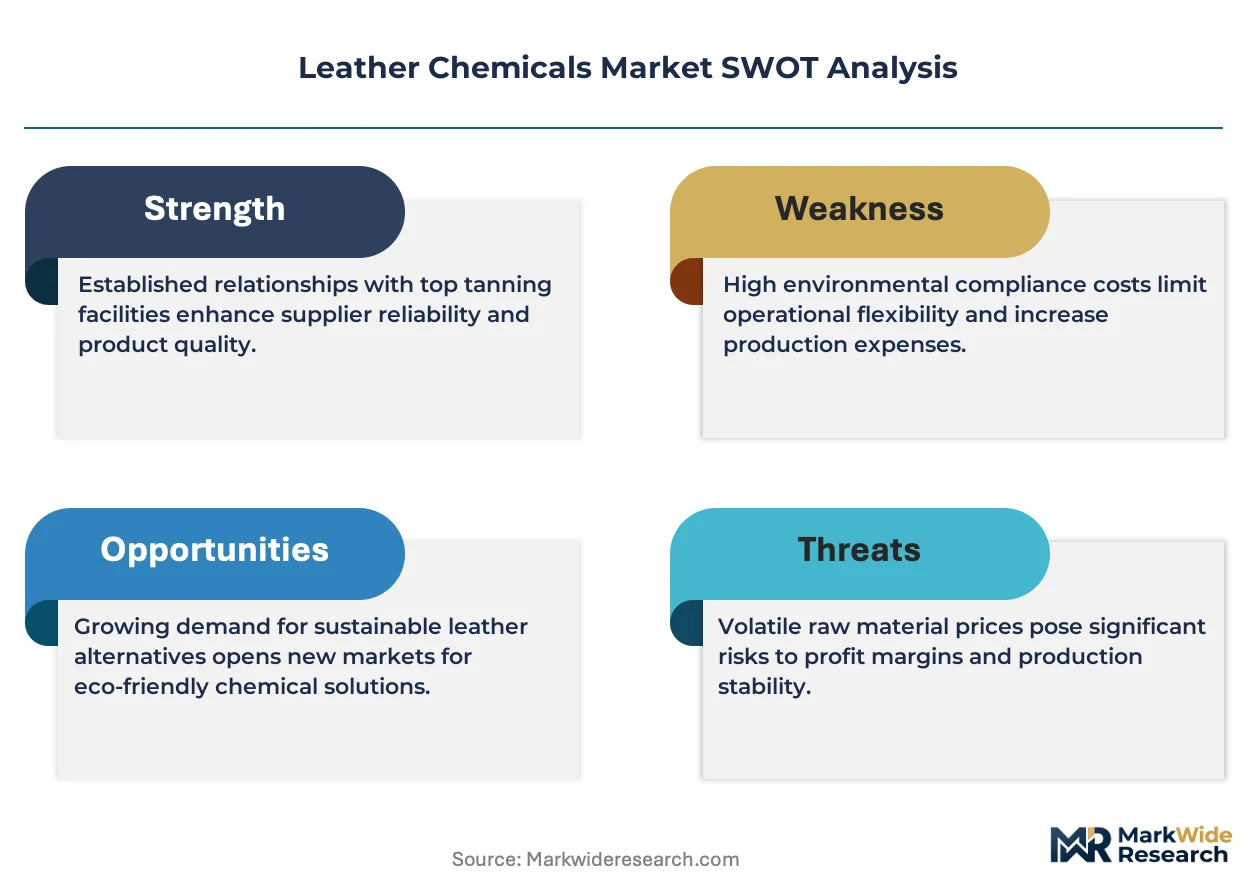
REACH compliance deadlines and EU Green Deal mandates are forcing tanneries across Italy, Germany, and France to abandon chromium-heavy processes, compressing established supply chains while creating entry points for polymer-based and vegetable-tanning alternatives. This regulatory compression is the dominant force restructuring competitive positioning.
Growth Catalysts
- EU Green Deal tanning mandates:REACH restrictions on chromium VI migration force European tanneries toward chrome-free chemistries, expanding addressable market for synthetic polymer and vegetable tannin suppliers.
- Automotive interior material upgrades:OEM specifications for cleaner cabin environments pull high-performance finishing systems into luxury and mass-market vehicle programs simultaneously.
- India leather cluster expansion:Kanpur and Unnao tanneries scale export-oriented finished leather production under zero liquid discharge mandates, concentrating wet-end chemical demand.
Market Restraints
- Chromium salt price volatility:Chrome ore supply concentration in South Africa and Kazakhstan creates input cost instability for mass-market footwear tanneries dependent on conventional tanning.
- Zero liquid discharge capex burdens:India's Central Pollution Control Board mandates require tanneries to install effluent recovery systems, raising barrier to entry for smaller Kanpur operators.
- Synthetic leather substitution:Polyurethane and microfiber alternatives capture share in automotive and accessories segments where performance specifications permit non-collagen materials.
Strategic Opportunities
- Brazilian automotive leather programs:Underpenetrated relative to European and Asian supply bases, Brazilian tanneries seek chrome-free system suppliers for export-bound seating leather.
- Water-based finishing convergence:Combination of UV-curable and water-borne technologies enables tanneries to meet volatile organic compound limits without sacrificing throughput.
- Direct tannery technical service models:Chemical suppliers bypass distributors to embed formulation chemists on-site at high-volume Italian and Indian tanneries, capturing specification control.
Industry Challenges
- Chrome-free color matching expertise:Vegetable and synthetic tanning chemistries require different dye fixation protocols, and skilled technicians familiar with both systems remain scarce in Asian mass-market tanneries.
- Multi-jurisdiction certification timelines:Tanneries supplying automotive OEMs must simultaneously satisfy REACH, EPA TSCA, and OEM-specific substance lists, extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Chemicals Market |
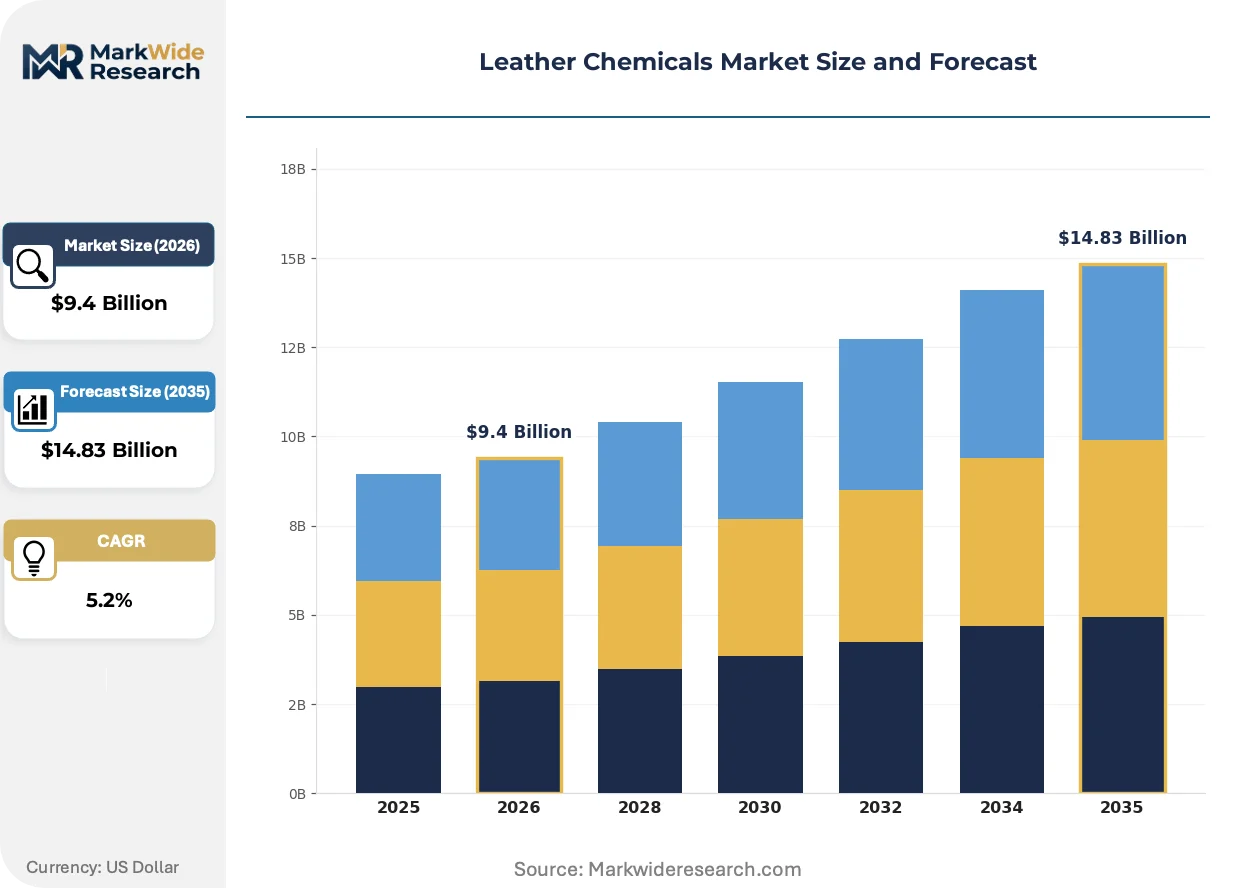
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $14.83 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromium Salts, Vegetable Tannins, Synthetic Polymers, Oil Fats Application: Footwear, Apparel, Upholstery, Automotive Interiors End User: Manufacturers, Retailers, Exporters, Distributors Packaging Type: Drums, Bags, Bulk Containers, Jerricans |
| Companies Covered | Clariant, Lanxess, Stahl Holdings, Zschimmer & Schwarz GmbH & Co KG, DyStar Group, BASF SE, Elementis plc, TEXAPEL, TFL Ledertechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Chemicals Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward water-borne and bio-based systems as regulatory thresholds tighten and automotive buyers consolidate supplier bases around compliant, consistent performance. Three developments dominate this transition.
Enzyme-assisted bating and degreasing is decentralizing process control from centralized chemical suppliers to tannery floor technicians. Mid-scale Indian and Brazilian tanneries adopt these systems to reduce chemical oxygen demand in effluent while maintaining throughput. The technology is decentralizing technical decision-making and compressing margins on conventional surfactant and solvent offerings from established suppliers.
REACH authorization requirements for chromium compounds are accelerating chrome-free process validation across European tanneries. ECHA's sunset dates for certain chromium salts force tanneries to qualify alternative cross-linking chemistries ahead of formal restrictions. Italian luxury leather goods manufacturers are responding fastest, converting production lines to vegetable and synthetic polymer systems to secure brand-level chrome-free claims.
Automotive OEMs now mandate lot-to-lot consistency certificates backed by third-party testing, replacing informal supplier relationships with audited quality agreements. Tier-one seating suppliers consolidate chemical vendor lists to three or fewer per tannery, prioritizing those with embedded technical service and global formulation standardization. This concentration is most visible in German and Japanese automotive supply chains, where single-source accountability reduces OEM audit burden.
Leather Chemicals Market Segmentation
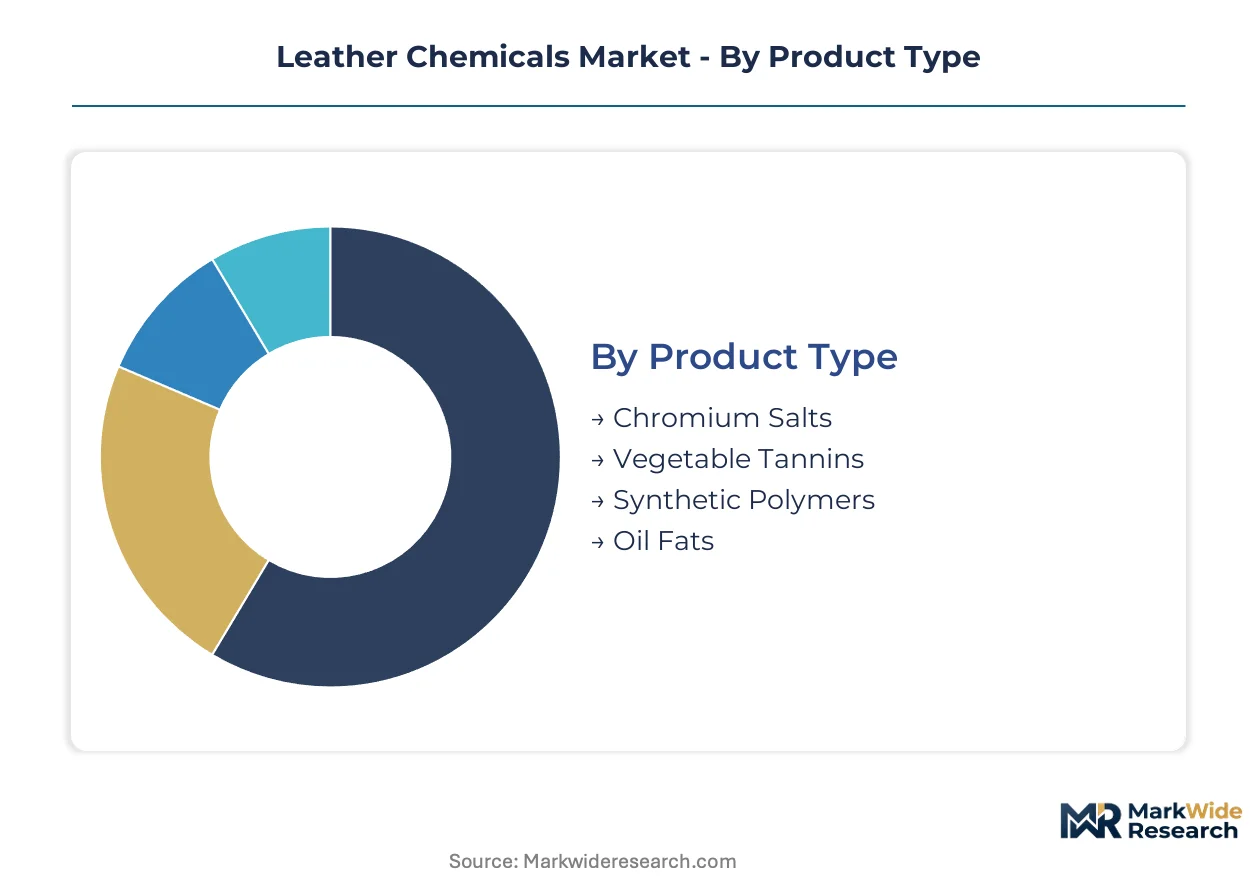
Leather chemical segmentation reveals divergent margin structures across tanning chemistries and end-use specifications. Product type splits between commodity chromium salts and premium vegetable or polymer alternatives directly shape supplier profitability and regulatory exposure.
Product Type:
Volume concentration favors conventional mineral tanning, while premium positioning clusters around bio-based and synthetic alternatives that command specification control in automotive and luxury goods.
- Chromium Salts:Basic chromium sulfate and chromium III salts remain the dominant cross-linking chemistry for collagen stabilization. Mass-market footwear tanneries in India and China rely on this chemistry for cost efficiency and processing speed, though REACH sunset dates in Europe are compressing long-term demand visibility.
- Vegetable Tannins:Extracts from quebracho, mimosa, and chestnut wood deliver chrome-free leather with distinctive aesthetic aging characteristics. Italian luxury leather goods manufacturers specify these systems to secure brand-level sustainability claims that support price premiums in export markets.
- Synthetic Polymers:Polyurethane dispersions and acrylic resins enable consistent lot-to-lot performance with reduced volatile emissions. Automotive seating programs specify these chemistries for cabin air quality compliance.
- Oil Fats:Sulfonated fish oils and synthetic fatliquors restore suppleness to tanned hides through internal lubrication of collagen fibers.
Mature deployment sits with chromium salts across Asian footwear clusters. Newer deployment is concentrated in vegetable tannins and synthetic polymers serving European automotive and luxury goods specifications.
Application:
End-use differentiation tracks durability requirements, with automotive and upholstery commanding the most stringent performance certifications.
- Footwear:Mass-market sneaker and leather shoe production consumes the largest chemical volumes, particularly chromium-based wet-end systems. Kanpur tanneries supply export-oriented finished leather to global footwear brands under zero liquid discharge mandates.
- Automotive Interiors:OEM specifications for fogging resistance, abrasion durability, and volatile organic compound limits pull high-performance finishing systems into seating and dashboard programs. German and Japanese tier-one suppliers consolidate vendor lists to three or fewer chemical partners per tannery.
- Apparel:Garment leather requires soft handle and consistent dye uptake, driving demand for specialized fatliquors and dye auxiliaries.
- Upholstery:Residential and commercial furniture leather emphasizes flame retardancy and stain resistance in formulation requirements.
Procurement consolidation is most advanced in automotive interiors, where single-source accountability reduces OEM audit burden. Footwear retains fragmented multi-supplier relationships.
End User:
Channel structure determines technical service intensity, with direct manufacturer relationships capturing specification influence.
- Manufacturers:Integrated tanneries with in-house finishing operations purchase wet-end and top-coat chemistries directly, embedding supplier technical staff on-site for process optimization.
- Exporters:Indian and Brazilian finished leather exporters require certified chrome-free systems to access European and North American automotive supply chains.
- Retailers:Private-label leather goods retailers specify chemical standards through supplier codes of conduct without direct procurement involvement.
- Distributors:Regional chemical distributors serve smaller tanneries with standardized product ranges and limited technical support.
Margin capture concentrates with manufacturer-direct relationships. Distributor channels face compression from price transparency and reduced service differentiation.
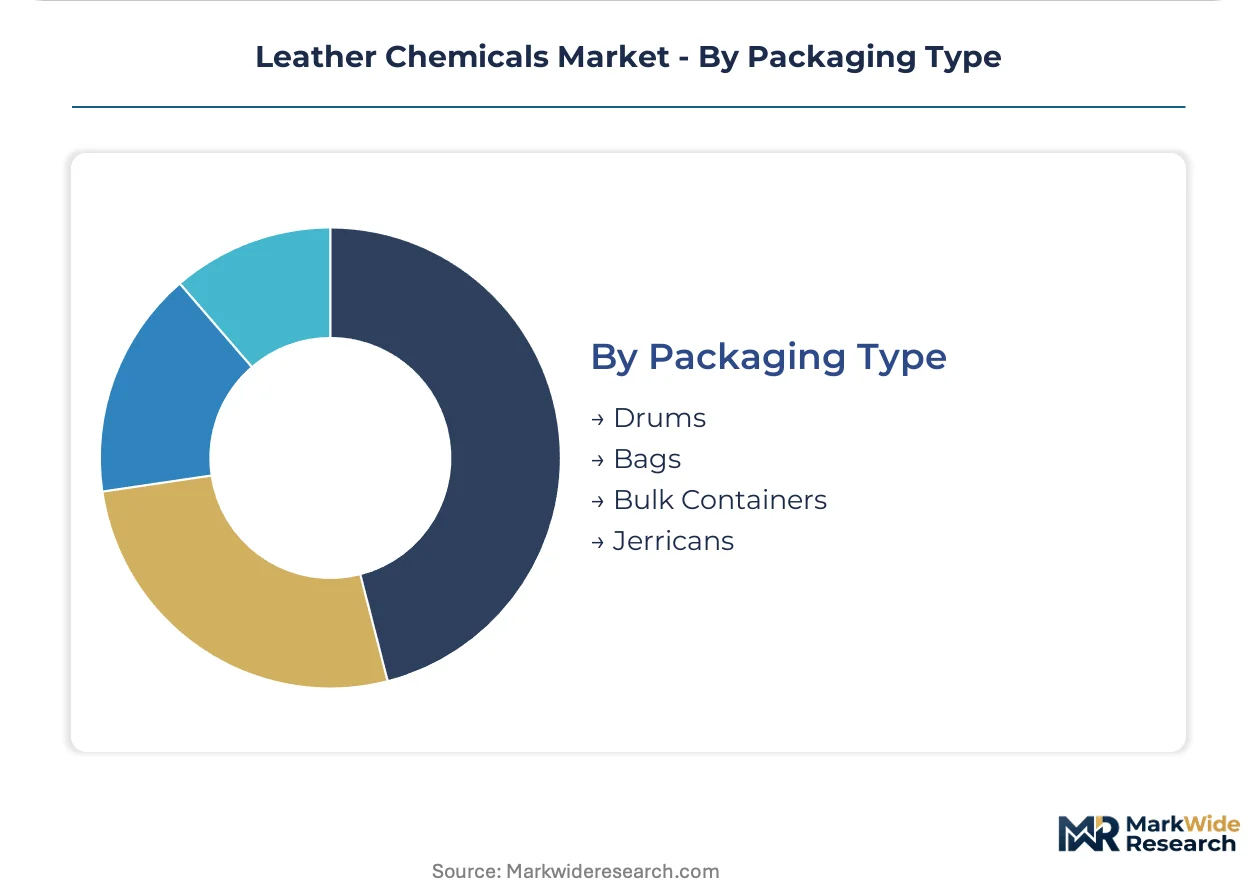
Packaging Type:
Packaging selection tracks shipment scale and chemical stability requirements, with liquid systems dominating high-volume automotive supply.
- Bulk Containers:ISO tank deliveries of chromium salt solutions and polymer dispersions serve high-volume Italian and Indian tanneries with dedicated storage infrastructure.
- Drums:Standard 200-liter steel and plastic drums remain the default for mid-scale tanneries across multiple chemistries, balancing handling convenience with inventory flexibility.
- Bags:Multi-layer paper and woven polypropylene bags package powdered vegetable tannins and solid fatliquor flakes for moisture protection.
- Jerricans:20-30 liter containers serve specialty dye and auxiliary shipments to small-batch luxury leather producers.
Packaging standardization is highest in bulk liquid systems serving automotive programs. Specialty solid chemistries retain fragmented packaging formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in India and China while consumption tilts toward European automotive and luxury goods sectors. This geographic asymmetry shapes chemical formulation standards and regulatory compliance requirements across supply chains.
India
Kanpur and Unnao leather clusters scale export-oriented finished leather production for global footwear brands. The Central Pollution Control Board enforces zero liquid discharge mandates requiring effluent recovery system installation. Tamil Nadu tanneries in Ambur and Vaniyambadi expand chrome-free capacity to access European automotive supply chains.
China
Wenzhou and Guangdong footwear manufacturers consume massive chromium salt volumes despite environmental ministry pressure. The Ministry of Ecology and Environment tightens wastewater discharge standards across Zhejiang and Fujian tanning belts. Hebei province clusters face capacity consolidation as smaller operators fail pollution control upgrades.
Germany
Automotive seating suppliers in Bavaria and Baden-Württemberg consolidate chemical vendor lists to three or fewer partners per tannery. ECHA sunset dates for chromium compounds accelerate chrome-free process validation across southern German supply chains. Stuttgart-area technical centers embed supplier chemists on-site for formulation standardization.
Italy
Luxury leather goods manufacturers in Tuscany and Veneto convert production lines to vegetable tanning systems for brand-level chrome-free claims. REACH restrictions on chromium VI migration drive chemical substitution across Arzignano and Santa Croce sull'Arno tanning districts. Solofra tanneries specialize in high-value calfskin finishing for export-bound accessories.
Brazil
Underpenetrated automotive leather capacity in Rio Grande do Sul seeks chrome-free system suppliers for export-bound seating programs. ANVISA oversight of chemical imports creates qualification timelines distinct from European or North American protocols. São Paulo state tanneries pivot from commodity footwear leather toward higher-specification automotive grades.
Leather Chemicals Market Key Industry Players
Top-tier vendors anchor automotive and luxury supply chains, while mid-scale regional formulators serve fragmented footwear clusters. German and Swiss specialty chemical groups concentrate on high-performance finishing systems with embedded technical service. Three archetypes dominate: polymer chemistry specialists, vegetable tannin extractors, and integrated wet-end-through-top-coat suppliers. Competitive moves center on direct tannery technical embedding and water-based formulation licensing.
Within the integrated wet-end-through-top-coat tier, BASF SE and Lanxess occupy positions exemplifying polymer chemistry breadth and water-based system scale respectively. Stahl Holdings represents the high-performance coating technology archetype for luxury automotive seating programs. These three anchors demonstrate how specification control in automotive supply chains concentrates around vendors with global formulation standardization and on-site technical deployment capabilities.
| Leading Market Players |
|---|
| Clariant |
| Lanxess |
| Stahl Holdings |
| Zschimmer & Schwarz GmbH & Co KG |
| DyStar Group |
| BASF SE |
| Elementis plc |
| TEXAPEL |
| TFL Ledertechnik GmbH |
| Others |
Cost & Logistics Intelligence
Backward integration into chrome ore sourcing anchors pricing power for South African and Kazakh suppliers, while European tanneries absorb premium costs for REACH-compliant alternatives. This integration choice compresses margins for mass-market footwear chemical buyers in India and China.
Pricing Analysis
Short lead-time premiums of 15-20% apply to synthetic polymer dispersions serving automotive seating programs with just-in-line delivery requirements. Three-tier pricing structure across premium vegetable tannins, standard chromium salts, and economy-grade fatliquors reflects certification grade and volume scale differentiation. Cost compression in commodity chromium sulfate is intensifying because of ore supply concentration and energy input volatility. Mass-market footwear tanneries in Kanpur exhibit highest price sensitivity, while German automotive tier-one suppliers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Freight costs from South African chrome ore ports to Asian tanning clusters represent 8-12% of landed chromium salt value, driving regional sourcing preferences. Supply concentrates in South Africa, Kazakhstan, and Turkey for mineral tanning inputs, while vegetable tannins draw from Argentina, Brazil, and South African mimosa bark. Raw material dependencies rest on chromium ore, quebracho extract, and petroleum-derived polymer feedstocks. Single-source vulnerability in chrome ore creates supply chain risk for conventional wet-end chemistry. Distribution runs through bulk ISO tank deliveries to high-volume tanneries, with drum shipments serving mid-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over water-based formulation R&D and on-site technical service teams determines specification capture in automotive supply chains.
For Market Incumbents: Acquire specialized vegetable tannin extraction assets in South America to secure chrome-free raw material positions ahead of REACH sunset deadlines. Consolidate formulation standardization capabilities across European technical centers to defend against polymer-focused entrants. Embedded technical service teams at Italian luxury tanneries represent the critical lever for maintaining specification control. For New Entrants and Emerging Players: Enter via underpenetrated Brazilian automotive leather programs where chrome-free system suppliers remain scarce relative to European and Asian bases. Target Rio Grande do Sul tanneries seeking export qualification for German OEM seating programs. Direct technical embedding with on-site formulation chemists offers the most penetrable go-to-market angle against distributor-dependent incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated specialty chemical groups seeking automotive specification control. Long-term viability favors vendors with captive water-based polymer technology and embedded service models rather than commodity chromium salt traders. Watch for ECHA acceleration of chromium compound authorization timelines as the inflection signal for chrome-free chemistry valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chrome-Free Raw Materials | Secures quebracho and mimosa extract supply for REACH-compliant tanning systems ahead of regulatory deadlines. |
| Embedded Technical Service Deployment | Positions formulation chemists on-site at high-volume Italian and Indian tanneries to capture specification influence. |
| Water-Based Finishing Scale-Up | Enables compliance with automotive OEM volatile organic compound limits without sacrificing throughput speed. |
| Automotive Supply Chain Qualification | Consolidates vendor lists to three or fewer chemical partners per tannery under German tier-one supplier mandates. |
| Zero Liquid Discharge System Partnerships | Aligns chemical suppliers with Kanpur and Unnao tanneries facing Central Pollution Control Board effluent mandates. |
Research Approach
Document review covered customs trade databases, ECHA substance registration filings, and tannery association sustainability reports, complemented by interviews with plant managers at Indian and Italian tanning clusters, procurement leads at German automotive seating suppliers, and technical R&D directors at specialty chemical formulators. Primary fieldwork validated secondary data from SEC 10-K filings and Cefic sector analyses. Bottom-up chemical volume estimates triangulated against top-down end-use consumption models.
Historical capacity utilization trends cross-referenced against expert panel input on regulatory timeline probabilities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include tanning chemistry type, end-use application tier, packaging format, and regional production hub. CAGRs derived from regression analysis of input cost trajectories and substitution elasticity parameters. Chrome ore price volatility and REACH authorization schedule uncertainty served as key forecast sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA chromium restriction scenarios or automotive OEM specification reversions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Elemental Formula Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Refinery Process Chemicals Market