
 Bill Splitting Apps Market | 2026-2036
Bill Splitting Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Bill Splitting Apps Market Analysis
A capital-intensity divergence between well-funded payment incumbents and lean standalone developers is reorganizing competitive dynamics in the bill splitting apps space. PayPal Holdings Inc. leverages its existing payment rails and merchant network to embed splitting features within broader financial workflows. Splitwise Inc. sustains user loyalty through purpose-built expense tracking and group management tools that generalist platforms struggle to replicate.
Bill splitting apps are software platforms that calculate, track, and settle shared financial obligations among multiple parties, typically processing transactions through linked bank accounts, debit cards, or stored-value balances with real-time synchronization across iOS and Android ecosystems. These applications serve the commercial purpose of reducing friction in informal group transactions where traditional invoicing or cash settlement proves inefficient. Mobile apps command the largest user base due to ubiquitous smartphone penetration and push-notification engagement, while peer-to-peer payment systems capture the highest transaction velocity by embedding splitting logic directly within payment flows. Banking integration represents the fastest-evolving service layer as open APIs enable instant account verification and automated settlement, though standalone solutions retain significant share among privacy-conscious users seeking minimal data sharing.
The Consumer Financial Protection Bureau in the United States enforces electronic fund transfer rules that govern dispute resolution and liability limits for P2P transactions, directly shaping product design and user agreement structures. The EU's PSD2 framework and GDPR impose strong authentication and data consent requirements on apps with banking integration, creating compliance cost barriers for new entrants. Stakeholders must monitor evolving state-level money transmission licensing requirements and central bank digital currency pilots that could reshape settlement infrastructure.
Market Dynamics
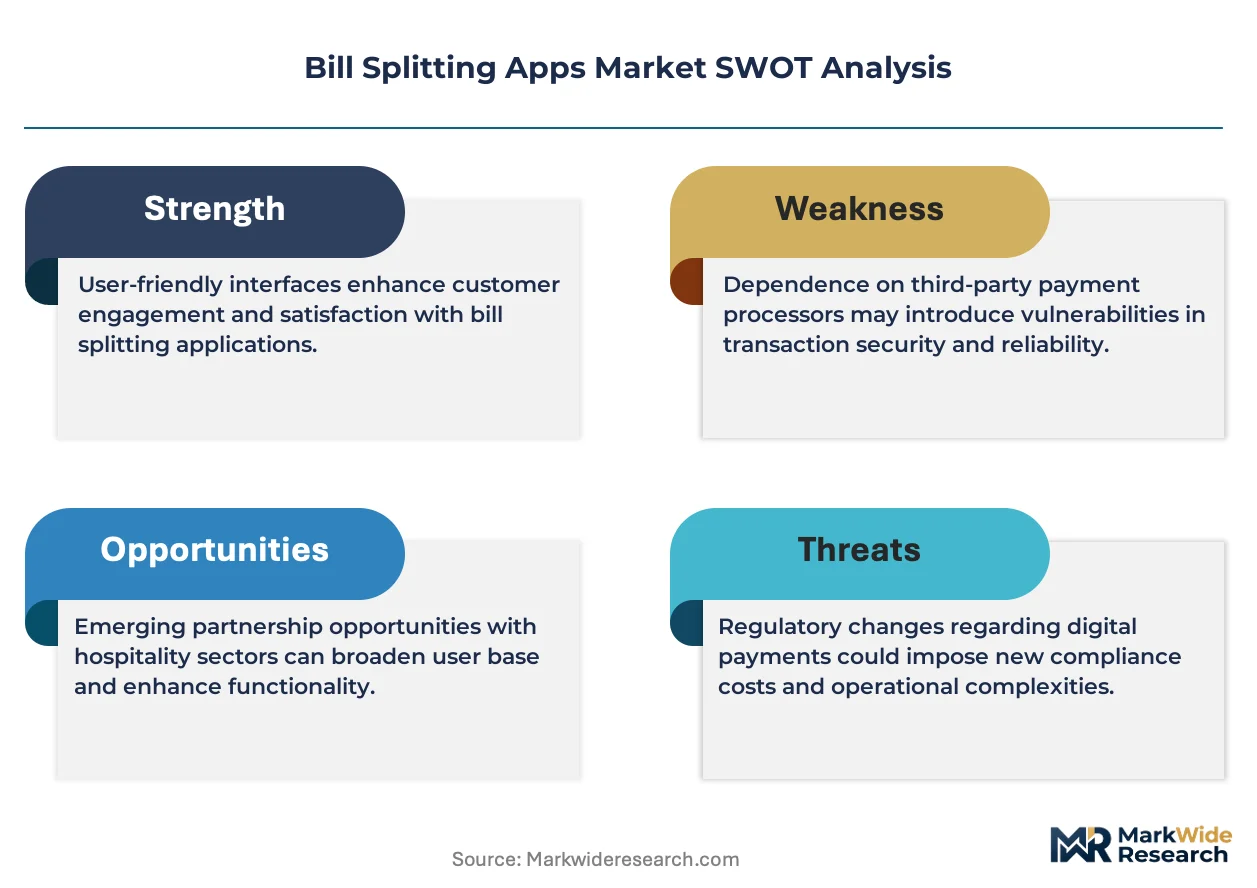
Open banking mandates are forcing fintech platforms to rebuild their technical infrastructure around standardized APIs, fundamentally altering how bill splitting apps authenticate users and execute settlements.
Growth Catalysts
- PSD2 Strong Customer Authentication:The EU's directive compels banks to expose payment initiation APIs, lowering integration barriers for third-party apps seeking direct account access.
- Young Professional Co-Living:Urban housing cost pressures in cities like New York, London, and Berlin drive recurring demand for automated rent and utility splitting.
- Real-Time Payment Rails:FedNow and similar instant settlement networks eliminate the float-dependent business models that previously constrained P2P platform economics.
Market Restraints
- Money Transmission Licensing:US state-by-state licensing creates compliance cost moats that favor incumbents with existing regulatory infrastructure.
- Bank API Reliability:European banks exhibit uneven technical readiness for PSD2 interfaces, producing service interruptions that erode user trust.
- Cash Settlement Persistence:Informal cash handling among older demographics and cash-preferred merchant categories limits addressable market expansion.
Strategic Opportunities
- Embedded Finance Convergence:Bill splitting functionality is decomposing into vertical SaaS platforms for property management, travel booking, and event planning.
- India UPI Integration:The country's unified payments interface offers standardized, low-cost rails for domestic and cross-border settlement innovation.
- Carbon Footprint Tracking:Shared expense data enables attribution of group consumption emissions, opening subscription tiers for climate-conscious user segments.
Industry Challenges
- Data Localization Requirements:Divergent national storage mandates complicate cloud architecture for apps serving multiple jurisdictions.
- Fraud Liability Allocation:Ambiguity in P2P transaction dispute resolution between platforms, banks, and users generates operational risk and support cost inflation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bill Splitting Apps Market |
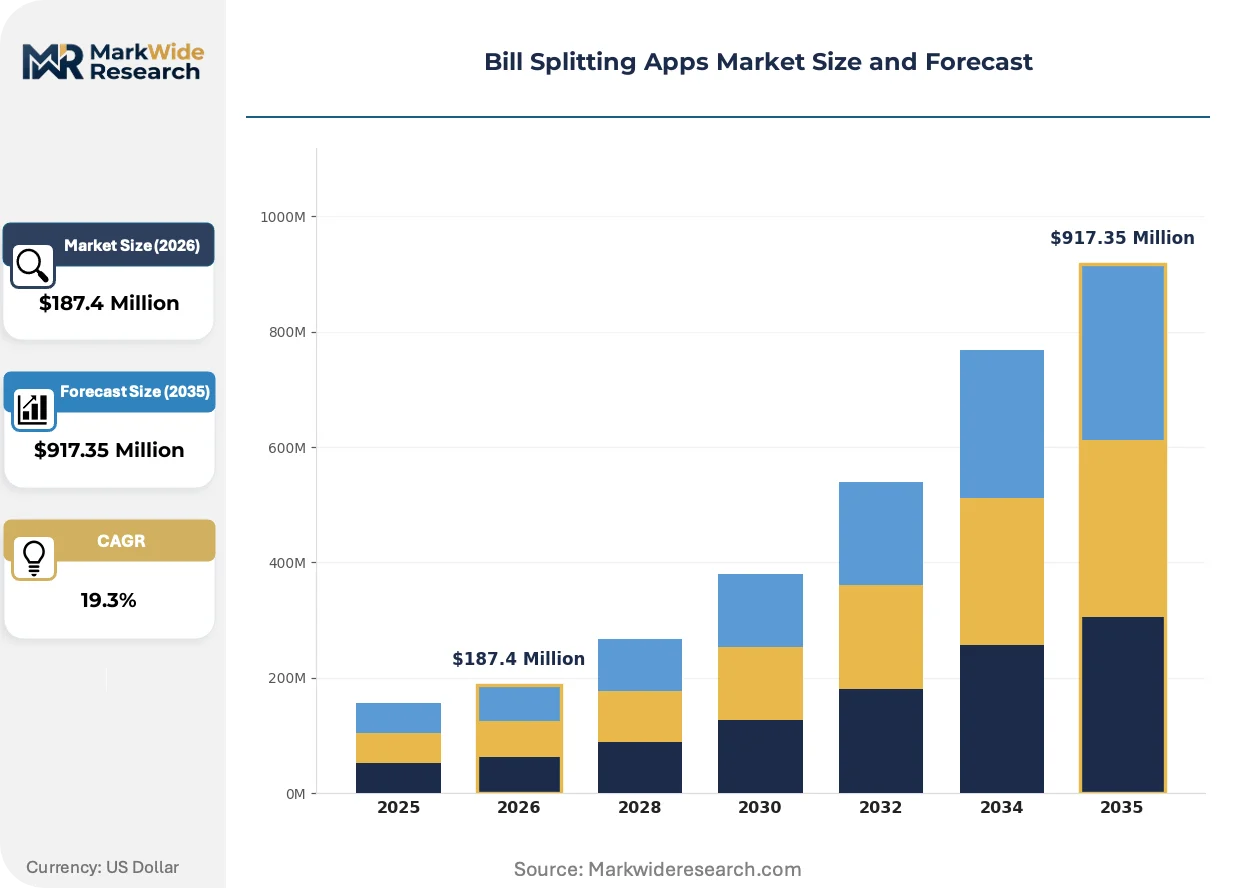
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $917.35 Million |
| CAGR (2026 – 2036) | 19.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Apps, Desktop Software, Peer-to-Peer Payment Systems End User: Roommates, Friends, Families, Business Groups Service Type: Direct Payments, Invoice Management, Budget Tracking, Expense Sharing Integration Level: Banking Integration, Social Media Integration, Accounting Software Connectivity, Standalone Solutions |
| Companies Covered | Splitwise Inc., PayPal Holdings Inc., Venmo, Tricount S.A., Block Inc., Bill.com LLC, Divvy, Bring10 LLC, Zelle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bill Splitting Apps Market Emerging Trajectories
Friction reduction in group financial coordination is driving technical investment toward invisible, context-aware settlement experiences rather than standalone application interfaces.
Embedded splitting logic is decomposing the traditional bill splitting app architecture. Payment processors now natively support group transaction division at the point of sale, eliminating the need for separate expense tracking workflows. Young professionals adopting these integrated experiences show reduced tolerance for manual data entry and app-switching friction.
GDPR Article 20 data portability requirements are reshaping user retention strategies. Platforms must engineer technical infrastructure enabling seamless account migration, compressing switching costs and intensifying competition on feature differentiation rather than data lock-in. European operators face the steepest compliance investment curves.
Subscription fatigue among digital natives is compressing willingness to pay for premium tiers. Freemium models face pressure from bank-native alternatives bundled at zero marginal cost. This behavioral shift concentrates monetization success in markets with weaker incumbent banking digitalization, particularly in Southern Europe and select Asian economies where standalone apps retain pricing power.
Bill Splitting Apps Market Segmentation
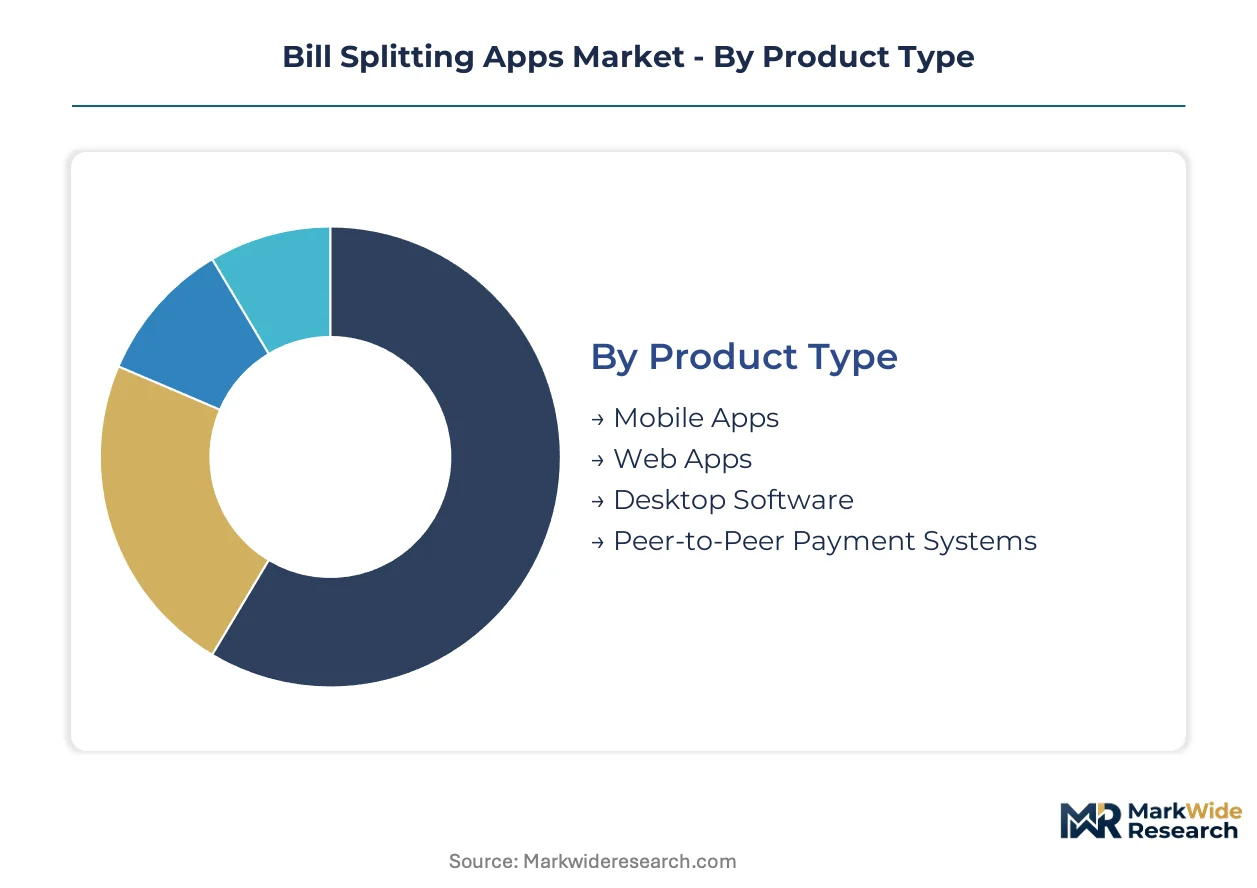
Segmentation in bill splitting apps reveals how revenue pools align with technical architecture choices and user relationship patterns. Platform developers optimize feature sets differently across these divides, with integration depth and social context driving monetization viability.
Product Type:
Margin pools concentrate where user acquisition costs are lowest and engagement frequency is highest, favoring mobile-native architectures with push-notification retention mechanics.
- Mobile Apps:Native iOS and Android applications dominate transaction volume through biometric authentication, real-time sync, and location-aware group formation. Young professionals in New York and London generate recurring demand for rent-splitting automation, though app store commission structures compress net margins.
- Peer-to-Peer Payment Systems:Embedded splitting logic within payment flows eliminates standalone app friction. Venmo and similar platforms capture the highest transaction velocity by integrating division features directly at settlement, reducing drop-off rates compared to separate expense-tracking workflows.
- Web Apps:Browser-based platforms serve enterprise procurement teams and cross-platform users requiring desktop-grade expense reporting without installation barriers.
- Desktop Software:Legacy installations persist among small business accountants managing multi-party vendor payments through QuickBooks-connected workflows.
Mobile Apps hold installed capacity. Peer-to-Peer Payment Systems are rotating up the share rankings.
End User:
Volume concentrates in recurring domestic arrangements where trust asymmetries are lowest and settlement predictability is highest.
- Roommates:Urban co-living arrangements in Berlin, San Francisco, and Toronto drive automated rent and utility splitting with the highest monthly active session frequency. Lease synchronization features and recurring payment schedules reduce churn compared to ad-hoc social splitting.
- Friends:Travel, dining, and entertainment expenses generate spiky transaction patterns with lower lifetime value but higher viral coefficient potential. Group trip planning in Barcelona and Amsterdam creates concentrated demand bursts around festival and holiday seasons.
- Families:Multi-generational household expense management spans childcare, eldercare, and shared property costs with longer decision cycles and higher average transaction values.
- Business Groups:Corporate teams require audit trails, receipt capture, and policy compliance features that command premium pricing but face procurement approval friction.
Roommates anchor revenue stability. Friends deliver the steepest expansion trajectory through network effects.
Service Type:
Application breadth determines pricing tier eligibility, with multi-module platforms capturing subscription upgrades more effectively than single-function tools.
- Expense Sharing:Core division algorithms with uneven split logic, currency conversion, and group balance tracking constitute the baseline feature set. European users under PSD2 frameworks prioritize SEPA-integrated settlement speed.
- Budget Tracking:Categorical spending analysis and savings goal attribution for groups opens subscription tiers among financially-engaged user segments in Scandinavia and Germany.
- Direct Payments:Instant settlement through linked accounts or stored balances generates interchange revenue but requires money transmission licensing compliance.
- Invoice Management:Formal receivable tracking with PDF generation and payment reminders serves freelance collectives and small business expense recovery.
Expense Sharing holds installed capacity. Budget Tracking is rotating up the share rankings.
Integration Level:
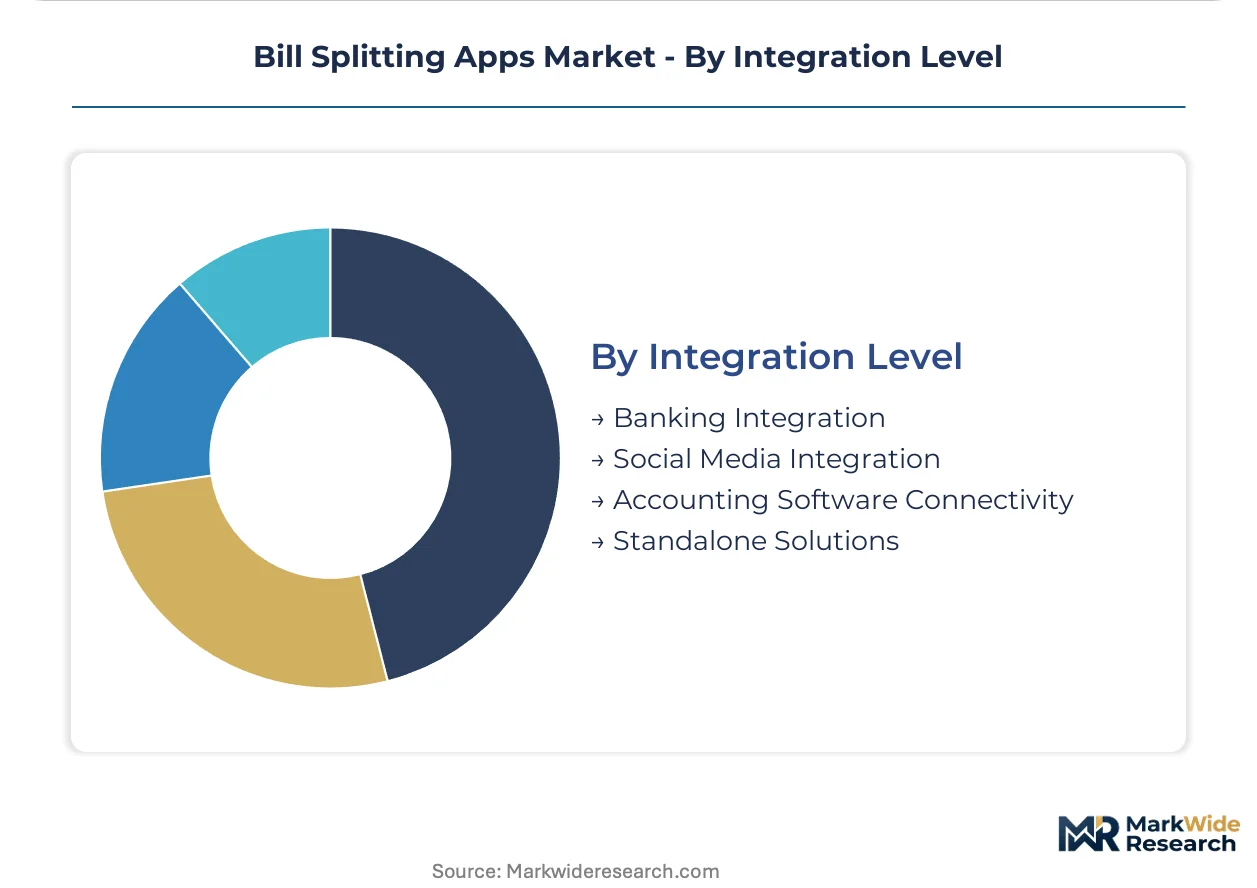
Technical depth correlates with user retention and data monetization potential, though privacy-conscious segments sustain demand for minimal-exposure alternatives.
- Banking Integration:Open API connections enabling instant account verification, automated settlement, and transaction enrichment deliver the lowest friction experience. EU PSD2 mandates and US FedNow adoption are accelerating infrastructure investment requirements.
- Standalone Solutions:Privacy-preserving platforms without external data sharing retain significant share among GDPR-sensitive users and cash-preference demographics in Southern Europe.
- Social Media Integration:Contact import and group formation through WhatsApp, Messenger, and WeChat reduces onboarding friction in Asian and Latin American markets.
- Accounting Software Connectivity:QuickBooks, Xero, and SAP synchronization targets small business and property management verticals with exportable expense reports.
Banking Integration holds installed capacity. Standalone Solutions are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. US users show lowest price sensitivity due to entrenched P2P payment culture, while Southern European markets resist subscription fees amid weaker banking digitalization.
United States
FedNow instant settlement rails and young professional co-living in New York and San Francisco drive platform adoption. The Consumer Financial Protection Bureau enforces electronic fund transfer rules governing dispute resolution. Venmo and Zelle dominate transaction velocity through embedded splitting logic.
Germany
PSD2 strong customer authentication mandates accelerate open banking integration for rent-splitting automation. Berlin's housing cost pressures sustain recurring demand among urban roommates. Frankfurt's fintech cluster hosts multiple banking API infrastructure providers serving third-party apps.
United Kingdom
London's dense flatshare market generates highest European session frequency for utility bill automation. The Financial Conduct Authority oversees payment initiation service provider authorizations under PSD2 equivalence rules. Manchester and Edinburgh emerging tech hubs incubate standalone privacy-focused alternatives.
India
UPI unified payments interface enables low-cost domestic settlement rails for group expense division. The Reserve Bank of India regulates payment aggregators and payment gateways under PSS Act licensing. Bengaluru and Mumbai fintech clusters concentrate developer talent for embedded finance integration.
Brazil
Pix instant payment system adoption reduces friction for informal group transactions among young professionals. The Central Bank of Brazil governs payment arrangement regulations for fintech platforms. São Paulo's startup ecosystem hosts emerging social payment solutions targeting LATAM expansion.
Bill Splitting Apps Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the bill splitting apps space. Payment incumbents leverage existing rails and merchant networks to embed splitting features, while standalone developers sustain loyalty through purpose-built expense tracking. Three archetypes dominate: banking-integrated generalists, privacy-preserving specialists, and vertical SaaS embedders. Competitive moves concentrate on strategic partnerships with property management platforms and geographic expansion through regulatory licensing.
Within the specialist tier, Splitwise Inc. and Tricount S.A. exemplify purpose-built expense tracking architectures that generalist platforms struggle to replicate. PayPal Holdings Inc. anchors the integrated leader position, occupying a scale-driven role where existing payment infrastructure depresses customer acquisition costs. These three represent the structural divergence between lean standalone development and capital-intensive incumbent expansion.
| Leading Market Players |
|---|
| Splitwise Inc. |
| PayPal Holdings Inc. |
| Venmo |
| Tricount S.A. |
| Block Inc. |
| Bill.com LLC |
| Divvy |
| Bring10 LLC |
| Zelle |
| Others |
Supply Flow & Price Mechanics
Thirty-to-ninety-day API integration lead times for banking connectivity concentrate pricing power among incumbents with pre-built regulatory infrastructure, while lean developers absorb compliance costs that compress their margin flexibility. This supply-side asymmetry feeds directly into tiered subscription economics, where faster settlement capabilities command premium positioning against manual-entry alternatives.
Pricing Analysis
Interchange revenue from instant settlement tiers drives lifetime value more than subscription fees alone. The dominant pricing structure runs SaaS-tiered with freemium entry points, premium-mid-economy pricing differentiation separates API-integrated automation from basic expense logging, and pricing pressure stems from bank-native alternatives bundling splitting at zero marginal cost. Small business segments show highest price sensitivity, while urban co-living roommates in New York and London demonstrate lowest sensitivity due to recurring utility automation needs.
Supply Chain Analysis
Inventory-light cloud architectures with near-zero provisioning lead times enable rapid geographic scaling without physical infrastructure constraints. Supply concentrates in the United States, Germany, and India where banking API density and fintech developer talent pools overlap, the stack draws from payment processor networks, identity verification services, and cloud hosting providers, and single-source vulnerability in critical banking APIs creates concentration risk. Distribution runs through app store ecosystems and direct enterprise sales for vertical embedders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in bill splitting apps sit at an inflection where open banking interoperability is decomposing standalone applications into embedded service layers. The shift toward invisible, context-aware settlement experiences rewards infrastructure-heavy positioning over interface-centric development.
For Market Incumbents: Compound defensive moats through deeper banking API exclusivity arrangements and accelerated FedNow settlement integration. Vertical integration into property management software ecosystems counters the threat of embedded finance convergence, while certification investment in state-level money transmission licensing preserves geographic expansion optionality against leaner challengers. For New Entrants and Emerging Players: Privacy-preserving standalone architectures represent the most penetrable white-space where GDPR-sensitive users in Southern Europe resist data sharing. Carbon footprint attribution for group expenses offers an unclaimed subscription tier among climate-conscious segments in Scandinavia. A go-to-market angle anchored in festival and travel seasonality in Barcelona and Amsterdam exploits spiky demand patterns that incumbents under-serve. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because settlement rail access and regulatory licensing accumulate durable competitive advantage faster than interface innovation. Acquisition targets should display banking API depth and multi-jurisdiction compliance infrastructure. The signal to watch is central bank digital currency pilot expansion, which would reshape settlement economics and entrench first-mover infrastructure holders.| Strategic Initiative | Industry Significance |
|---|---|
| Banking API Integration | PSD2-mandated access in Germany and UK reduces authentication friction for rent-splitting automation. |
| Embedded Finance Partnership | Property management SaaS integration in Berlin and San Francisco captures recurring utility workflows. |
| Geographic Licensing Expansion | State-by-state money transmission coverage in the US creates compliance moats against unlicensed competitors. |
| Instant Settlement Infrastructure | FedNow and UPI connectivity eliminates float-dependent economics for P2P platforms. |
| Privacy-First Architecture | GDPR-minimal data handling retains Southern European users resisting bank-native alternatives. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary data sources anchors the qualitative findings in observable platform behavior and regulatory filings. Conversations with fintech product managers, banking API engineers, property management software developers, and consumer financial protection attorneys inform the competitive dynamics assessment. Secondary validation draws from SEC filings of payment incumbents, EU PSD2 implementation reports, central bank payment system disclosures, and app store download analytics. Bottom-up user segmentation triangulates against top-down market sizing from transaction volume disclosures.
Sensitivity analysis across adoption rate assumptions and regulatory implementation timelines shapes the forecast confidence intervals. The analytical framework models segmentation across deployment model, user relationship type, integration depth, and regional banking infrastructure maturity. CAGRs derive from cohort-based user lifetime value projections and transaction velocity benchmarks. Forecast inputs include open banking API penetration curves, instant payment rail adoption rates, and co-living demographic growth in target urban centers.
Forecasts assume regulatory continuity in US state-level money transmission regimes and EU PSD2 enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Brazil Real Time Payments Market
Payments
North America Payments Market
Payments
Greece POS Terminals Market
Payments
Canada POS Terminal Market
Payments
Canada Buy Now Pay Later Market
Payments
Global Accounts Payable Automation Market
Payments
Indonesia Prepaid Cards Market
Payments
Global Point of Sale Terminals Market
Payments
Croatia POS Terminals Market
Payments
B2C Payment Market
Payments
South Korea Real Time Payments Market
Payments
Malta POS Terminal Market
Payments
Egypt Mobile Payments Market
Payments
Spain Mobile Payment Market
Payments
Global Master Card Market
Payments
Taiwan Mobile Payments Market