
 Benchtop Centrifuges Market | 2026-2036
Benchtop Centrifuges Market Size, Share, and Industry Trends Forecast 2026-2036
Benchtop Centrifuges Market Outlook
German precision engineering clusters is expanding output of refrigerated and high-speed benchtop units for pharmaceutical quality control labs. Thermo Fisher Scientific leverages vertical integration across consumables and instrumentation to sustain pricing power in clinical centrifuge lines. Eppendorf AG anchors its position through R&D intensity in microcentrifuge rotor design and digital connectivity protocols. Danaher Corporation competes on manufacturing scale, operating multiple assembly facilities that supply regulated markets with ISO-certified equipment.
Benchtop centrifuges are compact laboratory instruments that generate controlled centrifugal force—typically ranging from hundreds to over 100,000 revolutions per minute—to separate heterogeneous mixtures based on density differentials. These devices employ brushless or induction motors driving swing-bucket or fixed-angle rotors within temperature-controlled chambers, serving primary purposes in cell pelleting, blood fractionation, and biomolecule isolation across healthcare and research settings. Microcentrifuge demand leads in academic research settings where small-volume DNA extraction protocols dominate daily workflows, while high-speed centrifuge adoption is accelerating fastest in biotechnology protein purification applications where rotor aerodynamics and thermal stability command premium positioning. Clinical centrifuge lines remain mature margin pools in hospital laboratories, though floor model centrifuge configurations face displacement from automated sample handling systems in high-throughput pharmaceutical operations.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access conditions for clinical-grade benchtop centrifuges sold into diagnostic laboratories. EPA energy efficiency guidelines and ISO 13485 quality management standards further constrain design choices for manufacturers targeting regulated healthcare verticals. Procurement committees in pharmaceutical and biotechnology end-use settings must monitor evolving CE marking transition deadlines and rotor material certification protocols to avoid supply chain interruptions during facility qualification processes.
Market Dynamics
Pharmaceutical quality control labs in Germany and the United States are consolidating procurement around refrigerated high-speed units, compressing vendor margins while elevating rotor material certification requirements as the dominant market-shaping force.
Growth Catalysts
- EU MDR technical documentation mandates:Diagnostic laboratories across Europe must replace legacy clinical centrifuges with validated equipment, creating replacement demand for ISO 13485-certified manufacturers.
- Biotechnology protein purification workflows:Contract development organizations in Japan and Germany are specifying aerodynamically optimized rotors with active thermal management for monoclonal antibody processing.
- Cell therapy manufacturing scale-up:GMP-grade cell separation protocols in the United States require brushless motor systems with continuous monitoring capabilities.
Market Restraints
- Specialized alloy supply concentration:Titanium and aluminum rotor forgings depend on a limited supplier base in Germany and Japan, exposing lead times to aerospace industry demand fluctuations.
- FDA 510(k) pathway complexity:Clinical-grade centrifuge submissions face extended review timelines when predicate device comparisons involve novel rotor geometries or digital connectivity features.
- Automated sample handling substitution:High-throughput pharmaceutical operations are displacing floor-model centrifuge configurations with integrated robotic liquid handling systems.
Strategic Opportunities
- India's expanding CDMO infrastructure:Pharmaceutical contract manufacturers in Hyderabad and Bangalore require cost-optimized microcentrifuge platforms for generic API quality control.
- Digital rotor management systems:Integration of RFID rotor recognition with cloud-based usage tracking is enabling predictive maintenance revenue streams for instrument vendors.
- EPA energy efficiency guidelines:Brushless DC motor upgrades qualifying for utility rebate programs in the United States create specification advantages for compliant equipment.
Industry Challenges
- Rotor balancing technician scarcity:Precision instrument service organizations in Germany and Japan face recruitment gaps for specialists capable of dynamic balancing certification to ISO 1940 standards.
- CE marking transition timeline compression:Manufacturers must revalidate technical documentation under EU MDR before legacy directive expiration, straining regulatory affairs capacity.
- Legacy LIMS integration complexity:Digital connectivity protocols in new centrifuge models require middleware development to interface with established laboratory information management systems in hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benchtop Centrifuges Market |
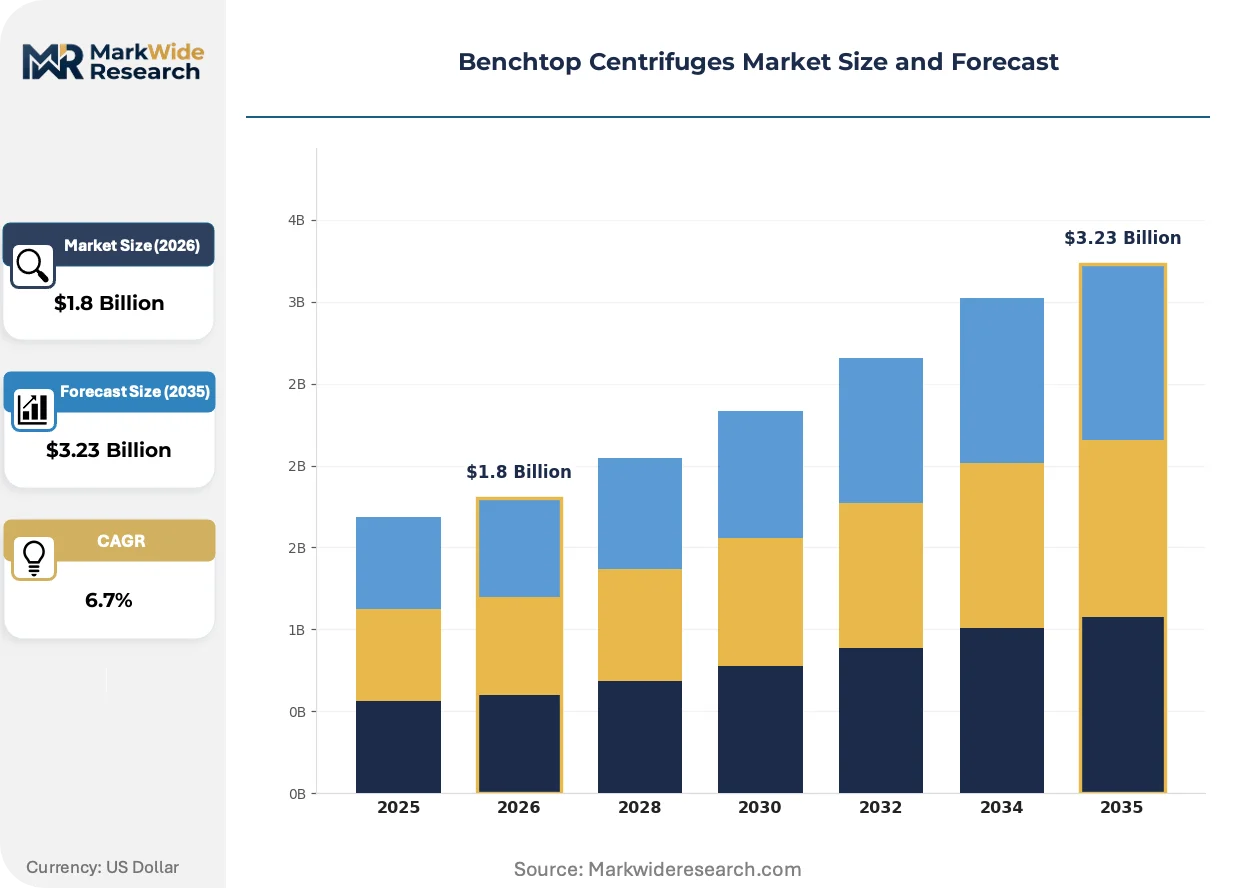
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcentrifuge, Clinical Centrifuge, Floor Model Centrifuge, High Speed Centrifuge Industry Vertical: Healthcare, Pharmaceutical, Academic Research, Biotechnology Application: Cell Separation, Blood Component Separation, Protein Purification, DNA Extraction Capacity: Small Scale, Medium Scale, Large Scale, Ultra-Large Scale |
| Companies Covered | Thermo Fisher Scientific Inc, Eppendorf AG, Danaher Corporation, Beckman Coulter Inc, Andreas Hettich GmbH & Co. KG, Sigma Laborzentrifugen GmbH, Sartorius AG, KUBOTA Corporation, HERMLE Labortechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benchtop Centrifuges Market Strategic Shifts
Connected instrument architectures and aerodynamic rotor engineering are compressing the performance gap between benchtop and floor-standing systems while regulatory digitization accelerates compliance workflow integration.
Brushless DC motor technology with integrated variable frequency drives is decentralizing speed control precision from centralized facility infrastructure to individual benchtop units. Biotechnology process development labs in Germany and the United States are specifying these systems for temperature-sensitive protein purification workflows. The shift is compressing demand for shared high-capacity floor models while elevating distributed instrument reliability requirements.
EU MDR electronic technical documentation submission requirements are mandating structured data formats for clinical centrifuge validation records. Manufacturers serving diagnostic laboratories must reconfigure quality management systems to generate machine-readable device master files. The transition most affects mid-sized vendors in Switzerland and Italy lacking dedicated regulatory technology infrastructure.
Academic core facilities are unbundling centrifuge service contracts from capital equipment purchases, shifting toward per-run consumable pricing models. Research universities in Japan and the United Kingdom are piloting rotor-as-a-service arrangements where vendors retain ownership of specialized carbon fiber rotors. The restructuring concentrates in multi-investigator institutes with intermittent high-speed separation needs.
Benchtop Centrifuges Market Segmentation
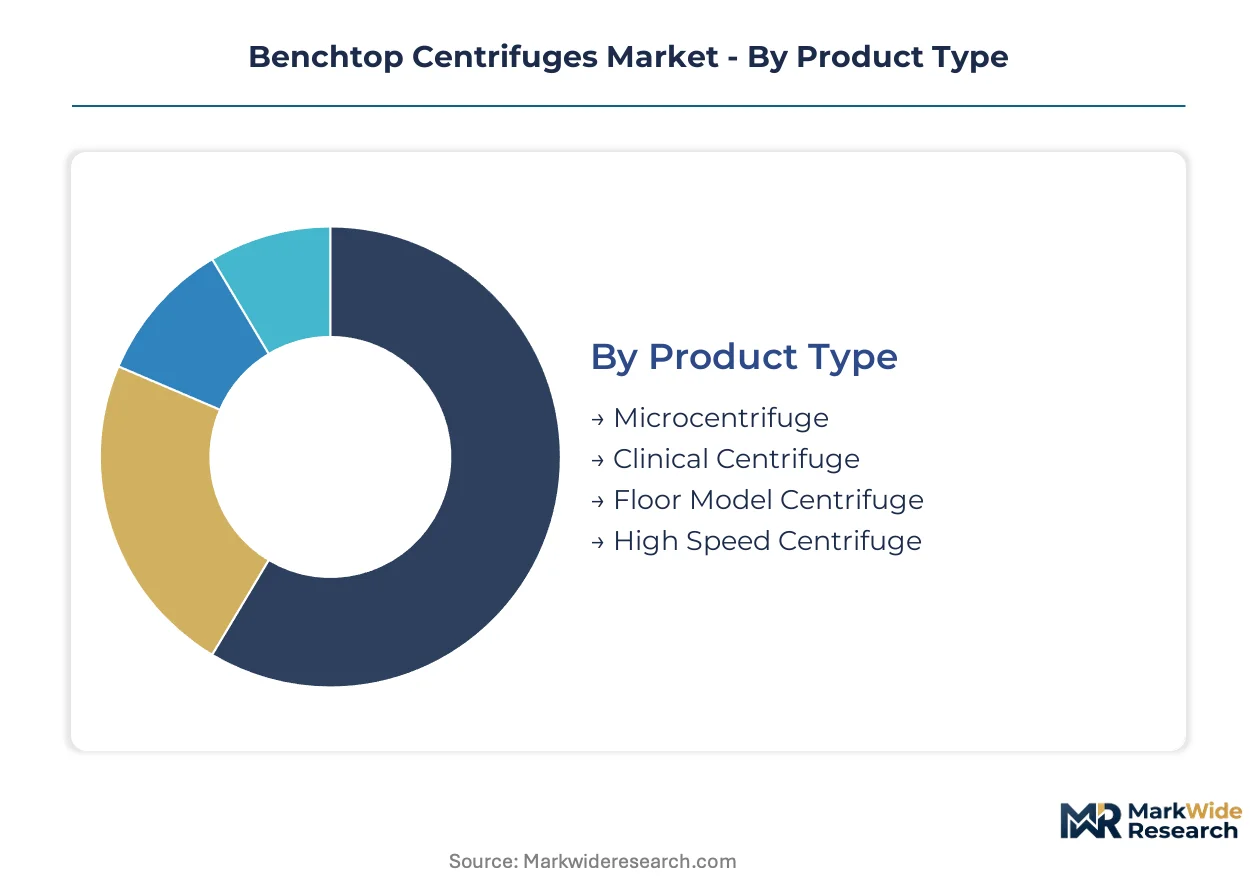
Benchtop centrifuge purchasing patterns diverge sharply across product specifications and end-use settings. Technical requirements for rotor speed precision, thermal stability, and regulatory certification create distinct buyer segments with incompatible procurement criteria.
Product Type:
Speed requirements and sample volume separate buyers into fundamentally different equipment categories with non-overlapping vendor shortlists.
- Microcentrifuge:Compact units process 0.2-2.0 mL tubes at speeds up to 21,000 × g for molecular biology workflows. Academic core facilities in Japan and the United States specify these for high-frequency DNA extraction protocols where rapid acceleration profiles reduce protocol time.
- High Speed Centrifuge:Advanced aerodynamic rotors achieve relative centrifugal forces exceeding 100,000 × g for subcellular fractionation. Contract development organizations in Germany prioritize active thermal management systems to protect temperature-sensitive protein structures during extended runs.
- Clinical Centrifuge:Moderate-speed units with swing-bucket rotors handle 15-50 mL blood collection tubes. Hospital laboratories in the United States select FDA 510(k)-cleared configurations for routine diagnostic workflows.
- Floor Model Centrifuge:High-capacity systems with refrigerated chambers process multiple liters per run. Pharmaceutical quality control labs retain these for bulk cell pelleting despite displacement pressure from automated handling systems.
Clinical centrifuge lines dominate installed base volumes today; high-speed configurations are gaining share fastest in biotechnology applications.
Industry Vertical:
Regulatory burden and capital allocation discipline create four distinct purchasing cultures with incompatible vendor engagement models.
- Biotechnology:Process development labs demand GMP-compatible documentation and rotor traceability for IND-enabling studies. Cell therapy manufacturers in the United States specify brushless motor systems with continuous monitoring to meet FDA guidance on cell separation reproducibility.
- Pharmaceutical:Quality control operations prioritize ISO 13485-certified equipment with validated cleaning protocols. German manufacturers specify refrigerated units with titanium rotors for monoclonal antibody stability testing under ICH guidelines.
- Academic Research:Core facilities balance capital constraints against multi-investigator access requirements. Research universities in Japan pilot service-based rotor ownership models to reduce upfront equipment expenditure.
- Healthcare:Hospital laboratories concentrate procurement around CLIA-waived or moderately complex testing equipment. Clinical chemistry departments in the United States favor closed-system centrifuges with barcode tracking for specimen chain-of-custody compliance.
Pharmaceutical procurement generates the highest average selling prices today; biotechnology verticals are expanding fastest as cell therapy manufacturing scales.
Application:
Biomolecule class and protocol sensitivity dictate rotor geometry, speed profile, and thermal management specifications.
- Protein Purification:Density gradient separations require precise acceleration/deceleration curves to preserve zone stability. Biotechnology labs in Germany specify carbon fiber rotors with low thermal mass for temperature-sensitive antibody fragments.
- Cell Separation:GMP-grade protocols demand continuous process verification and electronic batch records. Cell therapy manufacturers in the United States integrate centrifuge data directly into manufacturing execution systems for regulatory submission packages.
- DNA Extraction:Rapid pelleting of nucleic acid precipitates favors fixed-angle rotors with high relative centrifugal force. Academic genomics cores prioritize compact microcentrifuge footprints for crowded benchtop environments.
- Blood Component Separation:Clinical diagnostics rely on standardized centrifugation profiles for serum/plasma yield consistency. Hospital laboratories in Japan follow JIS standards for blood collection tube processing parameters.
Cell separation commands premium equipment specifications today; protein purification applications are climbing the fastest as biologics pipelines expand.
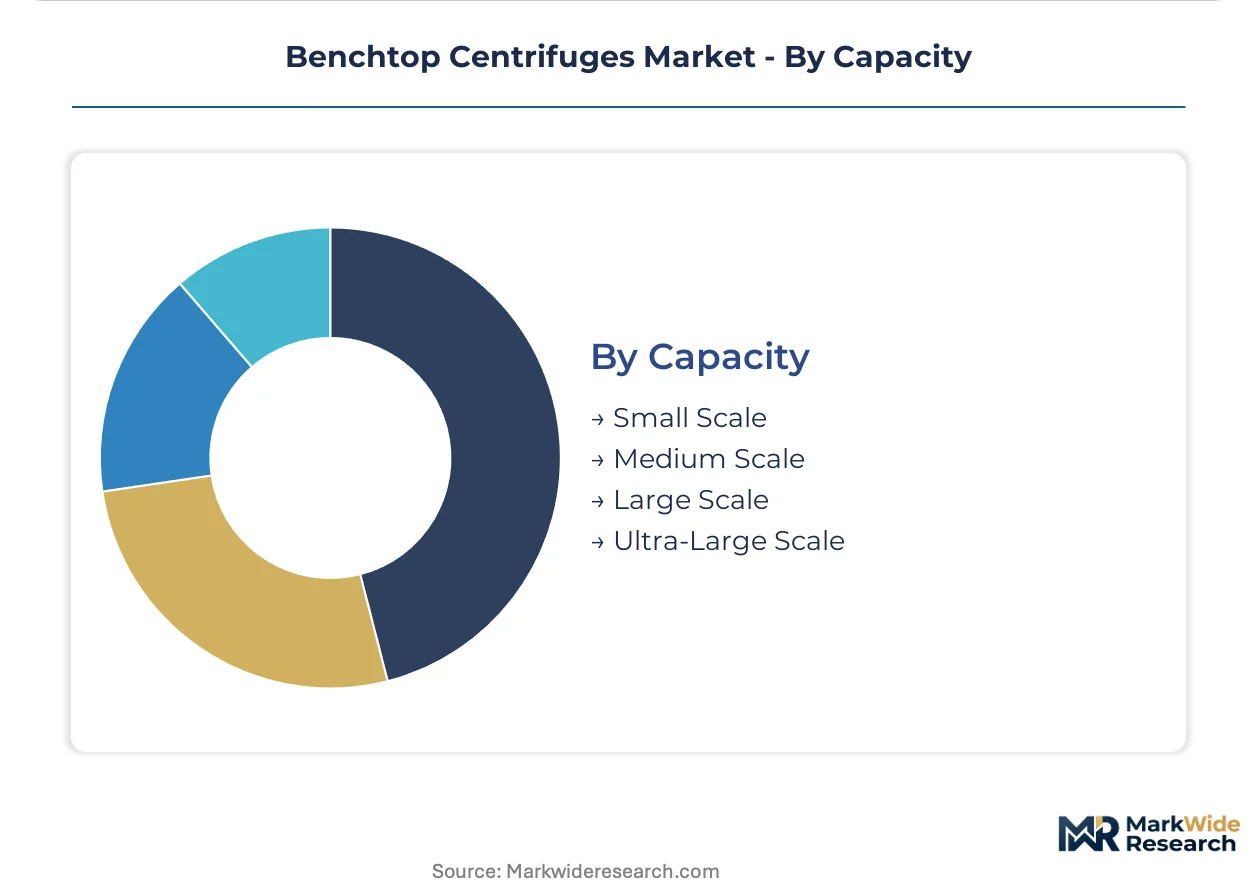
Capacity:
Batch size and facility throughput requirements separate buyers into equipment classes with distinct footprint and infrastructure demands.
- Small Scale:Personal centrifuges process 6-24 tubes for individual researcher workflows. Academic labs in the United States deploy these at individual benches to eliminate core facility queuing delays.
- Medium Scale:Shared instruments accommodate 48-96 tube formats for research group access. Biotechnology startups in Germany select these for process development before GMP scale-up commitment.
- Large Scale:High-throughput units with 4-6 liter rotor capacities support quality control batch testing. Pharmaceutical manufacturers specify refrigerated configurations for stability study sample processing.
- Ultra-Large Scale:Specialized continuous-flow systems exceed traditional benchtop boundaries for industrial bioprocessing. Contract manufacturers in Japan deploy these for plasma fractionation at blood product facilities.
Medium scale equipment leads unit shipments today; large scale configurations are expanding most quickly as pharmaceutical quality control consolidates around centralized testing hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production capacity toward jurisdictions with streamlined certification pathways, as EU MDR compliance costs widen the gap between European and Asian manufacturing economics.
United States
Cell therapy manufacturers in Boston and San Diego are driving procurement of GMP-compatible centrifuge systems with continuous monitoring capabilities. FDA 510(k) clearance requirements for clinical-grade equipment create barrier-to-entry advantages for established domestic vendors. The Research Triangle Park cluster in North Carolina hosts contract development organizations specifying refrigerated high-speed units for monoclonal antibody process development.
Germany
Precision engineering clusters in Baden-Württemberg and Bavaria dominate rotor forging and aerodynamic design for pharmaceutical quality control applications. EU MDR technical documentation mandates are accelerating replacement cycles for legacy clinical centrifuges in diagnostic laboratories. The Frankfurt-Rhine-Main biotech corridor concentrates demand for titanium rotor systems in stability testing workflows under ICH guidelines.
Japan
Contract development organizations in Osaka and Tokyo are specifying carbon fiber rotors with active thermal management for protein purification applications. METI industrial standards for laboratory equipment energy efficiency are compressing margins on conventional induction motor designs. The Kansai region's pharmaceutical manufacturing base is consolidating procurement around brushless DC systems with integrated variable frequency drives.
India
Contract manufacturers in Hyderabad and Bangalore require cost-optimized microcentrifuge platforms for generic API quality control testing. CDSCO medical device registration requirements are tightening documentation standards for imported clinical-grade equipment. The Genome Valley cluster in Telangana is attracting multinational biotech firms establishing process development labs with medium-scale centrifuge requirements.
China
Domestic biopharma companies in Shanghai and Suzhou are expanding in-house protein purification capabilities with locally assembled high-speed units. NMPA medical device classification rules for centrifuge equipment are extending registration timelines for imported systems. The Yangtze River Delta pharmaceutical manufacturing corridor is developing captive rotor machining capacity to reduce dependence on German and Japanese forging suppliers.
Benchtop Centrifuges Market Competitive Environment
German precision engineering specialists anchor the premium tier; United States-based diversified life sciences conglomerates hold scale advantages in clinical diagnostics. The vendor structure concentrates around three strategic archetypes: vertically integrated conglomerates with consumables-instrumentation bundles, mid-cap rotor engineering specialists with captive forging relationships, and regional assemblers serving price-sensitive emerging markets. Competitive moves center on regulatory technology infrastructure investments and predictive maintenance service contract expansion.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc and Danaher Corporation exemplify scale-driven positioning through multi-brand portfolio architectures and global distribution networks. Eppendorf AG occupies a specialist position representing German precision engineering heritage in microcentrifuge rotor design. These three entities collectively illustrate the competitive tension between breadth-driven platform strategies and depth-focused engineering differentiation in regulated healthcare verticals.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Eppendorf AG |
| Danaher Corporation |
| Beckman Coulter Inc |
| Andreas Hettich GmbH & Co. KG |
| Sigma Laborzentrifugen GmbH |
| Sartorius AG |
| KUBOTA Corporation |
| HERMLE Labortechnik GmbH |
| Others |
Value Chain & Pricing Dynamics
Family-owned German mid-caps with multi-generational rotor forging expertise anchor supply-side discipline, translating captive titanium machining relationships into pricing power that resists commoditization across clinical and biotechnology tiers.
Pricing Analysis
Distributor margins absorb 15-25 points on clinical-grade equipment sold through laboratory supply channels, compressing net manufacturer realization while direct OEM relationships for pharmaceutical quality control labs preserve fuller value capture. Three-tier pricing structure across GMP-certified, ISO-validated, and uncertified economy levels separates biotechnology procurement from hospital laboratory budgets. Pricing pressure stems from Indian contract manufacturers sourcing cost-optimized microcentrifuge platforms for generic API testing. Academic research facilities exhibit highest price sensitivity, while cell therapy manufacturers prioritize rotor traceability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese titanium forging specialists who supply precision-machined rotors to tier-one instrument manufacturers, exposing lead times to aerospace industry demand fluctuations. Component sourcing draws from Baden-Württemberg aerodynamic engineering clusters, Osaka carbon fiber composite facilities, and Chinese brushless motor assembly operations. Tariff exposure on precision-machined aluminum housings threatens margin stability for European vendors serving North American diagnostic laboratories. Distribution runs through multinational laboratory supply conglomerates with regional warehousing in Massachusetts, Hesse, and Kanagawa prefecture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on brushless DC motor standardization reducing service contract costs while biotechnology customers absorb premiums for GMP-compatible documentation packages.
For Market Incumbents: Deploy predictive maintenance software integration to convert instrument sales into recurring service revenue streams. Consolidate rotor forging relationships through equity stakes in Baden-Württemberg machining specialists to secure titanium supply against aerospace demand spikes. Counter automated sample handling substitution in pharmaceutical quality control by emphasizing centrifuge flexibility for multi-protocol workflows. For New Entrants and Emerging Players: Begin with cost-optimized microcentrifuge platforms targeting Indian CDMO quality control labs in Hyderabad and Bangalore where CDSCO registration requirements create specification gaps for established Western vendors. Exploit white-space in digital rotor management systems with RFID recognition and cloud-based usage tracking for academic core facilities piloting service-based ownership models. Pursue direct sales relationships with biotechnology startups before GMP scale-up commits them to incumbent vendor ecosystems. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap rotor engineering specialists with captive forging relationships but underdeveloped regulatory technology infrastructure for EU MDR electronic technical documentation. Long-term viability favors vendors with installed base density in cell therapy manufacturing corridors where FDA guidance on separation reproducibility creates switching costs. Watch for inflection when pharmaceutical quality control procurement committees consolidate vendor panels around single-source centrifuge-rotor-consumable bundles.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Electronic Technical Documentation Investment | Machine-readable device master files accelerate diagnostic laboratory replacement cycles for ISO 13485-certified manufacturers. |
| Brushless DC Motor Platform Standardization | Integrated variable frequency drives qualify for EPA utility rebate programs in United States pharmaceutical operations. |
| RFID Rotor Recognition System Deployment | Cloud-based usage tracking enables predictive maintenance revenue streams at academic core facilities in Japan and the United Kingdom. |
| Carbon Fiber Rotor-as-a-Service Pilot | Vendor-retained ownership models reduce upfront capital expenditure for multi-investigator research institutes with intermittent high-speed needs. |
| Captive Titanium Forging Equity Acquisition | Upstream control over German precision machining secures rotor supply against aerospace industry demand fluctuations. |
Study Parameters
Coverage spans Germany, the United States, Japan, India, and China, with primary inputs from each market combining structured interviews with biotechnology process development directors, pharmaceutical quality control managers, hospital laboratory procurement committees, and academic core facility administrators. Secondary validation draws from FDA 510(k) clearance databases, EU MDR technical documentation guidance, METI industrial standards filings, and ISO 13485 certification registries. Bottom-up instrument shipment modeling triangulates against top-down biotechnology and pharmaceutical capital expenditure tracking.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon, with segmentation modeling across product type, industry vertical, application, and capacity tier plus regional regulatory cluster complexity. CAGRs derive from fitted growth curves calibrated to replacement cycle timing for legacy clinical centrifuges and greenfield cell therapy manufacturing facility buildouts. Forecast inputs incorporate brushless motor adoption trajectories and EU MDR transition deadline compliance patterns.
Caveats apply where FDA 510(k) review timeline extensions for novel rotor geometries or aerospace industry demand spikes in titanium supply could materially shift the outlook for vendor delivery schedules and pricing stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Graduated Cylinder Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Global Slide Stainer Market