
 Europe Airport Electric Vehicle Charging Station Market | 2026-2036
Europe Airport Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Airport Electric Vehicle Charging Station Market Analytics
High-power charging architectures is tilting airport infrastructure planning toward DC fast charging hubs capable of delivering 350 kW outputs to electric ground support equipment. ABB Ltd leverages its traction in Nordic airport networks to sustain early-mover positioning in cold-climate charging reliability. Siemens AG anchors European manufacturing capacity for modular charging systems that integrate with airport energy management platforms.
Europe Airport Electric Vehicle Charging Station refers to grid-connected electrical infrastructure installed at aviation facilities to transfer energy to battery-electric vehicles serving aircraft turnaround operations, typically operating at voltage levels from 230V AC single-phase to 1000V DC with power ratings spanning 3.7 kW to 350 kW depending on vehicle class and dwell-time constraints. DC Fast Charging dominates capital allocation among hub airports due to compressed turnaround windows for electric buses and pushback tractors, while Smart Charging commands premium positioning through load-balancing algorithms that prevent peak-demand penalties. AC Charging retains cost advantages for overnight fleet depot applications where extended dwell times offset slower energy transfer rates.
The EU Green Deal, F-Gas Regulation, and ECHA REACH framework collectively mandate decarbonization pathways for ground operations while restricting hazardous substances in charging component manufacturing. CE marking requirements under the EU AI Act and MDR interoperability standards shape product certification timelines and cross-border procurement eligibility for airport authorities. Stakeholders must monitor evolving national building codes for electrical infrastructure as member states transpose EU directives into airport-specific installation standards that will determine deployment timelines and vendor qualification criteria.
Market Dynamics
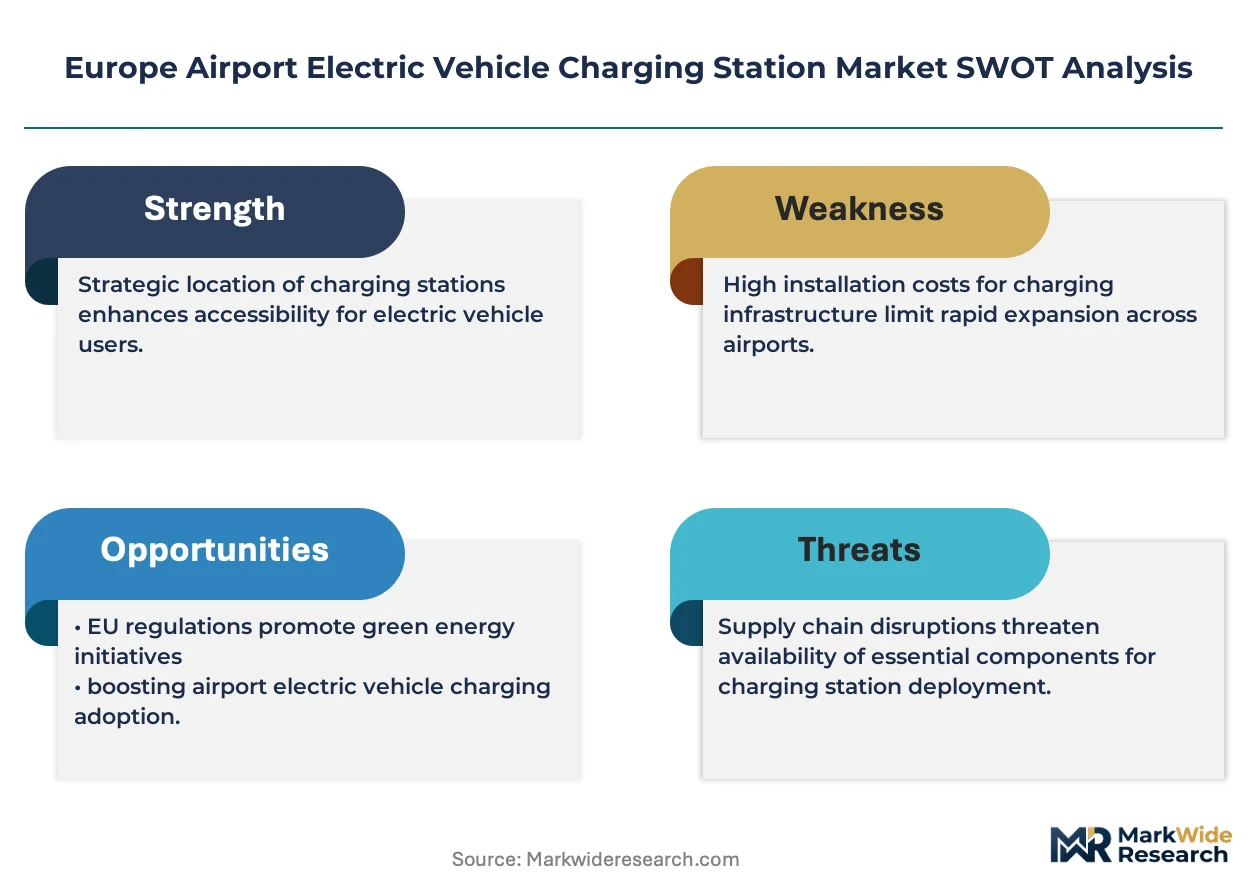
The EU Green Deal's binding emissions targets are forcing hub airports to replace diesel ground support equipment with electric fleets, triggering wholesale infrastructure overhauls that prioritize high-power charging corridors over incremental AC deployments.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbon refrigerants in ground handling equipment accelerate electric bus and baggage tractor procurement across German and Dutch hub airports.
- Hub airport consolidation:Schiphol, Frankfurt, and Charles de Gaulle are centralizing fleet electrification programs, creating concentrated demand corridors for 350 kW DC fast charging infrastructure.
- Battery chemistry advances:Lithium iron phosphate cells with enhanced cold-weather performance are extending operational ranges for electric pushback tractors in Nordic climates.
Market Restraints
- Grid capacity constraints:Rural regional airports in Eastern Europe lack the 1 MW+ substation upgrades required for simultaneous multi-vehicle fast charging during peak turnaround windows.
- Copper and silicon carbide volatility:Power electronics supply chains face input cost pressure from semiconductor foundry bottlenecks and refined copper sourcing concentration.
- CE marking complexity:The EU AI Act's conformity assessment procedures for smart charging algorithms extend vendor certification timelines by 8-14 months.
Strategic Opportunities
- Secondary airport electrification:Italy and Spain's regional aviation networks remain underpenetrated, offering first-mover positioning for modular charging systems with lower capital intensity.
- Vehicle-to-grid integration:Bidirectional charging protocols enable airport fleets to participate in frequency regulation markets, creating new revenue streams for ground handling operators.
- ECHA REACH compliance services:Vendors offering pre-certified component sourcing for hazardous substance restrictions can capture premium positioning in cross-border procurement.
Industry Challenges
- High-voltage technician scarcity:Certified electricians capable of installing and maintaining 1000V DC infrastructure are concentrated in Germany and the Netherlands, creating deployment bottlenecks in Southern Europe.
- Legacy fleet integration:Mixed electrification timelines across ground handling contractors complicate standardized charging access protocols and payment system harmonization.
- Interoperability certification delays:MDR standards for medical-grade electrical safety are being adapted for airport charging, extending product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Airport Electric Vehicle Charging Station Market |
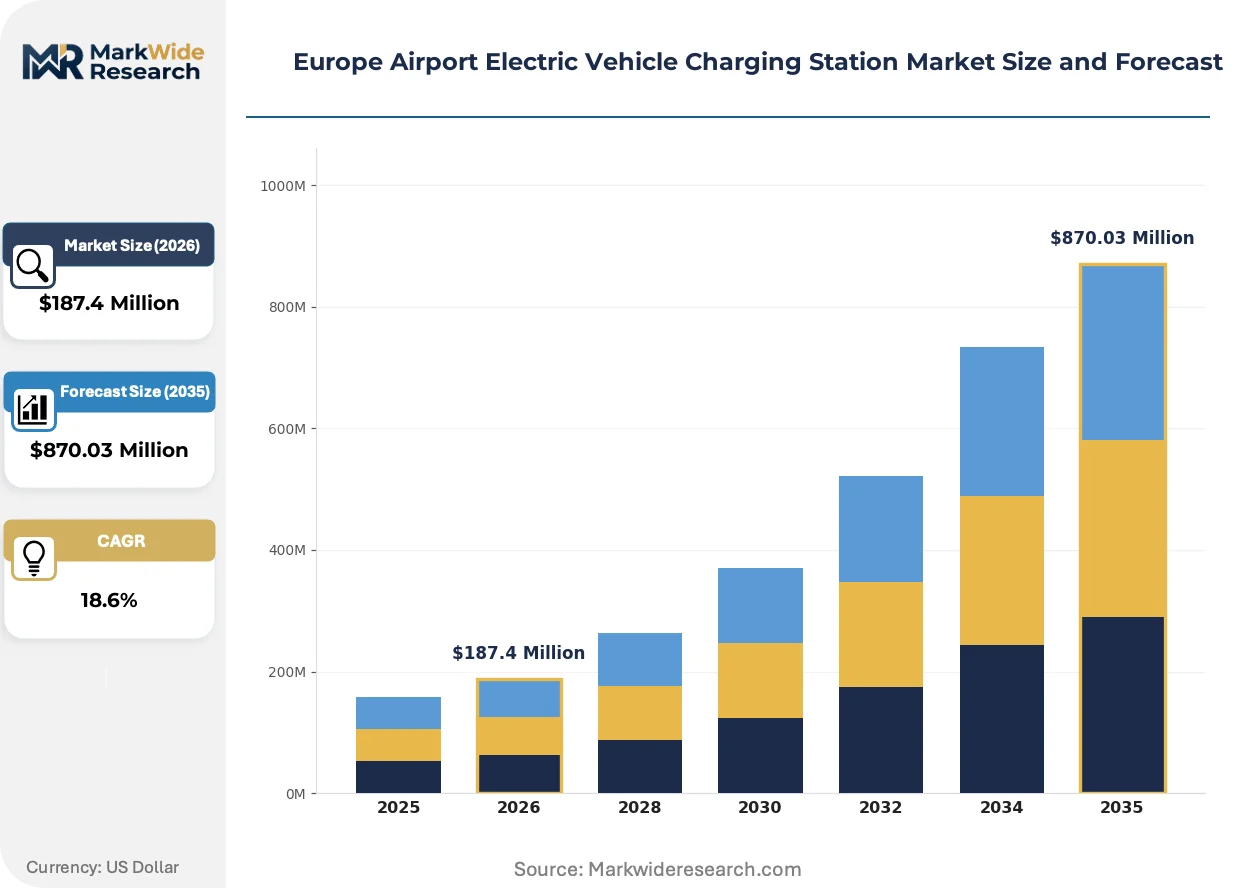
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Technology: AC Charging, DC Fast Charging, Wireless Charging, Smart Charging Installation Type: On-Site, Off-Site, Portable, Permanent End User: Airlines, Ground Handlers, Passengers, Car Rental Services Charging Capacity: Level 1, Level 2, Level 3, High Power |
| Companies Covered | ABB Ltd, ChargePoint, Inc., EVBox Group, Siemens AG, Schneider Electric SE, Alfen N.V., Tesla, Webasto SE, Allego B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Airport Electric Vehicle Charging Station Market Evolving Landscape
Charging infrastructure architectures are pivoting from standalone hardware sales toward integrated energy management platforms that optimize airport-wide electricity demand. This shift compresses vendor margins while expanding addressable revenue through software subscriptions and grid services.
Silicon carbide power semiconductors are rendering obsolete traditional IGBT-based rectifier designs in DC fast charging cabinets. Hub airports in France and Germany are specifying SiC-enabled 350 kW dispensers for their electric bus corridors, achieving 40% reduction in cooling system footprint and enabling denser charging plaza layouts that maximize tarmac space efficiency.
The EU AI Act's risk classification framework for automated load-balancing algorithms is tightening compliance requirements for smart charging vendors. CE marking pathways now mandate third-party assessment of cybersecurity and functional safety for systems managing airport peak demand, with German airport authorities leading enforcement through revised procurement specifications that disqualify non-compliant bidders.
Ground handling operators are consolidating vendor relationships from fragmented equipment-specific contracts toward integrated fleet electrification partnerships. Scandinavian airports pioneered this model, bundling charging infrastructure, vehicle procurement, and energy management under single-source agreements that transfer operational risk to turnkey providers and compress internal procurement cycles from 18 months to 6 months.
Europe Airport Electric Vehicle Charging Station Market Segmentation
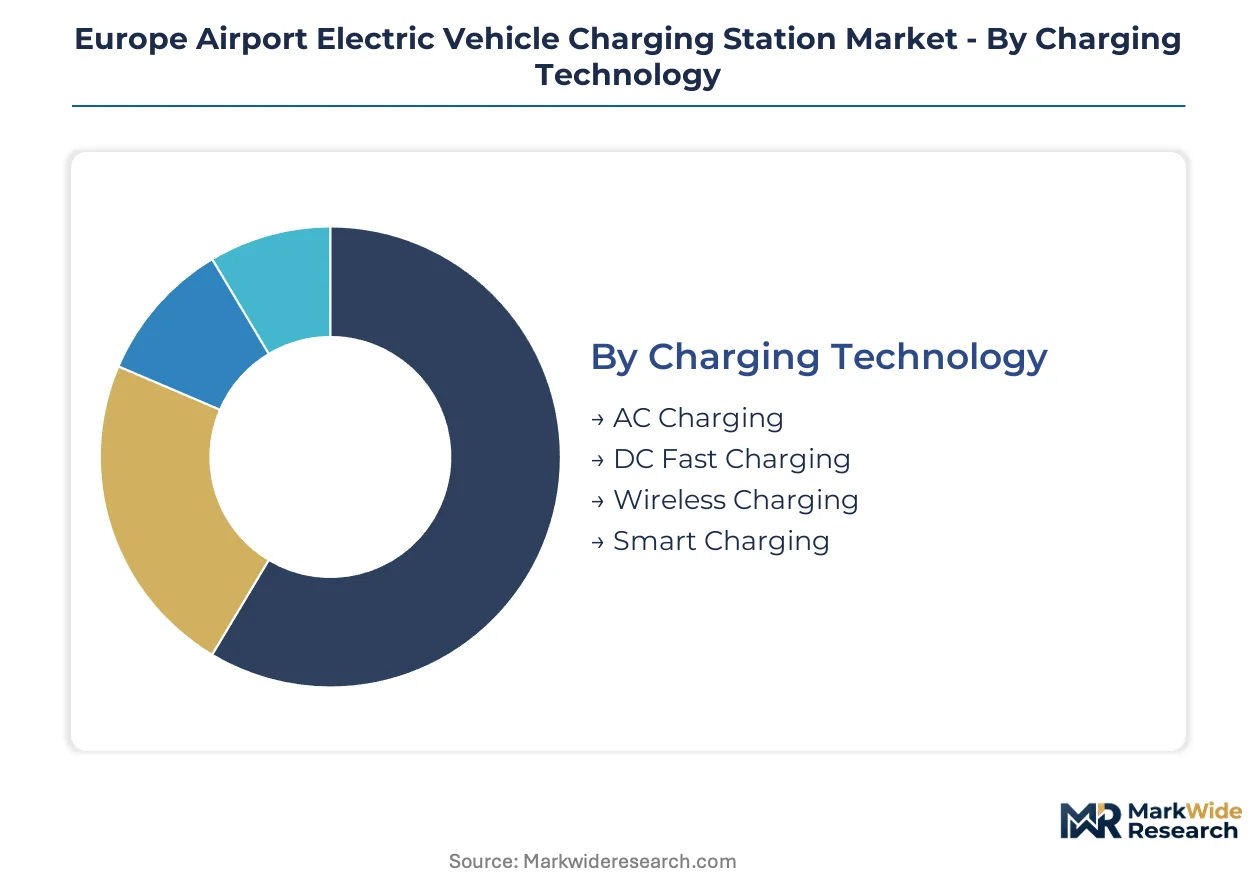
Segmentation in Europe Airport Electric Vehicle Charging Station Market reveals how charging infrastructure investment priorities diverge across operational contexts. Hub airports prioritize high-power corridors for ground support equipment turnaround efficiency, while regional facilities balance capital constraints against fleet electrification timelines. Understanding these segment dynamics enables vendors to align product roadmaps with procurement specifications that vary by airport scale and regulatory maturity.
Charging Technology:
Technology segmentation captures the voltage architecture and intelligence layer that determines charging speed, grid interaction, and total cost of ownership for airport operators.
- AC Charging:Operates at 230V single-phase or 400V three-phase delivering 3.7 kW to 22 kW, suited for overnight depot charging of electric baggage tractors with 8-12 hour dwell windows. Demand concentrates in Spain and Italy's regional airports where lower capital budgets and extended fleet parking periods offset slower energy transfer rates.
- DC Fast Charging:Delivers 50 kW to 350 kW through direct current rectification, enabling 15-30 minute turnaround for electric pushback tractors and apron buses. German and Dutch hub airports specify 350 kW SiC-enabled dispensers under EU Green Deal procurement mandates that prioritize compressed charging windows during peak operations.
- Wireless Charging:Inductive power transfer via ground-embedded pads eliminates connector wear in high-frequency bus circulation routes.
- Smart Charging:Load-balancing algorithms integrate with airport energy management platforms to prevent peak-demand penalties.
AC Charging commands the established base across regional airport depots. The steepest expansion runs through DC Fast Charging as hub airports consolidate fleet electrification around high-power corridor architectures.
Installation Type:
Installation topology determines capital deployment flexibility and operational permanence across airport master planning cycles that span 10-15 year infrastructure horizons.
- On-Site:Fixed infrastructure integrated into tarmac electrical distribution networks with dedicated substations and metering systems. Frankfurt and Schiphol anchor procurement for on-site 350 kW plazas serving centralized ground handling fleets under single-source electrification contracts.
- Permanent:Reinforced concrete foundations with weather-hardened cable management designed for 20-year service life in Nordic freeze-thaw cycles.
- Off-Site:Charging facilities located at remote fleet depots or parking structures separated from active aircraft movement areas.
- Portable:Mobile DC units on trailer-mounted skids for temporary deployment during construction phases or seasonal capacity surges.
Permanent installations absorb the majority of capital allocation in Northern European hub expansion programs. Portable configurations gain traction fastest among Eastern European regional airports navigating grid upgrade timelines.
End User:
End user segmentation distinguishes operational requirements between fleet operators with dedicated charging windows and transient users needing opportunistic access.
- Ground Handlers:Specialized contractors operating electric baggage tractors, pushback tugs, and catering trucks with predictable 4-8 hour dwell patterns. Swissport and dnata drive procurement for dedicated 150 kW DC hubs at Charles de Gaulle and Amsterdam Schiphol under consolidated fleet electrification partnerships.
- Airlines:Carriers with proprietary ground equipment fleets seeking branded charging access for electric apron buses.
- Passengers:Private electric vehicle owners requiring Level 2 or 50 kW DC access during flight dwell periods.
- Car Rental Services:Fleet operators with high-turnover charging needs for electric rental vehicle redistribution.
Ground Handlers anchor the revenue base through contracted infrastructure-as-a-service agreements. Passenger-facing charging climbs fastest as airports monetize parking assets through retail energy services.
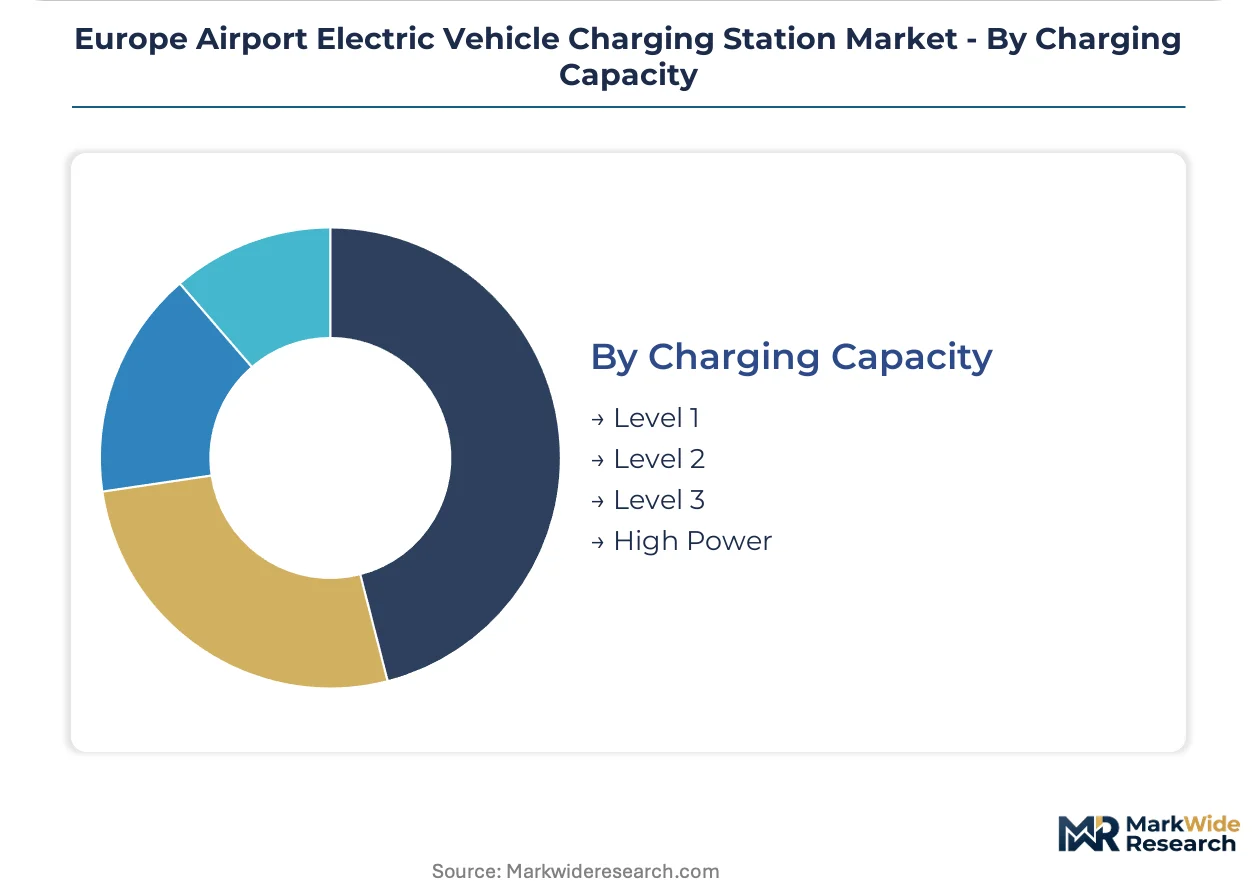
Charging Capacity:
Capacity tiers align power delivery specifications with vehicle battery sizes and operational duty cycles across ground support equipment categories.
- Level 3:DC fast charging at 50 kW to 150 kW serving mid-size electric baggage tractors with 100-200 kWh battery packs. Scandinavian airports specify Level 3 for cold-weather lithium iron phosphate fleets requiring higher C-rate charging to maintain operational availability.
- High Power:150 kW to 350 kW outputs for electric apron buses and heavy pushback tractors with 300+ kWh configurations.
- Level 1:3.7 kW single-phase AC for light utility vehicles with overnight dwell guarantees.
- Level 2:7 kW to 22 kW AC for passenger EVs and light commercial fleet vehicles.
Level 3 retains the installed base across mature electrification programs. High Power capacity segments are expanding most quickly as hub airports specify 350 kW corridors for next-generation electric ground support equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German charging equipment manufacturers supply high-power DC infrastructure to Dutch and French hub airports, creating a north-south trade corridor that dominates procurement patterns across the continent.
Germany
Frankfurt and Munich airports drive fleet electrification mandates for ground handling contractors under the EU Green Deal's binding emissions targets. The F-Gas Regulation accelerates replacement schedules for diesel baggage tractors. Bavarian engineering clusters near Nuremberg produce modular charging cabinets for export to Scandinavian markets.
Netherlands
Amsterdam Schiphol's centralized ground handling model creates concentrated demand corridors for 350 kW charging plazas serving electric apron buses. CE marking requirements under the EU AI Act extend vendor qualification timelines for smart charging algorithms. Rotterdam-The Hague corridor hosts testing facilities for vehicle-to-grid integration protocols.
France
Charles de Gaulle and Orly anchor procurement for DC fast charging infrastructure under national airport decarbonization programs. ECHA REACH compliance frameworks restrict hazardous substances in charging component manufacturing. The Île-de-France region concentrates systems integrators capable of airport-wide energy management platform deployment.
United Kingdom
Heathrow's ground support equipment electrification timeline lags continental peers due to post-Brexit regulatory divergence from EU certification pathways. The UK Civil Aviation Authority maintains separate conformity assessment procedures for high-voltage airport infrastructure. London Stansted and Manchester emerge as testing grounds for portable charging units during terminal expansion phases.
Spain
Barcelona and Madrid airports initiate pilot programs for electric pushback tractors with extended dwell-time charging requirements. National building codes for electrical infrastructure remain in transposition from EU directives, creating deployment uncertainty. Catalan regional authorities fund modular charging systems for seasonal capacity surges at Mediterranean tourism hubs.
Europe Airport Electric Vehicle Charging Station Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around integrated energy management platforms rather than standalone hardware sales. Siemens AG and ABB Ltd anchor the premium tier through airport-specific engineering capabilities, while mid-scale specialists populate the modular charging segment. Strategic archetypes separate into turnkey fleet electrification partners, component-focused power electronics suppliers, and software-integrated platform vendors. Competitive moves concentrate on strategic partnerships with ground handling operators and backward integration into power semiconductor sourcing.
Within the integrated platform tier, Siemens AG and ABB Ltd exemplify European engineering conglomerates with airport-sector traction. EVBox Group occupies a position among modular charging specialists addressing capital-constrained regional airports. These three anchors represent distinct strategic postures: full-stack energy management, high-power hardware leadership, and scalable deployment flexibility for secondary markets.
| Leading Market Players |
|---|
| ABB Ltd |
| ChargePoint, Inc. |
| EVBox Group |
| Siemens AG |
| Schneider Electric SE |
| Alfen N.V. |
| Tesla |
| Webasto SE |
| Allego B.V. |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container rates shape procurement economics for German charging cabinet manufacturers, concentrating supply-side power among Bavarian engineering clusters while forcing price stratification between CE-marked premium systems and uncertified economy alternatives for Eastern European regional airports.
Pricing Analysis
The 350 kW SiC-enabled dispenser generation commands 40-60% premiums over legacy IGBT-based 150 kW units, while next-generation wireless pad systems under pilot at Scandinavian airports threaten to compress hardware margins further. Three-tier pricing structure across premium CE-marked smart charging, standard DC fast charging, and economy AC depot systems differentiates on certification grade and grid-integration depth. Cost compression in mid-power DC segments is intensifying because silicon carbide foundry bottlenecks are easing and Chinese power module suppliers are entering European certification pipelines. Regional airports in Spain and Italy exhibit highest price sensitivity, deferring procurement until national building code transposition clarifies installation cost recovery mechanisms.
Supply Chain Analysis
Refined copper cathodes and silicon carbide wafers feed from German industrial metals traders and Taiwanese semiconductor foundries respectively, with power electronics assembly concentrating in Bavaria, the Netherlands, and Switzerland. Charging cabinet manufacturing draws from Austrian steel enclosures, Italian cable management systems, and Nordic cold-climate thermal management components. Single-source vulnerability runs through 200mm SiC wafer supply from two dominant foundries serving European automotive and airport infrastructure demand simultaneously. Distribution runs through direct OEM relationships with airport authorities for hub deployments, while regional airports procure via electrical infrastructure distributors with turnkey installation bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's airport charging infrastructure sits in early-cycle expansion as EU Green Deal procurement mandates force wholesale fleet electrification timelines that compress traditional 18-month procurement cycles to 6-month turnkey deployments.
For Market Incumbents: Pre-empt margin erosion in standalone hardware sales by bundling energy management software subscriptions and vehicle-to-grid integration services that lock ground handling operators into 10-year operational contracts. Consolidate backward integration into silicon carbide power module sourcing before Chinese suppliers achieve CE marking eligibility. Defend against modular charging specialists by embedding proprietary load-balancing algorithms that trigger EU AI Act compliance dependencies for airport energy managers. For New Entrants and Emerging Players: Secondary airports in Italy and Spain represent the most penetrable entry point, where national building code uncertainty has frozen incumbent procurement and created 12-18 month first-mover windows for portable DC systems with rapid deployment capabilities. Target Eastern European regional aviation networks lacking grid upgrade capital by offering power-as-a-service models that bypass upfront infrastructure investment. Partner with Scandinavian ground handling operators to pilot wireless charging corridors that differentiate from established plug-in architectures. For Investors and Strategic Acquirers: Turnkey fleet electrification partners with integrated vehicle procurement and charging infrastructure capabilities offer the strongest 5-10 year positioning as airport authorities consolidate vendor relationships. Software-integrated platform vendors with certified smart charging algorithms command scarcity premiums under tightening EU AI Act enforcement. Monitor CE marking approval timelines for Chinese power electronics suppliers as the inflection signal for hardware margin compression across European manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures wafer allocation from Taiwanese foundries before automotive demand crowds airport infrastructure procurement. |
| Vehicle-to-Grid Certification | Unlocks frequency regulation revenue streams for ground handling operators under FERC and national grid codes. |
| Turnkey Fleet Electrification Partnership | Compresses procurement cycles from 18 months to 6 months by bundling vehicles, charging, and energy management. |
| EU AI Act Compliance Investment | Creates 8-14 month certification barriers that disqualify non-compliant bidders from German airport tenders. |
| Secondary Airport Geographic Expansion | Captures first-mover positioning in Italy and Spain where building code transposition delays incumbent deployment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airport energy managers, ground handling fleet directors, charging equipment procurement officers, and electrical infrastructure contractors across Germany, the Netherlands, France, and Scandinavia. Secondary validation incorporated EU Green Deal implementation tracking, ECHA REACH substance restriction databases, CE marking notification files, airport authority capital expenditure disclosures, and silicon carbide supply chain filings from semiconductor foundries. Bottom-up installation forecasts triangulated against top-down EU emissions target allocations for ground operations.
Calibration against historical deployment velocities at Frankfurt, Schiphol, and Charles de Gaulle anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass charging technology tier, installation permanence, end-user operational profile, and power delivery capacity. CAGRs derived from logistic diffusion curves fitted to fleet electrification procurement timelines, with cross-validation against battery chemistry advancement trajectories and grid upgrade investment schedules from European distribution system operators.
Practitioners should monitor silicon carbide foundry capacity expansion, EU AI Act conformity assessment procedure revisions, and national building code transposition timelines for early signals of forecast deviation. Forecasts reflect assumptions regarding F-Gas Regulation enforcement consistency and hub airport consolidation patterns around single-source electrification contracts. Material shifts in Chinese power module CE marking pathways or German high-voltage technician training program scaling would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market