
 North America Electric Vehicle Charging Station Market | 2026-2036
North America Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Charging Station Market Insights
Certified electrical technician availability is collapsing across the United States and Canada, creating installation backlogs that constrain deployment velocity. Tesla leverages its Supercharger network density to dominate highway corridor positioning. ChargePoint sustains broad market coverage across retail and workplace segments through open-network interoperability. Electrify America anchors high-power charging investments along major freight corridors with 350 kW DC hardware.
North America Electric Vehicle Charging Station infrastructure encompasses hardware systems that convert grid alternating current to direct current at outputs ranging from 3.3 kW residential Level 1 to 350 kW DC fast charging, with integrated power electronics, cable management, and payment authentication serving electric vehicle energy replenishment. DC Fast Charger installations command premium hardware margins but require substantial grid interconnection upgrades, while Level 2 Charger deployments dominate residential and workplace volume through lower per-unit costs and simplified permitting. Smart Charging technology segments are attracting software investment as utilities deploy time-of-use rate structures that reward managed demand response across aggregated vehicle loads.
The US Federal Highway Administration's National Electric Vehicle Infrastructure program mandates Buy America compliance for federally funded charging equipment, while Canada's national building codes are incorporating EV-ready requirements for new construction. The US EPA tailpipe emission standards and California Air Resources Board's Advanced Clean Cars II rule are pressuring automakers to expand zero-emission vehicle sales, indirectly mandating charging density growth. Stakeholders must monitor interconnection queue reform progress and utility rate case outcomes to calibrate capital deployment timing against grid readiness constraints.
Market Dynamics
The US Inflation Reduction Act's alternative fuel infrastructure tax credits are compressing deployment timelines while certified electrical technician scarcity creates installation backlogs that throttle velocity. Grid interconnection queue reform lags behind hardware deployment, forcing capital timing recalibration against utility readiness constraints.
Growth Catalysts
- IRA Tax Credits:The US Inflation Reduction Act's Section 30C alternative fuel infrastructure credits reduce capital expenditure burdens for depot electrification programs. Fleet operators accelerate procurement schedules to capture incentive windows.
- CARB Advanced Clean Cars II:California Air Resources Board's zero-emission vehicle sales mandates pressure automakers to expand charging density. This regulatory pressure cascades into corridor infrastructure commitments.
- Highway Corridor Demand:Interstate freight electrification concentrates deployment along Texas interstate corridors and California metropolitan corridors. Long-haul trucking electrification creates anchor demand for high-power charging assets.
Market Restraints
- Copper and Silicon Carbide Cost Volatility:Power electronics input costs fluctuate with commodity markets. DC fast charger hardware margins compress when silicon carbide MOSFET prices spike.
- Certified Technician Concentration:Installation capacity concentrates in unionized electrical trades with limited apprenticeship throughput. Geographic mismatch between technician availability and project locations extends deployment timelines.
- Buy America Compliance Friction:US Federal Highway Administration NEVI program mandates domestic content thresholds. Sourcing compliant hardware delays federally funded projects.
Strategic Opportunities
- Workplace Charging Underpenetration:Employer-sponsored Level 2 deployment lags residential and public infrastructure. Commercial real estate portfolios represent untapped installation volume.
- Smart Charging Convergence:Vehicle-to-grid integration combines with time-of-use rate structures. Utilities deploy managed demand response across aggregated residential and fleet loads.
- Multi-Unit Dwelling Retrofit:Canada's national building code EV-ready requirements apply only to new construction. Existing condominium and apartment stock requires retrofit solutions.
Industry Challenges
- Master Electrician Certification Bottleneck:Journeyman-to-master progression timelines extend 4-7 years. Permitting authorities require master-level sign-off for commercial interconnections.
- Utility Interconnection Queue Delays:Distribution upgrade requests queue 18-36 months in high-growth regions. Hardware deployment outpaces grid capacity expansion.
- Payment Authentication Fragmentation:Roaming interoperability standards remain unsettled across network operators. Fleet operators face account management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Charging Station Market |
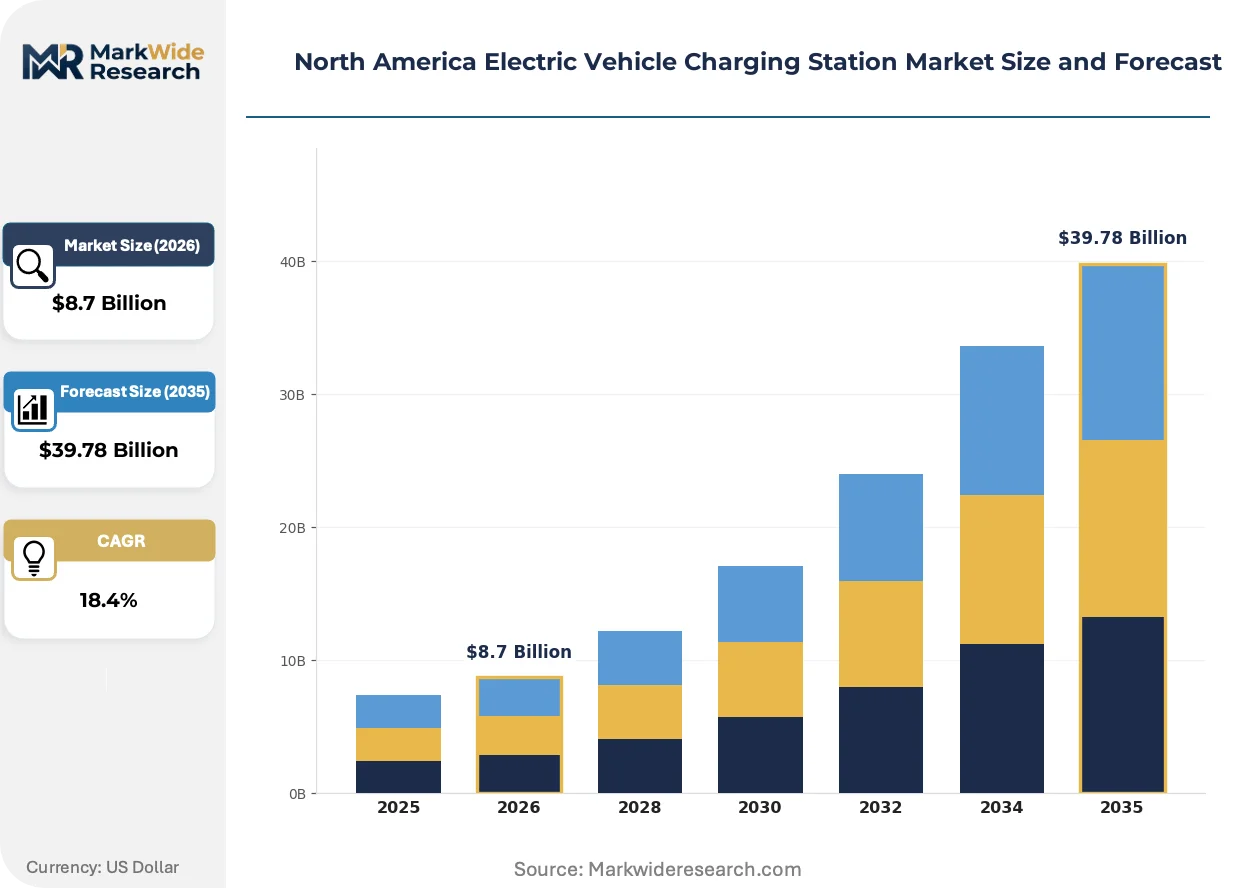
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Charger, Level 2 Charger, DC Fast Charger, Wireless Charger, Battery Swapping Station Technology: Plug-in, Inductive Charging, Conductive Charging, Battery Exchange, Solar Powered, Smart Charging Application: Public Charging, Residential Charging, Commercial Fleet, Workplace Charging, Transit Hub, Retail Locations End User: Electric Vehicle Owners, Fleet Operators, Municipalities, Property Managers, Transit Agencies |
| Companies Covered | Tesla, ChargePoint, ABB, Electrify America, EVBox, Blink Charging, EVgo, Schneider Electric, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Charging Station Market Trends and Innovations
Hardware miniaturization and power density improvements are compressing footprint requirements while regulatory mandates accelerate software-layer investment. Three forces are actively restructuring competitive positioning.
Silicon carbide power electronics replace silicon IGBTs in DC fast charger inverters. Tier 1 suppliers and charging network operators adopt 800V architectures to reduce thermal management overhead. This transition is miniaturizing cooling system requirements and enabling compact 350 kW dispenser footprints in constrained urban sites.
The US Federal Highway Administration NEVI program mandates open charging standards and interoperability protocols. Network operators must implement ISO 15118 Plug and Charge authentication to qualify for federal funding. Highway corridor projects face compliance timeline pressure as 2024-2026 deployment windows contract.
Fleet procurement teams are consolidating charging service contracts under single-network agreements. Long-haul trucking operators prefer subscription-based energy pricing over per-kWh transactions. This purchasing pattern shift concentrates volume with network operators offering guaranteed uptime service level agreements.
North America Electric Vehicle Charging Station Market Segmentation
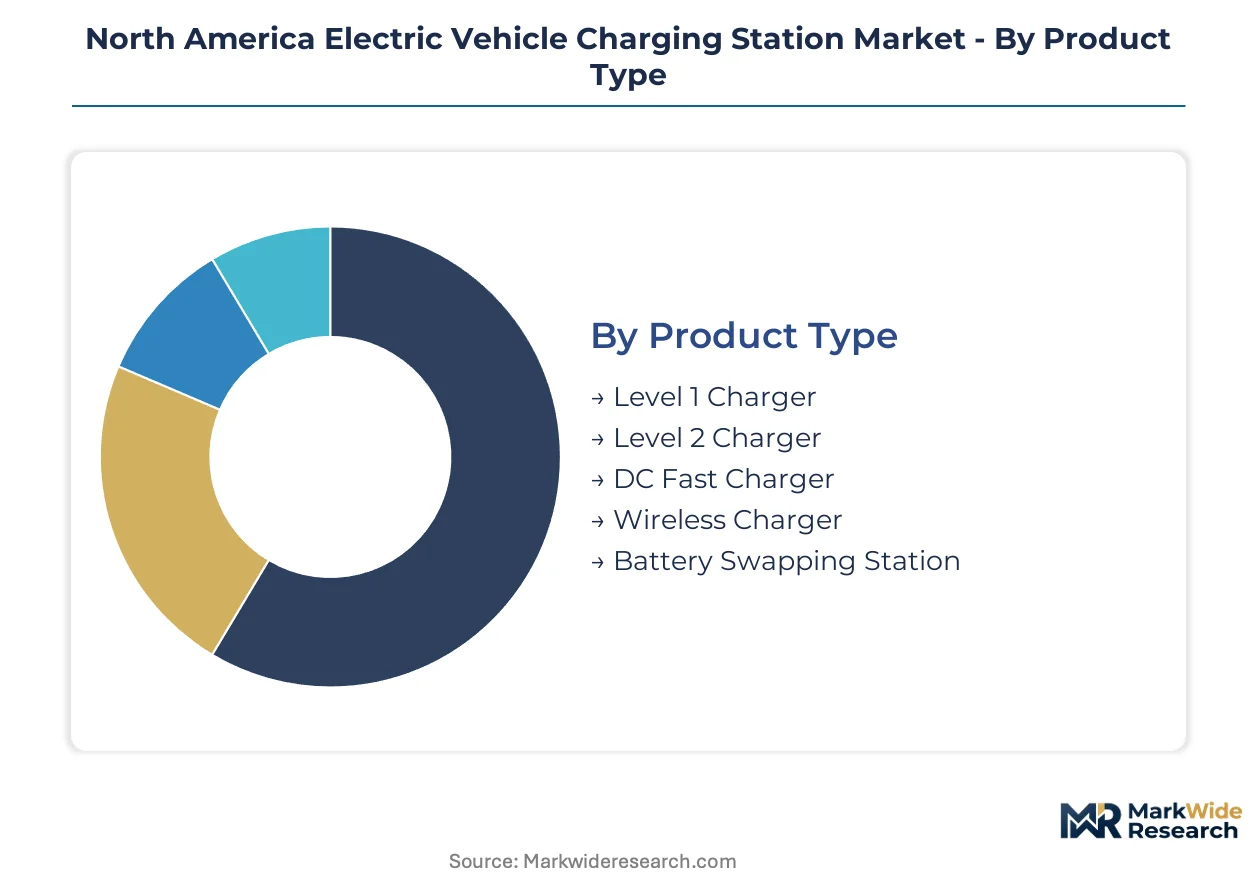
Segmentation reveals how capital deployment flows through distinct hardware tiers and customer channels. Product type and application dimensions govern procurement velocity, while technology and end-user categories determine margin capture and service complexity.
Product Type:
Channel mix varies sharply by power tier, with residential installers, electrical contractors, and network operators each dominating specific hardware categories.
- Level 1 Charger:Standard 120V residential units deliver 3.3 kW through standard household outlets. Demand concentrates in single-family housing across California and Texas where overnight charging suffices for daily commuting distances.
- Level 2 Charger:240V systems ranging 7-19 kW dominate workplace and multi-unit dwelling retrofits. Fleet depot electrification programs in the United States accelerate procurement through IRA tax credit capture.
- DC Fast Charger:High-power 50-350 kW highway corridor assets require substantial utility interconnection upgrades. Interstate freight electrification along Texas corridors anchors anchor deployment.
- Wireless Charger:Inductive pad systems eliminate cable handling for autonomous vehicle applications. Early deployments target controlled-access fleet yards.
- Battery Swapping Station:Automated exchange systems serve commercial trucking with standardized pack architectures. Pilot programs concentrate in California metropolitan freight hubs.
By volume, Level 2 Charger leads. By growth pace, DC Fast Charger is expanding most quickly.
Technology:
Cost tier stratification separates mature plug-in hardware from premium smart charging and emerging inductive systems.
- Plug-in:Conventional connector-based systems using SAE J1772 and CCS standards dominate installed base. Permitting simplicity sustains volume leadership across residential and workplace channels.
- Inductive Charging:Contactless power transfer through magnetic resonance enables automated charging without driver intervention. Transit agencies in California pilot curb-side inductive pads for electric bus fleets.
- Conductive Charging:Pantograph and overhead contact systems serve high-power opportunity charging for heavy-duty vehicles. Municipal transit hubs deploy conductive infrastructure for route midpoint energy replenishment.
- Battery Exchange:Automated pack swap mechanisms reduce vehicle downtime for commercial operators. Standardization barriers constrain deployment beyond captive fleet applications.
- Solar Powered:Off-grid charging assets integrate photovoltaic generation with battery storage buffers. Remote corridor locations in Texas leverage solar DC fast charging where grid extension proves uneconomical.
- Smart Charging:Network-connected systems enable demand response, time-of-use optimization, and vehicle-to-grid integration. Utilities across the United States deploy managed charging programs to align EV loads with renewable generation profiles.
By installed base, Plug-in dominates. By investment momentum, Smart Charging is gaining share fastest.
Application:
Customer type determines site complexity, with fleet operators driving standardized depot configurations and retail locations demanding flexible payment authentication.
- Public Charging:Highway corridor and urban curbside assets serve sporadic demand with high utilization variance. NEVI program funding concentrates deployment along federally designated alternative fuel corridors.
- Residential Charging:Single-family and multi-unit dwelling installations represent the largest addressable unit volume. California's Title 24 building code mandates EV-ready infrastructure for new construction.
- Commercial Fleet:Depot-based charging for delivery, logistics, and service vehicle fleets operates at high utilization with predictable schedules. IRA Section 30C credits compress payback periods for fleet electrification investments.
- Workplace Charging:Employer-sponsored Level 2 deployment lags residential penetration. Commercial real estate portfolios in Texas metropolitan areas represent underpenetrated installation volume.
- Transit Hub:Bus and rail terminal charging infrastructure serves municipal and regional transit agencies. California Air Resources Board mandates accelerate zero-emission bus procurement.
- Retail Locations:Shopping center and convenience store charging attracts dwell-time customers. Electrify America anchors 350 kW DC fast charging at major retail corridors.
By deployment volume, Residential Charging leads. By capital intensity per site, Commercial Fleet is climbing the fastest.
End User:
Procurement authority concentrates differently across segments, with fleet operators consolidating under single-network agreements and municipalities navigating public procurement complexity.
- Electric Vehicle Owners:Individual consumers purchase residential hardware through electrical contractors and retail channels. California's metropolitan corridors concentrate early adopter density.
- Fleet Operators:Logistics, delivery, and service vehicle managers negotiate enterprise charging service contracts. Long-haul trucking electrification drives subscription-based energy pricing preferences.
- Municipalities:City and county governments deploy public charging and transit infrastructure through competitive bidding processes. Buy America compliance requirements extend federally funded project timelines.
- Property Managers:Commercial and residential real estate operators retrofit existing buildings for tenant EV access. Canada's national building code EV-ready requirements apply only to new construction, leaving retrofit demand unaddressed.
- Transit Agencies:Public transportation authorities electrify bus and rail fleets through dedicated capital programs. California's Advanced Clean Transit regulation mandates zero-emission bus procurement timelines.
By unit volume, Electric Vehicle Owners leads. By contract value concentration, Fleet Operators show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Federal Highway Administration anchors North American deployment velocity through the National Electric Vehicle Infrastructure program, which mandates Buy America compliance and open charging standards. Canada and Mexico follow distinct regulatory trajectories shaped by national building codes and cross-border freight electrification corridors.
United States
California's metropolitan corridors and Texas interstate highways concentrate DC fast charger deployment for long-haul freight electrification. The Inflation Reduction Act's Section 30C alternative fuel infrastructure tax credits compress capital payback periods for fleet depot programs. Los Angeles and Dallas-Fort Worth anchor the highest installation density as municipal transit agencies accelerate zero-emission bus procurement.
Canada
Quebec and Ontario drive provincial charging infrastructure through Hydro-Québec's Electric Circuit network and Ontario's building code EV-ready mandates. The Canada Infrastructure Bank commits capital to Trans-Canada Highway corridor electrification. Toronto and Vancouver metropolitan areas dominate residential Level 2 volume as multi-unit dwelling retrofits lag new construction penetration.
Mexico
Nuevo León and Mexico City concentrate foreign direct investment in charging hardware manufacturing for North American export compliance. The Secretariat of Economy coordinates with US EPA tailpipe standards to align zero-emission vehicle timelines. Monterrey industrial parks host assembly operations serving Texas border freight electrification corridors.
North America Electric Vehicle Charging Station Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical integration separating network operators from hardware-only suppliers. Tesla and Electrify America anchor highway corridor positioning through captive charging networks, while ChargePoint and Blink Charging pursue asset-light software-platform models. Strategic archetypes include integrated network-hardware hybrids, open-network software platforms, and utility-facing infrastructure specialists. Competitive moves concentrate on NEVI program compliance acceleration and fleet service contract consolidation under single-network agreements.
Among integrated network operators, Tesla, ChargePoint, and Electrify America exemplify divergent strategic positions. Tesla represents the closed-network vertical integration archetype with proprietary connector standards and Supercharger density concentration. ChargePoint occupies the open-intermediary position, enabling roaming authentication across third-party hardware installations. Electrify America anchors the regulatory-driven highway corridor strategy, deploying high-power DC assets along federally designated alternative fuel corridors to capture NEVI program funding windows.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| Electrify America |
| EVBox |
| Blink Charging |
| EVgo |
| Schneider Electric |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
High-volume DC fast charger manufacturing concentrates in China and South Korea, compressing unit economics for 350 kW hardware while California's Buy America compliance requirements force price premiums on federally funded corridor projects. This geographic bifurcation stratifies procurement costs between IRA-subsidized domestic content and imported silicon carbide power electronics.
Pricing Analysis
California corridor projects command 15-25% hardware premiums over Texas interstate deployments due to stricter UL certification and seismic mounting requirements. Subscription-based energy pricing for fleet operators displaces per-kWh transactional models along long-haul freight routes. Price differentiation rests on NEVI compliance bundling and guaranteed uptime service levels. Municipalities exhibit highest price sensitivity due to public procurement constraints, while integrated fleet operators absorb premium hardware costs for single-network consolidation.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach extends silicon carbide MOSFET lead times from Taiwanese foundries, forcing charger OEMs to buffer inventory ahead of IRA deployment windows. Power electronics sourcing concentrates in Taiwan, South Korea, and Japan, with copper busbar fabrication anchored in Mexico for USMCA tariff compliance. Supply chain risk centers on single-source dependency for 800V-rated silicon carbide substrates. Distribution runs through electrical contractor networks with master electrician certification requirements gating final-mile installation capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
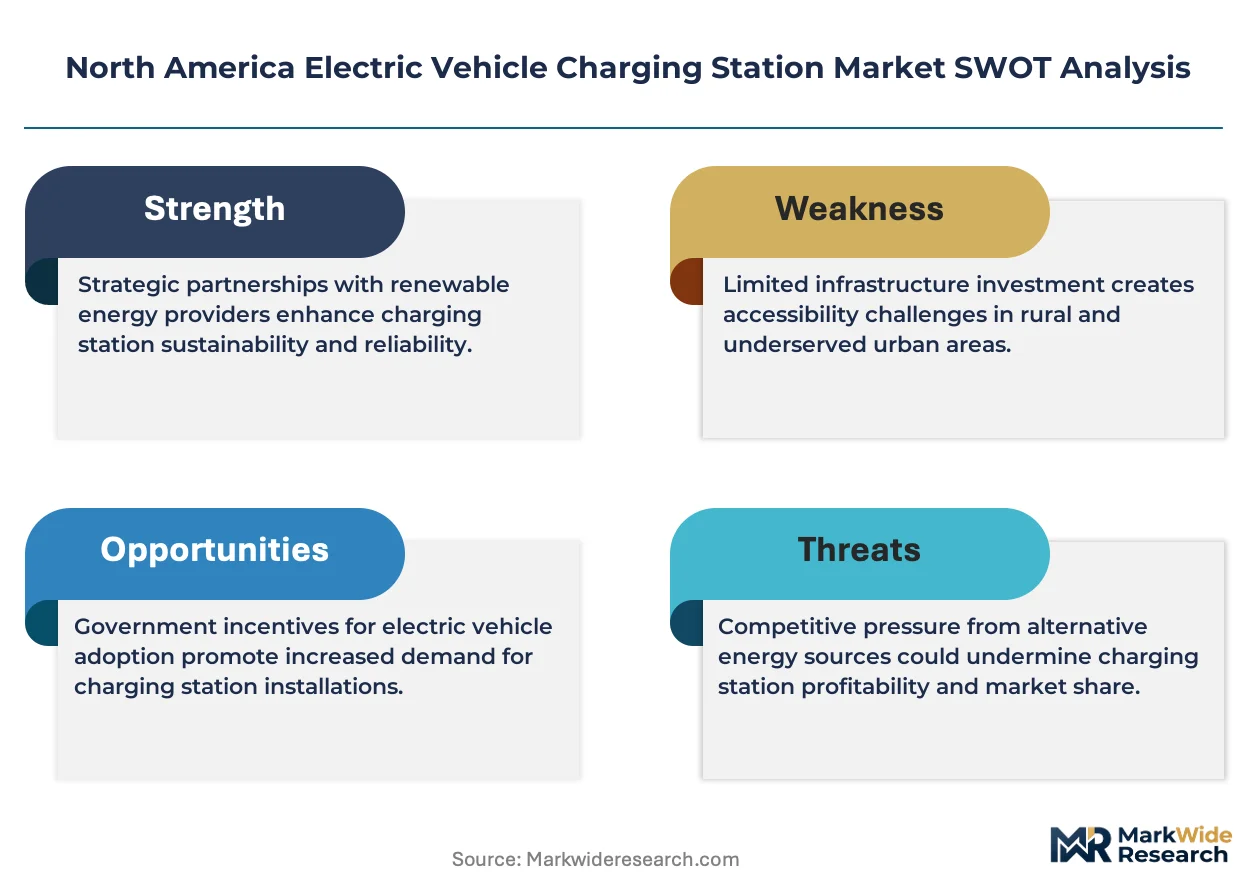
Market fragmentation creates entry niches as fleet procurement consolidates under single-network agreements while workplace charging remains underpenetrated across commercial real estate portfolios.
For Market Incumbents: Shield highway corridor positioning through accelerated NEVI compliance certification before 2026 funding windows contract. Deepen backward integration into power electronics assembly to offset silicon carbide cost volatility. Prioritize master electrician apprenticeship partnerships to unlock installation capacity constraints throttling deployment velocity. For New Entrants and Emerging Players: Differentiate on workplace charging deployment speed for commercial real estate portfolios in Texas metropolitan corridors where IRA tax credits compress payback periods. Target multi-unit dwelling retrofit demand in Canadian cities where national building code EV-ready mandates exclude existing stock. Pursue direct property manager channel relationships bypassing traditional electrical contractor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-layer specialists with ISO 15118 Plug and Charge authentication capabilities as NEVI interoperability mandates harden. Long-term viability hinges on vehicle-to-grid integration readiness across the projection horizon. Acquisition targets should demonstrate utility demand response program traction. The signal to watch is interconnection queue reform progress in high-growth utility territories.| Strategic Initiative | Industry Significance |
|---|---|
| NEVI Compliance Certification | ISO 15118 implementation unlocks federal highway corridor funding access. |
| Master Electrician Apprenticeship Programs | Installation capacity expansion addresses certified technician scarcity bottlenecks. |
| Silicon Carbide Supply Agreements | Long-term MOSFET sourcing hedges power electronics input cost volatility. |
| Workplace Charging Channel Partnerships | Commercial real estate relationships capture underpenetrated employer-sponsored deployment. |
| Vehicle-to-Grid Software Development | Managed demand response capabilities align with utility time-of-use rate structures. |
Research Methodology
Desk research of SEC filings from charging network operators, FHWA NEVI program disbursement records, and utility interconnection queue data preceded structured interviews with fleet electrification managers, electrical contractor operations directors, utility demand response program leads, and EV charging hardware procurement specialists. Primary fieldwork validated installation timeline assumptions and certified technician availability constraints. Secondary sources included EPA tailpipe standard rulemakings, CARB Advanced Clean Cars II regulatory filings, and Canada Infrastructure Bank capital commitment disclosures. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows.
Variance decomposition across product type, application, technology, and end-user segments governed the analytical framework over the projection horizon. CAGRs derived from installed base growth curves adjusted for interconnection queue delays and Buy America compliance friction. Modeled inputs incorporated IRA Section 30C tax credit capture rates, silicon carbide price trajectories, and fleet electrification procurement schedules.
Material uncertainties — copper commodity volatility, master electrician certification throughput, and utility rate case outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding federal funding continuity and state-level zero-emission vehicle mandate adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
Electric Vehicle Home Charger Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market