
 India Hybrid Electric Vehicle Battery Market | 2026-2036
India Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
India Hybrid Electric Vehicle Battery Market Insights
Silicon-anode integration in lithium-ion cells is reconfiguring energy density benchmarks for Indian hybrid applications. Amara Raja Batteries leverages its Tirupati manufacturing base to anchor domestic electrode production. LG Energy Solution competes through technology leadership in high-nickel cathode formulations. Exide Industries sustains its distribution reach across tier-2 and tier-3 dealership networks.
India hybrid electric vehicle batteries are electrochemical storage systems combining lithium-ion, nickel-metal hydride, or solid-state chemistries with power electronics to enable regenerative braking and electric-assist propulsion in internal combustion hybrids, typically operating at 200-400V with 1-5 kWh usable capacity. Lithium-ion chemistry dominates current production due to superior gravimetric energy density and cycle stability under Indian thermal conditions. Fleet operators represent the fastest-growing end-user segment as logistics companies electrify last-mile delivery platforms. Commercial vehicle applications command premium pricing due to heavier duty cycles and battery management system complexity.
BIS certification requirements and the PLI scheme administered by the Ministry of Heavy Industries shape product standards and capital access for domestic manufacturers. CDSCO and the country's national automotive regulator enforce cell-level safety protocols aligned with AIS standards for passenger and commercial vehicle integration. Stakeholders must monitor cell localization mandates and raw material offtake agreements before committing capacity expansion decisions.
Market Dynamics
Silicon-anode integration and the Ministry of Heavy Industries' PLI scheme are compressing cost curves while redirecting capital toward domestic electrode production in Tamil Nadu's automotive corridor.
Growth Catalysts
- Fleet electrification mandates:Logistics operators across Maharashtra and Gujarat are expanding hybrid commercial vehicle procurement to meet state-level emission targets and reduce diesel exposure.
- PLI scheme for advanced chemistry cells:The Ministry of Heavy Industries' production-linked incentive framework is accelerating gigafactory investment and reducing import dependency for lithium-ion cathode materials.
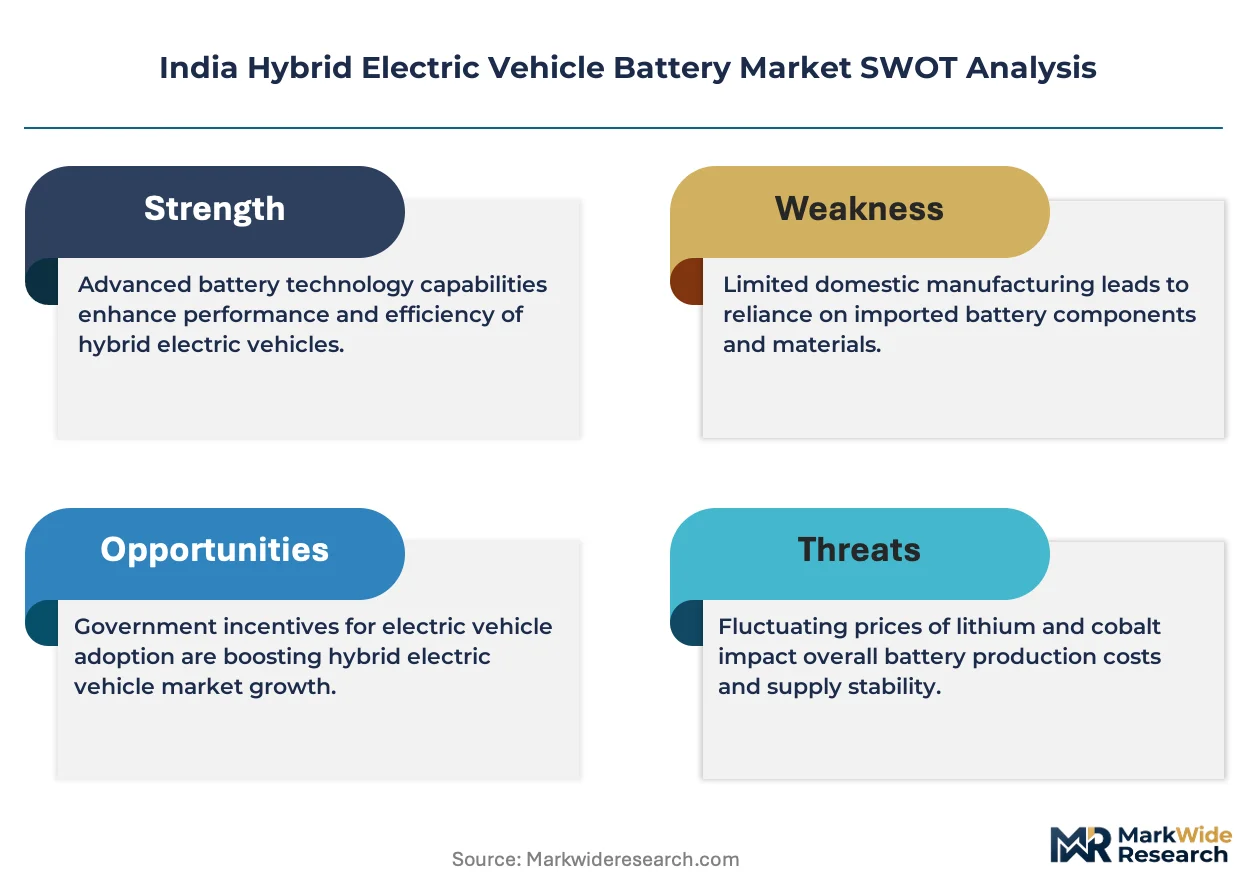
- Thermal management innovation:Solid-state electrolyte research is improving cycle stability under ambient temperatures exceeding 45°C in northern Indian operating conditions.
Market Restraints
- Lithium carbonate volatility:Raw material price swings from South American and Australian concentrate suppliers are compressing margin visibility for domestic pack assemblers.
- Cell import concentration:Over 75 percent of prismatic cell supply originates from East Asian contract manufacturers, creating geopolitical offtake risk.
- BIS certification timelines:Bureau of Indian Standards testing protocols for AIS 038-compliant battery packs extend product qualification cycles by 8-12 months versus comparable ASEAN markets.
Strategic Opportunities
- Karnataka-Telangana corridor expansion:Underpenetrated demand in Bengaluru's tech logistics ecosystem and Hyderabad's pharmaceutical cold-chain fleets offers first-mover positioning.
- Second-life stationary storage:Retired hybrid vehicle batteries are repurposing into telecom tower backup and rural microgrid applications at 40-60 percent residual capacity.
- Copper foil localization:The PLI scheme's downstream incentives are enabling domestic electrode substrate production previously sourced from Japanese and Korean rolling mills.
Industry Challenges
- Electrochemical engineering talent scarcity:Domestic universities produce fewer than 200 specialized cell scientists annually, forcing manufacturers to recruit from Korean and Taiwanese competitor programs.
- Pack-vehicle integration complexity:Legacy internal combustion platforms require structural redesign to accommodate 200-400V battery enclosures, extending OEM development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hybrid Electric Vehicle Battery Market |
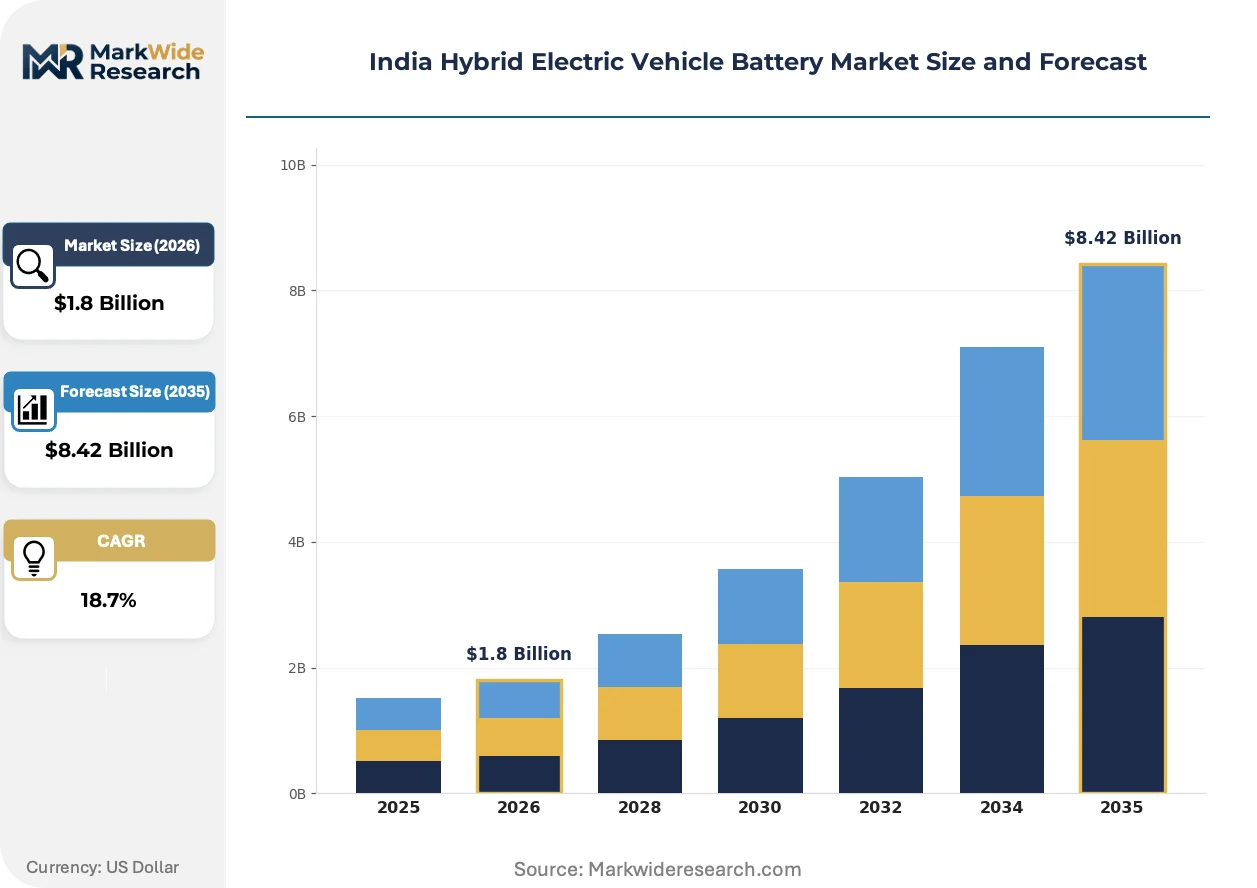
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid State Vehicle Type: SUVs, Hatchbacks, Sedans, Commercial Vehicles End User: Private Users, Fleet Operators, Government Agencies, Ride-Sharing Services Application: Personal Use, Public Transportation, Logistics, Emergency Services |
| Companies Covered | Amara Raja Batteries Ltd, Exide Industries Ltd, LG Energy Solution Ltd, Panasonic Holdings Corporation, Toshiba Corporation, Exicom Energy Systems Pvt. Ltd, Battrixx, Grinntech Motors & Services Pvt. Ltd., Bharatcell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hybrid Electric Vehicle Battery Market Trends and Innovations
Cell chemistry virtualization and regulatory localization mandates are compressing the traditional import-reliant supply architecture while accelerating domestic pilot production lines.
Solid-state lithium-metal prototypes are virtualizing conventional liquid electrolyte architectures by eliminating thermal runaway pathways and enabling 400Wh/kg gravimetric density. Fleet operators in Chennai's port logistics cluster are piloting these cells for heavy-duty hybrid trucks operating 18-hour duty cycles. This virtualization is compressing the performance gap between imported premium cells and domestically assembled packs.
The Ministry of Heavy Industries' phased manufacturing program is mandating progressive localization of cell components, with cathode active material production required to shift onshore by 2027. Domestic electrode coaters in Sriperumbudur are retooling solvent recovery systems to meet Central Pollution Control Board emission norms. Commercial vehicle integrators face the steepest compliance costs as their high-voltage architectures trigger stricter AIS 156 testing protocols.
Leasing-based battery procurement is displacing outright purchase in last-mile delivery fleets, transferring residual value risk to financial institutions and decoupling vehicle acquisition from energy storage capital. Tier-2 logistics aggregators in Pune and Ahmedabad are adopting this model fastest, driven by working capital constraints and uncertainty around second-life valuation. Tamil Nadu's state electric vehicle policy is incentivizing lessor registration through accelerated depreciation allowances.
India Hybrid Electric Vehicle Battery Market Segmentation
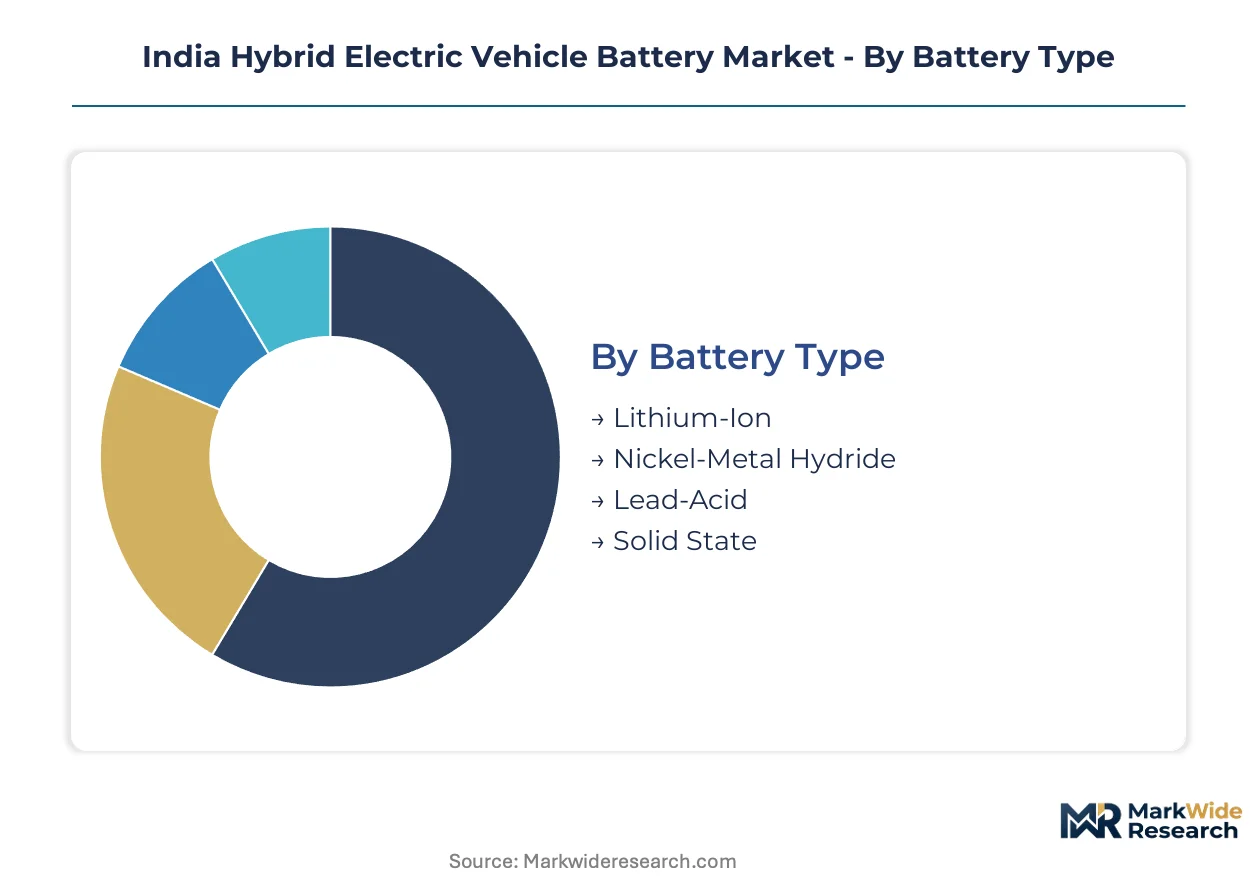
Segmentation in the India hybrid electric vehicle battery market reveals distinct performance requirements across vehicle platforms and duty cycles. Procurement patterns diverge sharply between private consumers prioritizing cost-per-kilometer and fleet operators optimizing for total cost of ownership over high-utilization schedules.
Battery Type:
Use cases span from urban commuter cycles demanding rapid charge acceptance to long-haul commercial routes requiring thermal stability under sustained loads.
- Lithium-Ion:Dominant chemistry employing nickel-manganese-cobalt or lithium-iron-phosphate cathodes with graphite-silicon composite anodes. Demand concentrates in Tamil Nadu's automotive corridor around Chennai and Sriperumbudur, driven by the Ministry of Heavy Industries' PLI scheme mandating progressive localization of cell components.
- Nickel-Metal Hydride:Mature technology utilizing rare-earth metal hydride anodes and nickel oxyhydroxide cathodes in prismatic cell formats. Toyota's local assembly operations in Karnataka sustain residual demand for mild-hybrid applications where cost sensitivity outweighs energy density requirements.
- Lead-Acid:Absorbent glass mat and enhanced flooded battery variants serve micro-hybrid start-stop systems in entry-level passenger vehicles. Maruti Suzuki's dominance in India's sub-4-meter segment preserves volume despite lithium-ion cost convergence.
- Solid State:Emerging architecture replacing liquid electrolytes with ceramic or sulfide ionic conductors. Pilot production lines in Bengaluru's electronics manufacturing cluster target 400Wh/kg prototypes for premium SUV integration.
The dominant share belongs to Lithium-Ion, while Solid State is closing the gap fastest through thermal runaway elimination and gravimetric density improvements.
Vehicle Type:
Platform architecture determines voltage class, thermal management complexity, and pack enclosure specifications across passenger and commercial categories.
- SUVs:Higher ground clearance enables larger battery enclosures with 400V architectures and liquid-cooled thermal management. Mahindra's XUV700 hybrid variant anchors demand in Maharashtra's premium personal mobility segment.
- Hatchbacks:Space-constrained platforms require 200V pouch cell configurations with passive air cooling. Maruti Suzuki's dominance in India's A-segment sustains volume through 48V mild-hybrid belt-integrated starter-generator systems.
- Sedans:Mid-size passenger vehicles balance cabin space against trunk-mounted battery placement. Honda City hybrid production in Rajasthan's Alwar district exemplifies 1.5 kWh nickel-metal hydride integration for urban fleet deployment.
- Commercial Vehicles:Heavy-duty cycles demand 5+ kWh usable capacity with active thermal management and IP67 ingress protection. Logistics operators across Gujarat's Mundra port corridor are expanding procurement of hybrid light commercial vehicles for last-mile freight.
Commercial Vehicles command the steepest pricing premiums, while SUVs are gaining share fastest through premium positioning and larger pack accommodation.
End User:
Procurement sophistication varies from individual cost-per-kilometer calculations to institutional total cost of ownership modeling across depreciation and residual value.
- Private Users:Individual consumers prioritizing fuel economy improvements and reduced maintenance intervals. Maharashtra and Delhi NCR account for concentrated demand due to state-level registration fee waivers for hybrid passenger vehicles.
- Fleet Operators:Logistics companies and mobility aggregators optimizing asset utilization across 18-hour duty cycles. BluSmart and similar ride-hailing platforms in Bengaluru are retrofitting hybrid powertrains into existing sedan fleets.
- Government Agencies:State transport undertakings and municipal corporations procuring hybrid buses under FAME-II subsidy frameworks. Tamil Nadu State Transport Corporation's Chennai metropolitan fleet represents anchor demand for 200kWh hybrid bus packs.
- Ride-Sharing Services:Platform-based mobility providers balancing driver earnings against fuel cost volatility. Ola and Uber's green vehicle mandates in Delhi and Bengaluru are accelerating hybrid hatchback deployment.
Fleet Operators capture the dominant procurement volume, while Ride-Sharing Services are expanding most quickly through platform-enforced green vehicle mandates.
Application:
Duty cycle intensity and ambient thermal exposure create divergent requirements for cycle stability and cooling system redundancy.
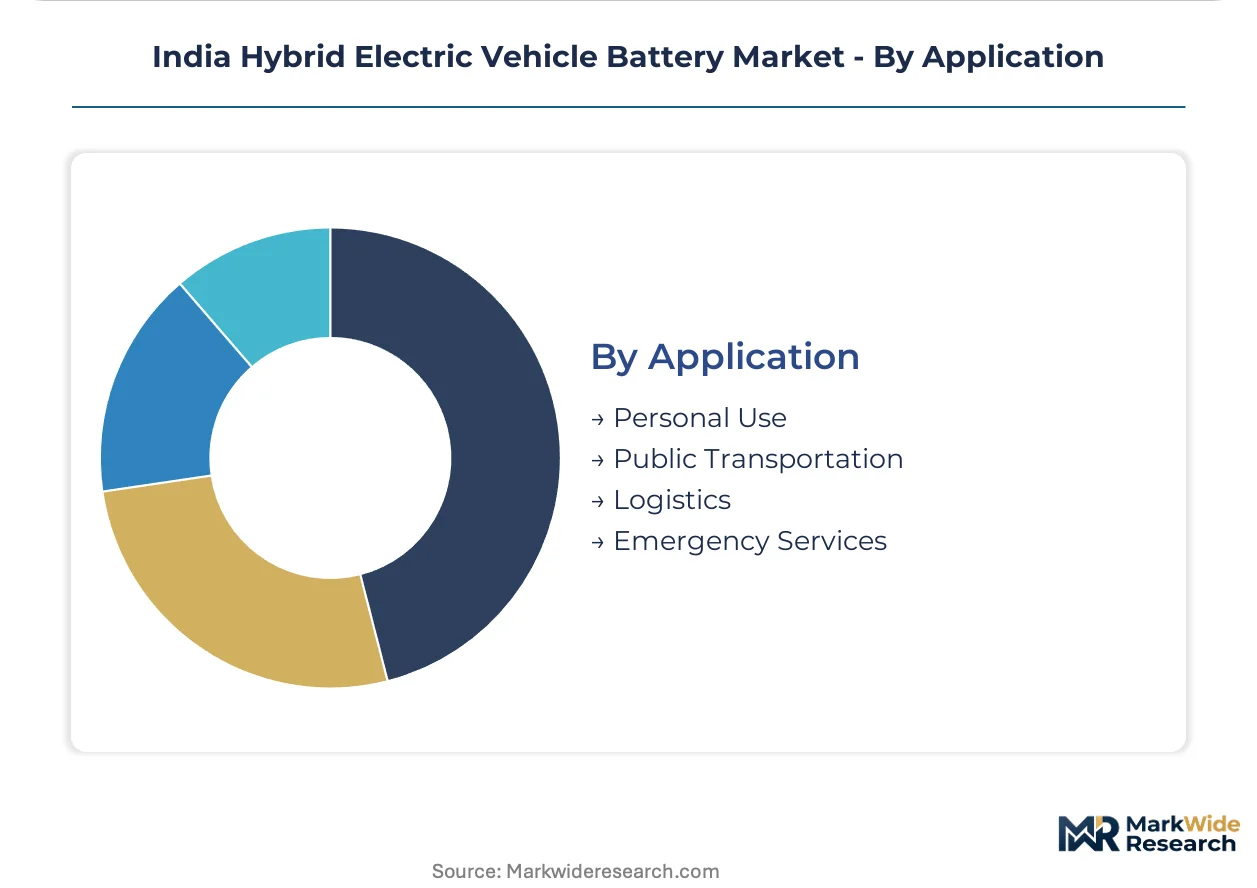
- Personal Use:Low daily utilization with intermittent charging patterns and moderate thermal stress. Urban commuter profiles in Pune and Hyderabad sustain demand for 1-2 kWh mild-hybrid systems.
- Public Transportation:High-frequency stop-start operations with regenerative braking energy recovery. BEST Mumbai's hybrid bus fleet exemplifies severe duty cycle requirements for 300,000+ kilometer pack lifetimes.
- Logistics:Cold-chain and e-commerce delivery platforms requiring uninterrupted power for auxiliary refrigeration. Hyderabad's pharmaceutical distribution corridor drives demand for hybrid refrigerated light commercial vehicles.
- Emergency Services:Police and ambulance fleets prioritizing reliability and rapid response over efficiency optimization. Gujarat's highway patrol vehicle procurement specifies hybrid powertrains for extended idle operation without engine running.
Logistics applications generate the dominant revenue concentration, while Public Transportation is climbing the fastest through state-level electrification mandates and FAME-II subsidy access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian cell manufacturers supply electrode materials to Tamil Nadu's automotive corridor, while domestic pack assemblers in Maharashtra and Gujarat integrate imported prismatic cells into commercial vehicle platforms.
Maharashtra
Logistics operators in Mumbai and Pune are expanding hybrid light commercial vehicle fleets to meet state-level emission mandates. The Maharashtra Electric Vehicle Policy offers registration fee waivers and road tax exemptions for hybrid commercial vehicles. Mahindra's Chakan manufacturing complex anchors domestic pack assembly for SUV and commercial platforms.
Gujarat
Mundra port logistics clusters drive demand for hybrid refrigerated trucks serving pharmaceutical cold-chain distribution. The state's industrial incentive schemes subsidize land acquisition for battery pack manufacturing facilities. Tata Motors' Sanand facility produces hybrid powertrain components for pan-Indian distribution.
Tamil Nadu
Chennai and Sriperumbudur host concentrated cathode active material production under the Ministry of Heavy Industries' PLI scheme. BIS certification laboratories in the region accelerate product qualification timelines for domestic manufacturers. Hyundai's Sriperumbudur plant integrates locally sourced lithium-ion packs into hybrid sedan exports.
Karnataka
Bengaluru's tech logistics ecosystem generates demand for last-mile delivery electrification among e-commerce aggregators. The state's electric vehicle policy mandates green procurement quotas for government fleet operators. Toyota's Bidadi facility sustains nickel-metal hydride production for mild-hybrid passenger vehicles.
Telangana
Hyderabad's pharmaceutical distribution networks require hybrid refrigerated vehicles for temperature-sensitive cargo transport. The Telangana State Electric Vehicle and Energy Storage Policy provides capital subsidies for cell manufacturing investments. Emerging electrode coating facilities in the city's industrial periphery target solvent recovery compliance with Central Pollution Control Board norms.
India Hybrid Electric Vehicle Battery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The market structure concentrates around domestic battery manufacturers with established distribution networks and Korean-Japanese technology licensors with cathode formulation expertise. Three archetypes dominate: integrated cell-to-pack manufacturers, electrode specialists with PLI scheme alignment, and import-dependent pack assemblers serving commercial vehicle integrators. Capacity expansion and strategic partnerships constitute the primary competitive vectors as localization mandates tighten.
Within the domestic integrated tier, Amara Raja Batteries Ltd and Exide Industries Ltd occupy positions anchored by established dealership networks and Tirupati-based electrode production infrastructure. Among Korean-Japanese technology providers, LG Energy Solution Ltd exemplifies the high-nickel cathode specialist archetype competing through energy density leadership. These named entities represent distinct strategic postures: backward integration into electrode manufacturing versus technology licensing and imported cell supply.
| Leading Market Players |
|---|
| Amara Raja Batteries Ltd |
| Exide Industries Ltd |
| LG Energy Solution Ltd |
| Panasonic Holdings Corporation |
| Toshiba Corporation |
| Exicom Energy Systems Pvt. Ltd |
| Battrixx |
| Grinntech Motors & Services Pvt. Ltd. |
| Bharatcell |
| Others |
Pricing and Supply Chain Analysis
Mundra port logistics corridors anchor cost dynamics for electrode material imports, concentrating supply-side leverage among East Asian cathode suppliers while forcing domestic pack assemblers into three-tier pricing stratification across premium certified, standard BIS-compliant, and economy import-dependent tiers.
Pricing Analysis
Next-generation solid-state prototypes command 40-60 percent premiums over current-generation lithium-ion packs, while prior-generation nickel-metal hydride systems sustain residual demand through Toyota's Karnataka assembly operations. Contract-based long-term offtake dominates commercial vehicle procurement, with price differentiation hinging on BIS certification grade and cathode active material localization status. Cost compression in economy-tier imports is intensifying because of lithium carbonate volatility from South American concentrate suppliers. Fleet operators exhibit highest price sensitivity due to total cost of ownership modeling, while premium SUV buyers show lowest sensitivity to pack premiums.
Supply Chain Analysis
Export-control regimes limiting high-nickel cathode technology transfers from South Korea and Japan are constraining domestic manufacturers' access to advanced formulations. Cell production concentrates in China, South Korea, and Japan, with India-dependent pack assemblers drawing from East Asian prismatic cell suppliers for over 75 percent of input volume. Raw material dependencies span lithium carbonate from Chile and Australia, cobalt from the Democratic Republic of Congo, and copper foil previously sourced from Japanese rolling mills. Single-source vulnerability around cathode active material supply creates structural risk. Distribution runs through Tamil Nadu's automotive corridor to Maharashtra and Gujarat commercial vehicle integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pure battery electric vehicle platforms pose the most acute substitution threat to hybrid architectures, forcing incumbent suppliers to defend their installed base through performance differentiation and fleet conversion cost economics.
For Market Incumbents: Insulate market position by accelerating backward integration into electrode coating capacity in Sriperumbudur before PLI scheme localization mandates tighten in 2027. Secure captive offtake agreements with Tamil Nadu-based cathode active material producers to reduce import dependency. Invest in BIS certification pre-qualification to compress 8-12 month testing cycles that currently disadvantage domestic pack assemblers against ASEAN competitors.
For New Entrants and Emerging Players: Karnataka-Telangana corridor underpenetration offers first-mover positioning in Bengaluru's tech logistics ecosystem and Hyderabad's pharmaceutical cold-chain fleets. Target second-life stationary storage applications for retired hybrid vehicle batteries at 40-60 percent residual capacity, serving telecom tower backup and rural microgrid demand. Pursue leasing-based battery procurement partnerships with tier-2 logistics aggregators facing working capital constraints.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant electrode manufacturing assets that could be repositioned under PLI scheme incentives. Five-to-ten year viability hinges on cell localization mandate compliance rather than import-dependent pack assembly margin capture. Monitor Ministry of Heavy Industries phased manufacturing program announcements as inflection indicators for cathode material production timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Gigafactory Investment | PLI scheme incentives are redirecting capital toward Tamil Nadu cathode active material production. |
| Solid-State Prototype Piloting | Chennai port logistics clusters are testing 400Wh/kg cells for 18-hour commercial duty cycles. |
| Leasing-Based Procurement Model | Financial institutions are absorbing residual value risk for Pune and Ahmedabad delivery fleets. |
| Second-Life Storage Repurposing | Retired hybrid packs are entering telecom tower backup at 40-60 percent residual capacity. |
| Copper Foil Localization | PLI downstream incentives are enabling domestic electrode substrate production. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at logistics operators, OEM platform engineers at commercial vehicle integrators, electrode coating facility managers, and BIS certification laboratory technical leads. Secondary validation drew from Ministry of Heavy Industries PLI scheme disclosures, Central Pollution Control Board emission compliance records, AIS standards documentation, and vehicle production registration databases. Bottom-up cell demand modeling triangulated against top-down fleet electrification mandate trajectories.
Calibration against historical localization timelines and cathode material cost curves anchored the analytical framework across the projection horizon. Segmentation dimensions spanned battery chemistry generation, vehicle platform voltage class, end-user procurement sophistication, and regional manufacturing cluster concentration. CAGRs derived from installed base turnover rates and fleet replacement cycle compression. Industry-specific forecast inputs incorporated thermal management performance under 45°C ambient operating conditions and BIS certification queue lengths.
Practitioners should monitor lithium carbonate spot price volatility and Ministry of Heavy Industries phased manufacturing program announcements for early signals of margin compression or localization acceleration. Forecasts reflect documented assumptions around PLI scheme continuation and AIS standards evolution. Material shifts in export-control regime stringency from East Asian technology licensors or abrupt BIS certification timeline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Solar Electric Car Market