
 Paperless Recorders Market | 2026-2036
Paperless Recorders Market Size, Share, and Industry Trends Forecast 2026-2036
Paperless Recorders Market Analytics
Buyer concentration across process industries is rebalancing as mid-sized pharmaceutical and food manufacturers digitize quality documentation, while oil and gas majors consolidate vendor lists. ABB Ltd leverages its automation portfolio to anchor large-scale DCS-integrated recorder deployments. Yokogawa Electric Corporation sustains dominance in Asia-Pacific process industries through specialized high-channel-count architectures. Honeywell International Inc. competes on wireless communication protocols that reduce installation costs in brownfield plants.
Paperless recorders are electronic data-acquisition devices that capture, display, and store process variables such as temperature, pressure, and flow rate using solid-state memory and TFT-LCD interfaces, eliminating consumable chart paper and enabling remote audit trails. Their primary industrial purpose centers on regulatory-compliant batch documentation and continuous process verification in GMP-regulated environments. Network recorders with cloud-based backhaul represent the fastest-expanding technology segment as manufacturers pursue centralized visibility across distributed sites. Portable recorders occupy a mature niche serving validation engineers who require mobile qualification of cleanrooms and autoclaves. Fixed recorders with embedded digital signal processing retain the deepest margin pools due to long replacement cycles and mandatory calibration services.
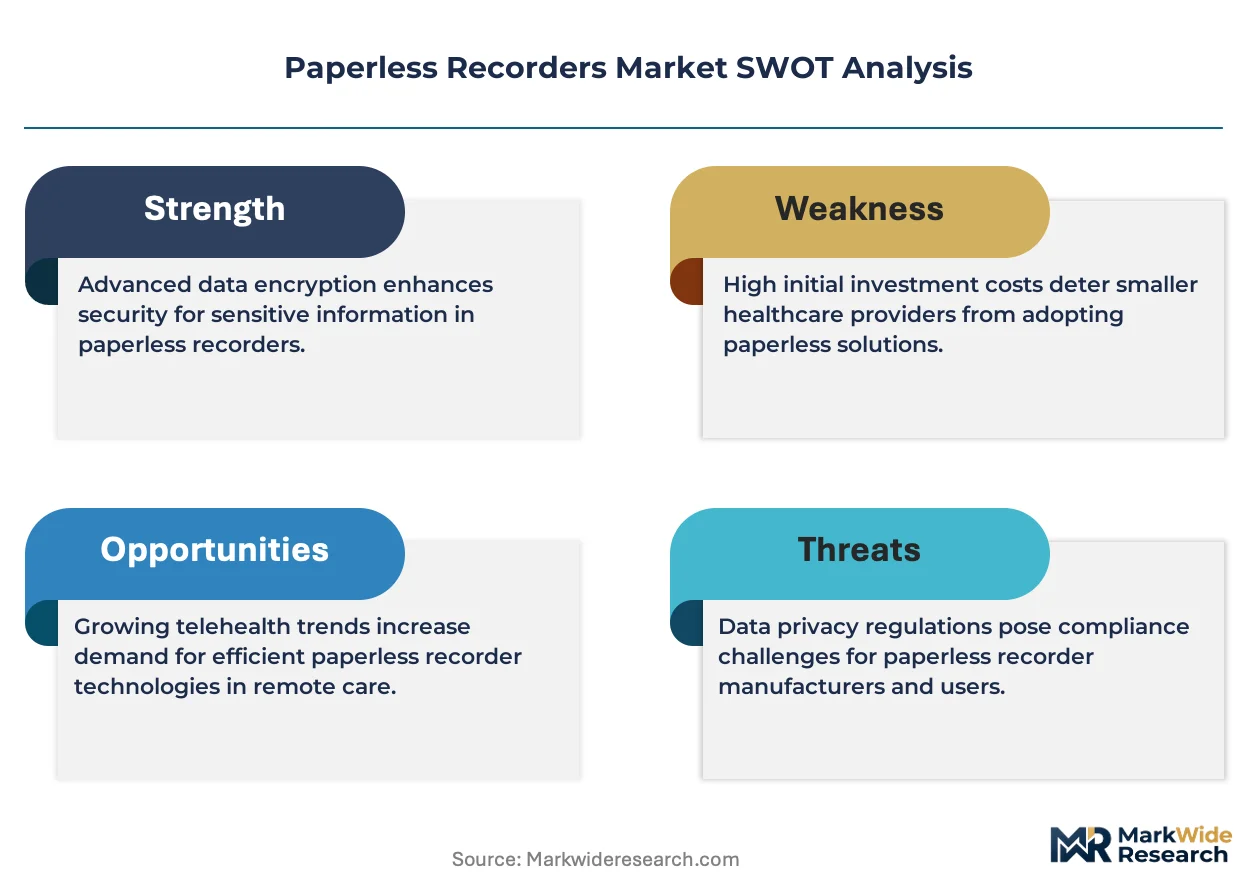
FDA 21 CFR Part 11 in the United States, EU GMP Annex 11 enforced by EMA, and ISO 9001 quality management standards collectively mandate electronic record integrity, audit trails, and user access controls that paper-based systems cannot satisfy. These frameworks shape demand by disqualifying non-validated recording devices from regulated manufacturing environments. Stakeholders must monitor evolving cybersecurity requirements for connected recorders as IEC 62443 adoption extends into operational technology layers.
Market Dynamics
Pharmaceutical batch record digitization is compressing replacement cycles for legacy chart recorders as FDA 21 CFR Part 11 and EU GMP Annex 11 mandates harden compliance requirements across GMP-regulated manufacturing environments.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail mandates in the United States are disqualifying paper-based systems from regulated pharmaceutical operations, forcing validated recorder upgrades.
- Process analytical technology:PAT initiatives in biologics manufacturing require real-time data capture with electronic batch records, embedding paperless recorders into continuous processing lines.
- Germany's industrial automation corridor:Process manufacturers in Baden-Württemberg and Bavaria prioritize validated electronic records, concentrating demand for high-channel-count architectures.
Market Restraints
- Semiconductor memory supply:Solid-state storage component availability fluctuates with foundry allocation cycles, constraining recorder production lead times.
- Calibration service infrastructure:Third-party metrology capacity concentrates in Western Europe and Japan, creating geographic gaps for validated maintenance in emerging manufacturing hubs.
- Legacy DCS protocol fragmentation:Proprietary communication standards in brownfield process plants complicate seamless recorder integration without gateway investments.
Strategic Opportunities
- India's pharmaceutical export sector:CDSCO alignment with PIC/S standards is accelerating electronic record adoption among API manufacturers serving regulated markets.
- Cloud-native validation:SaaS-based qualification documentation is converging with edge recorder deployments, reducing on-premise infrastructure burdens for mid-sized manufacturers.
- Brazil's ANVISA track-and-trace mandate:Serialization requirements for pharmaceutical supply chains are expanding electronic record scope beyond batch documentation to full genealogy capture.
Industry Challenges
- Cybersecurity competency gaps:IEC 62443 implementation for operational technology networks requires security engineering skills scarce among traditional automation technicians.
- Legacy system integration:Proprietary historian databases in 1990s-era DCS architectures resist seamless data exchange with modern Ethernet-connected recorders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperless Recorders Market |
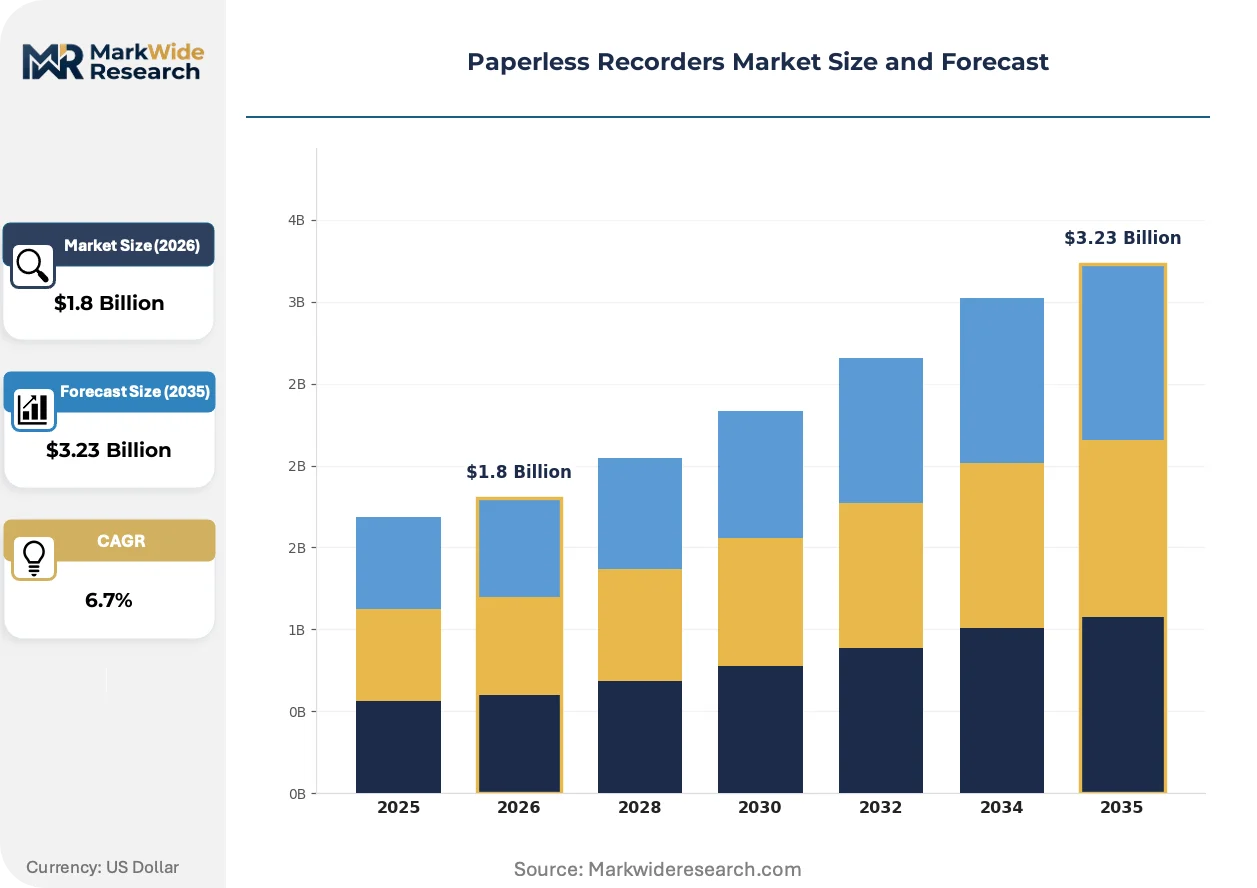
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Recorders, Network Recorders, Fixed Recorders, Hybrid Recorders Technology: Digital Signal Processing, Cloud-Based Solutions, Data Logging, Wireless Communication End User: Manufacturing, Pharmaceuticals, Oil & Gas, Food & Beverage Application: Temperature Monitoring, Pressure Tracking, Data Acquisition, Environmental Testing |
| Companies Covered | Honeywell International Inc., ABB Ltd, Yokogawa Electric Corporation, Siemens AG, Schneider Electric SE, Endress+Hauser Group, Emerson Electric Co., Fuji Electric Co., Ltd., OMEGA Engineering, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperless Recorders Market Evolving Landscape
Edge computing architectures are embedding analytical capabilities directly into recorder hardware, eliminating latency for critical process alarms while complicating traditional software licensing models.
Multi-variable transmitters with embedded digital signal processing are integrating edge analytics for predictive maintenance, enabling pharmaceutical manufacturers to correlate temperature excursions with equipment degradation patterns. Biologics producers in Switzerland and Singapore are deploying these units at twice the rate of small-molecule facilities. This capability is integrating condition-based monitoring into routine batch release workflows, compressing validation timelines for new production lines.
EMA's enhanced Annex 11 guidance on data integrity is mandating ALCOA+ principles for electronic records, requiring recorder vendors to implement write-once memory architectures and automated audit trail generation. Sterile injectable manufacturers face the steepest compliance burden, with inspectors scrutinizing time-stamp synchronization across distributed data loggers. German and Irish facilities are responding by consolidating recorder fleets under centralized qualification management platforms.
Equipment-as-a-service contracting is displacing capital purchase models for mid-sized food and beverage processors, with vendors retaining ownership of calibrated recorder assets and charging per-batch documentation fees. This restructures buyer-vendor relationships around uptime guarantees rather than hardware specifications. The shift is most visible in North American dairy and brewing operations, where margin pressure favors operational expenditure treatment of compliance infrastructure.
Paperless Recorders Market Segmentation
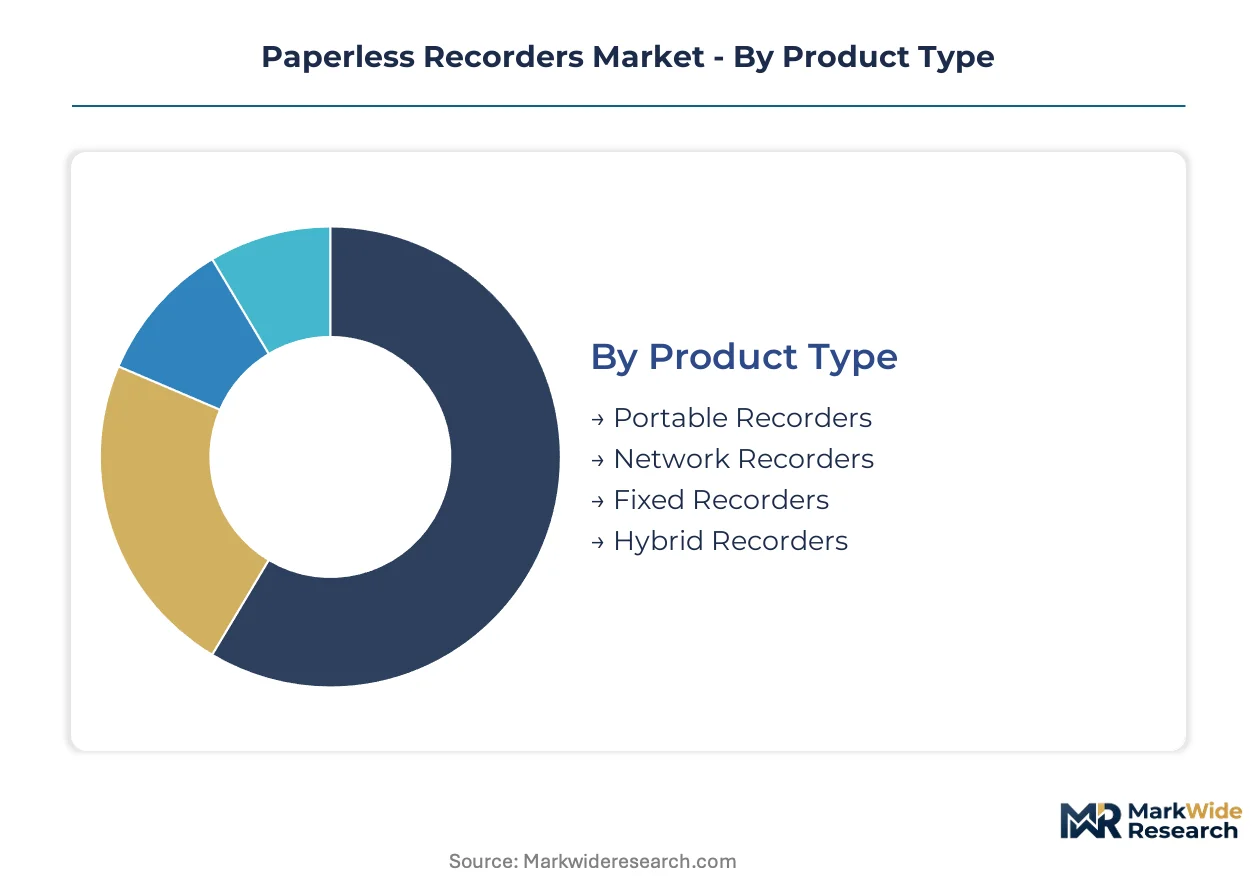
Paperless recorder procurement patterns diverge sharply across deployment contexts, with validated fixed installations dominating pharmaceutical capital budgets while portable units serve intermittent qualification workflows. Technology selection hinges on legacy infrastructure compatibility and regulatory audit trail requirements rather than hardware specifications alone.
Product Type:
Supply concentration favors fixed recorder architectures in high-channel-count manufacturing corridors, where calibration service density and spare parts logistics determine vendor selection.
- Fixed Recorders:These embedded units integrate directly into distributed control systems via proprietary fieldbus protocols, serving continuous process lines in German chemical and pharmaceutical plants. Demand clusters in Baden-Württemberg and Bavaria, where EMA-aligned validation documentation requirements favor long-term vendor relationships over price competition.
- Network Recorders:Ethernet-connected devices with cloud backhaul capabilities are capturing share among multi-site pharmaceutical operators seeking centralized batch record repositories. Swiss biologics manufacturers and Singapore sterile injectable facilities deploy these at elevated rates to synchronize time-stamped data across distributed cleanroom suites.
- Portable Recorders:Battery-powered mobile units enable validation engineers to qualify autoclaves and isolators without permanent installation.
- Hybrid Recorders:Dual-mode devices bridge standalone and networked operation for brownfield plants with mixed infrastructure ages.
Fixed recorders absorb the bulk of installed capacity; network recorders are expanding most quickly.
Technology:
Cost tiering separates premium digital signal processing architectures from commoditized data logging modules, with wireless protocols commanding intermediate pricing due to installation labor savings.
- Digital Signal Processing:Embedded DSP chips enable real-time filtering and alarm generation at the edge, eliminating latency for critical temperature excursions in bioreactor monitoring. Irish and German sterile injectable manufacturers specify these units to compress batch release timelines.
- Cloud-Based Solutions:SaaS-integrated recorders shift qualification documentation burdens to vendor-managed platforms, appealing to mid-sized North American food processors under margin pressure. Subscription pricing converts capital expenditure to operational treatment.
- Data Logging:Basic solid-state storage architectures satisfy ISO 9001 requirements without advanced analytics.
- Wireless Communication:IEEE 802.11 and proprietary industrial protocols reduce cabling costs in legacy brownfield renovations.
Digital signal processing dominates revenue contribution; cloud-based solutions are climbing the fastest.
End User:
Application maturity varies by sector compliance intensity, with pharmaceutical buyers demanding ALCOA+ audit trails that food and beverage purchasers often bypass.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU GMP Annex 11 mandates force validated electronic records for every batch release, embedding recorders into PAT-enabled continuous processing lines. CDSCO-aligned Indian API exporters are accelerating adoption to access regulated markets.
- Manufacturing:Process industries in Germany's automation corridor specify high-channel-count architectures for chemical and specialty material production.
- Oil & Gas:Upstream operators prioritize hazardous area certifications and wireless retrofit compatibility.
- Food & Beverage:Dairy and brewing operations in North America favor equipment-as-a-service contracting to convert compliance infrastructure to operational expenditure.
Pharmaceuticals command the deepest margin pools; food and beverage is gaining share fastest.
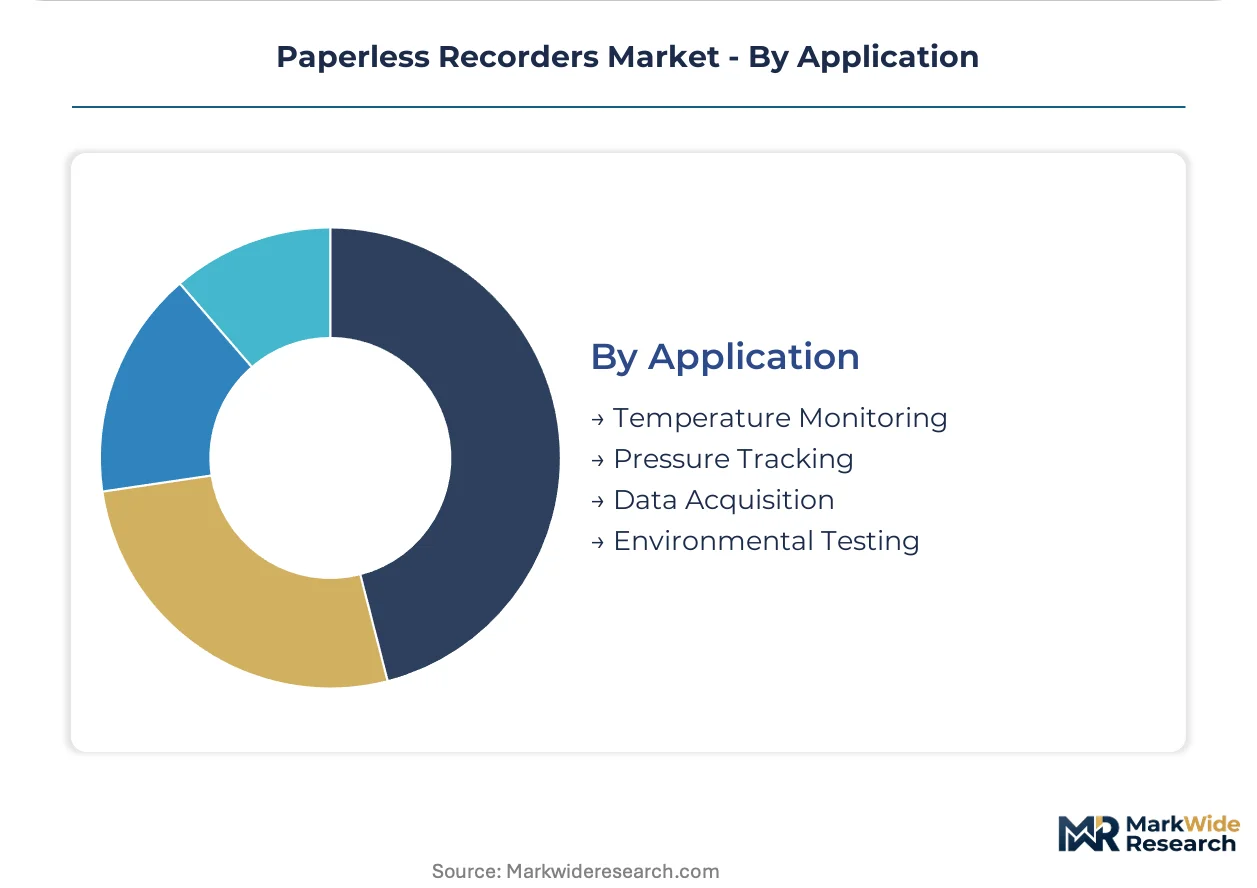
Application:
Customer type segmentation reflects diverging technical requirements between continuous process verification and episodic environmental qualification.
- Temperature Monitoring:Thermal mapping for autoclaves, freezers, and cleanrooms constitutes the most specification-intensive application, with Swissmedic and TGA inspectors scrutinizing sensor calibration intervals and time-stamp synchronization.
- Data Acquisition:Multi-parameter logging for batch records integrates pressure, flow, and analytical signals into unified electronic documentation.
- Pressure Tracking:Sterile barrier integrity monitoring in isolators and filling lines demands high-frequency sampling rates.
- Environmental Testing:Cleanroom qualification and HVAC validation represent episodic demand served by portable recorder rental fleets.
Temperature monitoring anchors installed base value; data acquisition is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer foundries in Taiwan and South Korea supply the solid-state memory components that constrain paperless recorder production cycles worldwide. Foundry allocation decisions in Hsinchu and Pyeongtaek directly shape delivery lead times for German and US process automation vendors.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts are replacing legacy chart recorders ahead of FDA 21 CFR Part 11 audits. The FDA's electronic signature mandates disqualify paper-based systems from sterile injectable operations. Boston-area biologics producers deploy high-channel-count architectures for continuous processing lines.
Germany
Process industries in Baden-Württemberg and Bavaria prioritize validated electronic records for chemical and specialty material production. EMA-aligned EU GMP Annex 11 requirements favor long-term vendor relationships over price competition. The Stuttgart industrial automation corridor concentrates demand for DCS-integrated recorder deployments.
India
API manufacturers in Maharashtra and Gujarat accelerate electronic record adoption to access regulated export markets. CDSCO alignment with PIC/S standards forces validated upgrades among contract manufacturers. Hyderabad's pharmaceutical cluster deploys cloud-backhaul recorders for multi-site batch documentation.
Switzerland
Biologics producers in Basel and Geneva deploy multi-variable transmitters at twice the rate of small-molecule facilities. Swissmedic inspectors scrutinize time-stamp synchronization across distributed data loggers. The Basel Life Sciences cluster integrates condition-based monitoring into routine batch release workflows.
Singapore
Sterile injectable facilities in Tuas and Biopolis deploy Ethernet-connected recorders to synchronize data across cleanroom suites. The national pharmaceutical regulator mandates ALCOA+ principles for electronic batch records. Singapore's biologics manufacturing hub leads Asia-Pacific adoption of edge-computing recorder architectures.
Paperless Recorders Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native validation and equipment-as-a-service contracting. The vendor base stratifies across three archetypes: diversified automation conglomerates with DCS integration capabilities, specialized instrumentation firms with metrology expertise, and regional fabricators serving price-sensitive replacement markets. Competitive positioning hinges on calibration service density and spare parts logistics rather than hardware differentiation alone. Consolidation pressure intensifies as mid-sized pharmaceutical buyers demand vendor-managed qualification platforms.
Among diversified automation conglomerates, Honeywell International Inc., ABB Ltd, and Yokogawa Electric Corporation exemplify distinct geographic anchoring strategies. Honeywell represents North American wireless protocol specialization for brownfield retrofit markets. ABB Ltd occupies a position within European process automation integration. Yokogawa Electric Corporation anchors Asia-Pacific high-channel-count architectures. These three firms sit within the premium tier where long-term validation relationships override procurement cost pressures.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd |
| Yokogawa Electric Corporation |
| Siemens AG |
| Schneider Electric SE |
| Endress+Hauser Group |
| Emerson Electric Co. |
| Fuji Electric Co., Ltd. |
| OMEGA Engineering, Inc. |
| Others |
Value Network & Pricing Analysis
Captive calibration service networks in Western Europe and Japan anchor both supply security and pricing power for paperless recorder vendors, creating geographic moats that resist commoditization despite hardware standardization. This backward integration into metrology infrastructure allows established suppliers to bundle validation documentation with hardware sales, compressing procurement cycles for pharmaceutical buyers while extracting premium pricing.
Pricing Analysis
Warranty and calibration bundling separates premium-tier recorder deployments from unbundled economy alternatives, with FDA-validated service contracts commanding substantial premiums over hardware-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity—EMA-aligned validation tiers price above basic ISO 9001-compliant units, while volume-scale pharmaceutical procurement softens per-unit costs through fleet standardization. Pricing pressure stems from equipment-as-a-service contracting in North American food processing, where subscription models convert capital expenditure to operational treatment. Mid-sized pharmaceutical buyers exhibit lowest price sensitivity due to audit risk exposure, while commodity chemical manufacturers prioritize hardware acquisition cost over service bundling.
Supply Chain Analysis
Solid-state memory supply rests on Taiwanese and South Korean wafer foundries, with Hsinchu and Pyeongtaek production cycles directly constraining German and US automation vendor delivery schedules. TFT-LCD display panels and embedded DSP chips draw from Japanese and South Korean component specialists, creating multi-source dependencies for high-channel-count architectures. Single-source vulnerability concentrates in advanced semiconductor nodes serving edge-computing recorder variants. Distribution runs through authorized system integrators in Germany's automation corridor and direct OEM relationships in North American pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry allocation cycles constrain paperless recorder production capacity, propping vendor pricing power and extending lead times for high-channel-count architectures during supply crunches.
For Market Incumbents: Lock in long-term validation service contracts with German pharmaceutical clusters to defend against cloud-native entrants offering SaaS-integrated alternatives. Expand captive calibration infrastructure into India's Maharashtra and Gujarat pharmaceutical corridors before CDSCO-aligned PIC/S standards mature. Vertical integration into solid-state memory inventory buffers insulates against Taiwanese foundry allocation volatility. For New Entrants and Emerging Players: Direct-to-validation-engineer digital channels bypass entrenched system integrator relationships, enabling portable recorder rental platforms to capture episodic cleanroom qualification demand. Brazil's ANVISA track-and-trace mandate creates white-space for serialization-integrated recorder solutions in pharmaceutical supply chains. Target North American dairy and brewing equipment-as-a-service contracting, where margin pressure favors operational expenditure treatment over capital purchase. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified automation conglomerates seeking DCS integration capabilities and validated service density. Long-term viability favors vendors with dense calibration infrastructure in regulated manufacturing corridors rather than hardware-only specialists. Watch IEC 62443 cybersecurity adoption in operational technology networks as inflection indicator for vendor capability requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Validation Platform Launch | SaaS-integrated recorders reduce on-premise infrastructure burdens for mid-sized CDSCO-aligned Indian API manufacturers. |
| Calibration Service Network Expansion | Captive metrology infrastructure in emerging hubs closes geographic gaps constraining validated maintenance capacity. |
| Edge Computing Architecture Development | Embedded DSP analytics compress batch release timelines for Swissmedic-scrutinized sterile injectable facilities. |
| Equipment-as-a-Service Contracting Model | Subscription pricing converts capital expenditure to operational treatment for margin-pressured North American food processors. |
| Cybersecurity Certification Investment | IEC 62443 implementation addresses security engineering skill scarcity among traditional automation technicians. |
Research Methodology
Independent corroboration across automation vendor sales directors, pharmaceutical validation engineers, and metrology service technicians underwrites the qualitative findings in this study. Primary interviews with plant engineers at German chemical facilities, procurement leads at Indian API exporters, and aftermarket service heads at Japanese instrumentation firms combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA Annex 11 inspection observations, and SEC filings of listed automation conglomerates. Bottom-up installed base estimates and top-down market sizing triangulate volume figures across the analysis window.
Rate-of-change decomposition separates hardware replacement cycles from regulatory-mandated upgrade waves, with CAGRs derived from segment-level growth differentials across product type, technology tier, end-use industry, and application intensity. The modeling framework incorporates pharmaceutical batch record digitization velocity, cloud-backhaul adoption curves among multi-site operators, and edge-computing penetration in biologics manufacturing. Semiconductor foundry allocation cycles and calibration service infrastructure density inform supply-side constraints.
The model holds under stable regulatory enforcement of FDA 21 CFR Part 11 and EU GMP Annex 11; deviation in cybersecurity mandate timing or foundry capacity allocation would shift replacement cycle assumptions. Forecasts reflect documented assumptions about validation documentation standardization and equipment-as-a-service contracting penetration. A small set of named triggers—IEC 62443 adoption pace, CDSCO PIC/S alignment progress, and Taiwanese semiconductor export restrictions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Industrial Direct Radiography Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Ultrasonic Wall Thickness Gauges Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Calorimeters Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
North America Automated Test Equipment Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market