
 Smart EV Battery Charger Market | 2026-2036
Smart EV Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Smart EV Battery Charger Market Insights
The capital-intensity divergence between integrated hardware-software platforms and component-assemblers is unwinding competitive stability in the Smart EV Battery Charger space. Tesla leverages its captive vehicle ecosystem to anchor proprietary charging protocols and destination networks. ChargePoint Holdings sustains broad interoperability across multiple OEM platforms, competing on network density rather than vertical integration.
A smart EV battery charger integrates power electronics, bidirectional communication modules, and thermal management systems to convert grid electricity into vehicle-compatible DC power while enabling remote monitoring, load balancing, and vehicle-to-grid feedback loops. DC Fast Chargers dominate public infrastructure deployment due to throughput requirements at highway corridors and commercial depots, while Home Chargers anchor residential margin pools through software subscription attach rates. Wireless Chargers occupy a nascent position in premium residential and automated fleet segments where installation aesthetics and hands-free operation justify cost premiums.
The US Department of Transportation coordinates with state regulators to enforce NEVI-funded charger reliability standards, while the EU F-Gas Regulation and CE marking framework shape thermal system design and refrigerant selection for European deployments. China's GB standards and MIIT interoperability mandates dictate connector protocols and communication layers for equipment accessing the world's largest EV charging network. Stakeholders must monitor evolving grid interconnection rules and cybersecurity certification requirements as utilities integrate distributed charger loads into active demand-response programs.
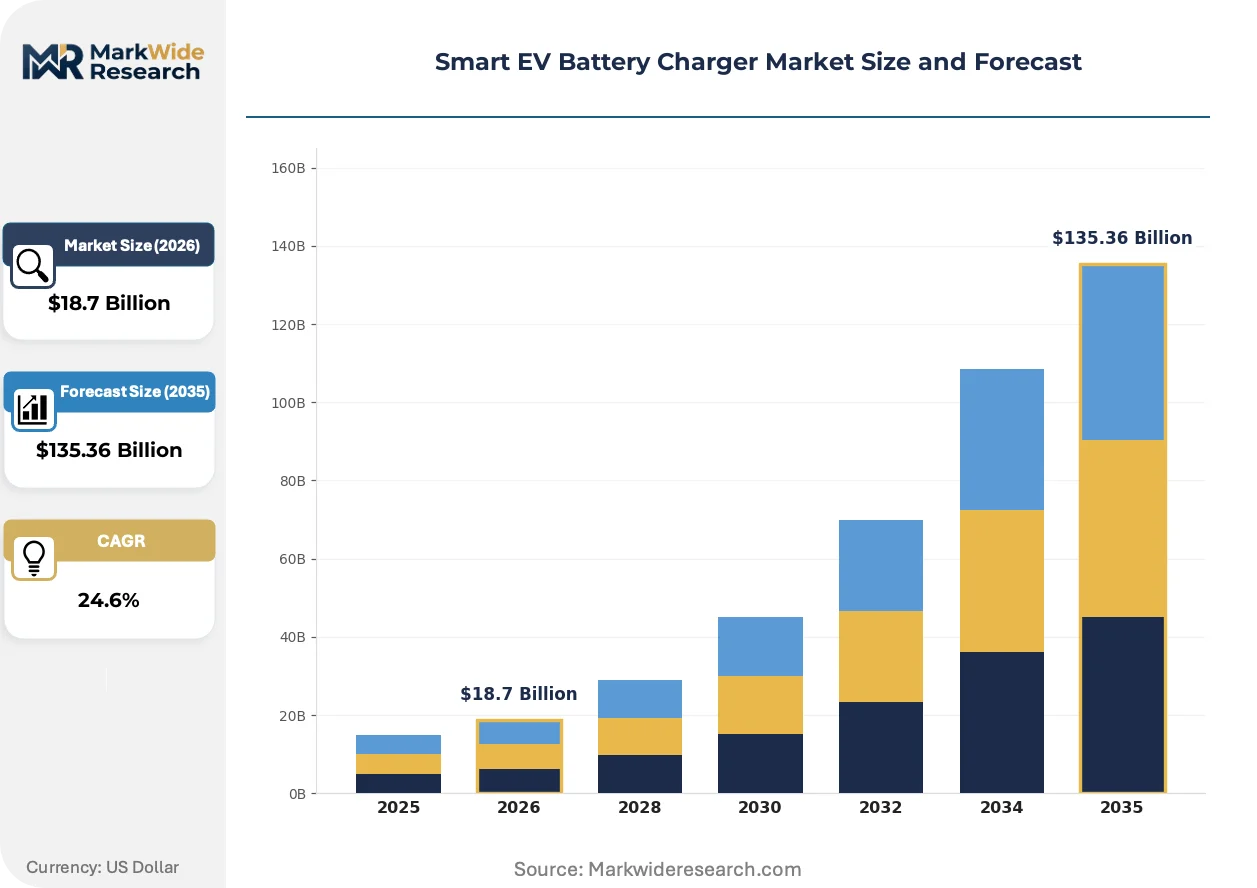
Market Dynamics
The convergence of bidirectional charging capabilities with utility-scale demand-response programs is restructuring how infrastructure operators monetize charger assets beyond transaction fees.
Growth Catalysts
- EU Green Deal infrastructure mandates:Binding targets for charging density along trans-European transport corridors are compelling member states to accelerate public procurement cycles and streamline permitting workflows for highway-adjacent sites.
- Fleet electrification economics:Commercial operators managing depot-based logistics networks are achieving total-cost-of-ownership parity earlier than projected, triggering bulk charger orders with integrated energy management software.
- Silicon carbide semiconductors:Wider bandgap materials are reducing switching losses in power conversion stages, enabling higher power density modules that shrink footprint requirements for urban installations.
Market Restraints
- Copper and rare-earth magnet volatility:Induction components in high-power transformers remain exposed to commodity price swings that compress hardware margins during contract execution periods.
- Transformer substation lead times:Grid interconnection queues in dense urban corridors extend deployment timelines by months, constraining site activation velocity for network operators.
- CE marking complexity under F-Gas Regulation:Thermal management system certification for European deployments requires refrigerant selection tradeoffs that limit supplier flexibility and extend validation cycles.
Strategic Opportunities
- Vehicle-to-grid aggregation services:Bidirectional chargers capable of grid-frequency regulation are unlocking recurring revenue streams for residential and commercial asset owners participating in wholesale power markets.
- India's PLI scheme for auto components:Localized manufacturing incentives are drawing component suppliers to establish power electronics assembly capacity serving domestic EV adoption curves.
- Wireless inductive highway segments:Dynamic charging infrastructure embedded in roadway surfaces is attracting pilot funding from transport authorities seeking to extend electric range for heavy-duty corridors.
Industry Challenges
- Embedded systems cybersecurity certification:IEC 62443 compliance timelines for communication modules are extending product development cycles as threat surface assessments become mandatory for grid-connected assets.
- Power electronics talent scarcity:Shortages of engineers with combined expertise in thermal management, magnetic design, and firmware architecture are constraining R&D throughput at mid-tier equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart EV Battery Charger Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Home Chargers Installation Type: Wall-Mounted, Portable, Stationary, Embedded Charging Speed: Level 1, Level 2, Level 3, Ultra-Fast End User: Residential Users, Commercial Fleets, Public Infrastructure, Utility Providers |
| Companies Covered | Tesla, Inc., ChargePoint Holdings, Inc., ABB Ltd., Siemens AG, Schneider Electric, Eaton Corporation PLC, Wallbox N.V., Delta Electronics, Inc., EVBox Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart EV Battery Charger Market Trends and Innovations
Hardware-software decoupling is enabling charger networks to function as distributed energy resources rather than passive electricity terminals.
Silicon carbide MOSFETs are supplanting silicon IGBTs in DC fast charger power stages, cutting switching losses by half and allowing liquid-cooled modules to achieve megawatt-class output in compact footprints. Tier-1 suppliers are qualifying these designs for 350kW highway installations where thermal density constraints previously capped output. The transition is compressing charger form factors and reducing cooling system mass, enabling pole-mounted configurations that minimize civil works.
China's MIIT interoperability mandates are mandating unified communication protocols across all public charging equipment, forcing foreign entrants to adapt controller firmware to GB/T standards for network access. Domestic operators must retrofit legacy installations to comply with real-time data reporting requirements for state monitoring platforms. The policy is consolidating protocol diversity and raising compliance costs for regional equipment vendors lacking in-country software development capacity.
Fleet operators are unbundling charger hardware procurement from energy management software subscriptions, treating charging infrastructure as a separable capital asset with independent financing structures. Third-party software platforms are displacing OEM-integrated control systems in commercial depot deployments across Germany and California. This purchasing pattern is most pronounced among logistics consolidators operating mixed-vehicle fleets requiring cross-platform charge scheduling optimization.
Smart EV Battery Charger Market Segmentation
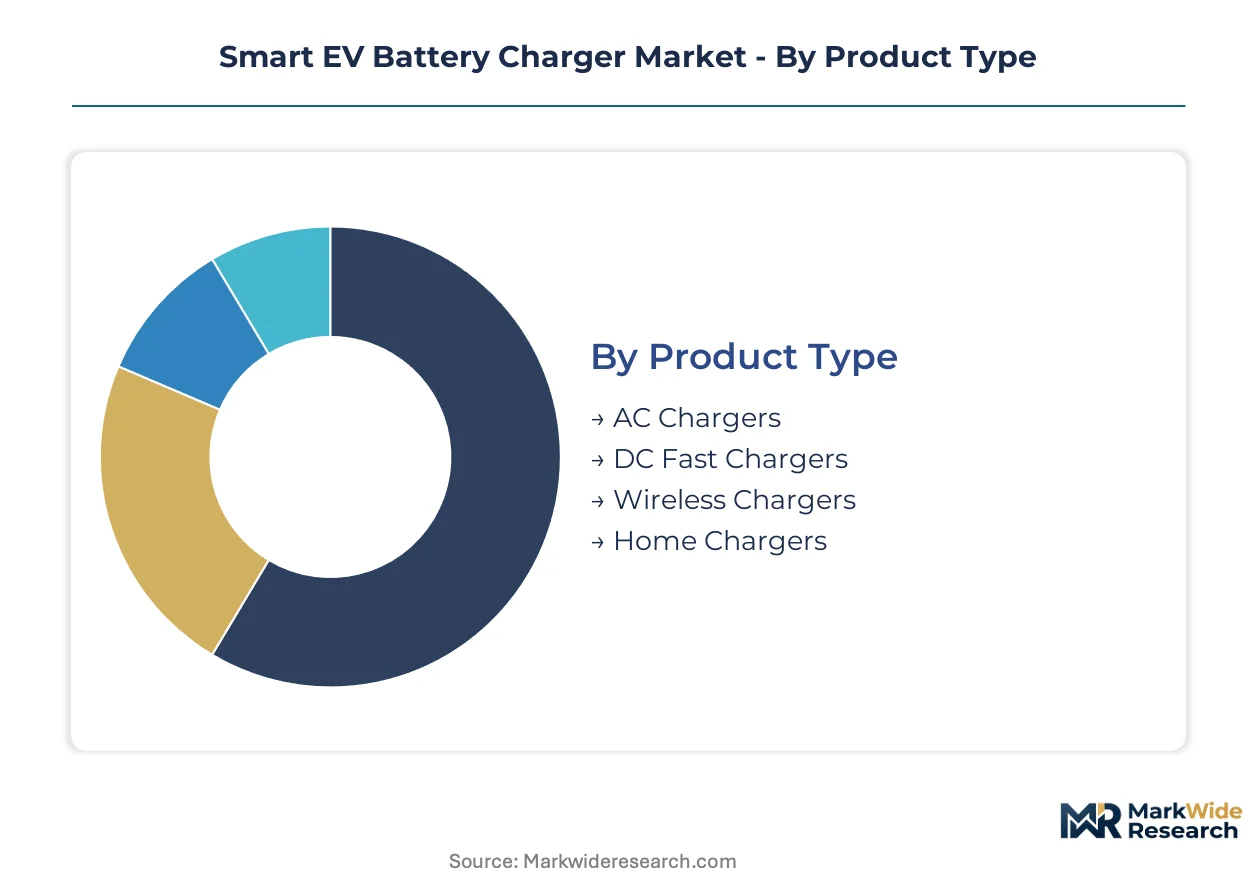
Segmentation in the Smart EV Battery Charger Market reveals how hardware specifications, deployment contexts, and user requirements fragment procurement patterns. Charger manufacturers must align product portfolios across power electronics tiers, installation constraints, and operational duty cycles to capture volume.
Product Type:
Geographic spread varies sharply: DC Fast Chargers and Home Chargers concentrate procurement in China, Germany, and California where policy subsidies and manufacturing clusters align, while Wireless Chargers remain export-constrained to premium residential markets in Japan and South Korea.
- DC Fast Chargers:High-power conversion systems utilizing liquid-cooled silicon carbide modules deliver 150-350kW output for highway corridor and commercial depot deployment. Demand clusters along trans-European transport networks and China's NEVI-equivalent highway buildouts where throughput economics dominate site selection.
- Home Chargers:Lower-power AC or DC units rated 7-22kW integrate with residential electrical panels and utility demand-response programs. Procurement concentrates in California and Germany where time-of-use tariffs and IRA or KfW subsidies accelerate residential electrification timelines.
- AC Chargers:Grid-tied alternating current systems common in workplace and multi-unit dwelling installations where dwell times accommodate slower charging cycles.
- Wireless Chargers:Inductive power transfer systems embedding coils in pavement or garage floors, currently limited to automated fleet pilots and luxury residential segments in Japan.
DC Fast Chargers commands the established base. The steepest expansion runs through Home Chargers.
Installation Type:
Cost tier stratification separates civil-works-intensive stationary installations from low-capital portable units, with margin structures inversely correlated to deployment flexibility.
- Stationary:Fixed pedestal or ground-mount systems requiring foundation work, trenching, and transformer interconnection for permanent highway and depot infrastructure. Demand concentrates in China's MIIT-mandated public network buildouts and Germany's Autobahn corridor tenders where 10-year operational lifecycles justify capital intensity.
- Wall-Mounted:Bracket-attached units minimizing footprint in parking structures and residential garages. Procurement accelerates in California's Title 24-compliant multi-family housing developments and EU Green Deal-funded commercial retrofits where space constraints dominate site design.
- Portable:Mobile units with plug-in connectivity for emergency or temporary deployment, common among commercial fleet operators managing seasonal demand spikes.
- Embedded:Infrastructure-integrated systems including roadway-embedded inductive coils and vehicle-integrated charging modules, currently restricted to pilot programs in Sweden and Germany.
Stationary installations anchor revenue volume. Wall-Mounted configurations are climbing the fastest as urban density constraints reshape procurement specifications.
Charging Speed:
Application context determines speed tier selection, with duty cycle requirements and dwell time economics driving segmentation between residential, commercial, and highway use cases.
- Level 3:Direct current systems delivering 50-150kW through standardized connectors for public infrastructure where 20-60 minute charging windows align with retail or service stops. Deployment concentrates in China's State Grid-operated highway networks and Germany's Fast Charging Act corridor mandates.
- Ultra-Fast:Megawatt-class systems exceeding 350kW utilizing liquid-cooled cables and high-voltage architectures for heavy-duty commercial corridors. Pilot installations target California's I-5 freight corridor and EU-funded heavy transport routes where battery-electric trucking economics depend on minimal charging downtime.
- Level 1:Standard 120V alternating current delivery through conventional outlets, predominant in legacy residential contexts with overnight dwell times.
- Level 2:240V AC or moderate DC systems balancing installation cost and charging speed for workplace and residential applications.
Level 3 systems command the established base. Ultra-Fast infrastructure shows the steepest expansion trajectory as commercial electrification timelines accelerate.
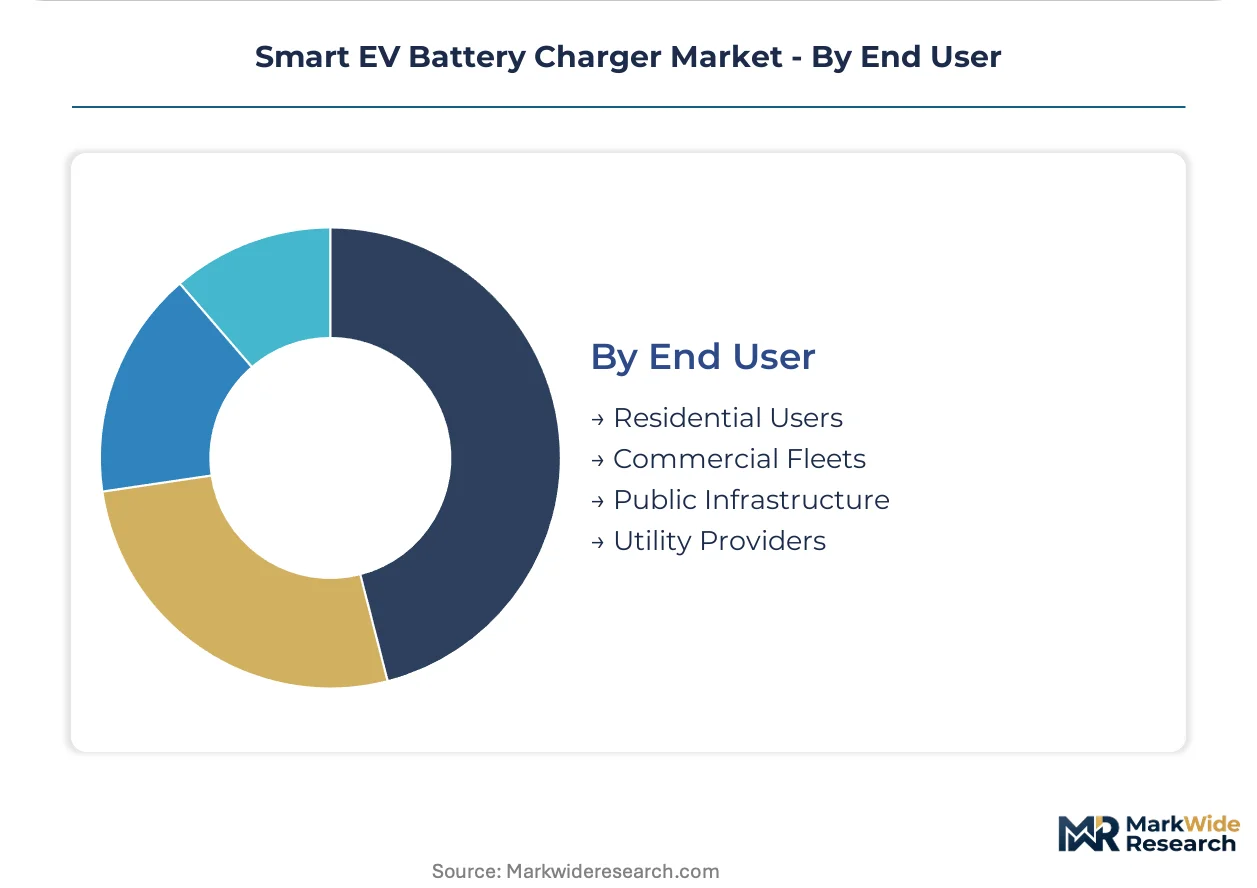
End User:
Customer type segmentation fragments procurement authority across decentralized residential decision-makers, centralized fleet operators, and regulated public infrastructure authorities with diverging technical specifications.
- Commercial Fleets:Depot-based logistics operators managing scheduled charging for medium- and heavy-duty vehicle pools with integrated energy management software. Procurement concentrates in California's CARB-regulated drayage and last-mile segments and Germany's logistics hubs near Frankfurt and Hamburg where total-cost-of-ownership parity triggers bulk charger orders.
- Public Infrastructure:State-funded highway corridor networks and municipal parking installations subject to reliability mandates and interoperability requirements. China's MIIT real-time monitoring mandates and US NEVI reliability standards shape technical specifications for equipment vendors.
- Residential Users:Individual homeowners and multi-family dwellers selecting units through contractor channels or direct-to-consumer platforms, price-sensitive to hardware and installation bundling.
- Utility Providers:Grid operators deploying chargers as managed distributed energy resources for demand-response aggregation, currently concentrated in California's CAISO market and Germany's transmission system operator zones.
Public Infrastructure commands the established base. Commercial Fleets are gaining share fastest as electrification economics reach parity ahead of projections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in smart EV battery chargers tilt toward surplus economies with integrated power electronics manufacturing. Import dependency concentrates in markets lacking silicon carbide foundry capacity or high-voltage transformer production.
China
State Grid Corporation deploys DC fast chargers along 35,000 kilometers of highway corridors under MIIT-mandated interoperability protocols. GB/T standards unify connector and communication layers, forcing foreign equipment vendors to localize firmware development. Yangtze River Delta clusters in Shanghai and Suzhou host power module assembly for both domestic consumption and Southeast Asian export.
Germany
Autobahn corridor tenders under the EU Green Deal mandate charging points every 60 kilometers, accelerating public procurement cycles. KBA enforces CE marking and F-Gas Regulation compliance for thermal management systems, extending validation timelines for refrigerant selection. Baden-Württemberg's Stuttgart region anchors Bosch and Siemens manufacturing for European distribution.
United States
NEVI-funded highway buildouts prioritize reliability standards enforced by the Department of Transportation across interstate corridors. IRA production tax credits draw power electronics assembly to Texas and Tennessee. California's CARB regulations for drayage and last-mile fleets trigger depot charger orders in the Los Angeles and Central Valley logistics hubs.
India
PLI scheme incentives for auto components attract power electronics suppliers to establish assembly capacity in Gujarat and Tamil Nadu. CEA grid interconnection rules shape charger specifications for distribution network compatibility. Delhi-NCR and Maharashtra concentrate early public infrastructure deployment through state-level electric mobility missions.
South Korea
Seoul Capital Area mandates building code integration of EV-ready parking infrastructure, driving residential and commercial charger procurement. MFDS cybersecurity frameworks for grid-connected devices extend certification timelines for communication modules. Busan-Ulsan industrial corridors host Hyundai-affiliated suppliers producing high-voltage charging components for export.
Smart EV Battery Charger Market Competitive Landscape
Concentration sits with integrated hardware-software platforms and specialized power electronics fabricators. Tier-1 industrial conglomerates compete against dedicated charging network operators and automotive-captive suppliers. Two archetypes dominate: vertically integrated vehicle-charger ecosystems, and interoperable network infrastructure providers. Competitive moves center on silicon carbide module qualification and bidirectional charging firmware development.
Among automotive-captive suppliers, Tesla, Inc. anchors proprietary protocol development through its Supercharger network. ChargePoint Holdings, Inc. exemplifies the interoperability-focused archetype with broad OEM platform coverage. ABB Ltd. represents industrial conglomerate positioning in high-power DC systems for highway and depot deployment.
| Leading Market Players |
|---|
| Tesla, Inc. |
| ChargePoint Holdings, Inc. |
| ABB Ltd. |
| Siemens AG |
| Schneider Electric |
| Eaton Corporation PLC |
| Wallbox N.V. |
| Delta Electronics, Inc. |
| EVBox Group |
| Others |
Pricing and Supply Chain Analysis
CE marking and F-Gas Regulation compliance for European thermal management systems simultaneously gates supplier qualification and creates three-tier pricing stratification across premium-certified, standard-compliant, and economy-grade equipment tiers. This regulatory threshold forces manufacturers to absorb certification costs into hardware margins while buyers sort procurement portfolios by reliability-grade requirements.
Pricing Analysis
Industrial OEM buyers anchor a subscription-anchored pricing structure where hardware margins compress against software recurring revenue pools. Price differentiation rests on silicon carbide module certification grade and after-sales service bundling rather than base unit economics. Cost compression in mid-tier DC fast charger assemblies is intensifying because copper and rare-earth magnet volatility feeds through transformer component costs. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership modeling, while utility providers prioritize interoperability certification over unit economics.
Supply Chain Analysis
Strategic stockpiling of silicon carbide wafers and high-voltage transformers has displaced just-in-time preferences as lead time volatility reshapes procurement calendars. Manufacturing gravity centers on China for power module assembly, Germany for thermal system integration, and South Korea for high-voltage cable production. Raw material dependencies draw from copper ore concentrates, rare-earth permanent magnets, and semiconductor-grade silicon carbide substrates. Single-source vulnerability concentrates in silicon carbide foundry capacity. Distribution runs through OEM-direct channels for fleet operators and contractor networks for residential deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across California and Germany logistics corridors is shifting procurement leverage toward volume buyers capable of dictating interoperability terms and software unbundling requirements.
For Market Incumbents: Consolidate silicon carbide module supply through backward integration into wafer qualification or captive foundry partnerships. Deepen firmware development capacity in Shanghai and Stuttgart to satisfy MIIT and KBA compliance timelines. Defensive positioning requires preemptive bidirectional charging certification before utility-scale demand-response programs mature.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized component assembly corridors where localized power electronics capacity serves underpenetrated domestic electrification curves. Wireless inductive systems for automated fleet depots represent the most penetrable white-space segment. A hardware-software decoupling go-to-market angle bypasses integrated platform incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core charging divisions amid energy transition portfolio rebalancing. Long-term viability hinges on bidirectional grid-integration capabilities rather than transactional charging economics. The signal to watch is utility-scale V2G aggregation contract awards as inflection indicator for recurring revenue model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Qualification | Enables 350kW highway deployments under NEVI reliability standards. |
| Bidirectional Charging Firmware Development | Unlocks CAISO and German TSO demand-response revenue pools. |
| GB/T Protocol Localization | Mandates controller adaptation for China's MIIT interoperability mandates. |
| Fleet Software Unbundling | Separates hardware capex from energy management SaaS subscriptions. |
| Wireless Inductive Pilot Deployment | Targets Sweden and Germany heavy-duty corridor automation programs. |
Research Methodology
Desk research of customs trade databases, SEC equipment manufacturer filings, and utility interconnection queues preceded structured interviews with fleet procurement directors, power electronics R&D leads, and grid operator planning officers. Primary fieldwork with depot charging operators and highway corridor developers was cross-validated against secondary sources including EIA infrastructure deployment data, IEA electrification outlooks, and MIIT equipment certification registries. Bottom-up unit economics modeling was triangulated against top-down policy target aggregation.
Variance decomposition across charger power tier, installation type, and end-user segment shaped the analytical framework over the projection horizon. Modeled dimensions included DC fast versus home versus wireless product categories, stationary versus wall-mounted versus portable installation formats, and commercial fleet versus public infrastructure versus residential user archetypes. CAGRs were derived from segment-level volume buildups incorporating silicon carbide adoption curves and fleet electrification timelines.
Underlying assumptions cover sustained IRA and EU Green Deal subsidy trajectories, with deviation risk concentrated in transformer substation lead time volatility and F-Gas Regulation refrigerant selection constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
DC Chargers Market