
 Electric Vehicle Battery Charger Market | 2026-2036
Electric Vehicle Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Charger Market Analysis
Multi-source procurement among tier-one automakers is consolidating as charger reliability and software interoperability become critical to vehicle launch timelines. Tesla anchors North American fast-charging infrastructure through its proprietary connector ecosystem and expansive Supercharger footprint. ChargePoint competes across residential, commercial, and fleet segments with open-network architecture. Wallbox specializes in bidirectional charging hardware for European residential and light-commercial installations.
An electric vehicle battery charger converts alternating current from the grid to direct current stored in lithium-ion battery packs, with power ratings spanning 3.7 kW residential units to 350 kW ultra-fast DC systems. AC charging dominates residential and workplace installations due to lower hardware costs and minimal grid upgrade requirements, while DC fast charging captures fleet and highway corridor applications where dwell-time minimization commands premium pricing. Smart chargers with embedded cellular connectivity and dynamic load management are displacing basic Level 2 units in commercial and municipal deployments. Fleet operators represent the fastest-growing end-user segment as logistics electrification mandates from the EU, California Air Resources Board, and China's MIIT tighten compliance windows.
The EPA's vehicle emissions standards and NHTSA's fuel economy rules indirectly mandate charger density as automakers electrify lineups. EMA and EU Green Deal funding mechanisms shape product certification and interoperability requirements across European member states. China's GB/T standards and MIIT charging infrastructure targets dictate domestic hardware specifications and deployment quotas. Stakeholders must monitor regulatory divergence between CCS, NACS, and GB/T connector protocols as this fragmentation determines hardware compatibility and market access costs across major automotive markets.
Market Dynamics
Connector protocol fragmentation between CCS, NACS, and GB/T standards is forcing hardware manufacturers to maintain multiple SKUs and certification tracks, compressing margins while extending product development cycles across all major automotive markets.
Growth Catalysts
- EU Green Deal infrastructure funding:Member states must deploy charging points every 60 kilometers on major highways by 2025, mandating procurement volumes that stabilize manufacturing capacity utilization.
- Fleet electrification mandates:California Air Resources Board's Advanced Clean Trucks regulation requires increasing zero-emission vehicle sales percentages, pulling DC fast charger installations into logistics depots.
- Solid-state battery readiness:Higher charge acceptance rates of next-generation cell chemistries are validating 350 kW and 500 kW charger architectures ahead of vehicle availability.
Market Restraints
- Copper and silicon carbide cost volatility:Power electronics substrate prices fluctuate with mining output and semiconductor fab allocation, destabilizing hardware BOM forecasting.
- Transformer lead times:Grid-interconnection equipment from concentrated European and Asian suppliers extends deployment timelines for highway corridor sites.
- Permitting heterogeneity:Municipal electrical code variations across German Länder and US states create compliance friction that slows site activation.
Strategic Opportunities
- V2G aggregation revenue streams:Bidirectional chargers enable residential and fleet battery participation in frequency regulation markets where FERC Order 2222 has cleared participation pathways.
- India PLI scheme localization:Production-linked incentives for advanced chemistry cell manufacturing will create captive demand for domestically assembled charging hardware.
- Wireless inductive integration:Taxi and autonomous vehicle fleets are piloting pad-based charging to eliminate connector wear and enable opportunity charging during passenger loading.
Industry Challenges
- Embedded systems cybersecurity certification:UN ECE R155 and ISO/SAE 21434 compliance requirements demand firmware audit capabilities that stretch smaller hardware vendors.
- Grid integration engineering capacity:Utility interconnection study backlogs and specialized electrical engineering talent scarcity delay commercial site energization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Charger Market |
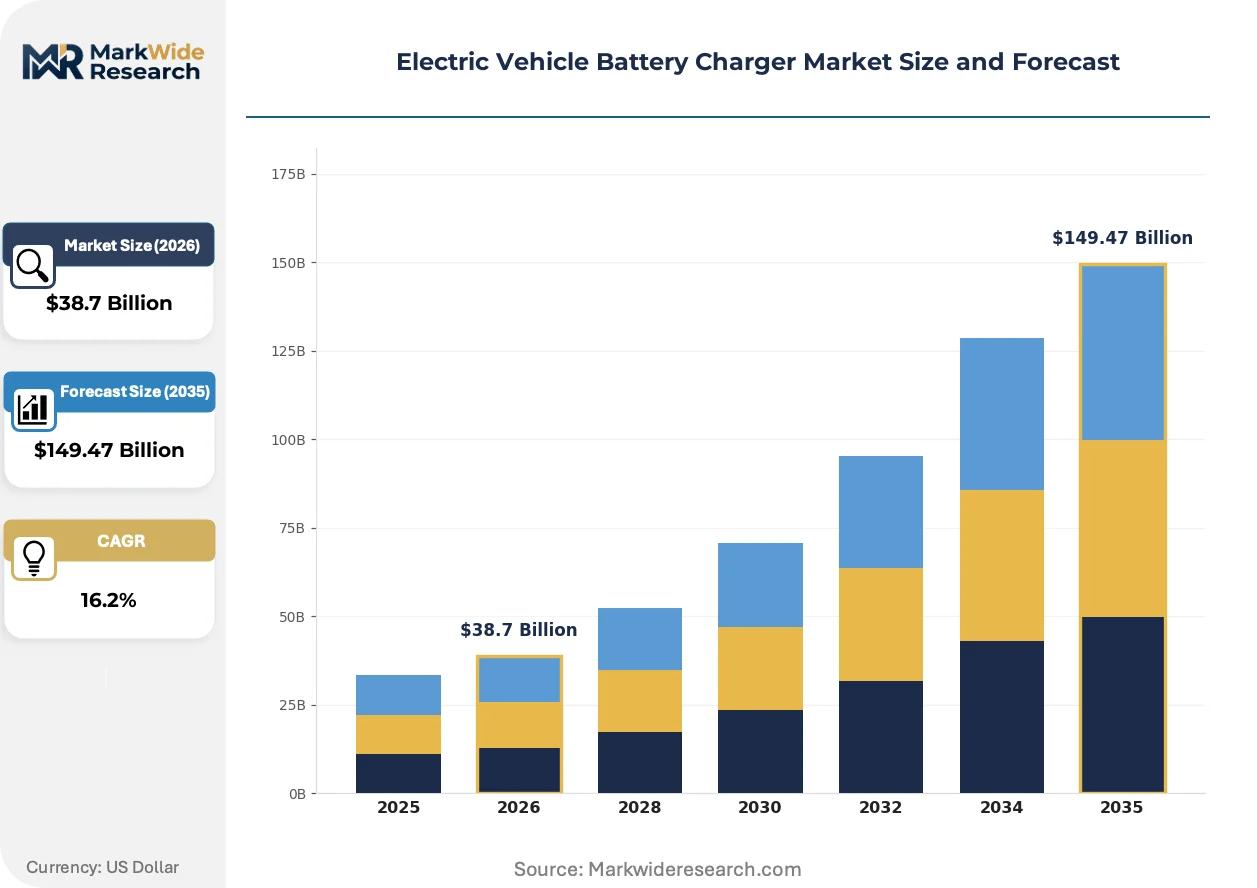
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $149.47 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Chargers, Public Chargers, Fast Chargers, Smart Chargers Charging Technology: AC Charging, DC Charging, Wireless Charging, Bidirectional Charging End User: Residential Users, Commercial Users, Fleet Operators, Municipalities Installation Type: Wall-Mounted, Portable, Embedded, Standalone |
| Companies Covered | Blink Charging, ADS-TEC Energy, Tesla, SemaConnect, Allego, ChargePoint, Wallbox, ClipperCreek, EVgo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Charger Market Emerging Trajectories
Software-defined power electronics and dynamic load orchestration are compressing the functional boundary between charger hardware and grid-edge energy management, enabling new revenue models that extend beyond electron delivery.
Modular power stack architectures with swappable 50 kW subunits are decentralizing maintenance and upgrade pathways for DC fast charging networks. Fleet operators and highway corridor developers are specifying these configurations to minimize site downtime during component replacement. The approach is compressing total cost of ownership calculations by isolating failure domains and extending asset lifecycles without full system replacement.
The EU's Alternative Fuels Infrastructure Regulation (AFIR) mandates payment interoperability and pricing transparency across all public charging points. Hardware manufacturers must now integrate contactless card readers and roaming protocol stacks that add per-unit cost while enabling seamless cross-border vehicle operation. Member states are accelerating enforcement timelines, pushing vendors to recertify existing installed bases ahead of penalty activation dates.
Property developers are bundling EV-ready electrical capacity into new construction specifications rather than retrofitting post-occupancy. Multifamily residential and workplace parking structures in Germany, the Netherlands, and California are pre-wiring for 11-22 kW AC outlets during concrete pours. This front-loaded investment pattern is shifting charger procurement earlier in building lifecycles and favoring vendors with construction-phase electrical contractor relationships over aftermarket retail channels.
Electric Vehicle Battery Charger Market Segmentation
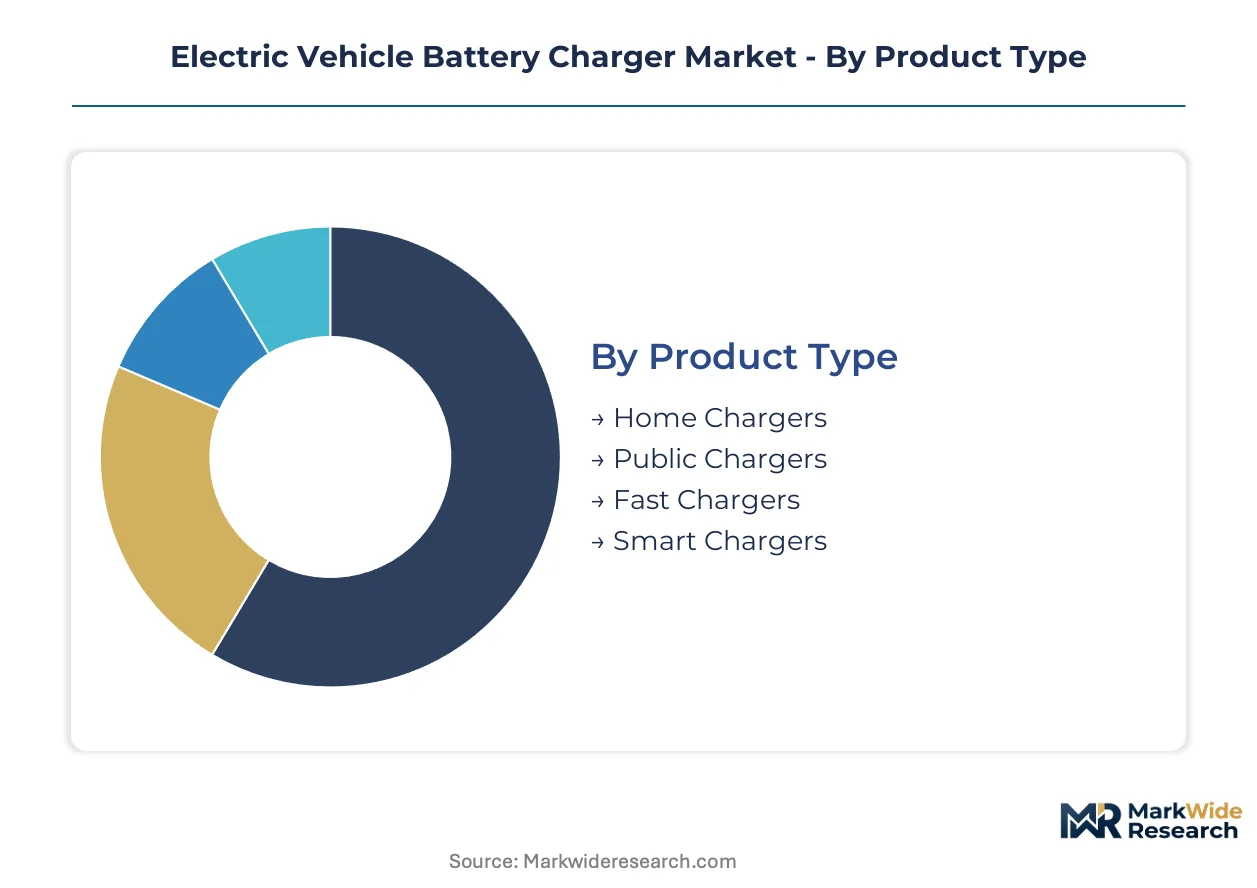
Charger segmentation determines capital allocation priorities across hardware manufacturers and infrastructure deployers. Product type and charging technology categories carry the heaviest upfront investment requirements, while end-user and installation dimensions shape recurring revenue models and site engineering complexity.
Product Type:
Capital intensity varies dramatically across product categories, with fast charging hardware requiring transformer upgrades and grid interconnection investments that dwarf residential unit economics.
- Fast Chargers:DC fast charging systems rated 50-350 kW demand dedicated medium-voltage connections and liquid-cooled cable assemblies. Fleet depots in Germany and highway corridor developers in the United States concentrate procurement volumes as dwell-time reduction commands premium hardware pricing.
- Smart Chargers:Embedded cellular modems and dynamic load management firmware enable demand response participation and software subscription revenue. Commercial workplace installations in California and the Netherlands specify these units to minimize peak demand charges and qualify for utility incentive programs.
- Home Chargers:Level 2 AC units rated 7-22 kW dominate residential garage installations with minimal electrical permitting requirements.
- Public Chargers:Curbside and retail parking hardware emphasizes payment interoperability and vandalism-resistant enclosures.
Most installed capacity flows through Home Chargers. Expansion is steepest in Fast Chargers.
Charging Technology:
Technology choice dictates power electronics architecture, with DC charging requiring active rectification and thermal management systems that multiply bill-of-materials costs against AC alternatives.
- DC Charging:Active front-end rectifiers and high-frequency DC-DC converters deliver direct current at 200-1000V to vehicle battery management systems. Highway corridor operators in China and fleet logistics providers across the EU specify 150-350 kW configurations to minimize charging downtime for commercial vehicle duty cycles.
- Bidirectional Charging:Vehicle-to-grid and vehicle-to-load capabilities require ISO 15118-20 communication stacks and grid-synchronization inverters. Residential pilots in Denmark and Japan's Kansai region validate frequency regulation revenue streams where regulatory frameworks permit battery aggregation.
- AC Charging:Onboard vehicle converters eliminate external rectification, limiting hardware to contactor assemblies and protection circuitry.
- Wireless Charging:Inductive pad systems target autonomous taxi fleets and fixed-route bus depots for opportunity charging without connector wear.
AC Charging retains the largest installed base. Bidirectional Charging is climbing the fastest as regulatory frameworks mature.
End User:
Customer type determines procurement scale and contract structure, with fleet operators consolidating purchasing power through multi-site framework agreements that reshape vendor pricing power.
- Fleet Operators:Logistics electrification mandates from California Air Resources Board and EU Green Deal compliance windows pull DC fast charger installations into depot facilities. Last-mile delivery operators and municipal bus agencies concentrate demand for 150-350 kW hardware with centralized fleet management software integration.
- Municipalities:Public procurement frameworks prioritize interoperability certification and local content requirements. German Länder and Dutch provinces specify open-network protocols to prevent vendor lock-in across publicly accessible charging infrastructure.
- Residential Users:Single-family homeowners and multifamily tenants drive Level 2 AC unit sales through retail channels and utility rebate programs.
- Commercial Users:Workplace and retail property owners install chargers as amenity infrastructure to attract tenants and customers.
Residential Users account for the highest unit volumes. Fleet Operators are gaining share fastest as electrification mandates tighten.
Installation Type:
Physical mounting configuration determines site preparation costs and relocation flexibility, with embedded systems requiring concrete pours that commit capital for building lifecycles.
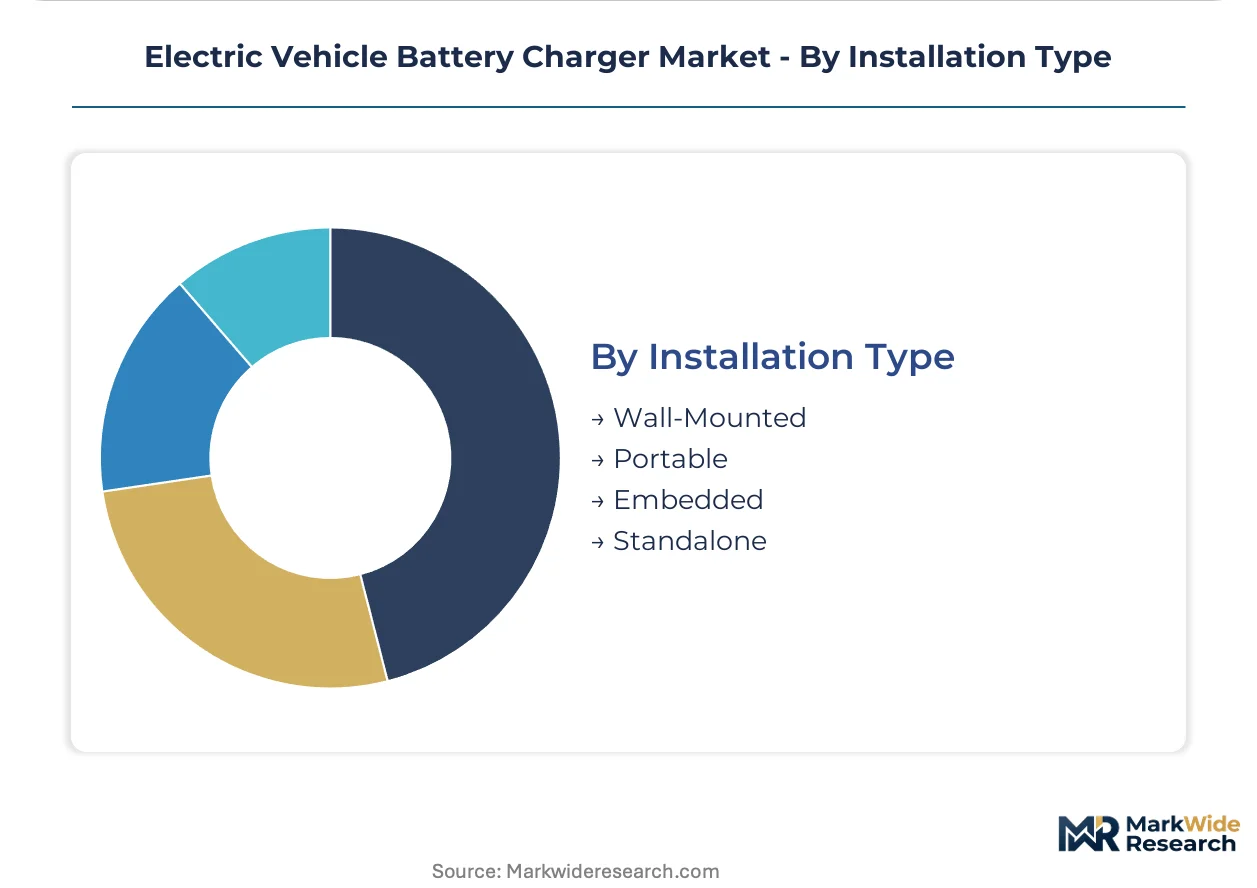
- Wall-Mounted:Bracket assemblies attach to existing structures in residential garages and commercial parking facilities. German and California building codes increasingly mandate EV-ready conduit during new construction, front-loading procurement into construction-phase electrical contractor relationships.
- Standalone:Pedestal and canopy-mounted systems enable highway corridor and retail parking deployments without building attachment. China's MIIT infrastructure targets and EU AFIR spacing mandates concentrate demand for weather-hardened enclosures with integrated payment terminals.
- Portable:Mobile units with NEMA 14-50 or industrial plug connections serve temporary and emergency charging applications.
- Embedded:Floor-integrated inductive pads and flush-mount conductive systems target autonomous vehicle and premium residential segments.
Wall-Mounted units dominate residential and workplace deployments. Standalone systems are expanding most quickly as highway corridor buildout accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors charger manufacturing capacity, with Shanghai and Suzhou hosting power electronics fabrication clusters that supply domestic deployment and export markets. Regional divergence in connector protocols and grid interconnection standards is fragmenting procurement patterns across major automotive markets.
China
MIIT infrastructure targets mandate 2 million public charging points by 2025, pulling hardware procurement into state-backed deployment quotas. GB/T standards dictate domestic connector specifications that diverge from CCS and NACS protocols. The Pearl River Delta manufacturing belt concentrates power module production for 350 kW ultra-fast systems.
Germany
The EU Green Deal's AFIR regulation requires charging points every 60 kilometers on major highways, compressing installation timelines for corridor developers. KBA type-approval processes and CE marking requirements shape product certification pathways. Bavaria's automotive engineering clusters around Munich integrate charger hardware into OEM vehicle launch programs.
United States
California Air Resources Board fleet electrification mandates drive DC fast charger procurement into logistics depots and municipal bus facilities. NHTSA fuel economy rules and EPA emissions standards indirectly mandate charging density as automakers electrify lineups. Texas and Florida corridor developers are expanding standalone highway infrastructure ahead of federal NEVI funding disbursement.
India
PLI scheme incentives for advanced chemistry cell manufacturing will create captive demand for domestically assembled charging hardware as battery production localizes. CEA grid interconnection standards and BIS certification requirements shape product specifications for public infrastructure. Gujarat and Tamil Nadu industrial corridors are attracting charger assembly investments tied to automotive OEM supply chains.
Japan
METI subsidies for V2G pilot programs validate bidirectional charging architectures in Kansai region frequency regulation markets. JIS standards and CHAdeMO protocol maintenance influence hardware specifications for domestic and Southeast Asian export markets. Chubu region power electronics manufacturers supply silicon carbide modules for next-generation high-efficiency rectifiers.
Electric Vehicle Battery Charger Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined power electronics and dynamic load management services. The vendor base stratifies across three archetypes: integrated automotive OEMs with captive charging networks, independent hardware manufacturers with open-network architectures, and software-platform operators aggregating distributed charging assets. Competitive positioning hinges on backward integration into power module production and strategic partnerships with fleet operators for multi-site deployment frameworks.
Among North American infrastructure deployers, Tesla, ChargePoint, and Blink Charging exemplify divergent strategic archetypes. Tesla anchors a closed-ecosystem model through proprietary connector dominance and vertical network operation. ChargePoint occupies the open-network position, emphasizing interoperability across residential, commercial, and fleet segments. Blink Charging represents the asset-light distributed model, prioritizing site-host partnerships over captive infrastructure ownership. Each archetype carries distinct capital intensity profiles and recurring revenue mechanics that reshape competitive dynamics as public funding programs expand deployment pools.
| Leading Market Players |
|---|
| Blink Charging |
| ADS-TEC Energy |
| Tesla |
| SemaConnect |
| Allego |
| ChargePoint |
| Wallbox |
| ClipperCreek |
| EVgo |
| Others |
Supply Flow & Price Mechanics
Fleet procurement consolidation around 150-350 kW DC fast charging specifications is compressing hardware margins as buyers negotiate multi-site framework agreements spanning Germany, California, and China's logistics corridors. Suppliers must absorb copper and silicon carbide substrate volatility while maintaining certification across CCS, NACS, and GB/T protocols, forcing selective SKU rationalization that elevates pricing for low-volume configurations.
Pricing Analysis
Input-cost pass-through from power electronics substrates dominates pricing dynamics, with silicon carbide module fluctuations feeding directly into DC fast charger bill-of-materials. Three-tier pricing structure across premium certified, standard interoperable, and economy residential levels separates UL-listed highway corridor hardware from basic Level 2 garage units. Cost compression in the mid-tier standard segment is intensifying because automakers are mandating open-network protocol compliance as a baseline procurement requirement. Fleet operators exhibit the lowest price sensitivity due to dwell-time minimization priorities, while residential buyers in multifamily housing drive sharp discounting through utility rebate aggregation.
Supply Chain Analysis
Reverse-logistics flows for power module refurbishment are emerging as Shanghai and Suzhou manufacturers recover silicon carbide MOSFETs from decommissioned 50 kW subunits to feed warranty replacement programs. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta anchoring power electronics fabrication and Bavaria hosting automotive-integrated assembly. The supply chain draws from Chilean copper cathodes, Mongolian rare earth processing, and Taiwanese semiconductor packaging. Single-source vulnerability around European transformer suppliers extends grid-interconnection timelines for highway corridor developers. Distribution runs through electrical contractor channels for construction-phase wall-mounted units and direct OEM relationships for fleet depot deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle battery charger market functions as a regulatory compounder where EU AFIR enforcement timelines and California CARB fleet mandates mechanically pull hardware procurement volumes regardless of near-term demand fluctuations.
For Market Incumbents: Extend backward integration into silicon carbide power module production to isolate margin pressure from semiconductor substrate volatility. Defend market position by pre-certifying hardware across all three connector protocols before NEVI funding disbursement accelerates US highway corridor competition. Capacity addition in India's Gujarat industrial corridor captures PLI-linked demand as domestic battery manufacturing localizes. For New Entrants and Emerging Players: The price-point gap between premium 350 kW liquid-cooled systems and economy 7 kW residential units creates entry space for mid-tier 50-150 kW modular architectures targeting municipal bus agencies and last-mile delivery depots. India's CEA certification pathway offers the most penetrable regulatory entry point among major markets. A software-overlay go-to-market angle emphasizing dynamic load management subscriptions differentiates against hardware-centric incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with software-platform operators aggregating distributed charging assets for grid services participation under FERC Order 2222 jurisdictions. Long-term viability hinges on regulatory durability across multiple electoral cycles rather than technology differentiation alone. Acquisition targets should demonstrate ISO 15118-20 bidirectional certification progress and embedded firmware audit capabilities for UN ECE R155 compliance. Monitor state-level NEVI funding disbursement velocity as an inflection indicator for US infrastructure deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Connector Protocol Certification Expansion | Multi-protocol hardware approval unlocks procurement eligibility across EU, US, and Chinese tender programs. |
| Silicon Carbide Power Module Integration | Higher-efficiency rectifiers reduce thermal management costs for 350 kW and 500 kW charger architectures. |
| Fleet Management Software Partnership | API integration with logistics operators' telematics platforms secures multi-site framework agreement renewals. |
| Construction-Phase Electrical Contractor Channel | EV-ready conduit mandates in Germany and California front-load procurement into building lifecycle early stages. |
| Vehicle-to-Grid Aggregation Platform Launch | FERC Order 2222 compliance enables frequency regulation revenue streams beyond electron delivery margins. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet procurement directors, power electronics engineers at Tier 1 suppliers, utility interconnection planners, and regulatory affairs leads at charging network operators with secondary validation against SEC filings, MIIT infrastructure deployment databases, EU AFIR implementation reports, and FERC Order 2222 compliance filings. Bottom-up unit shipment estimates by connector protocol and power rating tier triangulated against top-down infrastructure investment forecasts from national development banks.
Segment-weighting approaches distributed value projections across product type, charging technology, end user, and installation configuration dimensions, with power rating tiers and regional regulatory clusters as cross-cutting analytical layers. CAGRs were derived from logistic diffusion curves fitted to historical penetration rates and policy-mandated deployment floors. Forecast inputs incorporated solid-state battery charge acceptance specifications, transformer lead time surveys from European and Asian suppliers, and municipal permitting heterogeneity indices across German Länder and US states.
Caveats apply where copper and silicon carbide commodity volatility, grid interconnection study backlogs, or connector protocol regulatory divergence could materially shift the outlook. Practitioners should monitor state-level NEVI funding disbursement schedules, EU AFIR penalty activation timelines, and solid-state battery commercialization progress for early signals of deployment acceleration or delay.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charging System Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Electric Car Charging Pile Market