
 Solar Charging Station Market | 2026-2036
Solar Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Charging Station Market Analytics
Buyer fragmentation across municipal governments, corporate fleet operators, and retail property owners is expanding the addressable customer base beyond traditional utility customers. SunPower Corporation leverages its photovoltaic module efficiency leadership to anchor premium positioning in commercial installations. Envision Solar competes through patented tracking technology that maximizes energy yield per unit area. Giulio Barbieri SRL specializes in European-designed structural systems for urban streetscape integration.
A solar charging station combines photovoltaic energy conversion with power electronics and energy storage to deliver DC or AC charging capacity for electric vehicles and portable electronics, typically incorporating 5–50 kW solar arrays with bidirectional inverters and battery buffers for dispatchability. Monocrystalline Panels dominate product configurations where space constraints demand maximum wattage per square meter, while Thin-Film Technology occupies niche applications requiring flexible form factors or reduced weight loads on existing structures. Ground-Mounted installations sustain the largest project scale in dedicated parking facilities, though Wall-Mounted systems are gaining traction in dense urban environments where land availability constrains deployment.
The US Federal Energy Regulatory Commission and state-level public utility commissions shape interconnection standards and net metering rules that determine project economics, while the EU Green Deal's transport decarbonization targets mandate charging infrastructure density minimums that solar-integrated systems can satisfy in grid-constrained locations. California's building code requirements for solar readiness in new commercial construction create regulatory pull for pre-wired charging infrastructure. Stakeholders must monitor evolving inverter efficiency standards and battery safety certifications as jurisdictions tighten performance and fire-code requirements for energy-storage-coupled installations.
Market Dynamics
The US Inflation Reduction Act's clean vehicle tax credits are compressing deployment timelines for solar-integrated EV charging, forcing infrastructure developers to resequence capital allocation toward distributed generation assets.
Growth Catalysts
- California's Building Code Mandates:New commercial construction requirements for solar readiness are pulling pre-wired charging infrastructure into standard development timelines.
- Monocrystalline Panel Efficiency Gains:Wattage density improvements are expanding viable deployment footprints in space-constrained urban parking structures.
- Municipal Fleet Electrification:North American city procurement programs are expanding the addressable customer base beyond traditional utility customers.
Market Restraints
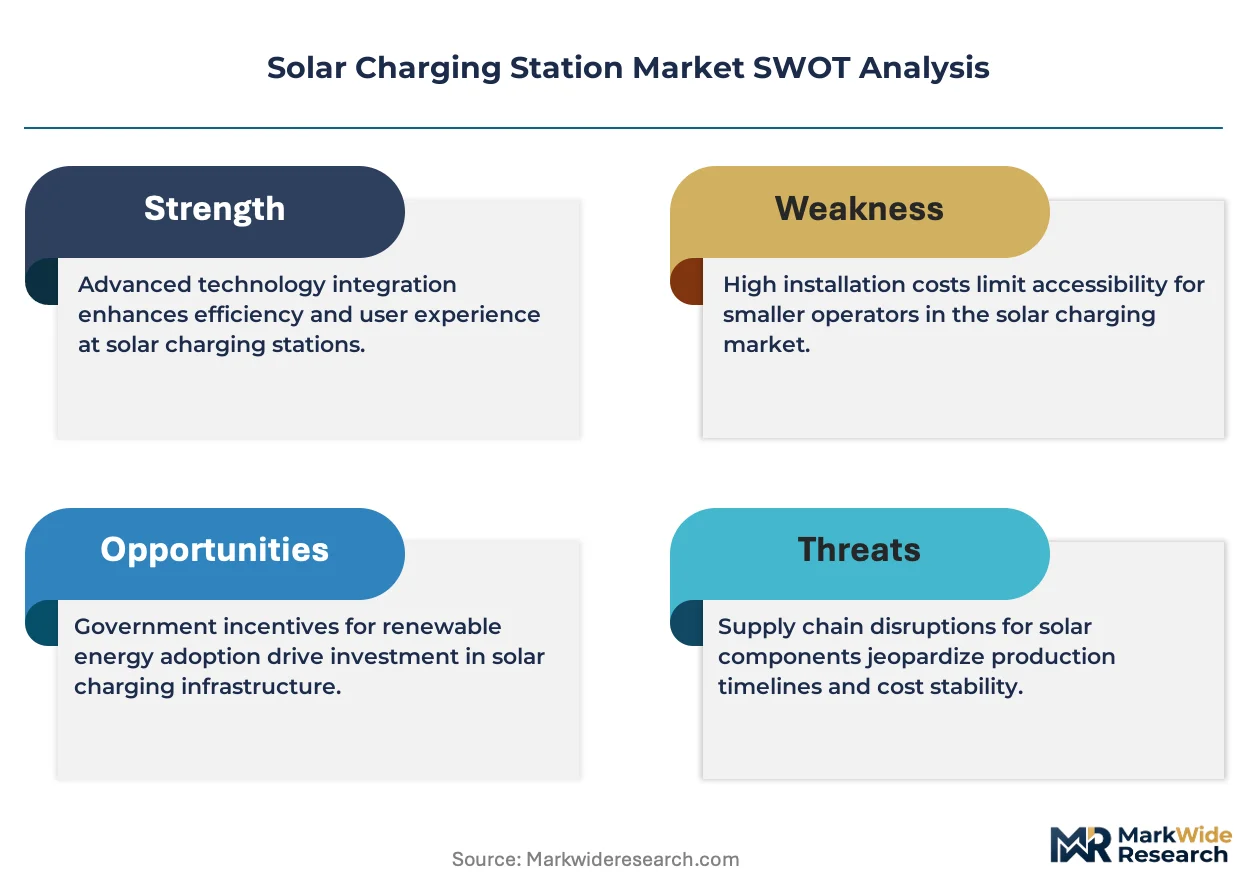
- Battery Input Cost Volatility:Lithium-ion cell pricing fluctuations are compressing project margins for storage-coupled installations.
- Interconnection Queue Delays:State-level public utility commission backlogs are extending commissioning timelines for grid-tied systems.
- Thin-Film Technology Substitution Pressure:Cadmium-telluride alternatives are capturing niche applications where weight constraints dominate site selection.
Strategic Opportunities
- EU Green Deal Transport Mandates:Charging infrastructure density minimums are creating deployment pull in grid-constrained European locations.
- Bidirectional Inverter Convergence:Vehicle-to-grid capability integration is opening revenue stacking models for fleet operators.
- Retail Property Channel Expansion:Big-box parking lot deployments are emerging as a direct sales pathway bypassing utility intermediaries.
Industry Challenges
- Certification Timeline Compression:Evolving battery safety certifications under tightened fire codes are extending pre-construction approval cycles.
- Electrical Integration Skill Scarcity:Shortages of technicians qualified in both photovoltaic and EVSE installation are constraining deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Charging Station Market |
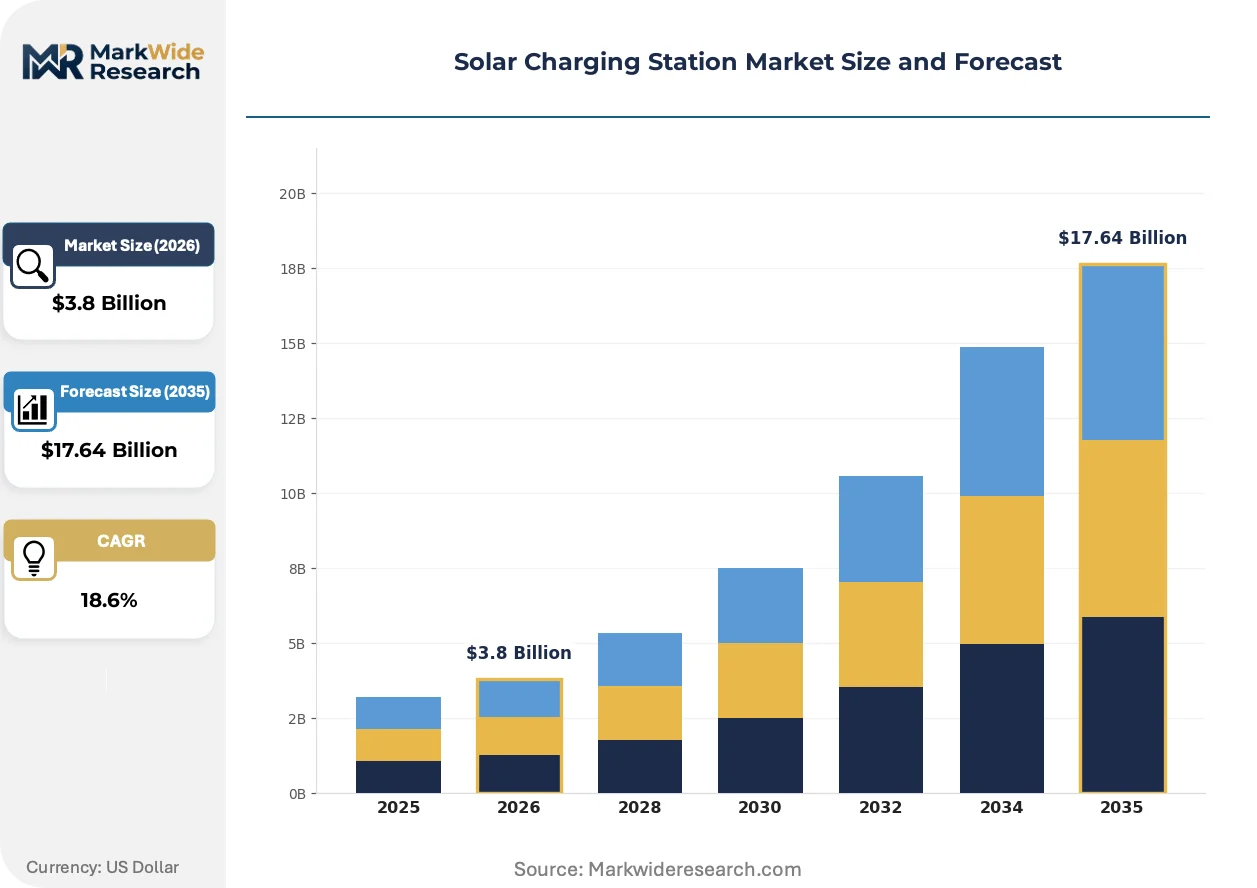
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Solar Charging Hubs, Built-In Solar Panels, Stationary Chargers End User: Residential Users, Commercial Entities, Electric Vehicle Owners, Government Facilities Technology: Monocrystalline Panels, Polycrystalline Panels, Thin-Film Technology, Hybrid Systems Installation Type: Ground-Mounted, Roof-Mounted, Wall-Mounted, Mobile Units |
| Companies Covered | MDT Sun Protection System AG, Inhabit Solar, SunPower Corporation, Sundial Solar Solutions, Giulio Barbieri SRL, Solarstone, Solarsense UK Limited, Envision Solar, PROINSO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Charging Station Market Evolving Landscape
Power electronics architecture is fragmenting into discrete, interchangeable subsystems that reduce site-specific engineering requirements and accelerate deployment velocity across heterogeneous installation environments.
Battery buffer systems are modularizing around standardized 50-100 kWh building blocks that fleet operators can scale incrementally as vehicle counts expand. Transit agencies in California's urban corridor are deploying these configurable units to match charging capacity to route electrification timelines. This modularizing architecture is compressing the traditional custom-engineering phase that previously dominated project development cycles.
The EU Green Deal's transport decarbonization targets are mandating minimum charging infrastructure density that solar-integrated systems can satisfy without grid reinforcement. Member states are interpreting these mandates through national building codes that privilege distributed generation in permitting queues. Commercial parking operators in Germany and France are responding by pre-approving solar canopy designs that streamline subsequent tenant EVSE installations.
Fleet procurement is consolidating around performance-based contracting where operators pay per delivered kWh rather than capitalizing hardware directly. This shift is displacing traditional equipment ownership models among municipal and corporate buyers. California's municipal fleet programs are exhibiting the most advanced adoption of this service-based procurement structure.
Solar Charging Station Market Segmentation
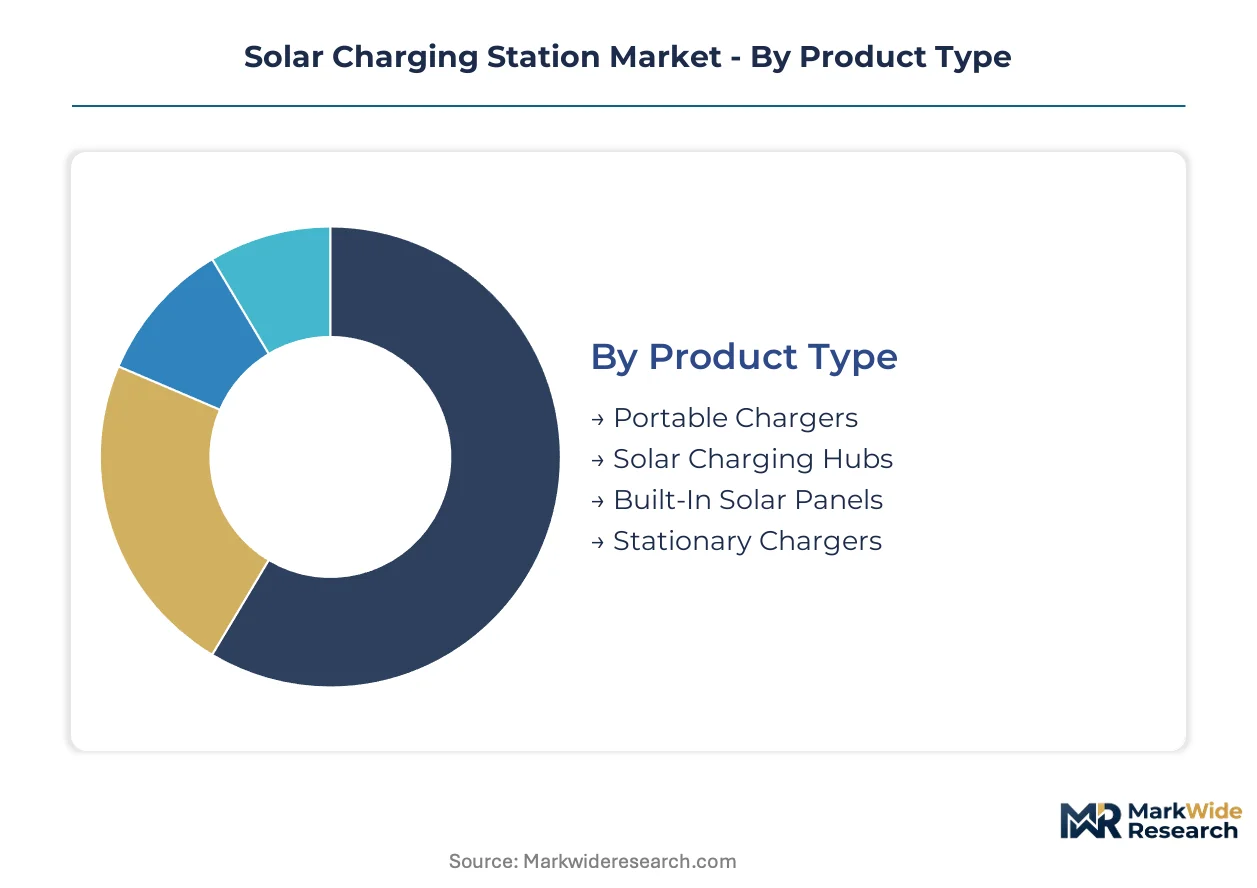
Segmentation in solar charging infrastructure reveals divergent engineering requirements across mobility, permanence, and power density. Product architecture and installation constraints dictate distinct supply chain configurations and margin structures for each category.
Product Type:
Volume concentrates in stationary hardware while premium margins attach to portable systems with integrated storage.
- Portable Chargers:Compact units integrating foldable photovoltaic arrays with lithium-ion buffers and DC output ports for consumer electronics and light mobility devices. Demand clusters with outdoor recreation retailers and emergency preparedness distributors in California's urban corridor, where utility rate volatility drives interest in off-grid alternatives.
- Solar Charging Hubs:Modular canopy structures combining 10-50 kW solar arrays with multiple EVSE ports and battery buffering for shared charging environments. Municipal fleet electrification programs across North American cities are standardizing procurement specifications around these configurable platforms.
- Built-In Solar Panels:Photovoltaic surfaces integrated directly into vehicle bodywork or structural building elements, capturing energy without dedicated installation footprint. Architectural glass manufacturers and automotive OEMs dominate development partnerships.
- Stationary Chargers:Fixed infrastructure with permanent foundation anchoring and grid-interconnection capabilities, typically deployed at 50+ kW scale for commercial parking facilities. Big-box retail property owners favor these for tenant amenity differentiation and sustainability credentialing.
Today's leader: Stationary Chargers. Tomorrow's challenger: Solar Charging Hubs.
End User:
Procurement authority fragments across public sector standard-setters and private fleet operators with divergent capital constraints.
- Residential Users:Individual homeowners purchasing 5-15 kW garage-mounted or carport-integrated systems, often bundled with rooftop solar installations. California's building code mandates for solar-ready new construction are pulling pre-wired charging infrastructure into standard residential development timelines.
- Commercial Entities:Corporate campuses, retail properties, and multi-tenant buildings deploying 50-200 kW shared charging infrastructure for employee and customer use. Performance-based contracting is displacing direct equipment ownership among Fortune 500 sustainability programs.
- Electric Vehicle Owners:Individual drivers seeking supplemental charging capacity for road trips, emergency reserves, or off-grid destinations. This segment exhibits highest price sensitivity and shortest replacement cycles.
- Government Facilities:Federal, state, and municipal installations subject to procurement regulations favoring domestic content and prevailing wage requirements. The US Inflation Reduction Act's clean vehicle tax credits are compressing deployment timelines for solar-integrated EV charging across federal vehicle fleets.
Commercial Entities currently anchor procurement volume. Government Facilities are climbing the fastest as IRA funding mechanisms mature.
Technology:
Efficiency premiums concentrate in monocrystalline architectures while thin-film alternatives exploit weight and flexibility advantages.
- Monocrystalline Panels:Single-crystal silicon cells delivering 20-22% conversion efficiency in standardized rectangular formats. Space-constrained urban parking structures in California's urban corridor specify these exclusively to maximize wattage per canopy square meter.
- Polycrystalline Panels:Multi-crystal silicon construction at 15-17% efficiency with lower manufacturing cost per watt. Utility-scale ground-mounted installations with land abundance tolerate the efficiency trade-off for capital savings.
- Thin-Film Technology:Cadmium-telluride or copper-indium-gallium-selenide deposition on flexible substrates, achieving 10-12% efficiency at radically reduced weight. Retrofit applications on existing structures with load-bearing constraints favor this technology despite higher per-watt pricing.
- Hybrid Systems:Combinations of photovoltaic generation with wind micro-turbines, fuel cells, or grid-interactive storage for dispatchability in remote locations. Mining operations and rural transit depots deploy these where grid reinforcement is economically prohibitive.
Monocrystalline Panels command technology leadership. Thin-Film Technology represents the steepest expansion trajectory as building-integrated applications proliferate.
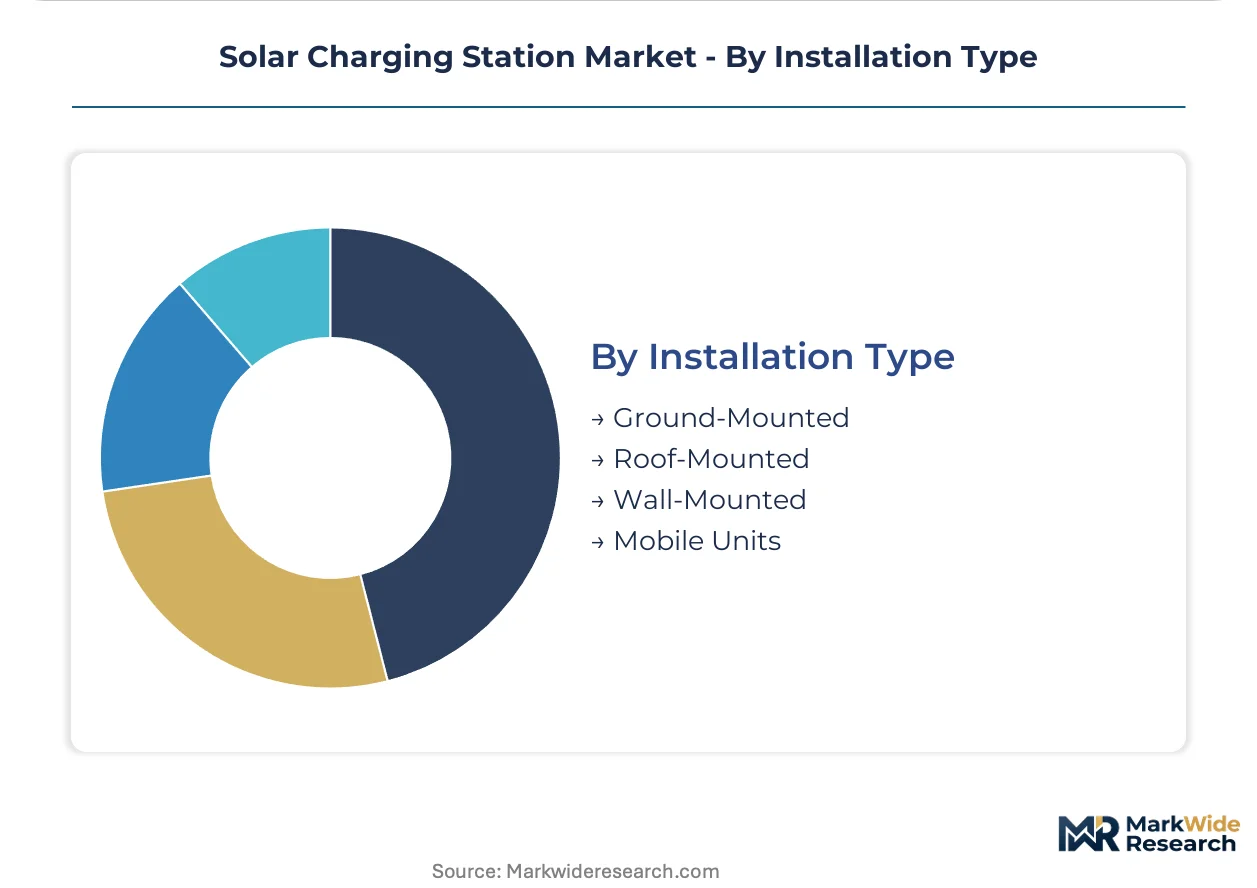
Installation Type:
Permanent foundations sustain largest project scale while mobile architectures enable rapid redeployment across transient demand.
- Ground-Mounted:Steel or concrete foundation systems supporting 100+ kW arrays in dedicated parking fields or brownfield remediation sites. These sustain the largest project scale in dedicated commercial and industrial facilities with land availability.
- Roof-Mounted:Ballasted or penetrating attachment to existing building structures, leveraging otherwise unproductive surface area. Structural engineering review requirements extend pre-construction timelines significantly.
- Wall-Mounted:Vertical surface attachment for 5-20 kW systems in dense urban environments where land availability constrains deployment. German and French commercial parking operators are pre-approving these designs to streamline tenant EVSE installations.
- Mobile Units:Trailer-mounted or skid-based configurations with integrated inverters and battery buffers for temporary events, construction sites, or disaster response. Transit agencies deploy these for route electrification pilot programs before committing to permanent infrastructure.
Ground-Mounted installations dominate project value. Wall-Mounted systems are gaining share fastest in metropolitan infill locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's solar charging infrastructure deployment outpaces France in absolute installations, yet California's municipal procurement volumes exceed both European markets combined. This geographic asymmetry reflects divergent regulatory architectures and fleet electrification timelines.
United States
Municipal fleet electrification programs in Los Angeles, San Diego, and Seattle are expanding procurement of off-grid charging infrastructure. The US Inflation Reduction Act's clean vehicle tax credits compress deployment timelines for solar-integrated EV charging. California's urban corridor concentrates demand where utility rate structures favor distributed generation paired with transportation electrification.
Germany
Commercial parking operators in Berlin, Munich, and Hamburg are pre-approving solar canopy designs that streamline tenant EVSE installations. The EU Green Deal's transport decarbonization targets mandate charging infrastructure density minimums that solar-integrated systems satisfy in grid-constrained locations. Baden-Württemberg's automotive supplier corridor is piloting fleet charging hubs for inbound logistics electrification.
France
Transit agencies in the Île-de-France region deploy modular battery buffer systems to match charging capacity to route electrification timelines. National building codes privilege distributed generation in permitting queues under EU Green Deal interpretation. Lyon and Marseille commercial zones are standardizing wall-mounted pre-approval designs for metropolitan infill.
United Kingdom
Corporate campus sustainability programs in London and the Southeast are shifting toward performance-based contracting for shared charging infrastructure. Ofgem's evolving interconnection standards shape net metering rules that determine project economics. The Midlands logistics corridor is emerging as a deployment cluster for distribution center fleet electrification.
Italy
Architectural glass manufacturers in Lombardy and Veneto are developing building-integrated photovoltaic surfaces for charging infrastructure without dedicated installation footprint. National recovery fund allocations prioritize transport decarbonization in urban regeneration zones. Milan's commercial property market is pulling pre-wired charging infrastructure into standard development timelines.
Solar Charging Station Market Competitive Landscape
US producers anchor one tier; European specialists hold differentiated positioning through design heritage and structural engineering capabilities. The vendor base concentrates around photovoltaic module manufacturers extending into charging integration, dedicated solar canopy fabricators, and power electronics suppliers. Three archetypes dominate: efficiency-led module integrators, tracking technology specialists, and urban streetscape designers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms resequence capital allocation toward distributed generation assets.
Within the efficiency-led tier, SunPower Corporation represents premium positioning in commercial installations. Envision Solar occupies a position among tracking technology specialists. Giulio Barbieri SRL exemplifies European-designed structural systems for urban streetscape integration. These three anchors illustrate the geographic and technological segmentation shaping procurement decisions across municipal, corporate, and retail property customer segments.
| Leading Market Players |
|---|
| MDT Sun Protection System AG |
| Inhabit Solar |
| SunPower Corporation |
| Sundial Solar Solutions |
| Giulio Barbieri SRL |
| Solarstone |
| Solarsense UK Limited |
| Envision Solar |
| PROINSO |
| Others |
Value Network & Pricing Analysis
Municipal fleet electrification programs across North American cities are demanding standardized canopy specifications with integrated battery buffering, forcing module suppliers and structural fabricators to coordinate pre-engineered subassemblies that compress installation timelines but compress margins through volume commitments.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for monocrystalline photovoltaic modules, driving project-based pricing stratification across premium efficiency tiers and standard commodity configurations. Price differentiation hinges on UL certification tier and volume scale, with California's municipal procurement exhibiting lowest price sensitivity due to IRA tax credit absorption, while independent retail property owners in secondary US markets face acute cost compression from interconnection queue delays and soft construction lending.
Supply Chain Analysis
The US Inflation Reduction Act's domestic content bonus credits are reshaping sourcing patterns, compelling developers to substitute Southeast Asian cell assembly for Chinese wafer supply despite cost premiums. Module production concentrates in China, Vietnam, and Malaysia; lithium-ion cells flow from South Korea and Japan; steel canopy structures source from domestic US fabrication to satisfy prevailing wage requirements. Single-source vulnerability in polysilicon refining creates tariff exposure risk. Distribution runs through engineering-procurement-construction contractors with utility-scale project experience.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where procurement is shifting toward performance-based contracting with guaranteed uptime specifications, rewarding suppliers with proven dispatchability and fire-code certification depth.
For Market Incumbents: Acquire battery buffer system engineering capabilities to defend against modular platform entrants displacing custom-engineered installations. Secure UL 9540A certification for thermal runaway propagation ahead of California's tightened fire-code enforcement. Anchor municipal fleet relationships through 10-year service contracts that lock out challenger pricing. For New Entrants and Emerging Players: Launch via retail property channel partnerships bypassing utility intermediaries, targeting big-box parking operators in Texas and Florida where IRA incentives remain underutilized. Exploit thin-film technology substitution pressure in rooftop retrofit applications where structural load constraints dominate site selection. White-space concentrates in wall-mounted metropolitan infill across German and French commercial zones. For Investors and Strategic Acquirers: Asymmetric upside sits with tracking technology specialists possessing patented solar yield optimization and vehicle-to-grid software integration. Five-to-ten year viability favors asset-light platform operators over capital-intensive module manufacturers. Watch California Public Utilities Commission net metering rulemaking as the critical inflection signal for distributed generation project economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Buffer Modularization | Standardized 50-100 kWh building blocks enable fleet operators to scale capacity incrementally alongside vehicle deployment. |
| Domestic Content Compliance | IRA bonus credit qualification requires steel fabrication and module assembly to satisfy prevailing wage and origin thresholds. |
| Vehicle-to-Grid Integration | Bidirectional inverter convergence opens revenue stacking models for California transit agencies and municipal fleet operators. |
| Performance-Based Contracting | Per-delivered-kWh structures displace equipment ownership among Fortune 500 sustainability programs and federal procurement. |
| Fire-Code Certification Acceleration | UL 9540A thermal runaway testing compresses pre-construction approval cycles in jurisdictions with tightened energy storage regulations. |
Research Methodology
Bottom-up municipal fleet deployment modeling reconciled against top-down photovoltaic module shipment tracking forms the analytical core of this study. Primary interviews with utility planning officers, EPC contractors, fleet electrification managers, and solar canopy fabricators were validated against secondary sources including FERC interconnection filings, EIA generation data, California Energy Commission building standards documentation, and EU Green Deal transport mandate implementation reports.
Historical trendline analysis of installation cost trajectories and capacity factor improvements informed the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, end-user procurement authority, cell efficiency tier, and installation permanence. CAGRs were derived from logistic diffusion curves fitted to early-adopter municipal deployment patterns and late-major retail property adoption, with inputs from lithium-ion cell pricing volatility indices and interconnection queue duration estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under battery input cost spikes and permitting timeline extensions. Assumptions reflect current IRA credit mechanics and EU Green Deal mandate interpretation by member state regulators. Ongoing watch attaches to FERC interconnection standard revisions and California fire-code enforcement timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
North America Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Electric Car Charging Pile Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
EV Charging Software Market