
 Electric Clothes Drying Hanger Market | 2026-2036
Electric Clothes Drying Hanger Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Clothes Drying Hanger Market Foresight
Heated-air circulation technology is fragmenting across multiple thermal architectures, forcing manufacturers to choose between PTC ceramic, infrared panel, or hybrid convection systems. Minky leverages its British heritage and retail channel depth to sustain premium positioning in European homeware. Leifheit anchors German engineering credibility through rigorous testing protocols and extended warranty programs. Foxydry competes on Italian design aesthetics and compact wall-mounted configurations for Mediterranean balconies.
An electric clothes drying hanger integrates electrically powered heating elements with forced or passive airflow to accelerate moisture evaporation from garments, typically operating at power ratings between 100 W and 400 W with load capacities from 5 kg to above 20 kg. The device serves residential and light commercial users seeking garment drying without dedicated floor space for tumble dryers. Foldable and wall-mounted variants capture the fastest-growing demand pools as urbanization squeezes living spaces across metropolitan zones. Stainless steel construction dominates material selection for durability and heat tolerance, while aluminum segments gain traction where weight reduction enables ceiling-suspension installations.
China's GB 4706 standards and the EU's Ecodesign Directive constrain permissible standby power and mandate efficiency disclosures, compelling redesigns of control circuits and heating modules. The US EPA ENERGY STAR program and DOE appliance standards shape North American market access thresholds. Japan's METI Top Runner program accelerates efficiency benchmarks for imported electric drying equipment. Stakeholders must monitor evolving energy-labeling regimes and building-code amendments that redefine permissible installation locations before committing to regional product lineups.
Market Dynamics
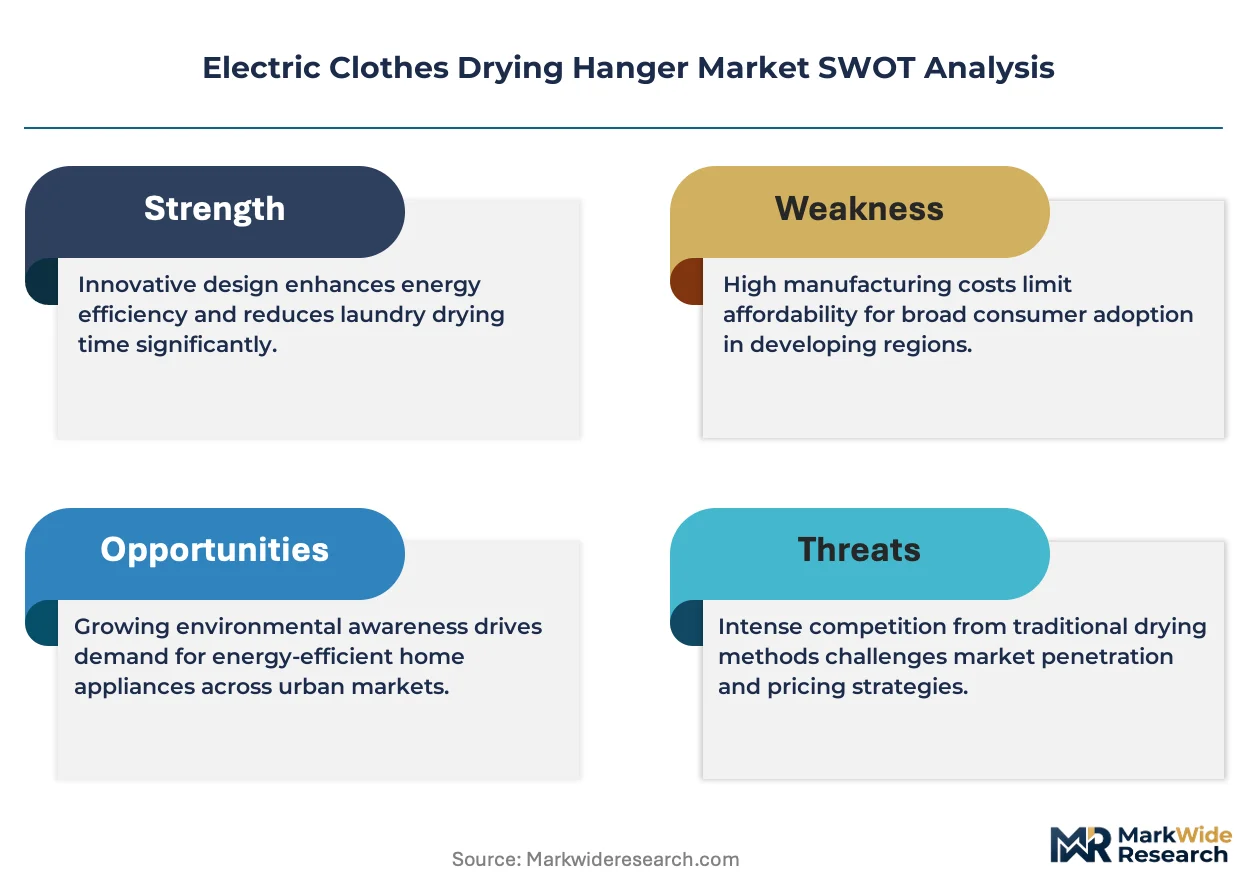
GB 4706 energy-efficiency mandates in China and the EU's Ecodesign Directive are forcing simultaneous redesigns of heating modules and control circuits, compressing product development cycles while fragmenting thermal architectures across PTC ceramic, infrared panel, and hybrid convection systems.
Growth Catalysts
- Urban Space Constraints:Dense apartment configurations in Shanghai, Tokyo, and Seoul sustain replacement demand for wall-mounted and foldable variants that eliminate floor-space requirements.
- GB Standards Compliance:China's household appliance energy-efficiency framework compels manufacturers to optimize standby power consumption, accelerating innovation in low-wattage heating elements.
- Humidity-Driven Clusters:Coastal Chinese tier-one cities with elevated moisture levels generate sustained usage intensity that shortens product lifecycles and drives repeat purchases.
Market Restraints
- Copper and Aluminum Volatility:Heating element and frame construction depends on non-ferrous metal inputs subject to commodity price swings that compress margin predictability.
- Regional Supply Concentration:Control circuit and PTC ceramic module production clusters in Guangdong province create single-source vulnerability for brands outside China's manufacturing ecosystem.
- Heat Pump Substitution:Integrated laundry appliances with heat pump drying cycles capture floor-space-sensitive consumers seeking multi-function solutions.
Strategic Opportunities
- India's Metro Expansion:Mumbai, Bangalore, and Delhi apartment construction is outpacing tumble dryer penetration, creating first-mover positioning for compact electric drying hardware.
- Smart Home Convergence:Integration of humidity sensors and app-based scheduling with existing IoT ecosystems enables premium pricing through connected functionality.
- Japan's METI Top Runner:Accelerating efficiency benchmarks for imported equipment reward early compliance with preferential market access and labeling advantages.
Industry Challenges
- Cross-Border Certification Timelines:Simultaneous navigation of China's GB 4706, EU CE marking, and US UL standards extends product launch windows and fragments engineering resources.
- Heating Element IP Licensing:Proprietary PTC ceramic formulations and infrared panel patents create royalty burdens or exclusion risks for non-vertically integrated manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Clothes Drying Hanger Market |
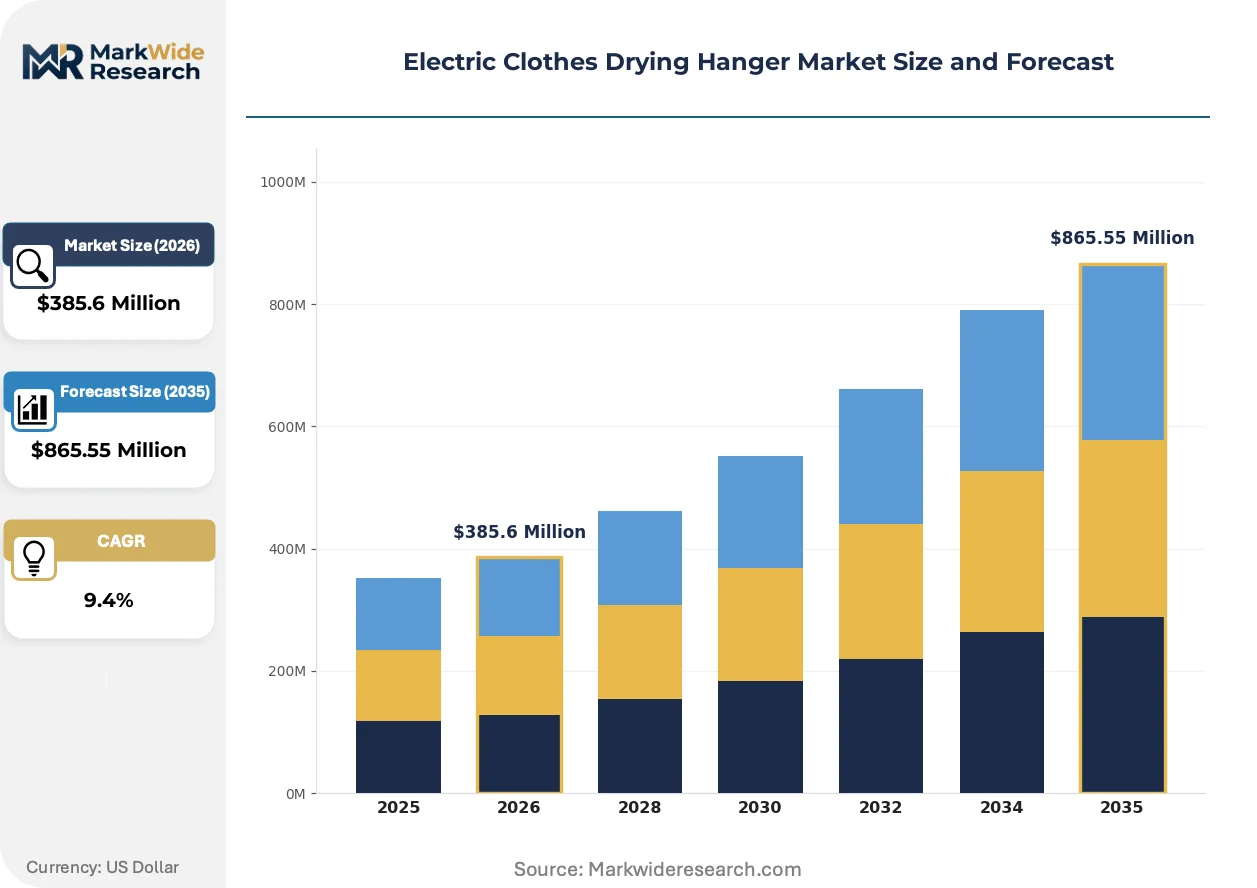
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Foldable, Portable, Ceiling-Mounted Material: Stainless Steel, Plastic, Aluminum, Wood Capacity: 5-10 kg, 10-15 kg, 15-20 kg, Above 20 kg Power Rating: 100-200 W, 200-300 W, 300-400 W, Above 400 W |
| Companies Covered | Minky, JLA, Leifheit, Brabantia, Dry:Soon, Foxydry, Tangkula, Honey-Can-Do, LBest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Clothes Drying Hanger Market Shifts & Advancements
Forced-air thermal management is virtualizing across multiple hardware configurations, while regulatory pressure on standby power and efficiency disclosures compresses design iteration cycles and fragments competitive positioning.
Ultraviolet-C LED integration is virtualizing surface sterilization functionality into electric drying hardware, extending value propositions beyond moisture removal. Health-conscious apartment dwellers in East Asian megacities are adopting these hybrid units at accelerated replacement cycles. The convergence is virtualizing traditional garment care boundaries and enabling premium tier pricing that separates UV-enabled configurations from baseline heating-only models.
The EU's Ecodesign Directive constrains permissible standby power and mandates granular efficiency disclosures, compelling manufacturers to redesign control circuits and heating modules for compliance. Industrial consequence includes accelerated obsolescence of legacy analog thermostat systems and forced migration to digital PWM controls. Wall-mounted and foldable variants targeting European retail channels are responding with modular heating architectures that permit field serviceability and component-level upgrades.
Rental housing procurement is consolidating purchasing authority into property management platforms and co-living operators, displacing individual consumer decision-making for in-unit appliance selection. Direct B2B contracting with institutional landlords is replacing traditional retail distribution in Berlin, Amsterdam, and Copenhagen residential developments. This channel rotation is most visible in Northern European markets where build-to-rent construction dominates new housing supply and standardizes appliance specifications across multi-unit portfolios.
Electric Clothes Drying Hanger Market Segmentation
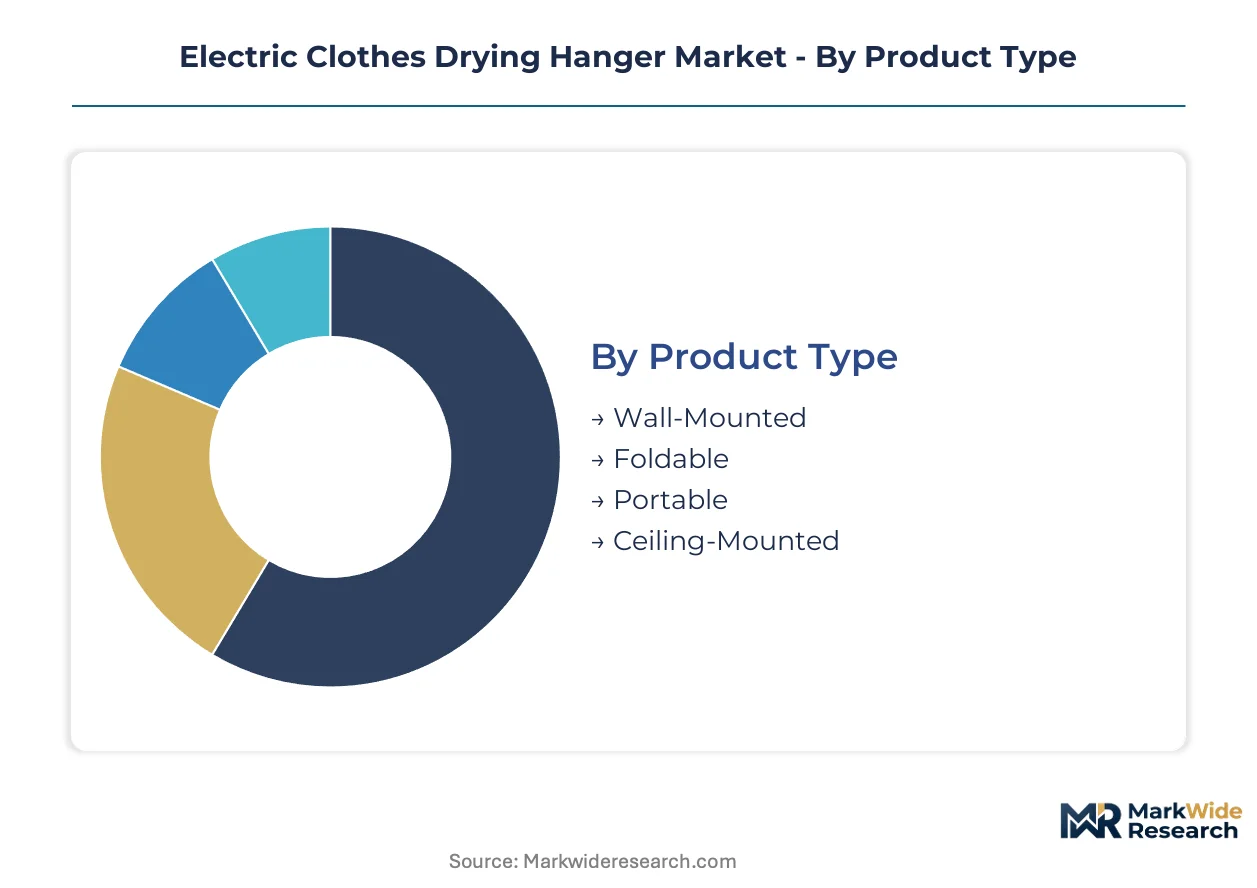
Electric clothes drying hanger configurations fragment across mounting topology, material selection, load capacity, and thermal output. Manufacturers must align product architectures with specific installation constraints and usage intensity patterns in dense urban housing.
Product Type:
The use-case spectrum spans permanent installation through fully mobile deployment, with each topology commanding distinct channel economics and replacement cycles.
- Wall-Mounted:Fixed bracket systems with integrated heating elements dominate Mediterranean balcony installations and Japanese compact apartments. Demand concentrates in Barcelona, Rome, and Osaka where outdoor drying space is restricted by building codes yet humidity necessitates active drying.
- Foldable:Collapsible frames with detachable power units capture Shanghai and Seoul apartment dwellers prioritizing storage minimalism. These configurations are closing the gap fastest as co-living operators standardize on stowable hardware across multi-unit portfolios.
- Portable:Freestanding lightweight units with wheeled bases serve temporary housing and seasonal users in German student dormitories.
- Ceiling-Mounted:Pulley-suspended heated rails prevail in Indian metro construction where vertical space utilization trumps floor footprint concerns.
The dominant share belongs to Wall-Mounted configurations, while Foldable variants are expanding most quickly through B2B rental housing procurement channels.
Material:
Cost tier stratification separates premium durability specifications from weight-optimized economy offerings.
- Stainless Steel:304 and 316-grade constructions withstand sustained thermal cycling in high-humidity coastal Chinese cities. Guangdong and Zhejiang manufacturing clusters source bar stock from local melt shops to contain input volatility.
- Aluminum:Extruded alloy profiles enable ceiling-suspension installations where structural load limits constrain hardware mass. These alloys are gaining share fastest in Indian and Southeast Asian new-build apartments.
- Plastic:Glass-filled polymer housings for control enclosures and non-structural components reduce unit cost in entry-tier SKUs.
- Wood:Laminated bamboo and hardwood accents serve Scandinavian design-conscious segments prioritizing aesthetic integration with interior finishes.
Stainless Steel retains the dominant share in revenue terms, though Aluminum is climbing the fastest as weight reduction becomes a specification priority.
Capacity:
Volume segmentation tracks household size and garment mix intensity across single-person studios through multi-generational units.
- 5-10 kg:Compact single-bar configurations serve Tokyo and Hong Kong micro-apartments where daily wash volumes are constrained by space and water access.
- 10-15 kg:Dual-rail heated systems with forced-air circulation capture European nuclear family demand in Paris and Milan residential stock.
- 15-20 kg:Multi-tier foldable arrays address Indian joint-family households in Mumbai and Delhi with centralized laundry processing.
- Above 20 kg:Heavy-duty commercial-grade units serve light commercial applications including boutique hotels and fitness center towel services.
The 10-15 kg segment holds the dominant share, while 5-10 kg configurations are gaining share fastest as studio and one-bedroom construction accelerates.
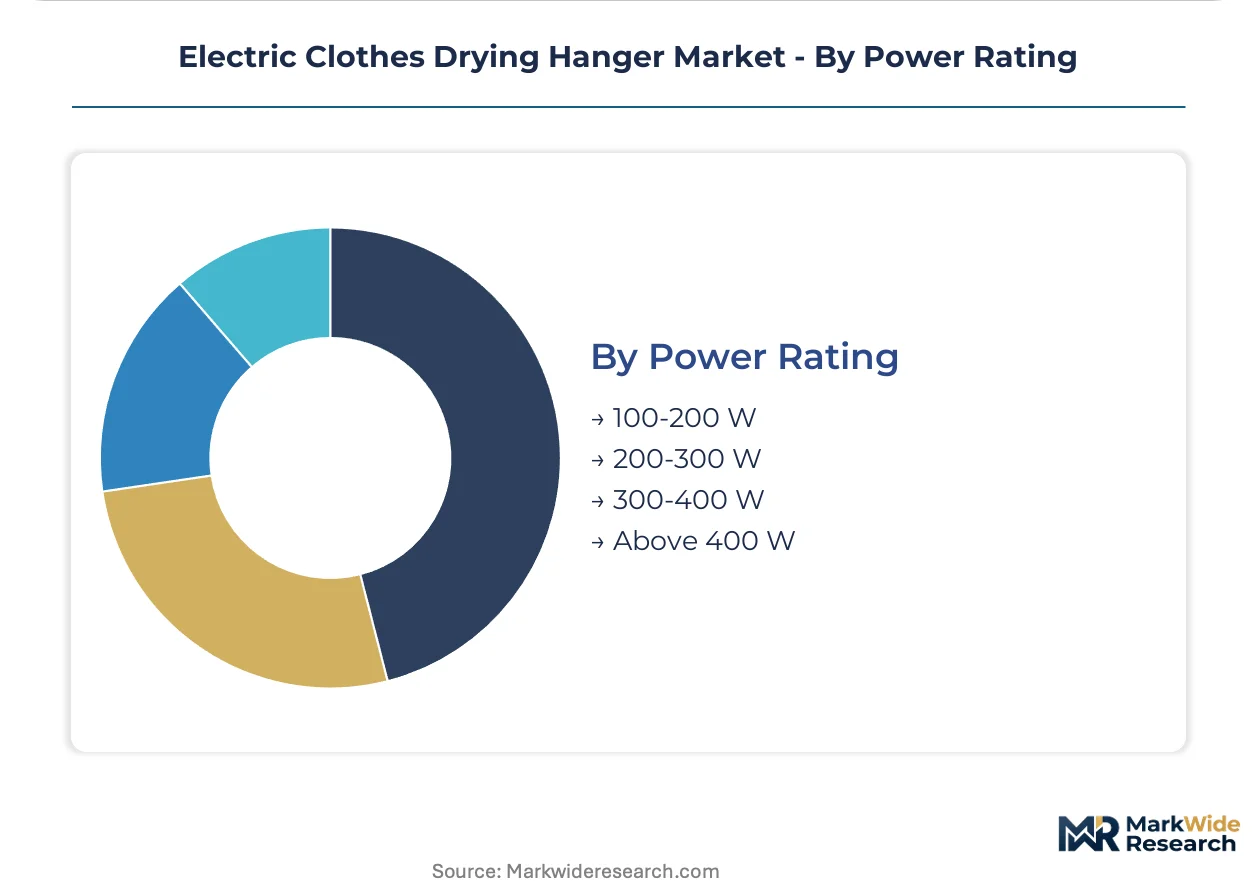
Power Rating:
Margin concentration aligns with thermal architecture sophistication and regulatory compliance burden.
- 100-200 W:Passive convection and low-wattage PTC elements meet Japan's METI Top Runner efficiency thresholds. These systems dominate sales volume in energy-price-sensitive European markets.
- 200-300 W:Balanced thermal output for standard garment loads captures the core replacement market in Chinese tier-one cities.
- 300-400 W:Accelerated drying cycles with infrared panel supplementation command premium positioning in time-constrained professional households.
- Above 400 W:High-output hybrid systems with UV-C sterilization integration serve health-conscious East Asian consumers and commercial hospitality procurement.
The 200-300 W segment commands the dominant share, while 100-200 W configurations are expanding most quickly under tightening EU Ecodesign and China GB 4706 efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters export compact electric drying hardware to European and North American retail channels, while domestic absorption in Asian megacities drives the highest replacement velocities. Cross-border certification requirements fragment product lineups across destination markets.
China
Guangdong and Zhejiang provinces concentrate PTC ceramic module and control circuit production for domestic and export markets. GB 4706 energy-efficiency standards compel manufacturers to redesign heating elements and standby power circuits. Shanghai and Shenzhen apartment construction sustains demand for wall-mounted and foldable configurations in tier-one cities with elevated humidity levels.
Japan
Tokyo and Osaka micro-apartments generate intense demand for 5-10 kg capacity units with minimal footprint requirements. METI Top Runner efficiency benchmarks accelerate import requirements for electric drying equipment. Nagoya industrial corridors host testing facilities certifying compliance with JIS standards for regional distribution.
Germany
Berlin and Munich rental housing procurement channels consolidate purchasing authority through property management platforms. EU Ecodesign Directive constraints on standby power mandate digital PWM control migration from analog thermostats. North Rhine-Westphalia manufacturing clusters supply modular heating architectures for field serviceability in European retail channels.
India
Mumbai, Bangalore, and Delhi metro construction outpaces tumble dryer penetration, creating first-mover positioning for ceiling-mounted aluminum configurations. BIS appliance safety standards govern import certification and domestic manufacturing licensing. Maharashtra and Karnataka industrial zones fabricate weight-optimized extruded alloy profiles for vertical space utilization in new-build apartments.
United States
EPA ENERGY STAR program and DOE appliance standards shape market access thresholds for imported hardware. New York and Los Angeles dense housing stock sustains niche demand for compact drying solutions where floor space constraints preclude conventional dryers. California Title 20 energy regulations impose additional efficiency disclosure requirements beyond federal baselines.
Electric Clothes Drying Hanger Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent retail and institutional procurement pathways. The vendor base stratifies into three tiers: heritage homeware brands with retail depth, engineering-focused manufacturers with testing protocols, and design-driven specialists with aesthetic positioning. Consolidation pressure concentrates in European markets where build-to-rent procurement displaces individual consumer channels. Dominant competitive moves include direct B2B contracting with institutional landlords and modular architecture development for component upgradability.
Among heritage European homeware specialists, Minky and Leifheit occupy positions anchored by geographic origin and channel presence. Foxydry exemplifies design-forward Mediterranean positioning. Chinese fabricators including LBest and Tangkula represent scale-driven supply capabilities. JLA and Brabantia sit within institutional procurement channels serving rental housing operators. Dry:Soon and Honey-Can-Do occupy mid-market retail positioning across North American and European distribution networks.
| Leading Market Players |
|---|
| Minky |
| JLA |
| Leifheit |
| Brabantia |
| Dry:Soon |
| Foxydry |
| Tangkula |
| Honey-Can-Do |
| LBest |
| Others |
Supply & Pricing Matrix
Guangdong province's concentration of PTC ceramic module fabrication and control circuit assembly feeds directly into margin compression for brands lacking captive production. Manufacturers outside China's manufacturing ecosystem face royalty burdens or exclusion risks that reshape where value accrues across the value chain.
Pricing Analysis
The technology-generation pricing gap separates legacy analog thermostat systems from digital PWM-controlled configurations and emerging UV-C sterilization hybrids. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal architecture sophistication and certification grade, with EU CE marking and China GB 4706 compliance tiers commanding measurable premiums. Cost compression in entry-tier SKUs is intensifying because glass-filled polymer housings and passive convection designs face commodity substitution pressure. Rental housing procurement through property management platforms exhibits lowest price sensitivity, while individual consumers in German student dormitories and seasonal markets show highest elasticity.
Supply Chain Analysis
Export-control regime angles around semiconductor components for digital control systems create friction in sourcing PWM modules and sensor arrays from certain jurisdictions. Manufacturing gravity centers on China, India, and Vietnam, with China dominating PTC ceramic formulation and control circuit production while India and Vietnam handle aluminum extrusion and final assembly. Raw material dependencies span copper for heating elements, aluminum for weight-optimized frames, and rare-earth components for infrared panel substrates. Single-source vulnerability concentrates in Guangdong province's PTC ceramic clusters. Distribution runs through direct B2B contracting with institutional landlords replacing traditional retail in Northern European build-to-rent markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart home interoperability is reshaping competitive positioning as humidity sensors and app-based scheduling converge with existing IoT ecosystems, creating platform lock-in effects that favor early movers with API integration depth.
For Market Incumbents: Entrench position through backward integration into PTC ceramic formulation to escape royalty burdens from proprietary patent holders. Prioritize certification investment in Japan's METI Top Runner program to secure preferential labeling advantages before efficiency benchmarks accelerate. Defend against heat pump substitution threat by emphasizing installation flexibility that integrated laundry appliances cannot match.
For New Entrants and Emerging Players: Indian metro construction outpacing tumble dryer penetration offers first-mover positioning for ceiling-mounted aluminum configurations tailored to vertical space utilization. Target Mumbai and Bangalore apartment developments through direct contracting with property developers before procurement authority consolidates. Leverage BIS appliance safety standards compliance as a market entry credential rather than retrofit burden.
For Investors and Strategic Acquirers: Capital is best deployed toward modular heating architecture specialists with field serviceability design and component-level upgrade pathways. Long-term viability across the analysis window hinges on regulatory compliance agility as GB 4706 and EU Ecodesign Directive iterations compress product cycles. Watch for consolidation signals when rental housing procurement platforms begin standardizing specifications across multi-unit portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | API connectivity with Xiaomi, Google Home, and Amazon Alexa ecosystems enables premium tier pricing through connected functionality. |
| Modular Heating Architecture Development | Field serviceable components address EU Ecodesign Directive service life extension mandates while reducing warranty costs. |
| Direct B2B Rental Housing Contracting | Bypassing retail channels captures Berlin, Amsterdam, and Copenhagen build-to-rent procurement standardization. |
| UV-C Sterilization Hybrid Launch | Health-conscious East Asian consumers in Tokyo and Shanghai drive accelerated replacement cycles for sterilization-enabled units. |
| Aluminum Extrusion Capacity Expansion | Weight reduction for Indian ceiling-suspension installations addresses structural load constraints in new-build apartments. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with appliance manufacturing executives, supply chain procurement leads, rental housing property managers, and smart home platform engineers; and secondary validation through customs trade records, SEC filings of listed homeware companies, GB standards documentation, and EU Ecodesign Directive regulatory filings. Bottom-up unit economics modeling triangulated against top-down market sizing from channel shipment data.
Forecast inputs span product type segmentation across wall-mounted, foldable, portable, and ceiling-mounted configurations; material tier stratification; capacity band distribution; and power rating compliance tiers. CAGRs derived from replacement cycle analysis in humidity-driven clusters and urban space constraint intensity across metropolitan zones. Regulatory timeline acceleration under METI Top Runner and EU Ecodesign Directive iterations shaped adoption curve assumptions.
Macroeconomic conditions sit as an overlay; deviation in copper and aluminum commodity volatility, cross-border certification timeline extensions, or rental housing construction finance availability would shift the trajectory. Material shifts in China's dual carbon goals implementation or EU building code amendments redefining permissible installation locations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
Latex Mattress Market
Household Items
Non-Stick Cookware Market
Household Items
Pocket Tissues Market
Household Items
Europe Hand Dryers Market
Household Items
Smart Spin Mop Market
Household Items
Smart Faucets Market
Household Items
France Digital Showers Market
Household Items
Smart Toilet Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Thermos Drinkware Market
Household Items
Sanitary Metal Ware Market
Household Items
Cast Iron Cookware Market
Household Items
Smart Bath Heater Market