
 Stainless Steel Thermos Cup Market | 2026-2036
Stainless Steel Thermos Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Thermos Cup Market Insights
The capital-intensity divergence between premium vacuum-insulation specialists and mass-market assemblers is collapsing as Chinese foundries scale precision welding capacity. YETI Holdings leverages vertical integration into rotational molding and powder-coating operations to sustain margin capture on high-end insulated cups. Fuguang Group anchors its position through captive stainless-steel forming and automated electrolytic polishing lines that compete on unit economics at 500ml and 750ml capacities.
A stainless steel thermos cup is a double-walled vacuum-insulated vessel constructed primarily from 304 or 316 grade austenitic stainless steel, employing copper-layered inner walls and laser-welded seams to achieve thermal retention exceeding six hours for liquids between negative five and ninety-nine degrees Celsius. Its primary commercial purpose is portable temperature preservation of beverages for mobile consumers across commuting, recreation, and institutional settings. Travel mugs lead volume within product type segmentation due to commuter-driven replacement cycles, while beverage dispensers command the deepest margin pools in commercial channels. Online retail represents the fastest-growing distribution channel as direct-to-consumer brands bypass wholesale markups through social commerce and subscription replenishment models.
The US FDA regulates food-contact surface compliance under 21 CFR 175.300, while China's SAMR enforces GB 4806.9-2016 for metal migration limits in food-contact stainless steel; both frameworks elevate testing costs for new market entrants. The EU's REACH regulation and F-Gas restrictions on hydrofluorocarbon blowing agents for insulation foam are reshaping vacuum-panel manufacturing specifications. Stakeholders must monitor how California's Proposition 65 enforcement trends and emerging state-level packaging EPR laws will cascade into material certification requirements and channel compliance costs.
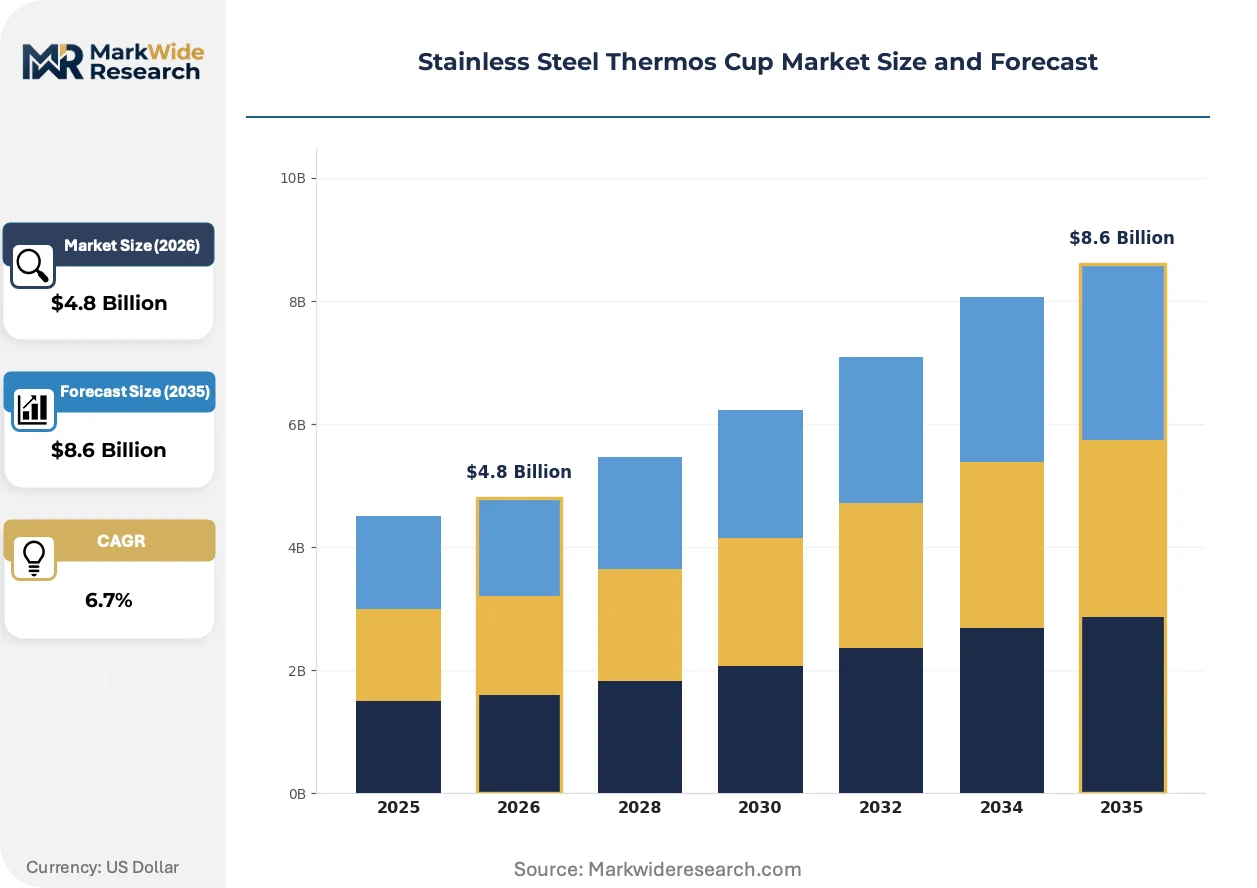
Market Dynamics
Precision laser welding automation is collapsing the cost barrier between premium vacuum insulation and commodity-grade double-walled construction, compressing margin hierarchies across all capacity tiers.
Growth Catalysts
- EU F-Gas Regulation:Hydrofluorocarbon restrictions on insulation foam blowing agents are accelerating copper-vacuum panel adoption, opening technical differentiation paths for compliant manufacturers.
- Commuter replacement cycles:Urban mobility patterns in dense metropolitan corridors are compressing thermos cup refresh intervals to eighteen-to-twenty-four months, sustaining baseline volume velocity.
- 316L grade austenitic steel:Enhanced corrosion resistance specifications for acidic beverage contact are elevating material certification premiums across food-service procurement channels.
Market Restraints
- Nickel price volatility:304 and 316 grade stainless feedstock costs swing with London Metal Exchange nickel futures, squeezing contract manufacturer margins on fixed-price retail agreements.
- Zhejiang-Guangdong supply concentration:Over seventy percent of formed shell capacity sits within two hundred kilometers of Ningbo and Foshan, creating geographic risk exposure to regional logistics disruptions.
- Copper-layer deposition limits:Thermal conductivity enhancement through electroplated copper inner walls faces thickness uniformity constraints above point-three millimeters, capping theoretical insulation performance.
Strategic Opportunities
- India FSSAI compliance:Food-contact metal migration testing infrastructure remains underdeveloped, creating first-mover advantage for pre-certified exporters targeting institutional catering procurement.
- Subscription replenishment models:Direct-to-consumer brands are bypassing wholesale markups through social commerce integration, capturing lifetime value through seasonal colorway drops.
- Solar-powered temperature display:Thin-film photovoltaic integration with digital readouts is converging with Bluetooth connectivity for beverage temperature logging, opening premium positioning in fitness tracking ecosystems.
Industry Challenges
- Laser welding technician scarcity:Precision seam operation on point-five-millimeter gauge steel requires eighteen-to-twenty-four month training curves, constraining capacity expansion timelines.
- Multi-jurisdiction certification stacking:Simultaneous FDA 21 CFR 175.300, GB 4806.9-2016, and REACH SVHC compliance documentation extends product launch cycles by eight-to-fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Thermos Cup Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Cups, Travel Mugs, Beverage Dispensers, Flasks End User: Households, Outdoor Enthusiasts, Office Workers, Travelers Capacity: 250ml, 500ml, 750ml, 1000ml Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | YETI Holdings, Inc., Hydro Flask, Thermos LLC, Klean Kanteen, Stanley PMI, Zojirushi Corporation, Contigo, Fuguang Group, S'well, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Thermos Cup Market Trends and Innovations
Material science breakthroughs and channel restructuring are compressing traditional tier boundaries while elevating performance verification as the primary purchase determinant across all buyer segments.
Titanium-lined vacuum chambers are displacing copper-plated stainless construction in high-performance outdoor applications. Alpine expedition outfitters and search-and-rescue procurement offices specify titanium for weight-to-retention ratios below three hundred grams per five-hundred-milliliter capacity. This displacement is collapsing the historical performance gap between aerospace-grade materials and consumer-accessible price points.
China's SAMR enforcement of GB 4806.9-2016 metal migration limits is tightening supplier qualification protocols for cross-border e-commerce platforms. Third-party laboratory certification costs per SKU have doubled since twenty-twenty-two, filtering out unverified white-label sellers. Domestic Chinese brands with captive testing infrastructure are absorbing compliance overhead faster than export-dependent trading houses.
Social commerce live-streaming is fragmenting traditional retail gatekeeper power in thermos cup distribution. Influencer-led flash sales on Douyin and TikTok Shop are compressing brand building timelines from years to months. This channel shift is most visible in East Asian urban markets where impulse purchase rates exceed forty percent during limited-drop events.
Stainless Steel Thermos Cup Market Segmentation
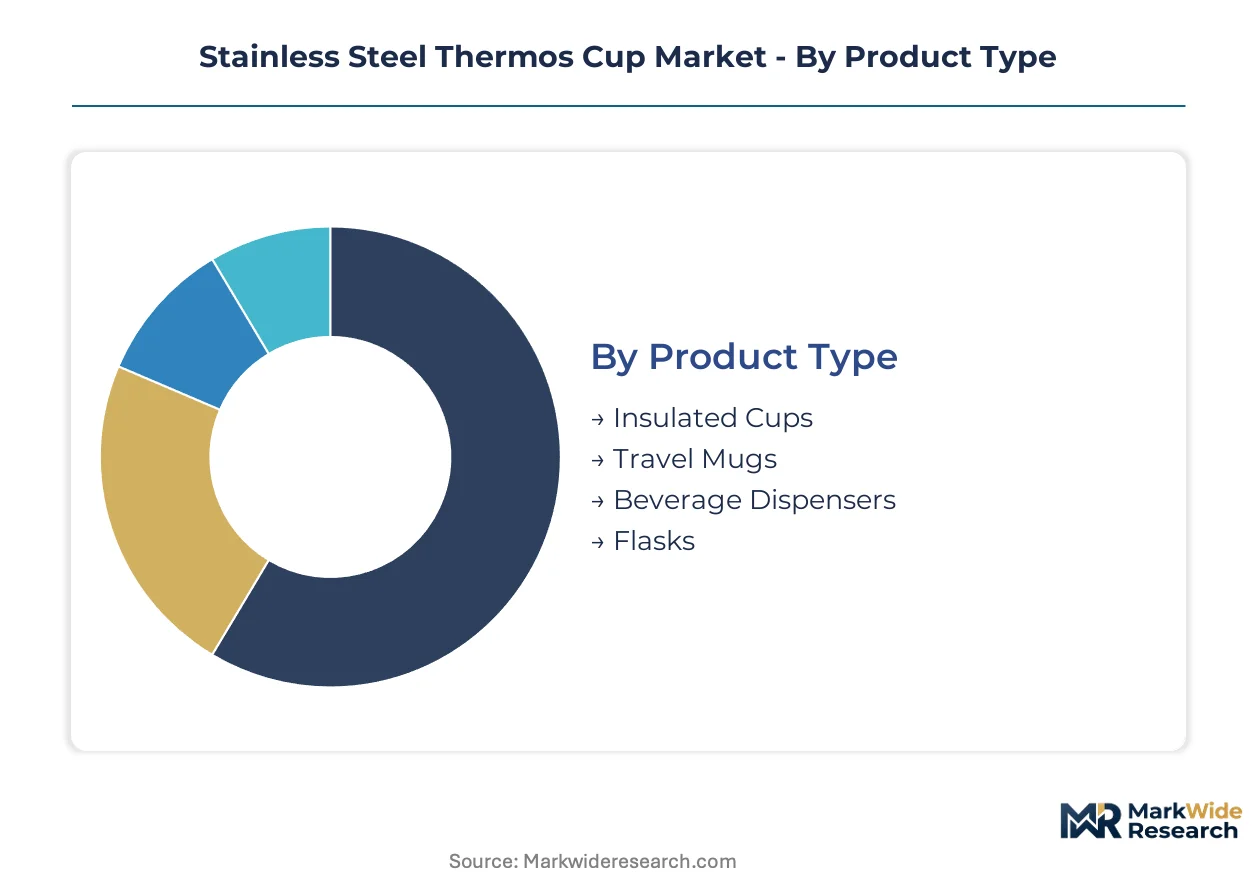
Segmentation in the stainless steel thermos cup market reveals how thermal performance specifications, mobility patterns, and procurement channels fragment demand across distinct buyer cohorts. Each dimension carries different margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Domestic Chinese brands dominate insulated cups and flasks through Zhejiang-based manufacturing clusters, while export-led demand concentrates in travel mugs and beverage dispensers bound for North American and European retail channels.
- Travel Mugs:Double-walled vacuum construction with leak-proof sealing mechanisms and ergonomic grip profiles. Commuter replacement cycles in dense metropolitan corridors like Tokyo, New York, and London compress refresh intervals to eighteen-to-twenty-four months, sustaining volume velocity through transit-oriented retail placement.
- Beverage Dispensers:High-capacity insulated vessels with pump-action or gravity-fed dispensing for institutional catering and commercial food-service. Procurement offices in US healthcare systems and EU corporate campuses specify 316L-grade austenitic steel for acidic beverage compatibility, elevating material certification premiums.
- Insulated Cups:Wide-mouth designs with sip-through lids for stationary consumption in home and office environments. Chinese domestic brands with captive testing infrastructure absorb GB 4806.9-2016 compliance overhead faster than export-dependent trading houses.
- Flasks:Narrow-neck cylindrical profiles optimized for pocket portability and extended outdoor exposure. Alpine expedition outfitters in Switzerland and search-and-rescue procurement offices in Norway specify titanium-lined variants for weight-to-retention ratios below three hundred grams per five-hundred-milliliter capacity.
Travel mugs hold the largest share; momentum sits with beverage dispensers as institutional procurement elevates performance specifications.
End User:
Cost tier stratification separates premium outdoor enthusiasts from price-sensitive household buyers, with office workers and travelers occupying overlapping mid-market positioning.
- Outdoor Enthusiasts:Expedition-grade specifications demand sub-zero thermal retention and impact-resistant construction. Search-and-rescue procurement offices in Norway and alpine outfitters in Switzerland drive titanium-lined vacuum chamber adoption for weight-critical applications.
- Office Workers:Desktop-optimized designs prioritize one-handed operation and spill resistance during multitasking. Commuter corridors in Tokyo, Seoul, and Singapore sustain replacement cycle compression through transit-oriented retail placement.
- Households:Volume-driven procurement favors multi-unit packs and seasonal colorway rotations through hypermarket channels. Chinese domestic brands leverage Douyin live-streaming flash sales to capture impulse purchase rates exceeding forty percent during limited-drop events.
- Travelers:TSA-compatible dimensions and leak-proof certification for pressurized cabin environments. Airport retail in Dubai, Singapore, and Frankfurt anchors impulse purchase placement for premium-branded compact capacities.
Households hold the largest share; outdoor enthusiasts are climbing the fastest as technical specifications migrate from professional to consumer-accessible price points.
Capacity:
Application-driven sizing separates commuter-optimized portability from stationary consumption volumes, with 500ml and 750ml formats commanding the deepest manufacturing specialization.
- 500ml:The dominant commuter format balancing single-serve beverage volume with pocket and cup-holder compatibility. YETI Holdings and Fuguang Group compete on unit economics through automated electrolytic polishing lines at this capacity tier.
- 750ml:Extended-duration outdoor and intercity travel specification requiring enhanced thermal retention engineering. Precision laser welding automation collapses cost barriers between premium vacuum insulation and commodity-grade construction at this scale.
- 250ml:Espresso and concentrated beverage specialization for European urban café culture. Limited manufacturing scale elevates per-unit tooling amortization relative to larger formats.
- 1000ml:Group serving and hydration-focused applications in athletic and expedition contexts. Institutional catering procurement in US healthcare systems drives specification for this capacity tier.
500ml holds the largest share; 750ml is gaining share fastest as outdoor recreation specifications penetrate mainstream consumer channels.
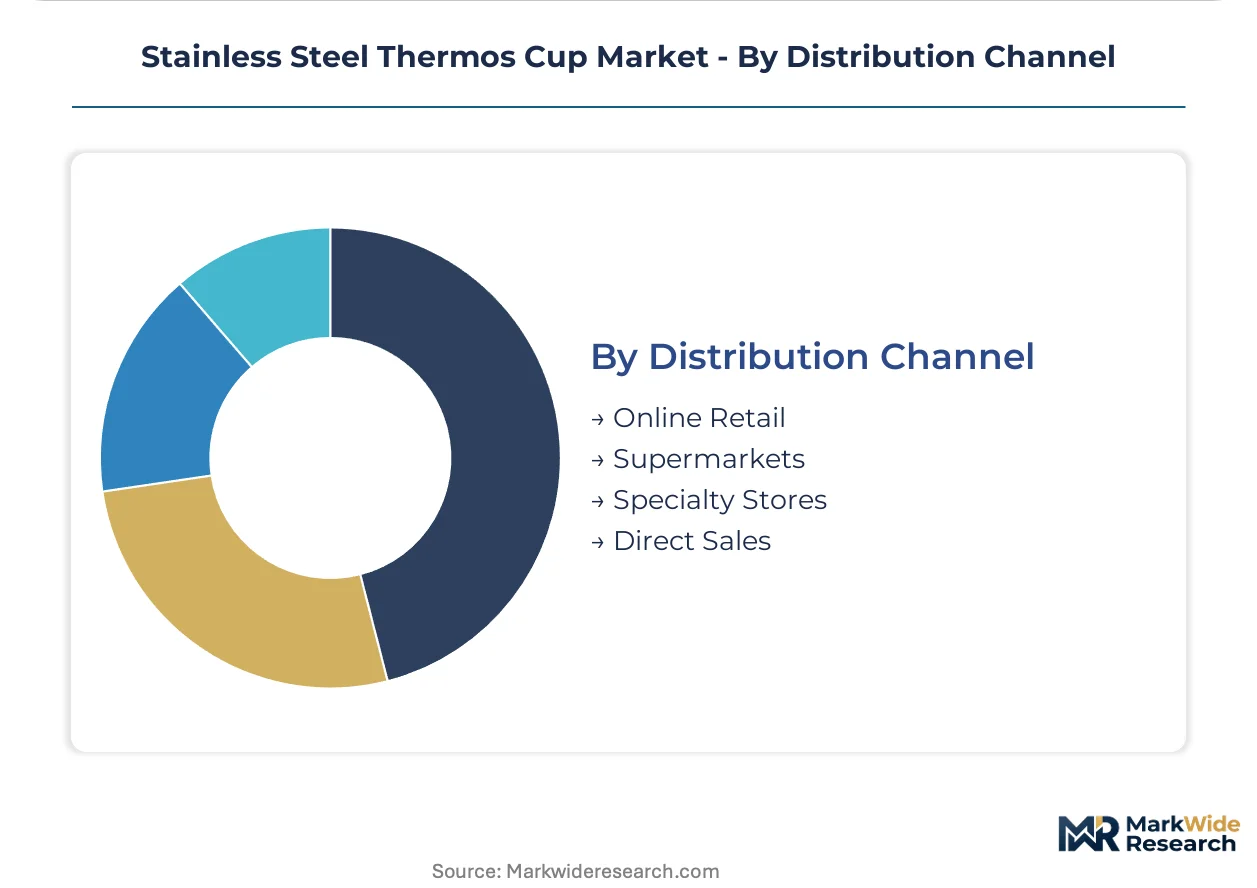
Distribution Channel:
Margin capture diverges between direct-to-consumer subscription models and traditional wholesale markups, with channel choice reshaping brand building timelines and compliance cost allocation.
- Online Retail:Social commerce integration on Douyin and TikTok Shop compresses brand building timelines from years to months. Direct-to-consumer brands bypass wholesale markups through seasonal colorway drops and replenishment subscriptions.
- Specialty Stores:Curated assortment and staff consultation for technical performance verification. Outdoor retailers in Germany, Japan, and Colorado anchor premium positioning through in-store thermal testing demonstrations.
- Supermarkets:High-velocity rotation of standard capacities through hypermarket chains in China's tier-two cities and India's emerging urban corridors. Price transparency and promotional dependency squeeze margin capture.
- Direct Sales:Corporate gifting and institutional procurement through dedicated account management. US healthcare systems and EU corporate campuses specify 316L-grade compliance through direct vendor qualification.
Supermarkets hold the largest share; online retail shows the steepest expansion trajectory as social commerce fragments traditional retail gatekeeper power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Swiss and Japanese alpine markets where expedition-grade specifications command material certification premiums, while Chinese manufacturing clusters compete on unit economics through automated forming and polishing lines.
United States
Commuter replacement cycles in New York, Chicago, and Los Angeles compress refresh intervals to eighteen-to-twenty-four months through transit-oriented retail placement. FDA regulates food-contact surface compliance under 21 CFR 175.300, elevating testing costs for new market entrants. Colorado and Pacific Northwest outdoor retailers anchor premium positioning through in-store thermal testing demonstrations.
China
Domestic brands leverage Douyin live-streaming flash sales to capture impulse purchase rates exceeding forty percent during limited-drop events. SAMR enforces GB 4806.9-2016 for metal migration limits in food-contact stainless steel. Zhejiang and Guangdong provinces concentrate over seventy percent of formed shell capacity within two hundred kilometers of Ningbo and Foshan.
Germany
Outdoor retailers curate technical performance verification for alpine expedition outfitters demanding sub-zero thermal retention. ECHA's REACH regulation and F-Gas restrictions on hydrofluorocarbon blowing agents reshape vacuum-panel manufacturing specifications. Bavarian and North Rhine-Westphalian distribution hubs channel premium-branded compact capacities through Frankfurt airport retail.
Japan
Tokyo and Seoul commuter corridors sustain replacement cycle compression through transit-oriented retail placement. METI oversees industrial standards coordination while PMDA maintains parallel medical-grade material protocols. Kansai and Chubu manufacturing regions specialize in precision laser welding automation for point-five-millimeter gauge steel.
India
Emerging urban corridors in tier-two cities drive volume through hypermarket channels with price transparency and promotional dependency. FSSAI food-contact metal migration testing infrastructure remains underdeveloped, creating first-mover advantage for pre-certified exporters. Maharashtra and Gujarat procurement offices specify 316L-grade austenitic steel for institutional catering.
Stainless Steel Thermos Cup Market Competitive Landscape
Concentration sits with vertically integrated specialists controlling captive stainless-steel forming and automated electrolytic polishing lines. The vendor base spans premium vacuum-insulation specialists, mass-market assemblers, and direct-to-consumer brands bypassing wholesale markups. Three archetypes dominate: precision welding specialists, social-commerce-native brands, and institutional procurement qualifiers. Competitive moves center on backward integration into rotational molding operations and geographic expansion through pre-certified export positioning.
Among premium-tier specialists, YETI Holdings exemplifies the vertically integrated archetype through upstream control over powder-coating operations. Fuguang Group anchors the scale-driven Chinese manufacturing tier with Zhejiang-based production infrastructure. Thermos LLC occupies the legacy brand position within institutional procurement channels. These three represent distinct competitive vectors rather than direct peer competition.
| Leading Market Players |
|---|
| YETI Holdings, Inc. |
| Hydro Flask |
| Thermos LLC |
| Klean Kanteen |
| Stanley PMI |
| Zojirushi Corporation |
| Contigo |
| Fuguang Group |
| S'well |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Zhejiang and Guangdong foundries lock in formed shell access while capping nickel feedstock exposure for premium vacuum-insulation specialists. These arrangements bind pricing visibility to London Metal Exchange futures hedging, compressing margin volatility for vertically integrated operators while exposing spot-market assemblers to raw material swings.
Pricing Analysis
Configured-to-order pricing for titanium-lined expedition-grade flasks commands spreads exceeding three standard tiers against commodity 304-grade travel mugs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade — FDA 21 CFR 175.300 compliance elevates base costs against uncertified white-label imports. Pricing pressure stems from precision laser welding automation collapsing cost barriers between vacuum-insulation tiers. Household buyers through Chinese hypermarket channels exhibit highest price sensitivity; alpine expedition outfitters in Switzerland demonstrate lowest elasticity due to weight-to-retention specification rigidity.
Supply Chain Analysis
Port congestion along the Ningbo-Shanghai corridor and container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for export-dependent trading houses. Formed shell capacity concentrates in China, South Korea, and Japan, with Zhejiang and Guangdong provinces anchoring over seventy percent of global output. Raw material dependencies rest on nickel ore from Indonesia and the Philippines, copper cathode from Chile, and 316L-grade stainless feedstock from Japanese mills. Single-source vulnerability to regional logistics disruptions within two hundred kilometers of Ningbo and Foshan constitutes primary structural risk. Distribution runs through direct-to-consumer social commerce platforms, specialty outdoor retailers, and institutional procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stainless steel thermos cup penetration in Indian institutional catering and Southeast Asian commuter corridors signals early-cycle expansion, with FSSAI compliance infrastructure gaps creating first-mover tailwinds for pre-certified exporters.
For Market Incumbents: Shield margin capture through backward integration into captive electrolytic polishing lines and automated laser welding capacity. Precision welding technician scarcity constrains competitor scale-up timelines. Prioritize GB 4806.9-2016 certification investment to filter unverified white-label sellers from cross-border e-commerce platforms. For New Entrants and Emerging Players: Subscription replenishment model gaps in seasonal colorway drops present exploitable service-layer white space. Target Indian institutional catering procurement through pre-certified 316L-grade positioning. Deploy Douyin and TikTok Shop social commerce integration for compressed brand building timelines. For Investors and Strategic Acquirers: Social-commerce-native brands with captive testing infrastructure represent the priority acquisition archetype. Long-term viability hinges on direct-to-consumer channel control and compliance infrastructure ownership. Monitor FSSAI enforcement acceleration as inflection indicator for Indian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Welding Capacity | YETI Holdings and Fuguang Group anchor margin capture through in-house precision seam operations. |
| FSSAI Pre-Certification Investment | First-mover exporters bypass India's underdeveloped metal migration testing infrastructure. |
| Direct-to-Consumer Social Commerce Launch | Douyin and TikTok Shop integration fragments traditional retail gatekeeper power. |
| Titanium-Lined Product Line Extension | Alpine outfitters in Switzerland drive aerospace-grade material adoption at consumer price points. |
| Subscription Replenishment Model Deployment | Seasonal colorway drops capture lifetime value through automated reorder cycles. |
Research Methodology
Cross-validation between primary interviews with Zhejiang foundry operators, SAMR compliance officers, and US healthcare procurement managers anchors the qualitative findings against secondary validation. Plant managers at electrolytic polishing lines, category buyers at German outdoor retailers, and channel sales heads at Douyin ecosystem partners provided operational perspective. Secondary sources include FDA 21 CFR 175.300 filings, SAMR GB 4806.9-2016 enforcement records, London Metal Exchange nickel futures data, and customs export manifests from Ningbo port. Bottom-up capacity modeling triangulates against top-down demand segmentation across commuter, outdoor, and institutional end-use cohorts.
Sensitivity analysis around nickel price volatility scenarios and laser welding automation adoption curves shapes the analytical framework. Segmentation dimensions span product type, capacity tier, end-user archetype, and distribution channel complexity. CAGRs derive from installed base replacement cycle compression and penetration rate trajectories across dense metropolitan corridors. Forecast inputs incorporate F-Gas Regulation compliance timelines and REACH SVHC documentation burden estimates.
Material uncertainties — nickel futures swings, regional logistics disruptions in Zhejiang-Guangdong clusters, and multi-jurisdiction certification stacking delays — sit outside the modeled envelope. Forecasts reflect assumptions about SAMR enforcement intensity and social commerce platform algorithm shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
North America Water Purifier Market
Household Items
Kitchen Towel Market
Household Items
Cutlery Market
Household Items
Smart Faucets Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Europe Handheld Fans Market
Household Items
Washing Capsules Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Water Purifier Bottle Market
Household Items
Hand Wash Station Market
Household Items
Shower Heads Market
Household Items
India POU Water Purifiers Market
Household Items
Smart Spin Mop Market
Household Items
Aromatherapy Diffuser Market
Household Items
Hands-Free Faucet Market
Household Items
Middle East and Africa Air Purifier Market