
 Smart Bath Heater Market | 2026-2036
Smart Bath Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bath Heater Market Insights
Energy Star certification and IPX4 waterproof rating tiers is reorganizing procurement criteria across the Smart Bath Heater landscape. Haier Group leverages its appliance ecosystem to bundle connected water heating with HVAC controls. Xiaomi Inc. competes through aggressive channel control in direct-to-consumer online platforms. Kohler Co. anchors the premium architectural specification segment with design-integrated installations.
A smart bath heater is an electronically controlled water heating appliance that integrates temperature modulation, connectivity protocols, and safety interlocks to deliver on-demand or stored hot water for bathing applications. Units typically incorporate thermistor arrays, flow sensors, and microprocessor-driven heating elements rated between 3 kW and 12 kW, with IP-rated enclosures for wet-environment durability. Tankless configurations dominate residential retrofit volumes due to compact form factors and reduced standby losses. Wi-Fi Enabled technology leads the connectivity segment as homeowners prioritize remote scheduling and utility rate optimization. Energy Monitoring capabilities are capturing margin pools among commercial and hospitality operators seeking operational transparency.
China's GB standards for electrical appliance safety and energy efficiency labeling, administered by SAMR, set baseline performance thresholds for domestic sales. The EU Ecodesign Directive and CE marking requirements, enforced by national market surveillance authorities in Germany and France, restrict imports that fail minimum efficiency benchmarks. Stakeholders must monitor regulatory divergence between Asian GB harmonization and European ecodesign tightening to avoid compliance fragmentation in cross-border product portfolios.
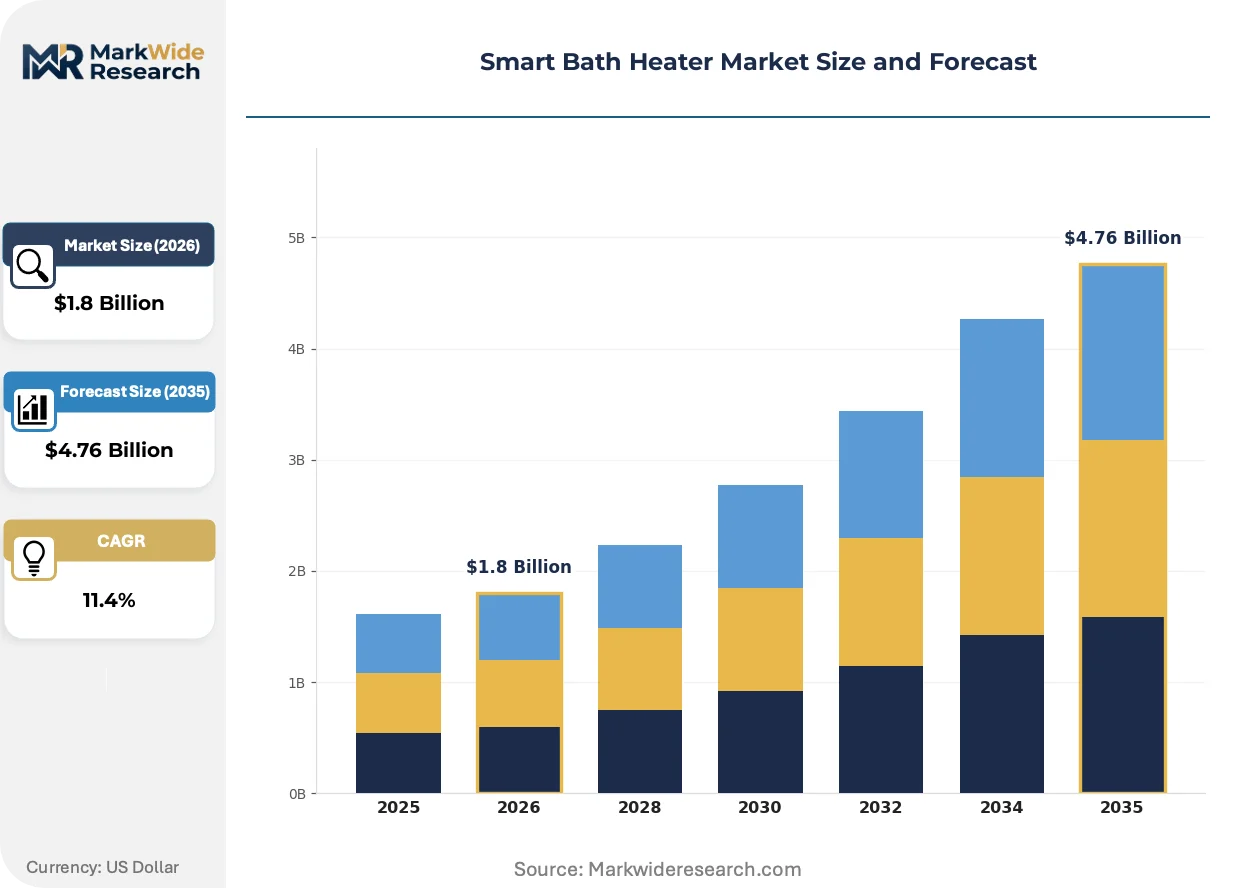
Market Dynamics
Heat pump-integrated smart bath heater architectures are restructuring competitive positioning as the EU F-Gas Regulation and China's dual carbon goals force refrigerant transitions and efficiency redesigns across manufacturer portfolios.
Growth Catalysts
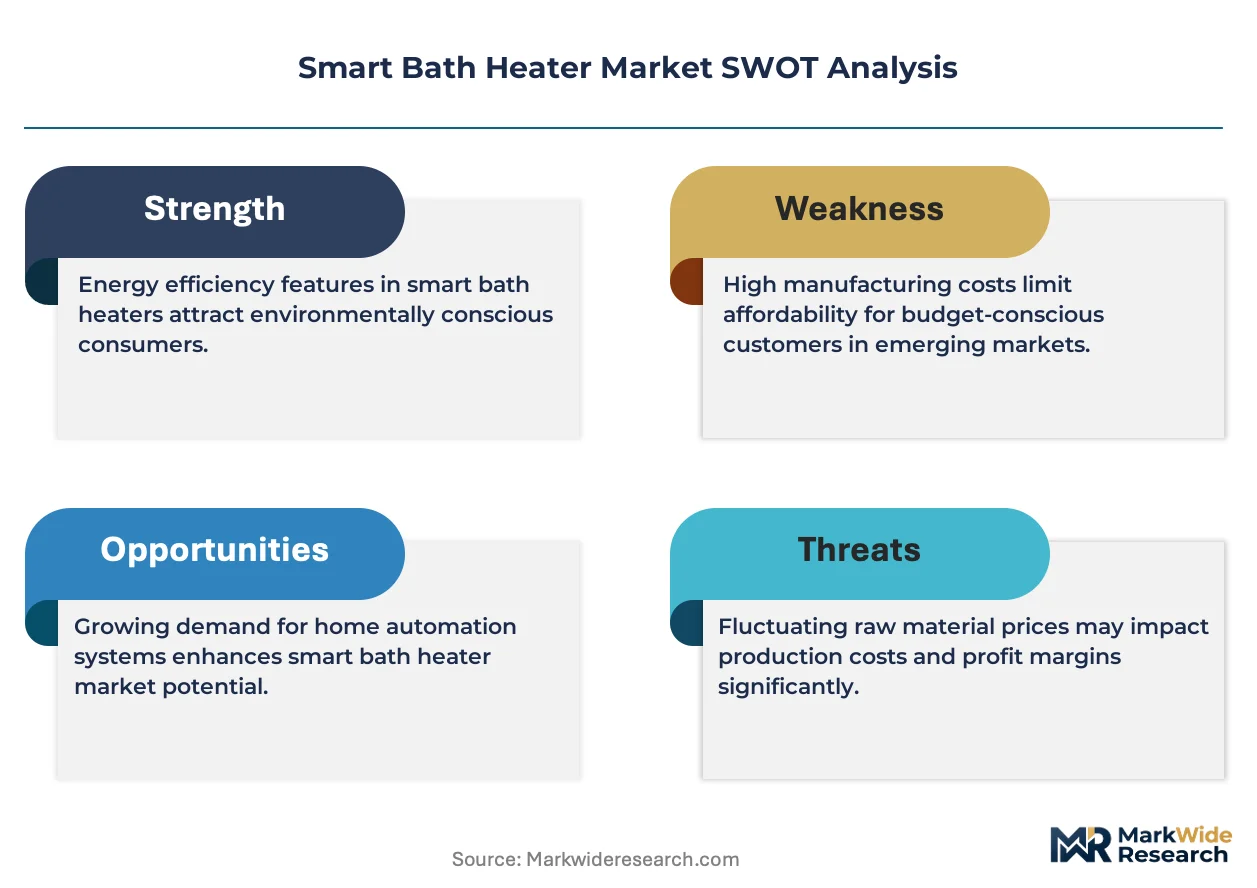
- EU F-Gas Regulation phase-down schedules:The mandated reduction in high-GWP refrigerants is accelerating R&D investment in propane-based and CO2 heat pump systems for residential water heating applications.
- Metropolitan corridor densification:South Korea's Seoul-Incheon corridor and China's coastal provinces are driving tankless retrofit volumes as apartment unit sizes shrink and standby loss intolerance rises.
- Energy Monitoring module integration:Commercial hospitality operators in California and Texas are mandating operational transparency dashboards, pulling embedded sensor arrays into specification requirements.
Market Restraints
- Copper and rare earth magnet cost volatility:Compressor motor laminations and heat exchanger tubing face input price swings that compress OEM margins on mid-tier product lines.
- IPX4 enclosure supply concentration:Waterproof seal manufacturing clusters in Guangdong and Zhejiang provinces create single-source vulnerability for ingress protection-rated housing assemblies.
- Legacy electrical infrastructure incompatibility:Pre-1990s residential panel ratings in Germany and Japan limit 9-12 kW instantaneous heater deployment without costly service upgrades.
Strategic Opportunities
- India's BIS energy efficiency labeling expansion:The Bureau of Indian Standards is extending mandatory star ratings to electric water heaters, creating first-mover positioning for connected, high-COP designs.
- AI-driven predictive maintenance convergence:Machine learning algorithms layered atop Wi-Fi Enabled units enable failure anticipation, opening subscription revenue streams in multi-unit residential management.
- Direct-to-installer platform channel innovation:Bypassing traditional wholesale distribution through contractor-facing apps is capturing margin in the United States Sun Belt replacement cycle.
Industry Challenges
- Embedded systems firmware certification timelines:CE marking and GB standard compliance testing for wireless protocol stacks extends product launch windows by 8-14 months.
- Heat pump refrigeration circuit skill scarcity:Installer certification for flammable refrigerant handling remains unevenly distributed across European and North American service networks.
- Legacy smart home protocol fragmentation:Thread, Zigbee, and proprietary ecosystem incompatibilities force redundant SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bath Heater Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Heater, Storage Heater, Tankless Heater, Hybrid Heater Technology: Wi-Fi Enabled, Bluetooth Control, Smart Sensors, Energy Monitoring End User: Residential, Commercial, Hospitality, Healthcare Installation Type: Wall-Mounted, Floor-Mounted, Portable, Integrated |
| Companies Covered | Haier Group, Xiaomi Inc., AUPU, Canpro, Yeelight, Opple, Kohler Co., Stiebel Eltron, Rheem Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bath Heater Market Trends and Innovations
Refrigerant chemistry and connectivity architecture choices are splitting product roadmaps as manufacturers place divergent bets on decarbonization pathways and platform ecosystem alignment.
CO2 transcritical heat pump cycles are bifurcating the premium residential segment from conventional electric resistance designs. Japanese and German utilities are subsidizing these systems through demand-response programs. The technology is compressing addressable market scope for pure tankless electric units above 6 kW ratings.
REACH and RoHS substance restrictions are tightening solder alloy and flame-retardant polymer specifications for wet-environment electronics. Manufacturers serving EU markets are reformulating PCB assemblies and enclosure plastics to maintain compliance. The regulatory pressure is most acute for value-tier suppliers lacking in-house materials science capabilities.
Buyer specification behavior is fragmenting between ecosystem-locked and ecosystem-agnostic purchase patterns. Homeowners invested in Apple HomeKit or Google Nest infrastructures are rejecting standalone app-controlled units, forcing OEMs to pursue multi-platform certification. This pattern is most visible in California's premium housing clusters and South Korea's newly built apartment complexes.
Smart Bath Heater Market Segmentation
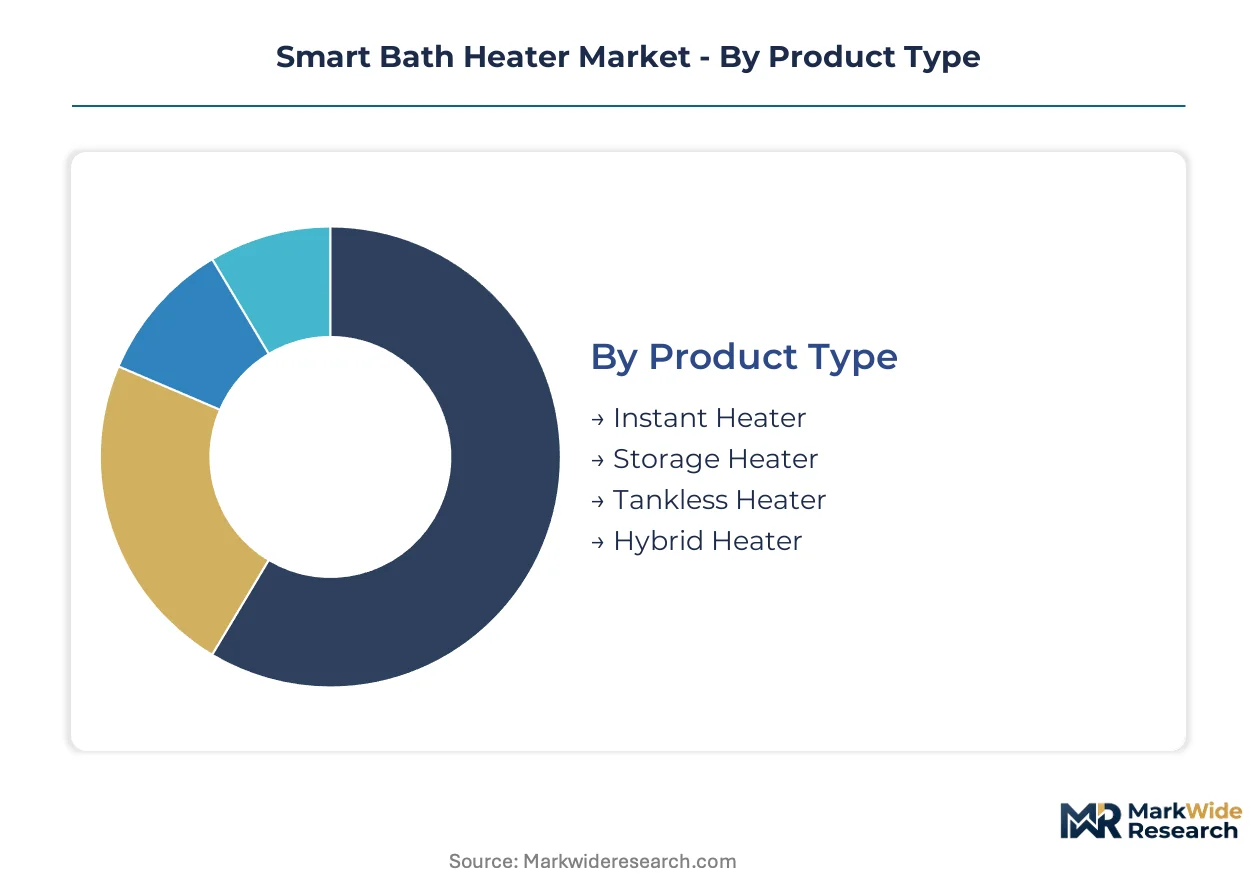
Smart bath heater procurement decisions split across technical performance thresholds, connectivity ecosystems, and installation constraints. Segment boundaries determine margin capture for OEMs and specification authority for contractors and facility managers.
Product Type:
Margin pools concentrate in compact retrofit solutions and heat pump-integrated architectures where efficiency mandates justify premium positioning.
- Instant Heater:Thermistor-controlled heating elements activate on flow detection, eliminating standby thermal losses. Demand clusters in South Korea's Seoul-Incheon corridor and Japan's Kanto region where apartment footprints constrain tank placement and electricity tariffs penalize idle consumption.
- Tankless Heater:Compact form factors with 3-12 kW element arrays deliver continuous output without storage volume. California and Texas replacement cycles are pulling specification authority toward contractor-facing procurement platforms as homeowners prioritize space reclamation.
- Storage Heater:Insulated tank assemblies with scheduled heating cycles exploit time-of-use rate structures.
- Hybrid Heater:Heat pump-integrated designs with electric resistance backup balance efficiency and output recovery speed.
Tankless Heater holds installed capacity. Hybrid Heater is rotating up the share rankings.
Technology:
Connectivity module integration separates specification tiers as buyers prioritize ecosystem alignment over standalone functionality.
- Wi-Fi Enabled:IEEE 802.11 protocol stacks enable remote scheduling, utility rate optimization, and demand-response program enrollment. Residential retrofits in Germany and the United States are mandating cloud-connected firmware for rebate eligibility under FERC-registered efficiency programs.
- Energy Monitoring:Embedded sensor arrays track consumption patterns and generate operational transparency dashboards. Commercial hospitality operators in California and Texas are specifying these modules for sustainability reporting compliance.
- Bluetooth Control:Local-device pairing without internet dependency suits privacy-sensitive installations.
- Smart Sensors:Thermistor arrays and flow detectors enable predictive fault detection and maintenance scheduling.
Wi-Fi Enabled dominates retrofit specification. Energy Monitoring is climbing the fastest as ESG disclosure requirements tighten.
End User:
Volume concentrates in residential replacement cycles, but margin accrues to commercial segments with operational transparency mandates.
- Residential:Single-family and multi-unit dwellings drive retrofit volumes through utility rebate programs and smart home ecosystem integration. Japan, Germany, and the United States are accelerating adoption as energy efficiency mandates tighten and electrical panel upgrades enable higher-kW installations.
- Hospitality:Hotels and resorts specify connected units for centralized energy management and guest experience customization. California and Texas premium properties are mandating operational dashboards for corporate sustainability reporting.
- Commercial:Office buildings and institutional facilities prioritize total cost of ownership over first cost.
- Healthcare:Hospitals and long-term care facilities require infection-control-rated enclosures and redundant temperature interlocks.
Residential commands unit volume. Hospitality is expanding most quickly among non-residential categories.
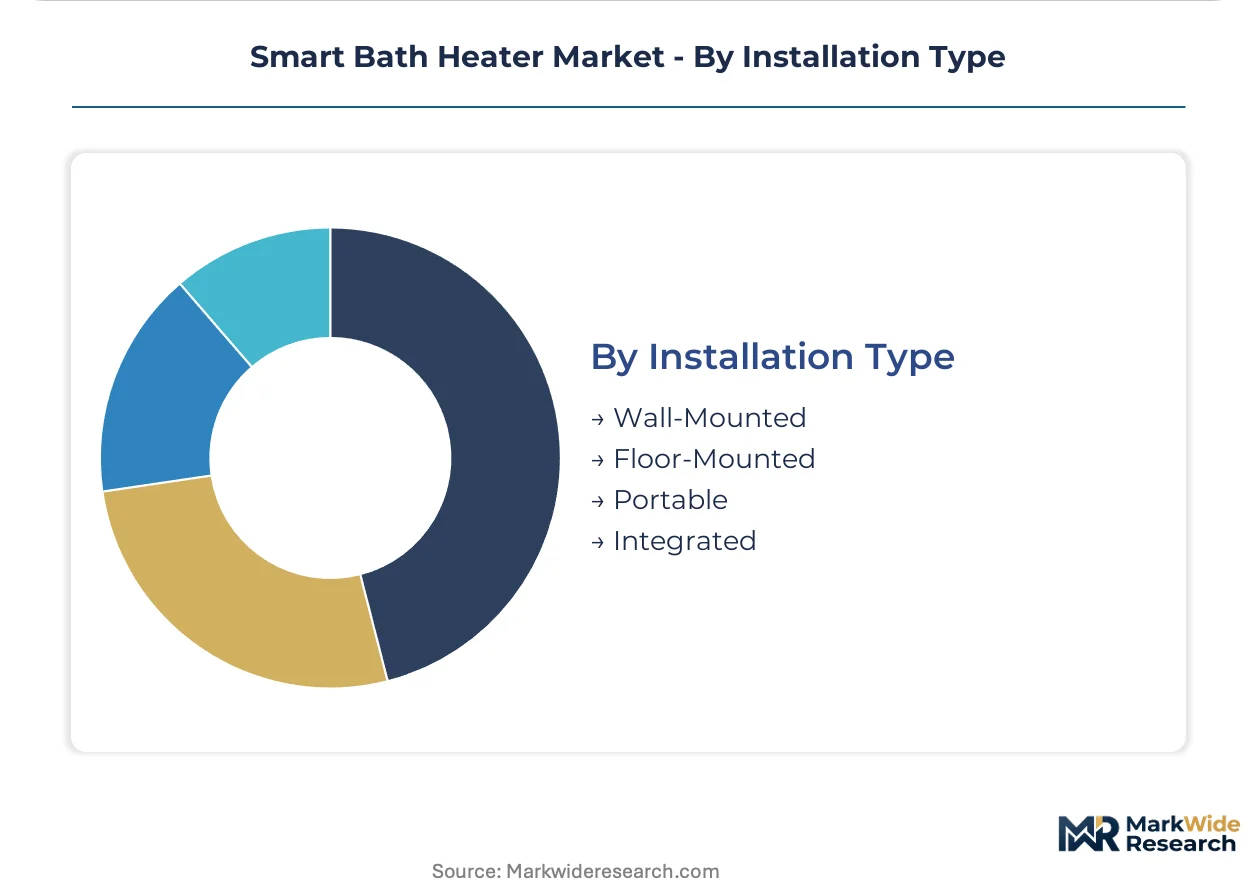
Installation Type:
Mounting configuration determines supply chain routing and installer certification requirements, with wall-mounted designs capturing retrofit economics.
- Wall-Mounted:Vertical enclosure mounting maximizes floor space in compact residential units and enables concealed plumbing routing. South Korea's metropolitan corridor and China's coastal provinces specify these configurations as standard in new apartment construction.
- Integrated:Architectural specification designs embed heating modules within vanity or shower wall assemblies. Kohler Co. anchors this segment through design-integrated installations in California premium housing clusters.
- Floor-Mounted:Freestanding tank assemblies suit utility room placement in single-family dwellings.
- Portable:Plug-and-play units without fixed plumbing connections serve temporary and rental applications.
Wall-Mounted dominates replacement volume. Integrated is gaining share fastest as architectural specification authority consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waterproof seal manufacturing clusters in Guangdong and Zhejiang provinces anchor supply-side capacity, while procurement authority fragments across utility rebate programs and smart home ecosystem mandates in Japan, Germany, and the United States.
China
Coastal provinces Jiangsu and Guangdong concentrate tankless retrofit volumes as apartment unit sizes shrink and standby loss intolerance rises. SAMR-administered GB standards for electrical appliance safety and energy efficiency labeling set baseline performance thresholds for domestic sales. Shenzhen and Hangzhou industrial corridors house IPX4 enclosure manufacturing clusters that create single-source vulnerability for ingress protection-rated housing assemblies.
Japan
Kanto region residential retrofits accelerate adoption as METI energy efficiency mandates tighten and electrical panel upgrades enable higher-kW installations. JIS standards compliance testing for wireless protocol stacks extends product launch windows. Tokyo metropolitan corridor demand clusters around compact form factors that eliminate standby thermal losses in constrained apartment footprints.
Germany
Pre-1990s residential panel ratings limit 9-12 kW instantaneous heater deployment without costly service upgrades. EU Ecodesign Directive and CE marking requirements enforced by national market surveillance authorities restrict imports failing minimum efficiency benchmarks. Bavaria and North Rhine-Westphalia drive heat pump-integrated specification as F-Gas Regulation phase-down schedules accelerate R&D investment in propane-based systems.
United States
California and Texas premium housing clusters mandate operational dashboards for corporate sustainability reporting, pulling embedded sensor arrays into specification requirements. FERC-registered efficiency programs mandate cloud-connected firmware for rebate eligibility. Sun Belt replacement cycles shift procurement authority toward contractor-facing platforms as homeowners prioritize space reclamation.
South Korea
Seoul-Incheon metropolitan corridor densification drives tankless retrofit volumes as electricity tariffs penalize idle consumption. MFDS-aligned safety certifications govern wet-environment electronics deployment. Newly built apartment complexes in Gyeonggi province exhibit ecosystem-locked purchase patterns that reject standalone app-controlled units.
Smart Bath Heater Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with appliance ecosystem bundlers occupying premium specification tiers while direct-to-consumer platforms capture volume through channel control. The vendor base stratifies across three tiers: integrated home appliance conglomerates, connected device specialists, and traditional plumbing fixture incumbents. Dominant competitive moves include ecosystem lock-in through HVAC control bundling and bypassing wholesale distribution through contractor-facing apps.
Within the integrated appliance tier, Haier Group and Xiaomi Inc. exemplify divergent channel strategies—Haier leveraging captive HVAC control ecosystems, Xiaomi anchoring direct-to-consumer online platforms. Kohler Co. occupies a position in the architectural specification segment where design-integrated installations command premium positioning. These three anchors illustrate how competitive advantage splits between ecosystem breadth, channel control, and specification authority.
| Leading Market Players |
|---|
| Haier Group |
| Xiaomi Inc. |
| AUPU |
| Canpro |
| Yeelight |
| Opple |
| Kohler Co. |
| Stiebel Eltron |
| Rheem Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
Propane-based refrigerant substitution for high-GWP alternatives is redrawing supplier geography toward German and Japanese compressor specialists while compressing margins on legacy electric resistance architectures that cannot capture green equipment subsidies.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure by mandating refrigerant-phase compliance costs that stratify offerings across premium heat pump-integrated, standard hybrid, and economy electric resistance levels. Price differentiation rests on Energy Star certification grade and IPX4 waterproof rating tier, with California hospitality operators showing least sensitivity due to ESG disclosure mandates while South Korean apartment developers exhibit highest cost consciousness. Pricing pressure intensifies in mid-tier tankless segments as copper and rare earth magnet input volatility squeezes OEM margins. Economy-tier buyers in China's coastal provinces resist premium positioning despite efficiency rebates.
Supply Chain Analysis
Inventory lead times for IPX4-rated enclosures stretch disproportionately during peak retrofit seasons due to waterproof seal manufacturing concentration in Guangdong and Zhejiang provinces. Supply draws from China for housing assemblies, Germany for heat pump compressors, and South Korea for control electronics. Raw material dependencies center on copper tubing, neodymium magnets, and flame-retardant polymers restricted under REACH. Single-source vulnerability in Guangdong seal production creates disruption exposure. Distribution runs through contractor-facing apps in the United States Sun Belt and traditional appliance wholesale channels in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installer certification scarcity for flammable refrigerant handling and heat pump refrigeration circuit repair is constraining deployment velocity, creating first-mover returns for capability-building investments.
For Market Incumbents: Secure captive supply of IPX4 enclosure assemblies through backward integration into Guangdong manufacturing clusters or long-term offtake agreements with Zhejiang seal specialists. Defend specification authority in California premium housing by accelerating multi-platform smart home certification beyond Apple HomeKit and Google Nest to capture ecosystem-locked buyers. Heat pump-integrated architectures from emerging appliance conglomerates threaten mid-tier positioning. For New Entrants and Emerging Players: Lead with direct-to-installer platform models targeting the United States Sun Belt replacement cycle, bypassing wholesale distribution to capture margin compression in contractor procurement. India's BIS energy efficiency labeling expansion offers the most penetrable white-space as mandatory star ratings create positioning for connected, high-COP designs absent entrenched competition. Channel control through contractor-facing apps enables rapid share capture without legacy distributor relationships. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated appliance conglomerates with captive HVAC ecosystems over standalone water heating specialists. Long-term viability hinges on heat pump refrigeration circuit capabilities and smart home platform certification breadth. Acquisition targets should demonstrate flammable refrigerant handling certification infrastructure and multi-protocol connectivity stacks. Watch F-Gas Regulation enforcement intensity in Germany and France as the inflection signal for refrigerant-transition investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Refrigeration Circuit Certification Buildout | Installer training infrastructure in Germany and Japan captures F-Gas Regulation subsidy flows. |
| Multi-Platform Smart Home Certification | Apple HomeKit and Google Nest alignment unlocks California premium housing specification authority. |
| Direct-to-Installer Platform Launch | Contractor-facing apps in Texas and Florida bypass wholesale margin extraction. |
| Backward Integration into IPX4 Enclosure Manufacturing | Guangdong and Zhejiang supply concentration creates single-source vulnerability for waterproof seals. |
| India BIS Star Rating First-Mover Positioning | Mandatory energy efficiency labeling creates uncontested entry window for connected designs. |
Research Methodology
A spread of perspectives from HVAC control system engineers, residential contractor network managers, hospitality facility directors, smart home platform integration specialists, and SAMR compliance officers converged on the working assumptions. Primary interviews combined with secondary validation against GB standards documentation, EU Ecodesign Directive enforcement records, FERC-registered efficiency program filings, and customs trade data for copper and rare earth magnet flows. Bottom-up unit shipment estimates triangulated against top-down energy efficiency mandate penetration models.
Segmentation dimensions modeled include product type architecture, connectivity protocol tier, end-use application, installation configuration, and regional regulatory cluster across the projection horizon. CAGRs derived from utility rebate program enrollment trajectories, apartment construction permit volumes in South Korea's Seoul-Incheon corridor, and heat pump subsidy allocation trends in Germany's Bavaria and North Rhine-Westphalia regions. Forecast inputs incorporated electrical panel upgrade rates in pre-1990s German and Japanese housing stock.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules, China's dual carbon goals enforcement, and Japan's METI efficiency mandate tightening; material policy shifts would require re-modeling. Heat pump refrigerant chemistry transitions and smart home protocol consolidation present specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Steamers Market
Household Items
Europe Handheld Fans Market
Household Items
Air Mattress Market
Household Items
Electric Shoe Polisher Market
Household Items
Aquarium Hydrometers Market
Household Items
United Kingdom Air Purifier Market
Household Items
Gas Hobs Market
Household Items
Washing Machine Cleaner Market
Household Items
Toilet Cistern Blocks Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
India Cookware Market
Household Items
Asean Cookware Market
Household Items
Can Opener Market
Household Items
North America Car Air Freshener Market
Household Items
Party Supplies Market
Household Items
Enameled Cookware Market