
 Thermos Drinkware Market | 2026-2036
Thermos Drinkware Market Size, Share, and Industry Trends Forecast 2026-2036
Thermos Drinkware Market Analytics
China is reshaping competitive dynamics in thermos drinkware through expanded stainless steel vacuum flask manufacturing capacity and integrated supply chains. Tiger Corporation leverages deep R&D heritage in vacuum insulation technology to sustain premium positioning across Asian retail channels. Stanley PMI anchors North American demand through heritage branding and controlled distribution in outdoor specialty retail. Hydro Flask competes on color customization and sustainability credentials, differentiating its recycled-steel product lines from commodity alternatives.
Thermos drinkware denotes vacuum-insulated or foam-insulated portable containers engineered to maintain beverage temperature through double-wall construction with evacuated airspace or polyurethane fill, typically achieving heat retention above 65°C after six hours. These vessels serve commercial and consumer markets requiring thermal stability for hydration, food transport, and beverage consumption away from fixed kitchen infrastructure. Stainless steel insulated bottles command the largest value pool due to durability premiums and replacement cycles, while tumblers represent the fastest-expanding category as office workers and commuters shift from disposable cups. Glass and plastic segments occupy lower-margin tiers where price sensitivity dominates student and mass-retail procurement decisions.
FDA food-contact material standards in the United States, EU REACH compliance for chemical migration in Europe, and China's GB national standards for stainless steel articles collectively govern material safety and market access across major demand centers. These frameworks elevate compliance costs for smaller manufacturers while creating specification advantages for certified producers serving institutional buyers. Stakeholders must monitor evolving extended producer responsibility mandates and single-use packaging restrictions, as regulatory expansion into circular economy obligations will reshape material sourcing and end-of-life collection requirements.
Market Dynamics
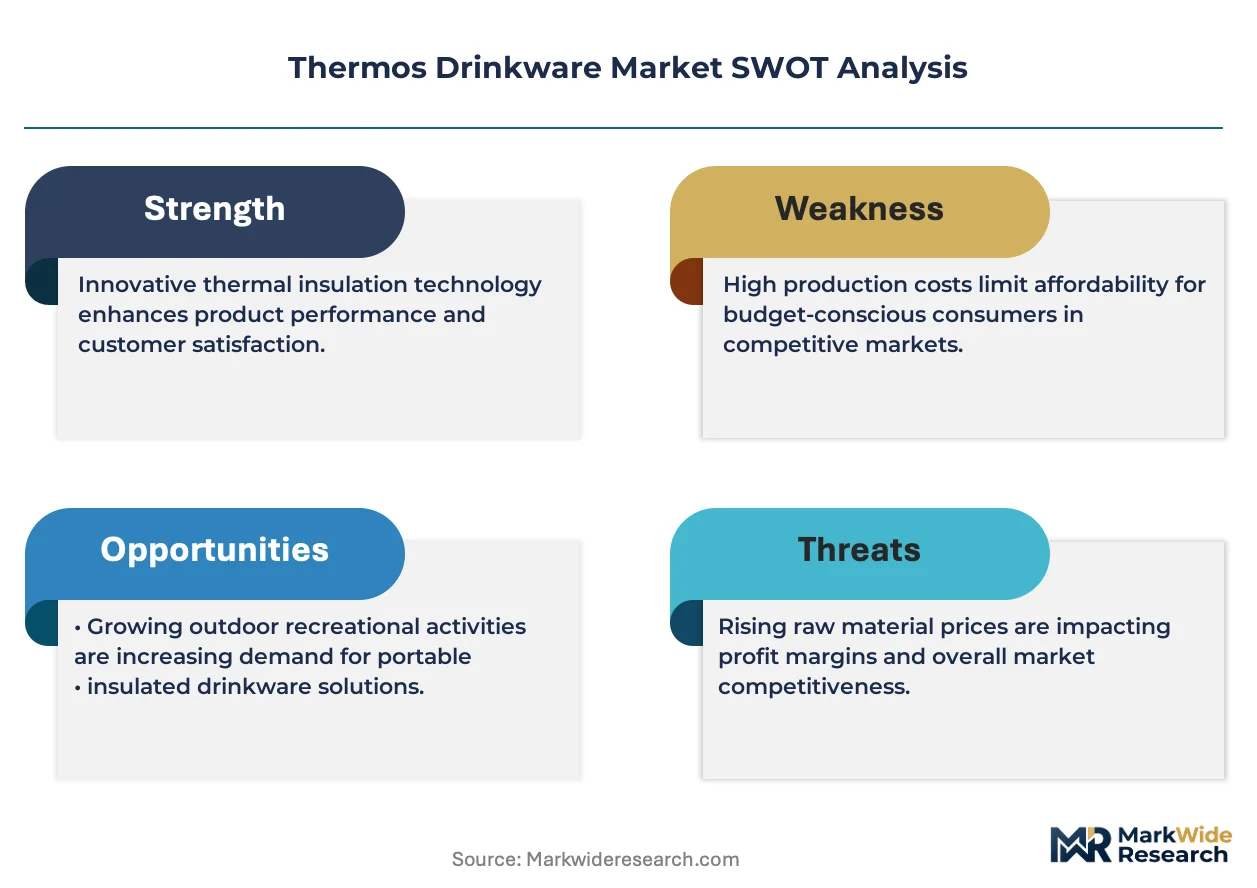
Stainless steel vacuum insulation technology is displacing single-wall construction across premium tiers, compressing replacement cycles and elevating material specifications for outdoor and commuter end-uses.
Growth Catalysts
- Adventure tourism participation:Outdoor enthusiasts represent an expanding buyer segment as hiking, camping, and expedition travel participation climbs across North American and European recreational markets.
- REACH chemical migration standards:EU compliance frameworks for food-contact materials elevate specification barriers, advantaging certified producers serving institutional procurement channels.
- Integrated manufacturing clusters:China's concentrated stainless steel processing and vacuum flask fabrication infrastructure compresses lead times and unit economics for export-oriented production.
Market Restraints
- Nickel and chromium price volatility:Stainless steel 304 and 316 input costs fluctuate with mining output and alloy demand from construction and automotive sectors.
- Single-wall commoditization:Low-margin plastic and aluminum alternatives dominate student and mass-retail procurement, constraining premium pricing power in price-sensitive tiers.
- Extended producer responsibility mandates:Emerging circular economy collection requirements in the European Union and select US states elevate end-of-life compliance burdens.
Strategic Opportunities
- India health-conscious consumption:Rising middle-class disposable income and temperature-control beverage preferences create underpenetrated demand for vacuum-insulated hydration products.
- Recycled steel certification:Sustainability-driven procurement policies in corporate and educational institutional channels reward verified recycled-content supply chains.
- Direct-to-consumer channel expansion:Brand-owned digital storefronts bypass wholesale margin compression and enable customization interfaces for color and capacity selection.
Industry Challenges
- Vacuum seal technician scarcity:Automated double-wall welding and evacuation chamber operation require specialized training unavailable in standard manufacturing labor pools.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and GB standard compliance testing extends product launch schedules by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermos Drinkware Market |
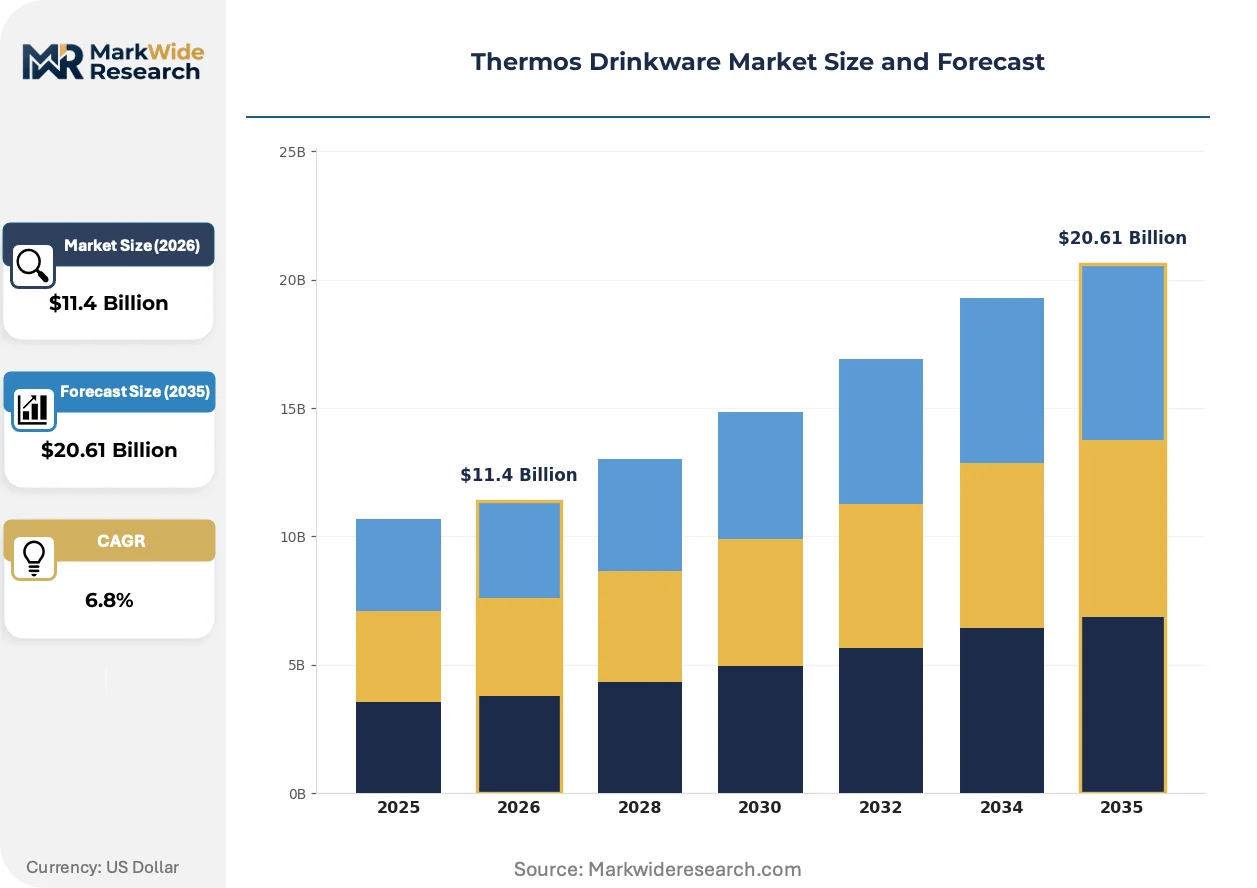
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Bottles, Travel Mugs, Tumblers, Food Jars Material: Stainless Steel, Glass, Plastic, Aluminum End User: Outdoor Enthusiasts, Office Workers, Students, Athletes Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Thermos L.L.C., Sigg Switzerland AG, Tiger Corporation, CamelBak Products, Zojirushi America Corporation, Stanley PMI, Hydro Flask, Klean Kanteen, YETI Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermos Drinkware Market Evolving Landscape
Material science advances and regulatory tightening are compressing traditional product lifecycles while opening premium positioning through verified sustainability credentials and performance differentiation.
Copper-lined vacuum insulation is rendering obsolete conventional air-gap construction in high-performance flasks. Serious outdoor users and temperature-critical applications like medical transport are adopting copper-doped double-wall designs. This thermal efficiency leap is compressing acceptable heat-retention thresholds and forcing mid-tier manufacturers toward specification upgrades or margin sacrifice.
EU REACH chemical migration restrictions are tightening allowable thresholds for heavy metal leaching from stainless steel food-contact surfaces. Manufacturers serving European institutional buyers must now document batch-level testing and supply chain material provenance. Premium producers with captive laboratory certification capabilities are capturing specification-driven procurement from healthcare and educational sectors.
Corporate sustainability officers are mandating recycled-content verification for branded merchandise and employee hydration programs. Distributors serving Fortune 500 procurement channels are consolidating supplier relationships around vendors with ISO 14001 environmental management and third-party recycled steel certification. This specification compression is visible most acutely in North American technology and financial services campus deployments.
Thermos Drinkware Market Segmentation
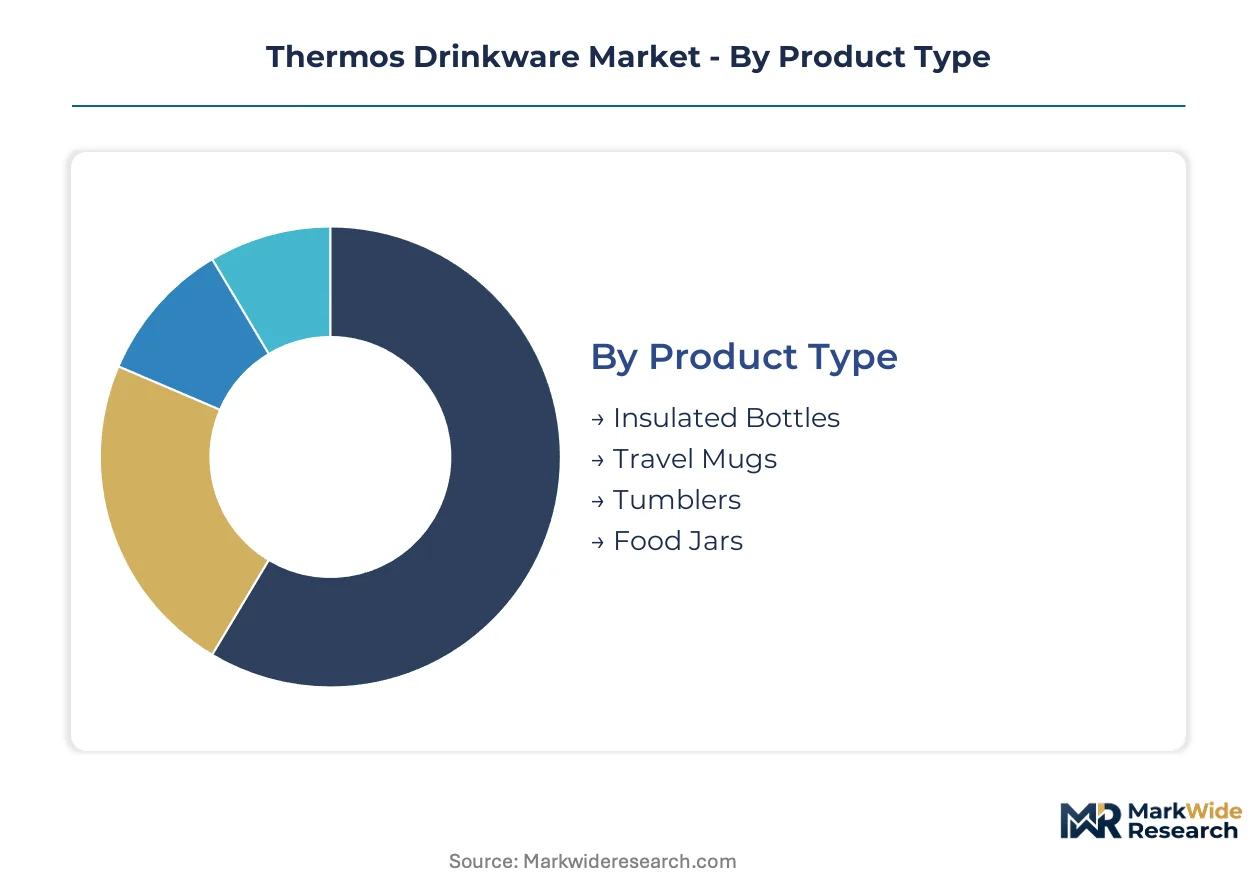
Thermos drinkware segmentation tracks divergent performance requirements across temperature-critical applications and material durability tiers. Category boundaries increasingly blur as hybrid-use products target commuters who alternate between office desks and weekend trails.
Product Type:
Cost tier stratification separates premium vacuum-insulated designs from mass-market single-wall alternatives across hydration, food transport, and beverage consumption use cases.
- Insulated Bottles:Double-wall vacuum construction with 304 or 316 stainless steel shells achieves heat retention above 65°C after six hours. Demand concentrates among outdoor enthusiasts and adventure tourists in China and the United States as hiking participation climbs. Replacement cycles compress as copper-lined thermal efficiency upgrades render older air-gap designs obsolete.
- Travel Mugs:Narrow-diameter vessels with leak-proof sealing mechanisms integrate with automotive cup holders and bicycle bottle cages. Office workers and commuters in Germany and Japan drive procurement as disposable cup restrictions tighten. One-handed operation and thermal stability specifications dominate institutional purchasing criteria.
- Tumblers:Wide-mouth open designs prioritize ice retention and ergonomic grip for stationary consumption. Athletes and home office workers in Australia favor capacity customization and color personalization options.
- Food Jars:Short-wide geometries with vacuum-insulated walls maintain meal temperatures for shift workers and students. School lunch programs in South Korea and corporate catering contracts in Singapore sustain volume procurement.
Insulated bottles command the established base. The steepest expansion runs through tumblers.
Material:
Application severity dictates material selection, with thermal performance, impact resistance, and chemical migration compliance forming the selection matrix.
- Stainless Steel:304 and 316 austenitic grades dominate premium tiers through corrosion resistance and FDA/REACH/GB multi-jurisdiction compliance. Outdoor enthusiasts and medical transport operators in the United States and European Union specify batch-level material provenance documentation. Nickel and chromium price volatility compresses margin buffers for mid-tier fabricators.
- Glass:Borosilicate and soda-lime constructions with silicone sleeves serve health-conscious consumers avoiding metallic taste perception. Office workers in France and Italy favor aesthetic transparency for desk-visible hydration. Fragility constraints limit expedition and athletic deployment.
- Plastic:Polypropylene and Tritan copolyester occupy student and mass-retail price tiers where unit economics dominate specification. India's educational procurement channels and Southeast Asian convenience store distribution sustain volume.
- Aluminum:Single-wall drawn construction with polymer linings serves cycling and ultralight backpacking weight minimization. European specialty outdoor retailers in Switzerland and Austria stock limited seasonal assortments.
Stainless steel anchors the value pool. Glass gains share fastest among design-conscious urban consumers.
End User:
Customer type segmentation isolates divergent durability requirements, thermal performance thresholds, and brand sensitivity across recreational, professional, and educational contexts.
- Outdoor Enthusiasts:Expedition-grade vacuum insulation with impact-resistant finishes withstands alpine, desert, and marine environments. Adventure tourism growth in Canada and New Zealand drives premium replacement cycles. Copper-lined thermal efficiency upgrades command price premiums for temperature-critical medical and scientific fieldwork.
- Office Workers:Aesthetic customization and desk-friendly footprints dominate procurement as corporate sustainability programs mandate reusable alternatives to disposable cups. Technology and financial services campuses in the United States specify recycled-steel certification for branded merchandise.
- Students:Price elasticity dominates as educational procurement channels and parent purchasing prioritize unit cost over thermal performance. Mass retailers in Brazil and Mexico stock seasonal color rotations.
- Athletes:Hydration volume, ergonomic grip geometry, and rapid-access cap mechanisms serve training and competition contexts. Team sports programs in the United Kingdom and institutional athletics departments in Japan drive volume tenders.
Outdoor enthusiasts anchor premium positioning. Office workers represent the most rapidly expanding specification tier.
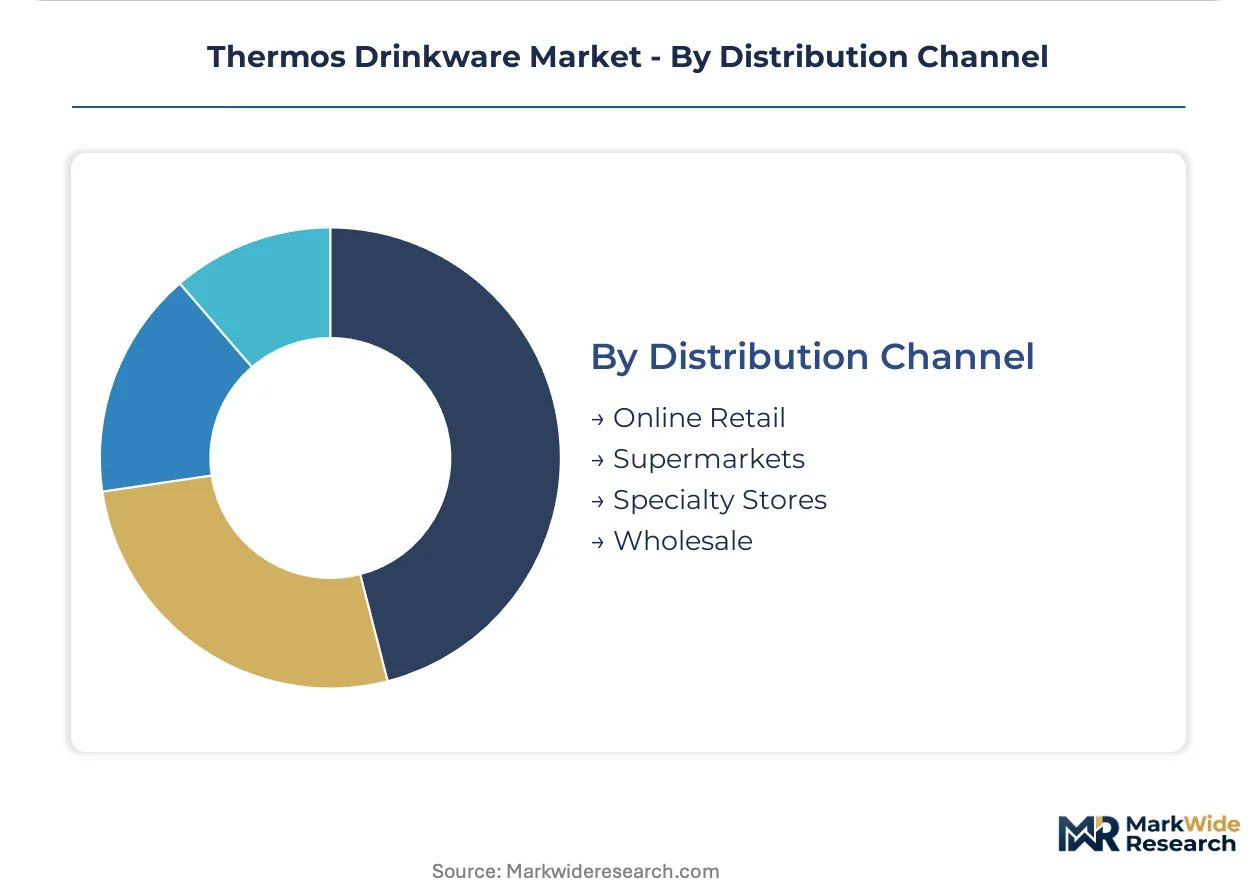
Distribution Channel:
Supply concentration varies dramatically across channel types, with direct-to-consumer capabilities compressing wholesale margin structures while specialty retail sustains premium positioning.
- Online Retail:Brand-owned digital storefronts and marketplace platforms enable customization interfaces for color and capacity selection. Direct-to-consumer expansion in the United States and China bypasses wholesale margin compression.
- Supermarkets:Mass-market velocity drives seasonal promotional cycles and private-label penetration. Price-sensitive student and family procurement in India and Indonesia concentrates here.
- Specialty Stores:Outdoor, cycling, and coffee equipment retailers sustain premium positioning through staff expertise and tactile evaluation. Heritage brands in Japan and Germany defend shelf space through controlled distribution.
- Wholesale:Institutional procurement channels for corporate campuses, educational systems, and healthcare facilities require volume pricing and certification documentation. North American technology sector sustainability mandates consolidate supplier relationships.
Specialty stores command premium price realization. Online retail climbs fastest as customization interfaces mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel vacuum flask fabrication clusters in Guangdong and Zhejiang provinces supply export-oriented brands worldwide. Manufacturing density in these coastal regions compresses lead times and unit economics for international distributors.
United States
Adventure tourism participation climbs across Colorado and Pacific Northwest trail systems, elevating demand for expedition-grade thermal retention. FDA food-contact material standards govern stainless steel surface chemistry for institutional procurement channels. Austin and Denver outdoor specialty retailers sustain premium positioning through heritage brand distribution.
China
Rising health-conscious consumption in Shanghai and Beijing metropolitan areas drives replacement of disposable cups with vacuum-insulated alternatives. GB national standards for stainless steel articles regulate material migration thresholds for domestic and export markets. Yongkang city in Zhejiang province anchors global vacuum flask manufacturing through integrated steel processing and double-wall welding infrastructure.
Germany
Office workers in Berlin and Munich corporate campuses shift from disposable coffee cups under sustainability procurement mandates. EU REACH compliance frameworks elevate specification barriers for heavy metal leaching documentation. Hamburg and Frankfurt distribution hubs consolidate wholesale relationships serving European institutional buyers.
Japan
Commuter culture in Tokyo and Osaka sustains demand for leak-proof travel mugs integrating with public transit consumption patterns. METI energy efficiency guidelines influence thermal performance benchmarking for domestic brands. Osaka-based R&D clusters advance copper-lined vacuum insulation technology for temperature-critical applications.
India
Rising middle-class disposable income in Mumbai and Bangalore creates underpenetrated demand for vacuum-insulated hydration products. FSSAI food safety standards govern material contact surfaces for educational and corporate procurement channels. Gujarat and Tamil Nadu manufacturing zones develop assembly capacity for price-sensitive student and mass-retail tiers.
Thermos Drinkware Market Competitive Landscape
Heritage specialists and outdoor-equipment diversifiers split the market across premium positioning vectors. Concentration remains moderate with tiered competition separating certified institutional suppliers from mass-market fabricators. Three archetypes dominate: Japanese R&D-heritage vacuum insulation specialists, North American outdoor-brand diversifiers, and Chinese integrated manufacturers serving private-label and export channels. Competitive moves center on recycled-steel certification acquisition and direct-to-consumer channel expansion.
Among Japanese heritage specialists, Tiger Corporation and Zojirushi America Corporation exemplify sustained premium positioning through controlled distribution in Asian and North American retail channels. Stanley PMI occupies a position within the outdoor-equipment archetype, leveraging heritage branding in specialty retail. Chinese integrated manufacturers including Thermos L.L.C. represent scale-driven supply consolidation for global brand licensing and private-label production.
| Leading Market Players |
|---|
| Thermos L.L.C. |
| Sigg Switzerland AG |
| Tiger Corporation |
| CamelBak Products |
| Zojirushi America Corporation |
| Stanley PMI |
| Hydro Flask |
| Klean Kanteen |
| YETI Holdings |
| Others |
Value Network & Pricing Analysis
Yongkang city in Zhejiang province anchors global vacuum flask manufacturing through integrated stainless steel processing and double-wall welding infrastructure, compressing unit economics for export-oriented brands while elevating pricing power for certified producers serving institutional procurement channels. Nickel and chromium price volatility in austenitic steel grades feeds downstream cost compression, forcing mid-tier fabricators toward margin sacrifice or specification downgrade.
Pricing Analysis
FDA food-contact material standards dictate the pricing tier structure across North American institutional channels, separating premium-mid-economy pricing differentiation based on batch-level certification documentation and laboratory testing capabilities. Brand heritage and recycled-steel verification command price premiums in corporate sustainability procurement, while student and mass-retail segments exhibit highest price sensitivity. Cost compression in aluminum and plastic single-wall alternatives intensifies pricing pressure at the commodity tier.
Supply Chain Analysis
Export control regimes on advanced welding and vacuum evacuation equipment limit technology transfer to emerging manufacturing zones, concentrating precision fabrication capacity in Chinese coastal provinces and Japanese R&D clusters. The supply chain draws from Indonesian nickel ore, South African chromium, and domestic Chinese stainless steel mills, creating tariff exposure on raw material flows. Distribution runs through brand-owned digital storefronts and outdoor specialty retailers with controlled shelf access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermos drinkware market fragmentation creates entry niches as adventure tourism participation diversifies performance requirements across expedition-grade, commuter, and institutional use cases. Demand-side specialization rewards targeted positioning over broad portfolio plays.
For Market Incumbents: Harden premium positioning through captive laboratory certification capabilities for FDA, REACH, and GB multi-jurisdiction compliance, defending against emerging Chinese integrated manufacturers with scale-driven private-label penetration. Deepen backward integration into recycled steel supply chains to meet corporate sustainability officer mandates.
For New Entrants and Emerging Players: India's underpenetrated vacuum-insulated hydration market offers white-space expansion as rising middle-class disposable income meets health-conscious consumption patterns. Target student and mass-retail price tiers through Gujarat and Tamil Nadu assembly partnerships, leveraging local distribution relationships against import-dependent incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory tightening across REACH, FDA, and GB standards consolidates procurement relationships around verified producers. Monitor extended producer responsibility mandate adoption in European Union member states as inflection signal for circular economy compliance investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Steel Certification Acquisition | ISO 14001 and third-party verification unlock Fortune 500 campus procurement mandates. |
| Direct-to-Consumer Channel Expansion | Brand-owned digital storefronts bypass wholesale margin compression in North America. |
| Copper-Lined Thermal Efficiency Upgrade | Copper-doped double-wall designs capture medical transport and scientific fieldwork premiums. |
| India Manufacturing Footprint Establishment | Gujarat assembly capacity addresses price-sensitive student and mass-retail tiers. |
| Specialty Retail Distribution Control | Heritage brand shelf access in outdoor and cycling retailers sustains premium positioning. |
Research Methodology
The analysis maps insulated bottles, travel mugs, tumblers, and food jars, each validated through plant managers at stainless steel fabricators, procurement leads at outdoor specialty retailers, brand managers at heritage vacuum insulation specialists, and supply planners at mass-market distributors. Primary fieldwork combined with secondary validation from customs records, SEC 10-K filings, and GB standard certification databases enabled bottom-up and top-down triangulation across the analysis window.
Forecasts assume stable regulatory enforcement intensity across FDA, REACH, and GB frameworks, with nickel and chromium price volatility held within historical bands. Segmentation dimensions modeled include product type, material grade tier, end-user archetype, and distribution channel complexity. CAGRs derived from installed base replacement cycles and penetration rate trajectories in underdeveloped geographies, with copper-lined thermal efficiency upgrade adoption and recycled-content verification serving as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese integrated manufacturers or accelerated extended producer responsibility mandates in European Union member states would shift outcomes. Material shifts in nickel mining output or alloy demand from automotive electrification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Fridge Market
Household Items
Household Sewing Machines Market
Household Items
Global Electric Scissors Market
Household Items
Electric Soap Dispenser Market
Household Items
Dishwashing Products Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
US Air Fresheners Market
Household Items
Non-Stick Cookware Market
Household Items
US Digital Showers Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Range Hood Cleaning Service Market
Household Items
Portable Showers Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Compressed Tablet Towel Market
Household Items
Knife Set Market