
 Sanitary Metal Ware Market | 2026-2036
Sanitary Metal Ware Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Metal Ware Market Analysis
Specialty plumbing distributors is reconfiguring how sanitary metal ware reaches end buyers across fragmented construction supply chains. Kohler leverages captive showrooms in major metropolitan corridors to control specification decisions at the architect level. Grohe sustains German-engineered positioning through in-house brass forging operations that limit third-party alloy variability. Moen competes on rapid fulfillment velocity, stocking brushed nickel and matte black finishes for same-day contractor pickup.
Sanitary metal ware encompasses precision-cast and machined fixtures including faucets, sinks, bathtubs, and showerheads fabricated from brass, stainless steel, bronze, or copper alloys with specified lead-content thresholds and flow-rate performance parameters, designed to deliver potable water distribution and drainage in built environments. Brass material grades dominate specification sheets for faucet bodies due to machinability and corrosion resistance, though stainless steel sinks command premium positioning in residential kitchen renovations. The residential application segment anchors volume throughput across multi-unit housing developments, while healthcare applications impose stricter surface-finish protocols that concentrate margin pools among polished and coated antimicrobial treatments.
EPA lead-free requirements under the Safe Drinking Water Act and NSF/ANSI 61 certification standards govern alloy composition and chemical leaching thresholds for potable water contact surfaces in the United States, while REACH restrictions in Europe limit certain plating chemistries and drive substitution toward physical vapor deposition finishes. China's SAMR enforces GB standards for water-efficiency labeling that filter market access for imported fixture assemblies. Stakeholders must monitor diverging regional material restrictions and efficiency mandates when configuring alloy sourcing and finish portfolios for cross-border product lines.
Market Dynamics
Water-efficiency mandates across major economies are compressing product development cycles and forcing alloy reformulation in brass forging operations, while hospitality renovation waves in Asia-Pacific accelerate specification turnover for premium fixture portfolios.
Growth Catalysts
- GB Standards Tightening:China's SAMR water-efficiency labeling requirements are filtering market access for imported fixture assemblies and driving domestic manufacturers toward certified low-flow designs.
- Hospitality Renovation Cycles:Asia-Pacific hotel refurbishment programs are accelerating replacement demand for premium-grade faucets and shower systems with antimicrobial surface treatments.
- Brass Alloy Machinability:Lead-free copper-zinc formulations meeting NSF/ANSI 61 thresholds enable precision casting for complex faucet geometries without post-machining correction.
Market Restraints
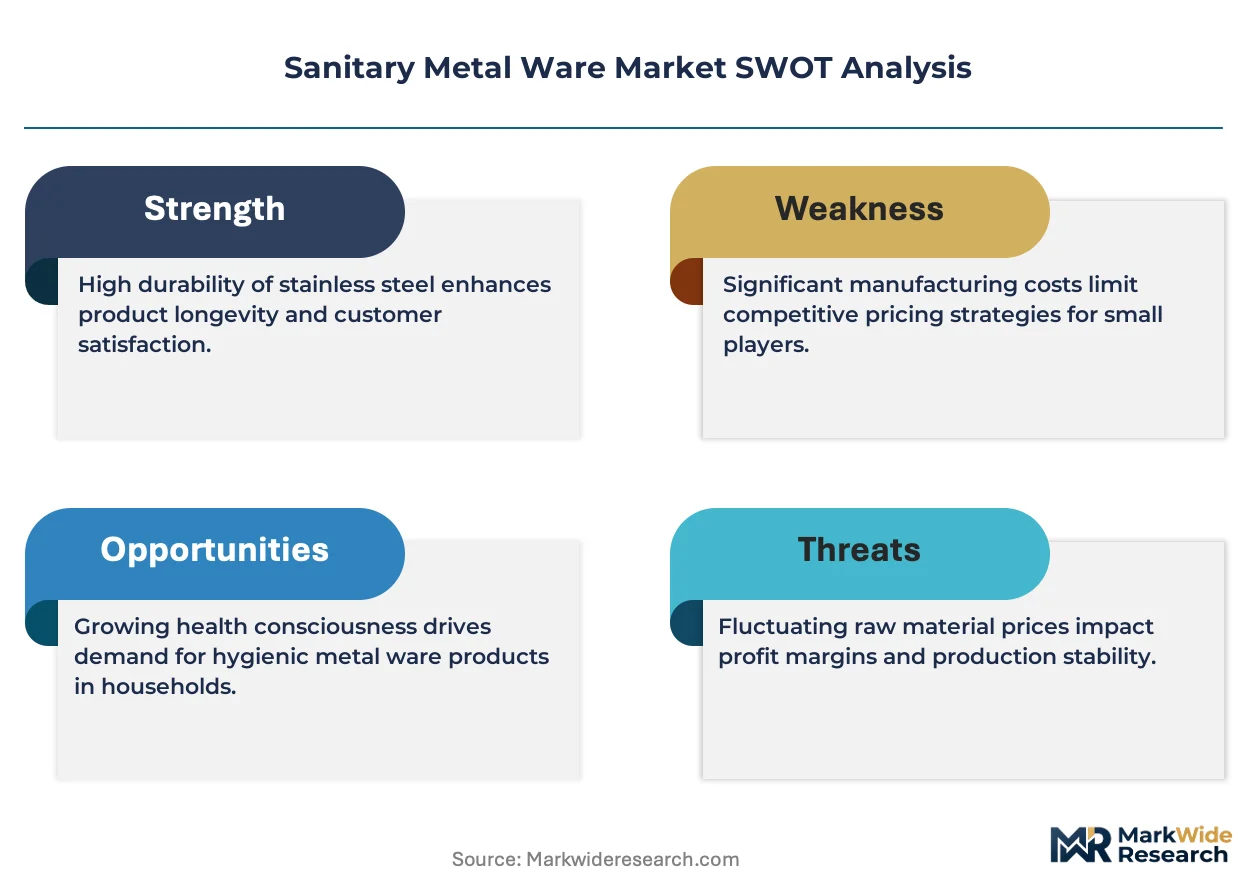
- Copper Price Volatility:Brass billet costs fluctuate with London Metal Exchange copper benchmarks, compressing margin buffers for mid-tier forging operations.
- REACH Plating Restrictions:ECHA limitations on hexavalent chromium chemistries force capital-intensive retooling toward physical vapor deposition finish lines.
- Regional Certification Fragmentation:Divergent potable water contact standards between EPA Safe Drinking Water Act requirements and European drinking water directives inflate compliance overhead for cross-border product lines.
Strategic Opportunities
- India Urban Residential Towers:Mumbai and Bangalore developers specify imported European faucet designs, creating specification pull for premium foreign brands in mid-rise construction.
- Sensor-Enabled Faucet Convergence:Integration of infrared proximity detection with ceramic disc valve technology opens healthcare and food-service applications requiring touchless operation.
- Green Building Certification Tailwinds:LEED and BREEAM point systems for water conservation incentivize specification of high-efficiency fixtures in commercial new-build projects.
Industry Challenges
- CNC Programming Talent Scarcity:Five-axis machining of complex faucet bodies requires specialized CAM operators, constraining output scaling for precision metalware foundries.
- Dual Certification Timelines:Simultaneous pursuit of EPA lead-free compliance and European drinking water approvals extends product launch windows by twelve to eighteen months.
- Antimicrobial Coating Integration:Embedding copper-ion or silver-based surface treatments into existing plating lines demands process revalidation without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Metal Ware Market |
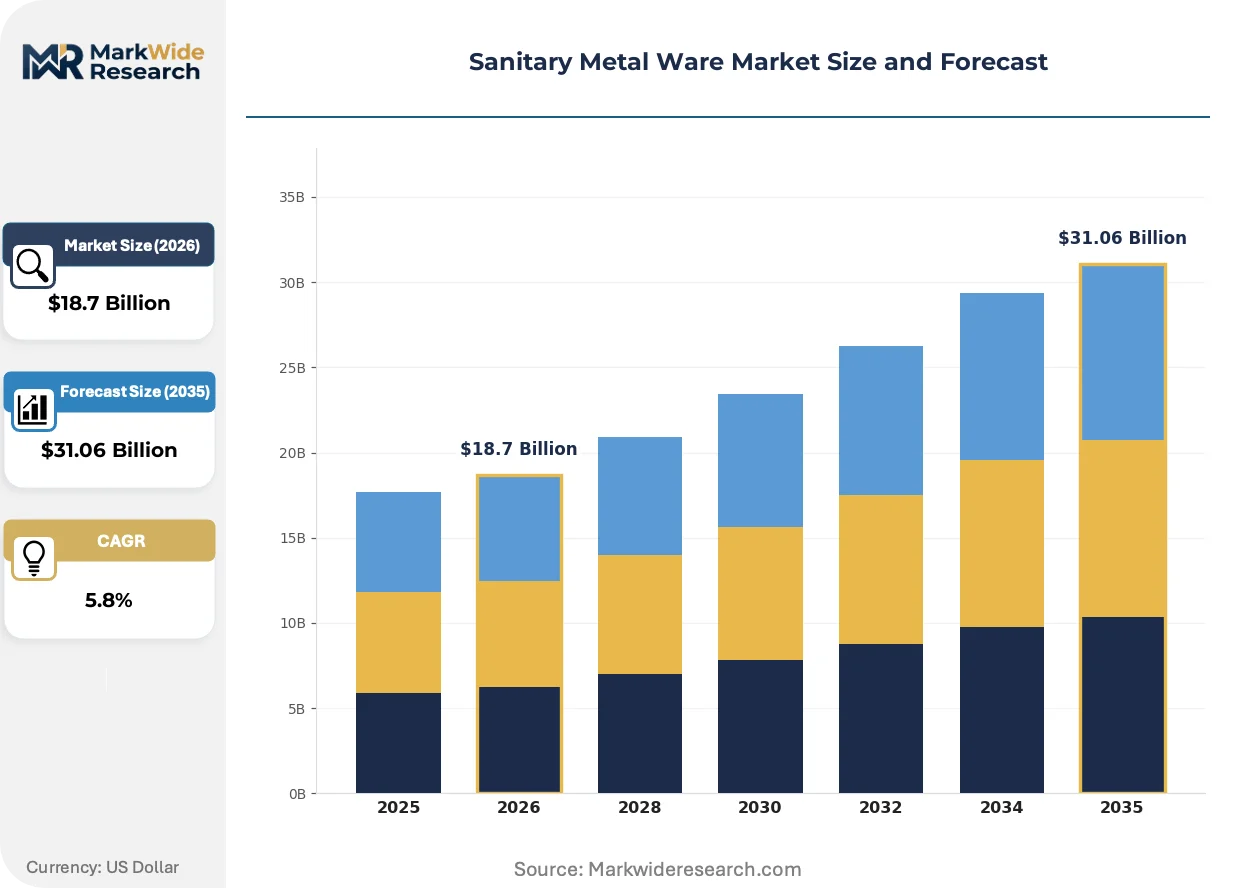
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faucets, Sinks, Bathtubs, Showerheads Material: Stainless Steel, Brass, Bronze, Copper Application: Residential, Commercial, Industrial, Healthcare Finish Type: Polished, Matte, Brushed, Coated |
| Companies Covered | Kohler, Moen, Grohe, TOTO, Hansgrohe, American Standard, Roca, Delta Faucet, Villeroy & Boch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Metal Ware Market Emerging Trajectories
Digital manufacturing workflows and surface treatment chemistry shifts are compressing traditional development timelines while reshaping how specification decisions flow through architect and contractor channels.
Additive manufacturing of sand-printed molds for brass casting is rendering obsolete conventional wooden pattern production for low-volume custom faucet designs. Boutique hospitality developers in Dubai and Singapore specify one-off geometries for signature properties. Lead times for prototype castings compress from six weeks to seventy-two hours, enabling specification decisions closer to construction mobilization.
REACH restrictions on nickel release rates are forcing substitution toward PVD titanium-nitride finishes for high-end residential kitchen faucets. German and Italian manufacturers retrofit existing electroplating lines with vacuum deposition chambers. The transition concentrates margin pools among capitalized suppliers capable of dual-finish capability, squeezing smaller plating houses dependent on traditional chrome.
Specification decisions increasingly bypass wholesale distributors through direct architect-showroom relationships. Kohler and Grohe operate captive specification centers in London, Shanghai, and Manhattan where designers configure assemblies digitally. Contractor procurement through traditional plumbing supply houses faces margin compression as project owners negotiate direct fixture supply agreements with manufacturers.
Sanitary Metal Ware Market Segmentation
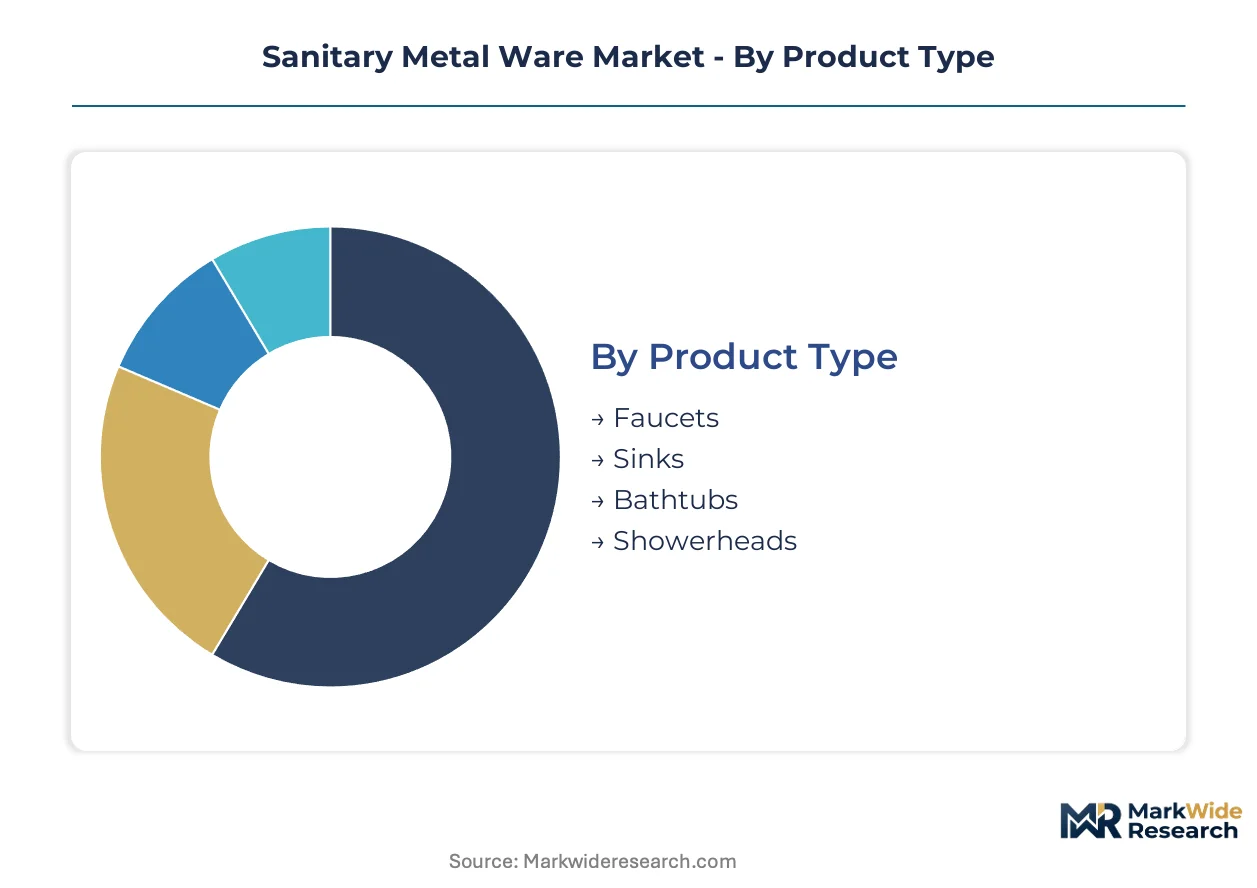
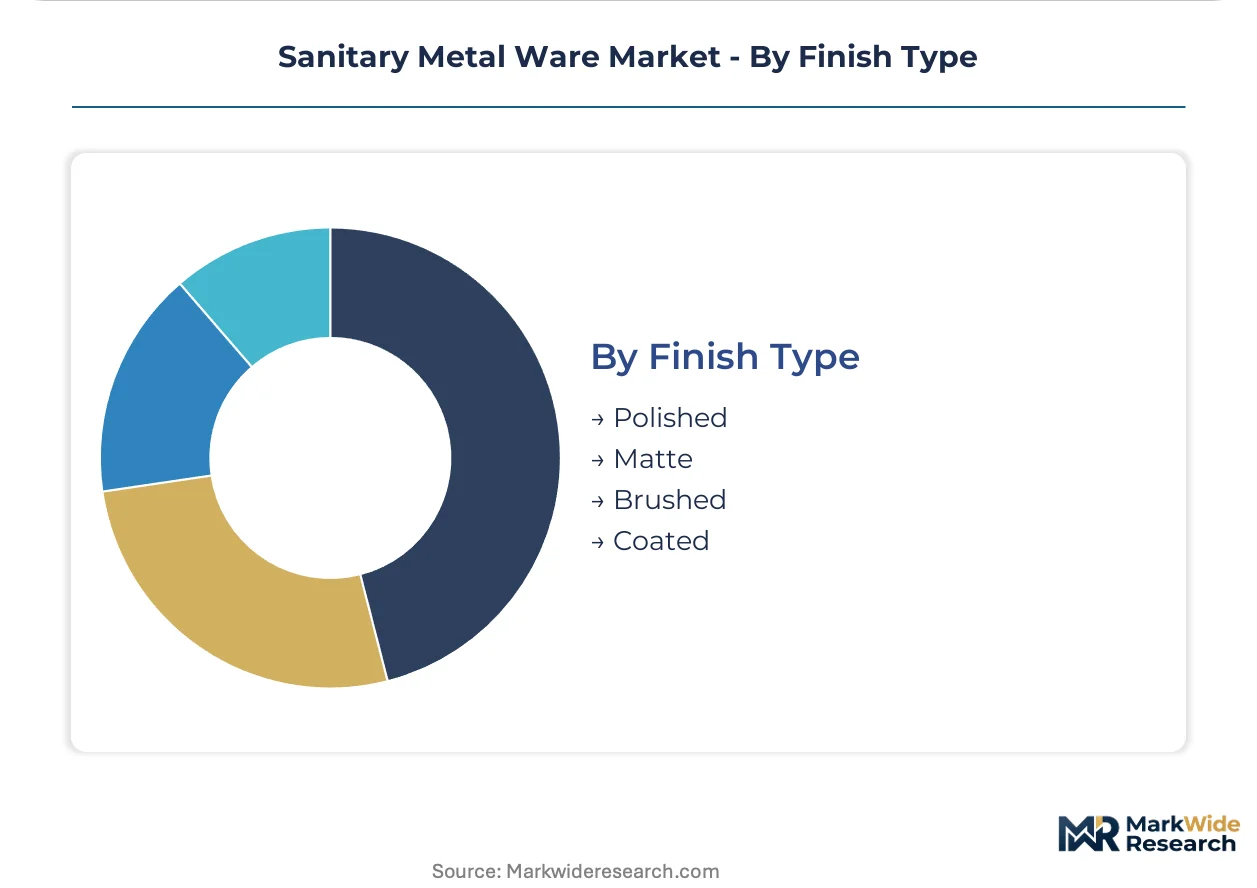
Sanitary metal ware segmentation reveals divergent margin structures across material grades and specification channels. Product architects configure alloy portfolios and finish specifications to match distinct end-use performance thresholds and regulatory contact requirements.
Product Type:
Mature fixture categories dominate specification volumes while emerging configurations reshape hospitality and healthcare procurement.
- Faucets:Precision-cast brass bodies with ceramic disc cartridges govern potable water distribution at point-of-use. Multi-unit residential towers in Mumbai and Bangalore specify European-imported single-lever designs with low-flow aerators meeting GB water-efficiency labeling.
- Sinks:Deep-drawn stainless steel bowls with sound-dampening undercoating anchor residential kitchen renovations. Premium gauge 16-18 steel commands specification in high-rise developments where developer brand positioning drives fixture selection.
- Bathtubs:Enamel-coated cast iron and acrylic-reinforced composites serve luxury hospitality refurbishment cycles across Asia-Pacific.
- Showerheads:Engineered spray-face geometries with integrated flow restrictors respond to tightening efficiency mandates in multiple jurisdictions.
Faucets retain volume leadership; showerheads hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity alloy sourcing from certified low-lead formulations required for potable water contact.
- Brass:Copper-zinc alloys with controlled lead content below NSF/ANSI 61 thresholds enable precision machining for complex faucet geometries. Forging operations in Germany and Italy maintain captive billet supply to limit London Metal Exchange copper volatility exposure.
- Stainless Steel:Austenitic 304 and 316 grades deliver corrosion resistance for sinks and healthcare applications requiring frequent sterilization cycles. Indian urban residential towers specify brushed 304 finishes for kitchen environments.
- Bronze:Copper-tin formulations with superior seawater resistance serve coastal hospitality properties and marine-adjacent developments.
- Copper:Pure alloy antimicrobial surfaces gain traction in healthcare specification sheets requiring EPA-registered infection control properties.
Brass commands the widest specification footprint; copper surfaces are climbing fastest on antimicrobial demand.
Application:
Customer type fragmentation separates bulk procurement for volume housing from specification-driven premium segments.
- Residential:Multi-unit housing developments drive throughput for standardized faucet and sink configurations with builder-grade finishes. Developers in India specify imported European designs for mid-rise towers targeting affluent urban buyers.
- Commercial:Office and retail fit-outs prioritize durability and standardized maintenance protocols across portfolio properties.
- Industrial:Heavy-duty brass and stainless fixtures withstand chemical exposure and high-frequency use in manufacturing environments.
- Healthcare:Antimicrobial surface treatments and touchless sensor integration impose strict finish protocols that concentrate margin pools among certified suppliers.
Residential anchors absolute volume; healthcare delivers the highest margin realization per fixture.
Finish Type:
Supply concentration in plating operations creates differentiation bottlenecks as REACH restrictions force chemistry transitions.
- Polished:Mirror-finish chrome and nickel plating traditionally dominated premium specification, though hexavalent chromium restrictions under ECHA mandates are forcing process retooling.
- Matte:Low-sheen PVD titanium-nitride and black oxide finishes respond to contemporary residential kitchen aesthetics in North American and European markets.
- Brushed:Directional surface texture on stainless steel and brass conceals water spotting and wear patterns in high-traffic commercial environments.
- Coated:Epoxy and powder-coat layers enable color matching for hospitality brand standards and custom architectural specifications.
Polished finishes retain legacy specification share; matte treatments are expanding most quickly on PVD technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR water-efficiency labeling mandates are filtering import access and accelerating domestic certification upgrades across brass forging operations. Germany maintains precision-engineering dominance through captive alloy supply chains. India's urban residential construction specifies European-imported fixtures for premium tower developments. United States EPA lead-free enforcement under the Safe Drinking Water Act governs potable water contact surfaces. Japan's METI efficiency standards drive sensor-integrated faucet adoption in commercial retrofits.
China
Multi-unit residential towers in Shanghai and Shenzhen specify low-flow aerators meeting GB water-efficiency labeling requirements. SAMR certification filters market access for imported fixture assemblies. Domestic manufacturers in Zhejiang and Guangdong provinces are retooling forging lines toward certified brass formulations.
Germany
Healthcare and hospitality specification sheets prioritize PVD titanium-nitride finishes responding to ECHA nickel release restrictions. ECHA REACH limitations on hexavalent chromium chemistries force vacuum deposition adoption. Engineering clusters in North Rhine-Westphalia and Bavaria maintain captive brass billet supply to limit copper price volatility exposure.
India
Mumbai and Bangalore developers specify imported European single-lever faucet designs for mid-rise residential towers targeting affluent urban buyers. BIS standards for water efficiency are tightening parallel to GB benchmarks. Fabrication activity concentrates in Gujarat and Maharashtra with domestic forging operations scaling toward export-grade certification.
United States
Commercial new-build projects specify high-efficiency fixtures to capture LEED water conservation points. EPA Safe Drinking Water Act lead-free requirements govern alloy composition for potable water contact surfaces. Distribution clusters in the Midwest and Southeast serve contractor procurement channels with same-day fulfillment velocity.
Japan
Commercial restroom retrofits integrate infrared proximity detection with ceramic disc valve technology for touchless operation. METI efficiency standards compress flow-rate parameters for public facility upgrades. Manufacturing concentration in the Chubu region around Nagoya serves precision casting requirements for complex faucet geometries.
Sanitary Metal Ware Market Vendor Landscape
On the supply side, the industry is tiered between integrated European engineering houses, North American mass-market fabricators, and Asian-scale forging operations. Three strategic archetypes dominate: premium German-engineered positioning through in-house alloy control, rapid fulfillment velocity via regional distribution density, and specification capture through captive architect showroom networks. Competitive moves concentrate on dual-finish capability expansion and direct procurement channel bypass of traditional plumbing distributors.
Among German-engineered specialists, Grohe and Hansgrohe occupy the precision-forging tier with captive brass operations that limit third-party alloy variability. Kohler anchors the North American premium specification vector through metropolitan showroom networks controlling architect-level decisions. These three exemplify how geographic origin and distribution architecture separate margin pools across the competitive landscape.
| Leading Market Players |
|---|
| Kohler |
| Moen |
| Grohe |
| TOTO |
| Hansgrohe |
| American Standard |
| Roca |
| Delta Faucet |
| Villeroy & Boch |
| Others |
Supply Flow & Price Mechanics
Zhejiang forging clusters in eastern China anchor global brass billet processing capacity, concentrating upstream supply power among domestic manufacturers retooling toward GB water-efficiency certification. This geographic concentration translates into asymmetric pricing leverage for certified low-lead alloy suppliers serving premium specification channels in India and Southeast Asia.
Pricing Analysis
Certification level creates the primary spread between commodity brass fixtures and NSF/ANSI 61-compliant assemblies for potable water contact. Three-tier pricing structure across premium PVD-finish, standard electroplated, and economy-grade builder fixtures separates margin pools. Cost compression in mid-tier forging operations is intensifying because London Metal Exchange copper volatility erodes buffer margins. Bulk procurement teams at Indian residential developers exhibit highest price sensitivity, while healthcare specification committees prioritize antimicrobial surface protocols over unit economics.
Supply Chain Analysis
Export-control regimes on precision CNC equipment from Germany and Japan limit five-axis machining capacity expansion in emerging forging operations. Supply concentrates in China, Germany, and India for brass casting and finish processing. Brass billet, ceramic disc cartridges, and PVD coating chemicals constitute critical input dependencies. Single-source vulnerability concentrates in German-engineered valve component suppliers. Distribution runs through specialty plumbing distributors facing margin compression from direct manufacturer-architect showroom relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification requirements for potable water contact surfaces create switching costs that protect incumbent positions against unqualified challengers.
For Market Incumbents: Build captive brass billet supply chains to insulate margin structures from London Metal Exchange volatility. Deepen specification control through metropolitan showroom networks that capture architect-level decisions before contractor procurement channels activate. Sensor-integrated faucet technology from emerging Asian competitors threatens premium positioning; accelerate touchless product line development to maintain specification leadership. For New Entrants and Emerging Players: Pursue white-space opportunities in India's urban residential tower segment where European-imported designs command specification premiums among Mumbai and Bangalore developers. Target antimicrobial surface treatment integration for healthcare applications requiring EPA-registered infection control properties. Establish direct procurement relationships with mid-rise construction owners to bypass entrenched plumbing distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fragmented domestic forging operations in China and India lack scale for dual-certification compliance across EPA and European drinking water directives. Acquisition targets include mid-cap specialists with captive PVD finish capability and established architect-specification relationships. Monitor copper price volatility indices as inflection indicator for margin compression timing across brass-dependent supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Billet Supply | Captive alloy sourcing insulates margin structures from London Metal Exchange copper benchmark fluctuations. |
| PVD Finish Line Retrofit | Vacuum deposition capability responds to ECHA REACH hexavalent chromium restrictions while capturing premium specification pools. |
| Sensor-Enabled Faucet Platform Launch | Infrared proximity integration opens healthcare and food-service procurement channels requiring touchless operation protocols. |
| Direct Architect Showroom Expansion | Captive specification centers in Shanghai and Manhattan bypass traditional plumbing distributor margin extraction. |
| Dual Certification Investment | Simultaneous EPA lead-free and European drinking water compliance extends addressable market across regulatory jurisdictions. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Brass forging executives, specification architects at hospitality design firms, plumbing distributor procurement directors, and healthcare facility engineering managers provided operational perspective. Secondary sources include SAMR GB standard documentation, EPA Safe Drinking Water Act enforcement records, ECHA REACH restriction updates, and customs trade data for brass alloy imports. Bottom-up volume estimates from forging capacity utilization triangulate against top-down construction spend projections across residential and commercial verticals.
Calibration against historical certification adoption curves and copper price cycles refines the projection framework. Segmentation dimensions span material grade, finish type, application vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, new construction permit trajectories, and efficiency mandate compliance deadlines. Brass alloy price elasticity and PVD finish adoption velocity constitute industry-specific forecast inputs across the modeling period.
Sensitivities concentrate around copper commodity volatility, REACH chemistry restriction timelines, and dual-certification approval delays. Forecasts reflect documented assumptions regarding construction activity levels and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Europe Digital Showers Market
Household Items
China Digital Showers Market
Household Items
Titanium Thermos Cup Market
Household Items
Smart Fork Market
Household Items
Netherlands Cookware Market
Household Items
Portable Iron Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
Wipes Market
Household Items
South Korea Cookware Market
Household Items
Sorting Hampers Market
Household Items
Handheld Fans Market
Household Items
Smart Pool Skimmer Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Party Balloon Market
Household Items
Barbecue Grill Market