
 Floor-Standing Integrated Smart Toilet Market | 2026-2036
Floor-Standing Integrated Smart Toilet Market Size, Share, and Industry Trends Forecast 2026-2036
Floor-Standing Integrated Smart Toilet Market Insights
The EU Green Deal's building renovation targets is broadening the addressable market for water-efficient sanitary fixtures across member states. TOTO leverages its ceramic manufacturing depth to control quality from raw material through finished product. Geberit anchors European distribution through its established plumbing infrastructure relationships. Duravit competes on design-led positioning in premium residential and hospitality specification channels.
A floor-standing integrated smart toilet combines a ceramic bowl, concealed tank system, and electronic control module into a single vertically mounted unit with specifications typically including 0.8–1.6 GPF dual-flush capability, instant water heating, and seat-mounted capacitive sensors. Its primary purpose is to deliver automated hygiene functions, water conservation, and user personalization in both residential and commercial washroom environments. The smart bidet segment leads current revenue contribution due to established consumer familiarity in East Asian markets, while IoT-enabled technology represents the fastest-growing category as connected home ecosystems expand. Residential end users dominate volume, though hospitality applications command higher per-unit margins through specification-grade customization.
REACH compliance in Europe governs chemical safety in electronic components and ceramic glazes, while Japan's JIS standards define performance benchmarks for bidet functionality and electrical safety. China's GB standards and NMPA-equivalent sanitary equipment certifications shape product access in the world's largest production hub. Stakeholders must monitor evolving water-efficiency mandates across multiple jurisdictions to align R&D roadmaps with compliance timelines.
Market Dynamics
Japan's Top Runner Program is compressing product development cycles for water-efficient sanitary fixtures, compelling manufacturers to redesign core subsystems ahead of mandatory compliance deadlines. This regulatory acceleration is reshaping competitive positioning across East Asian supply chains.
Growth Catalysts
- EU Green Deal renovation mandates:Building retrofit targets across member states are expanding replacement demand for water-efficient bathroom infrastructure in existing residential stock.
- China's tier-one construction codes:Municipal regulations in Shanghai and Shenzhen increasingly require smart bathroom specifications in new high-end developments, concentrating demand geographically.
- Instant water heating modules:Tankless heating technology is eliminating standby energy losses and enabling slimmer product profiles that fit aging plumbing infrastructure.
Market Restraints
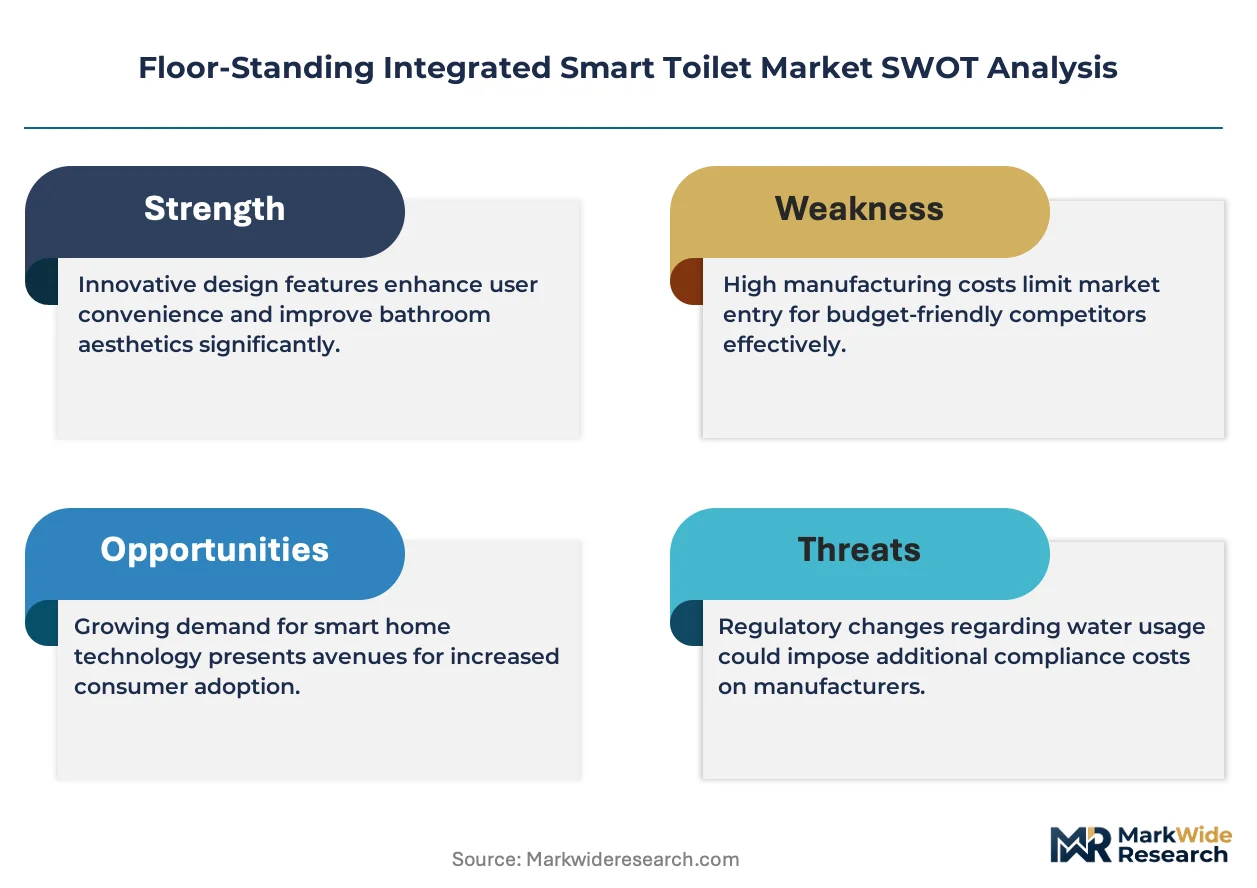
- Ceramic raw material volatility:Price instability in kaolin and feldspar inputs is compressing margins for manufacturers without captive mining operations.
- Electronic component concentration:Dependence on specialized sensor suppliers in South Korea and Taiwan creates vulnerability to semiconductor allocation disruptions.
- REACH compliance complexity:ECHA chemical safety requirements for electronic housings and ceramic glazes are extending certification timelines by 8-14 months.
Strategic Opportunities
- India's premium residential pipeline:Luxury apartment construction in Mumbai and Bangalore remains underpenetrated by integrated smart toilet suppliers relative to East Asian saturation levels.
- Saudi luxury hospitality specification:Giga-project developments in NEOM and the Red Sea coast are mandating specification-grade fixtures with extended customization capabilities.
- IoT-home ecosystem convergence:Integration with voice-activated platforms and water-usage monitoring apps is creating new specification criteria for connected bathroom products.
Industry Challenges
- Multi-jurisdiction certification backlog:Simultaneous GB standards, JIS compliance, and CE marking requirements are stretching technical documentation teams across divergent test protocols.
- Legacy plumbing interface incompatibility:Retrofit installations in European buildings with 100mm versus 90mm rough-in dimensions are forcing costly site-specific engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor-Standing Integrated Smart Toilet Market |
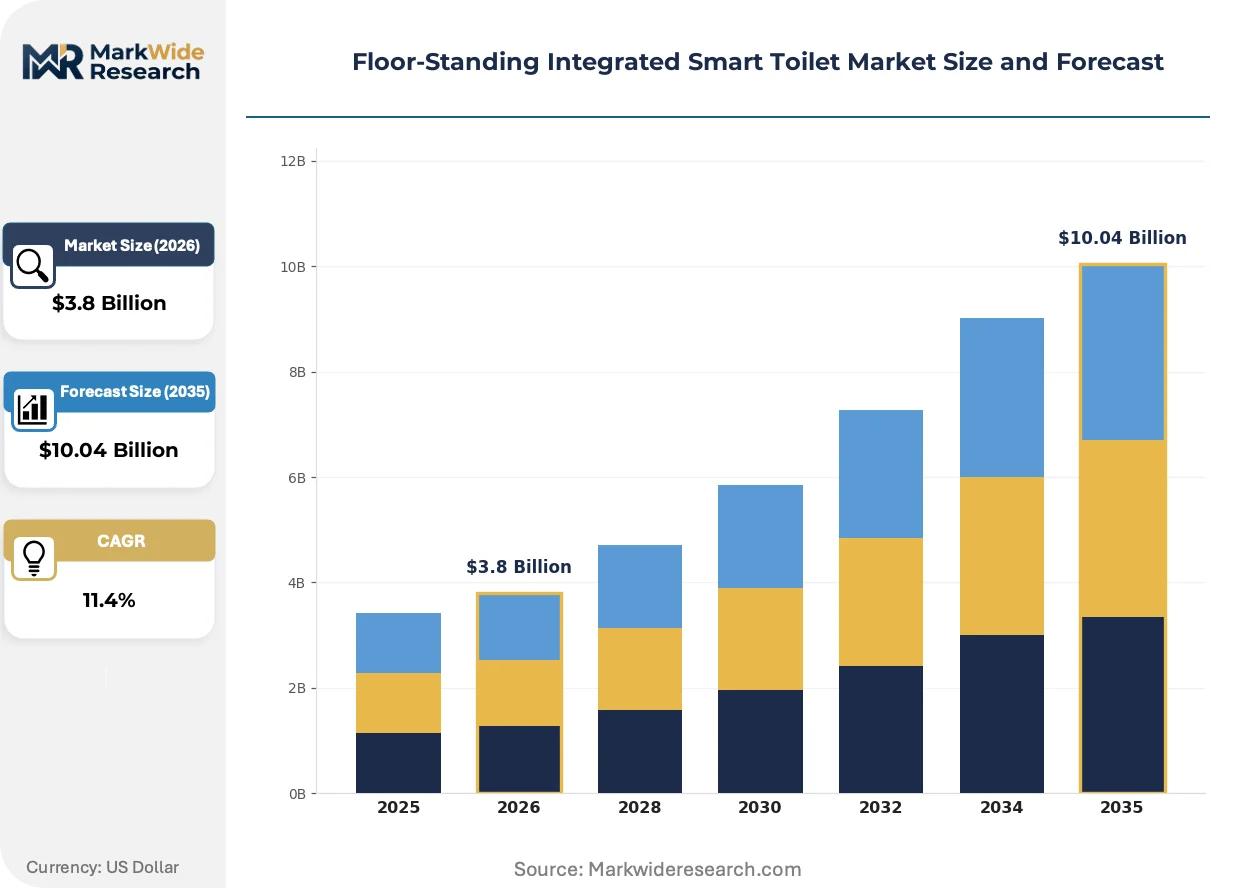
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bidet, Self-Cleaning, Heated Seat, Touchless Flush End User: Residential, Commercial, Healthcare, Hospitality Technology: IoT-Enabled, Water Saving, Automated Hygiene, Energy Efficient Installation Type: New Construction, Remodelling, Retrofit, Standard Installation |
| Companies Covered | Roca Sanitario, Duravit, TOTO, Jomoo Group, Geberit, Kohler, Villeroy & Boch, Panasonic Corporation, LIXIL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor-Standing Integrated Smart Toilet Market Trends and Innovations
Capacitive sensing arrays and edge-computing modules are transforming how sanitary fixtures interpret user behavior, shifting competitive advantage from mechanical reliability toward software-defined personalization.
UV-C LED sterilization is electrifying hygiene protocols in premium residential and healthcare-adjacent applications. Hospitality specifiers in Dubai and Singapore are specifying integrated sterilization cycles as standard. This capability is compressing the traditional separation between medical-grade and consumer sanitary equipment.
Japan's METI efficiency benchmarks are accelerating dual-flush mechanism redesigns to meet 0.8 GPF minimums. Domestic manufacturers are consolidating electronic control and ceramic production to capture compliance-driven specification wins. The Kanto and Kansai metropolitan markets are absorbing initial production volumes ahead of 2027 enforcement.
Specification-grade procurement through design-build contracts is displacing traditional distributor-led channel structures in luxury residential developments. Developers in Riyadh and Shanghai are sourcing directly from manufacturers with embedded project engineering teams. This compression is most visible in Gulf Cooperation Council countries where giga-project scale enables direct negotiation leverage.
Floor-Standing Integrated Smart Toilet Market Segmentation
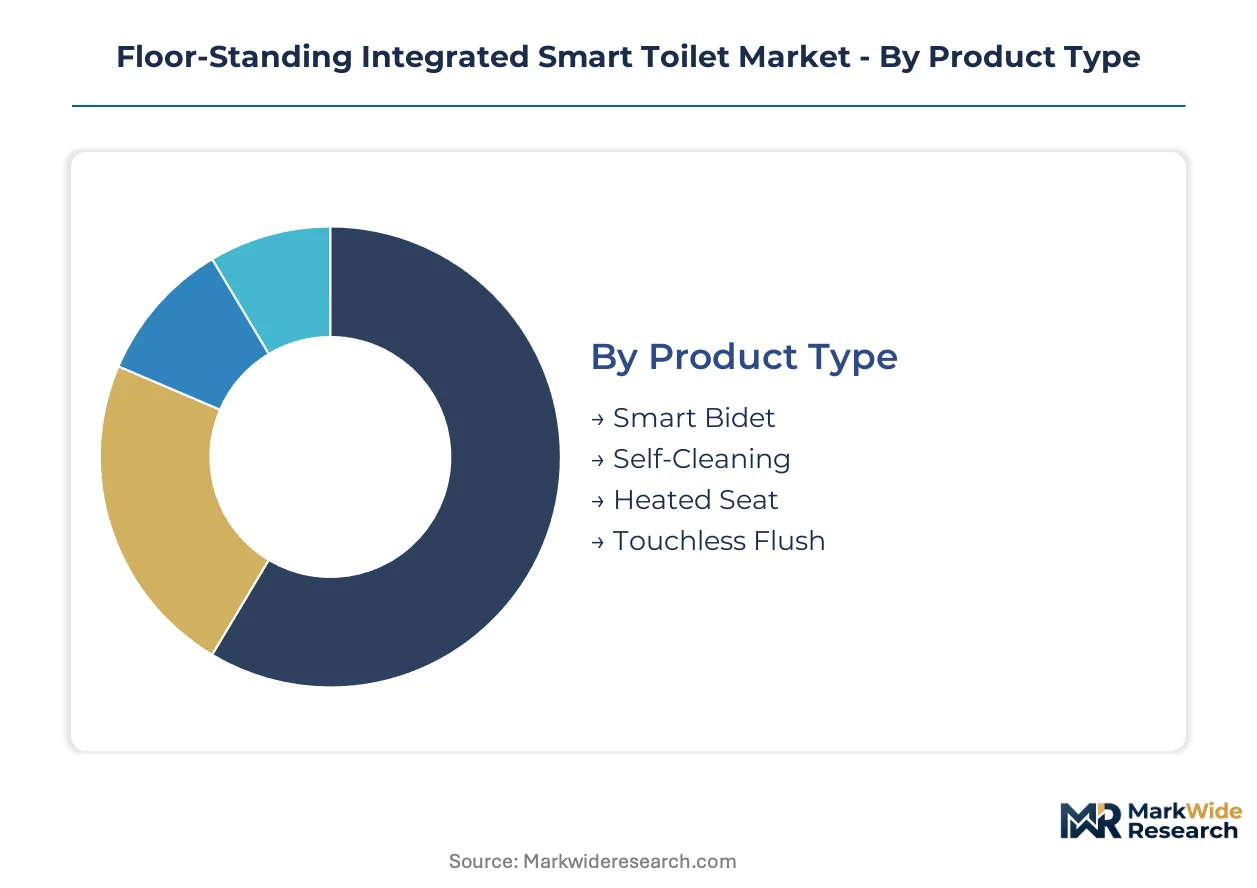
Floor-standing integrated smart toilet purchasing decisions split across four dimensions that rarely align. Product type determines baseline functionality, while end-user context dictates durability and customization requirements. Technology tier and installation complexity further fragment procurement patterns across residential renovations and commercial new-builds.
Product Type:
Upgrade cycles vary dramatically by fixture sophistication, with electronic modules driving shorter replacement intervals than ceramic basins.
- Smart Bidet:Combines heated water spray, air drying, and seat warming in a single integrated control module. Demand concentrates in Japan's Kanto and Kansai metropolitan markets where METI efficiency benchmarks are compressing development cycles ahead of compliance deadlines.
- Self-Cleaning:Incorporates electrolyzed water or UV-C LED sterilization cycles that reduce manual maintenance frequency. Hospitality specifiers in Dubai and Singapore are mandating integrated sterilization as standard, compressing the separation between medical-grade and consumer sanitary equipment.
- Heated Seat:Ceramic-embedded warming elements with temperature memory and occupancy sensors. Premium residential developments in Riyadh specify heated seats as baseline amenities in luxury apartment fit-outs.
- Touchless Flush:Capacitive or infrared-activated flushing mechanisms eliminating physical contact. Healthcare facilities specify touchless interfaces to minimize cross-contamination vectors in patient-adjacent washrooms.
Volume placements concentrate in Smart Bidet; the faster expansion belongs to Self-Cleaning.
End User:
Cost tier separation between specification-grade commercial procurement and price-sensitive residential replacement channels shapes manufacturer portfolio strategy.
- Residential:Single-family and multi-unit dwelling installations prioritizing user personalization and water conservation credentials. China's tier-one cities concentrate demand where municipal regulations increasingly mandate smart bathroom infrastructure in new high-end developments.
- Commercial:Office buildings, retail centers, and public facilities requiring vandal-resistant housings and centralized maintenance protocols. Procurement runs through design-build contracts displacing traditional distributor channels in Gulf Cooperation Council giga-projects.
- Healthcare:Hospitals, clinics, and eldercare facilities demanding infection-control certifications and antimicrobial surface treatments. UV-C LED sterilization integration is climbing fastest in this segment.
- Hospitality:Hotels, resorts, and serviced apartments commanding premium per-unit margins through extended customization capabilities. NEOM and Red Sea coast developments in Saudi Arabia mandate specification-grade fixtures with embedded project engineering support.
Residential captures absolute volume leadership; hospitality delivers the steepest expansion trajectory in value terms.
Technology:
Supply concentration in South Korean and Taiwanese sensor suppliers creates technology-tier vulnerability to semiconductor allocation disruptions.
- IoT-Enabled:Cloud-connected fixtures with water-usage monitoring, predictive maintenance alerts, and voice-platform integration. Integration with connected home ecosystems is creating new specification criteria in premium residential channels.
- Water Saving:Dual-flush mechanisms and pressure-assisted designs meeting 0.8–1.6 GPF efficiency bands. Japan's Top Runner Program is compelling subsystem redesigns to capture compliance-driven specification wins.
- Automated Hygiene:Sensor-activated lid opening, self-sanitizing nozzles, and deodorization cycles. Edge-computing modules are shifting competitive advantage from mechanical reliability toward software-defined personalization.
- Energy Efficient:Tankless instant water heating eliminating standby losses and enabling slimmer profiles for aging plumbing infrastructure. EU Green Deal renovation mandates are expanding replacement demand across member states.
Water Saving dominates current procurement volumes; IoT-Enabled is gaining share fastest as platform convergence accelerates.
Installation Type:
Customer type fragmentation between developer-led new construction and homeowner-driven renovation projects dictates channel access requirements.
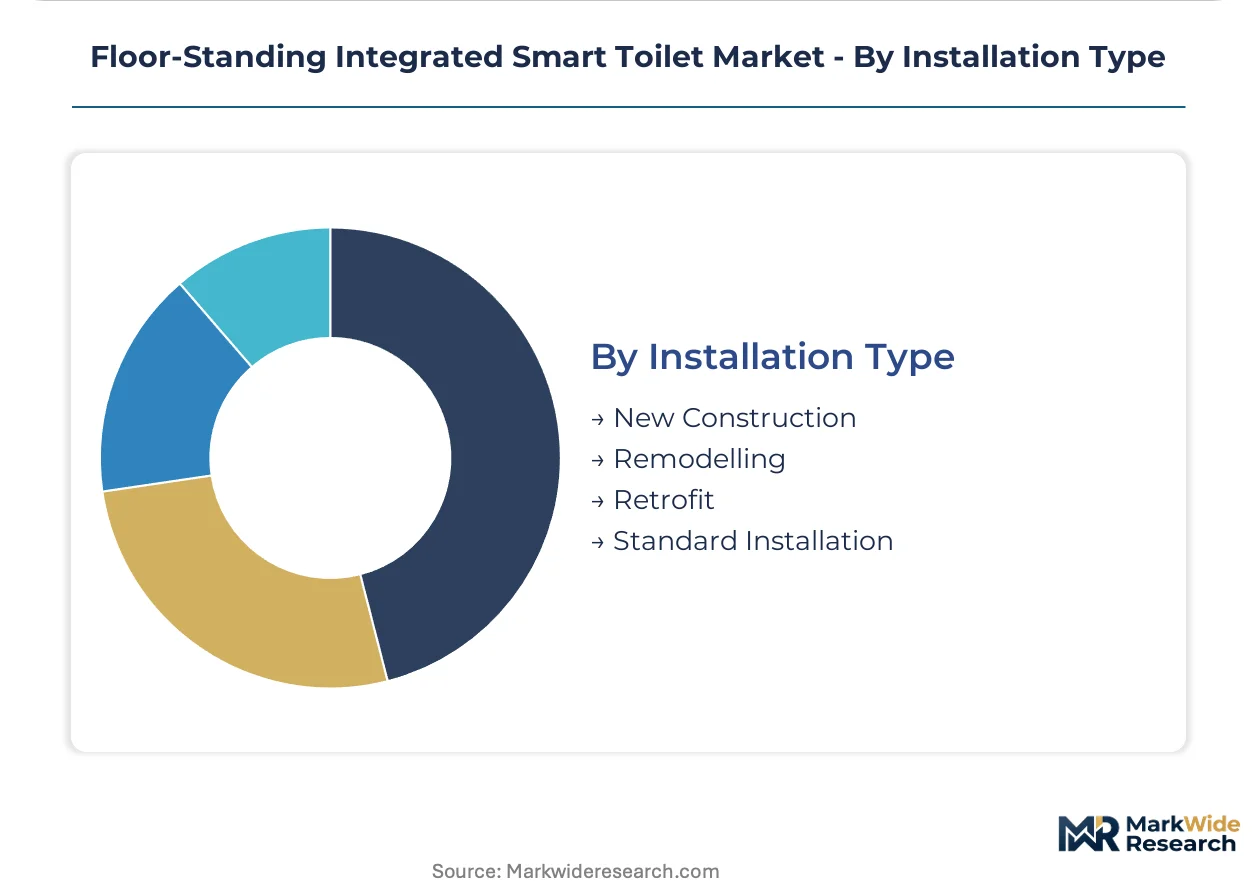
- New Construction:Greenfield installations with optimized rough-in dimensions and coordinated MEP sequencing. Direct manufacturer relationships are displacing distributor intermediaries in Shanghai and Riyadh luxury developments.
- Remodelling:Partial bathroom renovations retaining existing drainage infrastructure while upgrading fixture sophistication. European buildings with 100mm versus 90mm rough-in dimensions force costly site-specific engineering adaptations.
- Retrofit:Drop-in replacements for conventional toilets requiring minimal structural modification. Aging plumbing infrastructure in Japan's metropolitan housing stock drives demand for slimmer profiles enabled by tankless heating modules.
- Standard Installation:Conventional rough-in compatibility with widely available plumbing contractor skill sets. Margin compression is most severe in this commoditized tier.
New Construction absorbs the highest absolute shipments; Retrofit is climbing the fastest as replacement cycles shorten in mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's tier-one construction codes are concentrating demand for smart bathroom infrastructure in China's most affluent developments. Municipal mandates in Shenzhen and Beijing are accelerating specification-grade procurement. This geographic clustering shapes regional competitive dynamics across three continents.
China
Shanghai and Shenzhen municipal regulations increasingly mandate smart bathroom specifications in new high-end residential towers. GB standards and NMPA-equivalent certifications shape product access in the world's largest production hub. Yangtze River Delta manufacturing clusters are absorbing initial production volumes ahead of enforcement timelines.
Japan
METI's Top Runner Program is compressing development cycles for water-efficient fixtures ahead of 2027 compliance deadlines. JIS standards define performance benchmarks for bidet functionality and electrical safety. Kanto and Kansai metropolitan markets are capturing specification wins from domestic manufacturers consolidating electronic and ceramic production.
Germany
EU Green Deal building renovation targets are expanding replacement demand for water-efficient sanitary fixtures across existing residential stock. ECHA REACH compliance governs chemical safety in electronic housings and ceramic glazes. Baden-Württemberg industrial clusters anchor European distribution through established plumbing infrastructure relationships.
Saudi Arabia
NEOM and Red Sea coast giga-projects are mandating specification-grade fixtures with extended customization capabilities. SFDA-equivalent sanitary equipment protocols shape procurement requirements for luxury hospitality developments. Riyadh luxury residential developers are sourcing directly from manufacturers with embedded project engineering teams.
United States
EPA WaterSense certification requirements are driving dual-flush mechanism adoption in water-stressed western states. California's Title 24 building efficiency standards accelerate instant water heating module specification. Southwest corridor retrofit demand is climbing as aging plumbing infrastructure requires slimmer product profiles.
Floor-Standing Integrated Smart Toilet Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive ceramic production. Three tiers separate global volume leaders from regional specialists and private-label assemblers. Ceramic-embedded electronics specialists and plumbing infrastructure integrators represent the dominant strategic archetypes. Capacity consolidation and direct-to-developer specification relationships are the prevailing competitive moves displacing traditional distributor channels.
Among Japanese integrated manufacturers, TOTO exemplifies the ceramic-electronics consolidation archetype, while LIXIL occupies a position bridging residential and commercial specification channels. European plumbing infrastructure specialists include Geberit, which anchors distribution through established contractor relationships. Duravit represents the design-led positioning tier competing on premium residential and hospitality aesthetics.
| Leading Market Players |
|---|
| Roca Sanitario |
| Duravit |
| TOTO |
| Jomoo Group |
| Geberit |
| Kohler |
| Villeroy & Boch |
| Panasonic Corporation |
| LIXIL |
| Others |
Pricing and Supply Chain Analysis
Ceramic-electronics consolidation anchors both supply security and pricing power across the floor-standing integrated smart toilet market, with manufacturers controlling kaolin sourcing and sensor module assembly commanding premium positioning against assembler competitors.
Pricing Analysis
Value-based pricing anchored to water-efficiency outcomes and hygiene certification tiers separates specification-grade hospitality procurement from commoditized residential replacement channels. Three-tier pricing structure across premium, standard, and economy levels tracks JIS compliance status, GB certification grade, and after-sales service bundling. Cost compression in the economy tier is intensifying because raw material volatility in feldspar and kaolin inputs squeezes margins for non-integrated producers. Residential retrofit buyers exhibit highest price sensitivity, while hospitality specifiers in NEOM and Red Sea developments demonstrate lowest sensitivity due to customization requirements and direct manufacturer relationships.
Supply Chain Analysis
Freight cost differentials between containerized ceramic basin shipments and air-freighted electronic modules from South Korea and Taiwan compress margins for manufacturers without regional assembly presence. Production gravity centers on China's Yangtze River Delta, Japan's Kanto industrial corridor, and Germany's Baden-Württemberg cluster, with each hub feeding distinct regulatory certification pathways. The supply chain draws from specialized sensor suppliers in South Korea and Taiwan, kaolin deposits in Brazil and Ukraine, and feldspar from Turkey and India. Single-source vulnerability in semiconductor allocation for capacitive sensing arrays creates disruption exposure. Distribution runs through direct-to-developer specification channels displacing traditional plumbing distributor networks in Gulf Cooperation Council giga-projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The floor-standing integrated smart toilet market is a vertical-integration race, with captive ceramic production and in-house electronic control module assembly representing the decisive upstream lever separating volume leaders from margin-challenged assemblers.
For Market Incumbents: Anchor specification-grade positioning through METI and GB standards pre-certification ahead of compliance deadlines, while consolidating backward into kaolin mining joint ventures to neutralize raw material volatility. Defensive priorities center on locking direct procurement relationships with Riyadh and Shanghai luxury developers before regional specialists replicate the embedded project engineering model. Threat exposure concentrates in South Korean and Taiwanese sensor suppliers restricting allocation during semiconductor shortages. For New Entrants and Emerging Players: Design-build contractors in India's Mumbai and Bangalore luxury residential pipeline represent the most accessible channel partner type for bypassing entrenched distributor relationships. White-space targets concentrate on specification-grade hospitality procurement in Saudi giga-projects and connected-home ecosystem integration for IoT-enabled fixtures. The penetrable geography is India's tier-one cities, where East Asian saturation levels have not yet transferred. A service-led go-to-market angle emphasizing embedded project engineering support differentiates against product-only incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to plumbing infrastructure conglomerates seeking electronic capabilities and private-equity roll-ups of regional ceramic specialists. Long-term viability favors manufacturers with demonstrated JIS, GB, and CE marking competence across multiple regulatory jurisdictions. The acquisition target archetype is mid-cap ceramic-electronics integrators with captive production and direct developer relationships. The signal to watch is METI Top Runner Program enforcement timing, which will compress non-compliant competitors and create consolidation catalysts.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Electronics Integration | Captive control over kaolin-to-module production secures margin against raw material volatility and sensor allocation disruptions. |
| Direct Developer Specification | Bypassing distributor intermediaries in Shanghai and Riyadh captures premium pricing through embedded project engineering teams. |
| Multi-Jurisdiction Pre-Certification | Simultaneous JIS, GB, and CE marking investment compresses competitor entry timelines and locks specification-grade channels. |
| IoT Platform Convergence | Voice-activated integration and water-usage monitoring app development creates new specification criteria in premium residential procurement. |
| Sensor Supply Diversification | Reducing dependence on South Korean and Taiwanese semiconductor allocation through dual-source agreements mitigates production disruption risk. |
Research Methodology
Regulatory filings from METI, ECHA, and SAMR, trade databases tracking ceramic sanitary fixture flows, and hospitality procurement records from Gulf Cooperation Council project developers formed the secondary backbone. Primary interviews with product development directors at integrated manufacturers, specification managers at luxury residential developers, procurement leads at hospitality giga-project contractors, and regulatory compliance officers at certification bodies combined with secondary validation. Bottom-up and top-down triangulation cross-checked production volume estimates against end-user installation records.
Bottom-up modeling aggregated segment-level demand across product type, end-user context, technology tier, and installation complexity dimensions, while top-down analysis validated aggregate market scale against macroeconomic drivers. CAGRs were derived from regression analysis of historical adoption patterns and regulatory enforcement timelines. Industry-specific forecast inputs included municipal smart bathroom mandate adoption curves in China's tier-one cities and METI efficiency benchmark compliance schedules.
Caveats apply where ceramic raw material price spikes, semiconductor allocation disruptions, or accelerated regulatory enforcement timelines could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Air Humidifier Market
Household Items
Barbecue Grill Market
Household Items
Neck Pillows Market
Household Items
Infuser Water Bottles Market
Household Items
Soap Dispenser Market
Household Items
Wipes Market
Household Items
Netherlands Cookware Market
Household Items
Electric Hedge Trimmer Market
Household Items
Industrial Floor Mats Market
Household Items
Hydralight Lanterns Market
Household Items
Portable Steamers Market
Household Items
North America Tankless Water Heater Market
Household Items
Global Electronic Bidet Seats Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Leaf Blower Market
Household Items
Silicone Soap Mold Market