
 France Digital Showers Market | 2026-2036
France Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
France Digital Showers Market Insights
France's RE2020 building energy regulation is broadening the addressable market for thermostatically precise, flow-optimized digital showers in new construction and deep renovation projects. Grohe leverages its German manufacturing heritage and European distribution network to sustain premium positioning across French specification channels. Hansgrohe differentiates through design-forward digital interfaces developed at its Offenburg engineering center. Aqualisa Products Limited anchors its competitive stance on British-engineered digital valve technology adapted for continental European pressure systems.
Digital showers integrate electronically controlled thermostatic mixing valves with user-programmable temperature and flow settings, typically operating within 0.5 degree Celsius accuracy through servo-motor or stepper-motor actuation. The primary commercial purpose is to deliver consistent, safe, and personalized water delivery while enabling water and energy consumption monitoring. Smart showers and digital controllers lead product type demand as residential buyers prioritize app-connected scheduling and usage tracking. Wi-Fi enabled and touchscreen technology segments capture expanding margin pools as hospitality operators specify integrated bathroom management platforms. Wall-mounted installation dominates renovation-friendly retrofit applications where plumbing access constraints limit ceiling-mounted alternatives.
ANSM oversees product safety compliance for electronic water fixtures sold in France, while ECHA's REACH framework governs material composition of brass alloys and polymer seals in valve assemblies. The EU Ecodesign Directive sets mandatory water efficiency thresholds that digital shower manufacturers must certify through notified body testing. Stakeholders should monitor evolving RE2020 technical guidance on hot water system efficiency, as forthcoming amendments may tighten flow-rate requirements and reshape product development roadmaps for digital mixing technologies.
Market Dynamics
France's RE2020 building energy regulation is compressing installation timelines for thermostatically precise digital showers, forcing manufacturers to certify flow-optimized systems before construction permits issue. This regulatory pressure is reshaping product development roadmaps and specification channel access across Île-de-France residential and hospitality projects.
Growth Catalysts
- RE2020 Deep Renovation Mandates:France's building energy regulation requires flow-rate optimization in bathroom retrofits, expanding specification opportunities for digitally controlled thermostatic mixing valves in Parisian residential towers.
- Île-de-France Hospitality Upgrades:Luxury hotel operators in Paris prioritize app-connected shower management platforms to differentiate guest experiences and monitor water consumption across property portfolios.
- Servo-Motor Actuation Advances:Stepper-motor precision technology enables 0.5 degree Celsius temperature stability, satisfying safety requirements for multi-generational households in French retirement communities.
Market Restraints
- Brass Alloy Input Volatility:ECHA REACH compliance costs for lead-free brass formulations in valve assemblies compress manufacturer margins on mid-tier digital shower lines.
- Installation Skill Concentration:Certified plumbing technicians capable of integrating digital controllers with legacy hot water systems concentrate in Greater Paris, limiting deployment velocity in secondary French cities.
- Conventional Thermostatic Substitution:Non-connected thermostatic mixers retain cost advantage in budget residential renovations across France's peripheral regions.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Hospitality Expansion:Cannes and Nice luxury resort developments specify integrated bathroom management platforms, creating premium installation demand outside Paris concentration.
- EU Ecodesign Water Efficiency Thresholds:Tightening certification requirements for flow-rate performance position digitally optimized systems as compliant defaults for new French construction permits.
- Voice Interface Convergence:Integration of natural language control with existing digital shower platforms enables accessibility positioning for aging-in-place residential segments.
Industry Challenges
- ANSM Certification Timelines:Electronic water fixture safety approvals for connected shower systems extend product launch schedules, compressing competitive response windows.
- Legacy Plumbing Integration Complexity:Retrofit installations in Haussmann-era Parisian buildings require custom valve configurations, elevating project engineering costs and technician training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Digital Showers Market |
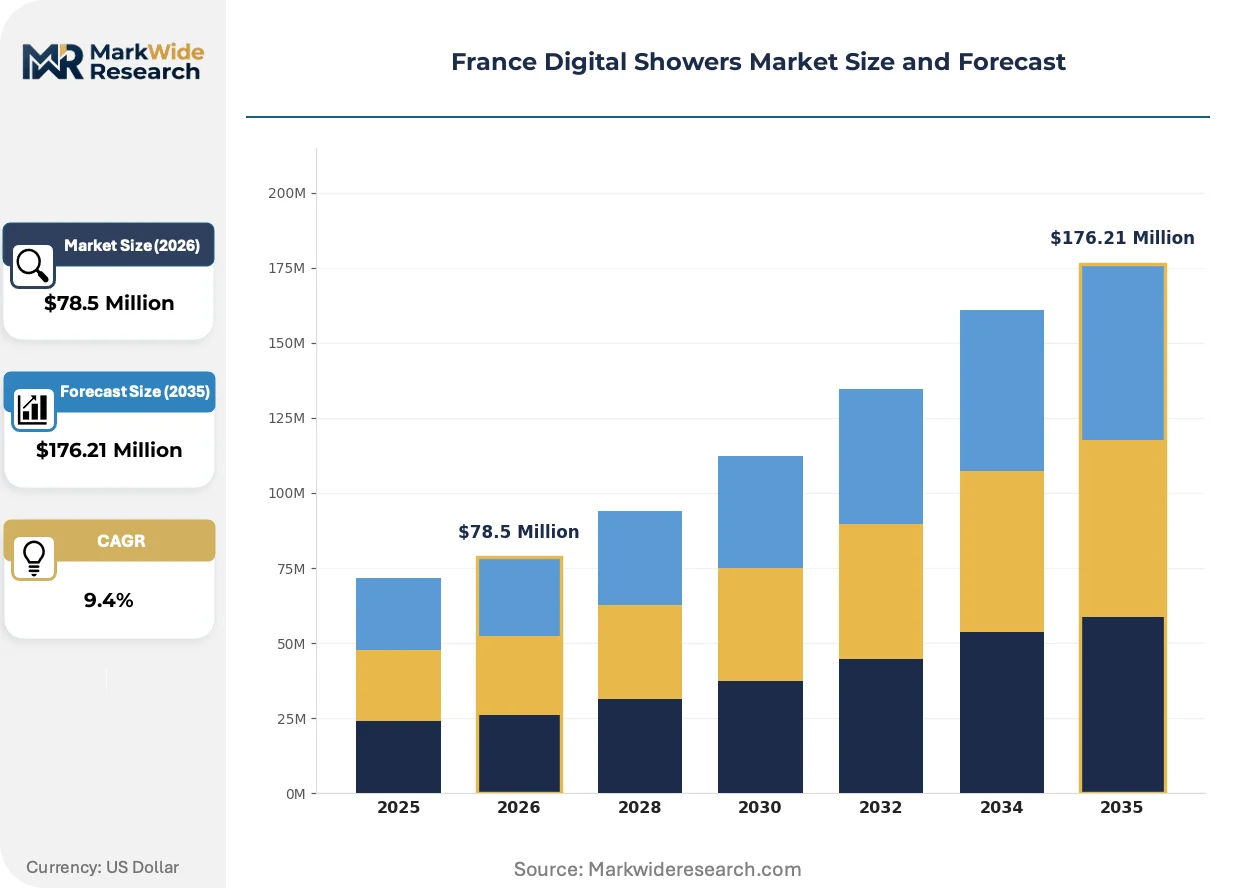
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $176.21 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Showers, Digital Controllers, Shower Panels, User Interfaces Installation Type: Wall-Mounted, Ceiling-Mounted, Thermostatic Valves, Digital Hoses End User: Residential, Commercial, Hospitality, Healthcare Technology: Wi-Fi Enabled, Bluetooth, Touchscreen, Voice Control |
| Companies Covered | Roca Sanitario, Aqualisa Products Limited, Lixil Corporation, Toto Ltd, Kohler Co, Dornbracht Deutschland GmbH & Co. KG, Grohe, Hansgrohe, Jaquar Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Digital Showers Market Trends and Innovations
Connected bathroom technology is penetrating French residential and hospitality specification channels through three reinforcing developments: hardware-software integration, regulatory compliance automation, and procurement model evolution toward integrated platform contracts.
Touchscreen digital interfaces are converging with cloud-based usage analytics platforms. Hospitality operators in Lyon and Bordeaux adopt these systems to centralize water consumption monitoring across property portfolios. This convergence is compressing the competitive window for standalone hardware manufacturers without software development capabilities.
France's Agence Nationale de Sécurité du Médicament and ECHA's REACH framework are tightening material composition and electronic safety requirements for water fixtures. Manufacturers must document brass alloy sourcing and polymer seal composition before market entry. The premium digital shower segment bears the heaviest compliance burden, with specification channels demanding pre-certified documentation packages.
Buyer concentration among French property developers is consolidating procurement authority for bathroom fixture packages. Large-scale residential developers in Île-de-France now negotiate direct platform contracts with digital shower suppliers, bypassing traditional wholesale distribution. This channel compression is most visible in Parisian social housing renovation programs where volume aggregation enables customized firmware configurations.
France Digital Showers Market Segmentation
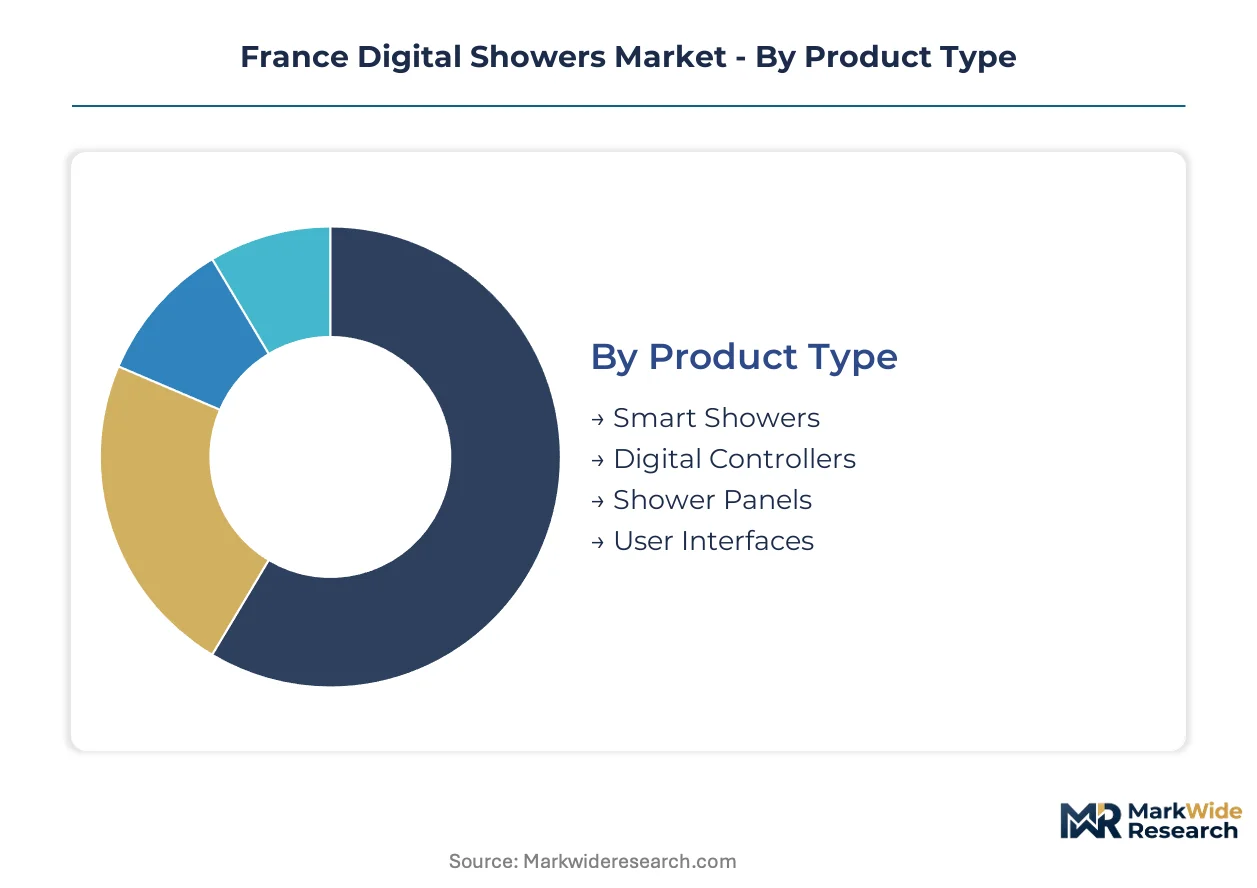
Digital shower segmentation in France reflects divergent paths between embedded infrastructure systems and standalone retrofit solutions. Product architecture choices determine regulatory compliance pathways under RE2020 and ANSM certification requirements.
Product Type:
Integration depth separates embedded valve systems from surface-mounted retrofit units, with implications for plumbing access and certification complexity.
- Smart Showers:App-connected systems with cloud-based usage analytics and programmable scheduling through Wi-Fi or Bluetooth protocols. Île-de-France hospitality operators specify these platforms for portfolio-wide water monitoring, driven by corporate sustainability reporting obligations under CSRD.
- Digital Controllers:Electronically actuated thermostatic mixing valves delivering temperature stability within 0.5 degree Celsius through servo-motor or stepper-motor mechanisms. Deep renovation mandates in Parisian residential towers concentrate demand for these flow-optimized units that satisfy RE2020 efficiency thresholds.
- Shower Panels:Integrated vertical assemblies combining digital controls with multiple spray functions.
- User Interfaces:Detachable control units enabling remote operation of concealed valve systems.
Digital Controllers lead volumes today; Smart Showers is gaining share fastest.
Installation Type:
Mounting configuration dictates project economics, with ceiling systems commanding premium positioning against renovation-friendly wall alternatives.
- Wall-Mounted:Surface or recessed installations accommodating retrofit constraints in Haussmann-era buildings where plumbing chase access is limited. Budget residential renovations across France's peripheral regions favor these configurations for lower labor intensity.
- Ceiling-Mounted:Concealed overhead installations requiring structural ceiling voids and coordinated MEP routing. New construction in Île-de-France luxury residential and hospitality developments specifies these for minimalist aesthetic outcomes.
- Thermostatic Valves:Core mixing components enabling temperature stability independent of mounting orientation.
- Digital Hoses:Flexible connections with embedded temperature sensing for handheld applications.
Wall-Mounted dominates renovation volumes; Ceiling-Mounted climbs fastest in new construction.
End User:
Customer type determines specification authority, with institutional buyers aggregating volume against fragmented residential decision-making.
- Residential:Individual homeowners and multi-unit developers selecting systems for single-family and apartment installations. Multi-generational households in French retirement communities prioritize servo-motor precision for safety compliance.
- Commercial:Office and mixed-use developments with centralized bathroom facilities. Corporate wellness amenities in Lyon and Bordeaux business districts specify app-connected platforms for tenant differentiation.
- Hospitality:Luxury hotel and resort operators with portfolio-scale procurement authority.
- Healthcare:Hospital and long-term care facilities requiring infection control and accessibility features.
Residential anchors absolute volumes; Hospitality shows steepest expansion trajectory.
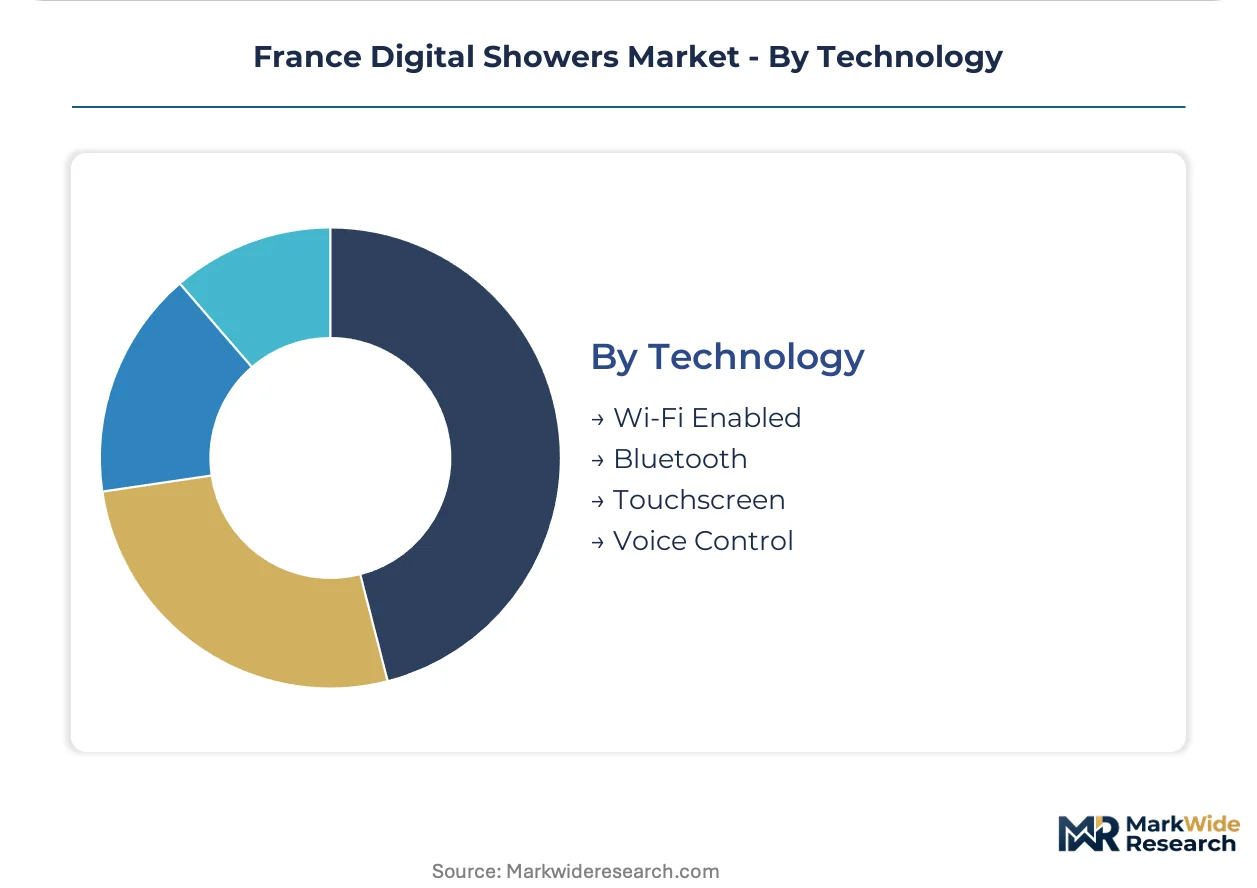
Technology:
Connectivity protocol selection shapes interoperability with broader building management platforms and accessibility compliance.
- Wi-Fi Enabled:Cloud-connected systems supporting remote monitoring, firmware updates, and integration with property management platforms. Hospitality operators in Cannes and Nice luxury resorts specify these for centralized consumption tracking across portfolios.
- Touchscreen:Capacitive or resistive glass interfaces enabling gesture-based temperature and flow control. Design-forward Parisian residential projects specify these for premium positioning, though ANSM electronic safety certification extends launch timelines.
- Bluetooth:Short-range wireless protocols for localized smartphone control without internet dependency.
- Voice Control:Natural language interfaces enabling hands-free operation for aging-in-place accessibility segments.
Wi-Fi Enabled leads installed base; Voice Control is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital shower technology originated in German and Swiss engineering centers during the early 2000s, with thermostatic precision systems later scaling through French and British specification channels. European regulatory frameworks subsequently standardized certification requirements across national markets.
Germany
German manufacturers pioneered servo-motor actuation systems for temperature-stable water delivery. The country's national building energy regulator enforces stringent flow-rate standards under the Energieeinsparverordnung (EnEV) framework. Engineering clusters in the Offenburg region concentrate development of design-forward digital interfaces for export across continental Europe.
United Kingdom
British-engineered digital valve technology addresses low-pressure domestic systems common in Victorian-era housing stock. The UK's Building Regulations Part G mandates thermostatic mixing in new residential construction. Specification activity concentrates in Greater London renovation projects where heritage building constraints favor retrofit-friendly wall-mounted configurations.
Italy
Italian manufacturers specialize in integrated shower panel assemblies combining digital controls with aesthetic metalwork. The country's Ministry of Economic Development enforces EU Ecodesign compliance through notified body certification. Production gravity sits in the Lombardy region, where Milan-based design studios influence premium bathroom fixture styling for Mediterranean hospitality markets.
Spain
Spanish hospitality operators in Barcelona and Madrid drive adoption of app-connected shower management platforms for portfolio-scale water monitoring. The country's national construction code (Código Técnico de la Edificación) incorporates EU water efficiency directives. Costa del Sol resort developments specify ceiling-mounted digital systems for luxury guest experience differentiation.
Netherlands
Dutch specification channels prioritize water conservation technologies aligned with national circular economy targets. The country's Environmental Management Act implements REACH material compliance for brass alloy components in valve assemblies. Rotterdam and Amsterdam social housing renovation programs aggregate procurement volume for standardized digital controller installations.
France Digital Showers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European digital shower value chain. The market structure fragments between integrated bathroom fixture conglomerates and specialized thermostatic valve engineers. Three archetypes dominate: German-engineered precision manufacturers, British digital valve specialists, and Asian-scale bathroom platform operators. Competitive moves center on RE2020 pre-certification racing and direct-to-developer procurement contracting that bypasses traditional wholesale channels.
Among German-origin manufacturers, Grohe and Hansgrohe exemplify the engineering-precision archetype with heritage positioning in specification channels. Aqualisa Products Limited represents British-engineered specialization adapted for continental European pressure systems. These three companies anchor the competitive landscape through differentiated technical positioning rather than scale-based cost leadership.
| Leading Market Players |
|---|
| Roca Sanitario |
| Aqualisa Products Limited |
| Lixil Corporation |
| Toto Ltd |
| Kohler Co |
| Dornbracht Deutschland GmbH & Co. KG |
| Grohe |
| Hansgrohe |
| Jaquar Group |
| Others |
Pricing and Supply Chain Analysis
Île-de-France property developers aggregating volume for Parisian social housing renovation programs negotiate direct platform contracts that compress wholesale margins and enforce three-tier pricing stratification across premium, standard, and economy certification levels. This buyer concentration shifts pricing power toward specification channels demanding pre-certified RE2020 compliance documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Grohe and Hansgrohe heritage positioning from mid-tier digital controller suppliers and budget thermostatic alternatives. Price differentiation hinges on ANSM certification grade and after-sales service bundling. Cost compression in mid-tier lines intensifies because ECHA REACH compliance expenses for lead-free brass formulations erode manufacturer margins. Budget residential renovations across France's peripheral regions exhibit highest price sensitivity, while hospitality operators in Cannes and Nice luxury resorts demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
France's RE2020 domestic-content preferences for building energy systems are reshaping sourcing patterns toward EU-based valve assembly operations. Manufacturing gravity centers on Germany, Italy, and domestic French production hubs for thermostatic mixing components. Raw material dependencies draw from lead-free brass alloy suppliers, polymer seal manufacturers, and servo-motor component specialists. Single-source vulnerability concentrates in precision stepper-motor actuation technology. Distribution runs through direct-to-developer platform contracts bypassing traditional wholesale channels in Île-de-France concentration zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
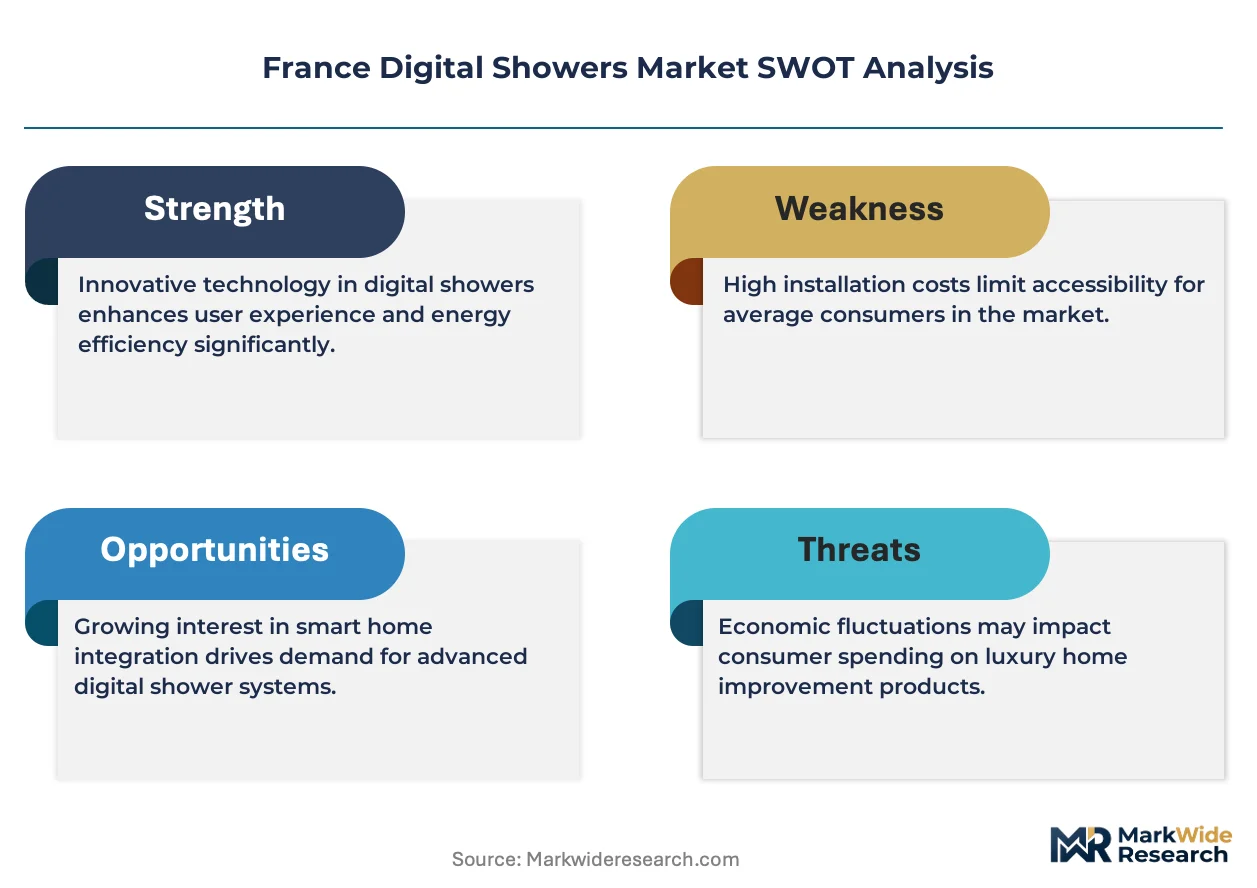
France's Digital Showers Market functions as a regulatory compounder where RE2020 building energy mandates and forthcoming technical guidance amendments continuously expand compliant product addressable demand.
For Market Incumbents: Deploy certification investment leverage to extend ANSM pre-approval timelines and compress competitive response windows for connected shower system launches. Defensive priorities center on backward integration into brass alloy sourcing to offset ECHA REACH compliance cost volatility, and channel control consolidation through direct platform contracting with Île-de-France developers to lock out mid-tier entrants. For New Entrants and Emerging Players: The premium-to-economy price-point gap in wall-mounted retrofit configurations offers accessible entry trajectory for digitally native competitors lacking heritage specification relationships. Most penetrable white-space sits in Provence-Alpes-Côte d'Azur hospitality developments outside Paris concentration, where portfolio-scale procurement authority remains fragmented. Voice control integration for aging-in-place residential segments provides differentiated go-to-market angle against established touchscreen incumbents. For Investors and Strategic Acquirers: Integrated bathroom fixture conglomerates are the most active acquirer in this space, seeking digital valve engineering capabilities to complement hardware-software platform strategies. Long-term viability frames around consolidation of RE2020-compliant product portfolios and software development competencies. Acquisition target archetype: British-engineered digital valve specialists with continental European pressure system adaptations. Signal to watch: tightening RE2020 technical guidance on hot water system efficiency as inflection indicator for flow-rate requirement reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| RE2020 Pre-Certification Racing | ANSM documentation packages accelerate construction permit issuance in Île-de-France developments. |
| Direct-to-Developer Platform Contracting | Bypassing wholesale channels captures volume aggregation from Parisian social housing renovation programs. |
| Voice Interface Development | Natural language control enables accessibility positioning for French aging-in-place residential segments. |
| Cloud-Based Usage Analytics Integration | Hospitality operators in Lyon and Bordeaux adopt centralized water consumption monitoring across portfolios. |
| Lead-Free Brass Alloy Backward Integration | ECHA REACH compliance costs compress margins on mid-tier lines without captive alloy sourcing. |
Research Methodology
Bottom-up residential and hospitality installation modeling reconciled against top-down manufacturer shipment tracking forms the analytical core. Primary interviews with specification channel architects, certified plumbing technicians, property development procurement leads, and ANSM regulatory affairs specialists combined with secondary validation from EU Ecodesign Directive documentation, RE2020 technical guidance publications, ECHA REACH substance databases, and French building permit issuance records. Triangulation between demand-side project pipelines and supply-side production schedules ensures coherence across estimation layers.
Input-output matrices map digital shower unit shipments against RE2020-compliant construction permit volumes, renovation project registrations, and hospitality development pipelines across the projection horizon. Segmentation dimensions modeled include product architecture depth, mounting configuration, end-user category, and connectivity protocol. CAGRs derive from regression analysis linking regulatory milestone timing to specification channel adoption curves, with servo-motor precision technology cost trajectories and Wi-Fi module commoditization rates as industry-specific forecast inputs.
Caveats apply where ANSM certification timeline extensions, ECHA REACH substance restriction amendments, or RE2020 technical guidance revisions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and construction permit issuance velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Flatware Market
Household Items
Porcelain Tableware Market
Household Items
Household Sewing Machines Market
Household Items
Crash Mat Market
Household Items
Home Use Air Purifiers Market
Household Items
Multi-Door Fridges Market
Household Items
Global Buddhist Supplies Market
Household Items
Global Sports Bottle Market
Household Items
Japan Cookware Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Garbage Disposals Market
Household Items
Toilet Brush Market
Household Items
Robot Mops Market
Household Items
Drain Cleaners Market
Household Items
United Kingdom Air Purifier Market
Household Items
Netherlands Cookware Market