
 Argentina Freight and Logistics Market | 2026-2036
Argentina Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Freight and Logistics Market Outlook
Biodiesel blends are broadening fuel economics for Argentine trucking fleets, lowering per-kilometer operating costs versus conventional diesel. DHL Group leverages its Buenos Aires hub network to sustain temperature-controlled pharmaceutical flows across Mercosur. Andreani Logistica S.A. anchors domestic parcel distribution through its provincial branch network, while Kuehne+Nagel competes on ocean freight forwarding via specialized agro-export lanes.
Argentina freight and logistics encompasses the physical movement, storage, and information management of goods across road, rail, air, and water modes, with cold chain operations requiring continuous temperature monitoring between minus 25 and plus 25 degrees Celsius to preserve pharmaceutical and food product integrity. Its primary commercial purpose centers on connecting interior production zones, particularly the Pampas grain belt, to Atlantic port terminals for export dispatch and to urban consumption centers for domestic distribution. Transportation services dominate service type revenue as bulk grain and soybean meal movements require dedicated hopper fleets and river barge capacity on the Paraná-Paraguay waterway. E-commerce logistics represents the fastest-growing application segment as last-mile delivery networks expand in Greater Buenos Aires and Córdoba metropolitan areas. IoT Solutions within the technology dimension command premium pricing as real-time cargo tracking reduces theft exposure on national routes.
Argentina's national customs authority AFIP enforces the Sistema Integral de Monitoreo de Cargas for cross-border cargo tracking, while the Comisión Nacional de Regulación del Transporte sets maximum freight tariffs for certain road corridors to prevent carrier price gouging during harvest peaks. The Mercosur Common External Tariff framework shapes import logistics costs for capital equipment and replacement vehicle parts. Stakeholders must monitor AFIP's digital manifest requirements and assess whether fleet telematics investments align with emerging mandatory emissions reporting for heavy-duty vehicles.
Market Dynamics
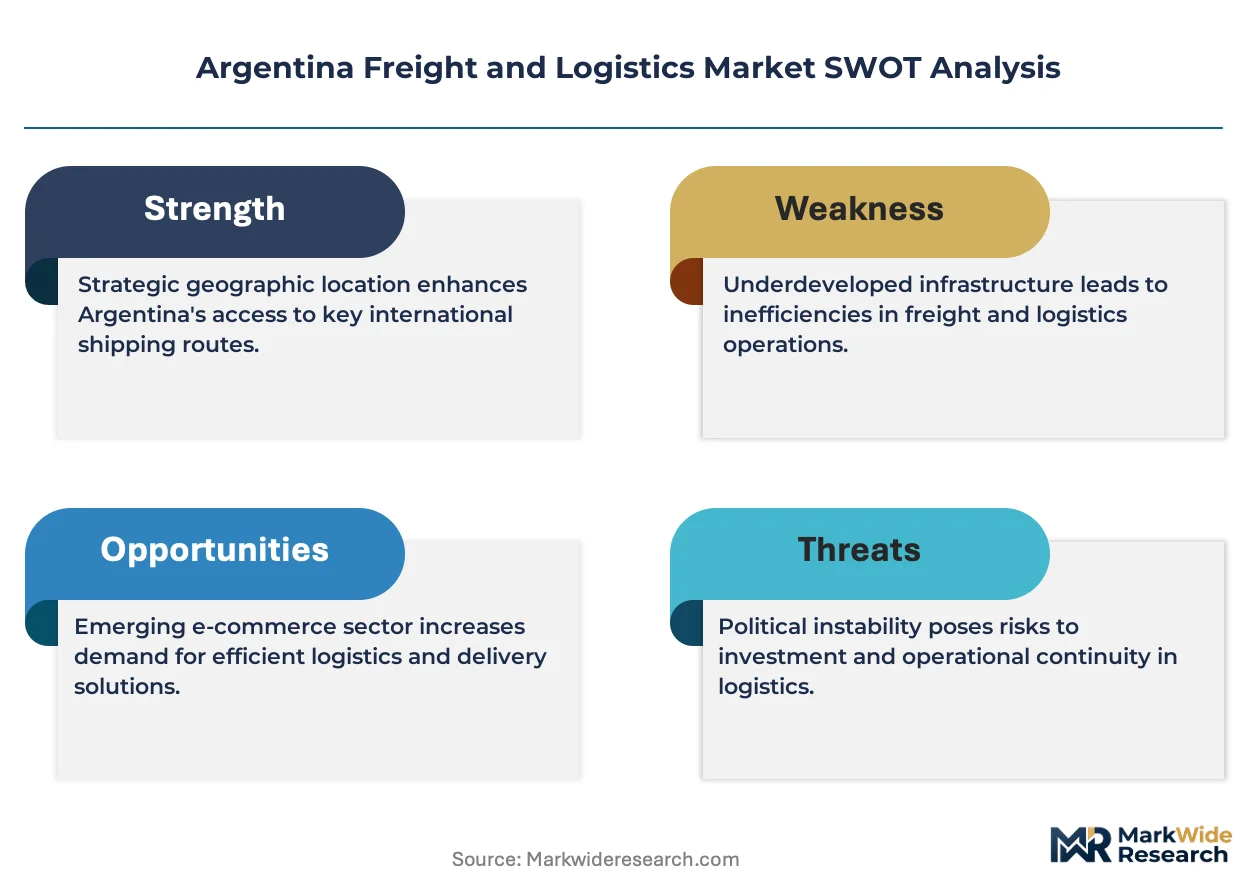
AFIP's customs modernization program is compressing cargo clearance times at Atlantic ports, forcing freight operators to accelerate digital manifest integration or lose agro-export contracts to more agile competitors.
Growth Catalysts
- Sistema Integral de Monitoreo de Cargas:Argentina's national cargo tracking mandate is reducing documentation friction for cross-border grain shipments, attracting investment in compliant fleet telematics.
- Soy-based biodiesel blending:Long-haul trucking fleets are adopting higher blend ratios to hedge against conventional diesel price volatility, expanding retrofit demand for compatible engine systems.
- Rosario-Buenos Aires corridor concentration:Agro-export volume density along this route is justifying dedicated intermodal terminals and specialized hopper fleet deployments.
Market Restraints
- CNRT tariff ceilings:Argentina's transport regulator caps freight rates during harvest peaks, compressing carrier margins when demand surges most intensely.
- Paraná-Paraguay waterway dependency:Bulk grain movements rely on shared river infrastructure with Paraguay and Brazil, exposing Argentine exporters to upstream dredging delays and bilateral transit disputes.
- Capital equipment import costs:Mercosur's Common External Tariff elevates prices for replacement truck parts and cold chain refrigeration units, aging domestic fleet composition.
Strategic Opportunities
- Greater Buenos Aires last-mile density:E-commerce fulfillment networks remain underpenetrated in peripheral metropolitan zones, creating whitespace for automated sorting hubs.
- IoT-enabled theft reduction:Real-time cargo tracking on national routes is commanding premium pricing as insurers recognize verified loss-prevention data.
- Pharmaceutical cold chain expansion:Temperature-controlled corridors between Córdoba manufacturing clusters and Ezeiza air cargo terminals offer specialized service differentiation.
Industry Challenges
- Telematics technician scarcity:Fleet operators struggle to recruit personnel capable of maintaining integrated sensor networks across dispersed provincial branch locations.
- AFIP digital manifest compliance timelines:Smaller carriers face documentation system upgrades requiring capital outlays that strain working capital during low-margin periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Freight and Logistics Market |
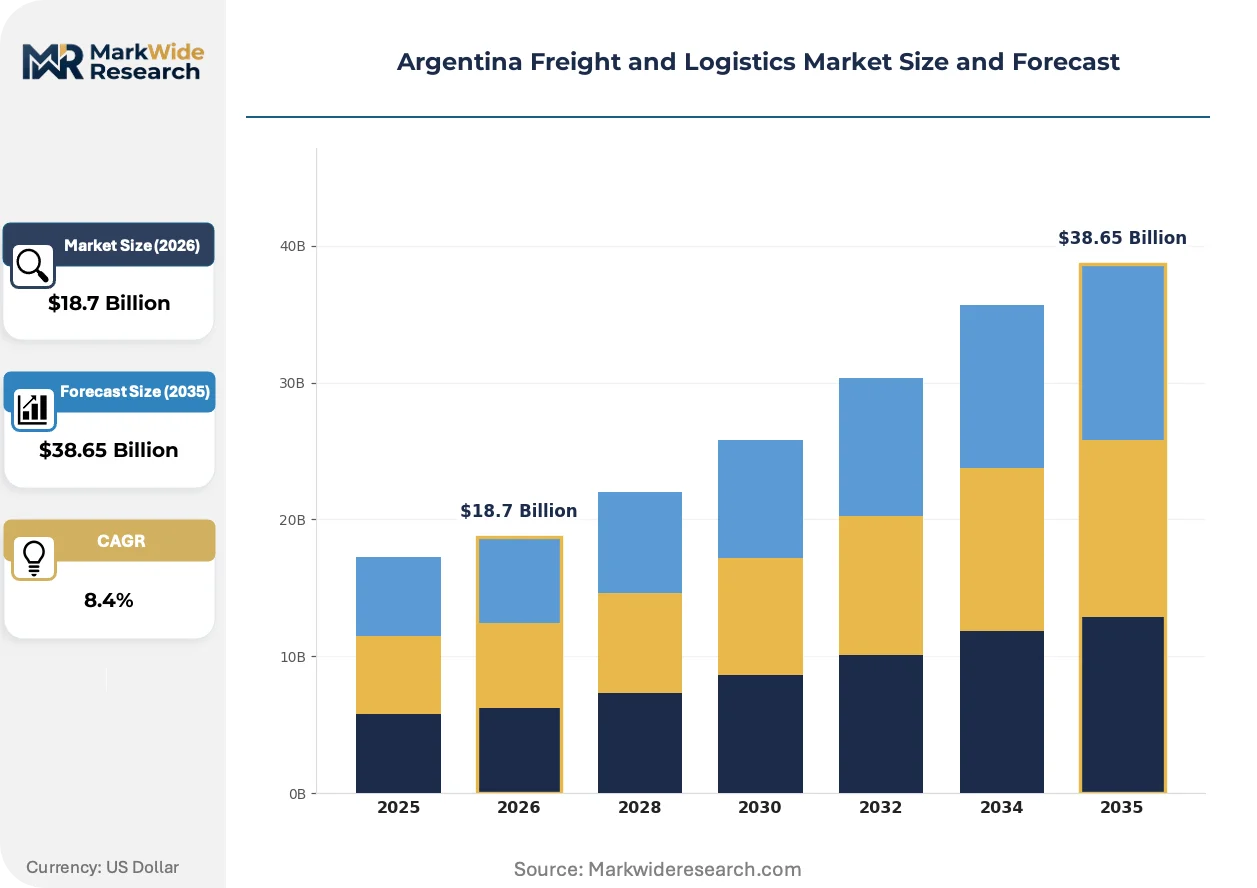
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding Application: Retail Logistics, Cold Chain, E-commerce Logistics, Industrial Transport Technology: TMS, WMS, RFID, IoT Solutions End User: Manufacturers, E-commerce Companies, Food Producers, Retailers |
| Companies Covered | Deutsche Bahn AG, DHL Group, DSV A/S, OCASA, TASA Logistica, Andreani Logistica S.A., Kuehne+Nagel, Dibiagi Group, International Cargo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Freight and Logistics Market Strategic Shifts
Digital freight platforms are compressing traditional broker margins while cold chain monitoring systems raise service quality thresholds across Argentina's temperature-sensitive cargo segments.
Blockchain-enabled bill-of-lading verification is integrating with AFIP's electronic manifest systems to create immutable cargo documentation trails. Large grain exporters in the Rosario hub are piloting these platforms to reduce documentary fraud exposure. The technology is integrating previously siloed customs, carrier, and shipper databases into unified visibility layers that accelerate port release decisions.
AFIP's phased digitalization mandates are eliminating paper-based customs declarations for cross-border cargo. The policy is forcing smaller freight forwarders to acquire electronic data interchange capabilities or exit international lanes. Pharmaceutical and perishable food exporters face the tightest compliance deadlines and are consolidating vendor relationships around providers with certified digital infrastructure.
Shippers are unbundling long-term logistics contracts into transactional spot-market engagements facilitated by freight-matching platforms. Traditional asset-heavy carriers in the Buenos Aires metropolitan zone are losing contract predictability to digital brokers offering real-time price discovery. This pattern is most pronounced among mid-sized agricultural exporters seeking harvest-season flexibility without committed fleet obligations.
Argentina Freight and Logistics Market Segmentation
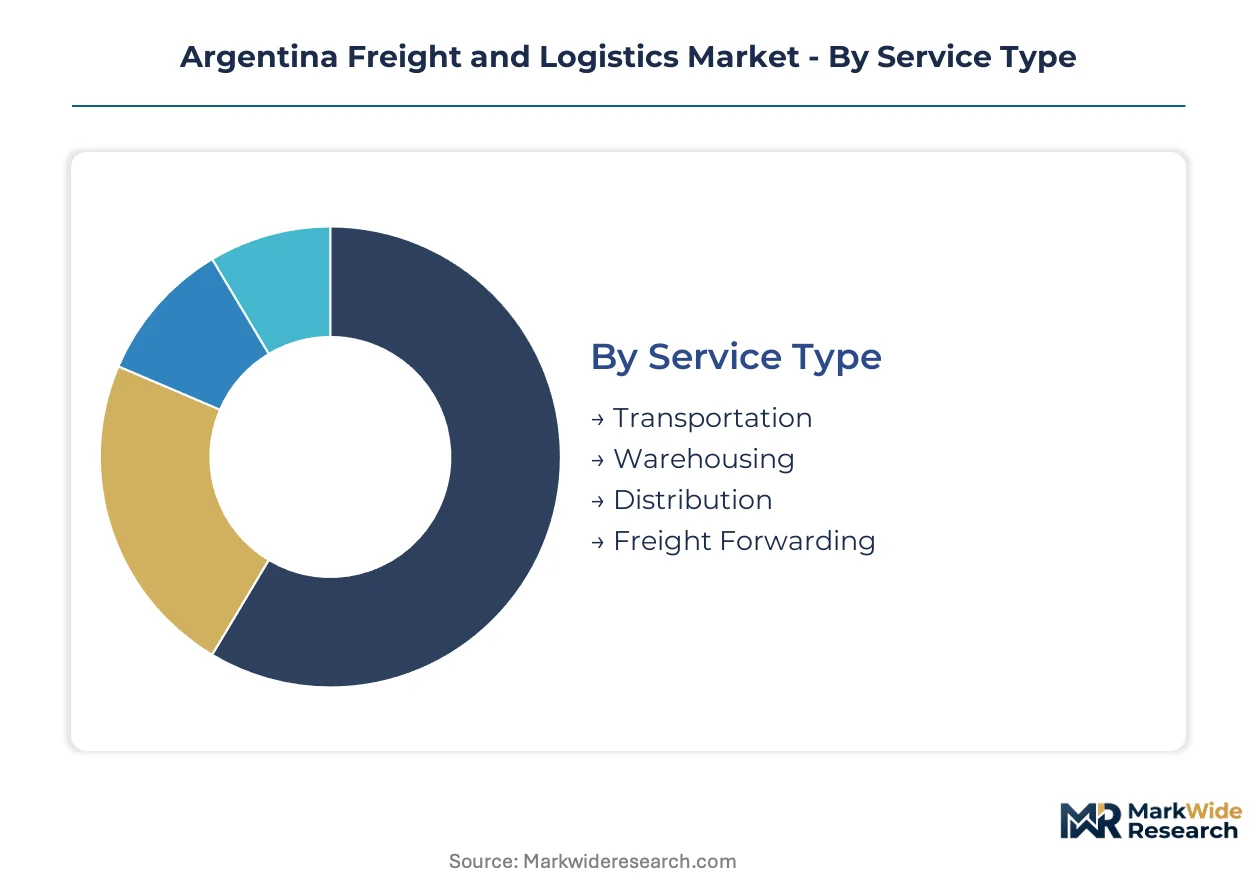
Freight and logistics segmentation in Argentina reflects the structural divide between commodity-driven bulk movements and precision service requirements. Understanding how service types, applications, technologies, and end users interlock reveals where capital deployment and margin compression concentrate across the value chain.
Service Type:
Transportation services operate as standalone offerings requiring dedicated asset ownership, while warehousing and distribution increasingly embed within integrated supply contracts.
- Transportation:Road haulage dominates with specialized hopper fleets for grain movements between the Pampas belt and Atlantic ports. AFIP's Sistema Integral de Monitoreo de Cargas mandate is accelerating telematics adoption among long-haul operators serving the Rosario-Buenos Aires corridor.
- Warehousing:Temperature-controlled facilities command premium positioning as pharmaceutical manufacturers in Córdoba demand validated cold storage. Capital constraints limit automated warehouse deployment outside Greater Buenos Aires, preserving labor-intensive operations in provincial hubs.
- Distribution:Last-mile networks in metropolitan zones integrate with e-commerce fulfillment platforms, though peripheral Buenos Aires neighborhoods remain underpenetrated for same-day delivery.
- Freight Forwarding:Ocean forwarding concentrates on agro-export documentation and customs brokerage, with digital manifest integration separating compliant operators from declining competitors.
Transportation leads volumes today; freight forwarding is gaining share fastest as exporters consolidate around digitally integrated providers.
Application:
Application segments stratify by temperature sensitivity and delivery velocity requirements, with cold chain and e-commerce representing opposite ends of the infrastructure investment spectrum.
- Retail Logistics:Department store replenishment and supermarket distribution center operations drive predictable demand for scheduled full-truckload services. Seasonal promotional cycles create volume spikes that strain contracted carrier capacity.
- Cold Chain:Continuous temperature monitoring between minus 25 and plus 25 degrees Celsius preserves pharmaceutical and food product integrity. The Comisión Nacional de Regulación del Transporte's tariff ceilings compress margins during peak harvest periods when refrigerated capacity faces competing demands.
- E-commerce Logistics:Parcel volume expansion in Córdoba and Greater Buenos Aires metro areas outpaces sorting automation investment, creating whitespace for automated hub development.
- Industrial Transport:Heavy machinery and automotive component movements rely on specialized flatbed and low-loader equipment, with Mercosur's Common External Tariff elevating replacement vehicle part costs for fleet maintenance.
Retail logistics anchors current revenue; e-commerce logistics is climbing the fastest as digital consumption penetrates secondary Argentine cities.
Technology:
Technology adoption patterns reveal a bifurcation between foundational enterprise systems and emerging sensor networks, with integration complexity determining vendor selection criteria.
- TMS:Transportation management systems optimize route planning and carrier selection for large agricultural exporters. AFIP's digital manifest requirements are forcing upgrades among mid-sized operators previously reliant on manual dispatch coordination.
- WMS:Warehouse management systems remain concentrated in pharmaceutical and food processing facilities where lot traceability mandates apply. Implementation lags in general cargo warehousing due to capital equipment import cost barriers.
- RFID:Radio-frequency identification supports inventory tracking in retail distribution centers, though deployment remains patchy across provincial branch networks.
- IoT Solutions:Real-time cargo tracking reduces theft exposure on national routes and commands premium pricing from risk-averse shippers. Technician scarcity limits maintenance capacity across dispersed provincial fleet locations.
TMS dominates current technology spending; IoT Solutions shows the steepest expansion trajectory as insurers recognize verified loss-prevention data.
End User:
End user segmentation reflects divergent procurement power, with multinational manufacturers and large e-commerce platforms driving standardization while smaller food producers accept fragmented service levels.
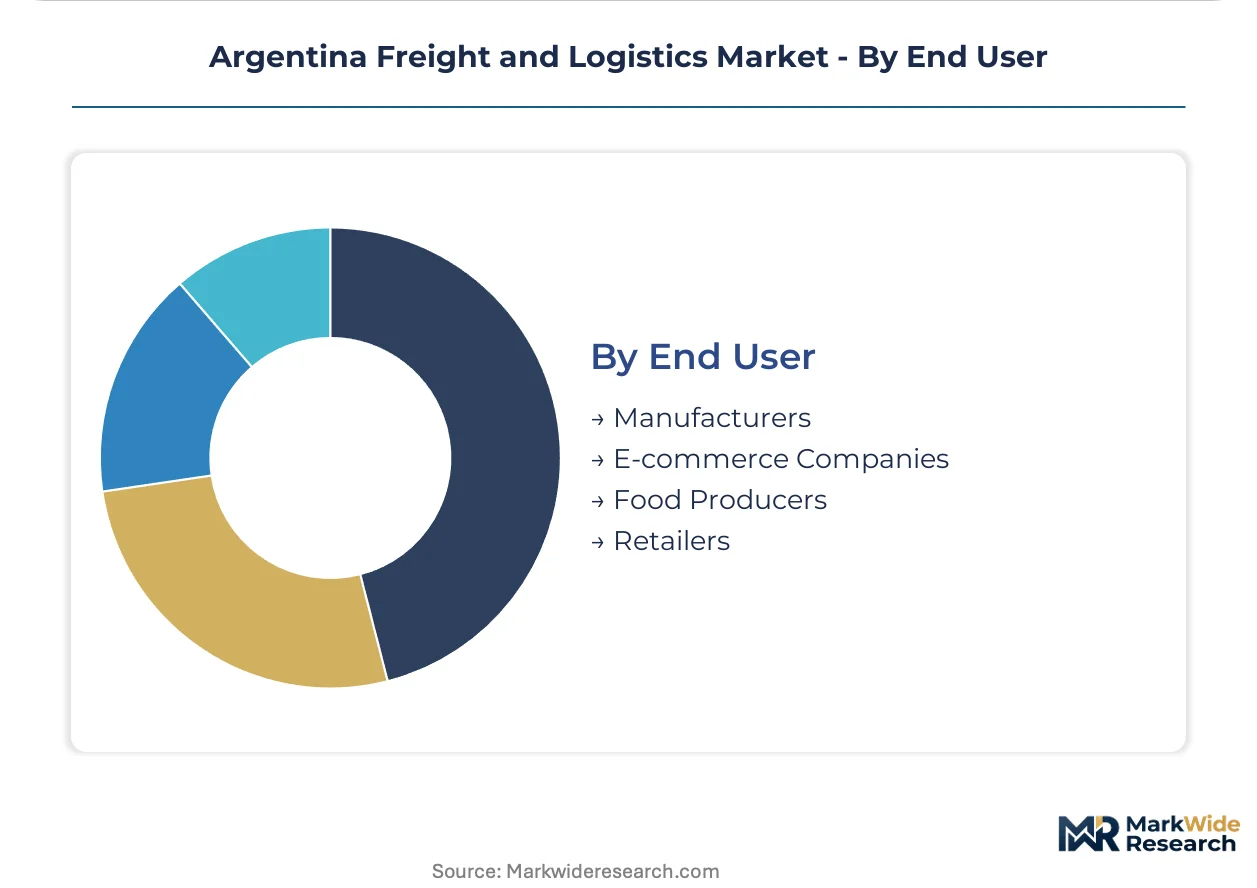
- Manufacturers:Automotive and industrial goods producers in Córdoba and Buenos Aires provinces demand integrated multi-modal solutions. These buyers leverage volume concentration to negotiate service level agreements with penalty clauses.
- E-commerce Companies:Digital retail platforms require flexible capacity scaling during promotional events, favoring freight-matching platforms over committed fleet contracts. This procurement shift is compressing margins for traditional asset-heavy carriers.
- Food Producers:Grain exporters and processed food manufacturers generate the bulk of temperature-controlled and bulk commodity movements. Paraná-Paraguay waterway dependency exposes these shippers to upstream dredging delays and bilateral transit disputes.
- Retailers:Supermarket chains and department stores prioritize inventory velocity over transportation cost minimization, accepting premium pricing for reliable replenishment schedules.
Manufacturers represent the largest current customer segment; e-commerce companies are expanding their logistics spend most rapidly as last-mile networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rosario-Buenos Aires corridor anchors Argentina's freight economy, concentrating grain export flows through Atlantic port terminals while interior provinces generate dispersed agricultural and industrial movements requiring multimodal connectivity.
Greater Buenos Aires
E-commerce fulfillment and pharmaceutical distribution dominate demand in this metropolitan zone. AFIP's digital manifest requirements are accelerating compliance investments among last-mile operators. Automated sorting hubs remain underpenetrated in peripheral districts, creating infrastructure whitespace for logistics developers.
Córdoba Province
Automotive manufacturing and food processing clusters generate temperature-controlled and industrial cargo flows. The Comisión Nacional de Regulación del Transporte's tariff ceilings compress carrier margins during seasonal volume surges. Pharmaceutical manufacturers in Córdoba city are validating cold chain corridors to Ezeiza air cargo terminals.
Santa Fe Province
The Rosario agro-export hub drives bulk grain movements requiring specialized hopper fleets and river barge capacity. Paraná-Paraguay waterway dependency exposes shippers to upstream dredging delays and bilateral transit disputes with Paraguay and Brazil. Intermodal terminal investments are concentrating along the Rosario-Buenos Aires rail corridor.
Mendoza Province
Wine production and mining equipment movements characterize this Andean region's logistics profile. Mercosur's Common External Tariff elevates replacement truck part costs, aging fleet composition in provincial branch networks. Cross-border connectivity with Chile through the Andes passes requires specialized heavy-haul capabilities.
Argentina Freight and Logistics Market Competitive Environment
Capacity expansion dominates the current landscape as operators retrofit fleets for biodiesel compatibility and deploy telematics to satisfy AFIP's Sistema Integral de Monitoreo de Cargas mandate. The market structure fragments between multinational forwarders with integrated Mercosur networks, domestic parcel specialists with provincial branch density, and asset-light digital brokers compressing traditional margins. Three archetypes define competitive positioning: integrated global networks, regional asset-heavy carriers, and technology-enabled freight platforms. M&A activity and strategic partnerships concentrate among mid-sized operators seeking scale to absorb compliance costs.
Within the integrated global network tier, DHL Group and Kuehne+Nagel exemplify the asset-light forwarding model, leveraging electronic manifest capabilities and temperature-controlled infrastructure to anchor pharmaceutical and agro-export flows. Andreani Logistica S.A. represents the domestic asset-heavy archetype, with provincial branch networks supporting parcel distribution density that multinational competitors struggle to replicate. Deutsche Bahn AG and DSV A/S occupy positions bridging European origin capabilities with South American operational scale.
| Leading Market Players |
|---|
| Deutsche Bahn AG |
| DHL Group |
| DSV A/S |
| OCASA |
| TASA Logistica |
| Andreani Logistica S.A. |
| Kuehne+Nagel |
| Dibiagi Group |
| International Cargo |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration across the Rosario-Buenos Aires grain corridor anchors both supply positioning and pricing power for Argentine freight operators, as dedicated hopper fleet ownership creates captive capacity during harvest peaks when CNRT tariff ceilings compress spot-market margins. This corridor concentration forces shippers into long-term contract structures that blend fixed-route commitments with seasonal surge pricing, embedding biodiesel retrofit costs into base rates while telematics compliance investments command premium positioning.
Pricing Analysis
Input-cost pass-through from soy-based biodiesel blending ratios and Mercosur tariff-elevated replacement parts flows directly into contract rate negotiations, with fuel cost volatility absorbed through fuel-surcharge mechanisms rather than base-rate adjustments. Pricing stratifies across premium, standard, and economy tiers based on telematics certification level and cold chain validation status, with pharmaceutical shippers showing least price sensitivity due to product integrity requirements. Cost compression in standard-tier road haulage is intensifying as digital freight platforms disintermediate traditional broker margins. Grain exporters represent the most price-sensitive buyer segment, unbundling long-term contracts into transactional spot engagements during harvest windows.
Supply Chain Analysis
Dual-sourcing requirements for temperature-controlled pharmaceutical movements mandate multi-carrier qualification across both dedicated fleet operators and freight forwarders with certified cold chain infrastructure. Argentina's logistics sector draws primary equipment inputs from Brazil, China, and Germany, with refrigeration units and replacement engine components subject to Mercosur Common External Tariff exposure. Raw material dependencies center on refined soy methyl ester for biodiesel blending, steel for trailer fabrication, and semiconductor components for telematics hardware. Single-source vulnerability concentrates in imported cold chain technology where AFIP digital manifest compliance deadlines accelerate obsolescence risk. Distribution runs through provincial branch networks anchored by Buenos Aires hub operations, with last-mile density in Greater Buenos Aires metropolitan zones determining service tier accessibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's freight and logistics market offers margin-expansion potential through biodiesel cost-down integration and premium-tier cold chain certification as pharmaceutical demand validates temperature-controlled service differentiation. Fleet operators capturing telematics compliance early position for contract consolidation as AFIP digital mandates eliminate smaller competitors.
For Market Incumbents: Anticipate digital freight platform disintermediation by embedding IoT-enabled cargo tracking into base service offerings rather than premium upsells, while securing backward integration into biodiesel supply through crushing facility partnerships that hedge fuel input volatility. Prioritize certification investment in AFIP's Sistema Integral de Monitoreo de Cargas compliance infrastructure to capture contract volume from exiting smaller carriers facing documentation system upgrade costs. For New Entrants and Emerging Players: Capture whitespace in peripheral Greater Buenos Aires e-commerce fulfillment zones where automated sorting hub deployment lags parcel volume growth, targeting mid-sized agricultural exporters seeking harvest-season flexibility without committed fleet obligations. Penetrate through freight-matching platform architecture that unbundles traditional broker functions into real-time price discovery tools, avoiding asset-heavy fleet investments that expose operators to CNRT tariff ceiling compression during peak periods. For Investors and Strategic Acquirers: Roll-up economics work for provincial branch network consolidators because AFIP compliance cost burdens disproportionately strain mid-sized operators with dispersed maintenance capabilities and limited working capital reserves. Long-term viability centers on platform scale sufficient to absorb telematics technician scarcity through centralized training infrastructure. Target acquisition archetypes include cold chain-certified regional carriers with validated pharmaceutical corridors and digital manifest-ready forwarding operations. Watch AFIP enforcement intensity on electronic manifest deadlines as the inflection indicator for accelerated market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Infrastructure Deployment | AFIP's Sistema Integral de Monitoreo de Cargas mandate eliminates non-compliant operators from cross-border lanes. |
| Biodiesel Fleet Retrofit Program | Higher blend ratio compatibility hedges conventional diesel price volatility for Rosario-Buenos Aires corridor operators. |
| Cold Chain Certification Investment | Pharmaceutical manufacturers in Córdoba demand validated temperature-controlled corridors to Ezeiza air cargo terminals. |
| Digital Manifest Integration | Electronic data interchange capabilities separate compliant freight forwarders from declining paper-based competitors. |
| Provincial Branch Network Expansion | Last-mile density in peripheral Buenos Aires zones creates whitespace for automated sorting hub development. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations managers, AFIP regulatory affairs officers, pharmaceutical supply chain directors, and grain export logistics coordinators with secondary validation against CNRT tariff filings, AFIP customs modernization bulletins, Mercosur trade statistics, and operator telematics deployment disclosures. Bottom-up carrier capacity assessments and top-down commodity flow estimates were triangulated against corridor-specific volume data.
Segment-weighting approaches applied differential growth assumptions across service types, applications, technologies, and end users, with transportation management systems and IoT Solutions receiving distinct trajectory modeling based on compliance mandate timing and insurance recognition patterns. CAGRs were derived from historical volume trends projected across the analysis window, incorporating biodiesel adoption curves, e-commerce penetration rates in secondary cities, and pharmaceutical cold chain expansion timelines as industry-specific forecast inputs.
Regulatory enforcement delays, Paraná-Paraguay waterway disruption events, and Mercosur tariff renegotiation outcomes are the dominant revision risks to modeled projections. Forecasts reflect assumptions documented in the analysis framework. Deviation in AFIP digital manifest compliance timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Vietnam Logistics Market