
 Gum Hydrocolloid Market | 2026-2036
Gum Hydrocolloid Market Size, Share, and Industry Trends Forecast 2026-2036
Gum Hydrocolloid Market Analysis
ISO 22000 certification is reorganizing competitive access for hydrocolloid suppliers, raising barriers for smaller processors. Kerry Group leverages its integrated ingredient platforms to sustain supply security across European dairy applications. Cargill Incorporated anchors its position through backward integration into seaweed sourcing in Southeast Asia. CP Kelco differentiates via specialized fermentation capacity for xanthan gum production.
Gum hydrocolloids comprise high-molecular-weight polysaccharides extracted from marine algae, plant seeds, or microbial fermentation, functioning as thickeners, stabilizers, and gelling agents with viscosity ranges from 100 to 10,000 cP in standard concentrations. Their primary commercial purpose centers on texture modification and shelf-life extension in formulated consumer goods. Carrageenan and xanthan gum occupy the dominant volume positions, with pectin commanding premium pricing in acid-stable beverage systems. Agar retains niche strength in pharmaceutical culture media where gel strength specifications exceed 900 g/cm².
EFSA purity standards and FDA GRAS self-affirmation requirements govern hydrocolloid specifications for food and pharmaceutical applications, with EFSA evaluations driving reformulation away from degraded carrageenan in EU-sold products. China's SAMR national food safety standards and India's FSSAI additive regulations create parallel compliance tracks for Asia-Pacific market entry. Stakeholders must monitor evolving clean-label definitions and regional maximum-use-level adjustments to anticipate specification shifts before they disrupt formulation contracts.
Market Dynamics
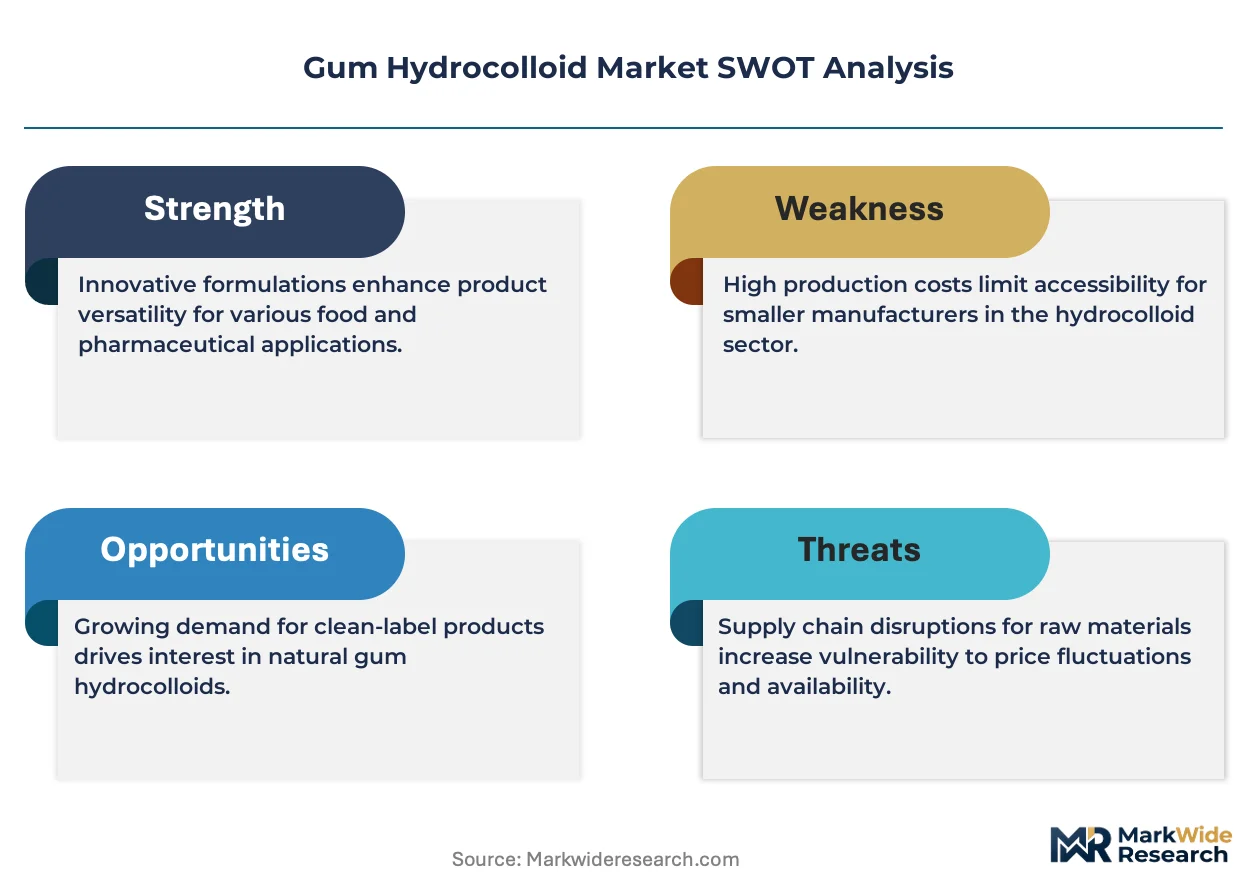
Clean-label formulation mandates and EFSA purity standards are compressing specification tolerances across food and pharmaceutical applications, forcing processors to rebuild supply chains around certified raw material streams rather than commodity spot markets.
Growth Catalysts
- EU EFSA purity standards:Degraded carrageenan restrictions in EU-sold products accelerate demand for refined extraction grades in dairy and meat alternatives.
- Plant-based meat alternatives:North American food manufacturers require hydrocolloid blends for texture replication in burger and sausage analogues.
- Indonesia-Philippines seaweed concentration:Carrageenan raw material access in these archipelagos secures supply for Asian and European processors.
Market Restraints
- Seaweed harvest volatility:El Niño events and warming waters in Southeast Asian growing regions destabilize carrageenan input costs.
- Fermentation capacity scarcity:Xanthan gum production requires specialized bioreactor infrastructure concentrated among limited microbial fermentation specialists.
- Cellulose gum substitution:Paper and textile-derived cellulose derivatives compete in low-viscosity thickening applications where gel strength is non-critical.
Strategic Opportunities
- Pharmaceutical culture media:Agar gel strength specifications above 900 g/cm² create premium positioning for laboratory-grade producers serving cell therapy manufacturing.
- India FSSAI additive harmonization:India's national food safety standards alignment with Codex Alimentarius opens formulation contract opportunities for compliant exporters.
- Precision fermentation convergence:Synthetic biology platforms combining CRISPR-edited microbial strains with continuous processing enable novel hydrocolloid molecular architectures.
Industry Challenges
- ISO 22000 certification timelines:Food safety management system audits require 12-18 month implementation cycles that delay market access for smaller processors.
- Extraction technology skill gaps:Seaweed processing facilities lack operators trained in ionic precipitation methods for kappa and iota carrageenan fractionation.
- Legacy dairy formulation integration:Acid-stable beverage systems using pectin demand pH-neutral equipment retrofits incompatible with existing plant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gum Hydrocolloid Market |
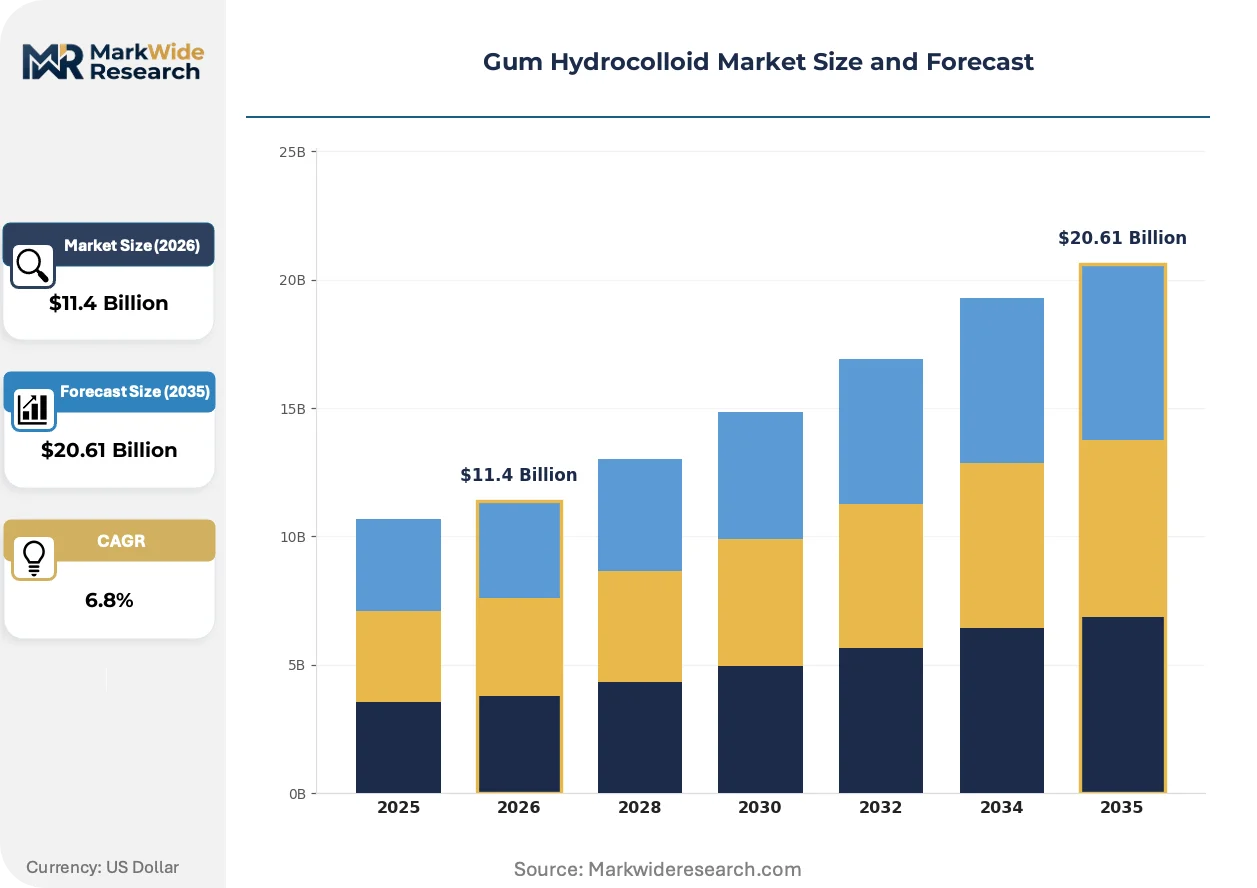
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Carrageenan, Pectin, Xanthan Gum Application: Beverages, Bakery Products, Dairy, Sauces End User: Food Industry, Pharmaceutical, Cosmetics, Nutraceuticals Form: Powder, Liquid, Granulate, Gel |
| Companies Covered | Tate & Lyle Plc, Kerry Group, DuPont, BASF, Ashland, Ingredion Incorporated, CP Kelco, Palsgaard, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gum Hydrocolloid Market Emerging Trajectories
Bioprocessing advances and regulatory specification tightening are converging to reshape how hydrocolloid functionality is manufactured, certified, and specified across end-use contracts.
Precision fermentation platforms are miniaturizing xanthan gum production economics. Specialty chemical producers deploy compact bioreactor arrays that slash capital requirements for entry-scale manufacturing. This distributed production model is compressing geographic concentration risk in microbial polysaccharide supply.
REACH substance evaluation protocols in Europe now classify certain degraded carrageenan grades as requiring authorization. Food manufacturers reformulate toward refined lambda and kappa fractions to preempt supply disruption. Acid-stable beverage systems using pectin face accelerated EFSA re-evaluation timelines affecting formulation lock-in periods.
Ingredient pre-blend procurement is displacing single-hydrocolloid spot purchasing among North American plant-based meat processors. Contract manufacturers now specify complete texture systems rather than raw polysaccharides, shifting technical risk upstream to integrated ingredient platforms. This specification change is most visible in US Midwest contract manufacturing corridors serving national retail brand launches.
Gum Hydrocolloid Market Segmentation
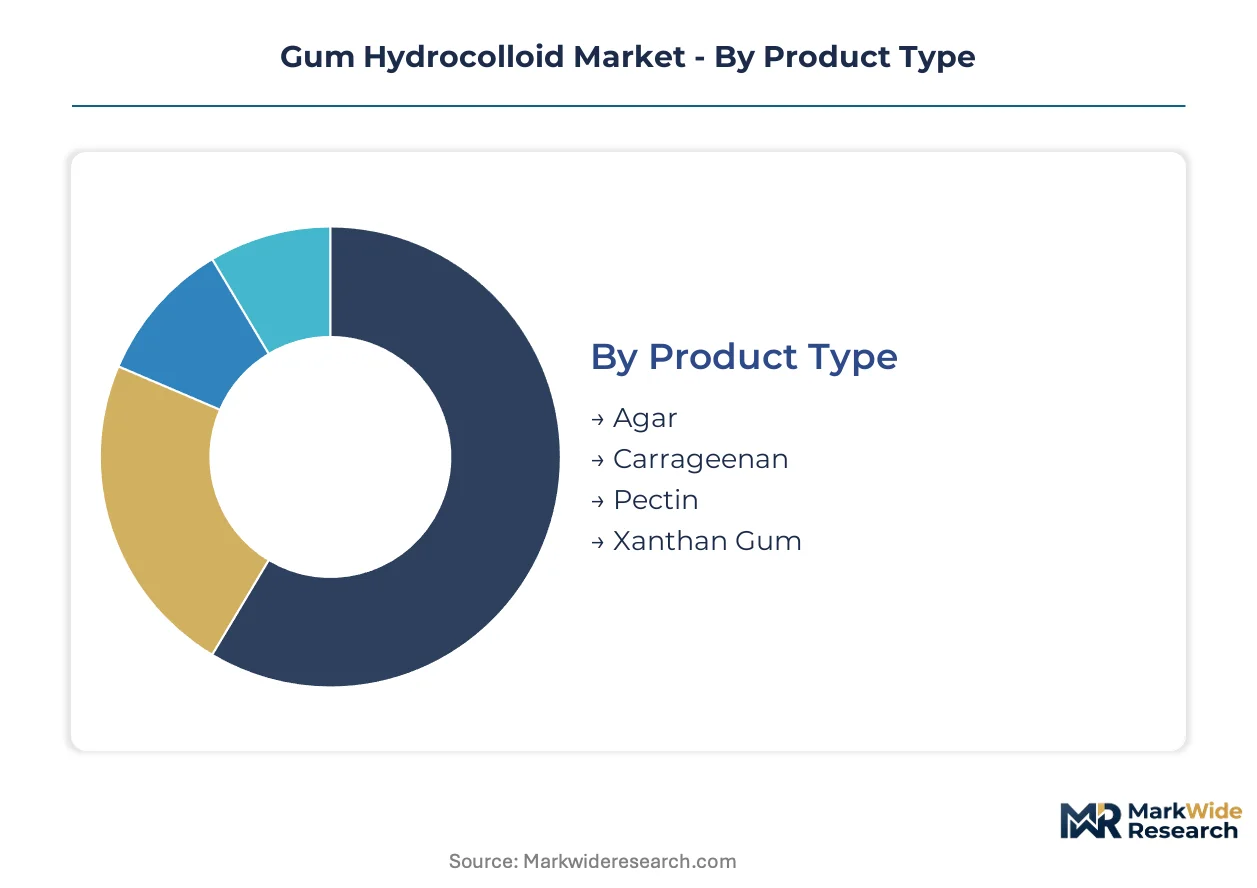
Hydrocolloid procurement channels diverge sharply by product physics and certification grade. Powder and liquid forms flow through integrated ingredient platforms, while pharmaceutical-grade agar demands direct laboratory supply contracts with documented chain-of-custody.
Product Type:
Carrageenan and xanthan gum dominate commodity procurement through distributors, whereas agar and premium pectin grades bypass intermediaries for direct manufacturer relationships.
- Carrageenan:Extracted from red seaweed through alkaline processing, this sulfated galactan delivers thermoreversible gelation critical to dairy stabilization. North American plant-based meat processors specify refined kappa grades for burger analogues, with EFSA purity mandates compressing acceptable impurity thresholds.
- Xanthan Gum:Microbial fermentation of Xanthomonas campestris yields this extracellular polysaccharide with pseudoplastic rheology. Sauces and dressings in US Midwest contract manufacturing corridors absorb volume, though fermentation capacity scarcity constrains spot market availability.
- Agar:Laboratory culture media and pharmaceutical cell therapy manufacturing drive demand for gel strength specifications exceeding 900 g/cm².
- Pectin:Acid-stable beverage systems in European dairy applications command premium positioning amid EFSA re-evaluation timelines.
By volume, carrageenan leads. By growth pace, xanthan gum is climbing the fastest.
Application:
Cost tier stratification separates commodity thickeners from performance-critical stabilizers, with beverage and dairy commanding specification premiums over bakery.
- Dairy:Yogurt and ice cream formulations require hydrocolloid synergy for freeze-thaw stability and mouthfeel control. EU processors reformulate around EFSA-degraded carrageenan restrictions, accelerating demand for refined extraction grades.
- Beverages:Acid-stable pectin systems dominate juice and soft drink applications where protein stabilization and pulp suspension determine shelf-life extension. China's SAMR national food safety standards and India's FSSAI additive regulations create parallel compliance tracks for Asia-Pacific market entry.
- Bakery Products:Bread and pastry applications leverage hydrocolloid moisture retention for extended freshness dating.
- Sauces:Viscosity modification in pourable and spoonable dressings relies on xanthan gum's shear-thinning behavior.
Dairy captures the highest value per kilogram. Beverages represent the steepest expansion trajectory.
End User:
Customer type determines certification burden, with pharmaceutical and nutraceutical buyers imposing ISO 22000 and GMP documentation that food manufacturers often bypass.
- Food Industry:Clean-label formulation mandates compress specification tolerances across bakery, dairy, and meat alternative applications. North American processors now specify complete texture systems rather than raw polysaccharides, shifting technical risk upstream.
- Pharmaceutical:Cell therapy manufacturing and culture media production demand agar with documented gel strength and endotoxin compliance. ISO 22000 certification timelines of 12-18 months filter supplier pools to established laboratory-grade producers.
- Cosmetics:Personal care formulations utilize hydrocolloid rheology modifiers for emulsion stability and skin-feel optimization.
- Nutraceuticals:Dietary supplement gelling and encapsulation applications require food-grade certification with enhanced traceability.
Food industry volume dominates. Pharmaceutical margins are expanding most quickly.
Form:
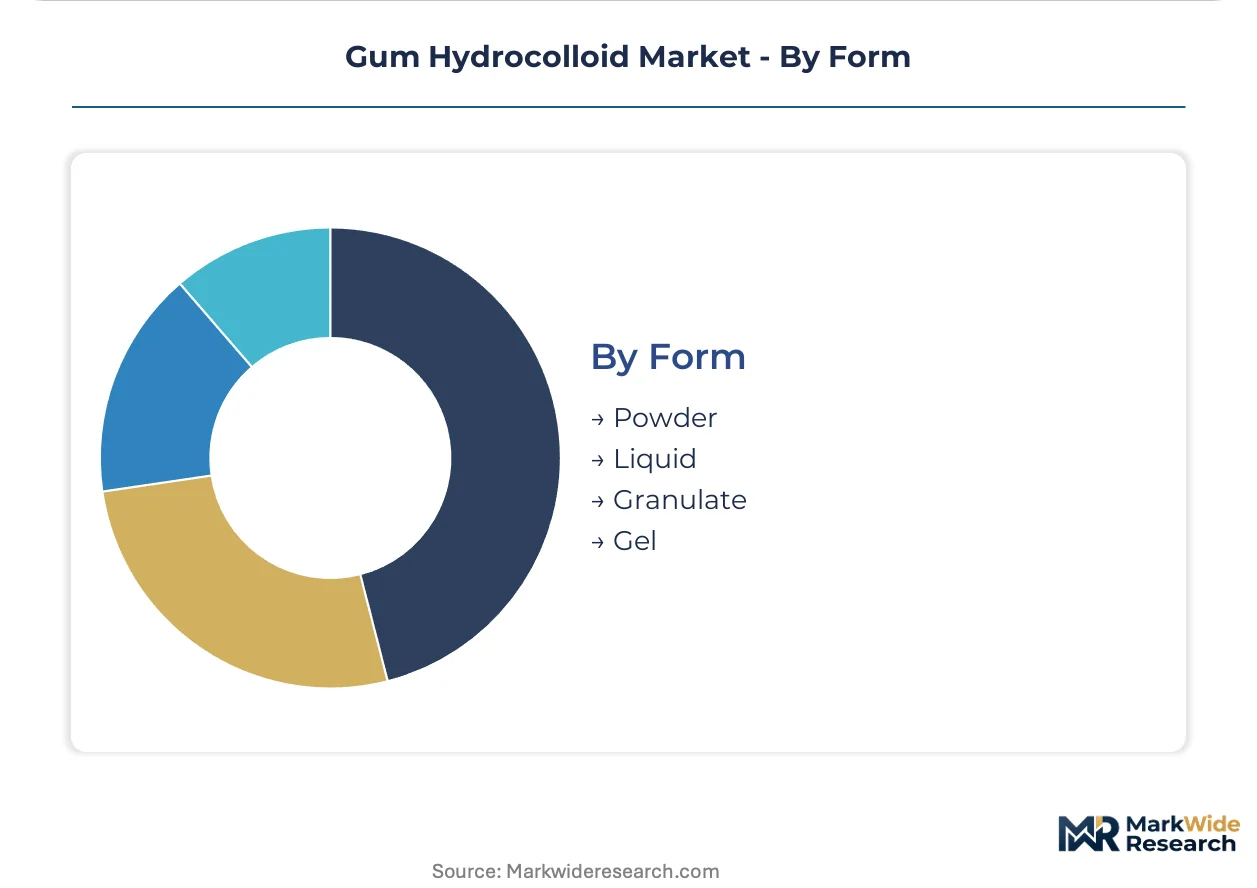
Supply concentration in Southeast Asian seaweed processing shapes powder and granulate availability, while liquid and gel forms concentrate among microbial fermentation specialists with captive bioreactor infrastructure.
- Powder:Spray-dried and drum-dried hydrocolloid powders constitute the standard procurement unit for food manufacturing scale-up. Indonesia and Philippines seaweed concentration secures carrageenan raw material access for Asian and European processors.
- Liquid:Pre-hydrated hydrocolloid dispersions eliminate dust handling and hydration time in high-throughput beverage plants.
- Granulate:Agglomerated particles improve dispersibility in dry-blend bakery premixes.
- Gel:Pre-formed gel matrices serve specialized pharmaceutical and cosmetic applications requiring precise rheological profiles.
Powder leads by volume. Liquid is gaining share fastest in North American beverage corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU EFSA purity standards and US FDA GRAS pathways are redirecting investment toward certified extraction capacity in coastal seaweed processing zones. Indonesia and the Philippines concentrate raw material access for carrageenan supply chains serving European dairy reformulation.
United States
Plant-based meat processors in the Midwest contract manufacturing corridor specify complete hydrocolloid texture systems for burger analogues. FDA GRAS self-affirmation requirements govern xanthan gum deployment in acid-stable beverage applications. Chicago-area ingredient platforms now source pre-blended stabilizers rather than single polysaccharides.
Germany
Dairy yogurt and ice cream formulators accelerate refined carrageenan procurement to meet EFSA degraded-grade restrictions. REACH substance evaluation protocols now classify certain extraction grades as requiring authorization. Hamburg serves as the distribution hub for EFSA-compliant hydrocolloid imports into Central European processing plants.
China
SAMR national food safety standards create parallel compliance tracks for acid-stable pectin systems in juice applications. Domestic fermentation capacity expansion targets xanthan gum supply security for sauce and dressing manufacturers. Shandong Province concentrates bioreactor infrastructure serving microbial polysaccharide output.
Indonesia
Carrageenan raw material harvesting in Sulawesi and Sumatra archipelagos supplies Asian and European refined extraction facilities. El Niño events and warming waters destabilize seasonal input costs for kappa and iota fractionation. Makassar processing clusters specialize in ionic precipitation methods for dairy-grade specifications.
India
FSSAI additive harmonization with Codex Alimentarius opens formulation contract opportunities for compliant exporters of agar and pectin grades. Pharmaceutical culture media manufacturers in Hyderabad and Bangalore demand laboratory-grade gel strength documentation. Maharashtra food processors trial hydrocolloid pre-blends in bakery moisture retention applications.
Gum Hydrocolloid Market Vendor Landscape
Listed leaders compete with private specialists across certification grade and supply security dimensions. The vendor base stratifies between integrated ingredient platforms with backward seaweed sourcing and microbial fermentation specialists with captive bioreactor networks. Three archetypes dominate: extraction-integrated processors, fermentation-centric bioproducers, and pre-blend formulation platforms. Competitive moves concentrate on ISO 22000 certification acceleration and precision fermentation capacity licensing.
Among integrated ingredient platforms, Kerry Group and Cargill Incorporated exemplify supply security strategies through upstream control over Southeast Asian seaweed sourcing and Midwest distribution infrastructure. CP Kelco occupies a position within the fermentation-specialist tier, representing microbial biopolymer production at scale. DuPont and BASF sit within the diversified chemical conglomerate archetype, leveraging existing industrial biotechnology networks to service pharmaceutical and food-grade specifications without dedicated hydrocolloid-only positioning.
| Leading Market Players |
|---|
| Tate & Lyle Plc |
| Kerry Group |
| DuPont |
| BASF |
| Ashland |
| Ingredion Incorporated |
| CP Kelco |
| Palsgaard |
| Cargill Incorporated |
| Others |
Supply Flow & Price Mechanics
Cellulose gum substitution in low-viscosity applications is redrawing procurement geography while compressing price premiums for commodity hydrocolloid grades. This displacement simultaneously shifts volume toward paper and textile-derived alternatives and forces carrageenan and xanthan suppliers to defend positioning through certification tiering.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade agar and commodity dairy thickeners. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 22000 documentation burden and EFSA purity compliance. Cost compression in standard-grade carrageenan is intensifying because El Niño harvest volatility feeds raw material uncertainty. Small-scale bakery processors exhibit highest price sensitivity; cell therapy manufacturers accept premium positioning for gel strength documentation.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for Southeast Asian seaweed processors serving European dairy reformulators. Geographic concentration in Indonesia, the Philippines, and coastal China anchors carrageenan raw material access. Production draws from red seaweed biomass, alkaline processing chemicals, and ionic precipitation reagents. Single-source vulnerability runs through Sulawesi harvesting clusters exposed to warming water events. Distribution runs through integrated ingredient platforms with backward sourcing control rather than spot-market distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrocolloid procurement is shifting toward pre-blend platform economics as North American meat processors outsource complete texture systems rather than sourcing raw polysaccharides. This interoperability pivot favors suppliers with integrated formulation capabilities over commodity extraction specialists.
For Market Incumbents: Compound certification advantage by accelerating ISO 22000 coverage across Southeast Asian extraction facilities before EFSA purity mandates tighten further. Lock in long-term offtake contracts with Midwest plant-based meat contract manufacturers to preempt fermentation-capacity entrants. Defend against cellulose gum substitution by emphasizing gel strength performance in dairy stabilization applications. For New Entrants and Emerging Players: Precision fermentation service-layer gaps in xanthan gum production present white-space entry points where incumbent capacity constraints create supply security demand. Target pharmaceutical-grade agar segments where laboratory documentation requirements filter established competitors. Deploy compact bioreactor arrays for distributed manufacturing economics as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-specialist archetypes with captive microbial production infrastructure and precision biology licensing potential. Five-to-ten-year viability hinges on synthetic biology platform convergence rather than commodity extraction scale. Watch for CRISPR-edited strain commercialization announcements as the signal indicating platform economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Sourcing | Cargill's Sulawesi harvesting control secures kappa carrageenan supply for EFSA-compliant dairy reformulation. |
| Precision Fermentation Capacity Licensing | CP Kelco's microbial biopolymer expertise enables novel hydrocolloid molecular architectures through synthetic biology platforms. |
| ISO 22000 Certification Acceleration | Kerry Group's food safety management coverage raises competitive barriers against smaller unqualified processors. |
| Pre-Blend Formulation Platform Expansion | Midwest contract manufacturers now specify complete texture systems rather than single-hydrocolloid procurement. |
| Pharmaceutical-Grade Agar Documentation Investment | Laboratory-grade gel strength certification above 900 g/cm² captures cell therapy manufacturing premium positioning. |
Methodological Framework
Cross-validation between extraction facility audits and fermentation capacity databases anchors the qualitative findings in this study. Primary interviews with seaweed processing plant managers, dairy formulation technologists, pharmaceutical culture media procurement leads, and bioreactor operations directors combined with secondary validation from FAO trade statistics, EFSA additive evaluations, FSSAI regulatory filings, and SEC chemical sector disclosures. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Sensitivity analysis across El Niño severity scenarios and fermentation yield assumptions stress-tests projection robustness. Segmentation dimensions modeled include hydrocolloid type, application category, end-user certification tier, form factor, and regional regulatory cluster. CAGRs derive from compound growth trajectory fitting across the projection horizon. Industry-specific forecast inputs incorporate seaweed harvest yield volatility and precision fermentation scale-up curves.
Forecasts assume regulatory continuity in EU EFSA purity regimes, US FDA GRAS pathways, and India FSSAI harmonization; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
France Feed Additives Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market