
 Tara Gum Market | 2026-2036
Tara Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Tara Gum Market Intelligence
The FSSC 22000 certification requirement for food-grade hydrocolloids is unwinding the competitive landscape, favoring suppliers with documented safety and quality management systems. TIC Gums leverages its extensive formulation expertise to serve specialized applications in the food industry. Argos Peru, a key supplier from the primary sourcing region, anchors a significant portion of the raw material supply chain. UNIPEKTIN Ingredients competes on the basis of its refined and purified tara gum offerings for high-value end uses.
Tara gum is a natural hydrocolloid extracted from the endosperm of Caesalpinia spinosa seeds. Functionally, it acts as a thickening agent and stabilizer in aqueous systems, often used to create specific textures and prevent syneresis in food products. Within applications, dairy products and sauces represent major volume segments due to the gum's synergistic effects with other hydrocolloids. The food & beverage manufacturing end-user industry dominates consumption, with nutraceuticals emerging as a high-margin niche for specialized powder grades.
Market access is governed by food additive regulations, such as the U.S. FDA's GRAS notices and the European Food Safety Authority's (EFSA) approval under the E number E417. These frameworks dictate purity criteria, acceptable daily intake levels, and labeling requirements for tara gum in consumer products. Stakeholders must now focus on securing sustainable and traceable supply chains from Peru to mitigate price volatility and meet corporate social responsibility mandates.
Market Dynamics
The imperative for food safety certification is the central force reconfiguring the tara gum supply base. Mandates like FSSC 22000 are creating a clear divide between certified, traceable suppliers and traditional commodity traders, influencing procurement decisions across the food and beverage industry.
Growth Catalysts
- Clean-Label Formulation:Demand from dairy and sauce producers for natural texturizers, recognized under frameworks like the FDA's GRAS status, propels adoption as a replacement for chemically modified ingredients.
- Functional Synergies:The ability of tara gum to enhance the viscosity and stability of other hydrocolloids, such as xanthan and carrageenan, expands its utility in complex food systems, particularly in frozen desserts and dressings.
- Geographic Demand Concentration:Major food and beverage manufacturing clusters in the United States create concentrated pockets of demand, rewarding suppliers who can ensure consistent volume and quality into these key production zones.
Market Restraints
- Supply Source Dependency:The high geographic concentration of Caesalpinia spinosa cultivation in Peru creates vulnerability to climate-related harvest disruptions, political instability, and subsequent price volatility across the global market.
- Substitution from Other Gums:In cost-sensitive applications, tara gum faces direct competition from other hydrocolloids like guar gum, locust bean gum, and carboxymethyl cellulose, especially when its unique textural properties are not essential.
- Regulatory Purity Standards:Strict purity criteria set by bodies like the European Food Safety Authority under E417 require significant processing investment, potentially acting as a barrier for smaller, less capitalized producers.
Strategic Opportunities
- Nutraceutical Applications:The development of highly purified, specialized powder grades opens a high-margin opportunity within the nutraceutical sector for use in dietary supplements and functional food powders.
- Expansion in Asian Food Processing:Growing food manufacturing sectors in countries like Indonesia and Vietnam present an underpenetrated market for tara gum, particularly in dairy, bakery, and convenience food applications.
- Blended System Development:Formulating synergistic blends of tara gum with plant-based proteins and fibers offers a path to creating novel texturizing systems for the expanding plant-based food and beverage market.
Industry Challenges
- Certification Compliance Burden:The significant investment and time required for suppliers to achieve and maintain FSSC 22000 certification can be a substantial operational hurdle, particularly for smaller enterprises in sourcing regions.
- Supply Chain Traceability:Implementing and documenting full, verifiable traceability from individual farms in Peru to the final product is a complex logistical challenge driven by corporate social responsibility mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tara Gum Market |
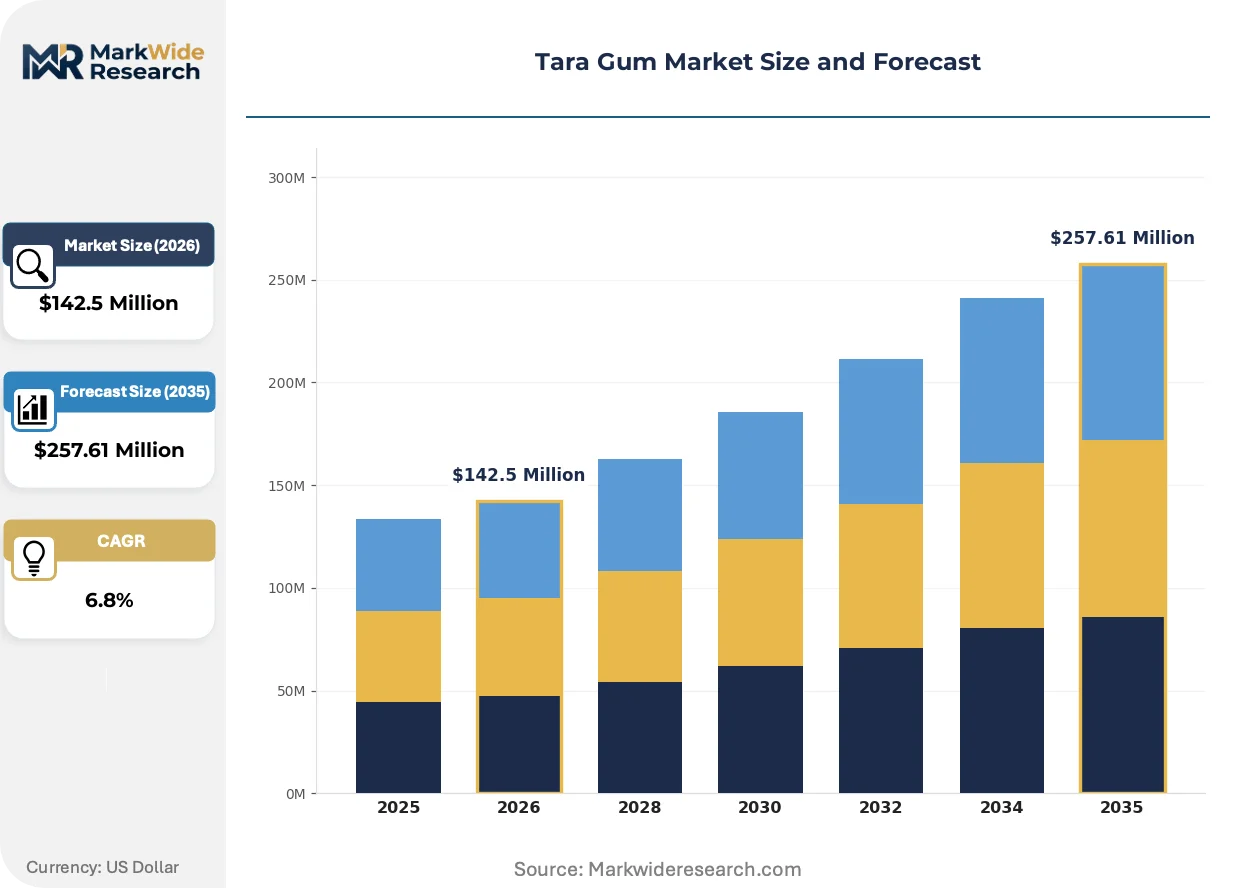
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid Concentrate, Granules, Capsules Application: Dairy Products, Bakery, Sauces, Meat Processing, Beverages End User Industry: Food & Beverage Manufacturing, Confectionery Production, Nutraceuticals, Animal Feed, Cosmetics Packaging Type: Bulk Bags, Sachets, Drums, Bottles, Tins |
| Companies Covered | TIC Gums, Argos Peru, Exandal, UNIPEKTIN Ingredients, Polygal, Molinos Asociados, Gelymar, Ingredients Solutions, Silvateam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tara Gum Market Strategic Shifts & Innovations
Purity, traceability, and functional specialization are the dominant themes driving innovation. The market is evolving from a single commodity product toward a portfolio of specialized grades, each tailored to specific performance requirements and regulatory expectations in high-value end-use sectors.
Advanced purification methods are enabling the creation of highly refined tara gum grades. These techniques are being adopted by specialty ingredient manufacturers to serve demanding sectors like nutraceuticals and medical foods. This evolution is decomposing the traditional, uniform market into a multi-tiered structure differentiated by purity, functionality, and certification level.
European Union sustainability mandates, particularly the Corporate Sustainability Reporting Directive (CSRD), are impacting procurement. The directive compels large companies to disclose supply chain risks, including environmental and social factors in sourcing regions like Peru. Food and beverage manufacturers are most affected, now demanding verifiable proof of sustainable harvesting and ethical practices from their hydrocolloid suppliers.
Buyer behavior is shifting toward a preference for suppliers with comprehensive certifications. This disrupts traditional purchasing models that were based primarily on price, favoring vertically integrated producers who can provide full transparency. This trend is most visible within multinational food companies headquartered in the United States and Europe, responding to investor and consumer pressure for ethical sourcing.
Tara Gum Market Segmentation
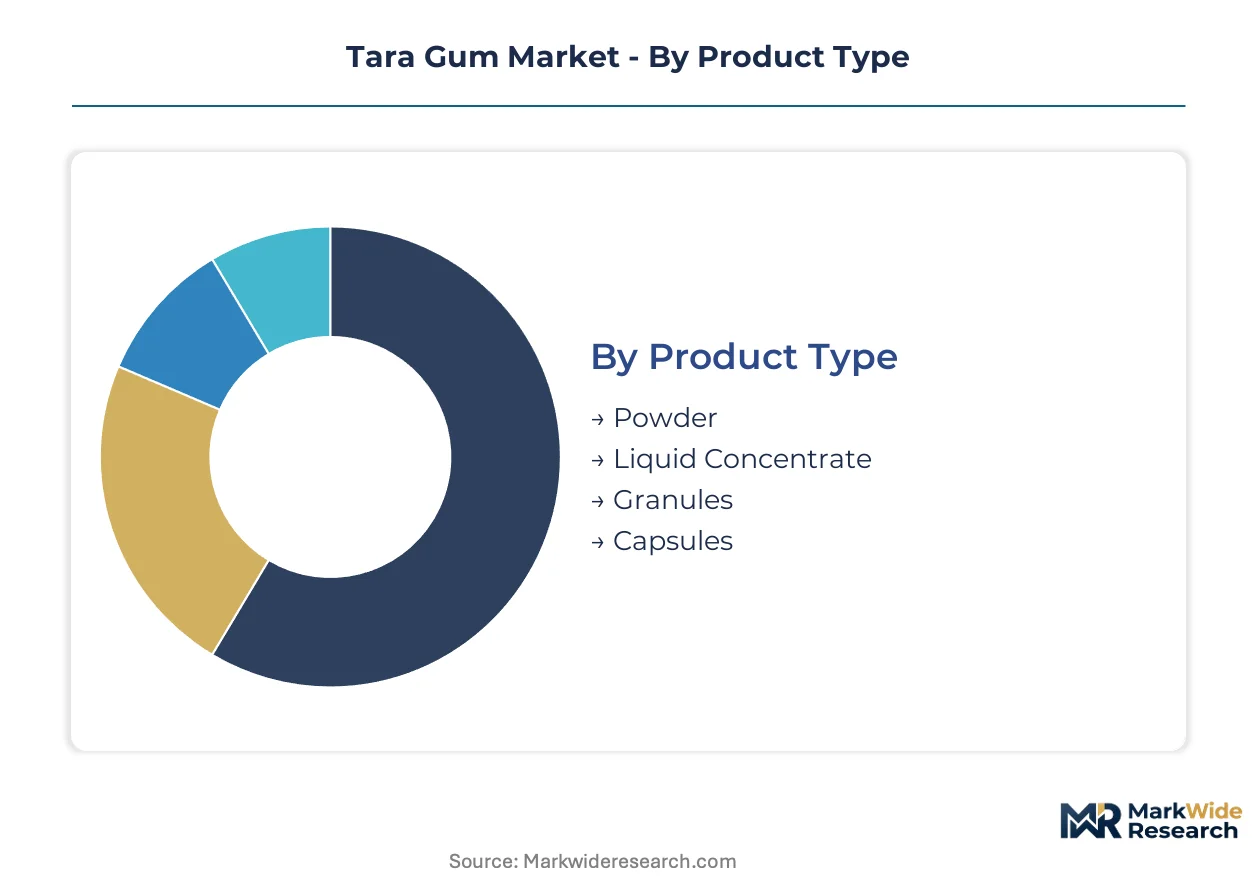
This market's segmentation highlights the diverse forms and applications of tara gum across various industries. Understanding these distinct segments is crucial for stakeholders to identify specific growth vectors and tailor product offerings. The different product types and end-use sectors demonstrate the ingredient's functional versatility.
Product Type:
The distribution channels for tara gum vary significantly based on its processed form.
- Powder:This is the most common form, offering ease of handling and a longer shelf life for industrial use. Demand concentrates in large-scale food manufacturing operations in the United States, driven by the need for consistent bulk ingredients.
- Liquid Concentrate:This pre-dissolved or dispersed form reduces processing time and enhances solubility for end-users. Demand is growing in beverage production, where precise viscosity control and rapid incorporation are critical for efficiency.
- Granules:Granules offer improved flowability and reduced dusting compared to powder, often preferred in specific dry blending applications.
- Capsules:This is a specialized, low-volume segment primarily for nutraceutical and dietary supplement formulations requiring precise dosage.
Powder dominates the installed base. Liquid Concentrate is where expansion concentrates.
Application:
Tara gum's functional properties dictate its suitability across a range of food applications.
- Dairy Products:Tara gum functions as a stabilizer and thickener, preventing syneresis and improving texture in yogurts and ice creams. Demand is strong from clean-label initiatives in European dairy companies.
- Sauces:It provides viscosity and emulsion stability, enhancing mouthfeel and preventing phase separation in dressings and marinades. Manufacturers in the United States value its natural profile for premium sauce lines.
- Bakery:Used to improve dough rheology, moisture retention, and crumb structure in gluten-free and conventional baked goods.
- Meat Processing:Acts as a binder and water retention agent in processed meats, enhancing texture and reducing cook loss.
- Beverages:Provides body and stabilizes suspensions in fruit juices, plant-based drinks, and ready-to-drink formulations.
Dairy Products and Sauces collectively account for the largest volume consumption within this segment.
End User Industry:
The value proposition for tara gum varies significantly across different end-user industries.
- Food & Beverage Manufacturing:This sector consumes the largest volumes of tara gum, utilizing it as a cost-effective thickener and stabilizer. Consistent supply and regulatory compliance are paramount for these large-scale producers.
- Nutraceuticals:This high-margin niche demands highly purified and specialized grades of tara gum for dietary supplements and functional food powders. Manufacturers prioritize stringent purity standards and specific functional attributes.
- Confectionery Production:Tara gum contributes to texture, chewiness, and moisture control in candies, gums, and jellies.
- Animal Feed:Incorporated as a binder and texturizer, improving palatability and nutrient delivery in pet food and livestock feed.
- Cosmetics:Functions as a rheology modifier and emulsifier in personal care products, including lotions and creams.
Food & Beverage Manufacturing represents the core demand, while Nutraceuticals offers the steepest expansion trajectory.
Packaging Type:
The choice of packaging for tara gum reflects the logistical requirements and scale of the purchasing customer.
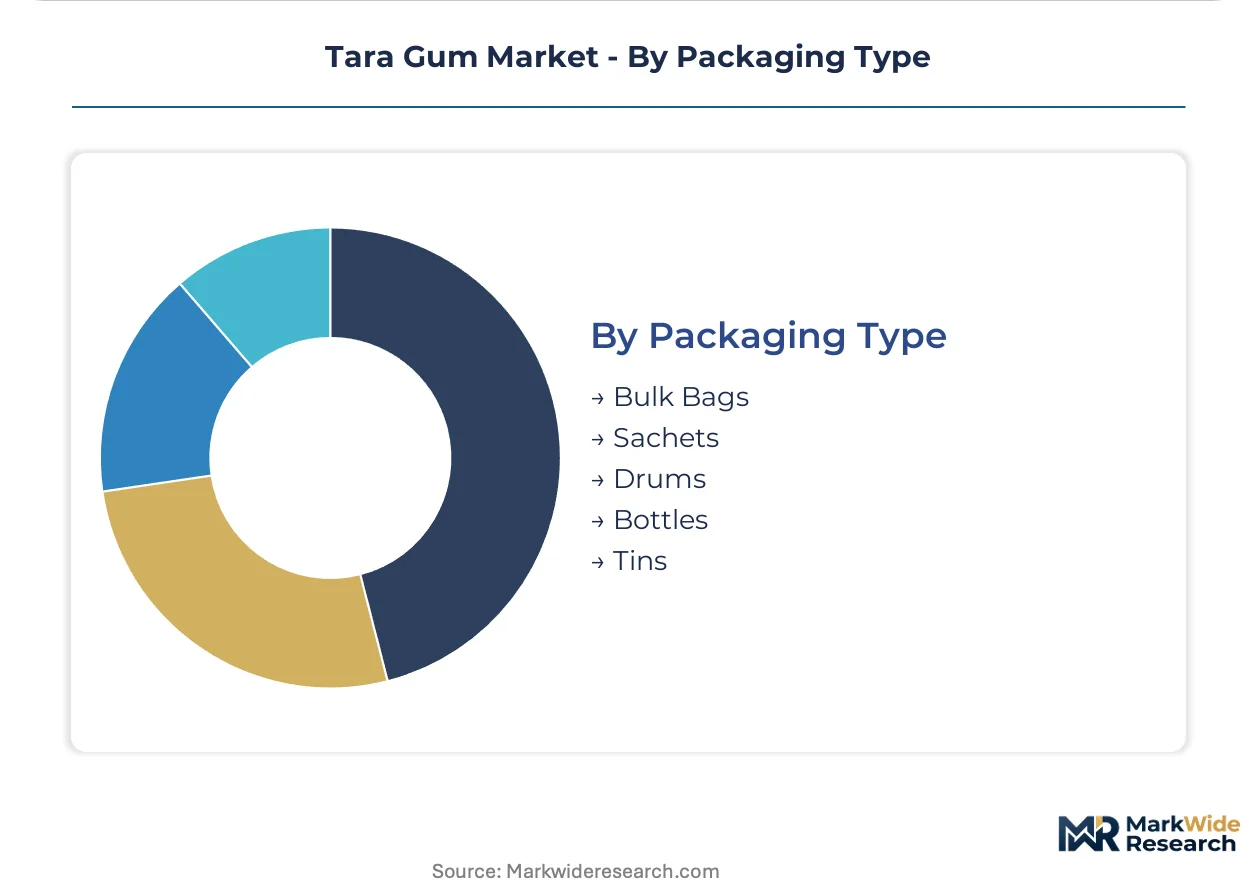
- Bulk Bags:These large-volume containers, typically 500-1000 kg, cater to industrial-scale food and beverage manufacturers. They optimize transport efficiency and reduce handling costs for high-volume users.
- Drums:Medium-sized packaging, often 25-200 kg, is used by intermediate processors or smaller industrial clients. Drums provide protection and ease of handling for ingredients requiring moderate volumes.
- Sachets:Small, portion-controlled packaging for specialized applications or retail distribution, ensuring precise dosing.
- Bottles:Used for liquid concentrate forms or highly specialized, low-volume applications, prioritizing product integrity.
- Tins:Offer robust protection against moisture and light, often for premium or sensitive powder grades in specific markets.
Bulk Bags and Drums facilitate the majority of industrial transactions for tara gum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The imperative for food safety certification, such as FSSC 22000, significantly influences regional market dynamics for tara gum. Regulatory frameworks like the U.S. FDA's GRAS classifications reinforce the use of natural hydrocolloids across diverse food applications. European Food Safety Authority (EFSA) approvals further shape market access and product development.
United States
Demand for clean-label formulation from dairy and sauce producers drives significant tara gum consumption in the United States. The U.S. FDA's GRAS notices facilitate market entry for natural thickeners and stabilizers. Major food and beverage manufacturing hubs in California and the Midwest concentrate high-volume procurement activities.
Germany
European clean-label initiatives and functional synergies with other hydrocolloids boost tara gum adoption in Germany. The European Food Safety Authority's E417 approval dictates purity standards for food additives. Dairy product manufacturers in Bavaria and North Rhine-Westphalia integrate tara gum for texture improvement.
China
The expanding food and beverage manufacturing sector in China increasingly seeks natural texturizers for processed foods. China's national food safety standards (GB standards) guide ingredient formulation and quality control. Food processing zones in the Yangtze River Delta drive demand for bulk tara gum ingredients.
Brazil
Growth in plant-based food and beverage production, alongside traditional dairy applications, increases tara gum demand in Brazil. ANVISA regulations for food additives ensure product safety and labeling compliance. São Paulo's extensive food industry ecosystem supports significant ingredient procurement and distribution.
India
The rising demand for convenience foods and clean-label products propels tara gum usage in India. The Food Safety and Standards Authority of India (FSSAI) sets strict guidelines for hydrocolloid use. Food processing clusters in Maharashtra and Gujarat actively source natural stabilizers for various applications.
Tara Gum Market Key Industry Players
Listed leaders compete with private specialists across supply chain integration and product purity tiers in the tara gum market. The competitive landscape is fragmented, with numerous regional players operating alongside a few global ingredient suppliers. Strategic archetypes include vertically integrated producers, specialized refiners focusing on high-purity grades, and commodity traders. Capacity expansion, strategic partnerships, and portfolio diversification are dominant competitive moves among these diverse entities.
Within the specialized ingredient formulation tier, TIC Gums exemplifies expertise in tailored hydrocolloid solutions for the food industry. This US-based company offers a broad portfolio of gums and stabilizers. Argos Peru, a key supplier from the primary sourcing region, anchors a significant portion of the raw material supply chain, ensuring consistent bulk ingredient availability. UNIPEKTIN Ingredients, a Switzerland-based entity, occupies a position among refiners offering highly purified tara gum offerings for high-value end uses. These companies collectively represent the varied approaches to market access and product differentiation within the tara gum sector.
| Leading Market Players |
|---|
| TIC Gums |
| Argos Peru |
| Exandal |
| UNIPEKTIN Ingredients |
| Polygal |
| Molinos Asociados |
| Gelymar |
| Ingredients Solutions |
| Silvateam |
Cost & Logistics Intelligence
Tara gum's functional versatility, enabling its substitution for chemically modified ingredients, simultaneously reshapes supply geography and pricing economics. This shift rewards suppliers who can guarantee both consistent quality and robust food safety certifications.
Pricing Analysis
Certification level (FSSC 22000) creates the primary spread in tara gum pricing. The dominant pricing structure combines commodity spot pricing for bulk grades with contract-based long-term offtake agreements for specialized, certified products. Purity grade and volume scale serve as additional price differentiation drivers. Pricing pressure stems from substitution by other gums like guar gum in cost-sensitive applications. Large-scale Food & Beverage Manufacturing exhibits high price sensitivity for bulk ingredients, while Nutraceuticals show lower price sensitivity for highly purified grades.
Supply Chain Analysis
Port congestion and container availability on trans-Pacific routes significantly impact inbound logistics costs for tara gum. Geographic supply concentration for *Caesalpinia spinosa* cultivation centers almost exclusively in Peru. The raw material supply chain depends on consistent harvests of these seeds. Single-source vulnerability to climate-related harvest disruptions in Peru represents a structural risk, leading to price volatility. Downstream distribution runs through a mix of vertically integrated suppliers and specialized ingredient distributors, serving direct-to-manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tara gum market offers fragmentation opportunities. Clean-label formulation demand from dairy and sauce producers creates niches for specialized, certified grades.
For Market Incumbents: Consolidate raw material sourcing through long-term contracts with Peruvian growers to mitigate supply chain volatility. Invest in advanced purification technologies and FSSC 22000 certification to counter substitution threats from other hydrocolloids. Develop synergistic blends with plant-based proteins to capture the expanding plant-based food market. Expand R&D into high-value nutraceutical applications.
For New Entrants and Emerging Players: Lead with specialized powder grades for the high-margin nutraceutical sector, emphasizing purity and specific functional attributes. Target underpenetrated Asian food processing markets, such as Indonesia and Vietnam, with tailored product offerings. Focus on verifiable traceability and sustainability claims as a key go-to-market differentiator. Develop expertise in blending systems for novel food textures.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized refiners with strong certification portfolios and traceable supply chains. Long-term viability rests on securing sustainable raw material access and functional differentiation. Acquisition targets should include vertically integrated producers with established Peru sourcing and FSSC 22000 compliance. Increasing M&A activity among ingredient processors serves as a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Peru | Secures raw material supply and mitigates climate-related risks. |
| FSSC 22000 Certification Investment | Strengthens market access and supplier credibility with multinational buyers. |
| Synergistic Blend Development | Creates novel texture systems for plant-based food and beverage applications. |
| Nutraceutical Grade Portfolio Expansion | Captures high-margin demand from dietary supplement manufacturers. |
| Strategic Partnerships in Asia | Penetrates emerging food processing markets in countries like Vietnam. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings. Industry stakeholders interviewed included R&D directors, procurement managers, regulatory affairs specialists, and ingredient suppliers. Secondary data sources comprised trade association reports, food safety authority publications (U.S. FDA, EFSA), and company financial disclosures. This approach ensured bottom-up and top-down triangulation for market sizing.
Sensitivity analysis informed the forecast framework, accounting for potential shifts in market dynamics across the projection horizon. The model segmented the market by product type, application, end-user industry, and packaging type. Compound annual growth rates were derived from historical trends and anticipated shifts in demand drivers. Key forecast inputs included clean-label adoption rates and regulatory approval timelines.
The analysis sits within stated boundaries; outcomes outside significant climate events impacting Peru's harvest or major new hydrocolloid discoveries would require recalibration. Forecasts reflect assumptions regarding regulatory stability and market access frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Bakery Stabilizers Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market