
 Feed Palatability Enhancers and Modifiers Market | 2026-2036
Feed Palatability Enhancers and Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Palatability Enhancers and Modifiers Market Analysis
Natural botanical extracts is pivoting toward synthetic flavor replacement as enzyme costs decline and clean-label pressure intensifies across livestock supply chains. Cargill Incorporated leverages its oilseed processing infrastructure to secure captive supply of palatability precursors. Kerry Group Plc anchors European flavor science capabilities to serve compound feed manufacturers with tailored masking systems. BASF SE differentiates through fermentation-derived nucleotides that enhance umami response in swine diets.
Feed palatability enhancers and modifiers comprise flavor compounds, sweeteners, nutritional additives, and colorants formulated to stimulate voluntary feed intake, mask anti-nutritional factors, and stabilize ration palatability across species. These products typically incorporate volatile aromatic molecules, high-intensity sweeteners such as neohesperidin dihydrochalcone, and Maillard reaction products applied at inclusion rates between 0.01% and 0.5% by feed weight. Flavors command the dominant margin pool in the product type dimension due to formulation complexity and species-specific customization requirements. Aquaculture represents the fastest-expanding application segment as marine feed producers confront carnivorous species' extreme sensitivity to off-flavors from alternative proteins.
The EU Green Deal and REACH frameworks restrict synthetic additive approvals, compelling suppliers to validate natural alternatives through EFSA feeding trials. The US FDA Center for Veterinary Medicine maintains color additive and GRAS notification pathways that shape product registration timelines for entrants. China's MEE enforces discharge standards on fermentation facilities producing yeast-based palatability agents, raising compliance costs for regional manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation lock-in on single-chemistry platforms.
Market Dynamics
The EU Green Deal is forcing compound feed manufacturers to abandon synthetic palatability systems and rebuild formulation platforms around validated natural alternatives, compressing approval timelines and reshaping supplier qualification criteria.
Growth Catalysts
- REACH framework restrictions:The EU's tightening synthetic additive approvals under ECHA oversight is redirecting R&D budgets toward botanical extract validation, accelerating natural flavor adoption across European livestock operations.
- Brazilian integrated poultry sector:Large-scale producers in São Paulo and Paraná states are systematically reformulating rations to cut feed refusal rates, creating concentrated demand for species-specific masking systems.
- Enzyme cost decline:Manufacturing scale efficiencies in fermentation-derived enzyme production are enabling cost-competitive synthetic-to-natural transitions in swine and poultry diet formulations.
Market Restraints
- EFSA feeding trial requirements:Natural additive validation demands extensive safety and efficacy documentation, extending product registration cycles and locking capital in regulatory pipelines.
- Chinese fermentation facility compliance:MEE discharge standards on yeast-based palatability agent production are raising fixed costs for regional manufacturers serving domestic aquaculture feed mills.
- Species-specific formulation complexity:Carnivorous aquaculture species exhibit extreme sensitivity to off-flavors from alternative proteins, limiting protein source flexibility and constraining formulation latitude.
Strategic Opportunities
- India's aquaculture expansion:Andhra Pradesh and Gujarat shrimp producers are scaling intensive pond systems, opening demand for marine feed palatability solutions masking fishmeal substitution effects.
- US FDA GRAS notification pathway:The Center for Veterinary Medicine's streamlined self-affirmation process offers faster market entry for novel natural flavor precursors compared to EU additive authorization.
- Precision fermentation convergence:Integration of synthetic biology with traditional flavor chemistry is enabling bespoke nucleotide production tailored to species-specific umami receptor profiles.
Industry Challenges
- Reformulation lock-in risk:Suppliers building single-chemistry natural platforms face stranded asset exposure if regulatory divergence between EFSA and FDA validation protocols widens.
- Flavor chemist scarcity:The intersection of feed science and volatile organic compound expertise sits in limited academic pipelines, constraining product development velocity for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Palatability Enhancers and Modifiers Market |
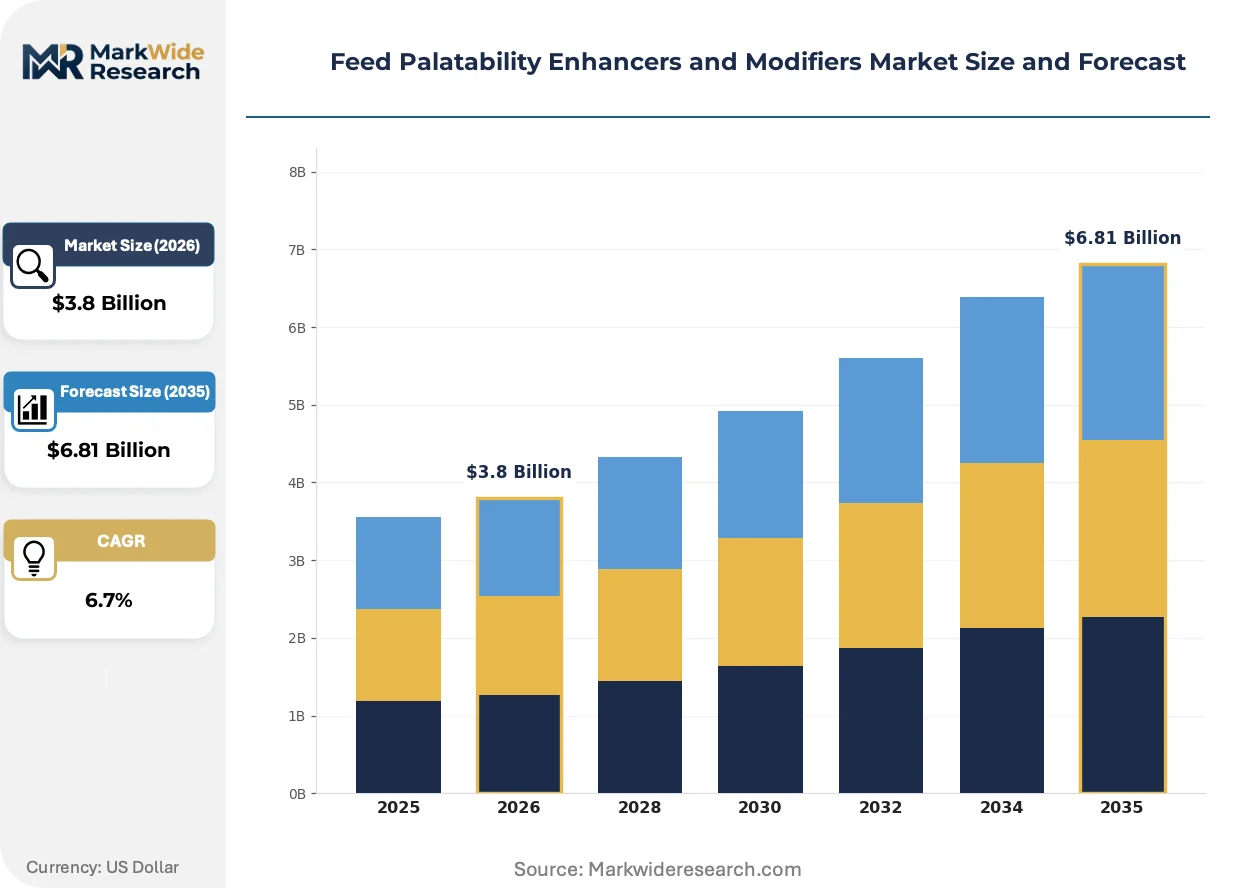
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavors, Nutritional Additives, Sweeteners, Colorants Application: Cattle, Poultry, Swine, Aquaculture Form: Granules, Powders, Liquids, Pellets Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Cargill Incorporated, Kerry Group Plc, Symrise AG, Adisseo, DuPont, Associated British Foods Plc, Kemin Industries, BASF SE, Elanco Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Palatability Enhancers and Modifiers Market Emerging Trajectories
Biotechnology and regulatory science are colliding to redefine how palatability systems are discovered, manufactured, and approved. Three intersecting movements are compressing development cycles while raising technical barriers to entry.
Precision fermentation of nucleotides and Maillard reaction precursors is electrifying the ingredient sourcing landscape. Aquaculture feed producers in Norway and Chile are adopting these bioengineered flavor enhancers at twice the rate of land-based livestock operations. The technology is compressing traditional botanical extraction supply chains and enabling year-round consistency in volatile aromatic profiles regardless of agricultural harvest variability.
EFSA's 2023 updated guidance on feed additive environmental risk assessment is extending data requirements for novel natural compounds. Manufacturers must now submit extended residue studies and ecosystem impact modeling alongside traditional toxicity dossiers. The aquaculture segment bears the heaviest compliance burden as marine discharge pathways trigger additional fate-and-transport analysis, pushing smaller suppliers toward regulatory consulting partnerships.
Integrated poultry and swine operations are consolidating procurement authority at the headquarters level, displacing decentralized mill-level purchasing. Large Brazilian and US producers now mandate centralized flavor system specifications across geographically dispersed feed manufacturing sites. This concentration is most visible in the US Midwest, where three protein companies control formulation standards for over sixty percent of regional compound feed volume.
Feed Palatability Enhancers and Modifiers Market Segmentation
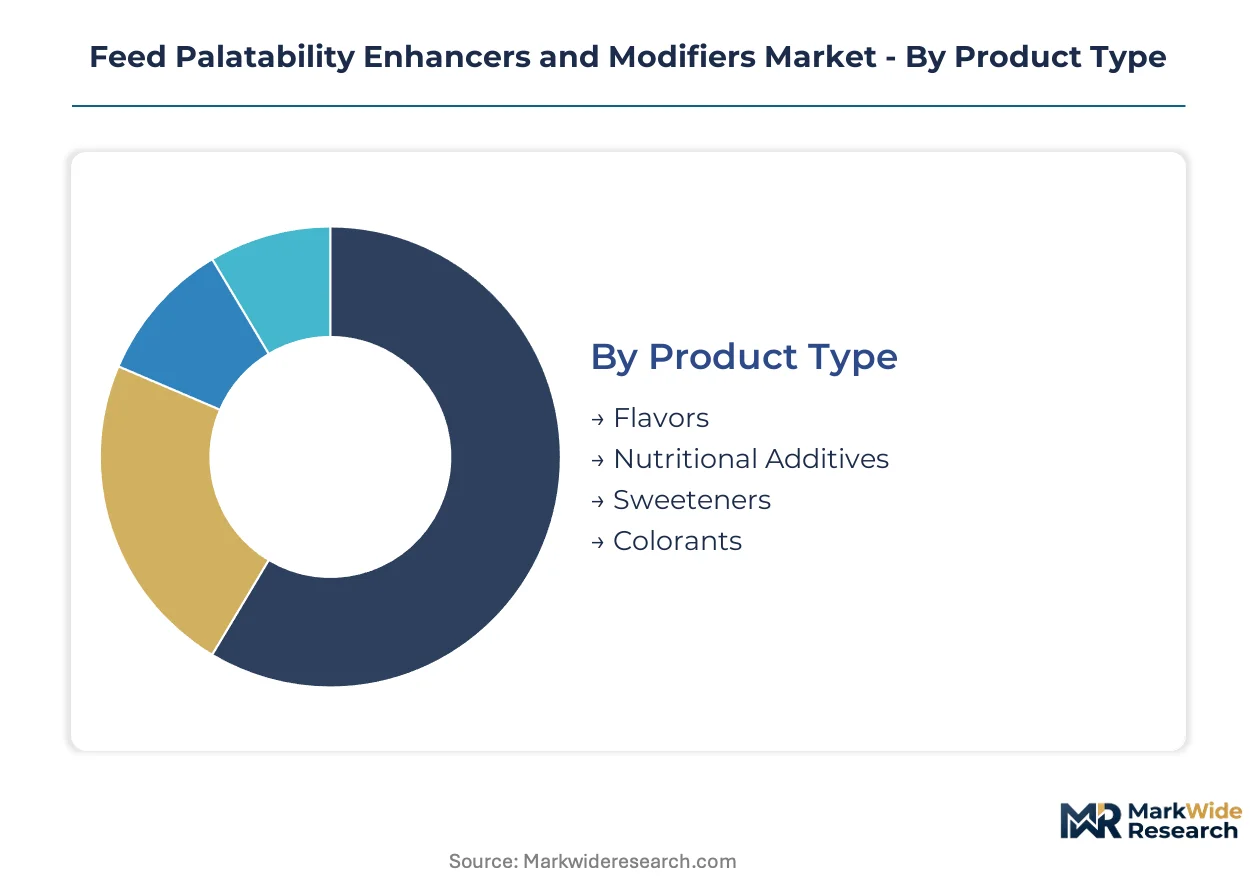
Feed palatability enhancers and modifiers segment across four critical dimensions that determine formulation complexity, regulatory pathway, and customer procurement behavior. Each dimension carries distinct margin profiles and technical barriers that shape supplier competitive positioning.
Product Type:
Flavors demand EFSA additive authorization or FDA GRAS self-affirmation depending on geographic market entry, while colorants trigger additional FDA color additive petitions in the US. Nutritional additives face dual jurisdiction under feed and food safety frameworks.
- Flavors:Volatile aromatic molecules and Maillard reaction products formulated for species-specific receptor profiles. Demand concentrates in São Paulo's integrated poultry operations where feed refusal reduction drives premium formulation spending.
- Nutritional Additives:Fermentation-derived nucleotides and yeast extracts enhancing umami response. Norwegian aquaculture feed producers are adopting these systems at twice the rate of land-based livestock operations as fishmeal substitution accelerates.
- Sweeteners:High-intensity compounds including neohesperidin dihydrochalcone applied at sub-0.1% inclusion rates. Swine diet reformulations in the US Midwest drive procurement concentration.
- Colorants:Carotenoid and natural pigment systems for species-specific visual feed attraction. EFSA's tightened environmental risk assessment requirements extend registration timelines for novel natural compounds.
Flavors sit at the top of the volume ranking, with nutritional additives climbing the fastest.
Application:
Species-specific formulation requirements create tiered margin structures, with carnivorous aquaculture commanding premium pricing due to extreme sensitivity to off-flavors from alternative proteins.
- Cattle:Rumen-protected flavor systems masking high-fiber ration bitterness. Large-scale feedlots in Texas and Nebraska specify centralized procurement standards across geographically dispersed mill operations.
- Poultry:Species-specific masking systems addressing anti-nutritional factors in soybean meal. Brazilian producers in Paraná state are systematically reformulating to cut feed refusal rates and improve conversion efficiency.
- Swine:Palatability enhancers targeting post-weaning feed intake depression. Precision fermentation of nucleotides is enabling bespoke umami receptor targeting in European operations.
- Aquaculture:Marine feed palatability solutions addressing carnivorous species' extreme off-flavor sensitivity. Andhra Pradesh shrimp producers in India are scaling intensive pond systems, opening concentrated demand for fishmeal substitution masking.
Poultry dominates current volume, while aquaculture gains share fastest on alternative protein transition pressures.
Form:
Physical form selection hinges on feed manufacturing infrastructure, with liquid systems requiring specialized dosing equipment that constrains adoption among smaller compound feed mills.
- Granules:Free-flowing carriers enabling uniform distribution in mash feeds. Mid-scale poultry operations in Germany specify granule formats for compatibility with existing batch mixing systems.
- Powders:Fine-particle systems for surface application on pelleted rations. Aquaculture feed producers in Chile favor powder formats for marine feed coating operations.
- Liquids:High-concentration solutions applied via spray systems in large continuous production lines. US Midwest protein companies mandate liquid formats for headquarters-controlled formulation standardization.
- Pellets:Co-extruded palatability cores for extended release in ruminant diets. Cattle feedlots in Alberta specify pellet forms for rumen bypass protection.
Powders lead volume rankings, with liquids expanding most quickly on integrated operation consolidation.
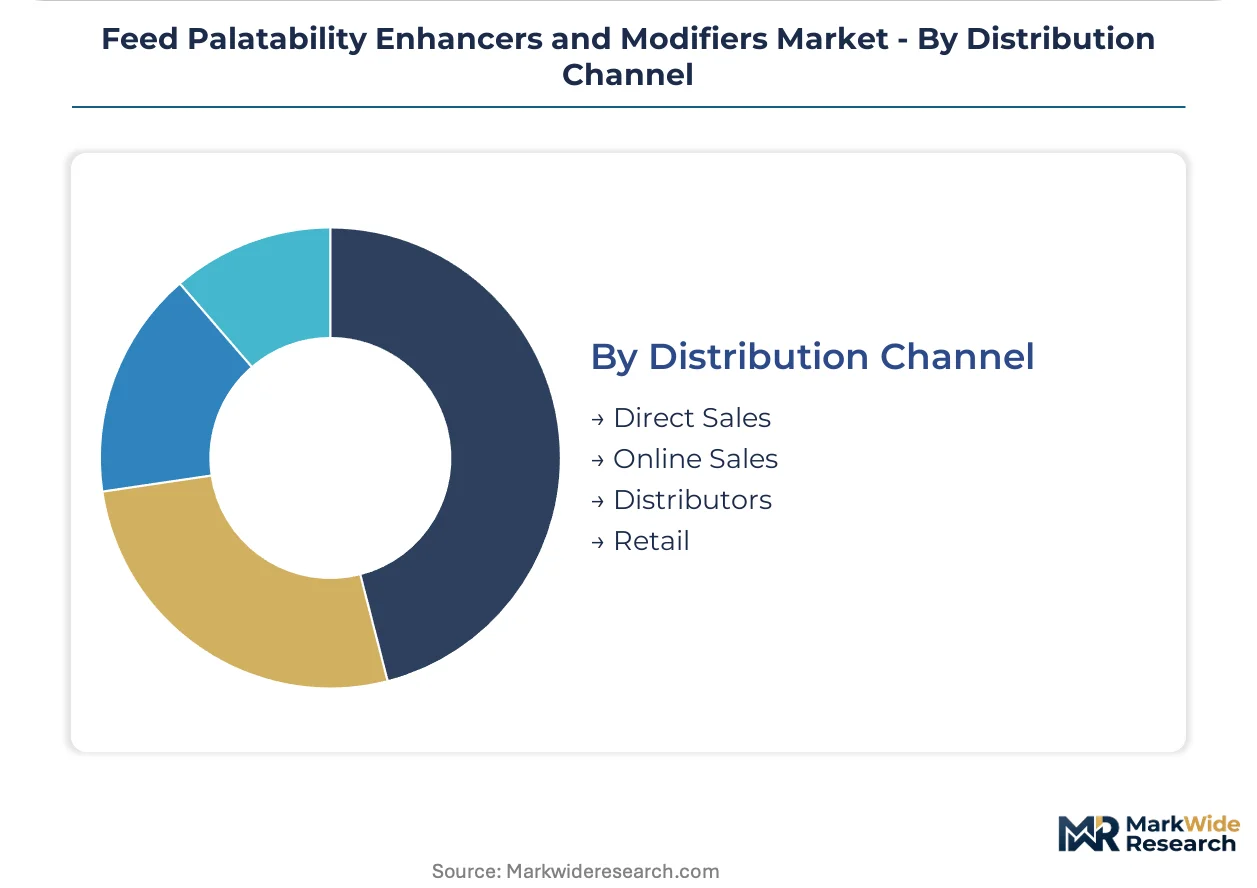
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with direct sales capturing formulation-intensive accounts and distributors serving fragmented regional markets.
- Direct Sales:Technical field service supporting complex species-specific formulation. Large Brazilian and US protein companies now mandate direct supplier relationships for centralized specification control.
- Distributors:Regional inventory and credit provision for mid-tier compound feed manufacturers. European distributors are building regulatory consulting capabilities to support EFSA additive authorization navigation.
- Online Sales:Digital procurement platforms for standardized product grades. Smaller aquaculture feed mills in Vietnam are adopting online channels for yeast-based palatability agent sourcing.
- Retail:Point-of-sale availability for specialty livestock and hobby farming segments. Limited penetration outside Western European markets with developed specialty feed retail infrastructure.
Direct sales sits at the top of the volume ranking, with online sales climbing the fastest among emerging market aquaculture producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's integrated poultry operations anchor demand concentration for species-specific masking systems as Brazilian producers reformulate rations to cut feed refusal rates. Regulatory divergence between EFSA and FDA pathways is fragmenting supplier qualification criteria across major livestock-producing jurisdictions.
United States
Midwest protein companies control formulation standards for over sixty percent of regional compound feed volume through centralized procurement. The FDA Center for Veterinary Medicine's GRAS notification pathway offers faster market entry for novel natural flavor precursors compared to European additive authorization. Nebraska and Texas feedlots specify rumen-protected flavor systems masking high-fiber ration bitterness.
Brazil
Large-scale producers in Paraná state are systematically reformulating rations to improve conversion efficiency, creating concentrated demand for poultry-specific palatability enhancers. ANVISA maintains feed additive registration requirements that align with Mercosur harmonization efforts. São Paulo's integrated operations mandate centralized flavor system specifications across geographically dispersed feed manufacturing sites.
Germany
Mid-scale poultry operations specify granule formats for compatibility with existing batch mixing systems as they transition from synthetic to natural flavor platforms. ECHA oversight under REACH framework restrictions redirects R&D budgets toward botanical extract validation. Bavarian compound feed manufacturers confront extended EFSA feeding trial requirements for novel natural compounds.
Norway
Marine feed producers adopt fermentation-derived nucleotides at twice the rate of land-based livestock operations as fishmeal substitution accelerates in aquaculture diets. The country's national veterinary regulator enforces environmental risk assessment requirements for marine discharge pathways. Norwegian aquaculture clusters push smaller suppliers toward regulatory consulting partnerships for fate-and-transport analysis.
India
Andhra Pradesh shrimp producers scale intensive pond systems, opening demand for marine feed palatability solutions masking fishmeal substitution effects. BIS standards for feed additives create compliance benchmarks for domestic and imported products. Gujarat's emerging aquaculture feed mills adopt online procurement channels for yeast-based palatability agent sourcing.
Feed Palatability Enhancers and Modifiers Market Vendor Landscape
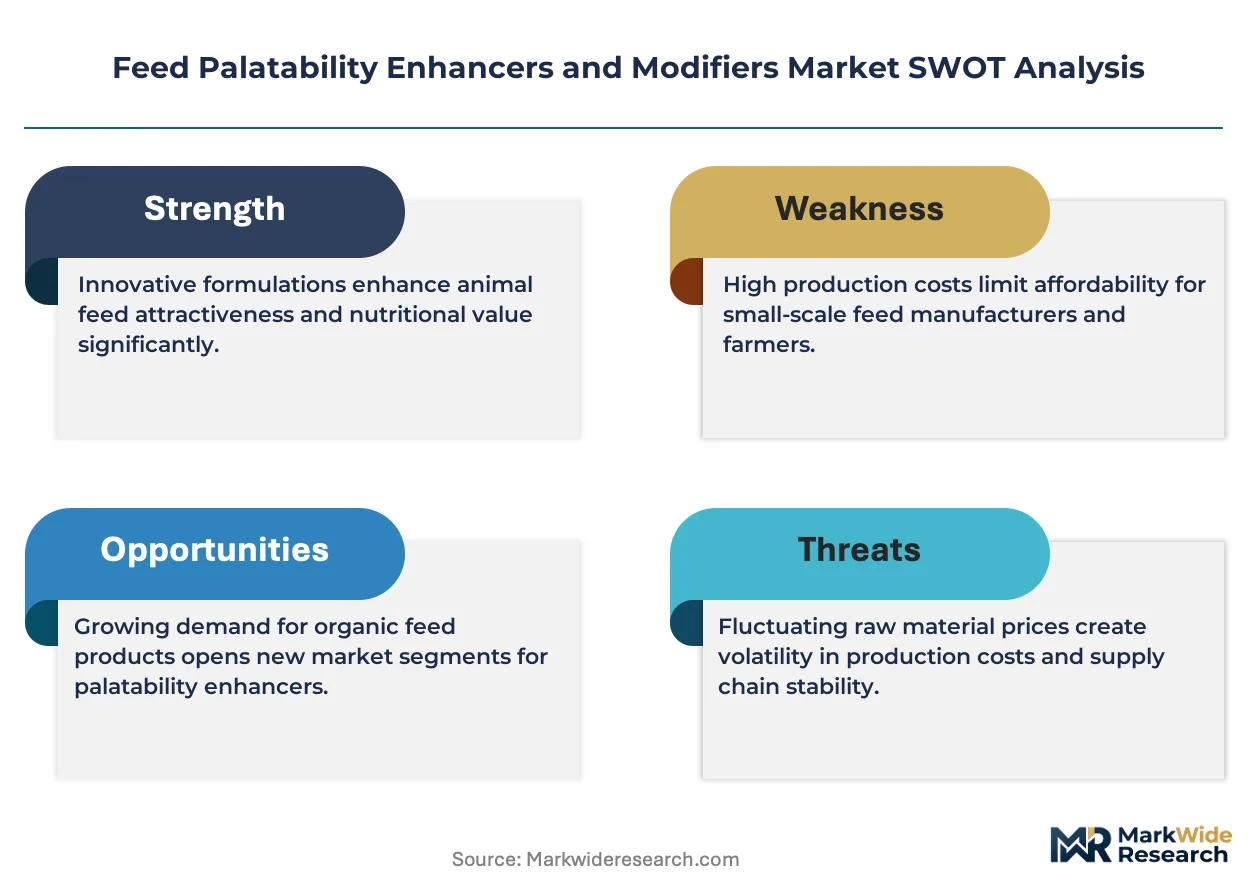
Capacity expansion dominates the current landscape as suppliers rebuild formulation platforms around validated natural alternatives. The vendor base concentrates among diversified nutrition conglomerates, specialized flavor houses, and fermentation technology firms. Three archetypes define positioning: oilseed processors leveraging captive supply chains, European flavor science specialists, and biotechnology platforms commercializing precision fermentation. M&A activity and strategic partnerships represent the dominant competitive moves as firms secure botanical extraction capabilities and regulatory consulting expertise.
Within the diversified nutrition tier, Cargill Incorporated and Kerry Group Plc occupy positions shaped by upstream infrastructure control and regional flavor science anchoring respectively. BASF SE sits within the biotechnology archetype, representing fermentation-derived nucleotide platforms. These three companies exemplify how competitive positioning depends on securing captive supply of palatability precursors, anchoring European regulatory navigation capabilities, or differentiating through synthetic biology integration with traditional flavor chemistry.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kerry Group Plc |
| Symrise AG |
| Adisseo |
| DuPont |
| Associated British Foods Plc |
| Kemin Industries |
| BASF SE |
| Elanco Animal Health |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal gates both qualified supply and premium-tier pricing access for natural botanical extracts, as compound feed manufacturers face reformulation mandates that compress approval timelines while elevating validation costs for synthetic-to-natural transitions. Buyers in São Paulo's integrated poultry operations now demand certified sustainable sourcing credentials as a condition for contract renewal, bifurcating the supplier base between EFSA-authorized premium tiers and uncertified economy alternatives.
Pricing Analysis
Input-cost pass-through from fermentation-derived nucleotides and yeast-based palatability agents is intensifying as MEE discharge standards raise fixed costs for Chinese manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated botanical systems from GRAS-notified US alternatives and uncertified commodity grades. Cost compression in the economy tier reflects oversupply of generic yeast extracts. Small-scale aquaculture feed mills in Vietnam exhibit highest price sensitivity, while Norwegian marine feed producers accept premium positioning for species-specific masking systems.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for botanical extract precursors as compound feed manufacturers hedge against EFSA authorization delays. Supply concentrates in China, India, and Brazil for fermentation-derived nucleotides, volatile aromatic molecules, and tropical botanical feedstocks respectively. Raw material dependencies span yeast cultures, oilseed processing byproducts, and Maillard reaction precursors. Single-source vulnerability intensifies around EU-validated natural flavor systems with limited EFSA-approved suppliers. Distribution runs through direct technical service relationships for large integrated operations, with regional distributors serving fragmented mid-tier compound feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into durable demand, with EFSA's updated environmental risk assessment guidance extending data requirements and locking capital in validation pipelines. Compound feed manufacturers face irreversible platform choices as divergence between EU and FDA pathways widens.
For Market Incumbents: Cement regulatory navigation capabilities through EFSA consulting partnerships and captive botanical extraction infrastructure. Cargill Incorporated and Kerry Group Plc anchor positions via upstream control over oilseed processing and European flavor science respectively. Precision fermentation scale-up in nucleotide production defends margin position against commodity yeast extract erosion. Capacity addition in Brazil's Paraná state captures concentrated poultry sector procurement authority.
For New Entrants and Emerging Players: Synthetic biology-enabled flavor precursor platforms offer white-space entry around species-specific umami receptor targeting underserved by incumbent botanical extract portfolios. India's Andhra Pradesh shrimp producers present the most penetrable geography as intensive pond systems scale without established palatability supplier relationships. Online procurement channels for yeast-based palatability agents enable direct access to Vietnam's fragmented aquaculture feed mills. Regulatory consulting bundling with product supply differentiates against commodity distributors.
For Investors and Strategic Acquirers: Roll-up economics work for specialized flavor houses with EFSA additive authorizations because regulatory validation creates artificial scarcity and pricing power in a consolidating buyer landscape. Five-to-ten year viability favors fermentation technology platforms over commodity botanical extraction. Target acquisition archetype: precision fermentation startups with validated nucleotide production pathways and existing aquaculture customer relationships. Signal to watch: EFSA authorization backlog clearance rates as indicator of competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Extraction | Cargill leverages oilseed infrastructure to secure captive palatability precursor supply against volatile agricultural harvests. |
| Precision Fermentation Scale-Up | BASF SE's nucleotide platforms enable year-round consistency regardless of tropical botanical availability. |
| EFSA Regulatory Consulting Partnership | European distributors build additive authorization navigation capabilities to serve Bavarian compound feed manufacturers. |
| Centralized Procurement Specification Control | US Midwest protein companies mandate liquid format standards across sixty percent of regional compound feed volume. |
| Online Channel Development | Vietnam's aquaculture feed mills adopt digital procurement for yeast-based palatability agent sourcing. |
Methodological Framework
Direct dialogue with compound feed formulators, flavor chemists, regulatory affairs directors at EFSA-authorized suppliers, and procurement leads at Brazilian integrated poultry operations grounded qualitative findings in operational reality. Secondary validation drew from EFSA additive authorization databases, FDA GRAS notification filings, ANVISA registration records, and customs trade data on yeast extract imports. Bottom-up demand modeling triangulated against top-down market sizing from fermentation capacity disclosures.
Segment-level projections across product type, application species, physical form, and distribution channel fed into analytical framework outputs over the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories incorporating enzyme cost decline curves and regulatory approval velocity assumptions. Species-specific formulation complexity and aquaculture alternative protein transition rates served as industry-specific forecast inputs.
The model holds under continued EFSA-FDA regulatory divergence and stable fermentation input costs; deviation in EU Green Deal implementation timelines or MEE enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
High Ratio Shortening Market