
 Disodium Cocoamphodiacetate Market | 2026-2036
Disodium Cocoamphodiacetate Market Size, Share, and Industry Trends Forecast 2026-2036
Disodium Cocoamphodiacetate Market Analytics
Specialty cosmetic formulators is reorganizing demand patterns for Disodium Cocoamphodiacetate as mass-market brands retreat from sulfate-based systems. BASF SE leverages its Ludwigshafen integrated surfactant complex to secure feedstock continuity for amphoteric derivatives. Croda International Plc anchors its position through biotechnology-derived fatty acid precursors that reduce petrochemical dependency. Evonik Industries AG differentiates via high-purity grades targeting ophthalmic-safe personal care applications.
Disodium Cocoamphodiacetate functions as an amphoteric surfactant synthesized through condensation of coconut fatty acids with iminodiacetic acid, exhibiting pH-dependent behavior with isoelectric points between 4.5 and 6.5 that enable mild cleansing with reduced irritation potential in personal care matrices. The ingredient serves primary industrial purposes as a secondary surfactant and foam stabilizer in rinse-off cosmetics, household detergents, and industrial cleaning compounds where compatibility with anionic systems proves essential. Liquid formulations dominate current volume flows due to processing ease in continuous manufacturing environments, while sulfate-free designation commands premium positioning as cosmetic manufacturers reformulate under tightening dermatological safety protocols. Biodegradable grades represent the fastest-expanding formulation category as agricultural firms adopt amphoacetates for pesticide adjuvancy where aquatic toxicity thresholds constrain conventional surfactant selection.
REACH registration requirements in Europe mandate full toxicological dossiers for surfactant imports, while EPA Safer Choice criteria in the United States steer procurement toward amphoacetates with verified biodegradability profiles. BIS certification in India imposes purity thresholds that filter substandard imports from Southeast Asian traders. Stakeholders must monitor evolving dermatological test protocols from ECHA and state-level chemical disclosure laws in California as these frameworks increasingly determine market access eligibility for amphoteric surfactant suppliers.
Market Dynamics
REACH compliance deadlines in Europe are forcing cosmetic formulators to eliminate sulfate-based surfactants, redirecting procurement toward amphoteric alternatives with verified dermatological safety profiles and biodegradable certification.
Growth Catalysts
- Sulfate-free mandates:REACH registration requirements in Europe now classify sodium lauryl sulfate derivatives as skin sensitizers, accelerating substitution with milder amphoteric surfactants in rinse-off personal care products.
- Biodegradability premiums:Agricultural pesticide adjuvancy applications favor amphoacetates meeting EPA Safer Choice aquatic toxicity thresholds over conventional nonylphenol ethoxylates.
- Ophthalmic safety protocols:Pediatric and eye-care cosmetic segments specify high-purity grades with residual iminodiacetic acid below 50 ppm, creating specification tiers that command value-added positioning.
Market Restraints
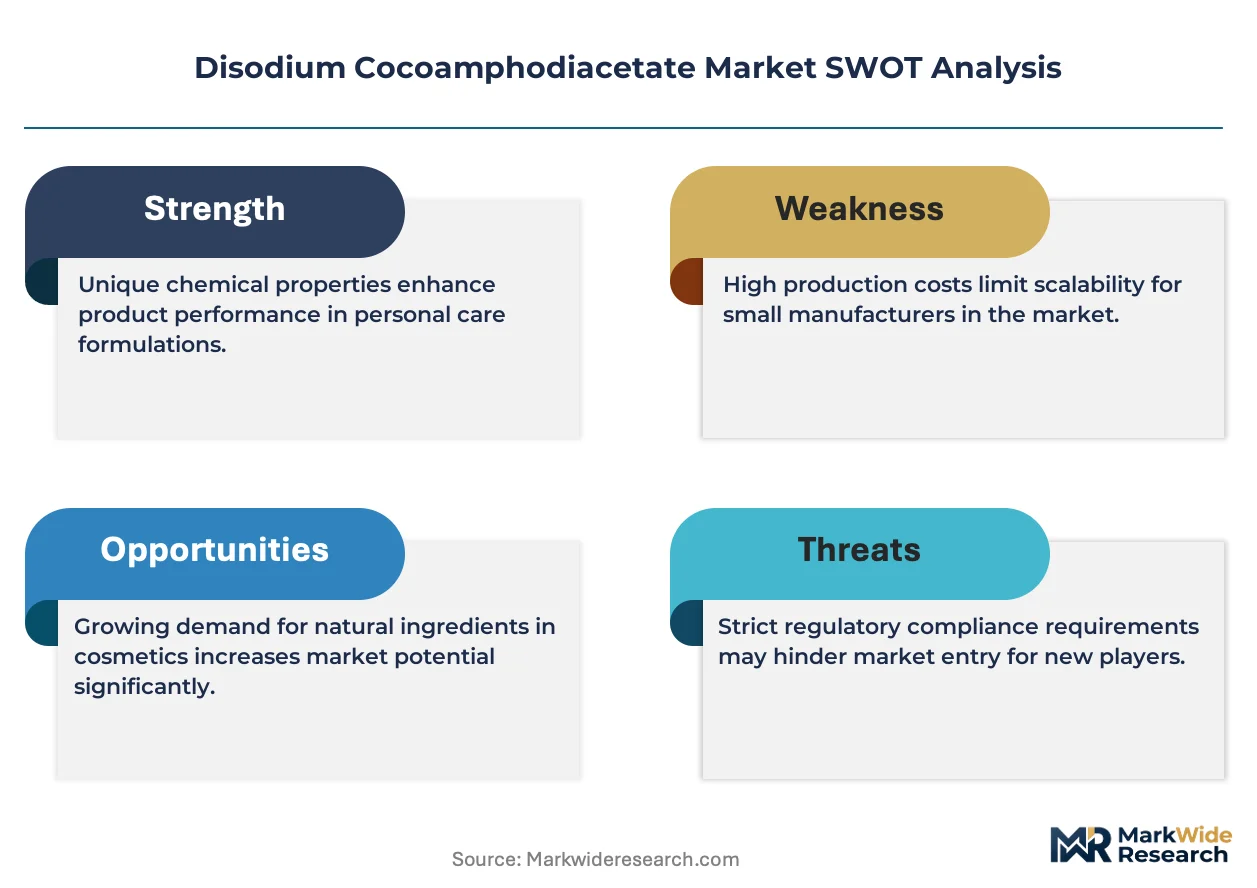
- Coconut fatty acid volatility:Feedstock costs fluctuate with Philippine and Indonesian copra harvest cycles, compressing margin stability for producers without backward integration into plantation assets.
- Specialized reactor concentration:Continuous condensation chemistry for amphoteric surfactants requires stainless-steel equipment resistant to chloroacetate intermediates, limiting viable manufacturing to established chemical complexes in Germany and the United States.
- Anionic compatibility limitations:Performance degradation in hard water above 300 ppm calcium carbonate restricts formulation flexibility for household detergent applications in limestone-rich groundwater regions.
Strategic Opportunities
- Indian BIS certification pathway:Domestic manufacturers can capture import-substitution value by achieving Bureau of Indian Standards purity certification ahead of 2026 enforcement deadlines for surfactant raw materials.
- Biotechnology-derived fatty acids:Fermentation-based C12-C14 lipid production from sugar feedstocks enables petrochemical-free supply chains for premium cosmetic claims targeting EU Green Deal circular economy metrics.
- Industrial cleaning compound reformulation:Food processing equipment sanitization protocols are adopting amphoacetate-based foaming agents to replace quaternary ammonium compounds facing residue accumulation restrictions.
Industry Challenges
- Toxicological dossier compilation:REACH registration requires reproductive toxicity studies and aquatic ecotoxicology data packages costing approximately €800,000 per substance, filtering participation to well-capitalized registrants.
- Specification drift across customer tiers:Mass-market cosmetic brands demand cost-optimized grades with broader impurity bands, while pharmaceutical-adjacent segments require GMP-compliant documentation that fragments production campaign planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disodium Cocoamphodiacetate Market |
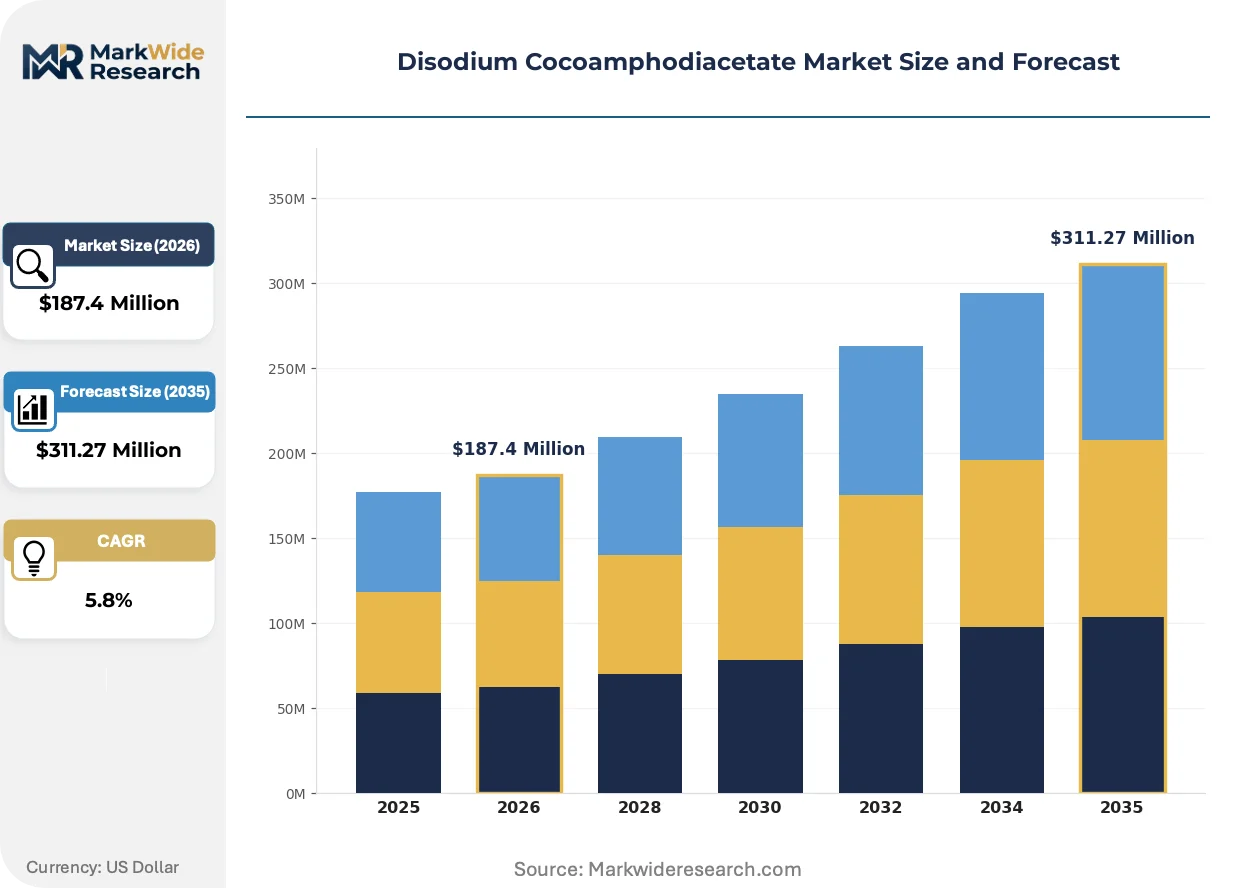
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Bead Application: Personal Care, Household Cleaning, Industrial Cleaning, Agrochemical End User: Cosmetic Manufacturers, Cleaning Product Companies, Agricultural Firms, Research Institutions Formulation Type: Sulfate-Free, Organic, Synthetic, Biodegradable |
| Companies Covered | BASF SE, Croda International Plc, Evonik Industries AG, Clariant AG, Solvay SA, Kao Corporation, Lubrizol Corporation, Galaxy Surfactants Ltd, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disodium Cocoamphodiacetate Market Evolving Landscape
Enzymatic esterification processes are replacing conventional chemical condensation for amphoteric surfactant synthesis, reducing energy intensity while enabling modular production scales that serve regional formulation houses.
Biocatalytic production routes using immobilized lipase enzymes are supplanting traditional acid-chloride activation chemistry for coconut fatty acid derivatization. Mid-sized European cosmetic manufacturers are adopting these processes to achieve cold-process formulation claims. This technology is compressing capital requirements for entry-level surfactant production while fragmenting supply concentration.
ECHA's 2024 update to the REACH Candidate List now includes several ethoxylated surfactant precursors, triggering downstream obligation notifications for cosmetic importers. Industrial consequence includes accelerated reformulation timelines and inventory write-downs for sulfate-containing finished goods. German personal care brands are responding by dual-sourcing amphoteric alternatives from domestic and Indian BIS-certified suppliers.
Formulation houses now specify surfactant premixes with certified dermatological test documentation rather than commodity chemical purchases. Specialty distributors with in-house toxicology consulting capabilities are displacing traditional chemical traders in procurement channels serving mid-tier cosmetic brands. This pattern is most visible in California, where Proposition 65 disclosure requirements have extended liability to finished goods retailers.
Disodium Cocoamphodiacetate Market Segmentation
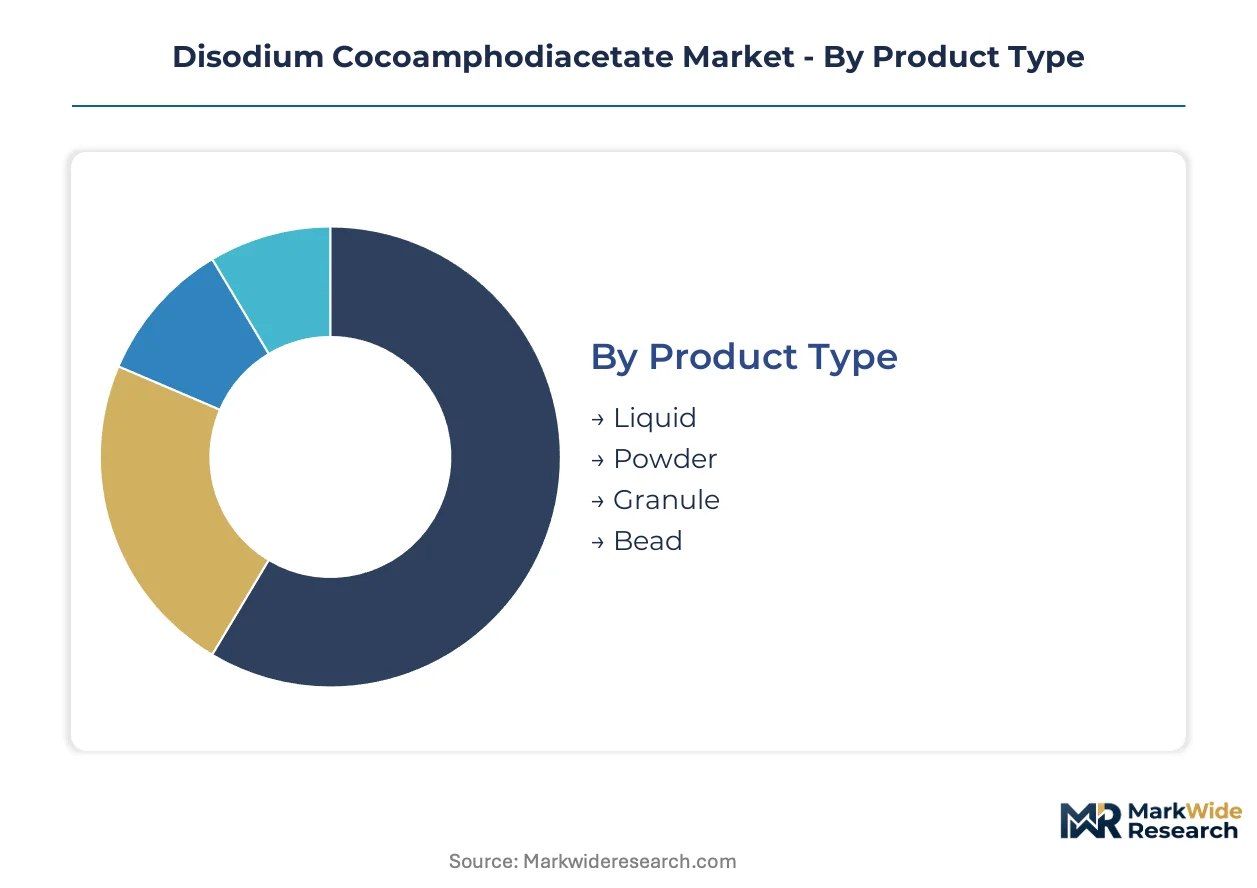
Segmentation in Disodium Cocoamphodiacetate markets reveals how specification tiers fragment procurement channels. Cosmetic formulators demand ophthalmic-grade purity while agricultural buyers prioritize aquatic toxicity profiles, creating parallel value chains with minimal overlap.
Product Type:
Margin pools concentrate in liquid formulations due to continuous manufacturing compatibility and reduced downstream processing costs for cosmetic houses.
- Liquid:Aqueous solutions at 30-40% active concentration dominate rinse-off cosmetic manufacturing. BASF SE and Evonik Industries AG anchor supply from German integrated complexes, serving formulators seeking cold-process compatibility. REACH registration bundling with other amphoteric surfactants reduces per-unit compliance burden.
- Powder:Spray-dried grades enable powdered facial cleansers and travel-format personal care products. Demand concentrates in Japanese cosmetic manufacturers seeking anhydrous formulation platforms for humidity-stable export products.
- Granule:Intermediate particle size for industrial compounding operations. Agricultural adjuvant blenders in India favor this format for pesticide tank-mix compatibility.
- Bead:High-density spherical particles for visual differentiation in premium cosmetic bars. Limited volume but commands specification premiums from boutique formulators.
The dominant share belongs to Liquid, while Powder is closing the gap fastest.
Application:
Volume flows track regulatory pressure intensity across end-use sectors, with personal care commanding value concentration despite smaller tonnage.
- Personal Care:Secondary surfactant and foam stabilizer functions in sulfate-free shampoos, facial cleansers, and baby care products. Pediatric ophthalmic safety protocols in EU and US markets specify residual iminodiacetic acid below 50 ppm, creating premium-grade demand from specialized distributors.
- Household Cleaning:Compatibility with anionic surfactants in hard-surface cleaners and dishwashing liquids. Performance degradation above 300 ppm calcium carbonate restricts penetration in limestone-rich groundwater regions of southern Germany and northern India.
- Industrial Cleaning:Food processing equipment sanitization foaming agents replacing quaternary ammonium compounds. US FDA residue accumulation restrictions drive substitution in dairy and beverage plant protocols.
- Agrochemical:Pesticide adjuvancy where EPA Safer Choice aquatic toxicity thresholds constrain conventional nonylphenol ethoxylate selection. Biodegradable amphoacetate grades expand most quickly in this segment.
Personal Care retains value leadership, though Agrochemical exhibits the steepest expansion trajectory.
End User:
Procurement sophistication divides customer tiers, with documentation requirements fragmenting supplier relationships.
- Cosmetic Manufacturers:Mass-market brands demand cost-optimized grades with broader impurity bands. Pharmaceutical-adjacent segments require GMP-compliant documentation that fragments production campaign planning for multi-tier suppliers.
- Cleaning Product Companies:Industrial and household formulators prioritize anionic compatibility and hard-water stability. Regional groundwater chemistry dictates specification customization.
- Agricultural Firms:Pesticide manufacturers specify biodegradability certification for aquatic toxicity compliance. Indian BIS certification pathways enable import substitution from domestic suppliers.
- Research Institutions:Small-volume specialty grades for dermatological testing and novel formulation development. Minimal revenue contribution but shapes future specification evolution.
Cosmetic Manufacturers command supplier attention, while Agricultural Firms are gaining procurement sophistication fastest.
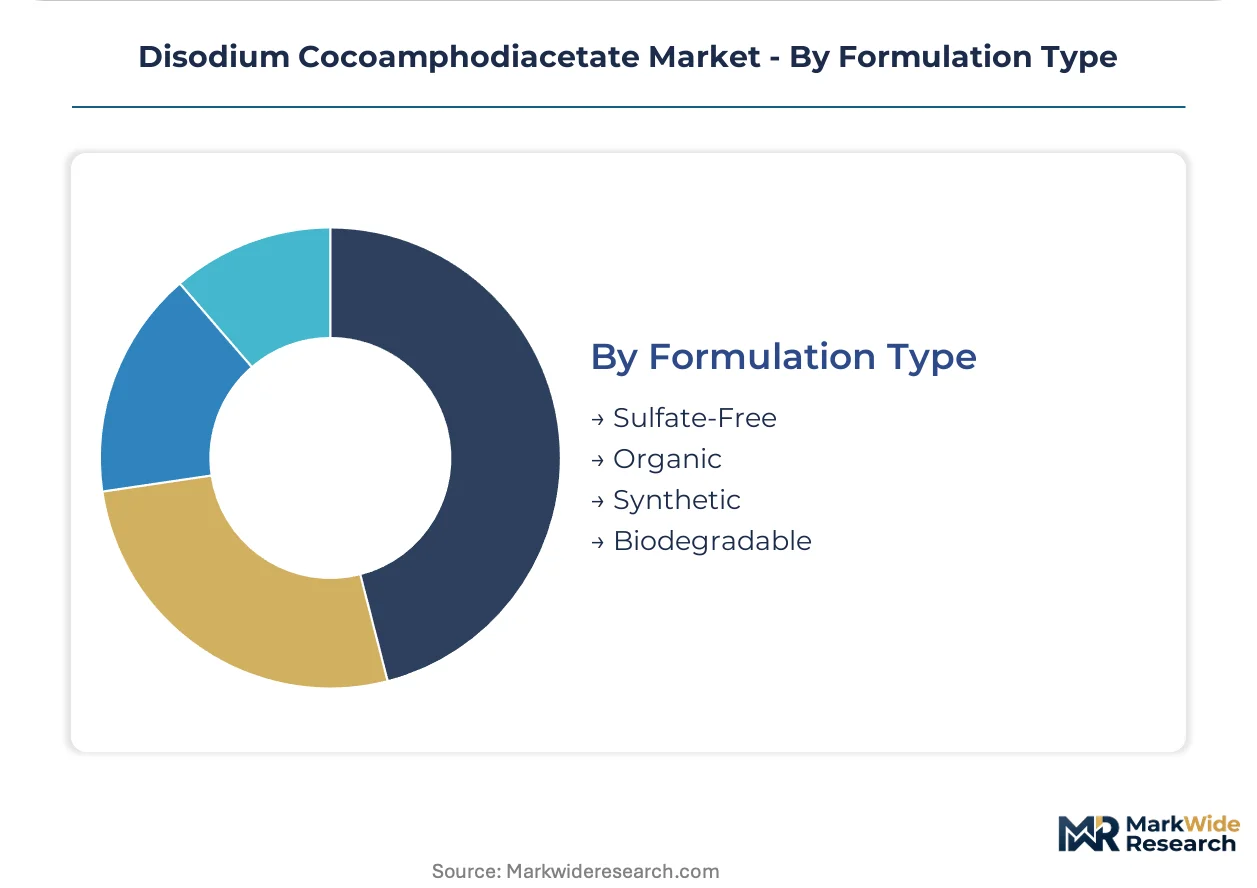
Formulation Type:
Certification premiums stratify pricing, with regulatory verification replacing commodity positioning.
- Sulfate-Free:Designation commands premium positioning as cosmetic manufacturers reformulate under tightening dermatological safety protocols. ECHA skin sensitizer classification of sodium lauryl sulfate derivatives accelerates substitution.
- Organic:Coconut fatty acid precursors from certified plantation sources. Supply constraints from Philippine and Indonesian copra harvest cycles compress margin stability.
- Synthetic:Petrochemical-derived C12-C14 lipid feedstocks. Cost advantage erodes as biotechnology-derived alternatives achieve scale.
- Biodegradable:Fastest-expanding category as fermentation-based production from sugar feedstocks enables EU Green Deal circular economy claims. Croda International Plc anchors supply through biotechnology-derived fatty acid precursors.
Sulfate-Free maintains position share, while Biodegradable is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical complexes export amphoteric surfactant precursors to cosmetic formulators across France, Italy, and the Netherlands, establishing a westward trade corridor anchored by Ludwigshafen production assets.
Germany
REACH registration bundling reduces per-unit compliance costs for domestic surfactant manufacturers. ECHA skin sensitizer classifications for sulfate derivatives accelerate substitution mandates across cosmetic supply chains. The Ludwigshafen chemical complex anchors specialized amphoteric production serving pan-European formulators.
United States
EPA Safer Choice criteria steer agricultural adjuvancy procurement toward biodegradable amphoacetate grades. California Proposition 65 disclosure requirements extend liability to finished goods retailers, forcing documentation upgrades. Industrial cleaning compound manufacturers in the Midwest adopt foaming agents for food processing sanitization protocols.
India
BIS certification deadlines for surfactant raw materials filter substandard imports from Southeast Asian traders. Domestic manufacturers capture import-substitution value through purity threshold compliance. Agricultural adjuvant blenders in Maharashtra and Gujarat favor granule formats for pesticide tank-mix compatibility.
China
Dual carbon goals under MEE frameworks pressure petrochemical-derived feedstock selection in surfactant synthesis. Cosmetic manufacturers in the Yangtze River Delta reformulate sulfate-free portfolios for export compliance with EU dermatological protocols. Fermentation-based C12-C14 lipid production from sugar feedstocks enables circular economy claims.
Japan
PMDA ophthalmic safety protocols specify residual iminodiacetic acid thresholds below 50 ppm for pediatric cosmetic segments. Spray-dried powder grades enable anhydrous formulation platforms for humidity-stable export products. Cosmetic manufacturers in the Kansai region prioritize GMP-compliant documentation for pharmaceutical-adjacent applications.
Disodium Cocoamphodiacetate Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive surfactant complexes. The vendor base concentrates around three strategic archetypes: European petrochemical majors with backward integration into fatty acid supply, Asian fermentation-based biotechnology specialists, and regional distributors with toxicology consulting capabilities. Dominant competitive moves include capacity expansion at existing integrated sites and technology licensing for enzymatic esterification processes.
Within the integrated petrochemical tier, BASF SE, Evonik Industries AG, and Croda International Plc exemplify divergent positioning strategies. BASF SE occupies a scale-driven position through its Ludwigshafen complex operations. Evonik Industries AG represents the high-purity specialization vector targeting ophthalmic-safe applications. Croda International Plc anchors the biotechnology-derived feedstock archetype, reducing petrochemical dependency through fermentation-based lipid production.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Evonik Industries AG |
| Clariant AG |
| Solvay SA |
| Kao Corporation |
| Lubrizol Corporation |
| Galaxy Surfactants Ltd |
| Stepan Company |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German integrated producers and pan-European cosmetic formulators lock in feedstock access and price visibility across volatile coconut fatty acid cycles. These arrangements concentrate pricing power with Ludwigshafen-based suppliers while insulating downstream buyers from Philippine and Indonesian copra harvest disruptions.
Pricing Analysis
Conventional chemical condensation technology commands lower unit costs than emerging enzymatic esterification processes, though biocatalytic routes are compressing the gap as modular scales achieve viability. Three-tier pricing structure across premium, standard, and economy levels separates ophthalmic-grade purity with sub-50 ppm residual iminodiacetic acid from industrial compounding grades. Pricing pressure stems from coconut fatty acid volatility as Philippine copra yields fluctuate with climate patterns. Mass-market cosmetic brands exhibit highest price sensitivity, while pediatric eye-care segments absorb premiums for documented dermatological safety.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for liquid formulations shipped from German integrated complexes to cosmetic houses across France, Italy, and the Netherlands. Supply concentrates in Germany, the United States, and India, with Ludwigshafen anchoring European amphoteric surfactant production. The chain draws from coconut fatty acid precursors, iminodiacetic acid intermediates, and chloroacetate activation reagents. Single-source vulnerability around stainless-steel reactor capacity resistant to corrosive intermediates constrains supply expansion. Distribution runs through specialty chemical distributors with in-house toxicology consulting capabilities serving mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH registration requirements and toxicological dossier costs approaching €800,000 per substance create prohibitive barriers that protect incumbent positions.
For Market Incumbents: Secure backward integration into coconut plantation assets or biotechnology-derived fatty acid supply chains to neutralize feedstock volatility. Add stainless-steel reactor capacity at existing German sites before Indian BIS certification deadlines trigger import-substitution competition. Defend against enzymatic esterification entrants by bundling REACH registration across amphoteric surfactant portfolios. For New Entrants and Emerging Players: Anchor in Indian domestic production certified under BIS purity thresholds ahead of enforcement deadlines for surfactant raw materials. Target agricultural adjuvancy applications where EPA Safer Choice biodegradability requirements displace nonylphenol ethoxylates. Pursue fermentation-based C12-C14 lipid production from sugar feedstocks to claim EU Green Deal circular economy positioning. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology-derived feedstock specialists with demonstrated fermentation scale and cosmetic-grade purity capabilities. The 5-10 year viability window favors assets with captive supply chains and regulatory dossier completeness. Watch for ECHA Candidate List expansions targeting ethoxylated surfactant precursors as inflection signals accelerating amphoteric substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive coconut fatty acid supply from Philippine plantation assets neutralizes copra harvest volatility. |
| Biocatalytic Capacity Expansion | Immobilized lipase enzyme reactors enable cold-process formulation claims for mid-sized European cosmetic houses. |
| REACH Registration Bundling | Shared toxicological dossiers across amphoteric surfactant portfolios reduce per-unit compliance burden for German producers. |
| Indian BIS Certification | Domestic purity compliance ahead of surfactant raw material deadlines captures import-substitution value. |
| Biodegradable Grade Development | Fermentation-based production from sugar feedstocks unlocks EU Green Deal circular economy procurement channels. |
Research Methodology
Desk research of customs/trade data, SEC 10-K filings, and Cefic surfactant industry reports preceded structured interviews with plant managers at integrated chemical complexes, procurement leads at downstream cosmetic OEMs, and technical R&D directors specializing in amphoteric surfactant synthesis. Primary fieldwork with specialty chemical distributors and regulatory affairs consultants validated secondary findings. Bottom-up volume modeling triangulated against top-down industry association estimates.
Variance decomposition across product type, application, formulation certification tier, and regional production hub shaped the analytical framework. CAGRs were derived from segmented growth rate assumptions applied across the projection horizon. Forecast inputs incorporated REACH registration timelines, coconut fatty acid price indices, and enzymatic esterification technology adoption curves.
Material uncertainties — regulatory reclassification of amphoteric surfactants, biotechnology feedstock scale delays, and Indian BIS enforcement timing — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Italy Food Additives Market