
 Unsupported Single Coated Tape Market | 2026-2036
Unsupported Single Coated Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Unsupported Single Coated Tape Market Analytics
ISO 9001 quality management certification is redrawing supplier eligibility for OEM qualification programs. 3M Company leverages its materials science portfolio to sustain technical leadership across high-performance bonding applications. Nitto Denko Corporation anchors its position through deep specialization in electronics-grade adhesive tapes. Avery Dennison Corporation competes by controlling distribution networks across North American industrial channels.
Unsupported single coated tape consists of a single adhesive layer applied directly to a flexible backing substrate without additional carrier or support film, typically manufactured through solvent-based or hot-melt coating processes at controlled thicknesses between 25 and 150 micrometers. The product serves primarily as a permanent or removable fastening solution across surface protection, temporary holding, and splicing operations in manufacturing environments. Foam tapes command premium positioning in automotive gasketing and vibration damping where conformability to irregular substrates determines specification. Acrylic adhesives dominate technical specifications for outdoor durability and UV resistance, while rubber-based formulations retain cost-sensitive packaging and general industrial applications where solvent resistance requirements remain moderate.
REACH chemical registration requirements in Europe mandate full substance disclosure for adhesive imports above one tonne annually, reshaping formulation strategies for tape suppliers serving EU manufacturing customers. The US EPA oversees volatile organic compound emissions from solvent-based coating operations, pushing conversion toward hot-melt and waterborne adhesive technologies. China's GB standards for pressure-sensitive adhesive products establish mandatory peel strength and shear resistance testing protocols for domestic certification. Stakeholders must monitor regulatory divergence between jurisdictions when configuring regional product portfolios and manufacturing footprints.
Market Dynamics
Automotive electrification is redrawing adhesive specification requirements as battery pack assembly demands higher thermal tolerance and dielectric strength from bonding materials. OEM qualification programs are tightening material traceability standards, forcing tape suppliers to restructure formulation documentation and testing protocols.
Growth Catalysts
- EV Battery Assembly:Electric vehicle manufacturers in Germany's industrial corridor are specifying unsupported single coated tapes for cell-to-cell bonding and thermal interface management, creating specification pull for high-temperature acrylic formulations.
- REACH Compliance:ECHA registration mandates for adhesive imports above one tonne annually are accelerating supplier consolidation toward compliant formulators with established EU substance dossiers.
- Solvent-to-Hot-Melt Conversion:Coating technology migration is expanding production capacity for waterborne and hot-melt adhesive systems, reducing VOC exposure and enabling faster line speeds.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic monomer and synthetic rubber prices fluctuate with crude oil indices, compressing margin predictability for tape manufacturers without backward integration into polymer production.
- Asian Supply Concentration:Specialty release liner substrates and modified acrylic polymers concentrate among Korean and Japanese chemical suppliers, creating single-source vulnerability for European and North American coaters.
- Technical Performance Ceiling:Unsupported constructions lack dimensional stability for precision electronics applications below 50-micrometer thickness, ceding share to double-coated and transfer tape alternatives in semiconductor packaging.
Strategic Opportunities
- India Industrial Corridor:PLI scheme incentives for domestic electronics manufacturing are attracting tape suppliers to establish localized coating operations serving smartphone and appliance assembly demand.
- CSRD-Driven Material Transparency:EU corporate sustainability reporting requirements are creating competitive advantage for suppliers with verified supply chain carbon footprints and circular adhesive recovery programs.
- Medical Device Convergence:Wearable health monitor assembly is merging requirements from electronics-grade precision and biocompatibility certification, opening specification space for ISO 10993-compliant tape constructions.
Industry Challenges
- Formulation Chemistry Expertise Gap:Solvent-based coating veterans lack training in hot-melt rheology and UV-curable adhesive chemistry, slowing workforce transition as production lines retool.
- OEM Qualification Timeline Compression:Automotive and electronics manufacturers are compressing supplier approval cycles from 18 months to 9 months, straining tape producers' testing and documentation bandwidth.
- Multi-Jurisdiction Compliance Stacking:Simultaneous adherence to US EPA VOC rules, REACH substance restrictions, and China's GB standards requires parallel formulation tracks, multiplying R&D overhead.
Report Scope
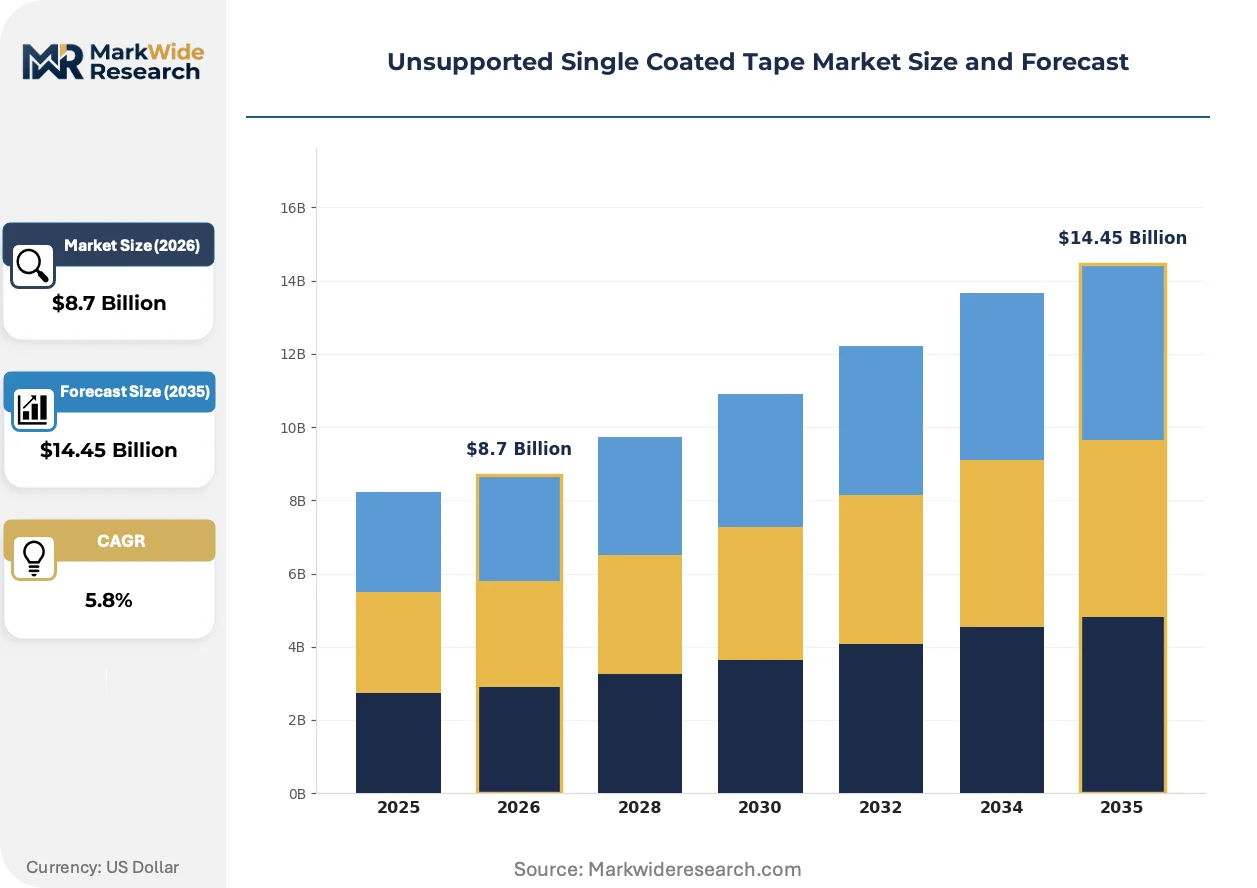
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unsupported Single Coated Tape Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Sided, Foam, Single Sided, Specialty End Use Industry: Construction, Electronics, Packaging, Automotive Application: Mounting, Bonding, Insulation, Surface Protection Adhesive Type: Acrylic, Rubber, Hot Melt, Silicone |
| Companies Covered | 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, Intertape Polymer Group, tesa SE, Shurtape Technologies, Scapa Group, Berry Plastics, Arkema (Bostik), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unsupported Single Coated Tape Market Evolving Landscape
Active material science development is narrowing the performance gap between commodity pressure-sensitive tapes and engineered bonding solutions, with coating precision and adhesive functionalization as the primary technical battlegrounds.
Nano-silica reinforcement technology is miniaturizing particle dispersion within acrylic adhesive matrices to sub-micrometer scales without viscosity degradation. Electronics contract manufacturers in South Korea are adopting these formulations for flexible circuit lamination where dielectric consistency determines yield. The technology is miniaturizing acceptable defect thresholds in display assembly, compressing specification windows that commodity tapes cannot satisfy.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is tightening solvent-based coating operations in the United States, accelerating capital redeployment toward hot-melt and electron-beam curing infrastructure. Tape converters with legacy solvent lines face facility reconfiguration costs or outsourcing to compliant toll coaters. General industrial and packaging segments are absorbing the transition friction through extended lead times and reformulation testing cycles.
Direct procurement relationships between automotive OEMs and adhesive raw material suppliers are disintermediating traditional tape distributors in North America and Western Europe. Tier-1 suppliers are losing specification influence as battery and powertrain engineers source bonding materials directly from certified formulators. This pattern concentrates most visibly in Germany and Michigan, where EV platform development teams maintain dedicated adhesive engineering functions.
Unsupported Single Coated Tape Market Segmentation
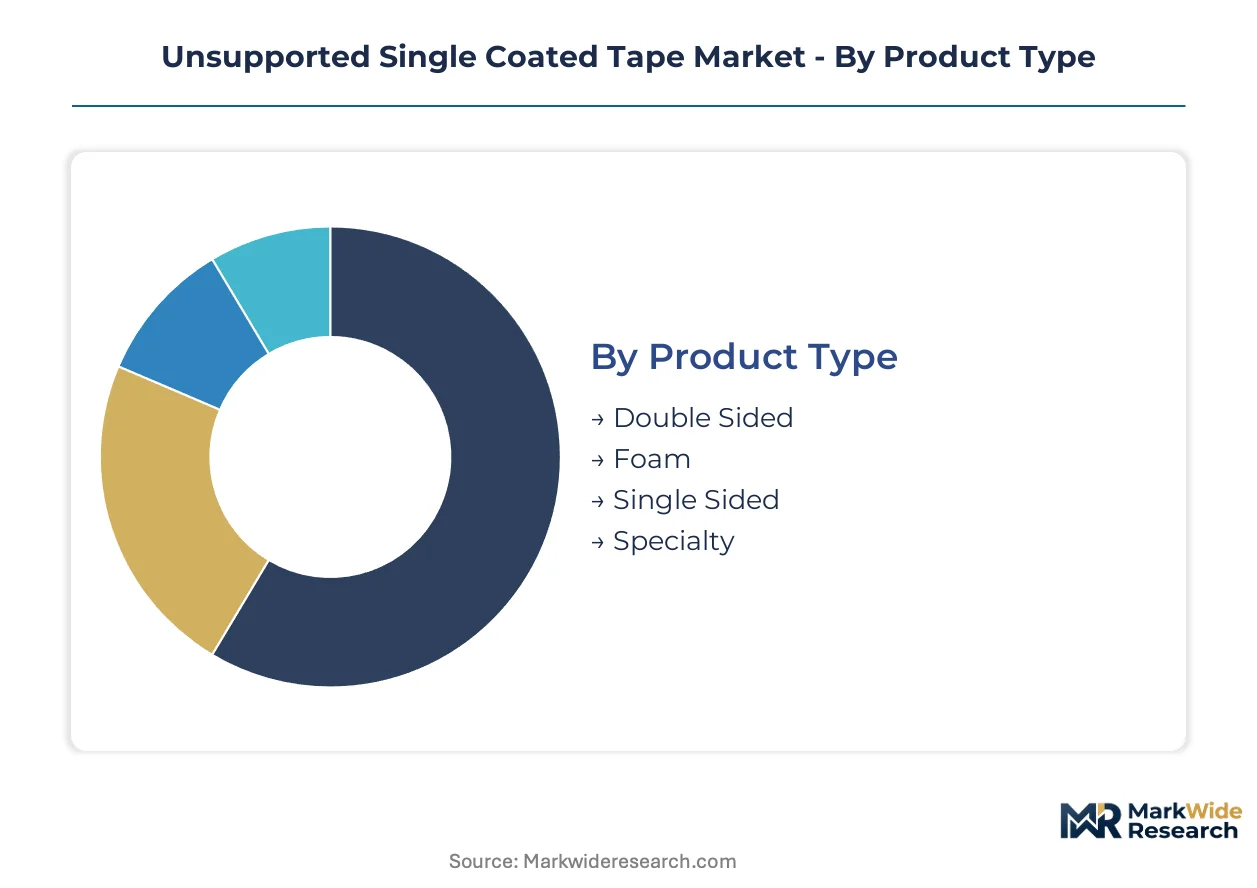
Unsupported single coated tape markets fragment across four distinct taxonomies, each revealing divergent margin structures and qualification barriers. Product type and adhesive chemistry determine manufacturing capital intensity, while end-use and application segments expose divergent customer consolidation patterns.
Product Type:
Foam tapes command the widest specification spreads, with automotive NVH applications justifying premium positioning against commodity single-sided alternatives.
- Foam:Closed-cell polyethylene or polyurethane substrates carry high-build adhesives for gap-filling and vibration damping. German automotive OEMs specify these formulations for battery pack compression pads and door seal bonding, where Shore A hardness and compression set resistance determine qualification.
- Specialty:Modified constructions incorporate conductive particles, flame-retardant additives, or optical-grade clarity for electronics and aerospace niche requirements. South Korean display manufacturers drive specification pull for ultra-cleanroom compatible formulations in OLED lamination.
- Single Sided:Standard constructions with direct adhesive-to-backing application dominate general industrial and masking applications where cost minimization outweighs performance differentiation.
- Double Sided:Unsupported constructions with adhesive coating on both faces of a thin carrier serve temporary holding and splicing operations in paper and film converting industries.
Foam holds installed capacity. Specialty is rotating up the share rankings.
End Use Industry:
Automotive electrification is rewriting volume allocation, with battery assembly displacing traditional body-in-white applications as the primary demand anchor.
- Automotive:Cell-to-cell bonding, thermal interface materials, and pack sealing now constitute the fastest-expanding specification cluster. Michigan and Stuttgart engineering centers specify acrylic foam tapes with dielectric breakdown above 3kV for module assembly.
- Electronics:Flexible circuit lamination and display bonding demand sub-50-micrometer coating precision with low-outgassing certification. Japanese and South Korean contract manufacturers enforce JIS and GB standard compliance for smartphone assembly.
- Construction:Weather sealing and temporary surface protection absorb commodity-grade rubber and hot-melt formulations where UV resistance requirements remain moderate.
- Packaging:Carton sealing and label attachment represent high-volume, low-margin throughput segments with minimal technical differentiation.
Automotive holds installed capacity. Electronics is rotating up the share rankings.
Application:
Mounting applications concentrate the highest qualification premiums, with permanent structural bonding commanding multi-year OEM approval cycles.
- Mounting:Permanent fixture of components to substrates demands shear resistance and thermal cycling durability. German EV battery suppliers specify high-temperature acrylics for cell stacking operations where 85°C continuous exposure is mandatory.
- Insulation:Electrical and thermal barrier functions require dielectric strength and thermal conductivity control. Chinese GB standards mandate specific volume resistivity thresholds for domestic certification.
- Bonding:General assembly operations span automotive trim attachment to appliance manufacturing, with formulation selection driven by substrate compatibility and process temperature.
- Surface Protection:Temporary masking during painting, plating, or machining operations prioritizes clean removability and residue-free performance over permanent adhesion.
Mounting holds installed capacity. Insulation is rotating up the share rankings.
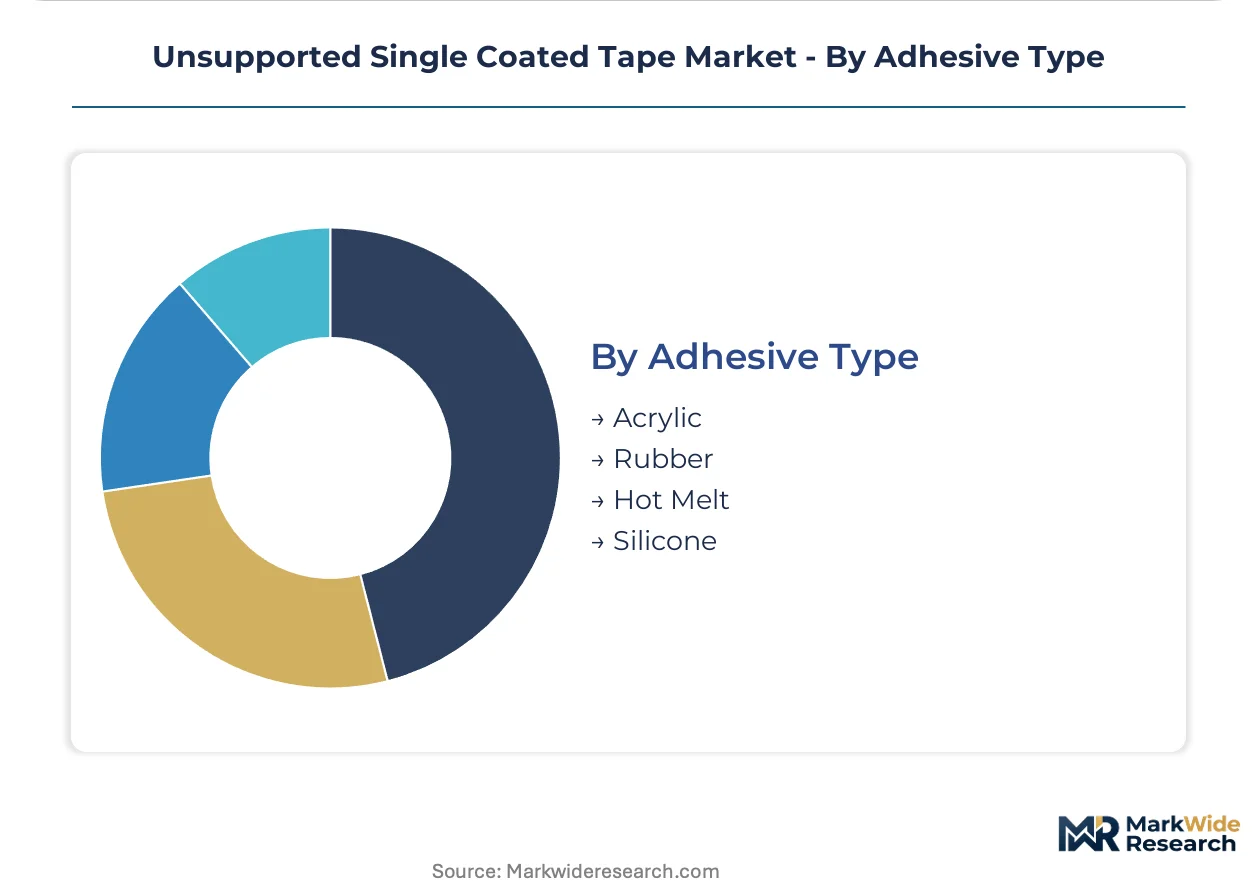
Adhesive Type:
Acrylic formulations capture the widest specification coverage, with solvent-borne, emulsion, and UV-curable variants spanning performance tiers.
- Acrylic:Outdoor durability, UV resistance, and broad temperature performance position these formulations across automotive, electronics, and construction applications. US EPA VOC regulations are accelerating waterborne acrylic adoption in domestic coating operations.
- Silicone:Extreme temperature tolerance from -40°C to 200°C plus chemical resistance serves aerospace, medical device, and industrial sealing where other chemistries fail. Premium positioning reflects raw material costs and specialized curing infrastructure.
- Rubber:Natural and synthetic rubber-based adhesives retain cost-sensitive packaging and general industrial applications where solvent resistance and high-temperature performance are secondary to initial tack and economy.
- Hot Melt:Thermoplastic formulations enable solvent-free coating at high line speeds, with pressure-sensitive and heat-activated variants serving disposable hygiene and industrial assembly markets.
Acrylic holds installed capacity. Silicone is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance disclosure mandates and EV battery assembly incentives are redirecting tape supplier investment toward jurisdictions with established chemical registration frameworks and automotive electrification clusters. Production capacity is migrating to serve these dual regulatory and demand anchors.
Germany
Stuttgart and Munich engineering centers specify high-temperature acrylic foam tapes for cell-to-cell bonding in EV battery packs. ECHA registration requirements for adhesive imports above one tonne annually favor suppliers with complete EU substance dossiers. The Baden-Württemberg industrial corridor concentrates coating operations serving OEM direct procurement relationships.
United States
Michigan-based battery platform teams source bonding materials directly from certified formulators, bypassing traditional distributors. EPA enforcement of National Emission Standards for Hazardous Air Pollutants accelerates solvent-to-hot-melt coating conversion. The Detroit-Toledo corridor anchors qualification activity for dielectric tape specifications exceeding 3kV breakdown thresholds.
China
GB standards for pressure-sensitive adhesive products mandate peel strength and shear resistance testing for domestic certification. MIIT oversight of dual carbon goals pressures coating operations toward waterborne adhesive technologies. The Yangtze River Delta concentrates display manufacturers driving specification pull for ultra-cleanroom compatible formulations.
South Korea
Electronics contract manufacturers enforce JIS and GB standard compliance for smartphone assembly applications. Nano-silica reinforced acrylic formulations from domestic coaters serve flexible circuit lamination demand. The Seoul Capital Area anchors production for sub-50-micrometer precision coatings with low-outgassing certification.
India
PLI scheme incentives for domestic electronics manufacturing attract tape suppliers to establish localized coating operations. BIS certification requirements for pressure-sensitive adhesive products create entry barriers for unregistered imports. The Maharashtra-Gujarat industrial corridor concentrates smartphone and appliance assembly demand.
Unsupported Single Coated Tape Market Competitive Landscape
Listed leaders compete with private specialists across qualification bandwidth and formulation documentation depth. The vendor base separates into consolidated material science conglomerates, mid-scale regional coaters, and niche specialists serving single end-use verticals. Three archetypes dominate: diversified adhesive portfolio holders, electronics-grade precision specialists, and automotive-direct qualification players. Capacity expansion and M&A activity concentrate among firms seeking backward integration into polymer production.
Within the diversified materials tier, 3M Company and Avery Dennison Corporation exemplify portfolio breadth across high-performance bonding applications. Nitto Denko Corporation anchors the electronics-grade precision segment through deep specialization in display and circuit lamination specifications. These three entities occupy positions that span multiple adhesive chemistry platforms and geographic qualification zones.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Intertape Polymer Group |
| tesa SE |
| Shurtape Technologies |
| Scapa Group |
| Berry Plastics |
| Arkema (Bostik) |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German automotive OEMs and certified tape formulators lock in acrylic foam supply for EV battery assembly while anchoring price visibility against petrochemical feedstock swings. These arrangements concentrate purchasing power among buyers with direct procurement teams, compressing margin negotiation space for distributors caught between raw material volatility and fixed contract terms.
Pricing Analysis
Certification level (REACH-compliant vs. standard industrial grade) creates the primary spread between premium and commodity tape offerings. Three-tier pricing structure across automotive-grade, electronics-grade, and general industrial levels reflects qualification burden and testing documentation depth. Cost compression in standard single-sided constructions is intensifying because Asian coaters are expanding waterborne acrylic capacity. Packaging and masking applications show highest price sensitivity, while medical device and EV battery segments absorb premiums for ISO 10993 and dielectric-certified formulations.
Supply Chain Analysis
Inventory buffers for specialty release liners and modified acrylic polymers have compressed to six-to-eight-week cycles, exposing coaters to Korean and Japanese chemical supplier lead-time volatility. Production gravity centers on Germany, China, and South Korea, with each jurisdiction feeding distinct qualification ecosystems. Raw material inputs draw from petrochemical derivatives (acrylic monomers, synthetic rubber), silicone precursors, and precision-coated polyester films. Single-source vulnerability concentrates in electronics-grade release liners from Japanese suppliers. Distribution runs through direct OEM procurement for automotive and electronics segments, with industrial channels retaining distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The unsupported single coated tape market is recovering from petrochemical input cost cyclicality, with EV battery assembly investment in Germany and Michigan driving demand normalization. Automotive electrification capital deployment is resetting volume allocation toward high-temperature acrylic formulations.
For Market Incumbents: Shield formulation documentation advantages by accelerating REACH substance dossier completion ahead of ECHA registration deadlines. Deepen backward integration into acrylic polymer production to offset petrochemical feedstock volatility. Channel control through direct OEM procurement relationships in Stuttgart and Detroit-Toledo corridors limits distributor disintermediation risk from emerging toll coaters.
For New Entrants and Emerging Players: Technical service gaps in hot-melt rheology training and UV-curable adhesive process support present white-space openings where solvent-based coating veterans dominate. India's Maharashtra-Gujarat industrial corridor offers the most penetrable geography, with PLI scheme incentives reducing BIS certification barriers for domestic electronics assembly. A go-to-market angle anchored to solvent-to-hot-melt conversion consulting captures facility reconfiguration demand from EPA-regulated US coaters.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional coaters with established EU substance dossiers and automotive-direct qualification bandwidth. Long-term viability over a multi-year horizon hinges on positioning within EV battery supply chains as cell-to-cell bonding specifications proliferate. The signal to watch is OEM qualification timeline compression below twelve months, indicating supplier testing bandwidth scarcity and potential consolidation triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymer Production | Captive supply of modified monomers insulates margin from crude oil index volatility. |
| Hot-Melt Coating Capacity Expansion | EPA NESHAP compliance enables continued US manufacturing without facility relocation. |
| REACH Substance Dossier Completion | Full ECHA registration preserves EU market access above one-tonne import thresholds. |
| Direct OEM Procurement Relationship Development | Bypassing distributors captures specification influence with Stuttgart and Michigan engineering centers. |
| Nano-Silica Reinforcement R&D Investment | Sub-micrometer particle dispersion technology penetrates South Korean flexible circuit lamination demand. |
Research Methodology
Desk research of trade association technical standards, customs import filings, and regulatory substance databases preceded structured interviews with coating plant managers, automotive Tier 1 procurement leads, electronics contract manufacturer quality directors, and adhesive raw material distribution channel partners. Secondary validation drew from ECHA registration dossiers, EPA enforcement records, GB standard certification listings, and SEC filings from listed adhesive portfolio holders. Bottom-up volume modeling across product type, adhesive chemistry, end-use industry, and application segments was cross-checked against top-down demand aggregation from regional automotive and electronics production data.
Variance decomposition across the projection horizon isolates volume drivers (EV battery platform launches, electronics manufacturing capacity additions) from price effects (petrochemical input costs, regulatory compliance premiums). Segmentation dimensions modeled include foam/specialty/single-sided/double-sided product types, acrylic/silicone/rubber/hot-melt adhesive chemistries, automotive/electronics/construction/packaging end-use industries, and mounting/insulation/bonding/surface protection applications. CAGRs were derived from slope analysis of segment-level demand curves calibrated to OEM qualification pipeline visibility. Industry-specific forecast inputs encompass cell-to-cell bonding specification proliferation rates and solvent-to-hot-melt coating conversion capex cycles.
Underlying assumptions cover sustained automotive electrification investment, REACH substance disclosure enforcement continuity, and hot-melt coating technology maturation, with deviation risk concentrated in petrochemical feedstock price shocks and Asian supply concentration disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Coding Foils and Tapes Market
Tapes
Painting Masking Tapes Market
Tapes
High Bond Tape Market
Tapes
Global Adhesive Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Gaffers Tape Market
Tapes
Tape Applicator Machines Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Paper Masking Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Double Sided Tape Market
Tapes
Utility Grade Duct Tapes Market
Tapes
Replica Tapes Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Security Tape Market
Tapes
Fine Line Striping Tape Market